China AI Computing Market Size & Growth Rate
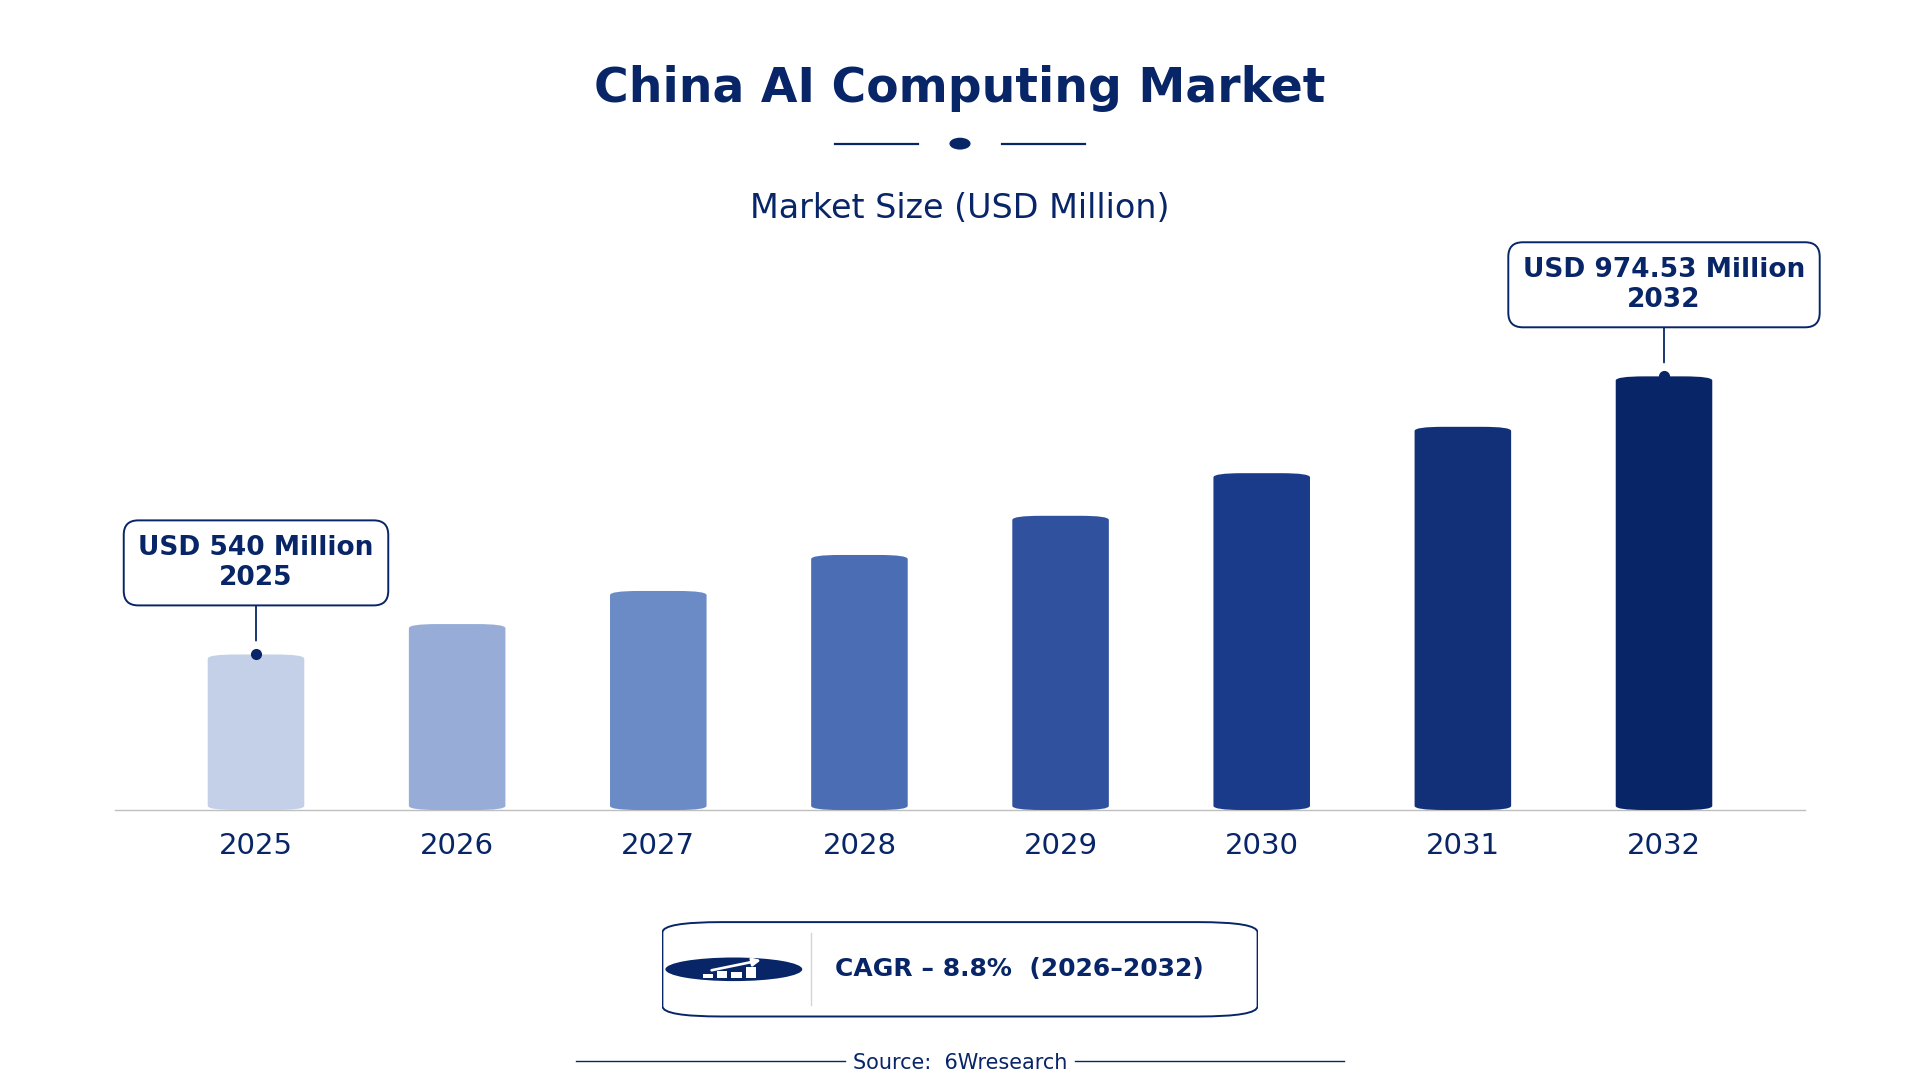
According to 6Wresearch internal database and industry insights, the China AI Computing Market was valued at USD 540.0 million in 2025 and is projected to reach USD 974.53 million by 2032, growing at a CAGR of approximately 8.8% during 2026–2032.
China AI Computing Market Highlights
| Report Metric | Details |
| Report Name | China AI Computing Market |
| Market Size 2025 | USD 540.0 million |
| Market Size 2032 | USD 974.53 million |
| Absolute Growth 2025–2032 | USD 434.53 million |
| CAGR 2026–2032 | 8.8% |
| Peak Annual Growth | 11.2% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Computing Type, 2025 | Cloud AI Infrastructure (45% share) |
| Leading Hardware Platform, 2025 | High-performance GPUs (42% share) |
| Leading Distribution Channel, 2025 | Cloud Service Providers (43% share) |
| Leading End User, 2025 | Large Enterprises (38% share) |
| Fastest-Growing Computing Type | Edge AI Computing (11.5% CAGR) |
| Fastest-Growing Hardware Platform | NPUs/SoCs (10.0% CAGR) |
| Fastest-Growing End User | Industrial IoT Firms (11.6% CAGR) |
| Growing Sector | Industrial IoT Firms |
| Key End Users | Large Enterprises, Industrial IoT Firms, Smart Device Manufacturers, Research Institutes |
China AI Computing Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
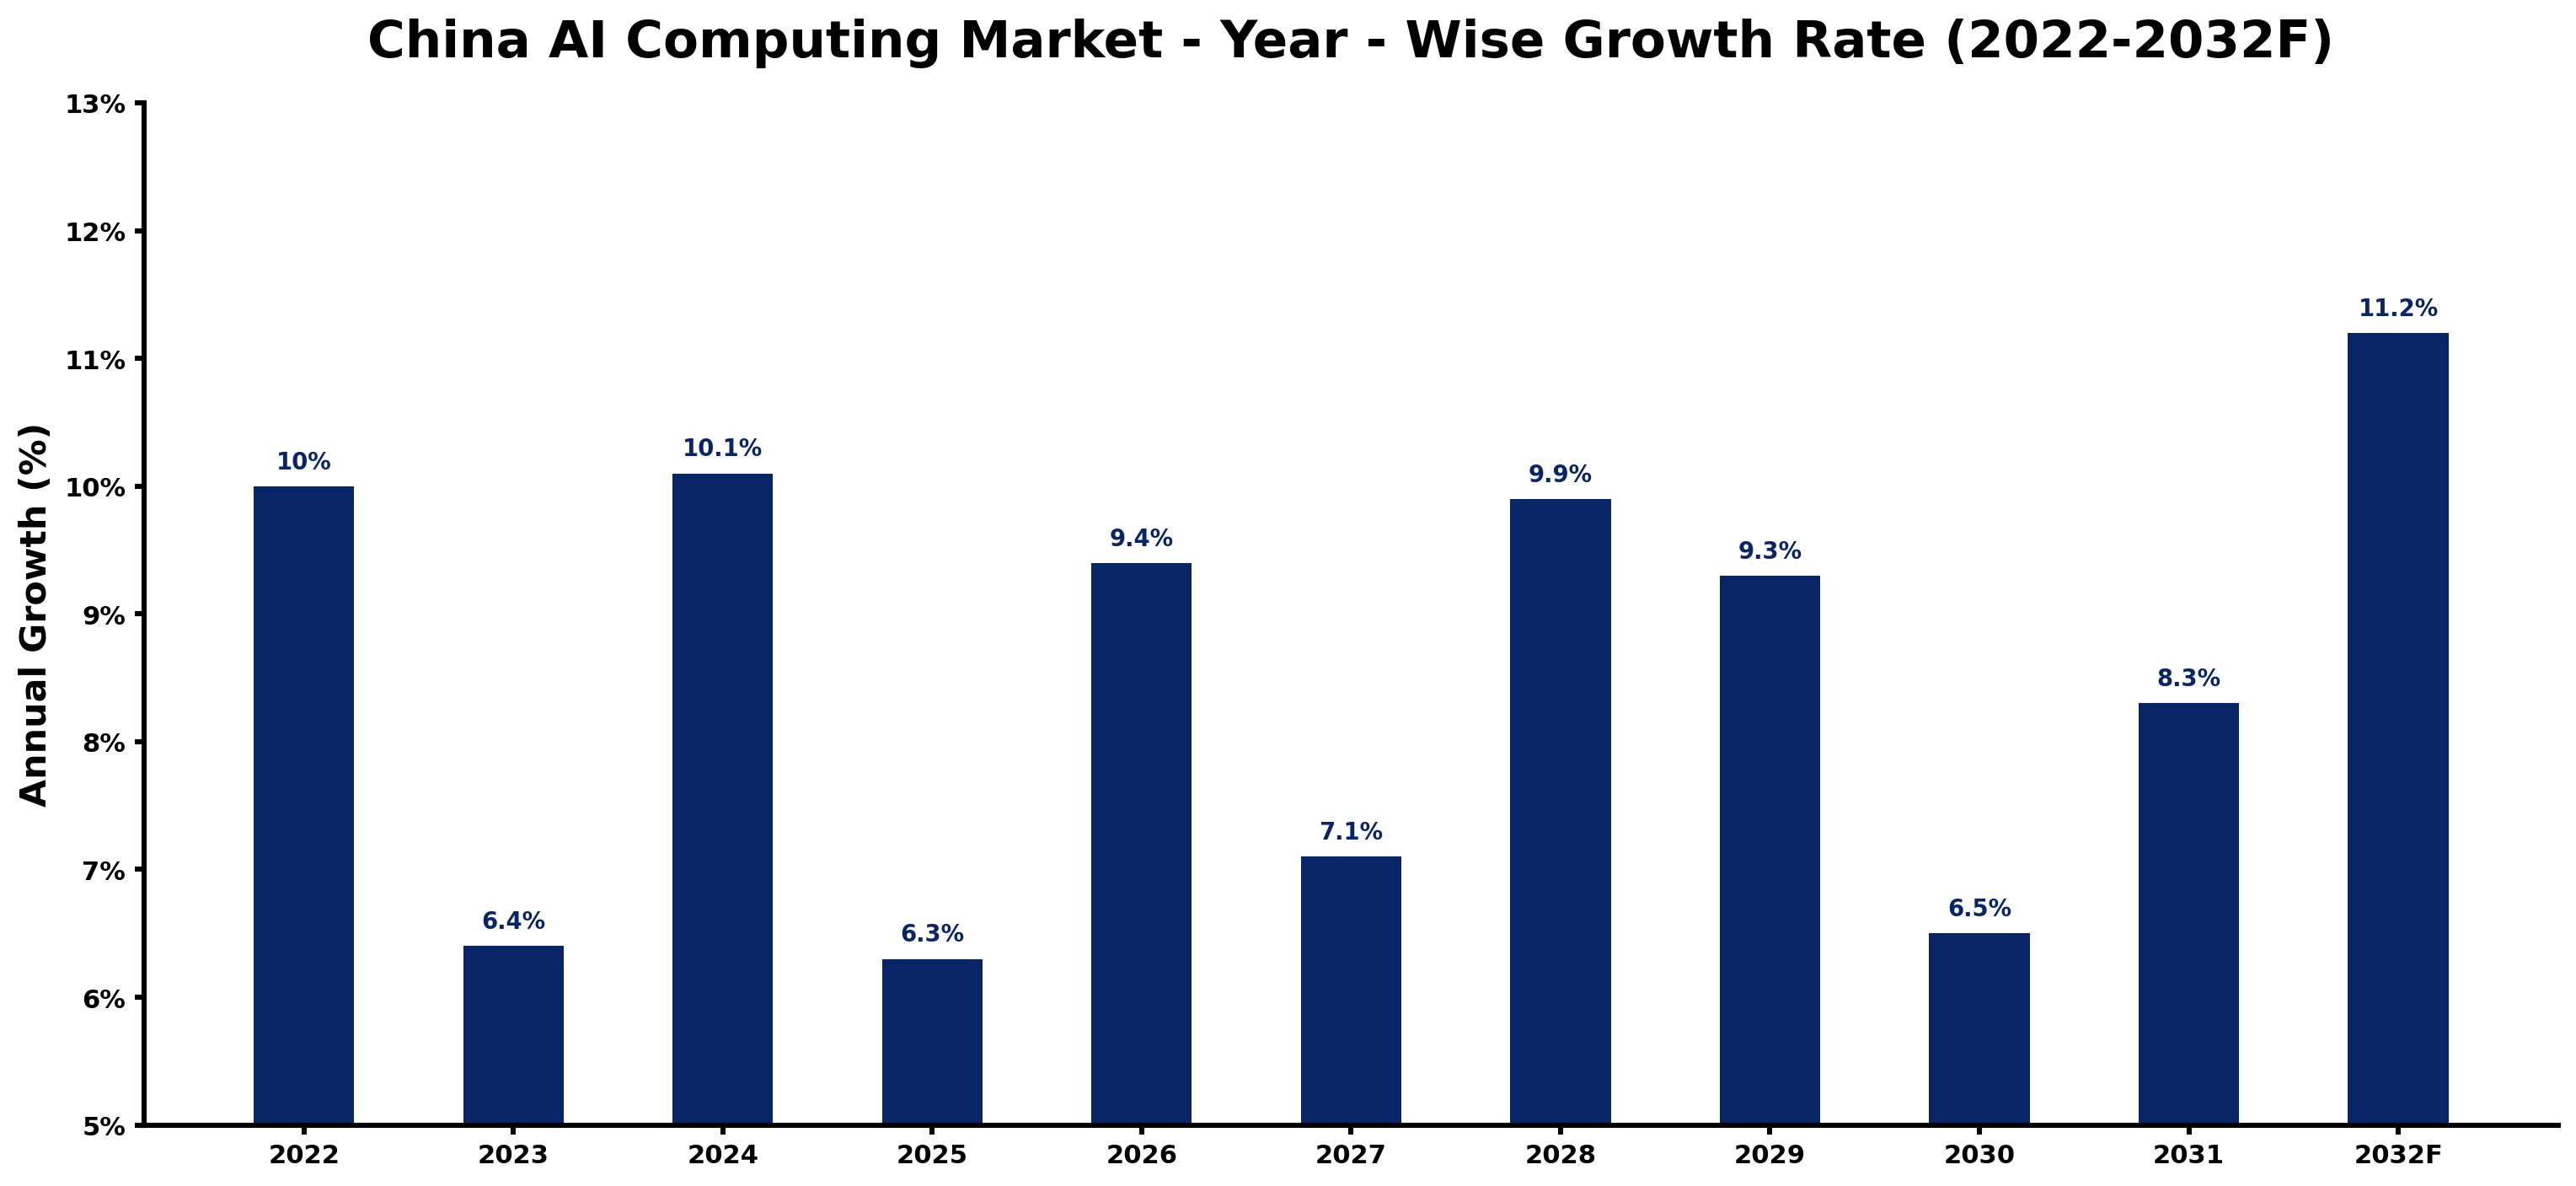
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 10.0 | The market experienced significant activity, driven by increased investments in AI technologies. |
| 2023 | 6.4 | Growth slowed due to market adjustments and a shift in focus towards more sustainable AI solutions. |
| 2024 | 10.1 | Demand surged as major investments in AI infrastructure began to materialise across sectors. |
| 2025 | 6.3 | Growth slowed again as companies reassessed their AI strategies amid changing market conditions. |
| 2026 | 9.4 | Investment in AI technologies rose, particularly in cloud infrastructure and supercomputing capabilities. |
| 2027 | 7.1 | A slowdown occurred as firms faced challenges in integrating AI into existing systems. |
| 2028 | 9.9 | Renewed interest in AI applications led to faster growth as new projects were initiated. |
| 2029 | 9.3 | Growth slowed as companies focused on optimising existing AI systems rather than new deployments. |
| 2030 | 6.5 | Demand stabilised as the market adjusted to the integration of AI across various sectors. |
| 2031 | 8.3 | Increased investments in AI talent and infrastructure spurred growth in several industries. |
| 2032 | 11.2 | The market peaked as AI technologies became integral to business operations across sectors. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China AI Computing Market Synopsis
AI Computing in China includes technologies that enable machines to perform tasks requiring human intelligence, such as learning and problem-solving. This is achieved through advanced algorithms and hardware integration, including GPUs and specialised processors. The China AI Computing Market is growing rapidly, driven by strong domestic demand and ongoing investments in research and development. With over 1.4 billion internet users, the need for AI solutions is substantial. The National AI Development Plan aims to position China as a global leader in AI by 2030, further propelling market growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased investment in AI infrastructure and talent development is driving demand for AI computing solutions. | Driver | High | Cloud AI Infrastructure |
| Growing adoption of AI technologies in industrial settings enhances operational efficiency and decision-making. | Driver | High | Industrial IoT Firms |
| The establishment of AI supercomputing centres in provinces like Guangdong creates new opportunities for research and development. | Opportunity | High | AI Supercomputing |
| The rapid growth of the AI talent pool, projected to exceed 1 million professionals by 2025, presents opportunities for skilled workforce development. | Opportunity | Medium | High-performance GPUs |
| Challenges in integrating AI into existing systems may limit the pace of adoption for some firms. | Restraint | High | Large Enterprises |
| Concerns over ethical AI use could hinder the deployment of AI solutions across various sectors. | Restraint | Medium | Research Institutes |
| The AI Computing market in China faces significant regulatory hurdles that complicate compliance for producers. | Challenge | High | Cloud AI Infrastructure |
| Limited access to advanced AI technologies can delay project timelines for companies needing immediate solutions. | Challenge | Medium | Smart Device Manufacturers |
Evaluation of Drivers in China AI Computing Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Growing investment in AI infrastructure | Cloud AI Infrastructure | In 2022, China's investment in AI technology reached 30 billion CNY, enabling Cloud Service Providers to expand their offerings and capabilities. |
| Increased demand for real-time data processing | Edge AI Computing | The Beijing-Tianjin-Hebei region's focus on real-time applications drives demand for Edge AI solutions, enhancing responsiveness in various industries. |
| Expansion of supercomputing capabilities | AI Supercomputing | AI supercomputing centres established in provinces like Guangdong support complex simulations, creating demand for high-performance computing resources. |
| Rising adoption of automation in industries | Industrial IoT Firms | The industrial IoT sector's increasing reliance on AI computing for automation boosts demand for AI solutions across manufacturing and logistics. |
| Growing integration of AI in smart devices | Smart Device Manufacturers | Smart Device Manufacturers are integrating AI computing to enhance functionalities, driven by the need for improved user experiences. |
Expansion of the AI Computing market in China is supported by rising investments in AI infrastructure, cloud services, and supercomputing capabilities. In 2022, China's investment in AI technology reached 30 billion CNY, improving service capabilities and infrastructure development. The Beijing-Tianjin-Hebei region serves as a major hub for AI research, driving demand for solutions that enable real-time data processing. AI supercomputing centres are being established in provinces like Zhejiang, supporting complex simulations and data-intensive tasks. The industrial IoT sector is increasingly adopting AI computing for automation, further increasing demand for these technologies.
Evaluation of Restraints in China AI Computing Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Regulatory hurdles complicate compliance for producers, affecting their ability to operate efficiently. | Cloud AI Infrastructure | Firms face challenges navigating the complex regulations of AI, resulting in increased compliance costs. |
| Concerns over ethical AI use may hinder the deployment of AI solutions across various sectors. | Research Institutes | Ethical considerations are becoming increasingly important, impacting research and development timelines and funding. |
| Integration challenges with existing systems can slow down the adoption of AI technologies. | Large Enterprises | Firms often struggle to incorporate new AI solutions into their legacy systems, delaying project timelines. |
| The high cost of advanced AI technologies limits access for smaller companies. | Smart Device Manufacturers | Smaller firms may find it difficult to invest in the latest AI computing resources, restricting their market participation. |
| Talent shortages in specific AI fields can delay project timelines for companies needing skilled professionals. | High-performance GPUs | While the talent pool is growing, certain specialized skills remain in short supply, affecting project execution. |
China AI Computing Market Challenges
In 2023, China's AI computing market faced supply chain disruptions, as over 70% of high-performance GPUs are sourced from a limited number of suppliers, causing delays for producers in meeting project deadlines. Regulatory hurdles arise from the National Standards of AI, which impose compliance requirements, extending development times for importers and distributors. Rising costs are a concern, with AI technology investments reaching 30 billion CNY in 2022, forcing buyers to allocate larger budgets for AI solutions. The talent shortage is pressing; by 2025, China's AI talent pool is projected to exceed 1 million professionals, complicating recruitment for buyers seeking skilled workers to implement AI projects effectively.
Trends in the China AI Computing Market
Several trends are reshaping the China AI Computing Market; the most important are set out below.
- Shift from Traditional to Cloud-Based AI Solutions: In 2021, many firms began transitioning to cloud-based AI solutions to improve scalability and flexibility. The shift is reflected in the increasing share of Cloud AI Infrastructure, projected to reach 45% by 2025.
- Emergence of AI Supercomputing Centres: AI supercomputing centres are being established across provinces, including Guangdong and Zhejiang, to support advanced research. This trend is set to boost the capabilities of AI applications in China, with multiple centres expected by 2025.
- Focus on Ethical AI Development: In recent years, there has been a notable shift towards ethical AI development, guided by the National Development and Reform Commission's guidelines. This focus aims to ensure responsible AI deployment, impacting how technologies are developed and used.
- Increased Investment in AI Talent Development: The AI Talent Development Program initiated in 2023 aims to cultivate skilled professionals in AI technologies. With an estimated 1 million professionals expected by 2025, this trend supports the growing demand for AI solutions.
Investment Opportunities in the China AI Computing Market
Several openings in the China AI Computing Market merit attention from investors.
- Investment in AI Infrastructure: With China's AI technology investment reaching 30 billion CNY in 2022, there is a strong opportunity to supply advanced AI infrastructure solutions. Large Enterprises are particularly interested in enhancing their AI capabilities.
- Supply of High-Performance GPUs: The demand for high-performance GPUs is set to grow as AI applications expand. Research Institutes are actively seeking suppliers to meet their increasing computational needs, presenting a lucrative market opportunity.
- Development of AI Supercomputing Facilities: The establishment of AI supercomputing centres in provinces like Guangdong offers opportunities for investment in advanced computing technologies. Now is the time to engage with local governments to support these initiatives.
- Cloud AI Services Expansion: The rapid growth of Cloud AI Infrastructure creates opportunities for service providers to deliver scalable solutions. With a projected market share of 45% by 2025, Cloud Service Providers are key targets for collaboration.
Government Initiatives in the China AI Computing Market
The 'AI Innovation Action Plan' by the Ministry of Industry and Information Technology, launched in 2021, promotes AI technology development and application across industries. This initiative encourages firms to invest in AI capabilities, improving their competitive edge. Additionally, the '14th Five-Year Plan for National Economic and Social Development' approved in 2022 emphasises AI as a critical technology for economic growth, setting specific targets for integration in various sectors.
The Ministry of Science and Technology oversees the 'AI Talent Development Program', initiated in 2023 to cultivate skilled professionals in AI technologies. This program aims to address the talent gap in the industry, ensuring a steady supply of qualified individuals. Furthermore, the National Development and Reform Commission released guidelines in 2023 for the ethical use of AI, which aim to ensure responsible development and deployment of AI technologies.
Future Insight of the China AI Computing Market
Several forward-looking factors should support the AI computing market in China over the coming years. The National AI Development Plan aims to make China a global leader in AI by 2030, promoting innovation and investment. AI research capabilities will improve as supercomputing centers are established across provinces, enhancing infrastructure. The 'AI Innovation Action Plan' launched by the Ministry of Industry and Information Technology in 2021 will streamline development processes, allowing suppliers to bring products to market more efficiently.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Computing Type – Cloud AI Infrastructure Dominated, Edge AI Computing Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, Cloud AI Infrastructure took a 45% share of computing type in 2025, more than any other category. Cloud AI Infrastructure commands the largest market share because it offers scalable resources crucial for diverse workloads across sectors like finance and healthcare. This is particularly evident in major urban centres, such as Beijing, where businesses increasingly rely on cloud solutions for their AI initiatives. Edge AI Computing is projected to grow fastest, at a CAGR of 11.5% during 2026–2032. Edge AI Computing is experiencing rapid growth as it enables real-time data processing at the source, essential for applications in smart cities and autonomous vehicles. The rising demand for low-latency responses in these sectors is driving its expansion, ensuring a wider adoption of edge technologies. Suppliers should enhance cloud capabilities while also exploring edge solutions to meet the increasing demand in the AI computing market.
By Hardware Platform – High-performance GPUs Dominated, NPUs/SoCs Expected to Grow Fastest
High-performance GPUs held a 42% share of the China AI Computing Market by hardware platform in 2025. High-performance GPUs lead the market share due to their critical role in efficiently training and running complex models across various industries. Their importance is particularly evident in research institutions where deep learning applications are prevalent, solidifying their position as the leading hardware platform. NPUs/SoCs are set to record the highest CAGR in this split, 10.0% over 2026–2032. NPUs/SoCs are witnessing rapid growth as they are specifically designed for AI tasks, significantly enhancing processing capabilities. The trend is driven by the rising integration of AI in consumer electronics and automotive applications, indicating a shift towards more specialised hardware solutions. Buyers should prioritise investments in NPUs/SoCs to leverage their advantages in specialised tasks, ensuring competitive performance in AI applications.
By Distribution Channel – Cloud Service Providers Dominated and Is Expected to Record the Fastest Growth
With a 43% revenue share in 2025, Cloud Service Providers was the largest distribution channel category. Cloud Service Providers dominate the market by delivering essential infrastructure that facilitates the deployment of AI solutions at scale across various industries. Their extensive networks and resources make them indispensable for businesses aiming to harness AI effectively and efficiently. Its lead should widen, with a projected CAGR of 11.4% during 2026–2032, the highest in this split. Cloud Service Providers are also the fastest-growing segment, as their services are increasingly in demand for rapid deployment and scalability in AI applications. The ongoing shift towards cloud-based solutions is solidifying their market position, ensuring sustained growth in this channel. Suppliers must enhance their cloud offerings to capitalise on the growing reliance on cloud services for AI computing.
By End User – Large Enterprises Dominated, Industrial IoT Firms Expected to Grow Fastest
The largest end user category in 2025 was Large Enterprises, with a 38% share of total revenue. Large Enterprises hold the largest market share as they implement AI computing to enhance operational efficiency and decision-making across various sectors. Their substantial investments in AI technologies reflect a strong need for competitive advantage in a rapidly changing market landscape. Over 2026–2032, Industrial IoT Firms are expected to post the fastest growth, at a CAGR of 11.6%. Industrial IoT Firms are the fastest-growing segment, as they leverage AI computing for automation and data analytics to optimise operations. The increasing emphasis on smart manufacturing and connected devices is propelling this growth, highlighting the importance of AI in industrial settings. Buyers in the industrial sector should consider AI computing solutions to enhance automation and improve data-driven decision-making.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China AI Computing Market Outlook
- Market Size of China AI Computing Market, 2025
- Forecast of China AI Computing Market, 2032
- Historical Data and Forecast of China AI Computing Revenues & Volume for the Period 2022 - 2032F
- China AI Computing Market Trend Evolution
- China AI Computing Market Drivers and Challenges
- China AI Computing Price Trends
- China AI Computing Porter's Five Forces
- China AI Computing Industry Life Cycle
- Historical Data and Forecast of China AI Computing Market Revenues & Volume By Computing Type for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Computing Market Revenues & Volume By Edge AI Computing for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Computing Market Revenues & Volume By Cloud AI Infrastructure for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Computing Market Revenues & Volume By AI Supercomputing for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Computing Market Revenues & Volume By On-device AI Processing for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Computing Market Revenues & Volume By Hardware Platform for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Computing Market Revenues & Volume By Microcontrollers for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Computing Market Revenues & Volume By High-performance GPUs for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Computing Market Revenues & Volume By HPC Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Computing Market Revenues & Volume By NPUs/SoCs for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Computing Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Computing Market Revenues & Volume By OEM Distributors for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Computing Market Revenues & Volume By Cloud Service Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Computing Market Revenues & Volume By Direct Hardware Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Computing Market Revenues & Volume By Online Electronics Stores for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Computing Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Computing Market Revenues & Volume By Industrial IoT Firms for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Computing Market Revenues & Volume By Large Enterprises for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Computing Market Revenues & Volume By Research Institutes for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Computing Market Revenues & Volume By Smart Device Manufacturers for the Period 2022 - 2032F
- China AI Computing Import Export Trade Statistics
- Market Opportunity Assessment By Computing Type
- Market Opportunity Assessment By Hardware Platform
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China AI Computing Top Companies Market Share
- China AI Computing Competitive Benchmarking By Technical and Operational Parameters
- China AI Computing Company Profiles
- China AI Computing Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Computing Type
- Edge AI Computing
- Cloud AI Infrastructure
- AI Supercomputing
- On-device AI Processing
By Hardware Platform
- Microcontrollers
- High-performance GPUs
- HPC Systems
- NPUs/SoCs
By Distribution Channel
- OEM Distributors
- Cloud Service Providers
- Direct Hardware Sales
- Online Electronics Stores
By End User
- Industrial IoT Firms
- Large Enterprises
- Research Institutes
- Smart Device Manufacturers































