China AI Hardware Market Size & Growth Rate
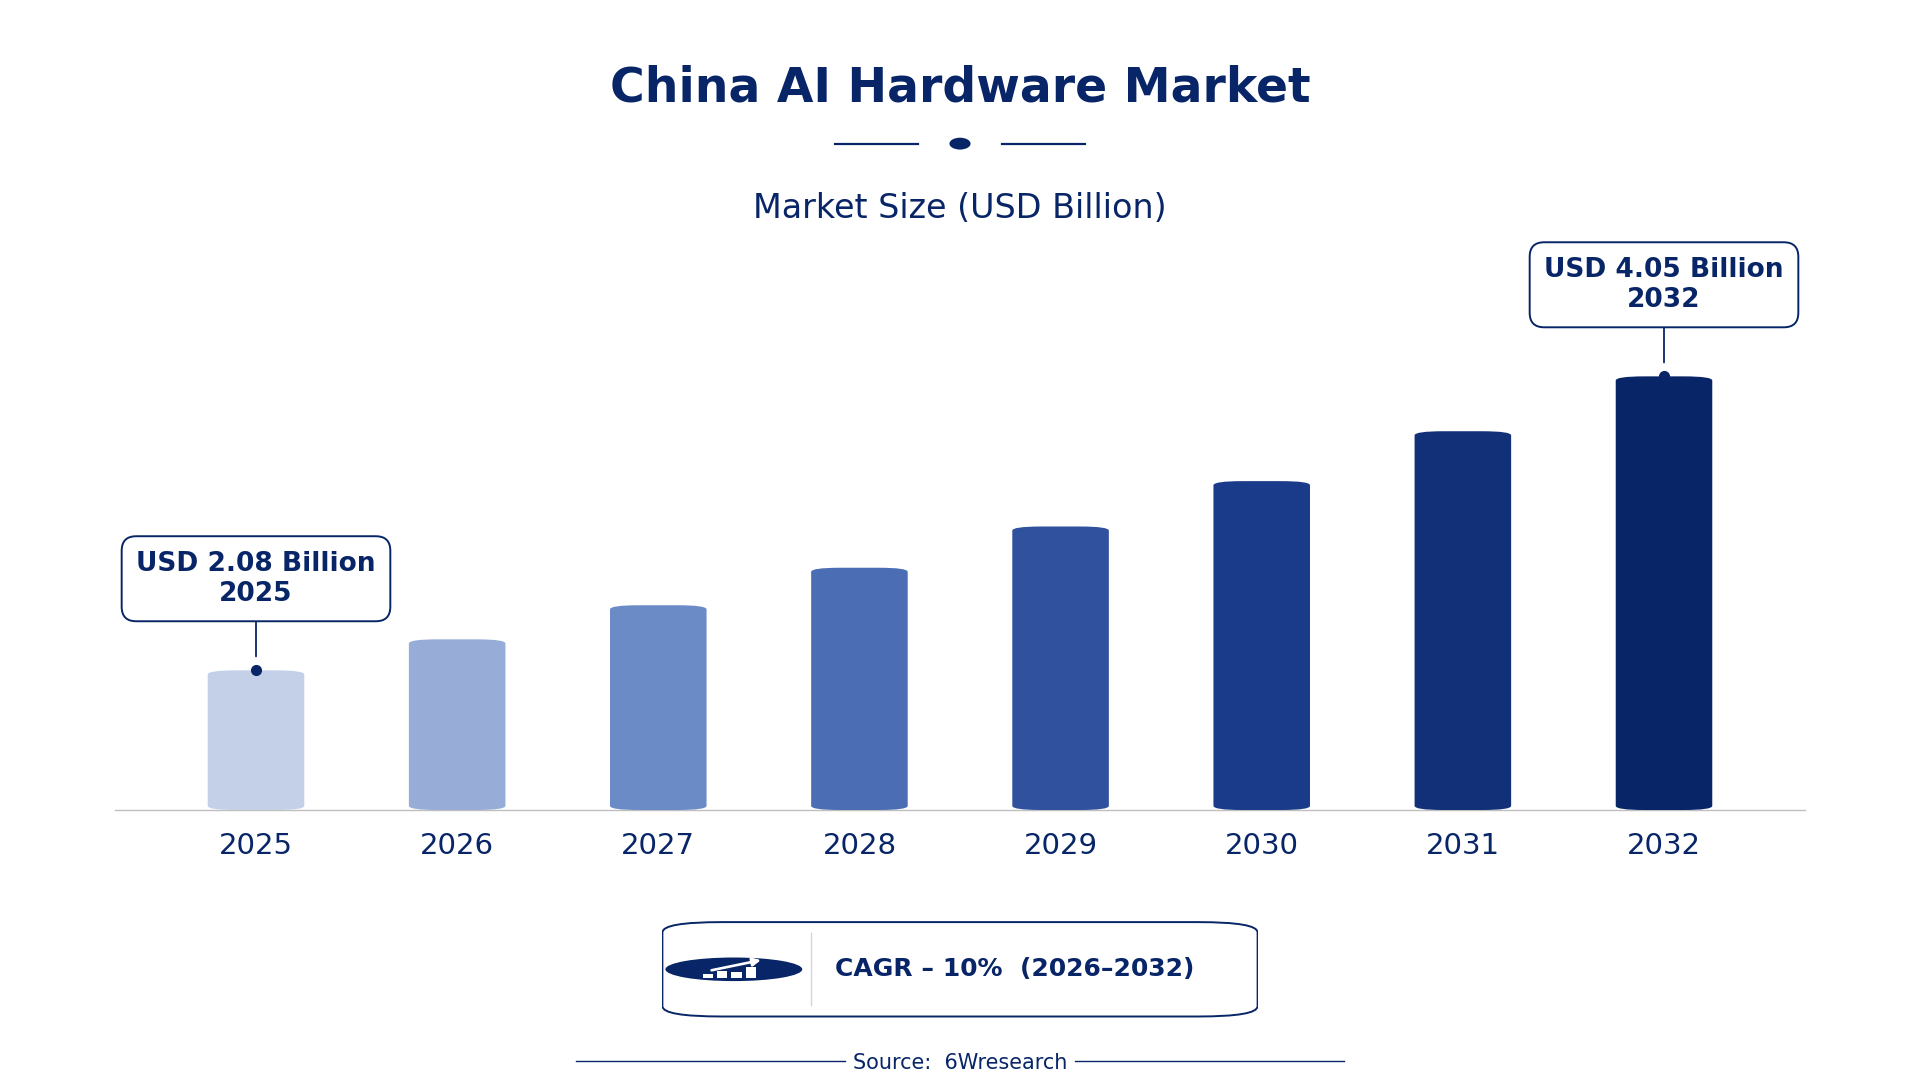
According to 6Wresearch internal database and industry insights, the China AI Hardware Market was valued at USD 2.08 billion in 2025 and is projected to reach USD 4.05 billion by 2032, growing at a CAGR of approximately 10% during 2026–2032.
China AI Hardware Market Highlights
| Report Metric | Details |
| Report Name | China AI Hardware Market |
| Market Size 2025 | USD 2.08 billion |
| Market Size 2032 | USD 4.05 billion |
| Absolute Growth 2025–2032 | USD 1.97 billion |
| CAGR 2026–2032 | 10% |
| Peak Annual Growth | 12.3% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Hardware Type, 2025 | GPUs (42% share) |
| Leading Functionality, 2025 | High-speed Training (33% share) |
| Leading Distribution Channel, 2025 | OEM Sales (50% share) |
| Leading End User, 2025 | Cloud Providers (50% share) |
| Fastest-Growing Hardware Type | ASICs (12.7% CAGR) |
| Fastest-Growing Functionality | Edge Inference (11.2% CAGR) |
| Fastest-Growing Distribution Channel | Semiconductor Dealers (12.6% CAGR) |
| Fastest-Growing End User | AI Accelerator Startups (11.1% CAGR) |
| Growing Sector | Cloud Computing |
| Key End Users | Cloud Providers, Autonomous Vehicle Developers, AI Accelerator Startups, Industrial Tech Suppliers |
China AI Hardware Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
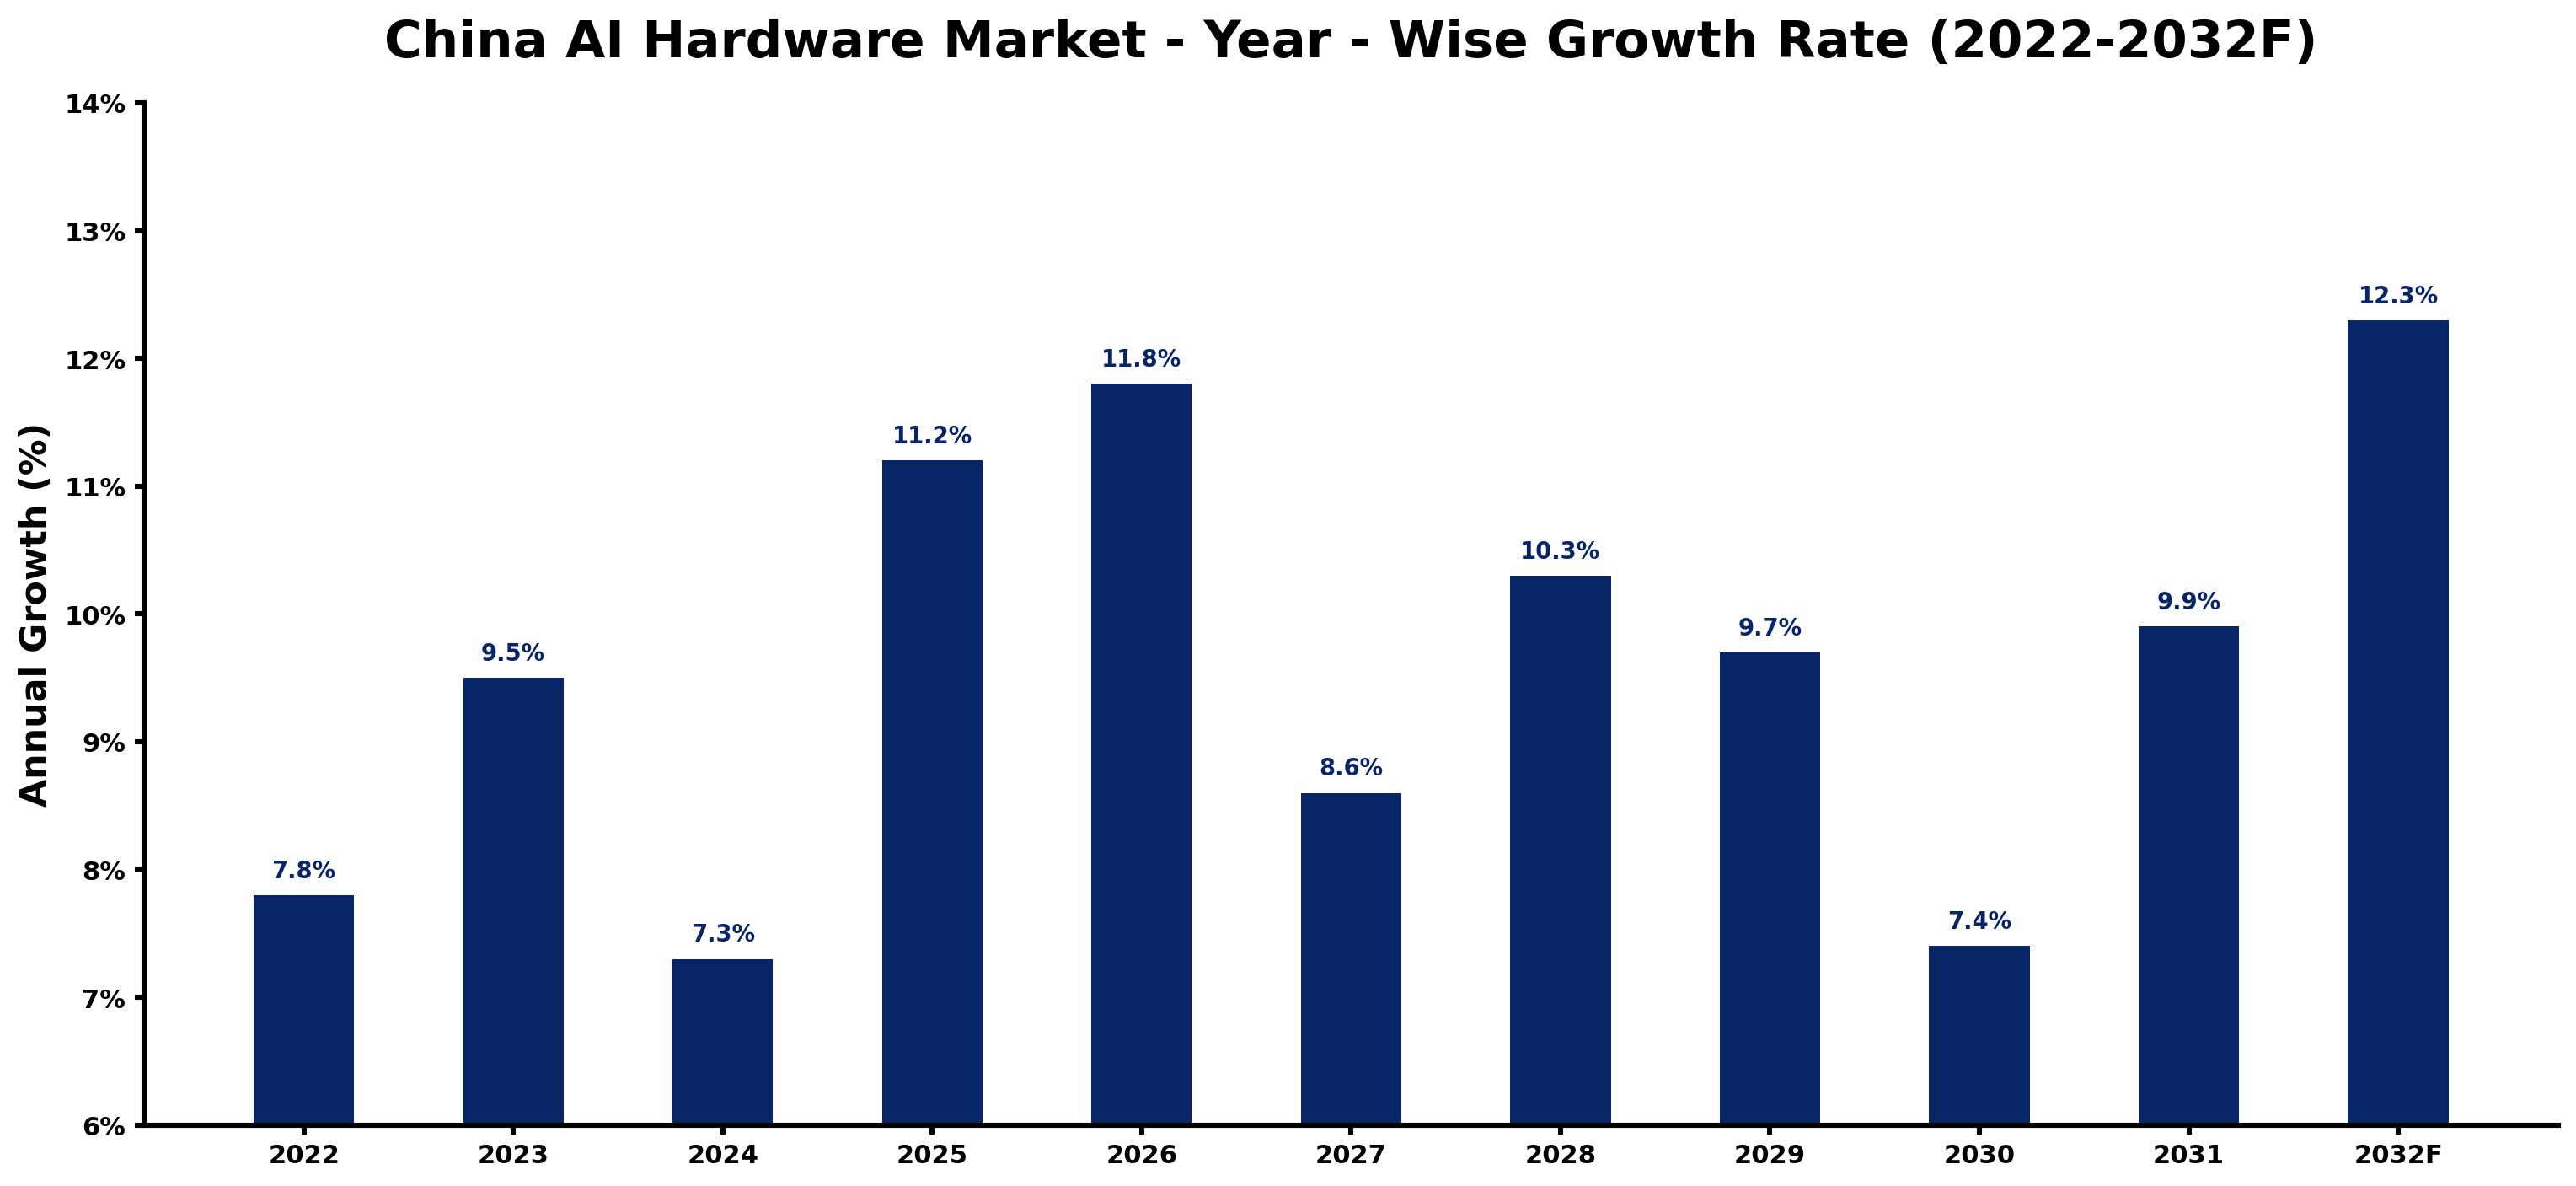
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.8 | The market experienced growth due to increasing demand from tech companies. |
| 2023 | 9.5 | Growth accelerated as investments in AI infrastructure expanded, including the $5 billion funding from the National Development and Reform Commission. |
| 2024 | 7.3 | A slowdown occurred as the AI Innovation Action Plan began to influence market conditions. |
| 2025 | 11.2 | Demand surged with the introduction of new AI standards and guidelines established by the AI Hardware Standardization Committee. |
| 2026 | 11.8 | Growth continued as funding for AI hardware startups increased through the $1 billion initiative by the Ministry of Science and Technology. |
| 2027 | 8.6 | A slowdown was noted as competition within the sector intensified, impacting pricing strategies. |
| 2028 | 10.3 | Demand rose again with advancements in edge inference technologies, driven by the AI Accelerator Program in Beijing. |
| 2029 | 9.7 | Growth slowed as the market adjusted to evolving buyer preferences in AI hardware solutions. |
| 2030 | 7.4 | A further slowdown was observed as the market stabilised after rapid expansion, influenced by the 14th Five-Year Plan for Digital Economy Development. |
| 2031 | 9.9 | Growth picked up again with renewed investments in AI hardware, particularly from cloud providers. |
| 2032 | 12.3 | The market peaked as demand surged for high-speed training capabilities, reflecting the increasing reliance on AI applications. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China AI Hardware Market Synopsis
The China AI Hardware Market includes a range of computing technologies tailored for artificial intelligence applications, such as GPUs, NPUs, ASICs, and FPGAs. These components enable rapid data processing and real-time inference in smart devices. The market is expanding quickly, fuelled by strong domestic demand from cloud providers and government initiatives like the 'New Generation Artificial Intelligence Development Plan'. With over 1 million units produced in 2022, the market showcases considerable investment in AI technologies and infrastructure, particularly in regions like Guangdong.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing demand for high-speed training capabilities among cloud providers | Driver | High | High-speed Training |
| Increased investments in AI infrastructure by the government | Driver | High | Cloud Providers |
| Rising need for specialized AI solutions in autonomous vehicles | Opportunity | Medium | Autonomous Vehicle Developers |
| Expanding market for AI hardware among startups | Opportunity | High | AI Accelerator Startups |
| Intense competition affecting pricing strategies | Restraint | High | GPUs |
| Supply chain disruptions impacting semiconductor availability | Restraint | Medium | ASICs |
| Regulatory hurdles delaying product approvals | Challenge | High | NPUs |
| Technological obsolescence due to rapid advancements | Challenge | Medium | FPGAs |
Evaluation of Drivers in China AI Hardware Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increasing cloud computing demand | Cloud Providers | Over 50% of AI hardware demand stems from cloud providers, driving purchases of specialized components. |
| Government funding for AI infrastructure | High-speed Training | The National Development and Reform Commission's $5 billion investment in AI infrastructure boosts demand for high-speed training hardware. |
| Rise in autonomous vehicle development | Autonomous Vehicle Developers | Investments in AI hardware for autonomous vehicles are driving demand for specialized components, with a reported 15% increase in semiconductor sales in 2023. |
| Growth of AI startups | AI Accelerator Startups | The AI Accelerator Program in Beijing supports startups, increasing demand for AI hardware, with over 1,000 startups now in the ecosystem. |
| Expansion of AI applications in various industries | Industrial Tech Suppliers | The growing need for AI solutions across industries boosts purchases from industrial tech suppliers, reflecting a broader trend in technology adoption. |
Over 50% of AI hardware demand stems from cloud providers, driving purchases of specialized components. The National Development and Reform Commission's $5 billion investment in AI infrastructure boosts demand for high-speed training hardware. Investments in AI hardware for autonomous vehicles are increasing, with a 15% rise in semiconductor sales reported in 2023.
Evaluation of Restraints in China AI Hardware Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Intense competition affecting pricing strategies | GPUs | The presence of numerous suppliers has led to price wars, reducing profit margins for GPU manufacturers. |
| Supply chain disruptions impacting semiconductor availability | ASICs | Global semiconductor shortages have delayed production schedules, affecting ASIC availability for buyers. |
| Regulatory hurdles delaying product approvals | NPUs | Strict compliance requirements slow down the approval process for new NPU technologies. |
| Technological obsolescence due to rapid advancements | FPGAs | The fast pace of innovation in AI hardware can render existing FPGA models outdated quickly. |
| Market saturation in certain AI hardware segments | High-speed Training | As more players enter the market, saturation in high-speed training solutions may limit growth opportunities. |
China AI Hardware Market Challenges
The China AI Hardware Market encounters several practical challenges, starting with fierce competition among producers. This competition arises from a surge in new entrants, resulting in price wars that diminish profit margins for established firms. Supply chain issues also pose difficulties, as producers rely on semiconductor components, which can face delays due to global shortages, disrupting production timelines. Increasing raw material costs further burden manufacturers, with reports indicating a 15% rise in semiconductor prices in 2023, forcing some to raise prices for buyers. Rapid technological advancements create additional pressure, as many producers find it challenging to keep pace, risking obsolescence and losing market share.
Trends in the China AI Hardware Market
Several trends are reshaping the China AI Hardware Market; the most important are set out below.
- Shift from General-Purpose to Specialized AI Hardware: Cloud Providers are increasingly adopting specialised AI hardware to improve performance, as seen in the 2023 AI Hardware Summit, which attracted over 5,000 attendees.
- Transition to Edge Inference Solutions: The demand for Edge Inference solutions has surged, particularly in smart devices, reflecting a 15% increase in semiconductor sales in 2023.
- Emergence of AI Accelerator Startups: The AI Accelerator Program in Beijing has led to a growing number of startups, contributing to the network of over 1,000 AI-focused companies in China.
- Prioritisation of AI Hardware Standardization: The establishment of the AI Hardware Standardization Committee in 2022 is driving uniformity in product specifications, boosting buyer confidence.
Investment Opportunities in the China AI Hardware Market
Several openings in the China AI Hardware Market merit attention from investors.
- Timing for Investment in AI Startups: With the National Development and Reform Commission's $5 billion funding, now is the ideal time to invest in AI startups needing hardware solutions.
- Supply of Specialized AI Hardware: The growing demand for autonomous vehicles presents an opportunity to supply specialised AI hardware, particularly in regions like Guangdong, known for its manufacturers.
- Gap in High-Speed Training Solutions: Cloud Providers are increasingly seeking advanced AI hardware, creating opportunities for suppliers to meet this rising demand with tailored solutions.
- Investment in Edge Inference Technologies: With a significant rise in smart devices, there is a pressing need for edge inference technologies, particularly in urban areas like Shanghai.
Government Initiatives in the China AI Hardware Market
The 'New Generation Artificial Intelligence Development Plan' by the Ministry of Industry and Information Technology, launched in 2021, aims to improve AI hardware capabilities with a focus on innovation and infrastructure. This plan has led to increased funding for research and development in AI technologies, with the National Development and Reform Commission's 'AI Innovation Action Plan' launched in 2022 allocating $5 billion to support AI research initiatives. The '14th Five-Year Plan for Digital Economy Development' emphasises investment in AI hardware, targeting advancements by 2025, ensuring that producers align with national goals.
The National Development and Reform Commission administers funding programs that support AI hardware startups and research projects, including a $1 billion initiative announced in 2023. This funding is aimed at promoting innovation and collaboration in AI technologies. The AI Hardware Standardization Committee established by the Ministry of Industry and Information Technology in 2022 is responsible for developing industry standards and guidelines, ensuring compliance and quality across the sector. These measures collectively improve the operational capabilities of AI hardware producers and streamline the approval processes for new technologies.
Future Insight of the China AI Hardware Market
By 2032, the China AI Hardware Market will undergo substantial transformations, influenced by government initiatives and advancements in technology. The National AI Strategy aims to establish China as a global leader in AI, promoting collaboration between academia and industry. Infrastructure investments, including a $5 billion commitment for AI development, will strengthen production capabilities and research facilities. The establishment of national standards for AI hardware will improve efficiency and interoperability, providing long-term benefits for both suppliers and buyers.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Hardware Type – GPUs Dominated, ASICs Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, GPUs held a 42% share of the China AI Hardware Market by hardware type in 2025. GPUs hold the largest market share due to their extensive use in training models, which is essential for various applications. The high demand from cloud providers, who depend on GPUs, reinforces their leading position in the market. ASICs are projected to grow fastest, at a CAGR of 12.7% during 2026–2032. ASICs are experiencing rapid growth because they are optimised for specific tasks, significantly enhancing processing efficiency. The increasing focus on specialised applications, particularly in sectors like autonomous vehicles, is driving this segment's expansion. Suppliers should focus on developing ASIC technologies to cater to the growing demand for efficiency in AI applications.
By Functionality – High-speed Training Dominated, Edge Inference Expected to Grow Fastest
With a 33% revenue share in 2025, High-speed Training was the largest functionality category. High-speed Training commands the largest share as it is crucial for efficiently training large models, foundational for numerous applications. Its significance to cloud providers, who require robust training capabilities, solidifies its leading status in the market. The quickest growth will come from Edge Inference, forecast to expand at a CAGR of 11.2% between 2026 and 2032. Edge Inference is the fastest-growing segment as it enables real-time data processing on devices, which is essential for modern technologies. The rise in IoT devices demanding immediate analysis is propelling this segment's growth. Buyers should invest in edge inference capabilities to maintain a competitive advantage in the evolving AI landscape.
By Distribution Channel – OEM Sales Dominated, Semiconductor Dealers Expected to Grow Fastest
In 2025, OEM Sales led the distribution channel split with a 50% share. OEM Sales capture the largest market share as they are vital for integrating hardware into final products, which is essential for manufacturers. This channel is particularly important for companies providing comprehensive solutions to end users. Semiconductor Dealers are set to record the highest CAGR in this split, 12.6% over 2026–2032. Semiconductor Dealers are witnessing the fastest growth as they supply essential components for hardware, addressing the rising demand across various sectors. The reported 15% increase in semiconductor sales in 2023 underscores this trend. Suppliers should strengthen partnerships with semiconductor dealers to ensure a reliable supply of components for hardware.
By End User – Cloud Providers Dominated, AI Accelerator Startups Expected to Grow Fastest
Cloud Providers took a 50% share of end user in 2025, more than any other category. Cloud Providers account for the largest market share as they deliver services using advanced hardware, which is critical for their operations. The $5 billion investment in AI infrastructure approved in 2023 further supports this segment's dominance. Over 2026–2032, AI Accelerator Startups are expected to post the fastest growth, at a CAGR of 11.1%. AI Accelerator Startups are the fastest-growing end user segment, focusing on innovative solutions and hardware to advance technology. Initiatives like the AI Accelerator Program in Beijing highlight the increasing support for these startups. Investors should consider backing AI accelerator startups to leverage the innovative potential within the hardware market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China AI Hardware Market Outlook
- Market Size of China AI Hardware Market, 2025
- Forecast of China AI Hardware Market, 2032
- Historical Data and Forecast of China AI Hardware Revenues & Volume for the Period 2022 - 2032F
- China AI Hardware Market Trend Evolution
- China AI Hardware Market Drivers and Challenges
- China AI Hardware Price Trends
- China AI Hardware Porter's Five Forces
- China AI Hardware Industry Life Cycle
- Historical Data and Forecast of China AI Hardware Market Revenues & Volume By Hardware Type for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Market Revenues & Volume By GPUs for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Market Revenues & Volume By NPUs for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Market Revenues & Volume By ASICs for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Market Revenues & Volume By FPGAs for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Market Revenues & Volume By Functionality for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Market Revenues & Volume By High-speed Training for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Market Revenues & Volume By Edge Inference for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Market Revenues & Volume By Task-Specific AI Ops for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Market Revenues & Volume By Custom AI Hardware for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Market Revenues & Volume By Semiconductor Dealers for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Market Revenues & Volume By OEM Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Market Revenues & Volume By Online Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Market Revenues & Volume By Industrial Tech Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Market Revenues & Volume By Cloud Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Market Revenues & Volume By Smart Device Companies for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Market Revenues & Volume By AI Accelerator Startups for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Market Revenues & Volume By Autonomous Vehicle Developers for the Period 2022 - 2032F
- China AI Hardware Import Export Trade Statistics
- Market Opportunity Assessment By Hardware Type
- Market Opportunity Assessment By Functionality
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China AI Hardware Top Companies Market Share
- China AI Hardware Competitive Benchmarking By Technical and Operational Parameters
- China AI Hardware Company Profiles
- China AI Hardware Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Hardware Type
- GPUs
- NPUs
- ASICs
- FPGAs
By Functionality
- High-speed Training
- Edge Inference
- Task-Specific AI Ops
- Custom AI Hardware
By Distribution Channel
- Semiconductor Dealers
- OEM Sales
- Online Platforms
- Industrial Tech Suppliers
By End User
- Cloud Providers
- Smart Device Companies
- AI Accelerator Startups
- Autonomous Vehicle Developers































