China AI Hardware Platforms Market Size & Growth Rate
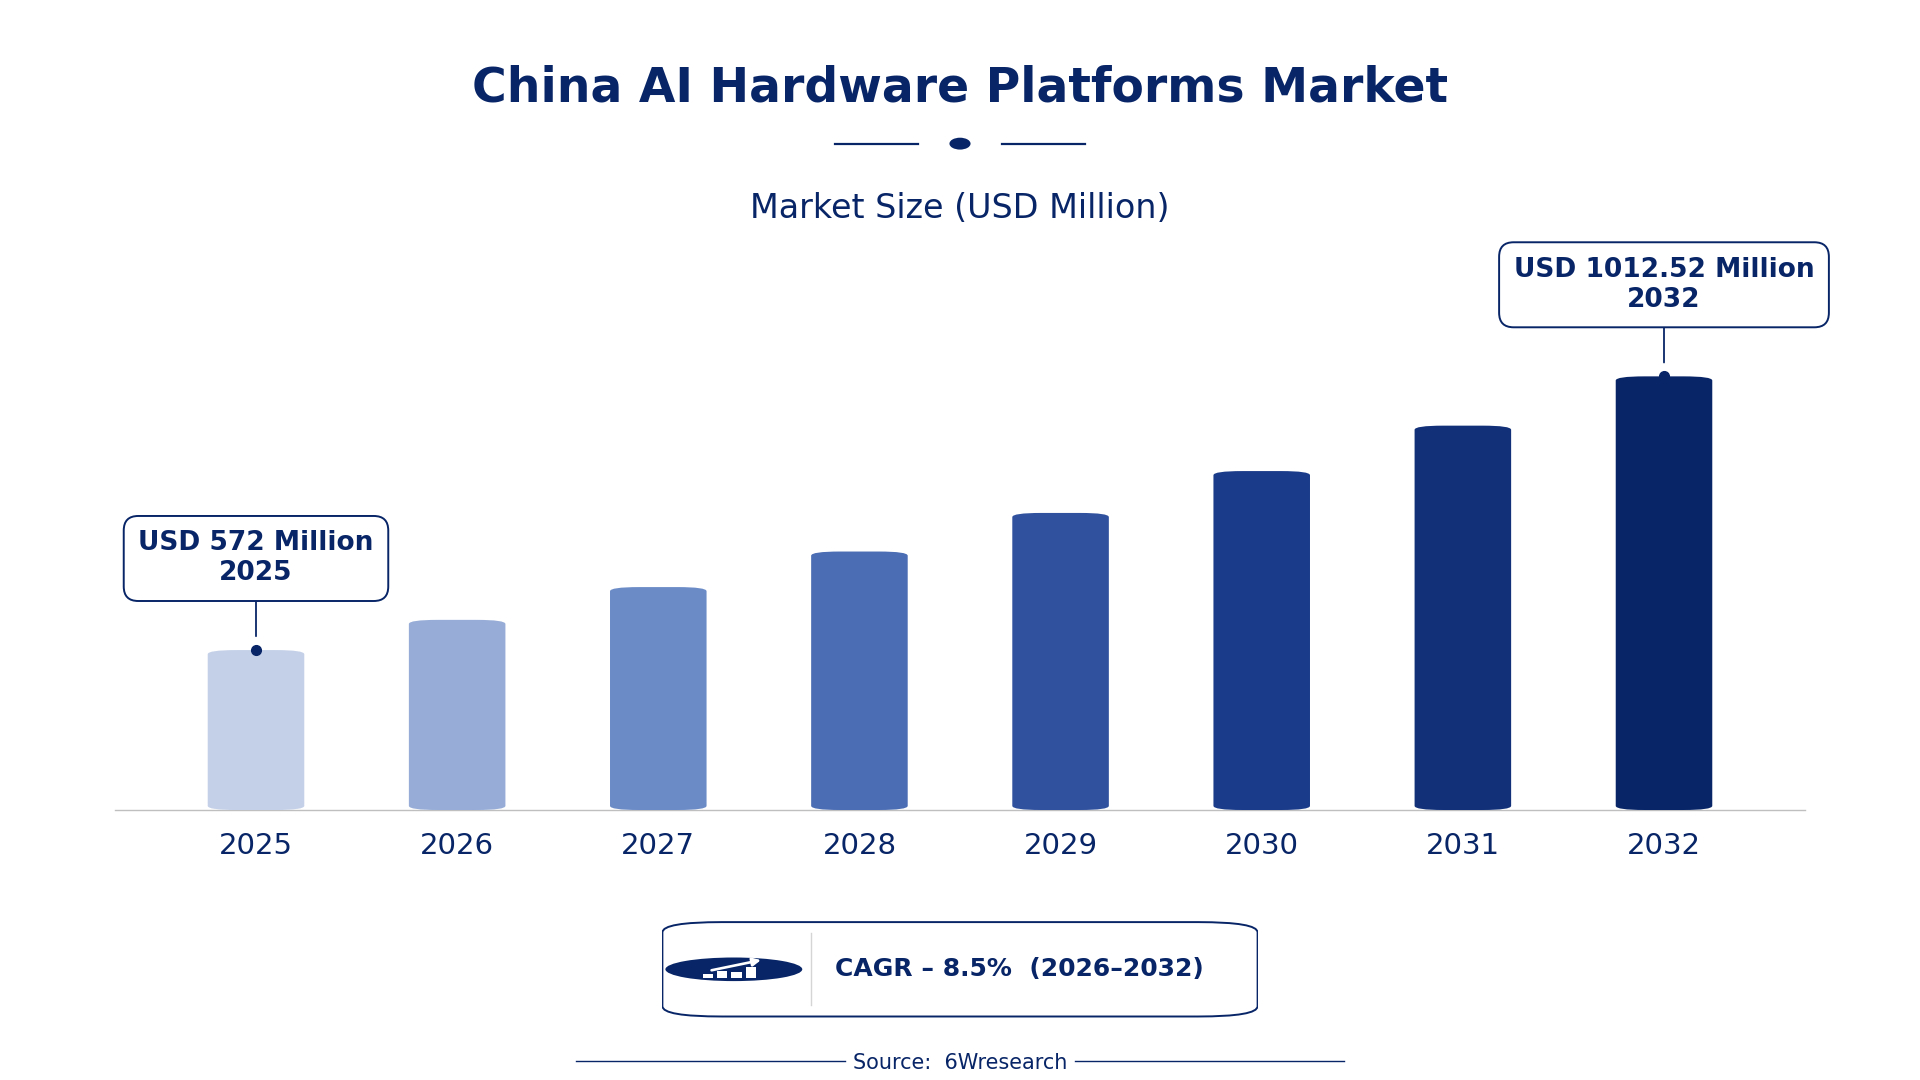
According to 6Wresearch internal database and industry insights, the China AI Hardware Platforms Market was valued at USD 572.0 million in 2025 and is projected to reach USD 1,012.52 million by 2032, growing at a CAGR of approximately 8.5% during 2026–2032.
China AI Hardware Platforms Market Highlights
| Report Metric | Details |
| Report Name | China AI Hardware Platforms Market |
| Market Size 2025 | USD 572.0 million |
| Market Size 2032 | USD 1,012.52 million |
| Absolute Growth 2025–2032 | USD 440.52 million |
| CAGR 2026–2032 | 8.5% |
| Peak Annual Growth | 11.4% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Platform Type, 2025 | System-on-Chip (SoC) (40% share) |
| Leading Integration Type, 2025 | Embedded Processing (41% share) |
| Leading Distribution Channel, 2025 | Tech Distributors (38% share) |
| Leading End User, 2025 | AI Product Developers (34% share) |
| Fastest-Growing Platform Type | AI Edge Kits (10.2% CAGR) |
| Fastest-Growing Integration Type | Multi-GPU Integration (10.0% CAGR) |
| Fastest-Growing Distribution Channel | OEM and Resellers (10.7% CAGR) |
| Fastest-Growing End User | Data Center Architects (10.5% CAGR) |
| Growing Sector | AI Research and Development |
| Key End Users | AI Product Developers, Data Center Architects, Robotics Manufacturers |
China AI Hardware Platforms Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
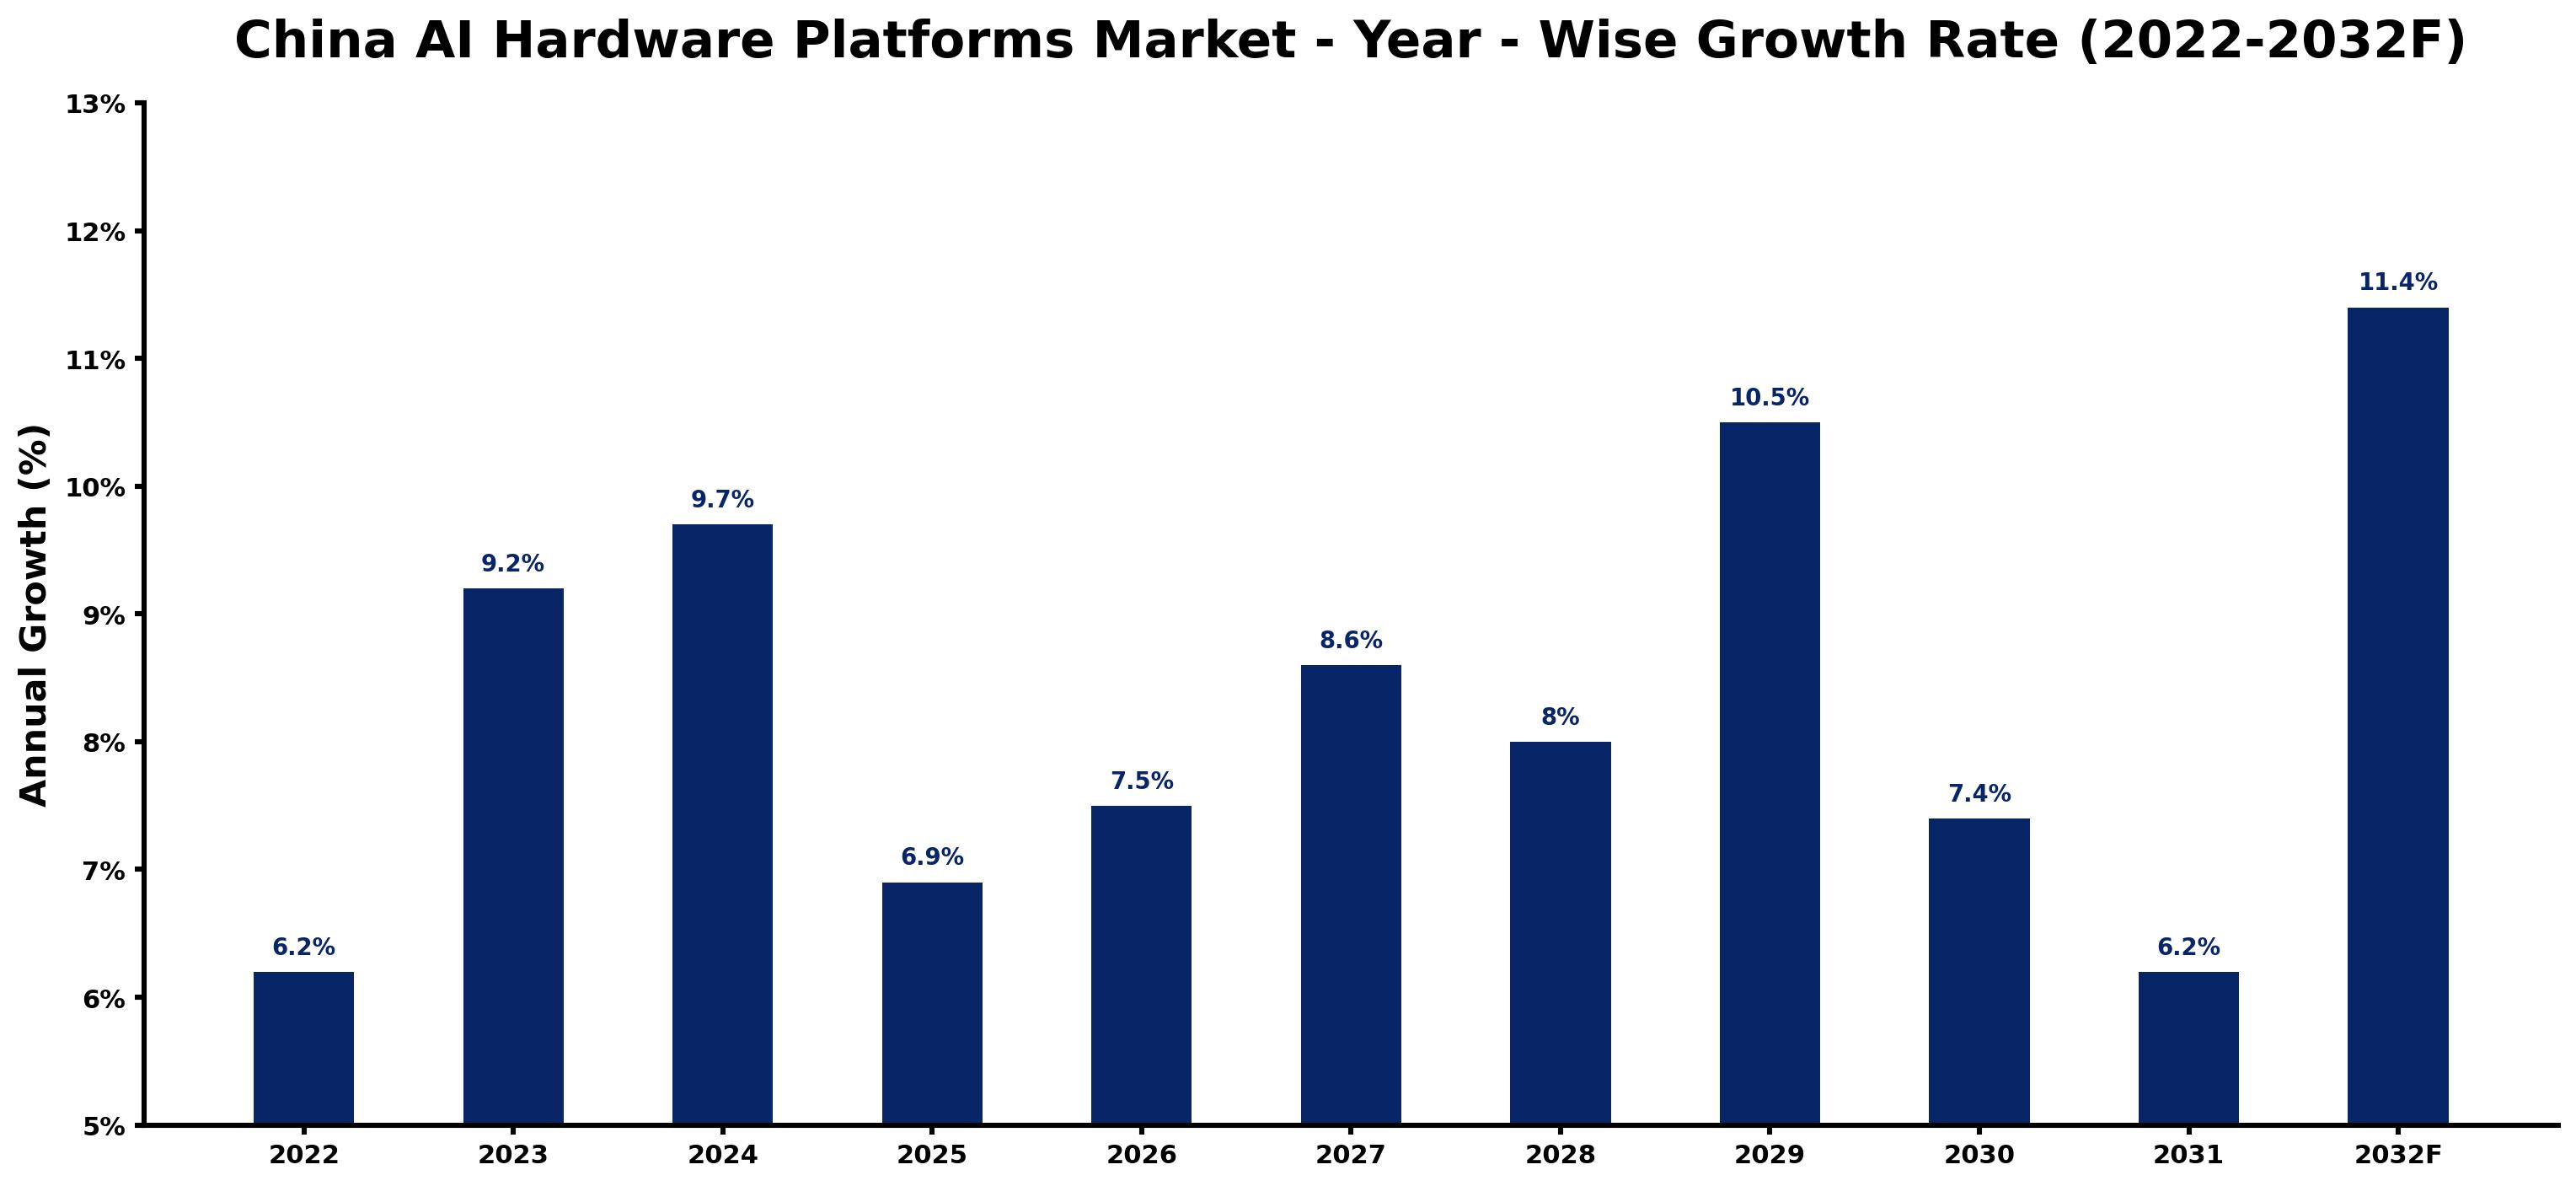
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.2 | The market experienced steady growth, driven by increasing demand from domestic tech firms. |
| 2023 | 9.2 | Demand surged due to significant investments in AI solutions across various sectors, particularly in Shenzhen. |
| 2024 | 9.7 | Growth continued as the National AI Development Plan encouraged advancements in AI hardware capabilities. |
| 2025 | 6.9 | Growth slowed slightly as the market adjusted following rapid expansion in previous years. |
| 2026 | 7.5 | The market is projected to rebound with renewed interest in AI infrastructure development. |
| 2027 | 8.6 | Demand will strengthen as more sectors adopt AI-driven solutions for operational efficiency. |
| 2028 | 8.0 | Growth is expected to decelerate as the market stabilises after rapid expansion. |
| 2029 | 10.5 | Increased investments from data centre architects will drive faster growth in AI hardware. |
| 2030 | 7.4 | Growth will moderate as the market adjusts to evolving technology demands and standards. |
| 2031 | 6.2 | The market will continue to grow, supported by ongoing investments in AI applications and infrastructure. |
| 2032 | 11.4 | Demand is anticipated to peak as the market reaches new heights with advanced AI hardware solutions. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China AI Hardware Platforms Market Synopsis
AI Hardware Platforms in China encompass specialized computing systems tailored for artificial intelligence applications. These systems utilise advanced semiconductor technologies to facilitate machine learning, data processing, and real-time analytics across diverse sectors. The China AI Hardware Platforms Market is on an upward trajectory, with local tech companies accounting for 70% of demand in 2022. The National AI Development Plan aims to establish China as a global leader in AI by 2030, propelling further market growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising domestic demand from technology firms drives investment in AI solutions. | Driver | High | AI Workstations |
| Increasing adoption of AI Edge Kits in smart city projects enhances localized processing capabilities. | Driver | High | AI Edge Kits |
| Investment opportunities exist in AI Workstations, particularly in research institutions. | Opportunity | High | AI Workstations |
| AI Product Developers are expanding their offerings, creating a demand for advanced hardware. | Opportunity | High | AI Product Developers |
| High costs associated with advanced semiconductor technologies can limit accessibility. | Restraint | High | System-on-Chip (SoC) |
| Regulatory compliance with the National Standard for AI Hardware may pose challenges for producers. | Restraint | Medium | Modular AI Boards |
| Supply chain disruptions can delay hardware availability for critical projects. | Challenge | High | AI Workstations |
| Rapid technological advancements require continuous investment, straining budgets for smaller firms. | Challenge | Medium | Data Center Architects |
Evaluation of Drivers in China AI Hardware Platforms Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased investment from tech firms in AI solutions drives demand for AI Workstations. | AI Workstations | In 2022, 70% of AI hardware demand came from domestic technology firms. |
| Growing adoption of AI Edge Kits in smart city projects boosts demand for localized processing. | AI Edge Kits | Over 200 smart city initiatives across multiple provinces are driving the adoption of AI technologies. |
| Data Center Architects are investing heavily in AI infrastructure to support cloud computing needs. | Data Center Architects | Investments in AI infrastructure are projected to reach billions to enhance cloud computing capabilities. |
| The National AI Development Plan supports the growth of AI hardware capabilities. | System-on-Chip (SoC) | The plan allocates 300 billion CNY by 2025 to develop AI hardware solutions. |
| AI Product Developers are rapidly expanding their offerings, increasing demand for advanced hardware. | AI Product Developers | This segment is expected to see rapid growth due to rising demand for AI solutions. |
In 2022, local tech companies accounted for 70% of AI hardware demand, driving the need for advanced solutions. Significant investments are being made in AI infrastructure, with funding reaching billions to support cloud computing needs. The National AI Development Plan aims to develop AI hardware capabilities, further stimulating market growth and innovation.
Evaluation of Restraints in China AI Hardware Platforms Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs associated with advanced semiconductor technologies limit accessibility for smaller firms. | System-on-Chip (SoC) | Producers face challenges in managing production costs, impacting pricing strategies and market entry. |
| Regulatory compliance with the National Standard for AI Hardware can pose challenges for producers. | Modular AI Boards | Producers must invest in quality assurance and testing to meet the established standards. |
| Supply chain disruptions can delay hardware availability for critical projects. | AI Workstations | Disruptions in semiconductor supply chains have affected timely deliveries and project timelines. |
| Limited access to skilled talent can hinder innovation in AI hardware development. | AI Edge Kits | The demand for highly skilled professionals exceeds the available workforce, impacting project execution. |
| Market volatility can create uncertainty for long-term investments in AI hardware. | Data Center Architects | Fluctuations in technology trends can impact project viability and investment decisions. |
China AI Hardware Platforms Market Challenges
The China AI Hardware Platforms market faces high production costs, driven by expensive semiconductor materials and complex manufacturing processes, which inflate prices for domestic tech firms by around 30%. Supply chain disruptions hinder access to essential components, delaying product launches for manufacturers and risking potential revenue losses. Many local firms find it challenging to keep up with rapid technological advancements, leading to outdated products that fail to meet current market demands. Regulatory hurdles, such as the ongoing development of national standards for AI hardware, create uncertainty, delaying product approvals and restricting market entry for suppliers.
Trends in the China AI Hardware Platforms Market
Buyers and suppliers in the China AI Hardware Platforms Market are adjusting to the following trends.
- Shift towards AI Edge Kits in Smart City Projects: Smart city initiatives across various provinces are increasingly adopting AI Edge Kits for localized processing. This shift boosts efficiency and responsiveness in urban management, with over 200 projects reported in 2023.
- Growing Use of AI Workstations in Research Institutions: In 2023, AI Workstations are gaining traction in research institutions in Beijing and Shanghai. This trend bolsters advanced research capabilities, with a reported increase in AI-related research output by 15%.
- Emergence of Multi-GPU Integration for High-Performance Tasks: The demand for Multi-GPU Integration is escalating as AI applications necessitate greater computational power. This trend is particularly pronounced in the gaming and simulation sectors, with a projected growth rate of 10.0% through 2032.
- Development of National Standard for AI Hardware: The establishment of the National Standard for AI Hardware in 2023 aims to regulate quality and performance. This standardisation is anticipated to improve interoperability and consumer confidence in AI products.
Investment Opportunities in the China AI Hardware Platforms Market
The following opportunities in the China AI Hardware Platforms Market pair current demand with a clear way in.
- Investment in AI Workstations for Research: There exists a growing opportunity to supply AI Workstations to research institutions, especially in Beijing and Shanghai, where demand is on the rise. The market for this segment is projected to grow by 50% by 2025.
- Supply of AI Edge Kits for Smart Cities: With the expansion of smart city projects, there is a notable opportunity to supply AI Edge Kits. Demand is expected to increase, particularly in Shenzhen, where over 50 smart city initiatives are in progress.
- Partnerships with Data Center Architects: Now presents an opportune time to collaborate with Data Center Architects to supply advanced AI hardware. The rising investments in AI infrastructure are projected to reach substantial amounts by 2025.
- Expansion into OEM and Reseller Channels: Investing in OEM and Reseller channels offers a timely opportunity as they are anticipated to grow significantly. This segment is projected to expand due to increasing demand from various end-users.
Government Initiatives in the China AI Hardware Platforms Market
The National AI Development Plan, issued by the State Council in 2021, aims to improve AI hardware capabilities with a budget of 300 billion CNY by 2025. This plan encourages investment in AI technologies and supports local manufacturers in developing advanced solutions. The AI Hardware Innovation Program, launched by the Ministry of Industry and Information Technology in 2022, promotes technological advancements and collaboration among industry stakeholders. This initiative is vital for fostering innovation and ensuring that Chinese manufacturers remain competitive in the global market.
The Standardization Administration of China oversees the implementation of the National Standard for AI Hardware, which regulates quality and performance. This ensures that manufacturers meet the required standards, improving product reliability and consumer trust. Additionally, the Smart Manufacturing 2025 initiative encourages the integration of AI hardware in manufacturing processes to boost productivity. This initiative supports manufacturers in adopting AI technologies, enhancing their operational efficiency.
Future Insight of the China AI Hardware Platforms Market
The outlook for the China AI Hardware Platforms market by 2032 indicates a shift towards increased innovation and collaboration. Government initiatives, including the National AI Development Plan, aim to position China as a global leader in AI, driving advancements across multiple sectors. Research institutions will work closely with tech firms to accelerate the development of cutting-edge AI solutions. By 2030, domestic demand for AI hardware is expected to reach 70%, primarily fueled by local technology firms pursuing enhanced capabilities.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Platform Type – System-on-Chip (SoC) Dominated, AI Edge Kits Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, in 2025, System-on-Chip (SoC) led the platform type split with a 40% share. System-on-Chip (SoC) holds the largest market share due to its essential role in compact solutions, particularly in consumer electronics. Its widespread use in smart devices across urban centres like Shenzhen exemplifies its dominance in the market. Over 2026–2032, AI Edge Kits are expected to post the fastest growth, at a CAGR of 10.2%. AI Edge Kits are witnessing rapid growth as they enable localized processing for IoT devices, catering to the rising demand for smart city projects. The acceleration of smart city implementations across multiple provinces is a significant factor driving this segment's expansion. Suppliers should enhance their offerings in AI Edge Kits to capitalise on the growing demand from urban development initiatives.
By Integration Type – Embedded Processing Dominated, Multi-GPU Integration Expected to Grow Fastest
With a 41% revenue share in 2025, Embedded Processing was the largest integration type category. Embedded Processing leads the market share as it is widely utilised in specific applications, particularly within the hardware ecosystem. Its integration in various devices ensures consistent performance, appealing to developers across diverse sectors. Multi-GPU Integration is set to record the highest CAGR in this split, 10.0% over 2026–2032. Multi-GPU Integration is set for rapid growth, driven by its critical role in high-performance tasks, especially in data-intensive applications. The increasing complexity of models necessitates this integration, propelling its market presence significantly. Buyers should consider investing in Multi-GPU Integration solutions to remain competitive in high-performance applications.
By Distribution Channel – Tech Distributors Dominated, OEM and Resellers Expected to Grow Fastest
The largest distribution channel category in 2025 was Tech Distributors, with a 38% share of total revenue. Tech Distributors command the largest market share as they serve as a key channel for reaching various end-users, ensuring widespread availability of hardware platforms. Their established networks facilitate effective distribution across multiple sectors, enhancing market penetration. OEM and Resellers are projected to grow fastest, at a CAGR of 10.7% during 2026–2032. OEM and Resellers are poised for rapid growth, as they play an important role in broad distribution, particularly for customised solutions. The increasing demand for tailored hardware solutions is driving this segment's expansion significantly. Suppliers should strengthen partnerships with OEMs and Resellers to enhance their market reach and cater to diverse customer needs.
By End User – AI Product Developers Dominated, Data Center Architects Expected to Grow Fastest
AI Product Developers accounted for a 34% market share by end user in 2025. AI Product Developers dominate the market share as the primary users driving demand for hardware platforms, particularly in software and application development. Their continuous innovation in solutions fuels the overall market growth, making them pivotal in the ecosystem. The quickest growth will come from Data Center Architects, forecast to expand at a CAGR of 10.5% between 2026 and 2032. Data Center Architects are experiencing rapid growth, as they are essential for infrastructure development in cloud computing environments. The surge in cloud services and increasing data processing requirements are propelling this segment forward significantly. Buyers in the hardware market should align their strategies with the needs of Data Center Architects to ensure robust infrastructure support.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China AI Hardware Platforms Market Outlook
- Market Size of China AI Hardware Platforms Market, 2025
- Forecast of China AI Hardware Platforms Market, 2032
- Historical Data and Forecast of China AI Hardware Platforms Revenues & Volume for the Period 2022 - 2032F
- China AI Hardware Platforms Market Trend Evolution
- China AI Hardware Platforms Market Drivers and Challenges
- China AI Hardware Platforms Price Trends
- China AI Hardware Platforms Porter's Five Forces
- China AI Hardware Platforms Industry Life Cycle
- Historical Data and Forecast of China AI Hardware Platforms Market Revenues & Volume By Platform Type for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Platforms Market Revenues & Volume By Modular AI Boards for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Platforms Market Revenues & Volume By System-on-Chip (SoC) for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Platforms Market Revenues & Volume By AI Edge Kits for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Platforms Market Revenues & Volume By AI Workstations for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Platforms Market Revenues & Volume By Integration Type for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Platforms Market Revenues & Volume By Plug-and-Play Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Platforms Market Revenues & Volume By Embedded Processing for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Platforms Market Revenues & Volume By Pre-configured Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Platforms Market Revenues & Volume By Multi-GPU Integration for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Platforms Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Platforms Market Revenues & Volume By IoT Hardware Stores for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Platforms Market Revenues & Volume By Tech Distributors for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Platforms Market Revenues & Volume By Developer Marketplaces for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Platforms Market Revenues & Volume By OEM and Resellers for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Platforms Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Platforms Market Revenues & Volume By AI Product Developers for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Platforms Market Revenues & Volume By Robotics Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Platforms Market Revenues & Volume By Industrial AI Integrators for the Period 2022 - 2032F
- Historical Data and Forecast of China AI Hardware Platforms Market Revenues & Volume By Data Center Architects for the Period 2022 - 2032F
- China AI Hardware Platforms Import Export Trade Statistics
- Market Opportunity Assessment By Platform Type
- Market Opportunity Assessment By Integration Type
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China AI Hardware Platforms Top Companies Market Share
- China AI Hardware Platforms Competitive Benchmarking By Technical and Operational Parameters
- China AI Hardware Platforms Company Profiles
- China AI Hardware Platforms Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Platform Type
- Modular AI Boards
- System-on-Chip (SoC)
- AI Edge Kits
- AI Workstations
By Integration Type
- Plug-and-Play Systems
- Embedded Processing
- Pre-configured Platforms
- Multi-GPU Integration
By Distribution Channel
- IoT Hardware Stores
- Tech Distributors
- Developer Marketplaces
- OEM and Resellers
By End User
- AI Product Developers
- Robotics Manufacturers
- Industrial AI Integrators
- Data Center Architects































