China AI SoC (System on Chip) Market Size & Growth Rate
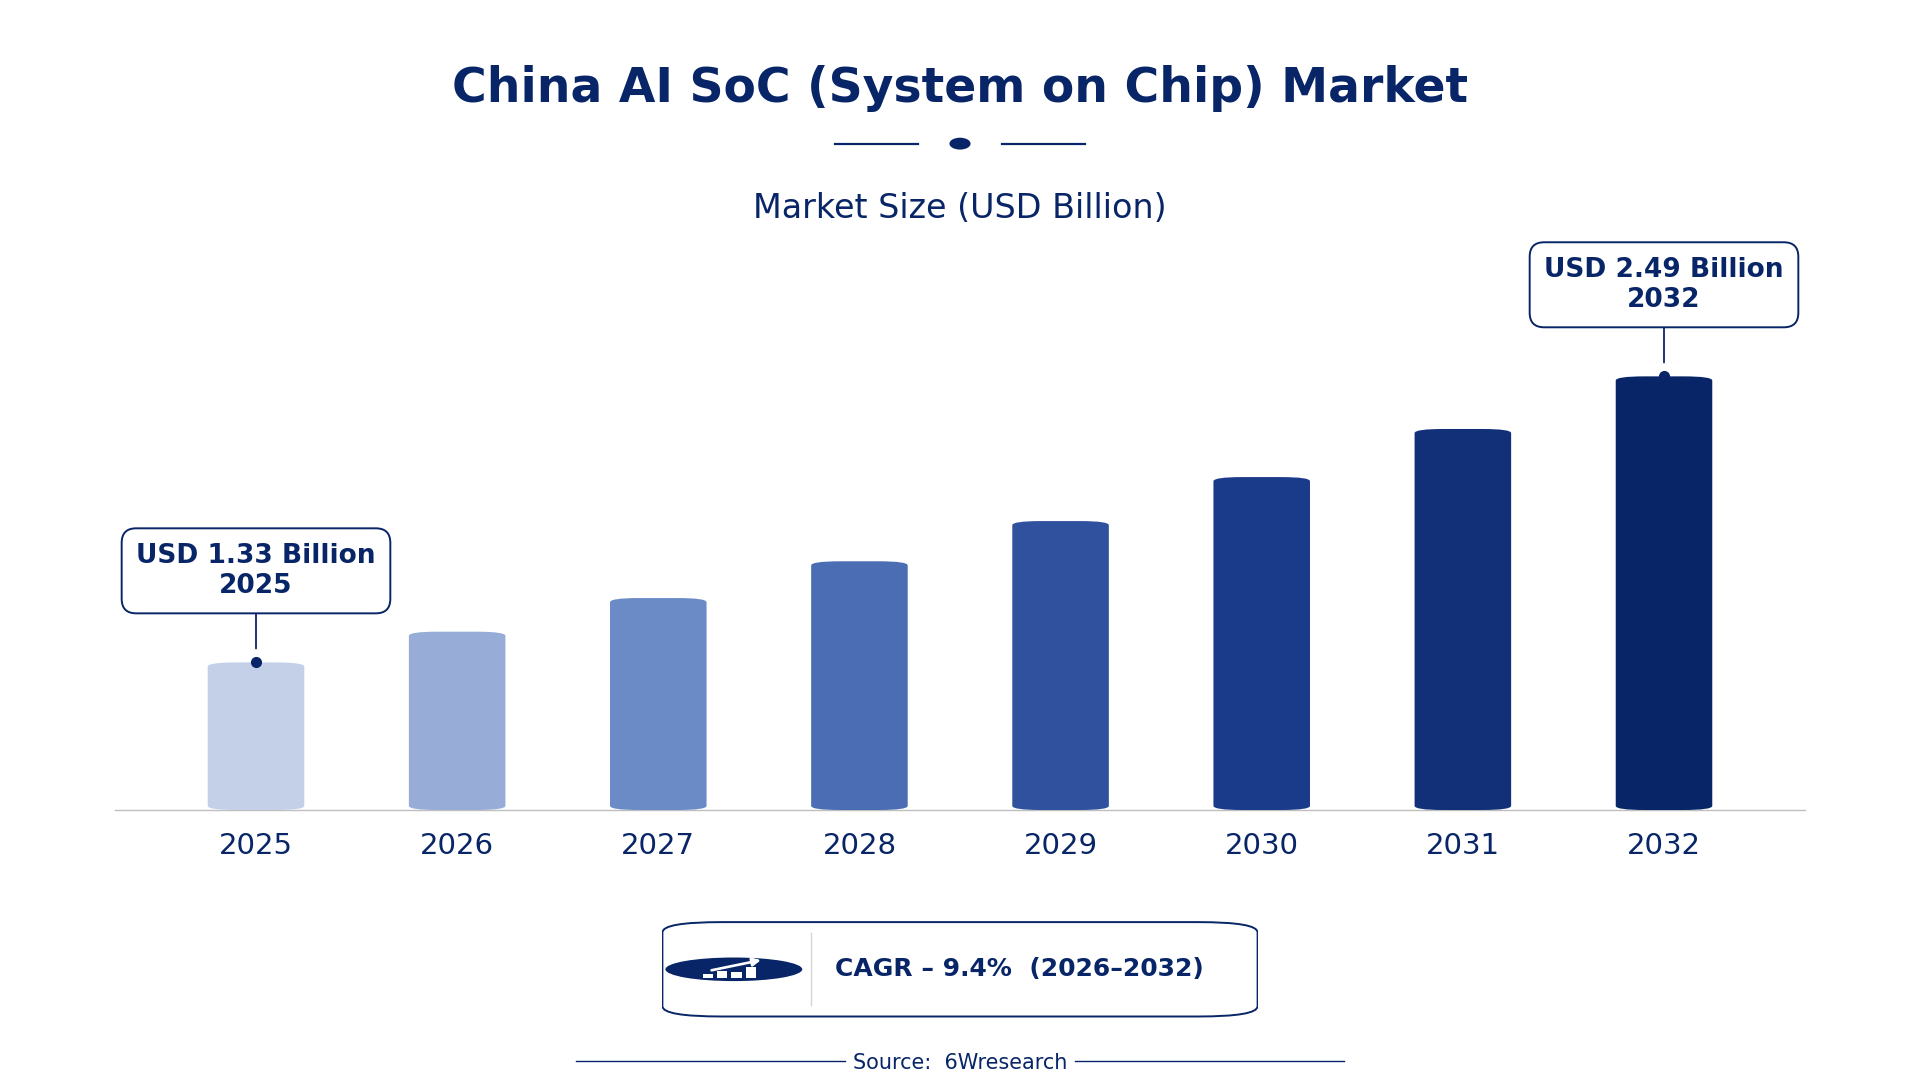
According to 6Wresearch internal database and industry insights, the China AI SoC (System on Chip) Market was valued at USD 1.33 billion in 2025 and is projected to reach USD 2.49 billion by 2032, growing at a CAGR of approximately 9.4% during 2026–2032.
China AI SoC (System on Chip) Market Highlights
| Report Metric | Details |
| Report Name | China AI SoC (System on Chip) Market |
| Market Size 2025 | USD 1.33 billion |
| Market Size 2032 | USD 2.49 billion |
| Absolute Growth 2025–2032 | USD 1.16 billion |
| CAGR 2026–2032 | 9.4% |
| Peak Annual Growth | 11.8% in 2029 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading SoC Type, 2025 | Mobile AI SoCs (37% share) |
| Leading Target Application, 2025 | Real-Time Processing (45% share) |
| Leading Distribution Channel, 2025 | OEM Partnerships (51% share) |
| Leading End User, 2025 | Smartphone Companies (49% share) |
| Fastest-Growing SoC Type | Embedded AI SoCs (10.9% CAGR) |
| Fastest-Growing Target Application | Vision AI (11.9% CAGR) |
| Fastest-Growing End User | EV Companies (10.7% CAGR) |
| Growing Sector | automotive applications |
| Key End Users | automotive manufacturers, IoT device manufacturers, smartphone companies, consumer electronics firms |
China AI SoC (System on Chip) Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
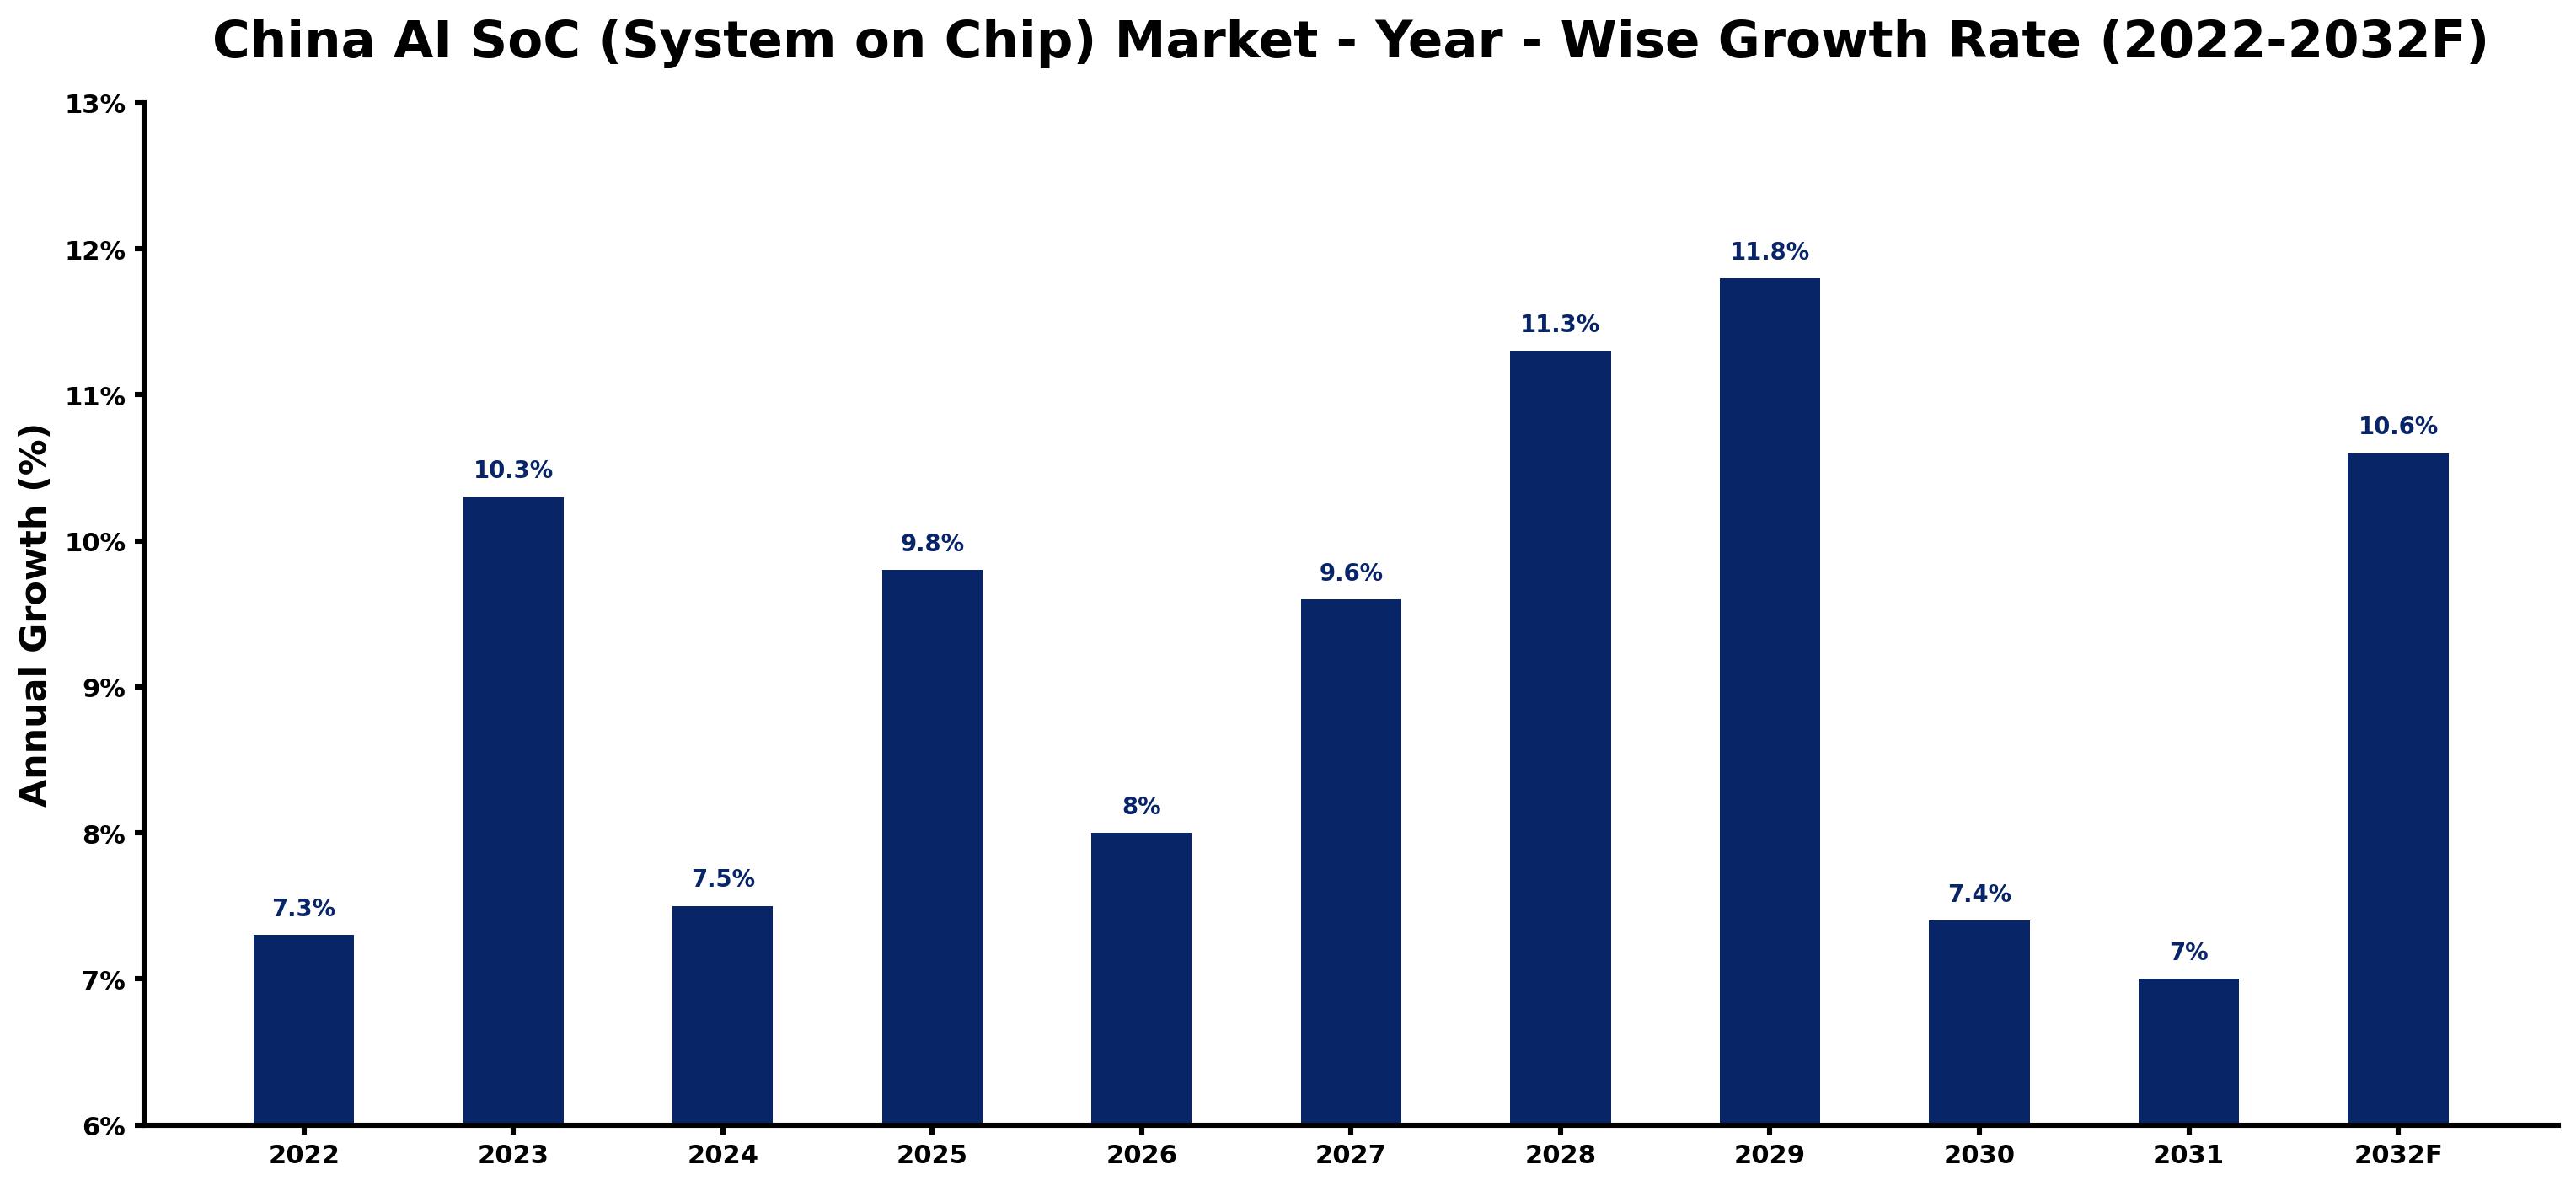
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.3 | The market experienced steady growth due to increasing demand from IoT device manufacturers. |
| 2023 | 10.3 | Growth accelerated as the installed base of AI SoCs in IoT devices reached 300 million units. |
| 2024 | 7.5 | A slight slowdown occurred as the market adjusted to previous rapid growth rates in automotive applications. |
| 2025 | 9.8 | Demand increased again, driven by the automotive sector's integration of AI SoCs in new vehicles. |
| 2026 | 8.0 | Growth is anticipated to slow due to the impact of the GB/T 34590-2017 standard on production processes. |
| 2027 | 9.6 | The market is projected to rebound as investments in the 'AI Semiconductor Research Program' surge. |
| 2028 | 11.3 | Growth is expected to accelerate as the automotive sector continues to adopt AI SoCs for advanced features. |
| 2029 | 11.8 | The peak growth rate is expected to be achieved as innovation in AI technology drives further demand. |
| 2030 | 7.4 | A slowdown is anticipated as the market stabilises after rapid expansion in previous years. |
| 2031 | 7.0 | Growth is projected to continue to slow as the market matures and competition intensifies. |
| 2032 | 10.6 | Demand is expected to surge again, driven by new applications in consumer electronics and automotive sectors. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China AI SoC (System on Chip) Market Synopsis
The AI SoC (System on Chip) Market in China includes semiconductor devices tailored for artificial intelligence tasks. These chips combine processing units, memory, and AI-specific hardware, crucial for improving performance in automotive applications and mobile devices. The market is poised for growth driven by the demands of China's 1.4 billion population, with over 1 billion AI SoCs produced in 2022. The automotive sector is expected to incorporate AI SoCs in 80% of new vehicles by 2025, further propelling growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing demand for AI SoCs in automotive applications is driving significant investments in technology. | Driver | High | Automotive AI SoCs |
| Increasing integration of AI SoCs in IoT devices creates new market opportunities. | Driver | High | AI for Edge Devices |
| The surge in demand for AI SoCs in consumer electronics presents a lucrative opportunity for suppliers. | Opportunity | High | Mobile AI SoCs |
| Investment in AI semiconductor research is increasing, opening avenues for innovation. | Opportunity | High | Embedded AI SoCs |
| High production costs for AI SoCs can limit profitability for manufacturers. | Restraint | High | Embedded AI SoCs |
| Competition from international semiconductor firms may constrain market share for local producers. | Restraint | High | AI for Edge Devices |
| The AI SoC market in China faces challenges from fluctuating raw material prices, affecting production costs. | Challenge | High | Automotive AI SoCs |
| Technological advancements in competing regions may pose a threat to local market growth. | Challenge | Medium | Mobile AI SoCs |
Evaluation of Drivers in China AI SoC (System on Chip) Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Demand for advanced driver-assistance systems boosts the need for Automotive AI SoCs. | Automotive AI SoCs | The automotive sector in China is set to integrate AI SoCs in 80% of new vehicles by 2025. |
| Growing adoption of smart devices drives demand for AI for Edge Devices. | AI for Edge Devices | China's population of 1.4 billion drives substantial demand for consumer electronics using AI SoCs. |
| Increased production of mobile devices fuels the market for Mobile AI SoCs. | Mobile AI SoCs | The demand for AI SoCs in mobile applications is expected to reach 500 million units by 2025. |
| The push for real-time data processing in various sectors boosts demand for Real-Time Processing AI SoCs. | Real-Time Processing | The Real-Time Processing segment is expected to capture 45% of the total SoC market by 2025. |
| Collaborations through OEM Partnerships are essential for expanding market reach. | OEM Partnerships | OEM Partnerships hold a 51% share in the distribution channel for AI SoCs. |
Growth in the AI SoC (System on Chip) market in China stems from the increasing demand for advanced driver-assistance systems and a rise in mobile device production. The automotive sector is projected to integrate AI SoCs in 80% of new vehicles by 2025, which will boost demand. With a population of 1.4 billion, consumer electronics demand is substantial, and AI SoCs in mobile applications are expected to reach 500 million units by 2025. The Real-Time Processing segment is forecasted to represent 45% of the total SoC market by 2025, highlighting the importance of immediate data analysis. Collaborations through OEM Partnerships, which account for a 51% share in the distribution channel, further support market growth.
Evaluation of Restraints in China AI SoC (System on Chip) Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High production costs can limit profitability for manufacturers of Embedded AI SoCs. | Embedded AI SoCs | Production costs for AI SoCs are rising, impacting profit margins for manufacturers. |
| Competition from international firms may constrain market share for local producers in AI for Edge Devices. | AI for Edge Devices | Local producers face increasing competition from established international semiconductor companies. |
| Fluctuating raw material prices can disrupt production schedules for Automotive AI SoCs. | Automotive AI SoCs | Raw material price volatility affects the cost structure and reliability of supply chains. |
| Technological advancements in competing regions may threaten local market growth for Mobile AI SoCs. | Mobile AI SoCs | Emerging technologies in other regions could outpace local developments, affecting competitiveness. |
| Limited access to advanced fabrication technologies can hinder innovation in Embedded AI SoCs. | Embedded AI SoCs | Local manufacturers may struggle to access advanced semiconductor fabrication technologies. |
China AI SoC (System on Chip) Market Challenges
The China AI SoC market faces a few practical problems, beginning with intense competition among local producers, which drives down prices and squeezes profit margins for manufacturers. This situation arises from the rapid expansion of the electronics industry in Guangdong province, compelling suppliers to reduce costs and often sacrificing product quality. Rapid technological advancements in AI SoC design create challenges for manufacturers, causing delays in product launches and hindering buyers' access to the latest innovations. Skills shortages in semiconductor design further complicate matters, leading to production delays and increased expenses for producers. Supply chain disruptions also impact the availability of essential raw materials, resulting in longer lead times and elevated costs for manufacturers.
Trends in the China AI SoC (System on Chip) Market
The trends below show where the China AI SoC (System on Chip) Market is heading.
- Shift towards AI Integration in Automotive Sector: Automotive manufacturers are increasingly incorporating AI SoCs for vehicle intelligence. By 2025, 80% of new vehicles are expected to integrate these technologies, transforming the automotive sector.
- Transition from Traditional to Smart Devices: The market is moving towards smart devices that utilise AI SoCs for improved functionality. In 2023, the installed base of AI SoCs in IoT devices reached 300 million units, indicating a strong trend towards smart technology.
- Emergence of Real-Time Processing Applications: Real-Time Processing is becoming a leading application for AI SoCs, driven by demand for immediate data analysis. This segment is expected to capture 45% of the market share by 2025, reflecting its growing importance.
- Prioritisation of OEM Partnerships: OEM Partnerships are increasingly vital for market success, holding a 51% share in distribution channels. This trend highlights the need for collaboration in product development to meet rising demand.
Investment Opportunities in the China AI SoC (System on Chip) Market
Below are the investment opportunities with the strongest case in the China AI SoC (System on Chip) Market.
- Establishing Collaborations with Local Manufacturers: Building partnerships with local manufacturers is timely, as the AI SoC market is set to see a 25% increase in investment by 2025. Collaborating with IoT device manufacturers can facilitate market entry.
- Investment in AI Semiconductor Research: With the National Development and Reform Commission allocating 500 million CNY for AI semiconductor research, there is an opportunity to invest in innovative technologies. Engaging with research institutions can yield fruitful collaborations.
- Supply of Advanced AI SoCs for Automotive Applications: The automotive sector's projected integration of AI SoCs in 80% of new vehicles by 2025 presents a strong opportunity. Targeting vehicle OEMs can facilitate market entry and growth.
- Expansion in Consumer Electronics: The demand for AI SoCs in mobile applications is anticipated to reach 500 million units by 2025, indicating a substantial market gap. Focusing on smartphone companies can lead to lucrative business opportunities.
Government Initiatives in the China AI SoC (System on Chip) Market
The Ministry of Science and Technology initiated the 'AI Semiconductor Research Program' in 2020 with a budget of 1 billion CNY to support research and development in AI SoCs. The National Development and Reform Commission approved the 'National Semiconductor Innovation Strategy' in 2022, aiming to increase local semiconductor production by 30% by 2025. These initiatives are designed to assist manufacturers in reducing production costs and encouraging innovation in AI SoCs. The Ministry of Industry and Information Technology also launched the 'AI SoC Development Plan' in 2023 to enhance domestic production capabilities and innovation in semiconductor technology.
The National Development and Reform Commission oversees funding for AI semiconductor research, approving 500 million CNY in 2023. The Ministry of Industry and Information Technology plays a role in implementing the 'AI SoC Development Plan', which aims to boost domestic production capabilities. These measures are important for supporting manufacturers in enhancing their production processes and reducing costs.
Future Insight of the China AI SoC (System on Chip) Market
Several forward-looking factors should support the China AI SoC market through 2032. The 'AI SoC Development Plan' introduced in 2023 is set to stimulate innovation, improving product capabilities and attracting new buyers. By 2025, the automotive sector is expected to integrate AI SoCs in 80% of new vehicles, significantly increasing demand. Investment in AI semiconductor research is projected to rise by 25% by 2025, providing manufacturers with critical resources for development. The 'Digital China' initiative will further encourage the adoption of AI technologies across various sectors, driving market expansion.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By SoC Type – Mobile AI SoCs Dominated, Embedded AI SoCs Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, Mobile AI SoCs held a 37% share of the China AI SoC (System on Chip) Market by soc type in 2025. Mobile AI SoCs hold the largest market share due to their essential role in smartphones, which are widely adopted across China. The extensive production of over 1 billion AI SoCs in 2022 underscores the high demand for advanced functionalities in mobile devices. Embedded AI SoCs are projected to grow fastest, at a CAGR of 10.9% during 2026–2032. Embedded AI SoCs are experiencing rapid growth as they are increasingly integrated into various consumer electronics for immediate processing tasks. The anticipated 25% rise in investment for semiconductor technologies by 2025 is expected to further accelerate this segment's expansion. Suppliers should enhance their mobile AI SoC offerings while also investing in embedded solutions to capture emerging opportunities.
By Target Application – Real-Time Processing Dominated, Vision AI Expected to Grow Fastest
The largest target application category in 2025 was Real-Time Processing, with a 45% share of total revenue. Real-Time Processing leads the application segment as it is critical for tasks requiring immediate data analysis across various industries. The rising demand for quick decision-making in consumer electronics solidifies this segment's dominant position. The quickest growth will come from Vision AI, forecast to expand at a CAGR of 11.9% between 2026 and 2032. Vision AI is the fastest-growing application, vital for image processing and recognition tasks that are becoming more prevalent in consumer devices. The increasing focus on advanced imaging capabilities in smartphones and security systems will drive this segment's growth. Buyers should prioritise solutions that improve real-time processing and vision AI capabilities to remain competitive in the fast-paced market.
By Distribution Channel – OEM Partnerships Dominated and Is Expected to Record the Fastest Growth
OEM Partnerships accounted for a 51% market share by distribution channel in 2025. OEM Partnerships dominate the distribution landscape as they are crucial for collaborative product development, enabling tailored solutions that meet market demands. This channel's prominence is evidenced by its substantial share in the AI SoC market. The same category are also set to grow fastest, at a CAGR of 10.5% during 2026–2032. OEM Partnerships are also the fastest-growing channel, as manufacturers seek to enhance their product offerings through strategic collaborations. The ongoing emphasis on integrating AI technologies across various sectors will further strengthen this channel's significance. Suppliers must focus on strengthening their OEM partnerships to leverage collaborative opportunities and drive market growth.
By End User – Smartphone Companies Dominated, EV Companies Expected to Grow Fastest
Smartphone Companies took a 49% share of end user in 2025, more than any other category. Smartphone Companies represent the largest end-user group, relying heavily on AI SoCs to enhance device capabilities for a vast consumer base in China. The projected installed base of AI SoCs in mobile applications reaching 500 million units by 2025 highlights this segment's importance. EV Companies are set to record the highest CAGR in this split, 10.7% over 2026–2032. EV Companies are the fastest-growing end-user segment, utilising AI SoCs for automation and efficiency in the rapidly expanding electric vehicle market. With projections of China's EV market reaching 10 million units by 2025, this segment is poised for significant growth. Suppliers should tailor their products to meet the specific needs of smartphone and EV companies to maximise their market share.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China AI SoC (System on Chip) Market Outlook
- Market Size of China AI SoC (System on Chip) Market, 2025
- Forecast of China AI SoC (System on Chip) Market, 2032
- Historical Data and Forecast of China AI SoC (System on Chip) Revenues & Volume for the Period 2022 - 2032F
- China AI SoC (System on Chip) Market Trend Evolution
- China AI SoC (System on Chip) Market Drivers and Challenges
- China AI SoC (System on Chip) Price Trends
- China AI SoC (System on Chip) Porter's Five Forces
- China AI SoC (System on Chip) Industry Life Cycle
- Historical Data and Forecast of China AI SoC (System on Chip) Market Revenues & Volume By SoC Type for the Period 2022 - 2032F
- Historical Data and Forecast of China AI SoC (System on Chip) Market Revenues & Volume By AI for Edge Devices for the Period 2022 - 2032F
- Historical Data and Forecast of China AI SoC (System on Chip) Market Revenues & Volume By Embedded AI SoCs for the Period 2022 - 2032F
- Historical Data and Forecast of China AI SoC (System on Chip) Market Revenues & Volume By Automotive AI SoCs for the Period 2022 - 2032F
- Historical Data and Forecast of China AI SoC (System on Chip) Market Revenues & Volume By Mobile AI SoCs for the Period 2022 - 2032F
- Historical Data and Forecast of China AI SoC (System on Chip) Market Revenues & Volume By Target Application for the Period 2022 - 2032F
- Historical Data and Forecast of China AI SoC (System on Chip) Market Revenues & Volume By Smart Inference for the Period 2022 - 2032F
- Historical Data and Forecast of China AI SoC (System on Chip) Market Revenues & Volume By Real-Time Processing for the Period 2022 - 2032F
- Historical Data and Forecast of China AI SoC (System on Chip) Market Revenues & Volume By Sensor Fusion & Driving for the Period 2022 - 2032F
- Historical Data and Forecast of China AI SoC (System on Chip) Market Revenues & Volume By NLP, Vision AI for the Period 2022 - 2032F
- Historical Data and Forecast of China AI SoC (System on Chip) Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China AI SoC (System on Chip) Market Revenues & Volume By OEM Partnerships for the Period 2022 - 2032F
- Historical Data and Forecast of China AI SoC (System on Chip) Market Revenues & Volume By Chipset Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China AI SoC (System on Chip) Market Revenues & Volume By Vehicle OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China AI SoC (System on Chip) Market Revenues & Volume By Consumer Electronics Stores for the Period 2022 - 2032F
- Historical Data and Forecast of China AI SoC (System on Chip) Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China AI SoC (System on Chip) Market Revenues & Volume By IoT Device Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China AI SoC (System on Chip) Market Revenues & Volume By Wearables Firms for the Period 2022 - 2032F
- Historical Data and Forecast of China AI SoC (System on Chip) Market Revenues & Volume By EV Companies for the Period 2022 - 2032F
- Historical Data and Forecast of China AI SoC (System on Chip) Market Revenues & Volume By Smartphone Companies for the Period 2022 - 2032F
- China AI SoC (System on Chip) Import Export Trade Statistics
- Market Opportunity Assessment By SoC Type
- Market Opportunity Assessment By Target Application
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China AI SoC (System on Chip) Top Companies Market Share
- China AI SoC (System on Chip) Competitive Benchmarking By Technical and Operational Parameters
- China AI SoC (System on Chip) Company Profiles
- China AI SoC (System on Chip) Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By SoC Type
- AI for Edge Devices
- Embedded AI SoCs
- Automotive AI SoCs
- Mobile AI SoCs
By Target Application
- Smart Inference
- Real-Time Processing
- Sensor Fusion & Driving
- NLP
- Vision AI
By Distribution Channel
- OEM Partnerships
- Chipset Suppliers
- Vehicle OEMs
- Consumer Electronics Stores
By End User
- IoT Device Manufacturers
- Wearables Firms
- EV Companies
- Smartphone Companies































