China Implantable Materials Market Size & Growth Rate
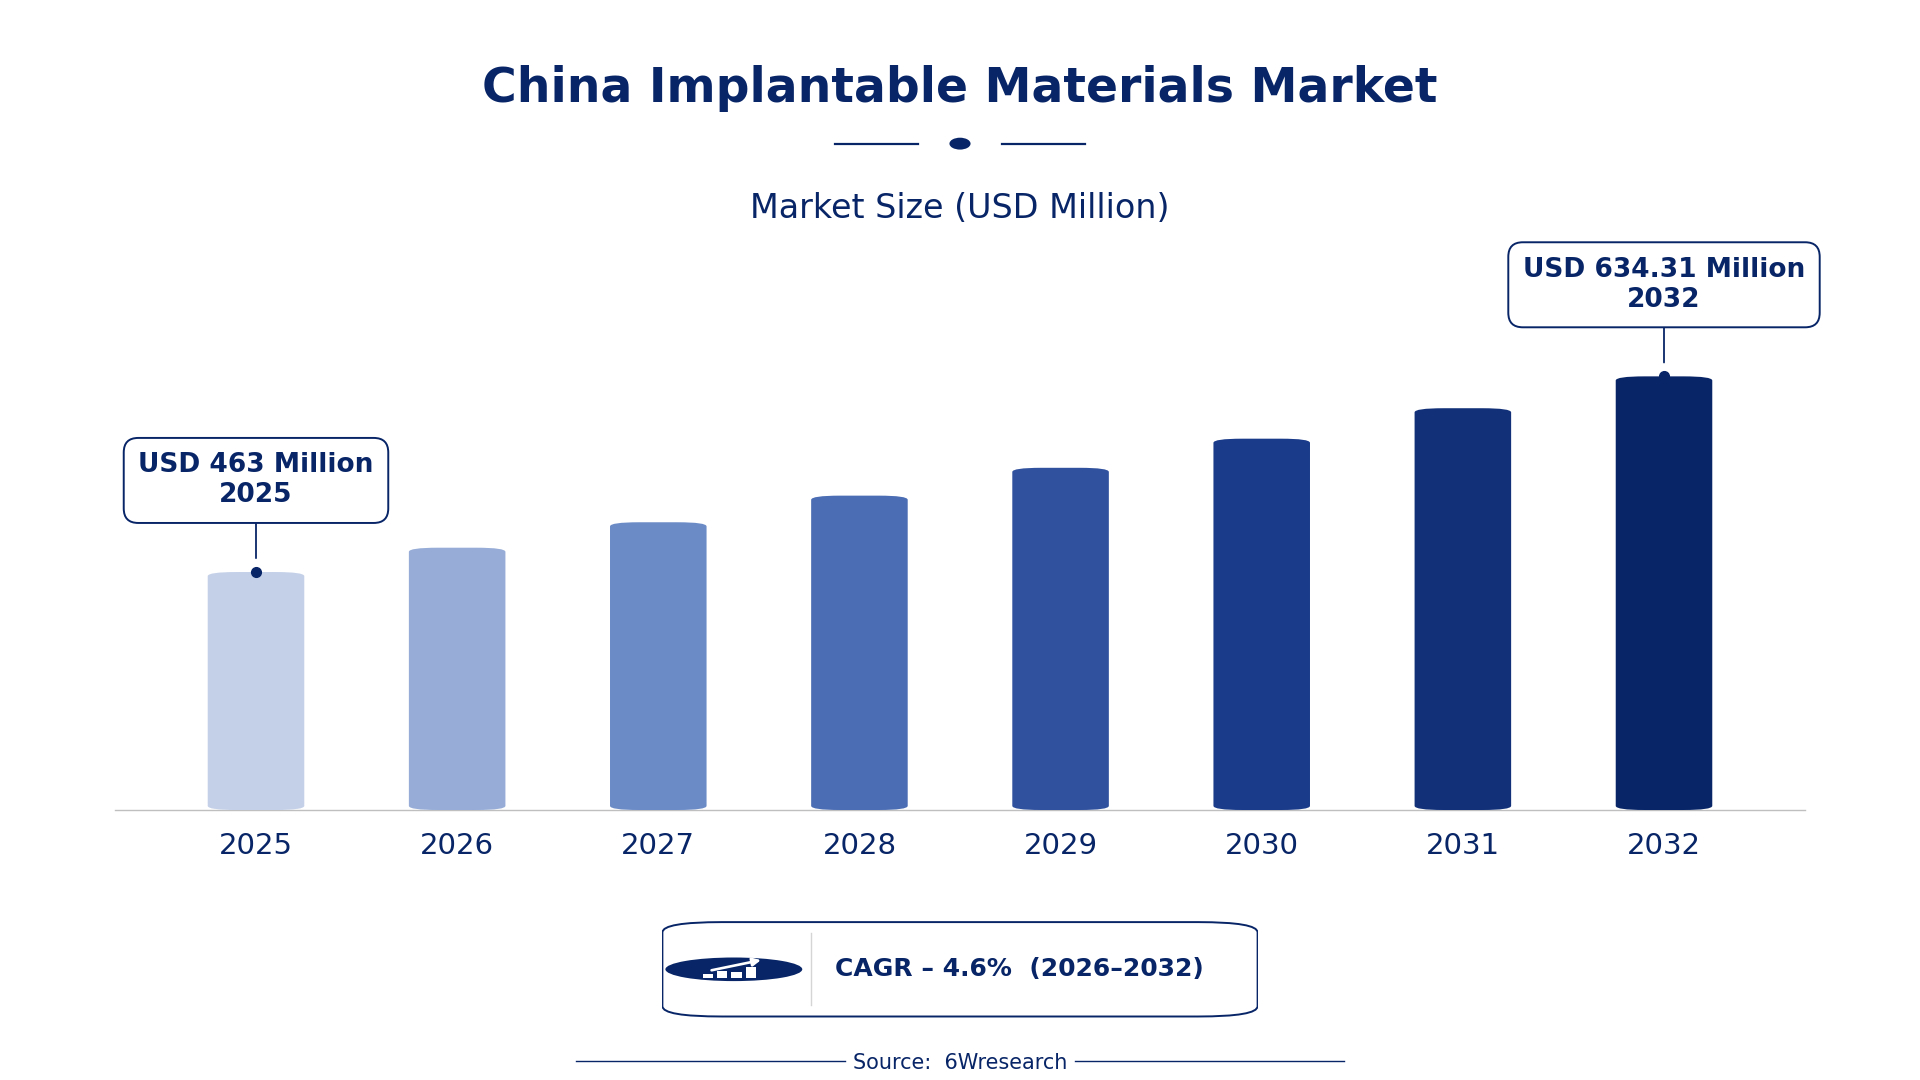
According to 6Wresearch internal database and industry insights, the China Implantable Materials Market was valued at USD 463.0 million in 2025 and is projected to reach USD 634.31 million by 2032, growing at a CAGR of approximately 4.6% during 2026–2032.
China Implantable Materials Market Highlights
| Report Metric | Details |
| Report Name | China Implantable Materials Market |
| Market Size 2025 | USD 463.0 million |
| Market Size 2032 | USD 634.31 million |
| Absolute Growth 2025–2032 | USD 171.31 million |
| CAGR 2026–2032 | 4.6% |
| Peak Annual Growth | 6.5% in 2027 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Material Type, 2025 | Titanium Alloys (45% share) |
| Leading Use Case, 2025 | Bone/Joint Implants (39% share) |
| Leading Biocompatibility Level, 2025 | High (33% share) |
| Leading End User, 2025 | Orthopedic Implant Firms (42% share) |
| Fastest-Growing Material Type | PEEK (Polyether ether ketone) (7.1% CAGR) |
| Fastest-Growing Use Case | Spinal & Dental (7.3% CAGR) |
| Fastest-Growing Biocompatibility Level | Excellent (7.0% CAGR) |
| Fastest-Growing End User | Medical Material Suppliers (6.2% CAGR) |
| Growing Sector | Orthopedic implants |
| Key End Users | Orthopedic Implant Firms, Biomedical OEMs, Medical Material Suppliers |
China Implantable Materials Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
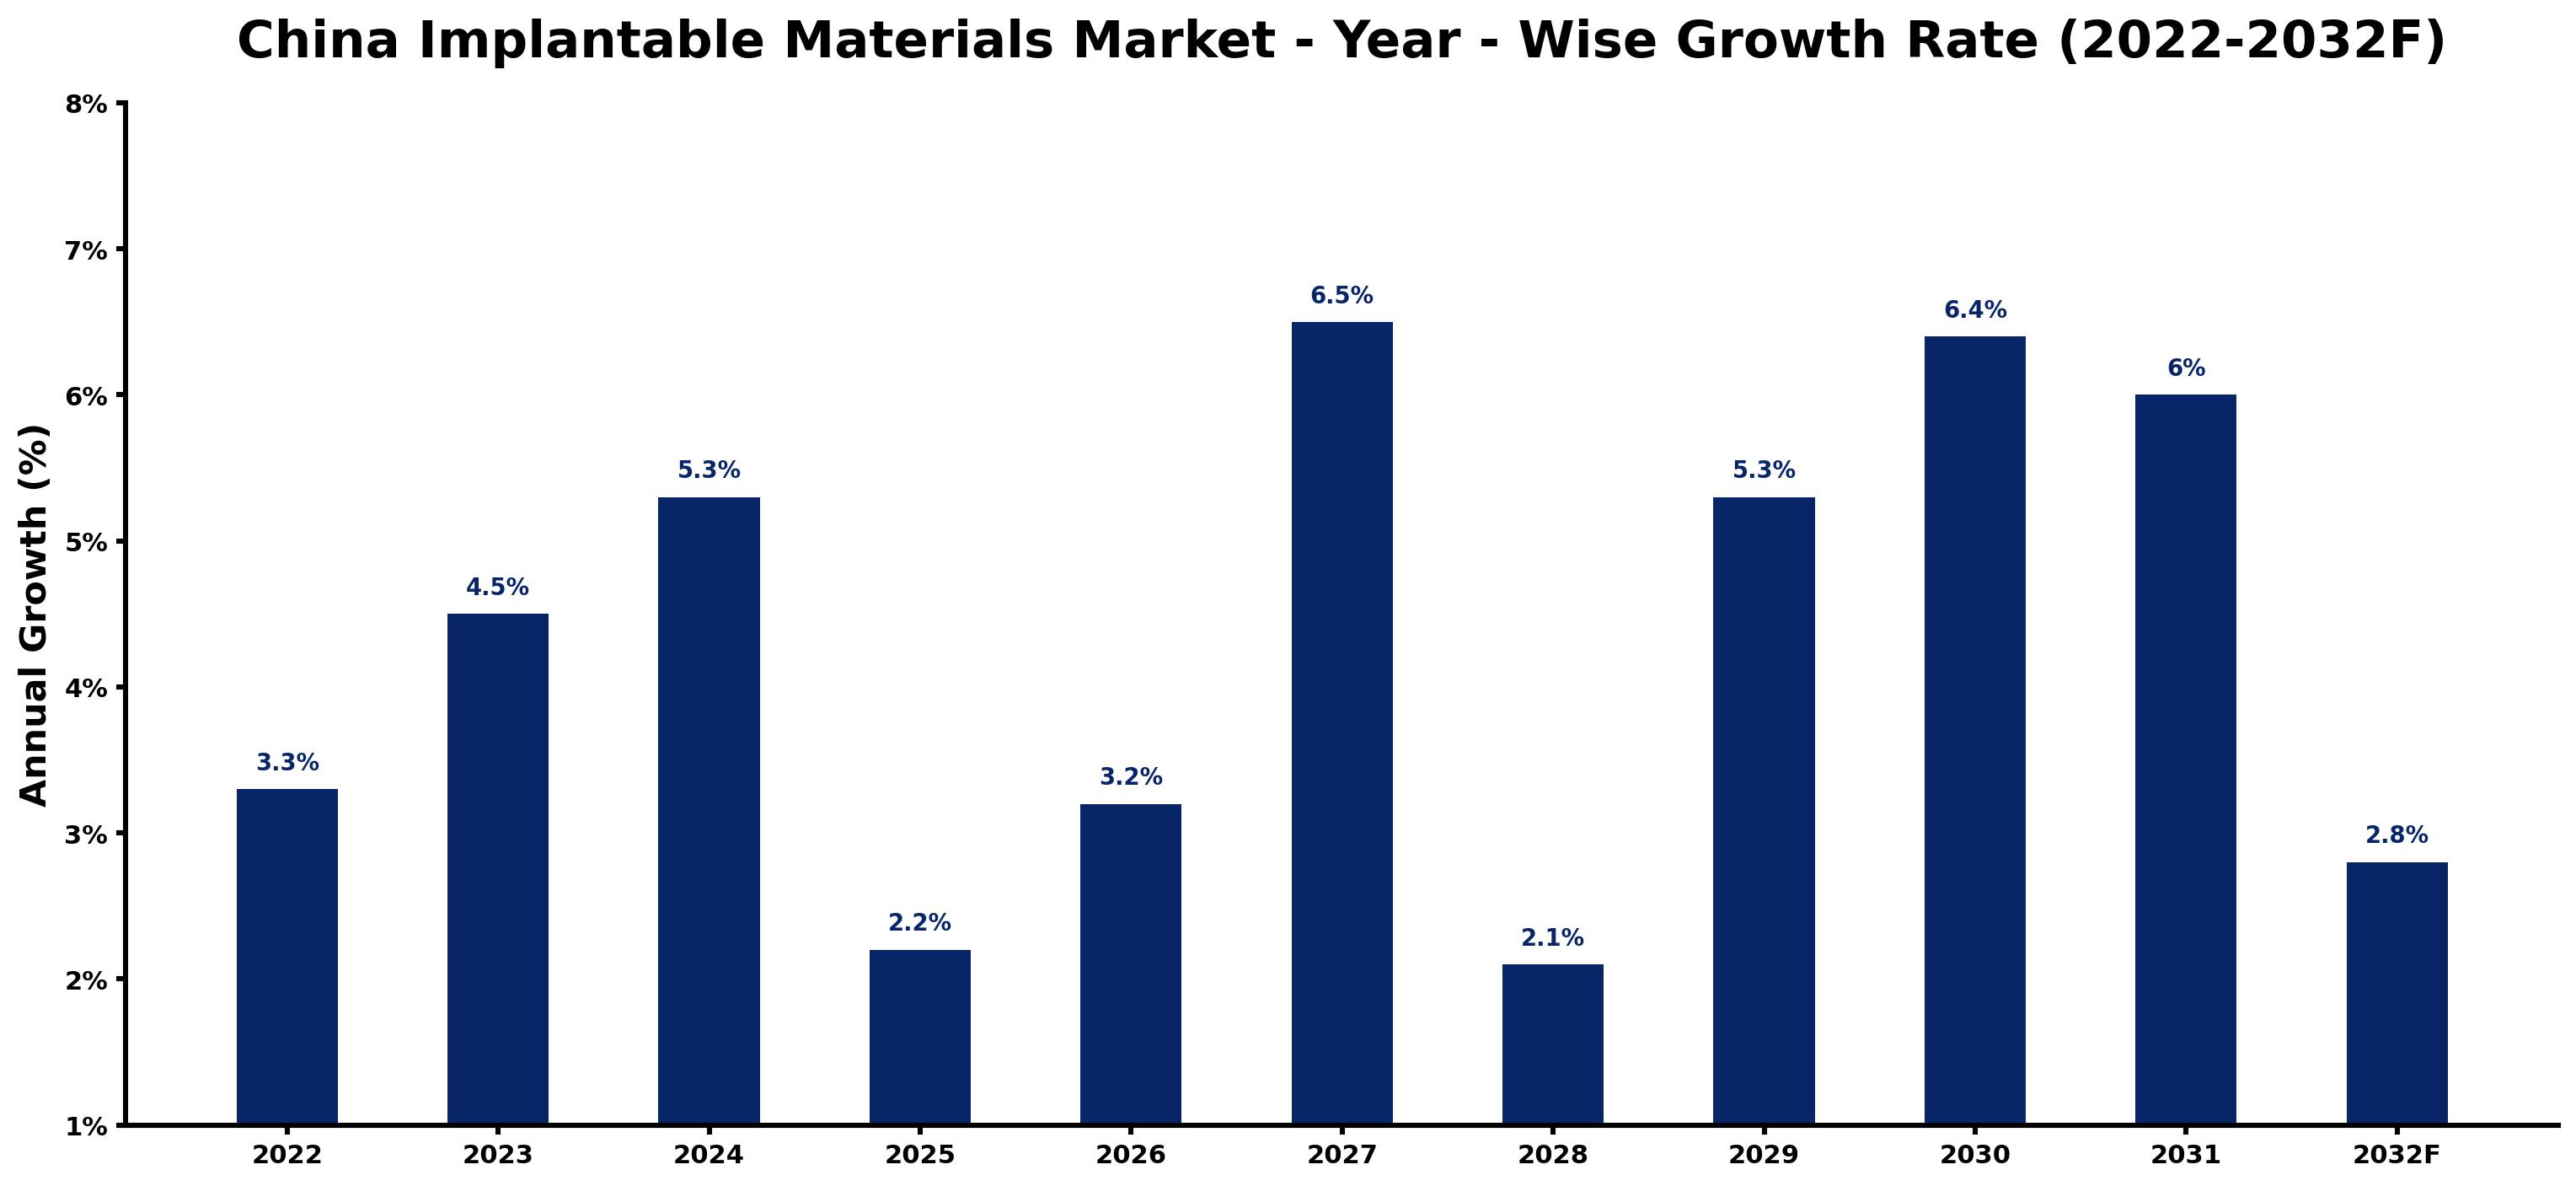
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.3 | The market experienced steady growth due to increasing healthcare investments in the sector. |
| 2023 | 4.5 | Demand for orthopedic implants rose significantly as the aging population required more surgeries. |
| 2024 | 5.3 | The aging population drove higher demand for joint and bone surgeries, particularly in urban areas. |
| 2025 | 2.2 | Growth slowed as the market adjusted to increased competition among established suppliers. |
| 2026 | 3.2 | Healthcare technology advancements are expected to positively influence purchasing decisions for new implants. |
| 2027 | 6.5 | The peak growth year will see increased investment in biomedical research facilities in Shanghai. |
| 2028 | 2.1 | A slight slowdown is projected as some sectors face capacity constraints in production. |
| 2029 | 5.3 | Growth is expected to accelerate again as innovations in implant materials gain traction across hospitals. |
| 2030 | 6.4 | The market is projected to rebound with renewed focus on advanced implant technologies and materials. |
| 2031 | 6.0 | A slowdown is anticipated as the market stabilises after rapid growth in previous years. |
| 2032 | 2.8 | The market will continue to grow, albeit at a slower pace due to maturity in the sector. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Implantable Materials Market Synopsis
Implantable Materials in China are advanced biomaterials designed for implantation in the human body. These materials include metals, polymers, and ceramics, primarily used in orthopedic implants, dental applications, and cardiovascular devices. The China Implantable Materials Market is expanding due to a high volume of orthopedic surgeries and government initiatives focusing on healthcare innovation. With approximately 300 million orthopedic surgeries performed annually, demand is expected to rise. Initiatives like 'Healthy China 2030' are stimulating medical device innovation and driving market growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased healthcare investments are driving demand for advanced implantable materials. | Driver | High | Bone/Joint Implants |
| The aging population is leading to higher demand for orthopedic surgeries. | Driver | High | Orthopedic Implant Firms |
| Growing demand for spinal implants presents opportunities for new suppliers. | Opportunity | High | Spinal & Dental |
| The Guangdong province's concentration of manufacturers creates investment potential. | Opportunity | Medium | Medical Material Suppliers |
| Regulatory hurdles can slow down the approval process for new materials. | Restraint | High | Bioceramics |
| High competition among suppliers may limit market entry for new players. | Restraint | Medium | Titanium Alloys |
| The China Implantable Materials Market faces challenges in regulatory compliance. | Challenge | High | Titanium Alloys |
| Technological advancements require continuous investment, posing a challenge. | Challenge | Medium | PEEK (Polyether ether ketone) |
Evaluation of Drivers in China Implantable Materials Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising healthcare investments are boosting demand for implantable materials. | Bone/Joint Implants | With 300 million orthopedic surgeries annually, the need for implants is increasing. |
| The aging population is increasing the demand for orthopedic surgeries. | Orthopedic Implant Firms | As the population ages, more individuals require joint replacements and related surgeries. |
| Technological advancements in materials are improving product offerings. | PEEK (Polyether ether ketone) | PEEK's favorable mechanical properties make it increasingly popular for spinal implants. |
| Government initiatives are promoting healthcare technology advancements. | Bioceramics | The 'Healthy China 2030' initiative aims to improve medical device innovation. |
| Growing biomedical research is expanding the application of implantable materials. | Spinal & Dental | The Shanghai region is a hub for biomedical research, driving demand for innovative implants. |
Market growth for Implantable Materials in China is underpinned by rising healthcare investments, increasing demand for orthopedic surgeries, and advancements in material technology. Approximately 300 million orthopedic surgeries performed annually create a strong need for implants. The aging population further drives demand for joint replacements, while the focus on biomedical research in the Shanghai region encourages innovation and expands applications for implantable materials. The growing popularity of PEEK in spinal implants illustrates the shift towards advanced materials, broadening market potential.
Evaluation of Restraints in China Implantable Materials Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High production costs due to advanced material requirements | Titanium Alloys | The need for high-quality titanium alloys increases manufacturing expenses, limiting affordability for buyers. |
| Regulatory delays in product approvals | PEEK (Polyether ether ketone) | Lengthy approval processes from the China Food and Drug Administration slow market entry for new PEEK products. |
| Limited availability of skilled workforce | Bioceramics | A shortage of trained professionals in bioceramics manufacturing hampers production capacity and innovation. |
| Supply chain disruptions affecting raw materials | Bone/Joint Implants | Global supply chain issues can delay the procurement of essential materials for bone and joint implants. |
| Market competition from imported materials | Spinal & Dental | Imported alternatives may offer lower prices, challenging local producers in the spinal and dental implant sectors. |
China Implantable Materials Market Challenges
Buyers in the China Implantable Materials Market face escalating costs due to the high volume of orthopedic surgeries, with 300 million performed annually. Supply chain disruptions hinder the timely acquisition of essential biomaterials, causing delays that can extend production timelines for manufacturers by up to six months. Regulatory hurdles from the China Food and Drug Administration slow the approval process for new technologies, which can postpone market entry and limit innovation. A shortage of skilled workers in advanced biomaterials manufacturing restricts producers' ability to innovate, ultimately affecting their competitiveness in the healthcare sector.
Trends in the China Implantable Materials Market
Several trends are reshaping the China Implantable Materials Market; the most important are set out below.
- Shift towards Advanced Bioceramics: In 2023, over 20 million dental implant procedures were performed using bioceramics, reflecting a growing preference for these materials. This shift indicates a rising demand for biocompatible solutions in dental applications.
- Emergence of PEEK in Spinal Implants: Since 2022, PEEK has gained traction in spinal implants due to its flexibility and strength. This trend is projected to continue, with a CAGR of 7.1% for PEEK materials.
- Increased Focus on Regulatory Compliance: The introduction of ISO 13485 in 2023 has heightened the emphasis on quality management in medical device manufacturing. This standard ensures that products meet necessary safety and effectiveness criteria.
- Growing Demand from Orthopedic Implant Firms: With a projected 42% market share in 2025, orthopedic implant firms are increasingly investing in advanced materials. This trend highlights the sector's commitment to improving patient outcomes through effective solutions.
Investment Opportunities in the China Implantable Materials Market
Below are the investment opportunities with the strongest case in the China Implantable Materials Market.
- Orthopedic Implant Firms Seeking Advanced Materials: Orthopedic implant firms are looking for advanced materials to enhance product performance. With a projected market size of USD 463 million by 2025, suppliers can enter this sector through partnerships with local manufacturers.
- Medical Material Suppliers Expanding Offerings: With the market for implantable materials growing, medical material suppliers can invest in new technologies. The Guangdong province's concentration of manufacturers presents a strategic opportunity for collaboration and development.
- Spinal & Dental Market Growth: The spinal and dental implant market is expanding rapidly, driven by technological advancements. Suppliers can target this sector by offering tailored solutions to meet specific needs and demands.
- Investment in Biocompatible Materials: There is a growing need for biocompatible materials in medical devices. With over 20 million dental procedures annually, suppliers can focus on developing high-quality bioceramics to meet increasing demand.
Government Initiatives in the China Implantable Materials Market
The China Implantable Materials Market is influenced by various regulations and initiatives. The ISO 13485 standard, established in 2023, mandates stringent quality management practices for medical device manufacturers. Additionally, the 'Healthy China 2030' initiative, launched in 2023, aims to improve medical device innovation and healthcare outcomes. These measures ensure that implantable materials meet necessary safety and efficacy standards, benefiting producers and buyers alike.
The China Food and Drug Administration regulates the approval of implantable materials. This agency oversees compliance with safety standards and provides funding for healthcare technology advancements. In 2022, the government allocated 3 billion CNY for healthcare technology improvements, supporting the development of innovative implantable materials. The Ministry of Industry and Information Technology also funds advanced materials development, facilitating research and production in the sector.
Future Insight of the China Implantable Materials Market
The China Implantable Materials Market will undergo significant changes by 2032, driven by the 'Healthy China 2030' initiative that prioritises medical device innovation. Increased government funding for healthcare technology advancements will support research and development efforts. The Shanghai region's role as a hub for biomedical research will facilitate the introduction of advanced materials. With over 20 million dental procedures annually, suppliers will need to improve their offerings to meet the rising demand for high-quality implantable materials.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Material Type – Titanium Alloys Dominated, PEEK (Polyether ether ketone) Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, Titanium Alloys held a 45% share of the China Implantable Materials Market by material type in 2025. Titanium alloys hold the largest market share in China due to their exceptional strength and biocompatibility, making them ideal for load-bearing implants. Their widespread use in orthopedic surgeries, supported by 300 million annual procedures, solidifies their leading position. Over 2026–2032, PEEK (Polyether ether ketone) is expected to post the fastest growth, at a CAGR of 7.1%. PEEK is experiencing rapid growth because of its superior flexibility and mechanical properties, particularly in spinal and orthopedic implants. The increasing adoption of PEEK by healthcare providers for improved patient outcomes indicates its potential for sustained expansion. Suppliers should focus on enhancing their PEEK offerings to meet the growing demand in the implantable materials market.
By Use Case – Bone/Joint Implants Dominated, Spinal & Dental Expected to Grow Fastest
The largest use case category in 2025 was Bone/Joint Implants, with a 39% share of total revenue. Bone and joint implants account for the largest market share as they are the primary focus of orthopedic surgeries performed extensively across China. The substantial number of these surgeries each year highlights the robust demand for such implants. Spinal & Dental is projected to grow fastest, at a CAGR of 7.3% during 2026–2032. The spinal and dental segment is expanding swiftly, driven by the rising number of spinal fusion and dental restoration procedures. With over 20 million dental implant procedures conducted annually, this segment is poised for significant growth. Buyers in the spinal and dental markets should expect an increase in the availability of advanced implantable materials as demand rises.
By Biocompatibility Level – High Dominated, Excellent Expected to Grow Fastest
High accounted for a 33% market share by biocompatibility level in 2025. High biocompatibility materials command the largest market share as they are essential for many implantable devices, ensuring patient safety and effective integration. The stringent regulatory standards in China, such as ISO 13485, further reinforce the necessity for high biocompatibility in medical devices. Excellent is set to record the highest CAGR in this split, 7.0% over 2026–2032. Excellent biocompatibility is gaining traction as the fastest-growing segment, particularly among top-tier materials used for implants. The increasing focus on patient outcomes and safety is driving manufacturers to prioritise excellent biocompatibility in their product offerings. Manufacturers should invest in developing materials with excellent biocompatibility to capture the growing demand in the implantable materials market.
By End User – Orthopedic Implant Firms Dominated, Medical Material Suppliers Expected to Grow Fastest
Orthopedic Implant Firms took a 42% share of end user in 2025, more than any other category. Orthopedic implant firms lead the market share as they are the main manufacturers of orthopedic solutions, catering to the vast number of surgeries performed annually. Their established expertise and presence in the industry reinforce their dominant role in the implantable materials market. The quickest growth will come from Medical Material Suppliers, forecast to expand at a CAGR of 6.2% between 2026 and 2032. Medical material suppliers are witnessing the highest growth due to their critical role in providing advanced materials to manufacturers. As the demand for innovative implantable materials escalates, these suppliers are becoming increasingly vital in the supply chain. Suppliers should develop strong partnerships with orthopedic firms to ensure a reliable supply of materials that meet the market's evolving needs.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Implantable Materials Market Outlook
- Market Size of China Implantable Materials Market, 2025
- Forecast of China Implantable Materials Market, 2032
- Historical Data and Forecast of China Implantable Materials Revenues & Volume for the Period 2022 - 2032F
- China Implantable Materials Market Trend Evolution
- China Implantable Materials Market Drivers and Challenges
- China Implantable Materials Price Trends
- China Implantable Materials Porter's Five Forces
- China Implantable Materials Industry Life Cycle
- Historical Data and Forecast of China Implantable Materials Market Revenues & Volume By Material Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Implantable Materials Market Revenues & Volume By Titanium Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of China Implantable Materials Market Revenues & Volume By PEEK (Polyether ether ketone) for the Period 2022 - 2032F
- Historical Data and Forecast of China Implantable Materials Market Revenues & Volume By Silicone-Based Polymers for the Period 2022 - 2032F
- Historical Data and Forecast of China Implantable Materials Market Revenues & Volume By Bioceramics for the Period 2022 - 2032F
- Historical Data and Forecast of China Implantable Materials Market Revenues & Volume By Use Case for the Period 2022 - 2032F
- Historical Data and Forecast of China Implantable Materials Market Revenues & Volume By Bone/Joint Implants for the Period 2022 - 2032F
- Historical Data and Forecast of China Implantable Materials Market Revenues & Volume By Spinal & Dental for the Period 2022 - 2032F
- Historical Data and Forecast of China Implantable Materials Market Revenues & Volume By Pacemakers, Catheters for the Period 2022 - 2032F
- Historical Data and Forecast of China Implantable Materials Market Revenues & Volume By Dental/Orthopedic for the Period 2022 - 2032F
- Historical Data and Forecast of China Implantable Materials Market Revenues & Volume By Biocompatibility Level for the Period 2022 - 2032F
- Historical Data and Forecast of China Implantable Materials Market Revenues & Volume By High for the Period 2022 - 2032F
- Historical Data and Forecast of China Implantable Materials Market Revenues & Volume By Excellent for the Period 2022 - 2032F
- Historical Data and Forecast of China Implantable Materials Market Revenues & Volume By Flexible/Bio-Stable for the Period 2022 - 2032F
- Historical Data and Forecast of China Implantable Materials Market Revenues & Volume By Non-Toxic, Durable for the Period 2022 - 2032F
- Historical Data and Forecast of China Implantable Materials Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Implantable Materials Market Revenues & Volume By Orthopedic Implant Firms for the Period 2022 - 2032F
- Historical Data and Forecast of China Implantable Materials Market Revenues & Volume By Medical Material Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Implantable Materials Market Revenues & Volume By Biomedical OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Implantable Materials Market Revenues & Volume By Surgical Product Firms for the Period 2022 - 2032F
- China Implantable Materials Import Export Trade Statistics
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By Use Case
- Market Opportunity Assessment By Biocompatibility Level
- Market Opportunity Assessment By End User
- China Implantable Materials Top Companies Market Share
- China Implantable Materials Competitive Benchmarking By Technical and Operational Parameters
- China Implantable Materials Company Profiles
- China Implantable Materials Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Material Type
- Titanium Alloys
- PEEK (Polyether ether ketone)
- Silicone-Based Polymers
- Bioceramics
By Use Case
- Bone/Joint Implants
- Spinal & Dental
- Pacemakers
- Catheters
- Dental/Orthopedic
By Biocompatibility Level
- High
- Excellent
- Flexible/Bio-Stable
- Non-Toxic
- Durable
By End User
- Orthopedic Implant Firms
- Medical Material Suppliers
- Biomedical OEMs
- Surgical Product Firms































