China In-App Payment Market Size & Growth Rate
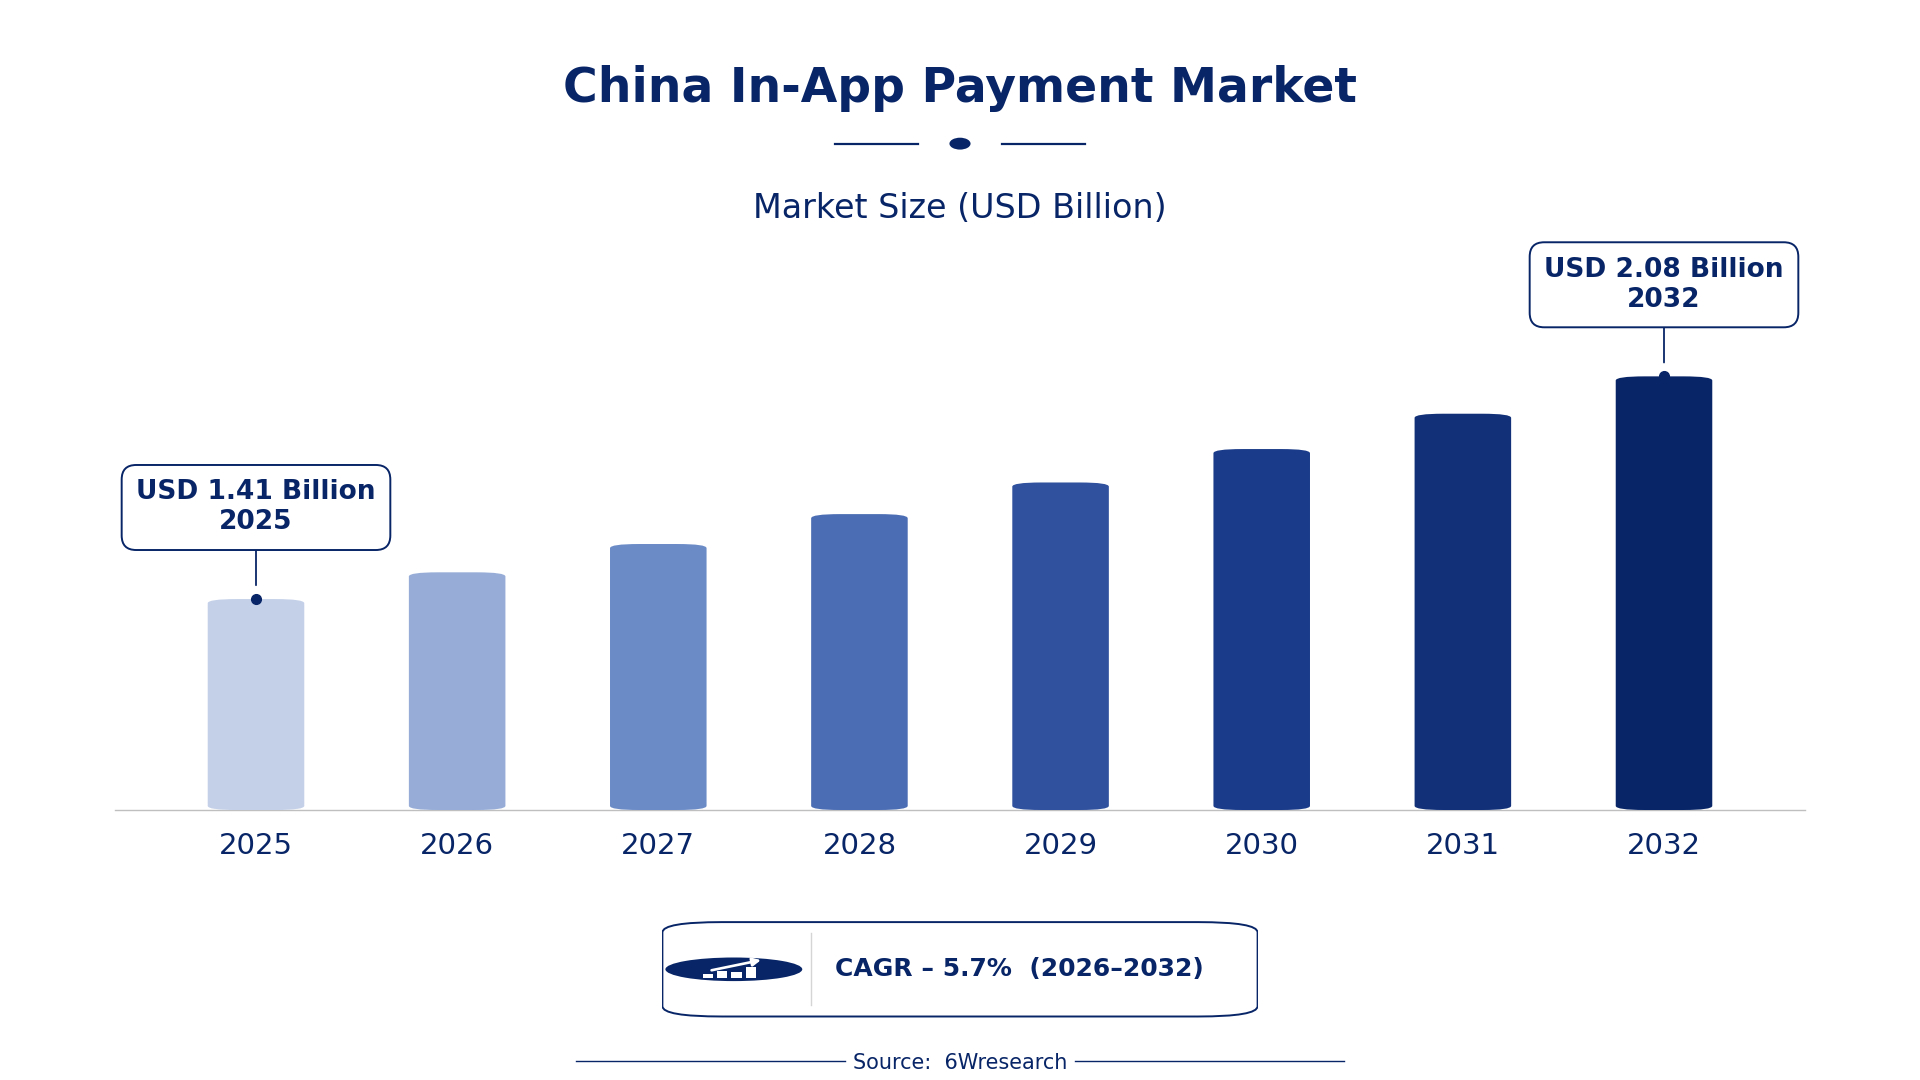
According to 6Wresearch internal database and industry insights, the China In-App Payment Market was valued at USD 1.41 billion in 2025 and is projected to reach USD 2.08 billion by 2032, growing at a CAGR of approximately 5.7% during 2026–2032.
China In-App Payment Market Highlights
| Report Metric | Details |
| Report Name | China In-App Payment Market |
| Market Size 2025 | USD 1.41 billion |
| Market Size 2032 | USD 2.08 billion |
| Absolute Growth 2025–2032 | USD 0.67 billion |
| CAGR 2026–2032 | 5.7% |
| Peak Annual Growth | 8.0% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Payment Method, 2025 | Wallet-Based Payments (44% share) |
| Leading Security Layer, 2025 | Tokenization (45% share) |
| Leading Platform Type, 2025 | iOS/Android (42% share) |
| Leading End User, 2025 | Digital App Owners (46% share) |
| Fastest-Growing Payment Method | UPI/Bank Transfers (8.2% CAGR) |
| Fastest-Growing Security Layer | Biometric Authentication (7.6% CAGR) |
| Fastest-Growing Platform Type | Gaming/Entertainment (7.8% CAGR) |
| Fastest-Growing End User | Fintech Developers (7.0% CAGR) |
| Growing Sector | Digital Payments |
| Key End Users | Digital App Owners, Payment Gateway Providers, Fintech Developers |
China In-App Payment Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
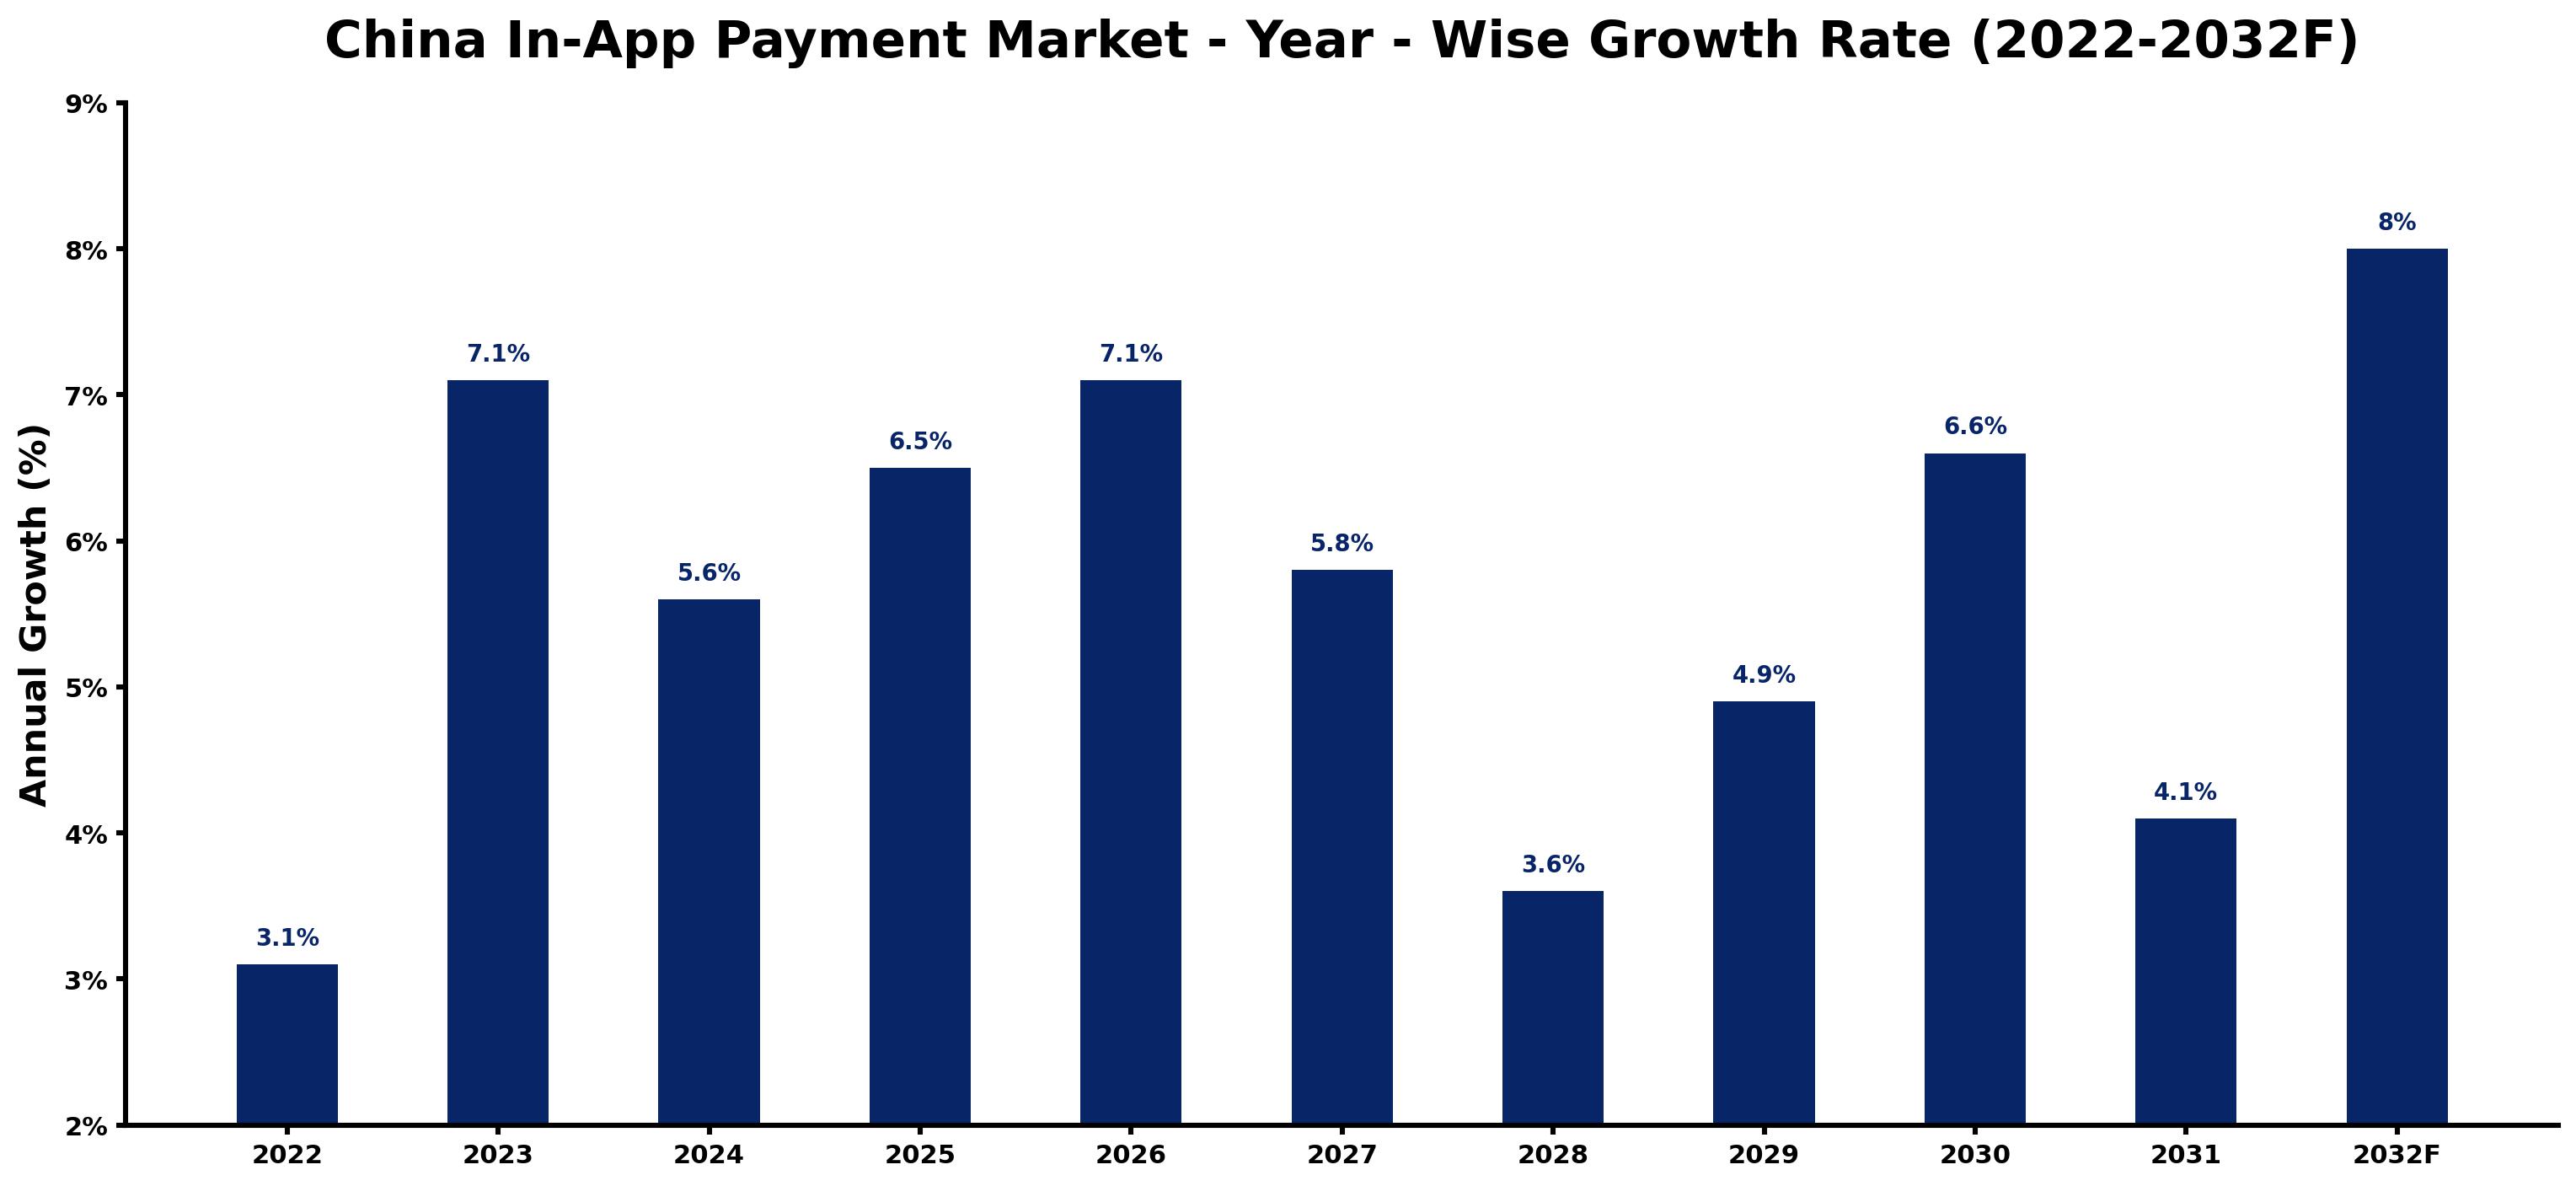
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.1 | Mobile payment transactions reached approximately 300 trillion yuan, indicating strong activity. |
| 2023 | 7.1 | The market experienced accelerated growth due to increased mobile payment user adoption, surpassing 1 billion. |
| 2024 | 5.6 | Growth slowed as the market adjusted to the rapid expansion of previous years. |
| 2025 | 6.5 | The introduction of new fintech solutions contributed to a resurgence in growth rates. |
| 2026 | 7.1 | Investment in the fintech sector is expected to support a return to higher growth rates. |
| 2027 | 5.8 | Growth is projected to slow again as the market stabilises after rapid expansion. |
| 2028 | 3.6 | Market growth is expected to decelerate as competition intensifies among payment methods. |
| 2029 | 4.9 | A renewed interest in digital payment solutions is likely to lead to a faster growth rate this year. |
| 2030 | 6.6 | The integration of digital currencies is expected to positively influence market conditions. |
| 2031 | 4.1 | Growth is projected to slow as the market matures and competition becomes more pronounced. |
| 2032 | 8.0 | The market is expected to peak as demand for innovative payment solutions surges. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China In-App Payment Market Synopsis
In-App Payment in China refers to digital transactions within mobile applications, primarily using various payment methods. This sector is supported by APIs and SDKs that integrate payment gateways into apps, facilitating purchases of digital goods and subscriptions. The China In-App Payment Market is growing due to a thriving digital economy and increased user adoption, with over 80% of smartphone users utilizing these services. The gaming industry drives revenue, accounting for 50% of in-app payments. Demand for payment solutions continues to rise.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased mobile payment user adoption drives demand for in-app payment solutions. | Driver | High | Wallet-Based Payments |
| The gaming industry’s growth leads to higher in-app purchases. | Driver | High | Gaming/Entertainment |
| Growing demand for secure payment methods presents opportunities for fintech developers. | Opportunity | High | Fintech Developers |
| The rise of subscription-based apps creates a need for reliable payment solutions. | Opportunity | Medium | Subscription Apps |
| Regulatory compliance can increase operational costs for payment gateway providers. | Restraint | High | Payment Gateway Providers |
| Intense competition among payment methods may limit market share for some providers. | Restraint | Medium | Wallet-Based Payments |
| Buyers face challenges with integration of new payment technologies into existing systems. | Challenge | High | Digital App Owners |
| Suppliers encounter delays in meeting evolving security standards for payment systems. | Challenge | Medium | Payment Gateway Providers |
Evaluation of Drivers in China In-App Payment Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased smartphone penetration leads to more users adopting in-app payments. | Wallet-Based Payments | Over 80% of smartphone users in China utilize in-app payment services. |
| The gaming industry's expansion drives higher in-app purchase volumes. | Gaming/Entertainment | The gaming industry accounted for 50% of in-app payment revenues in 2022. |
| The introduction of the Digital Payment Development Plan improves payment security. | Card-On-File Payments | This plan requires providers to adopt stricter security measures, encouraging user adoption. |
| Growing interest in subscription models boosts demand for in-app payment solutions. | Subscription Apps | Subscription apps have become increasingly popular, driving the need for reliable payment methods. |
| The rise of biometric authentication improves user confidence in payment security. | Biometric Authentication | The implementation of biometric security measures is gaining traction among users. |
Growth in the In-App Payment market in China comes from rising smartphone penetration, which leads to more users adopting these payment solutions. Over 80% of smartphone users in China utilize in-app payment services, driving demand for transactions. The expansion of the gaming industry contributes to higher in-app purchase volumes, which accounted for 50% of revenues in 2022. The introduction of the Digital Payment Development Plan enhances payment security, encouraging more users to adopt card-on-file payments. Additionally, the rise of biometric authentication is expected to boost user confidence in payment security, further increasing demand for these solutions.
Evaluation of Restraints in China In-App Payment Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Regulatory compliance increases operational costs for payment gateway providers. | Payment Gateway Providers | The Central Bank of China introduced a regulatory framework in 2020, raising compliance costs significantly. |
| Intense competition may limit market share for some payment methods. | Wallet-Based Payments | The increasing number of payment options leads to competitive pricing pressures, affecting profitability. |
| Integration of new payment technologies can be complex and costly for developers. | Digital App Owners | Adapting to evolving security standards requires significant investment in technology and resources. |
| User trust issues can hinder the adoption of new payment methods. | Fintech Developers | Concerns about security and privacy may slow user acceptance of new solutions, impacting growth. |
| Market saturation in urban areas limits growth potential for new entrants. | UPI/Bank Transfers | Urban markets are already saturated with established payment solutions, restricting new market players. |
China In-App Payment Market Challenges
Buyers and suppliers in the China In-App Payment market encounter technological integration challenges, as many apps struggle to implement secure payment gateways effectively. This can result in transaction failures, potentially causing losses exceeding 1 million yuan for developers. High transaction fees burden buyers, with costs reaching up to 5% per transaction, significantly impacting profit margins for small businesses. Regulatory changes also present challenges; for example, the updated National Standard for Mobile Payment Security necessitates compliance, delaying app updates and incurring additional costs for developers. Supply chain disruptions in fintech services can further extend payment processing times, negatively affecting user experience and retention rates.
Trends in the China In-App Payment Market
Four trends stand out in the China In-App Payment Market.
- Shift towards Biometric Authentication: The implementation of biometric authentication is becoming more prevalent in China, improving security for in-app payments. In 2022, 30% of digital app owners adopted biometric solutions, increasing user confidence.
- Rise of Subscription-Based Apps: The popularity of subscription-based applications has surged since 2022, with over 40% of digital app owners integrating in-app payment solutions. This shift reflects changing consumer preferences for recurring revenue models.
- Growing Adoption of QR Code Payments: In urban areas, QR code payments have been adopted in over 90% of retail transactions, facilitating quick in-app purchases. This trend supports the payment experience sought by consumers.
- Expansion of Digital Currency Integration: The pilot program for digital currency integration launched in 2023 is influencing mobile payment practices. This initiative aims to improve transaction efficiency and security in the coming years.
Investment Opportunities in the China In-App Payment Market
Below are the investment opportunities with the strongest case in the China In-App Payment Market.
- Partner with Fintech Startups: Collaborating with fintech startups focusing on payment solutions presents a valuable opportunity. The Ministry of Finance's subsidy program for fintech startups, amounting to 500 million yuan, encourages new entrants.
- Supply Biometric Security Solutions: The rising demand for biometric authentication in payment systems offers a lucrative opportunity. Digital app owners are actively seeking secure payment methods to enhance user trust and satisfaction.
- Target Subscription App Developers: With the rise of subscription-based apps, there is a growing need for reliable payment solutions. Engaging with digital app owners can facilitate entry into this expanding market segment.
- Focus on Urban Payment Solutions: Urban areas show a high adoption rate of mobile payments, creating opportunities for tailored solutions. Developing partnerships with local payment gateway providers can enhance market presence and customer reach.
Government Initiatives in the China In-App Payment Market
The Digital Payment Development Plan launched by the People's Bank of China in 2023 aims to improve the security and efficiency of digital payments. This initiative requires payment service providers to adopt stricter security measures, ensuring user protection and building trust in transactions. The updated National Standard for Mobile Payment Security by the Ministry of Industry and Information Technology in 2021 further strengthens these requirements, promoting safer transaction environments. Compliance with these regulations is crucial for producers and buyers in the in-app payment market, impacting operational practices and user trust.
In 2023, a pilot programme for digital currency integration in mobile payments was launched, aiming to streamline transaction processes. The Ministry of Finance announced a subsidy programme for fintech startups focusing on payment solutions, with funding of 500 million yuan. These initiatives support the development of secure and efficient payment systems, benefiting both producers and users in the in-app payment market. The regulatory framework established by the Central Bank of China in 2020 ensures compliance and security for payment service providers, facilitating smoother operations.
Future Insight of the China In-App Payment Market
By 2032, buyers and suppliers in the China In-App Payment market can anticipate enhanced security measures driven by the Digital Payment Development Plan, which will cultivate user trust and improve transaction safety. The pilot programme for digital currency integration in mobile payments will streamline processes and reduce costs for users. With the fintech sector projected to attract over 200 billion yuan in investments by 2025, innovation in payment solutions will accelerate, creating opportunities for app developers. Increased mobile payment adoption in rural areas will broaden the customer base, offering new revenue streams.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Payment Method – Wallet-Based Payments Dominated, UPI/Bank Transfers Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, the largest payment method category in 2025 was Wallet-Based Payments, with a 44% share of total revenue. Wallet-based payments dominate the market due to their widespread use for seamless transactions, appealing to over 80% of smartphone users in China. This method is particularly favoured for purchasing digital goods and subscriptions, making it essential for app developers. The quickest growth will come from UPI/Bank Transfers, forecast to expand at a CAGR of 8.2% between 2026 and 2032. The rapid growth of UPI and bank transfers is driven by increasing user acceptance and government initiatives, such as the Digital Payment Development Plan introduced in 2023. As users seek alternative payment options, this segment's expansion will likely continue. Suppliers should enhance wallet-based payment solutions to capture the growing demand from digital app owners.
By Security Layer – Tokenization Dominated, Biometric Authentication Expected to Grow Fastest
Tokenization accounted for a 45% market share by security layer in 2025. Tokenization holds the largest share as it plays a crucial role in protecting sensitive payment information, essential for users and app developers. The updated National Standard for Mobile Payment Security in 2021 has reinforced its importance in the market. Over 2026–2032, Biometric Authentication is expected to post the fastest growth, at a CAGR of 7.6%. Biometric authentication is experiencing rapid growth as it is increasingly implemented in mobile apps, enhancing user trust and security. As more app developers adopt this technology, its market share will likely expand significantly. Buyers should prioritise security solutions like tokenization and biometric authentication to ensure user confidence in in-app payment transactions.
By Platform Type – iOS/Android Dominated, Gaming/Entertainment Expected to Grow Fastest
iOS/Android held a 42% share of the China In-App Payment Market by platform type in 2025. iOS and Android platforms lead the market as they are the primary environments for in-app payments, catering to over 1 billion mobile payment users. Their dominance is reinforced by the extensive range of apps available on these platforms. Gaming/Entertainment is projected to grow fastest, at a CAGR of 7.8% during 2026–2032. The gaming and entertainment segment is the fastest-growing area, driven by substantial revenue generated from in-app purchases, which accounted for 50% of total in-app payment revenues in 2022. This trend is likely to continue as gaming apps proliferate. Suppliers should optimise payment solutions for gaming and entertainment apps to tap into this lucrative segment.
By End User – Digital App Owners Dominated, Fintech Developers Expected to Grow Fastest
In 2025, Digital App Owners led the end user split with a 46% share. Digital app owners represent the largest share of the market as they are the primary users of in-app payment solutions, seeking to maximise revenue from their applications. Their extensive reliance on these services underscores their critical role in the ecosystem. Fintech Developers are set to record the highest CAGR in this split, 7.0% over 2026–2032. Fintech developers are the fastest-growing end-user group, driven by their need to integrate advanced payment solutions into their offerings. With the fintech sector expected to attract over 200 billion yuan in investments by 2025, this segment's growth is poised to accelerate. Suppliers should tailor their offerings to meet the specific needs of fintech developers to capitalise on this expanding market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China In-App Payment Market Outlook
- Market Size of China In-App Payment Market, 2025
- Forecast of China In-App Payment Market, 2032
- Historical Data and Forecast of China In-App Payment Revenues & Volume for the Period 2022 - 2032F
- China In-App Payment Market Trend Evolution
- China In-App Payment Market Drivers and Challenges
- China In-App Payment Price Trends
- China In-App Payment Porter's Five Forces
- China In-App Payment Industry Life Cycle
- Historical Data and Forecast of China In-App Payment Market Revenues & Volume By Payment Method for the Period 2022 - 2032F
- Historical Data and Forecast of China In-App Payment Market Revenues & Volume By Wallet-Based Payments for the Period 2022 - 2032F
- Historical Data and Forecast of China In-App Payment Market Revenues & Volume By Card-On-File Payments for the Period 2022 - 2032F
- Historical Data and Forecast of China In-App Payment Market Revenues & Volume By Carrier Billing for the Period 2022 - 2032F
- Historical Data and Forecast of China In-App Payment Market Revenues & Volume By UPI/Bank Transfers for the Period 2022 - 2032F
- Historical Data and Forecast of China In-App Payment Market Revenues & Volume By Security Layer for the Period 2022 - 2032F
- Historical Data and Forecast of China In-App Payment Market Revenues & Volume By Biometric Authentication for the Period 2022 - 2032F
- Historical Data and Forecast of China In-App Payment Market Revenues & Volume By Tokenization for the Period 2022 - 2032F
- Historical Data and Forecast of China In-App Payment Market Revenues & Volume By Telco Integration for the Period 2022 - 2032F
- Historical Data and Forecast of China In-App Payment Market Revenues & Volume By QR/NFC Enabled for the Period 2022 - 2032F
- Historical Data and Forecast of China In-App Payment Market Revenues & Volume By Platform Type for the Period 2022 - 2032F
- Historical Data and Forecast of China In-App Payment Market Revenues & Volume By iOS/Android for the Period 2022 - 2032F
- Historical Data and Forecast of China In-App Payment Market Revenues & Volume By Subscription Apps for the Period 2022 - 2032F
- Historical Data and Forecast of China In-App Payment Market Revenues & Volume By Gaming/Entertainment for the Period 2022 - 2032F
- Historical Data and Forecast of China In-App Payment Market Revenues & Volume By Indian Payment Apps for the Period 2022 - 2032F
- Historical Data and Forecast of China In-App Payment Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China In-App Payment Market Revenues & Volume By Digital App Owners for the Period 2022 - 2032F
- Historical Data and Forecast of China In-App Payment Market Revenues & Volume By Payment Gateway Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China In-App Payment Market Revenues & Volume By Telecom Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China In-App Payment Market Revenues & Volume By Fintech Developers for the Period 2022 - 2032F
- China In-App Payment Import Export Trade Statistics
- Market Opportunity Assessment By Payment Method
- Market Opportunity Assessment By Security Layer
- Market Opportunity Assessment By Platform Type
- Market Opportunity Assessment By End User
- China In-App Payment Top Companies Market Share
- China In-App Payment Competitive Benchmarking By Technical and Operational Parameters
- China In-App Payment Company Profiles
- China In-App Payment Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Payment Method
- Wallet-Based Payments
- Card-On-File Payments
- Carrier Billing
- UPI/Bank Transfers
By Security Layer
- Biometric Authentication
- Tokenization
- Telco Integration
- QR/NFC Enabled
By Platform Type
- iOS/Android
- Subscription Apps
- Gaming/Entertainment
- Indian Payment Apps
By End User
- Digital App Owners
- Payment Gateway Providers
- Telecom Providers
- Fintech Developers































