China In-Flight Connectivity C-Band Market Size & Growth Rate
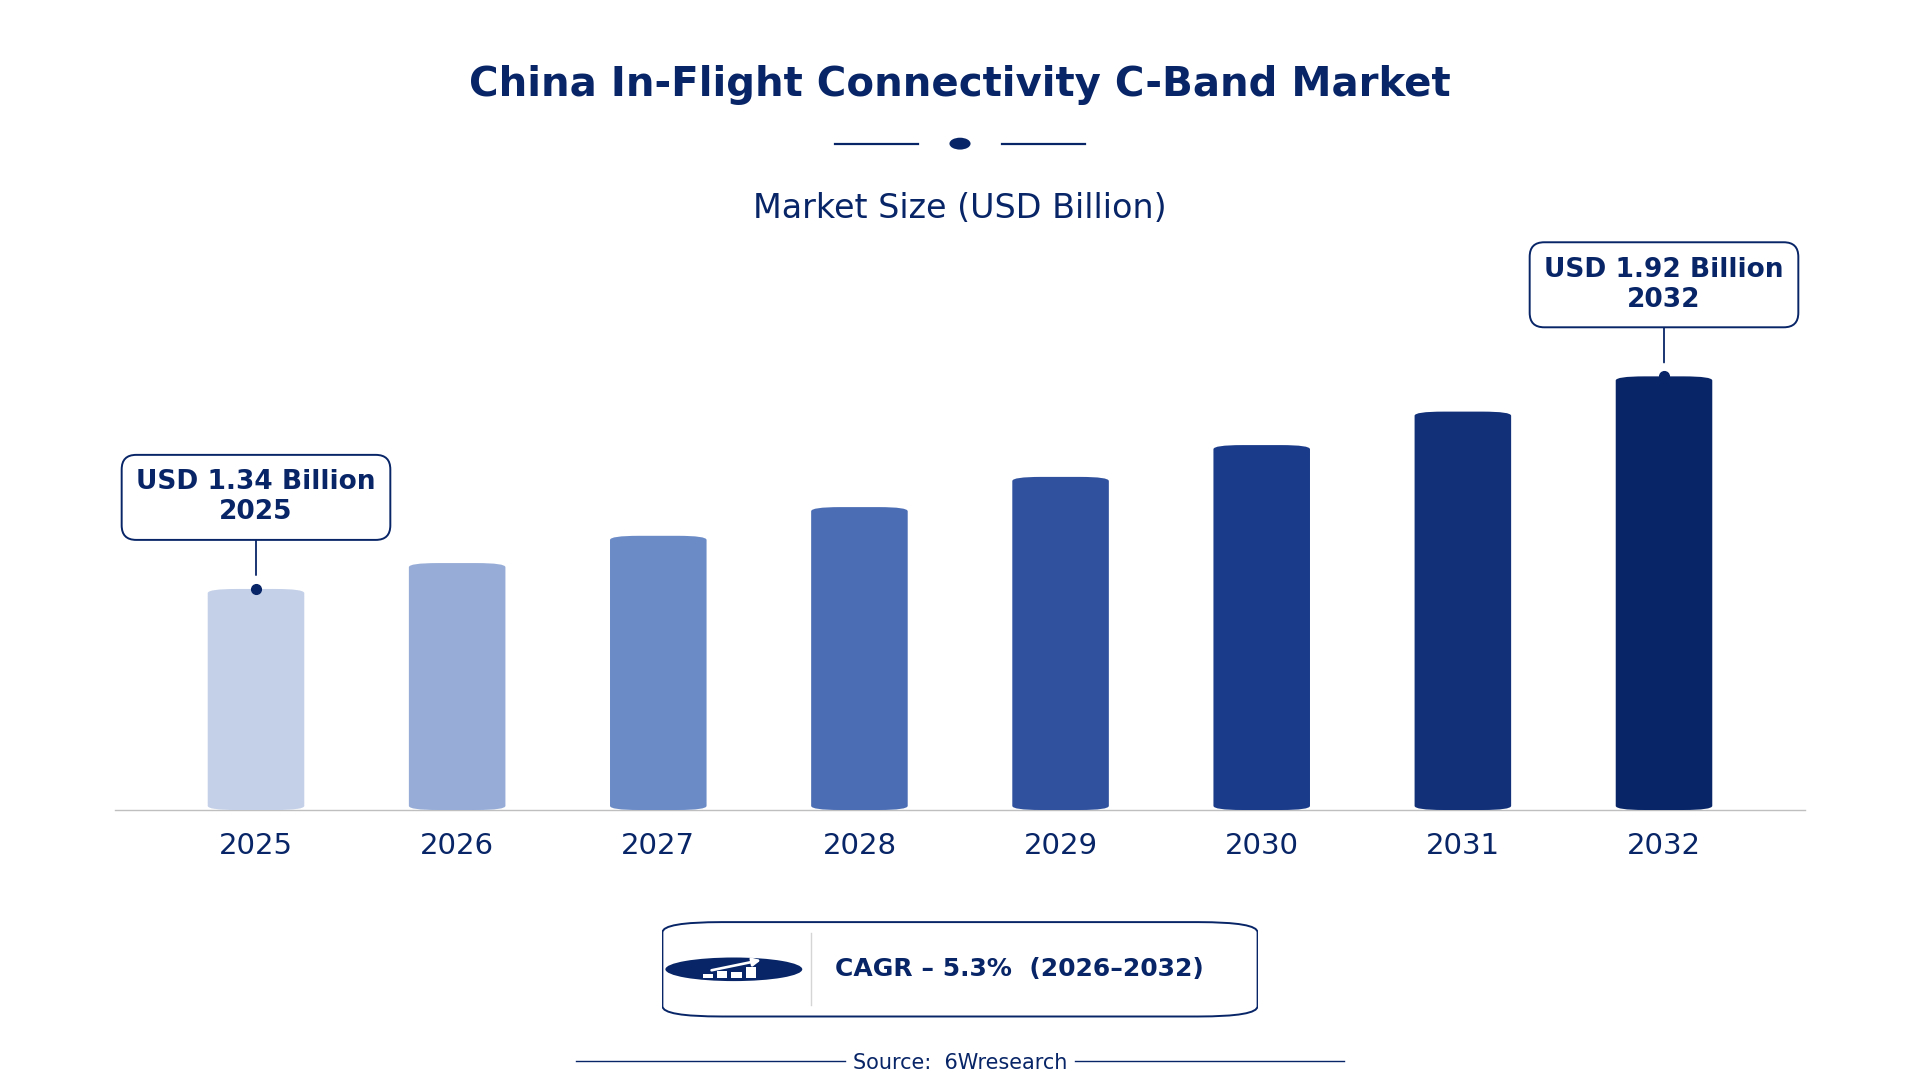
According to 6Wresearch internal database and industry insights, the China In-Flight Connectivity C-Band Market was valued at USD 1.34 billion in 2025 and is projected to reach USD 1.92 billion by 2032, growing at a CAGR of approximately 5.3% during 2026–2032.
China In-Flight Connectivity C-Band Market Highlights
| Report Metric | Details |
| Report Name | China In-Flight Connectivity C-Band Market |
| Market Size 2025 | USD 1.34 billion |
| Market Size 2032 | USD 1.92 billion |
| Absolute Growth 2025–2032 | USD 0.58 billion |
| CAGR 2026–2032 | 5.3% |
| Peak Annual Growth | 8.0% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Connectivity Type, 2025 | Satellite-Based (35% share) |
| Leading Application, 2025 | Inflight Wi-Fi (46% share) |
| Leading Aircraft Type, 2025 | Commercial Aircraft (52% share) |
| Leading Distribution Channel, 2025 | Satcom Providers (49% share) |
| Fastest-Growing Connectivity Type | C-Band Transceivers (7.4% CAGR) |
| Fastest-Growing Aircraft Type | Business Jets (6.3% CAGR) |
| Fastest-Growing Distribution Channel | OEMs (6.7% CAGR) |
| Growing Sector | Aviation |
| Key End Users | Commercial Airlines, Business Jet Operators, Cargo Airlines, Military Aviation |
China In-Flight Connectivity C-Band Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
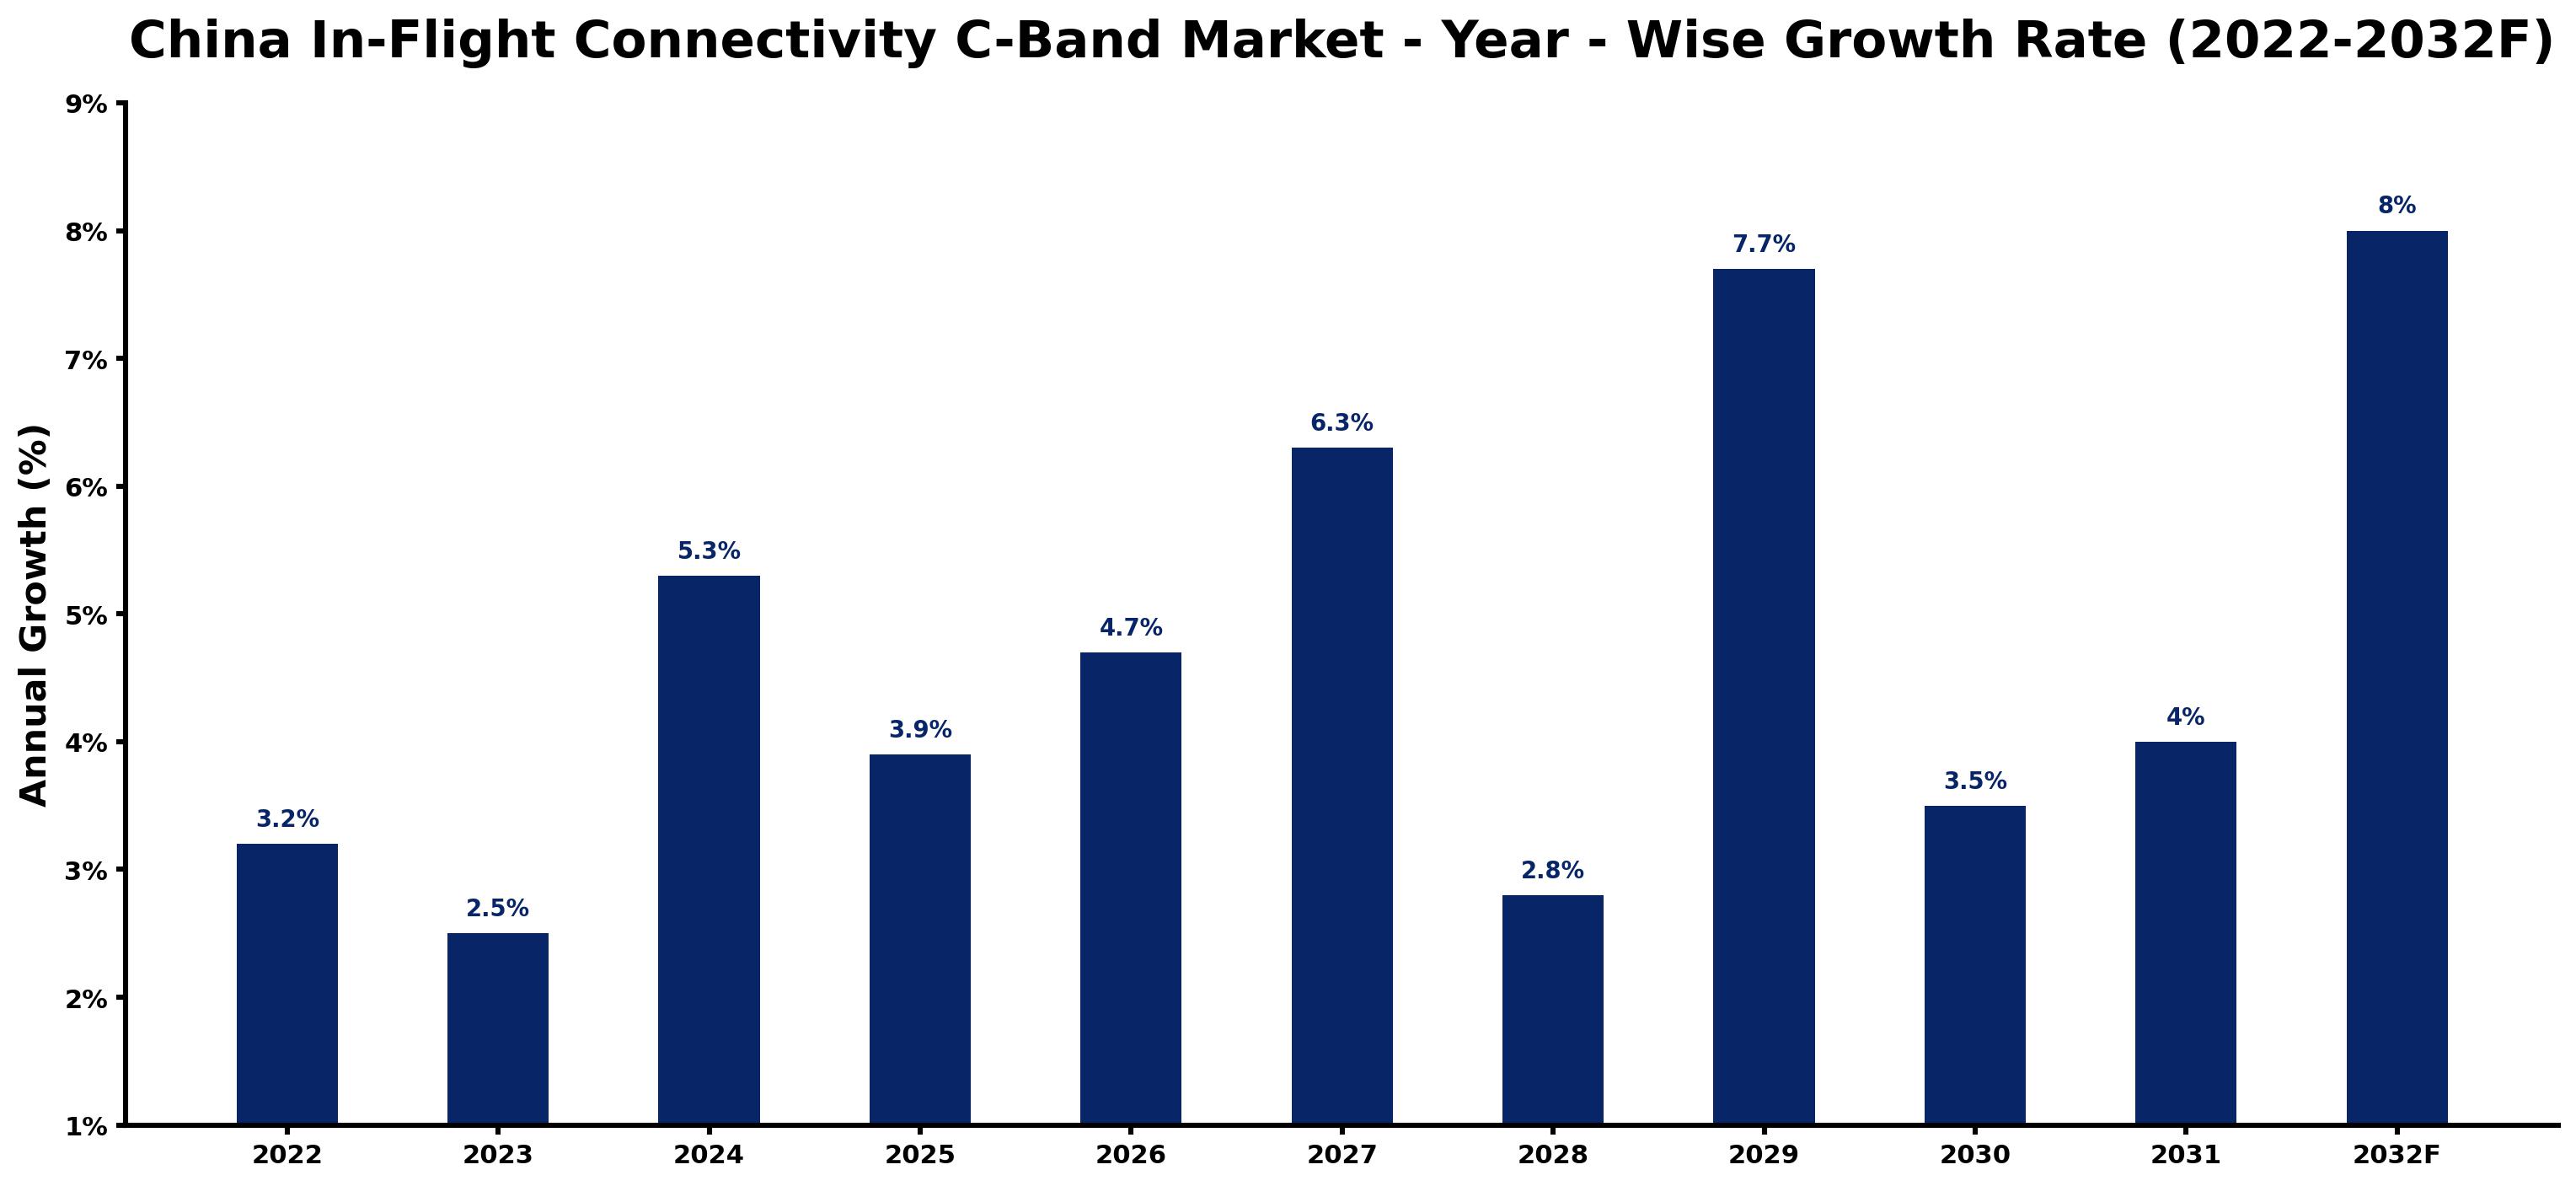
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.2 | The aviation sector experienced steady demand for connectivity services amid recovery efforts. |
| 2023 | 2.5 | Growth slowed due to ongoing adjustments in service offerings and market conditions. |
| 2024 | 5.3 | Increased passenger traffic and service improvements drove a faster growth rate. |
| 2025 | 3.9 | Demand for in-flight connectivity services remained strong but showed signs of moderation. |
| 2026 | 4.7 | The 'Aviation Connectivity Enhancement Program' is expected to improve growth. |
| 2027 | 6.3 | The expansion of commercial airlines and routes will stimulate higher demand for connectivity. |
| 2028 | 2.8 | Market growth is projected to slow as competition intensifies among service providers. |
| 2029 | 7.7 | Rising passenger expectations for connectivity services will accelerate market growth. |
| 2030 | 3.5 | Growth will moderate as the market adjusts to new service standards and expectations. |
| 2031 | 4.0 | Technological improvements and regulatory support will help boost growth rates. |
| 2032 | 8.0 | The market is expected to peak due to significant investments in connectivity technologies. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China In-Flight Connectivity C-Band Market Synopsis
The China In-Flight Connectivity C-Band Market refers to satellite communication systems that provide internet and communication services to aircraft. This technology integrates satellite technology with onboard equipment to deliver broadband internet, voice communication, and data services. The market is expanding due to a passenger base exceeding 600 million annually and increasing investments in connectivity technologies, projected to surpass 100 million yuan by 2025. Standards set by the Civil Aviation Administration of China further improve service quality, driving demand.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing passenger base exceeding 600 million annually drives demand for connectivity services. | Driver | High | Inflight Wi-Fi |
| Investment in connectivity technologies is expected to exceed 100 million yuan by 2025. | Driver | High | C-Band Transceivers |
| The increasing number of commercial airlines presents opportunities for connectivity providers. | Opportunity | High | Commercial Aircraft |
| The expansion of business jets necessitates high-end connectivity solutions. | Opportunity | Medium | Business Jets |
| High costs associated with technology upgrades can limit market expansion. | Restraint | High | C-Band Transceivers |
| Regulatory compliance can slow down the deployment of new systems. | Restraint | Medium | Inflight Wi-Fi |
| Supply chain disruptions can delay equipment availability for service providers. | Challenge | High | Equipment Vendors |
| Intense competition among service providers can lead to pricing pressures. | Challenge | Medium | Satcom Providers |
Evaluation of Drivers in China In-Flight Connectivity C-Band Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increasing passenger demand for reliable internet services during flights. | Inflight Wi-Fi | The growing passenger base of over 600 million annually drives airlines to improve connectivity offerings. |
| Technological advancements in satellite communication systems. | C-Band Transceivers | The average speed of in-flight internet services is projected to reach 50 Mbps by 2025, prompting upgrades. |
| Investment in aviation infrastructure and connectivity technologies. | C-Band Radomes | China's aerospace industry plans to invest over 100 million yuan in connectivity technologies by 2025. |
| Support for improved connectivity standards from regulatory bodies. | Ground-to-Air | The Civil Aviation Administration of China has set standards that improve service quality and reliability. |
| Expansion of commercial airlines and routes increases demand for connectivity. | Commercial Aircraft | China's aviation sector has over 300 commercial airlines operating as of 2023. |
The In-Flight Connectivity C-Band market in China is expanding as passenger demand for reliable internet services rises, driven by a base of over 600 million annually. Technological advancements in satellite communication systems are facilitating better connectivity, with average in-flight internet speeds projected to reach 50 Mbps by 2025. Investment in aviation infrastructure is substantial, with over 100 million yuan allocated for connectivity technologies by 2025. The expansion of commercial airlines further fuels demand for in-flight connectivity solutions.
Evaluation of Restraints in China In-Flight Connectivity C-Band Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs associated with upgrading technology can limit market growth. | C-Band Transceivers | Investments required for modernising systems can deter smaller airlines from improving their connectivity. |
| Regulatory compliance can slow down the deployment of new systems. | Inflight Wi-Fi | Meeting the standards set by the Civil Aviation Administration of China requires time and resources. |
| Supply chain disruptions can delay equipment availability for service providers. | Equipment Vendors | Global supply chain issues have affected timely delivery of essential connectivity hardware. |
| Limited awareness of advanced connectivity solutions among smaller airlines. | Commercial Aircraft | Smaller operators may lack the resources to invest in the latest technologies. |
| Intense competition among service providers can lead to pricing pressures. | Satcom Providers | Aggressive pricing strategies can impact profitability and service quality. |
China In-Flight Connectivity C-Band Market Challenges
In the China In-Flight Connectivity C-Band market, buyers struggle with high service costs due to limited competition among providers, resulting in fees that can reach 30%. Many airlines still use outdated onboard systems, which require costly upgrades, delaying the implementation of essential connectivity services. Suppliers face challenges in obtaining timely access to C-Band frequencies, as regulatory approvals from the Ministry of Industry and Information Technology can take several months, hindering service rollouts. Compliance with standards set by the Civil Aviation Administration of China can further increase operational costs for providers, forcing airlines to adjust their pricing strategies.
Trends in the China In-Flight Connectivity C-Band Market
Several trends are reshaping the China In-Flight Connectivity C-Band Market; the most important are set out below.
- Shift from Traditional to Enhanced In-Flight Connectivity: Since 2021, airlines have been modernising their in-flight connectivity systems to satisfy passenger demands. Standards set by the Civil Aviation Administration of China have encouraged many airlines to adopt advanced systems, with over 1,500 Wi-Fi systems installed in commercial aircraft.
- Transition to Higher-Speed Internet Services: As of 2023, the average speed of in-flight internet services is anticipated to reach 50 Mbps by 2025. This shift reflects the growing expectations for dependable connectivity among passengers, especially on long-haul flights.
- Commercial Airlines Prioritising Connectivity Solutions: In recent years, commercial airlines have concentrated on enhancing their in-flight connectivity offerings. With over 300 commercial airlines operating in China, the competition to deliver superior services is intensifying.
- Business Jets Emphasising High-End Connectivity: Since 2022, business jets have increasingly embraced advanced connectivity solutions. This trend indicates the rising demand for premium services among affluent travellers, with the business jet segment expected to grow rapidly.
Investment Opportunities in the China In-Flight Connectivity C-Band Market
The following opportunities in the China In-Flight Connectivity C-Band Market pair current demand with a clear way in.
- Timing is Right for Connectivity Investments: With China's aerospace industry projected to invest over 100 million yuan in connectivity technologies by 2025, suppliers have a clear opportunity to offer advanced solutions to airlines and service providers.
- Demand for In-Flight Wi-Fi Solutions: The in-flight Wi-Fi segment is poised for substantial growth, driven by passenger expectations for connectivity. Airlines are actively pursuing providers to enhance the passenger experience, creating a significant opportunity.
- Expanding Business Jet Market Needs Connectivity: The business jet segment is experiencing increased demand for high-end connectivity solutions. Suppliers can enter this market through partnerships with business jet operators, targeting affluent travellers.
- Commercial Aircraft Fleet Expansion Creates Demand: China's commercial aircraft fleet is expected to grow by 5% annually, leading to heightened demand for connectivity solutions. Suppliers can target this expanding market by offering customised connectivity packages.
Government Initiatives in the China In-Flight Connectivity C-Band Market
In 2022, the Ministry of Industry and Information Technology approved the 'C-Band Frequency Allocation Plan', facilitating improved satellite communication for aviation. This measure builds on the standards set by the Civil Aviation Administration of China, enhancing the regulatory framework for in-flight connectivity systems. The combination of these measures aims to improve service quality and operational efficiency in the aviation sector, benefiting both producers and buyers. Additionally, the 'Aviation Connectivity Enhancement Program' launched by the CAAC in 2021 promotes the integration of advanced connectivity solutions across domestic airlines, ensuring compliance with evolving standards.
The Civil Aviation Administration of China oversees initiatives like the 'Aviation Connectivity Enhancement Program' launched in 2021. This program aims to elevate in-flight internet services across domestic airlines, ensuring that connectivity solutions meet the growing demands of passengers. Furthermore, the National Development and Reform Commission supports projects that enhance satellite communication capabilities, further promoting advancements in the sector. These initiatives collectively aim to raise the standards of in-flight connectivity, enabling airlines to offer better services to their customers.
Future Insight of the China In-Flight Connectivity C-Band Market
The China In-Flight Connectivity C-Band market will undergo transformative changes by 2032, primarily due to advancements in satellite technology and increased investments in connectivity solutions. By 2025, the average speed of in-flight internet services will reach 50 Mbps, greatly improving passenger experience. Enhanced regulatory frameworks will enable quicker approvals for new technologies, allowing for faster deployment. As the fleet of commercial aircraft expands by 5% annually, airlines will actively seek reliable connectivity solutions to meet the rising expectations of their passengers.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Connectivity Type – Satellite-Based Dominated, C-Band Transceivers Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, in 2025, Satellite-Based led the connectivity type split with a 35% share. Satellite-Based connectivity dominates the market share in China as it provides essential global coverage for aircraft operations. With over 1,500 installed in-flight Wi-Fi systems, this technology is vital for meeting the connectivity requirements of both domestic and international flights. Over 2026–2032, C-Band Transceivers are expected to post the fastest growth, at a CAGR of 7.4%. C-Band Transceivers are experiencing rapid growth due to their critical role in efficient signal transmission and reception during flights. The expected investment of over 100 million yuan in connectivity technologies by 2025 will further accelerate this segment's expansion. Suppliers should focus on advancing C-Band Transceiver technology to capture the increasing demand within the aviation sector.
By Application – Inflight Wi-Fi Dominated and Is Expected to Record the Fastest Growth
Inflight Wi-Fi accounted for a 46% market share by application in 2025. Inflight Wi-Fi commands the largest share in the application segment, significantly enhancing passenger experience during flights. With over 600 million passengers annually, the demand for reliable in-flight Wi-Fi services continues to grow. Inflight Wi-Fi is also forecast to expand faster than any other category, at a CAGR of 6.6% over 2026–2032. Inflight Wi-Fi also leads in growth rate as airlines recognise its importance for passenger satisfaction and competitive positioning. The focus on improving in-flight internet speeds to an expected 50 Mbps by 2025 will further stimulate this segment's growth. Providers must prioritise the development of robust in-flight Wi-Fi solutions to meet the rising expectations of passengers.
By Aircraft Type – Commercial Aircraft Dominated, Business Jets Expected to Grow Fastest
Commercial Aircraft held a 52% share of the China In-Flight Connectivity C-Band Market by aircraft type in 2025. Commercial Aircraft account for the largest share in the aircraft type segment, primarily utilising in-flight connectivity services to cater to a vast passenger base. With a projected annual growth of 5% in China's commercial aircraft fleet, this segment's dominance is set to persist. The quickest growth will come from Business Jets, forecast to expand at a CAGR of 6.3% between 2026 and 2032. Business Jets represent the fastest-growing segment as they increasingly adopt high-end connectivity solutions for an enhanced passenger experience. The rising demand for luxury travel and personalised services is driving this growth. Suppliers should tailor connectivity solutions specifically for the business jet market to leverage its rapid expansion.
By Distribution Channel – Satcom Providers Dominated, OEMs Expected to Grow Fastest
The largest distribution channel category in 2025 was Satcom Providers, with a 49% share of total revenue. Satcom Providers hold the largest share in the distribution channel segment, being essential for delivering satellite communication services to aircraft. Their established networks and expertise in satellite technology position them as pivotal players in the in-flight connectivity market. OEMs are projected to grow fastest, at a CAGR of 6.7% during 2026–2032. OEMs are the fastest-growing distribution channel, playing a vital role in integrating connectivity systems into new aircraft. Ongoing advancements in aircraft technology and the need for seamless connectivity are propelling this growth. Suppliers should strengthen partnerships with OEMs to ensure their connectivity solutions are integrated into future aircraft models.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China In-Flight Connectivity C-Band Market Outlook
- Market Size of China In-Flight Connectivity C-Band Market, 2025
- Forecast of China In-Flight Connectivity C-Band Market, 2032
- Historical Data and Forecast of China In-Flight Connectivity C-Band Revenues & Volume for the Period 2022 - 2032F
- China In-Flight Connectivity C-Band Market Trend Evolution
- China In-Flight Connectivity C-Band Market Drivers and Challenges
- China In-Flight Connectivity C-Band Price Trends
- China In-Flight Connectivity C-Band Porter's Five Forces
- China In-Flight Connectivity C-Band Industry Life Cycle
- Historical Data and Forecast of China In-Flight Connectivity C-Band Market Revenues & Volume By Connectivity Type for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity C-Band Market Revenues & Volume By Satellite-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity C-Band Market Revenues & Volume By Ground-to-Air for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity C-Band Market Revenues & Volume By C-Band Transceivers for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity C-Band Market Revenues & Volume By C-Band Radomes for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity C-Band Market Revenues & Volume By Application for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity C-Band Market Revenues & Volume By Broadband Internet for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity C-Band Market Revenues & Volume By Voice + Data Link for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity C-Band Market Revenues & Volume By Inflight Wi-Fi for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity C-Band Market Revenues & Volume By Signal Shielding for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity C-Band Market Revenues & Volume By Aircraft Type for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity C-Band Market Revenues & Volume By Commercial Aircraft for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity C-Band Market Revenues & Volume By Business Jets for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity C-Band Market Revenues & Volume By Cargo Planes for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity C-Band Market Revenues & Volume By Military Aircraft for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity C-Band Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity C-Band Market Revenues & Volume By Satcom Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity C-Band Market Revenues & Volume By Telecom Integrators for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity C-Band Market Revenues & Volume By Equipment Vendors for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity C-Band Market Revenues & Volume By OEMs for the Period 2022 - 2032F
- China In-Flight Connectivity C-Band Import Export Trade Statistics
- Market Opportunity Assessment By Connectivity Type
- Market Opportunity Assessment By Application
- Market Opportunity Assessment By Aircraft Type
- Market Opportunity Assessment By Distribution Channel
- China In-Flight Connectivity C-Band Top Companies Market Share
- China In-Flight Connectivity C-Band Competitive Benchmarking By Technical and Operational Parameters
- China In-Flight Connectivity C-Band Company Profiles
- China In-Flight Connectivity C-Band Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Connectivity Type
- Satellite-Based
- Ground-to-Air
- C-Band Transceivers
- C-Band Radomes
By Application
- Broadband Internet
- Voice + Data Link
- Inflight Wi-Fi
- Signal Shielding
By Aircraft Type
- Commercial Aircraft
- Business Jets
- Cargo Planes
- Military Aircraft
By Distribution Channel
- Satcom Providers
- Telecom Integrators
- Equipment Vendors
- OEMs































