China In-Flight Connectivity Market Size & Growth Rate
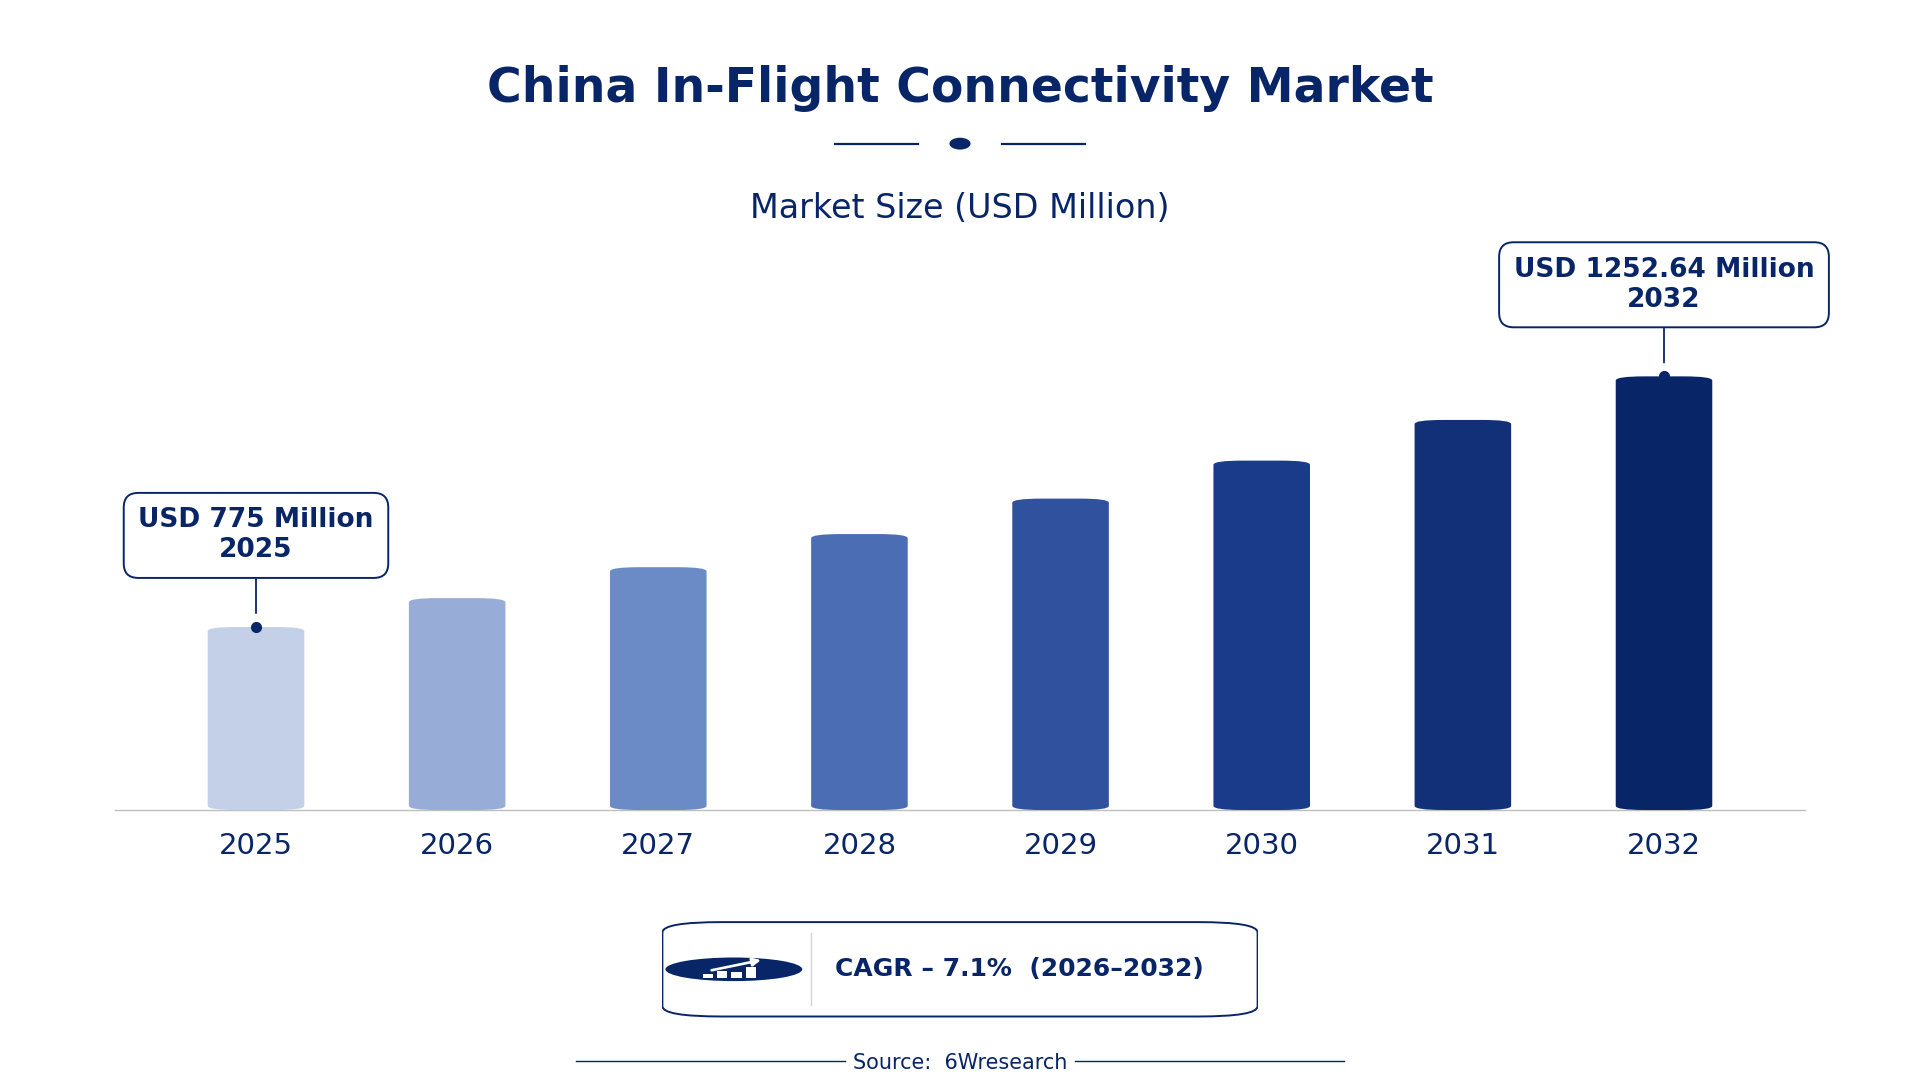
According to 6Wresearch internal database and industry insights, the China In-Flight Connectivity Market was valued at USD 775.0 million in 2025 and is projected to reach USD 1,252.64 million by 2032, growing at a CAGR of approximately 7.1% during 2026–2032.
China In-Flight Connectivity Market Highlights
| Report Metric | Details |
| Report Name | China In-Flight Connectivity Market |
| Market Size 2025 | USD 775.0 million |
| Market Size 2032 | USD 1,252.64 million |
| Absolute Growth 2025–2032 | USD 477.64 million |
| CAGR 2026–2032 | 7.1% |
| Peak Annual Growth | 9.5% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Connectivity Type, 2025 | Satellite-Based (41% share) |
| Leading Frequency Band, 2025 | Ku / Ka / L Band (41% share) |
| Leading Service Type, 2025 | Wi-Fi / VPN (45% share) |
| Leading Distribution Channel, 2025 | Satellite Network Vendors (40% share) |
| Fastest-Growing Connectivity Type | Managed Connectivity (8.7% CAGR) |
| Fastest-Growing Frequency Band | ATG / LTE (9.2% CAGR) |
| Fastest-Growing Service Type | B2B Airline Services (9.7% CAGR) |
| Fastest-Growing Distribution Channel | Telecom Operators (8.5% CAGR) |
| Growing Sector | Aviation |
| Key End Users | Domestic airlines, international carriers, aviation service providers |
China In-Flight Connectivity Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
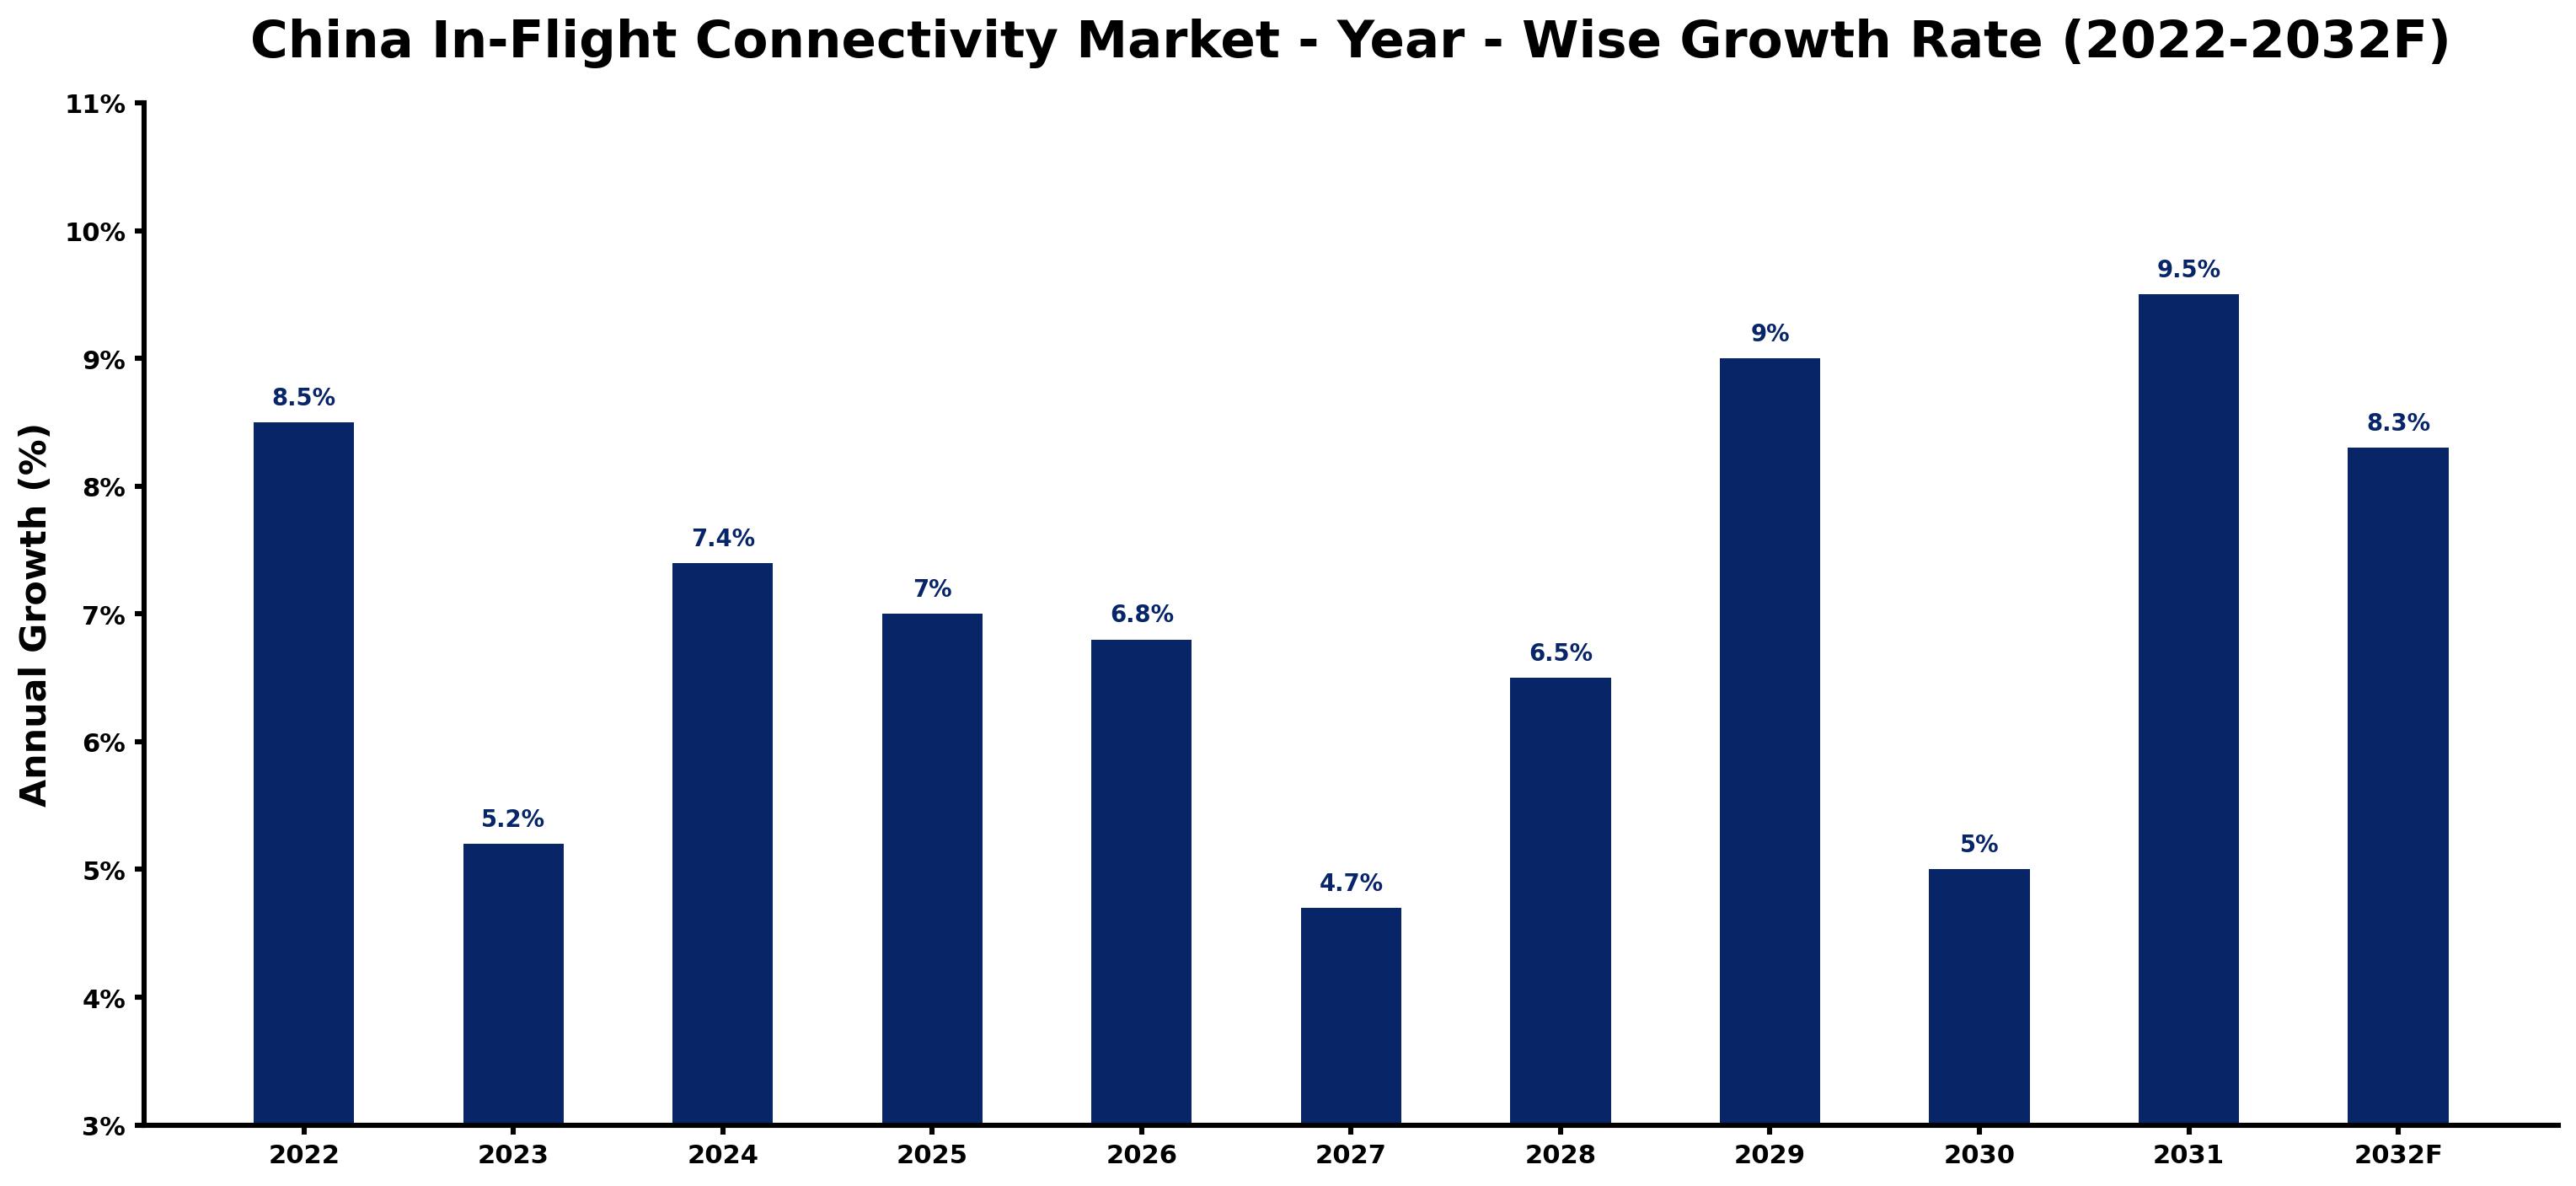
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 8.5 | The aviation sector saw over 300 million passengers, driving connectivity needs. |
| 2023 | 5.2 | Demand for in-flight services slowed as airlines adjusted to evolving travel patterns. |
| 2024 | 7.4 | Investment in Wi-Fi services increased as domestic airlines aimed to improve passenger experience. |
| 2025 | 7.0 | Growth continued, supported by the National Civil Aviation Development Plan emphasizing advanced connectivity solutions. |
| 2026 | 6.8 | Connectivity demand is expected to remain steady as airlines focus on service optimisation under new regulations. |
| 2027 | 4.7 | A slowdown is projected as airlines face challenges integrating new technologies into existing systems. |
| 2028 | 6.5 | Investment in managed connectivity systems is expected to rise, improving service offerings for passengers. |
| 2029 | 9.0 | Demand is expected to surge as airlines expand their in-flight service portfolios, enhancing passenger experience. |
| 2030 | 5.0 | A slowdown is projected as airlines face operational adjustments post-expansion of connectivity services. |
| 2031 | 9.5 | Peak growth is expected to be driven by the successful implementation of new connectivity standards set by the CAAC. |
| 2032 | 8.3 | Growth is projected to slow as the market matures, but demand for advanced services remains strong due to increasing passenger expectations. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China In-Flight Connectivity Market Synopsis
In-Flight Connectivity refers to technology enabling internet access and communication services for passengers on aircraft in China. This connectivity is primarily achieved through satellite or air-to-ground systems, providing services like Wi-Fi and streaming. The China In-Flight Connectivity Market is expanding due to increased passenger numbers, with over 300 million in 2022, and investments by domestic airlines to enhance service quality. The Civil Aviation Law of 2020 and the Aviation Connectivity Enhancement Program are key drivers behind this growth, improving safety and service standards in aviation.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising passenger numbers drive demand for in-flight internet services. | Driver | High | Wi-Fi / VPN |
| Investment in managed connectivity systems enhances service offerings for airlines. | Driver | High | Managed Connectivity |
| The Aviation Connectivity Enhancement Program aims for 80% coverage by 2025. | Opportunity | High | Satellite-Based |
| Growing demand for B2B airline services presents new market potential. | Opportunity | Medium | B2B Airline Services |
| Challenges in integrating new technologies can slow service rollouts. | Restraint | High | Managed Connectivity |
| High costs associated with infrastructure upgrades may limit expansion. | Restraint | Medium | Satellite-Based |
| Supply chain disruptions affect timely installation of connectivity systems. | Challenge | High | Air-to-Ground |
| Regulatory hurdles can delay the approval of new connectivity solutions. | Challenge | Medium | Hybrid Systems |
Evaluation of Drivers in China In-Flight Connectivity Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increasing passenger numbers drive demand for in-flight connectivity. | Wi-Fi / VPN | In 2022, over 300 million passengers in China required internet access during flights. |
| Investment in managed connectivity systems improves service offerings. | Managed Connectivity | Domestic airlines are investing heavily to improve in-flight services for passengers. |
| The Civil Aviation Law of 2020 mandates improved connectivity standards. | Satellite-Based | This regulation ensures that airlines meet safety and quality requirements for in-flight services. |
| The 2023 Aviation Connectivity Enhancement Program aims for 80% coverage. | Air-to-Ground | This initiative will expand connectivity options across domestic flights, enhancing passenger experience. |
| Growing digital economy increases demand for in-flight services. | B2B Airline Services | The 2022 National Development Plan emphasises digital services in aviation, driving further investment. |
Growth in the In-Flight Connectivity market in China comes from rising passenger numbers, significant investments in connectivity systems, and regulatory support. In 2022, over 300 million passengers required internet access during flights, prompting airlines to improve their service offerings. Domestic airlines are investing heavily to enhance in-flight services, while the Civil Aviation Law of 2020 mandates better connectivity standards. The 2023 Aviation Connectivity Enhancement Program aims for substantial coverage by 2025, expanding options for passengers. The growth of the digital economy is driving demand for B2B airline services, further supporting the market's expansion.
Evaluation of Restraints in China In-Flight Connectivity Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Integration challenges with new technologies can delay service rollouts. | Managed Connectivity | Airlines may struggle with implementing advanced systems, affecting service quality due to complexity. |
| High costs of infrastructure upgrades can limit expansion efforts. | Satellite-Based | Airlines face financial burdens when upgrading connectivity systems, restricting their ability to enhance services. |
| Supply chain disruptions impact timely installation of connectivity systems. | Air-to-Ground | Delays in equipment delivery can hinder service availability for airlines, affecting passenger satisfaction. |
| Regulatory hurdles can complicate the approval of new solutions. | Hybrid Systems | Complex approval processes may slow the introduction of new technologies, limiting service improvements. |
| Limited awareness among passengers about available services can restrict usage. | Wi-Fi / VPN | Many passengers may not be informed about in-flight connectivity options, leading to underutilisation. |
China In-Flight Connectivity Market Challenges
Buyers and suppliers in the China In-Flight Connectivity market encounter rising costs due to high satellite communication expenses, which can exceed 30% of operational costs for airlines. This financial burden limits domestic airlines' capacity to offer affordable connectivity services, negatively affecting passenger satisfaction. A lack of skilled technicians to install and maintain in-flight connectivity systems further complicates the situation, delaying service rollouts and upgrades for airlines. Moreover, the fast-paced evolution of technology requires producers to invest continuously, resulting in higher prices for buyers seeking to meet passenger demands for enhanced services.
Trends in the China In-Flight Connectivity Market
Below mentioned are some of the trends shaping the China In-Flight Connectivity Market growth.
- Domestic Airlines Increasing Wi-Fi Offerings: Domestic airlines are enhancing their Wi-Fi services to align with rising passenger expectations. In 2022, over 300 million passengers travelled, driving the demand for superior connectivity options.
- Shift Towards Managed Connectivity Solutions: Managed connectivity solutions are becoming increasingly common as airlines aim to optimise in-flight services. The 2023 Aviation Connectivity Enhancement Program supports this shift by providing funding for infrastructure improvements.
- Expansion of Satellite-Based Services: Satellite-based connectivity is broadening to reach remote areas, ensuring global coverage for passengers. The Ku-band is primarily utilised for satellite communications in China, improving service availability.
- Growth in B2B Airline Services: B2B airline services are gaining momentum as airlines invest in enhanced connectivity. The 2022 National Development Plan highlights the significance of digital services in aviation, prompting further investments.
Investment Opportunities in the China In-Flight Connectivity Market
Some of the investment opportunities in the China In-Flight Connectivity Market are mentioned below.
- Investment in Managed Connectivity Systems: Now is the time to invest in managed connectivity systems, with a projected growth rate of 8.7% from 2026 to 2032. Domestic airlines are seeking partners to improve their in-flight services and enhance passenger satisfaction.
- Expansion of In-Flight Wi-Fi Services: With over 300 million passengers in 2022, there is a notable gap in Wi-Fi service availability. Airlines in the Shanghai region are looking for local partners to improve connectivity options for their passengers.
- Development of Hybrid Connectivity Solutions: The demand for hybrid systems is growing, with a projected growth rate of 8.7%. Airlines in the Beijing-Tianjin-Hebei region are exploring new technologies to enhance their service offerings.
- Improving Satellite-Based Connectivity: Investment in satellite-based connectivity is vital, with the market expected to grow significantly. Airlines can enter through joint ventures with technology providers to enhance service delivery.
Government Initiatives in the China In-Flight Connectivity Market
The Civil Aviation Law of 2020 mandates enhanced connectivity standards for airlines, ensuring safety and quality in in-flight services. This law requires airlines to implement effective systems for internet access and communication. Additionally, the National Civil Aviation Development Plan (2021) stresses the need for advanced connectivity solutions, aiming to improve passenger experience and operational efficiency in the aviation sector. The Digital Transportation Initiative (2021) allocates funding to enhance digital infrastructure, including in-flight connectivity systems, supporting overall growth in aviation services.
The CAAC initiated the Aviation Connectivity Enhancement Program in 2023, targeting 80% coverage by 2025. This program focuses on improving in-flight internet services across the country. The CAAC also oversees the implementation of regulations for satellite communication services in aviation, streamlining the approval process for new technologies. The agency is responsible for ensuring compliance with safety standards, thereby enhancing the reliability of in-flight connectivity services.
Future Insight of the China In-Flight Connectivity Market
By 2032, the China In-Flight Connectivity market will undergo notable changes driven by national infrastructure initiatives and advancements in satellite technology. The Civil Aviation Administration of China will maintain strict standards to ensure high-quality service, creating a safer travel environment for passengers. With the aviation sector projected to serve 1.5 billion passengers by 2035, airlines will need to significantly improve their connectivity offerings. The integration of new technologies into aircraft will streamline services and elevate the overall passenger experience.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Connectivity Type – Satellite-Based Dominated, Managed Connectivity Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, in 2025, Satellite-Based led the connectivity type split with a 41% share. Satellite-based connectivity leads the market share due to its crucial role in delivering global coverage, especially for long-haul flights over oceans. Airlines operating in remote areas rely heavily on this technology to ensure uninterrupted service for passengers. Managed Connectivity is projected to grow fastest, at a CAGR of 8.7% during 2026–2032. Managed connectivity is growing rapidly as airlines focus on optimising in-flight services to improve passenger satisfaction. The increasing investments by domestic airlines in Wi-Fi services are propelling this segment's growth. Suppliers should prioritise satellite technology solutions to meet the rising demand for comprehensive in-flight connectivity.
By Frequency Band – Ku / Ka / L Band Dominated, ATG / LTE Expected to Grow Fastest
Ku / Ka / L Band took a 41% share of frequency band in 2025, more than any other category. The Ku / Ka / L Band dominates the market share, being extensively used for satellite communications that provide reliable connectivity for passengers. Their widespread adoption across various airlines solidifies their leading position in the market. Over 2026–2032, ATG / LTE is expected to post the fastest growth, at a CAGR of 9.2%. ATG / LTE is experiencing rapid growth, particularly in urban areas where ground-based connectivity complements satellite services. The increasing number of airports adopting these solutions is a key factor driving this segment's expansion. Buyers should assess the advantages of ATG / LTE solutions to enhance connectivity options in specific regions.
By Service Type – Wi-Fi / VPN Dominated, B2B Airline Services Expected to Grow Fastest
Wi-Fi / VPN accounted for a 45% market share by service type in 2025. Wi-Fi / VPN services capture the largest market share as they are the primary means for passengers to access the internet during flights. The strong demand for in-flight internet access ensures this service type remains dominant in the market. The quickest growth will come from B2B Airline Services, forecast to expand at a CAGR of 9.7% between 2026 and 2032. B2B airline services are rapidly growing as airlines seek to enhance their competitive edge through improved in-flight experiences. The heightened focus on connectivity solutions among airlines is driving this segment's growth. Suppliers must focus on developing tailored B2B solutions to meet the specific needs of airlines.
By Distribution Channel – Satellite Network Vendors Dominated, Telecom Operators Expected to Grow Fastest
The largest distribution channel category in 2025 was Satellite Network Vendors, with a 40% share of total revenue. Satellite network vendors hold the largest market share as they provide essential infrastructure for in-flight connectivity, enabling airlines to deliver effective services. Their established networks and partnerships with airlines reinforce their leading position in the market. Telecom Operators are set to record the highest CAGR in this split, 8.5% over 2026–2032. Telecom operators are experiencing significant growth as they facilitate connectivity solutions, particularly in regions where ground-based services are viable. Their expanding role in the aviation sector is a notable factor in this segment's growth. Buyers should explore partnerships with telecom operators to enhance their connectivity offerings.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China In-Flight Connectivity Market Outlook
- Market Size of China In-Flight Connectivity Market, 2025
- Forecast of China In-Flight Connectivity Market, 2032
- Historical Data and Forecast of China In-Flight Connectivity Revenues & Volume for the Period 2022 - 2032F
- China In-Flight Connectivity Market Trend Evolution
- China In-Flight Connectivity Market Drivers and Challenges
- China In-Flight Connectivity Price Trends
- China In-Flight Connectivity Porter's Five Forces
- China In-Flight Connectivity Industry Life Cycle
- Historical Data and Forecast of China In-Flight Connectivity Market Revenues & Volume By Connectivity Type for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity Market Revenues & Volume By Satellite-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity Market Revenues & Volume By Air-to-Ground for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity Market Revenues & Volume By Hybrid Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity Market Revenues & Volume By Managed Connectivity for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity Market Revenues & Volume By Frequency Band for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity Market Revenues & Volume By Ku / Ka / L Band for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity Market Revenues & Volume By ATG / LTE for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity Market Revenues & Volume By Satellite + ATG for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity Market Revenues & Volume By Subscription Model for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity Market Revenues & Volume By Service Type for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity Market Revenues & Volume By Wi-Fi / VPN for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity Market Revenues & Volume By Streaming / Messaging for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity Market Revenues & Volume By Real-Time Browsing for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity Market Revenues & Volume By B2B Airline Services for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity Market Revenues & Volume By Satellite Network Vendors for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity Market Revenues & Volume By Telecom Operators for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity Market Revenues & Volume By Aircraft OEM Integration for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Connectivity Market Revenues & Volume By SaaS Platforms for the Period 2022 - 2032F
- China In-Flight Connectivity Import Export Trade Statistics
- Market Opportunity Assessment By Connectivity Type
- Market Opportunity Assessment By Frequency Band
- Market Opportunity Assessment By Service Type
- Market Opportunity Assessment By Distribution Channel
- China In-Flight Connectivity Top Companies Market Share
- China In-Flight Connectivity Competitive Benchmarking By Technical and Operational Parameters
- China In-Flight Connectivity Company Profiles
- China In-Flight Connectivity Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Connectivity Type
- Satellite-Based
- Air-to-Ground
- Hybrid Systems
- Managed Connectivity
By Frequency Band
- Ku / Ka / L Band
- ATG / LTE
- Satellite + ATG
- Subscription Model
By Service Type
- Wi-Fi / VPN
- Streaming / Messaging
- Real-Time Browsing
- B2B Airline Services
By Distribution Channel
- Satellite Network Vendors
- Telecom Operators
- Aircraft OEM Integration
- SaaS Platforms































