China In-Flight Data Link Market Size & Growth Rate
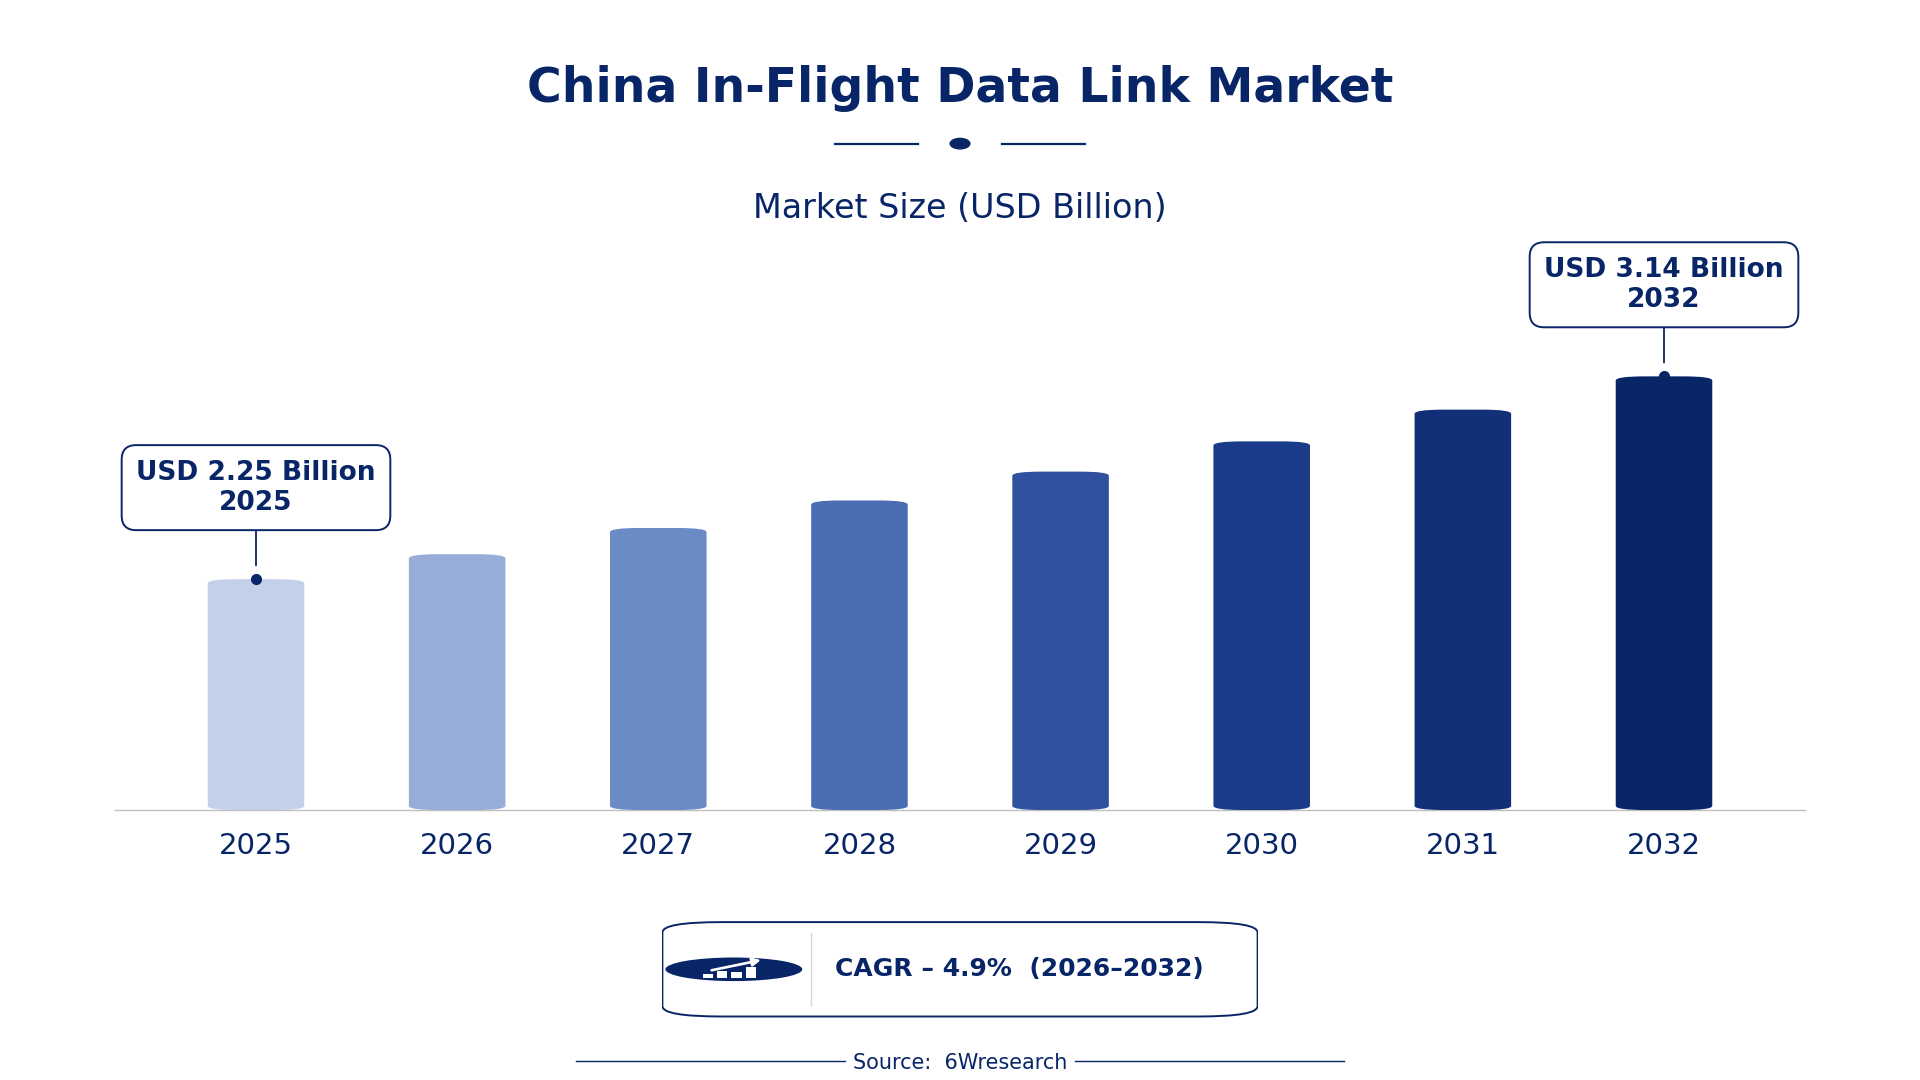
According to 6Wresearch internal database and industry insights, the China In-Flight Data Link Market was valued at USD 2.25 billion in 2025 and is projected to reach USD 3.14 billion by 2032, growing at a CAGR of approximately 4.9% during 2026–2032.
China In-Flight Data Link Market Highlights
| Report Metric | Details |
| Report Name | China In-Flight Data Link Market |
| Market Size 2025 | USD 2.25 billion |
| Market Size 2032 | USD 3.14 billion |
| Absolute Growth 2025–2032 | USD 0.89 billion |
| CAGR 2026–2032 | 4.9% |
| Peak Annual Growth | 7.5% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Link Type, 2025 | ACARS (37% share) |
| Leading Technology Used, 2025 | VHF / SATCOM (44% share) |
| Leading Use Case, 2025 | Aircraft Communication (49% share) |
| Leading Distribution Channel, 2025 | Avionics Suppliers (38% share) |
| Fastest-Growing Link Type | CPDLC (6.6% CAGR) |
| Fastest-Growing Technology Used | Data Link Messaging (5.9% CAGR) |
| Fastest-Growing Use Case | ATC Interaction (7.6% CAGR) |
| Fastest-Growing Distribution Channel | OEM Integrators (7.1% CAGR) |
| Growing Sector | Aviation |
| Key End Users | Domestic airlines, regional airports, avionics suppliers, OEM integrators |
China In-Flight Data Link Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
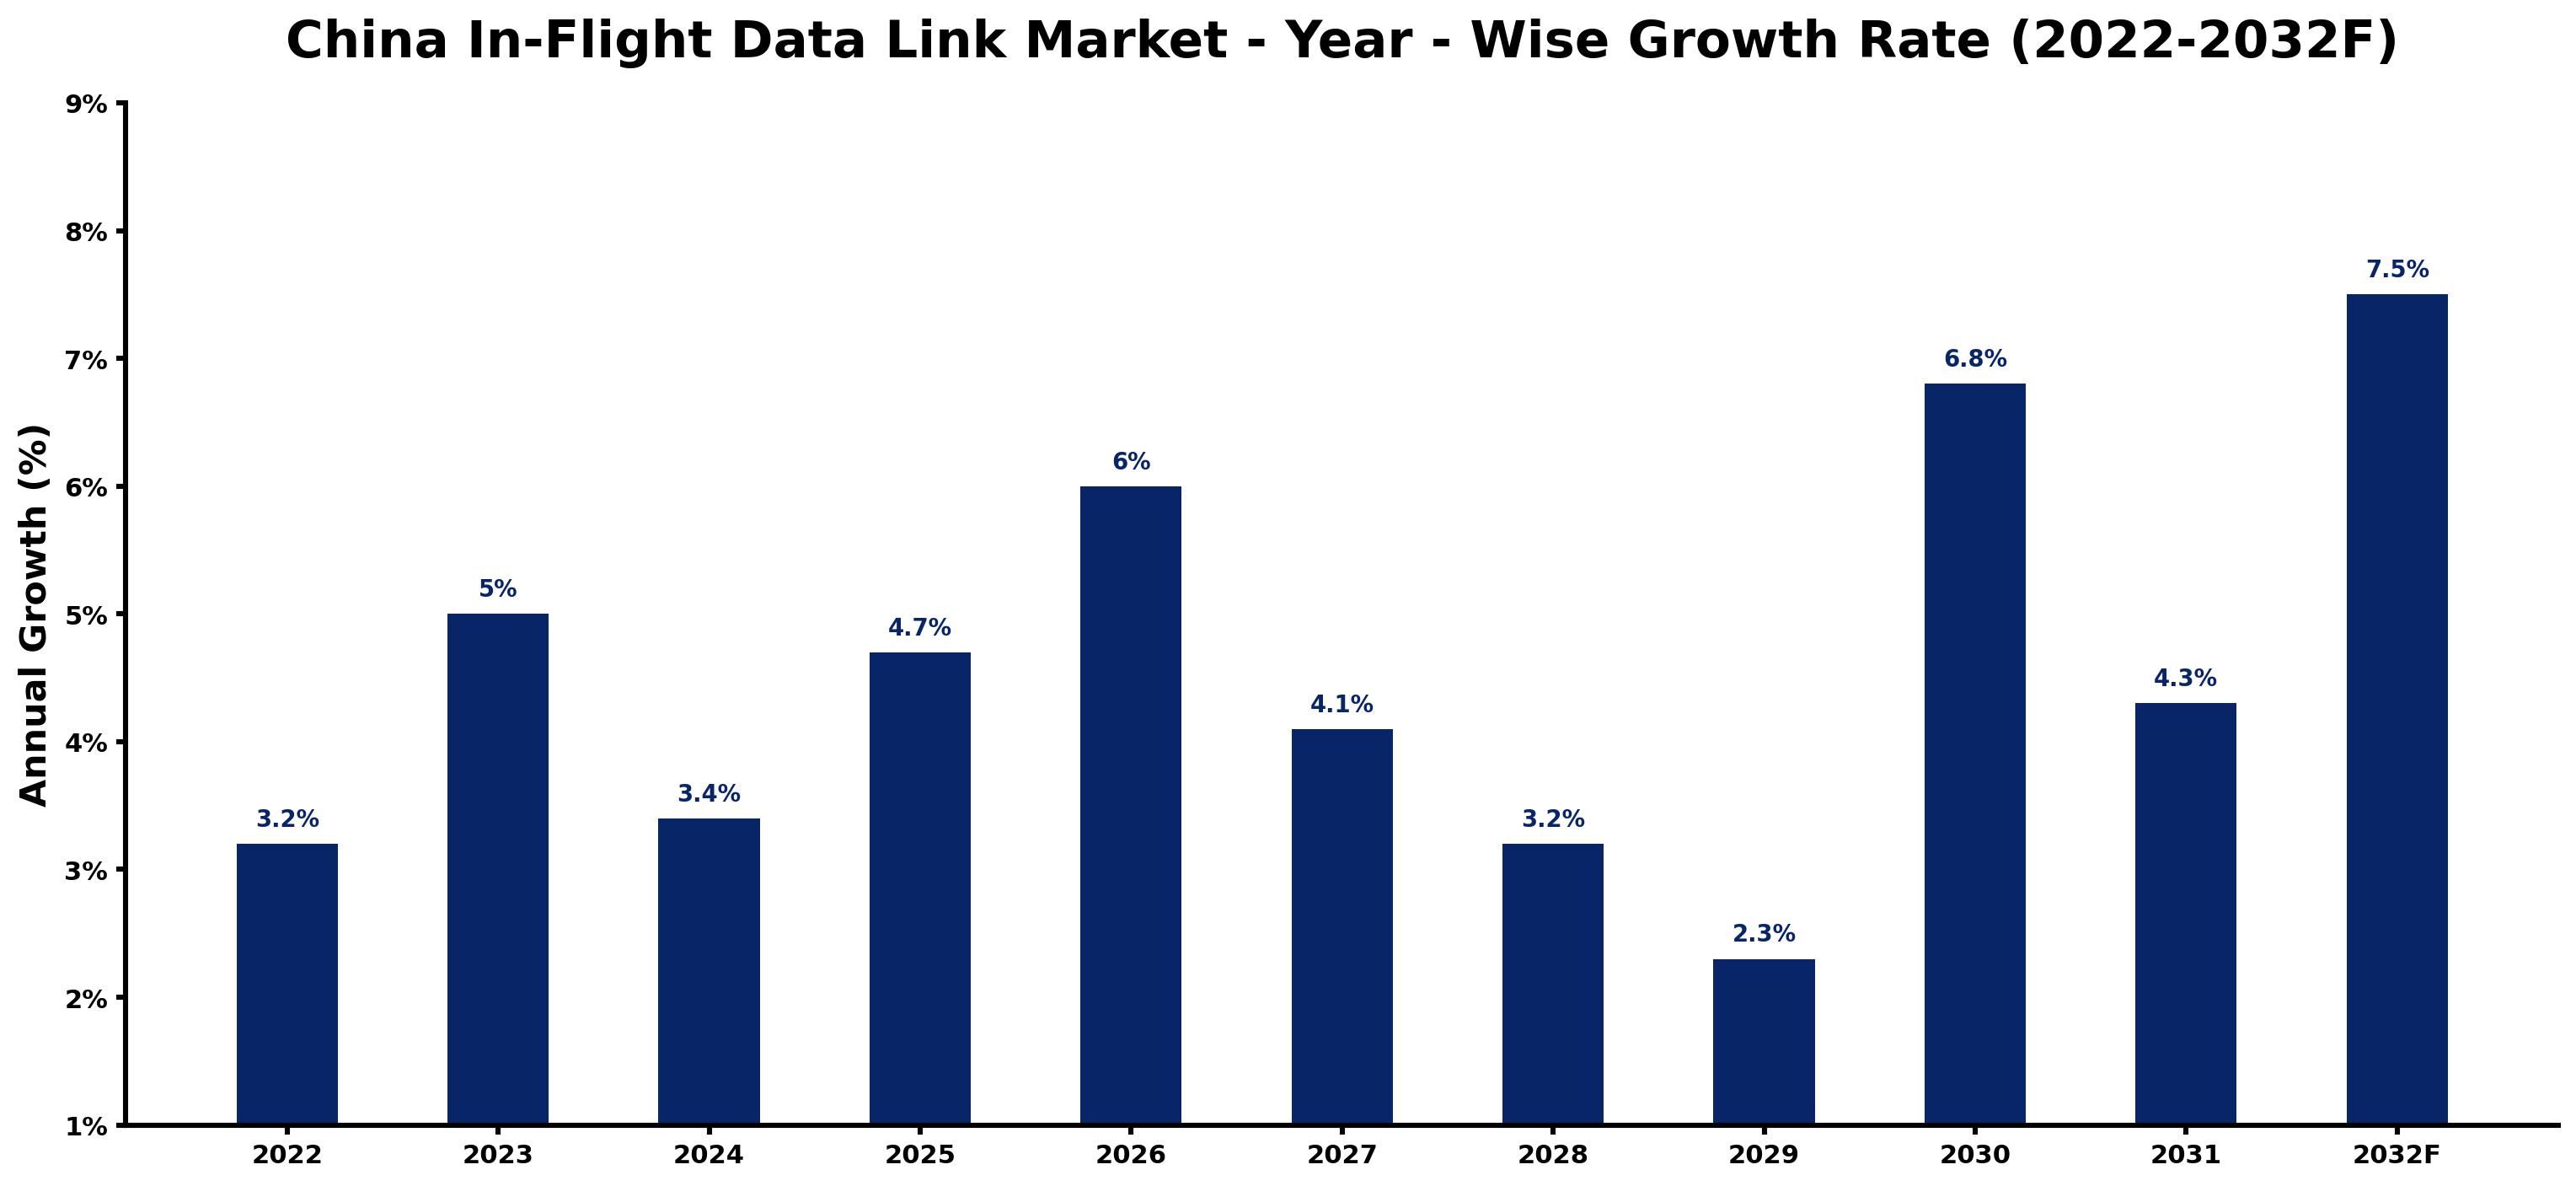
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.2 | The aviation sector experienced steady demand with over 700 million passengers served. |
| 2023 | 5.0 | Growth accelerated due to the CAAC's new standards for data link communications. |
| 2024 | 3.4 | The market saw a slowdown as demand stabilised following rapid increases in previous years. |
| 2025 | 4.7 | Demand rose again as airlines invested in advanced communication technologies under the National Civil Aviation Development Plan. |
| 2026 | 6.0 | The implementation of the National Civil Aviation Development Plan spurred growth. |
| 2027 | 4.1 | A slowdown occurred as the market adjusted to previous high growth rates. |
| 2028 | 3.2 | Demand continued to slow as market conditions normalised after rapid expansion. |
| 2029 | 2.3 | The market experienced a further slowdown as adoption rates began to plateau. |
| 2030 | 6.8 | Growth rebounded as new aircraft deliveries increased demand for data link systems. |
| 2031 | 4.3 | A slowdown was noted as the market stabilised after the previous year's surge. |
| 2032 | 7.5 | The market is projected to peak as investment in satellite communication systems rises. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China In-Flight Data Link Market Synopsis
In-Flight Data Link in China represents a communication technology that enables real-time data exchange between aircraft and ground systems. This technology utilises satellite and radio systems to ensure reliable connectivity for aircraft communication and air traffic control. The China In-Flight Data Link Market is expanding due to rising passenger numbers and the need for improved safety and operational efficiency. By 2025, the aviation sector is expected to serve over 700 million passengers, driving demand for advanced communication systems. The CAAC's recent initiatives further support this upward trend.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing passenger numbers driving demand for reliable communication systems | Driver | High | Aircraft Communication |
| Investment in advanced data link technologies by domestic airlines | Driver | High | VHF / SATCOM |
| Growing need for improved air traffic management systems | Opportunity | High | ATC Interaction |
| Expansion of regional airports enhancing data link capabilities | Opportunity | Medium | Satellite Providers |
| High costs associated with upgrading existing communication systems | Restraint | High | OEM Integrators |
| Limited adoption of certain data link technologies across all aircraft | Restraint | Medium | VDL Mode 2 |
| Buyers face challenges in integrating new technologies into existing systems | Challenge | High | Avionics Suppliers |
| Suppliers struggle with the rapid pace of technological advancements | Challenge | Medium | Navigation Vendors |
Evaluation of Drivers in China In-Flight Data Link Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising passenger numbers necessitating improved communication systems | Aircraft Communication | China's aviation sector is expected to serve over 700 million passengers by 2025. |
| Investment in satellite communication systems by airlines | VHF / SATCOM | China has invested significantly in upgrading its aviation infrastructure since 2020. |
| Implementation of the National Civil Aviation Development Plan | ATC Interaction | The plan aims to enhance air traffic control systems by 2025, improving overall efficiency. |
| Growing demand for operational efficiency in aviation | Data Link Messaging | The CAAC has set standards for data link communications to improve operational efficiency. |
| Increased focus on safety measures in aviation | Crew/Flight Info Relay | The Aviation Safety Enhancement Program prioritises advanced communication technologies to improve safety. |
Market growth in China for In-Flight Data Link rests on rising passenger numbers, increased investment in satellite communication systems, and the implementation of the National Civil Aviation Development Plan. The aviation sector is expected to serve over 700 million passengers by 2025, driving demand for reliable communication systems. Investments in aviation infrastructure since 2020 have further boosted the market, leading to greater adoption of advanced technologies. Standards for data link communications improve operational efficiency, ensuring that airlines can meet the growing demands of air traffic. The focus on implementing advanced communication systems reinforces safety as a priority for the industry.
Evaluation of Restraints in China In-Flight Data Link Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs associated with upgrading communication systems | OEM Integrators | Upgrading to advanced data link technologies requires considerable financial investment. |
| Limited adoption of VDL Mode 2 technology across the industry | VDL Mode 2 | VDL Mode 2 is not universally adopted, limiting its market penetration. |
| Integration challenges for new technologies into existing systems | Avionics Suppliers | Buyers face difficulties in adapting new systems to legacy aircraft. |
| Competition among suppliers for advanced technology solutions | Navigation Vendors | Suppliers must continually innovate to keep up with rapid technological changes. |
| Regulatory compliance costs for new communication technologies | Satellite Providers | Meeting CAAC standards for data link communications incurs additional costs. |
China In-Flight Data Link Market Challenges
Buyers in the China In-Flight Data Link market encounter a skills shortage, as the rapid pace of communication technology development outstrips available training programs, causing delays for airlines in adopting new systems. Suppliers face high costs, with infrastructure upgrades consuming over 30% of their annual budgets, limiting their capacity to invest in advanced solutions. Regulatory compliance is another hurdle, as the Civil Aviation Administration of China enforces stringent standards that can prolong the certification process for new technologies, impacting airlines' operational timelines. Integration challenges arise, as outdated systems frequently struggle to accommodate new data link technologies, resulting in inefficiencies for airlines.
Trends in the China In-Flight Data Link Market
The trends below show where the China In-Flight Data Link Market is heading.
- Shift towards Enhanced Air Traffic Management Systems: China is updating its air traffic management systems to incorporate advanced data link technologies. The CAAC's 2023 program aims to improve efficiency, with funding allocated for upgrades across regional airports, enhancing overall communication capabilities.
- Transition from Traditional to Satellite Communication Systems: The aviation sector is increasingly adopting satellite communication systems for in-flight data links. By 2025, significant investments are expected to improve satellite capabilities, enhancing connectivity for airlines operating in China.
- Emergence of Advanced Communication Standards: The CAAC's 2022 Digital Aviation Strategy integrates modern data link technologies into the national framework. This initiative is set to standardise communication protocols across the industry, enhancing operational efficiency and safety.
- Growth in Aircraft Communication Demand: Aircraft Communication is projected to hold a 49% market share by 2025. This demand is driven by the increasing need for reliable communication systems to support the growing passenger traffic in China's aviation sector.
Investment Opportunities in the China In-Flight Data Link Market
Several openings in the China In-Flight Data Link Market merit attention from investors.
- Partnerships for Technology Integration: Local partnerships with OEM Integrators are essential for supplying advanced data link systems. With the aviation sector projected to serve over 700 million passengers by 2025, collaboration can facilitate market entry.
- Investment in Satellite Communication Systems: Investing in satellite communication technologies is timely as demand grows. The CAAC's funding for upgrading regional airports presents opportunities for suppliers to enhance their offerings.
- Focus on Regional Airport Upgrades: Regional airports are prioritising upgrades to their data link capabilities. With over 200 airports equipped with advanced technology, suppliers can target this growing segment effectively.
- Timing for Enhanced Safety Measures: The ongoing Aviation Safety Enhancement Program creates a timely opportunity for suppliers. Investing in advanced communication technologies aligns with the government's focus on improving aviation safety.
Government Initiatives in the China In-Flight Data Link Market
In 2021, the CAAC launched the 'Civil Aviation Development Plan' to improve aviation safety and efficiency through advanced communication technologies. This measure builds on previous regulations by setting clear standards for data link communications, ensuring that all new systems meet modern safety requirements. As a result, producers must adhere to these standards when developing new technologies, driving innovation in the sector. Additionally, the CAAC's updated 'National Air Traffic Management Plan' in 2022 incorporates modern data link systems for better air traffic control. This initiative aims to enhance communication capabilities across regional airports, ensuring they meet the latest technological standards.
The CAAC oversees the implementation of various initiatives, including funding for upgrading satellite communication systems in regional airports. This funding supports projects that integrate advanced communication systems, enabling producers to enhance their offerings. By approving these projects, the CAAC facilitates the overall growth of the In-Flight Data Link market in China, ensuring that communication technologies align with modern safety and operational standards.
Future Insight of the China In-Flight Data Link Market
Several forward-looking factors should support the China In-Flight Data Link market by 2032. The aviation sector is projected to accommodate over 700 million passengers, driving demand for effective communication systems. The government's initiative to improve air traffic management will enhance operational safety and efficiency. Investments in satellite communication infrastructure will facilitate better connectivity, allowing airlines to handle increased air traffic more effectively. These developments will create opportunities for suppliers and improve the safety and operational capabilities of airlines.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Link Type – ACARS Dominated, CPDLC Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, ACARS accounted for a 37% market share by link type in 2025. ACARS commands the largest market share as it is widely implemented in commercial aircraft for operational messaging, ensuring effective communication. The endorsement of its use by the Civil Aviation Administration of China has solidified its position as a standard across the aviation sector. Over 2026–2032, CPDLC is expected to post the fastest growth, at a CAGR of 6.6%. The rapid growth of CPDLC is driven by the rising need for efficient air traffic control communication, particularly with the anticipated increase in passenger traffic. This demand for improved communication capabilities will likely accelerate the adoption of CPDLC in the coming years. Suppliers should focus on developing advanced CPDLC solutions to cater to the escalating requirements for efficient air traffic management.
By Technology Used – VHF / SATCOM Dominated, Data Link Messaging Expected to Grow Fastest
The largest technology used category in 2025 was VHF / SATCOM, with a 44% share of total revenue. VHF / SATCOM technology dominates the market due to its critical role in facilitating both voice and data communication in aviation. This technology is essential for maintaining reliable connectivity across China's extensive airspace. The quickest growth will come from Data Link Messaging, forecast to expand at a CAGR of 5.9% between 2026 and 2032. Data Link Messaging is experiencing rapid growth as it becomes fundamental for real-time message exchanges between aircraft and ground systems, particularly with the surge in air traffic. This trend is likely to continue as airlines seek improved operational efficiency. Buyers will benefit from investing in advanced Data Link Messaging systems to ensure effective communication and operational reliability.
By Use Case – Aircraft Communication Dominated, ATC Interaction Expected to Grow Fastest
Aircraft Communication held a 49% share of the China In-Flight Data Link Market by use case in 2025. Aircraft Communication holds the largest share as it is the core function of in-flight data link systems, ensuring vital operational messaging. With China's aviation sector projected to serve over 700 million passengers by 2025, this capability is essential for maintaining safety and efficiency in busy airspace. ATC Interaction is set to record the highest CAGR in this split, 7.6% over 2026–2032. ATC Interaction is witnessing rapid growth due to the increasing demand for real-time communication with air traffic control, essential for managing rising air traffic volumes. This focus on enhanced communication aligns with the government's initiatives to improve air traffic management systems by 2025. Suppliers should focus on developing solutions that enhance ATC Interaction capabilities to address the growing requirements of air traffic management.
By Distribution Channel – Avionics Suppliers Dominated, OEM Integrators Expected to Grow Fastest
In 2025, Avionics Suppliers led the distribution channel split with a 38% share. Avionics Suppliers lead the market as they provide the essential equipment required for the implementation of data link systems in aircraft. Their established relationships with airlines and manufacturers position them as key players, ensuring a reliable supply of technology in the aviation sector. OEM Integrators are projected to grow fastest, at a CAGR of 7.1% during 2026–2032. OEM Integrators are experiencing the fastest growth as they play a crucial role in integrating data link systems into new aircraft, reflecting the industry's shift towards advanced communication technologies. This trend is supported by the increasing number of aircraft deliveries in China, driving demand for their services. Suppliers must work closely with OEM Integrators to ensure the smooth integration of advanced data link technologies in newly manufactured aircraft.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China In-Flight Data Link Market Outlook
- Market Size of China In-Flight Data Link Market, 2025
- Forecast of China In-Flight Data Link Market, 2032
- Historical Data and Forecast of China In-Flight Data Link Revenues & Volume for the Period 2022 - 2032F
- China In-Flight Data Link Market Trend Evolution
- China In-Flight Data Link Market Drivers and Challenges
- China In-Flight Data Link Price Trends
- China In-Flight Data Link Porter's Five Forces
- China In-Flight Data Link Industry Life Cycle
- Historical Data and Forecast of China In-Flight Data Link Market Revenues & Volume By Link Type for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Data Link Market Revenues & Volume By ACARS for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Data Link Market Revenues & Volume By CPDLC for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Data Link Market Revenues & Volume By VDL Mode 2 for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Data Link Market Revenues & Volume By ADS-C for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Data Link Market Revenues & Volume By Technology Used for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Data Link Market Revenues & Volume By VHF / SATCOM for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Data Link Market Revenues & Volume By Data Link Messaging for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Data Link Market Revenues & Volume By Digital Radio for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Data Link Market Revenues & Volume By GPS / SAT for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Data Link Market Revenues & Volume By Use Case for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Data Link Market Revenues & Volume By Aircraft Communication for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Data Link Market Revenues & Volume By ATC Interaction for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Data Link Market Revenues & Volume By Crew/Flight Info Relay for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Data Link Market Revenues & Volume By Remote Tracking for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Data Link Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Data Link Market Revenues & Volume By Avionics Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Data Link Market Revenues & Volume By OEM Integrators for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Data Link Market Revenues & Volume By Satellite Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Data Link Market Revenues & Volume By Navigation Vendors for the Period 2022 - 2032F
- China In-Flight Data Link Import Export Trade Statistics
- Market Opportunity Assessment By Link Type
- Market Opportunity Assessment By Technology Used
- Market Opportunity Assessment By Use Case
- Market Opportunity Assessment By Distribution Channel
- China In-Flight Data Link Top Companies Market Share
- China In-Flight Data Link Competitive Benchmarking By Technical and Operational Parameters
- China In-Flight Data Link Company Profiles
- China In-Flight Data Link Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Link Type
- ACARS
- CPDLC
- VDL Mode 2
- ADS-C
By Technology Used
- VHF / SATCOM
- Data Link Messaging
- Digital Radio
- GPS / SAT
By Use Case
- Aircraft Communication
- ATC Interaction
- Crew/Flight Info Relay
- Remote Tracking
By Distribution Channel
- Avionics Suppliers
- OEM Integrators
- Satellite Providers
- Navigation Vendors































