China In-Flight Entertainment Satcom Market Size & Growth Rate
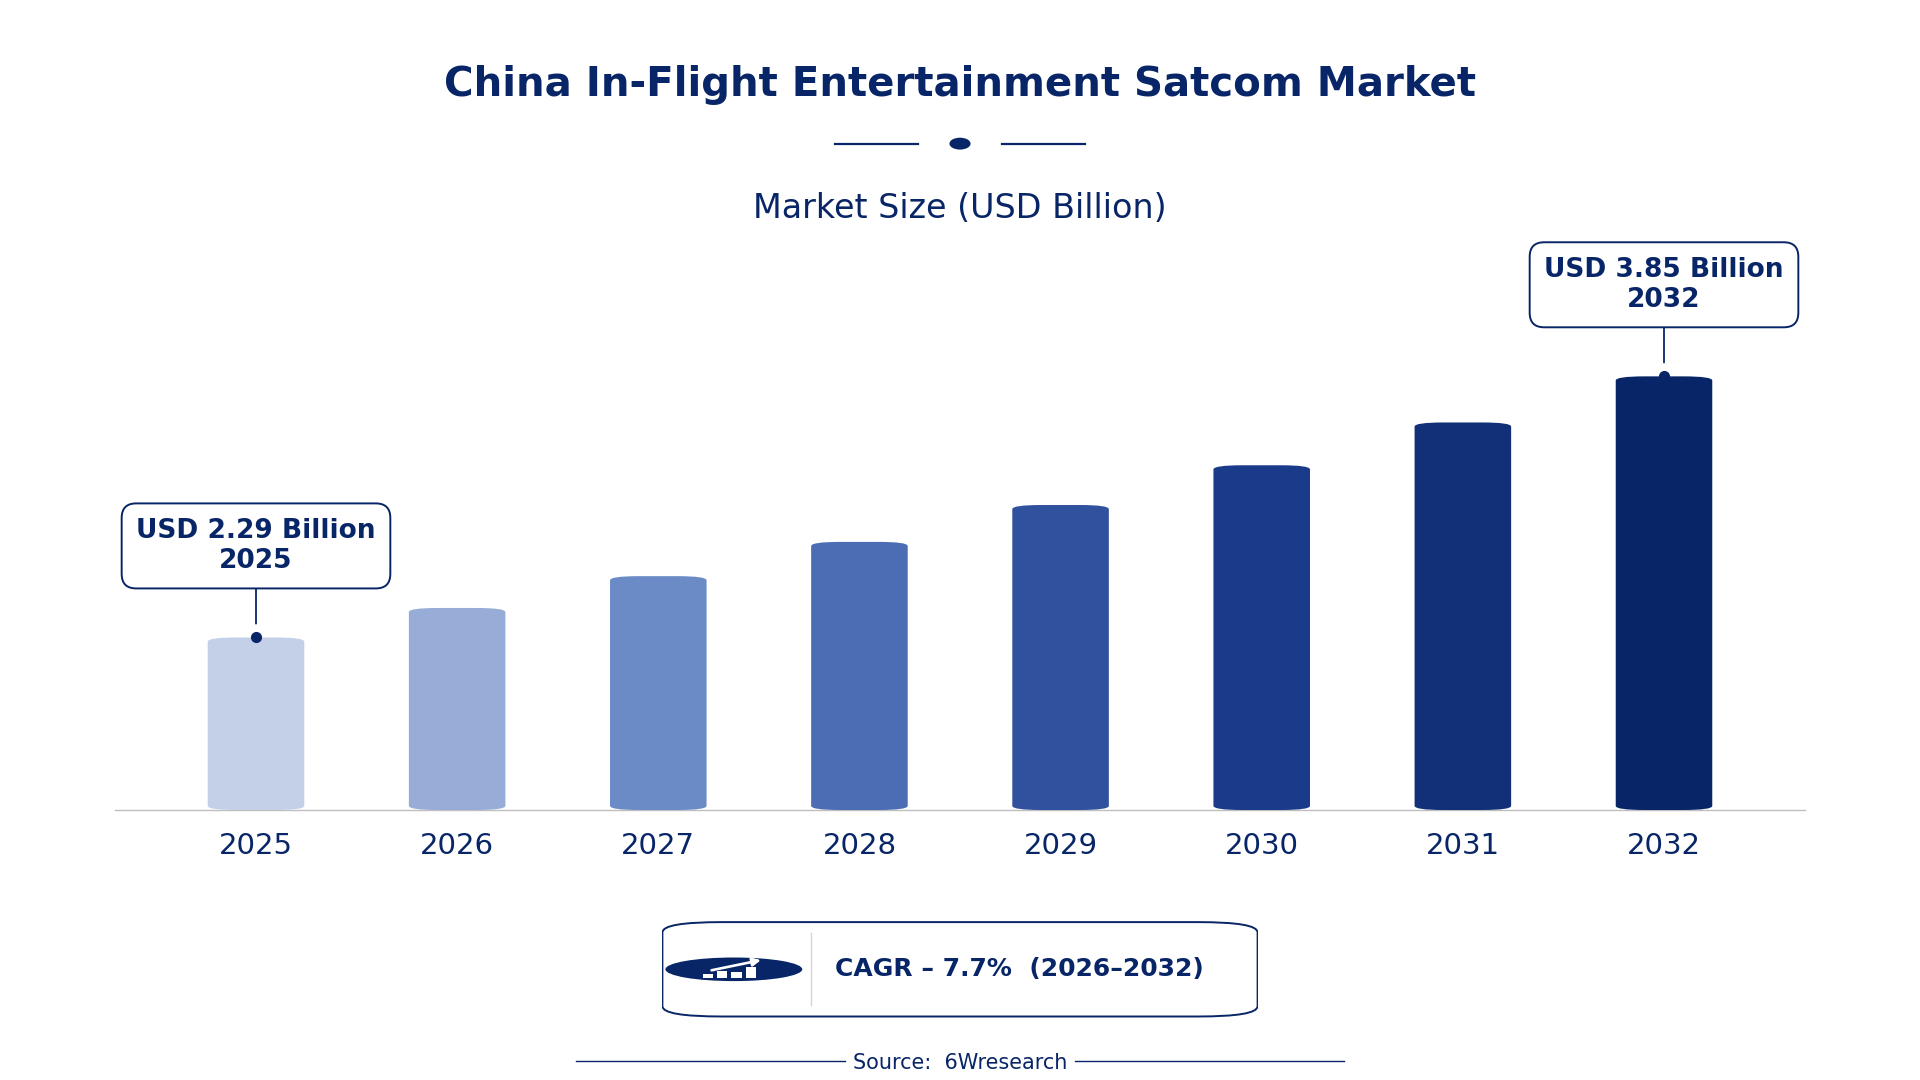
According to 6Wresearch internal database and industry insights, the China In-Flight Entertainment Satcom Market was valued at USD 2.29 billion in 2025 and is projected to reach USD 3.85 billion by 2032, growing at a CAGR of approximately 7.7% during 2026–2032.
China In-Flight Entertainment Satcom Market Highlights
| Report Metric | Details |
| Report Name | China In-Flight Entertainment Satcom Market |
| Market Size 2025 | USD 2.29 billion |
| Market Size 2032 | USD 3.85 billion |
| Absolute Growth 2025–2032 | USD 1.56 billion |
| CAGR 2026–2032 | 7.7% |
| Peak Annual Growth | 9.8% in 2026 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Satcom Type, 2025 | GEO Satcom (51% share) |
| Leading Orbit Type, 2025 | Fixed / Mobile (35% share) |
| Leading Connectivity Mode, 2025 | Video Streaming (45% share) |
| Leading Distribution Channel, 2025 | Satellite Operators (52% share) |
| Fastest-Growing Satcom Type | LEO Satcom (9.4% CAGR) |
| Fastest-Growing Orbit Type | Low-Latency Internet (10.5% CAGR) |
| Fastest-Growing Connectivity Mode | Gaming / Conferencing (9.6% CAGR) |
| Fastest-Growing Distribution Channel | OEM Aircraft Integrators (9.1% CAGR) |
| Growing Sector | aviation |
| Key End Users | domestic airlines, international airlines, satellite service providers, aircraft manufacturers |
China In-Flight Entertainment Satcom Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
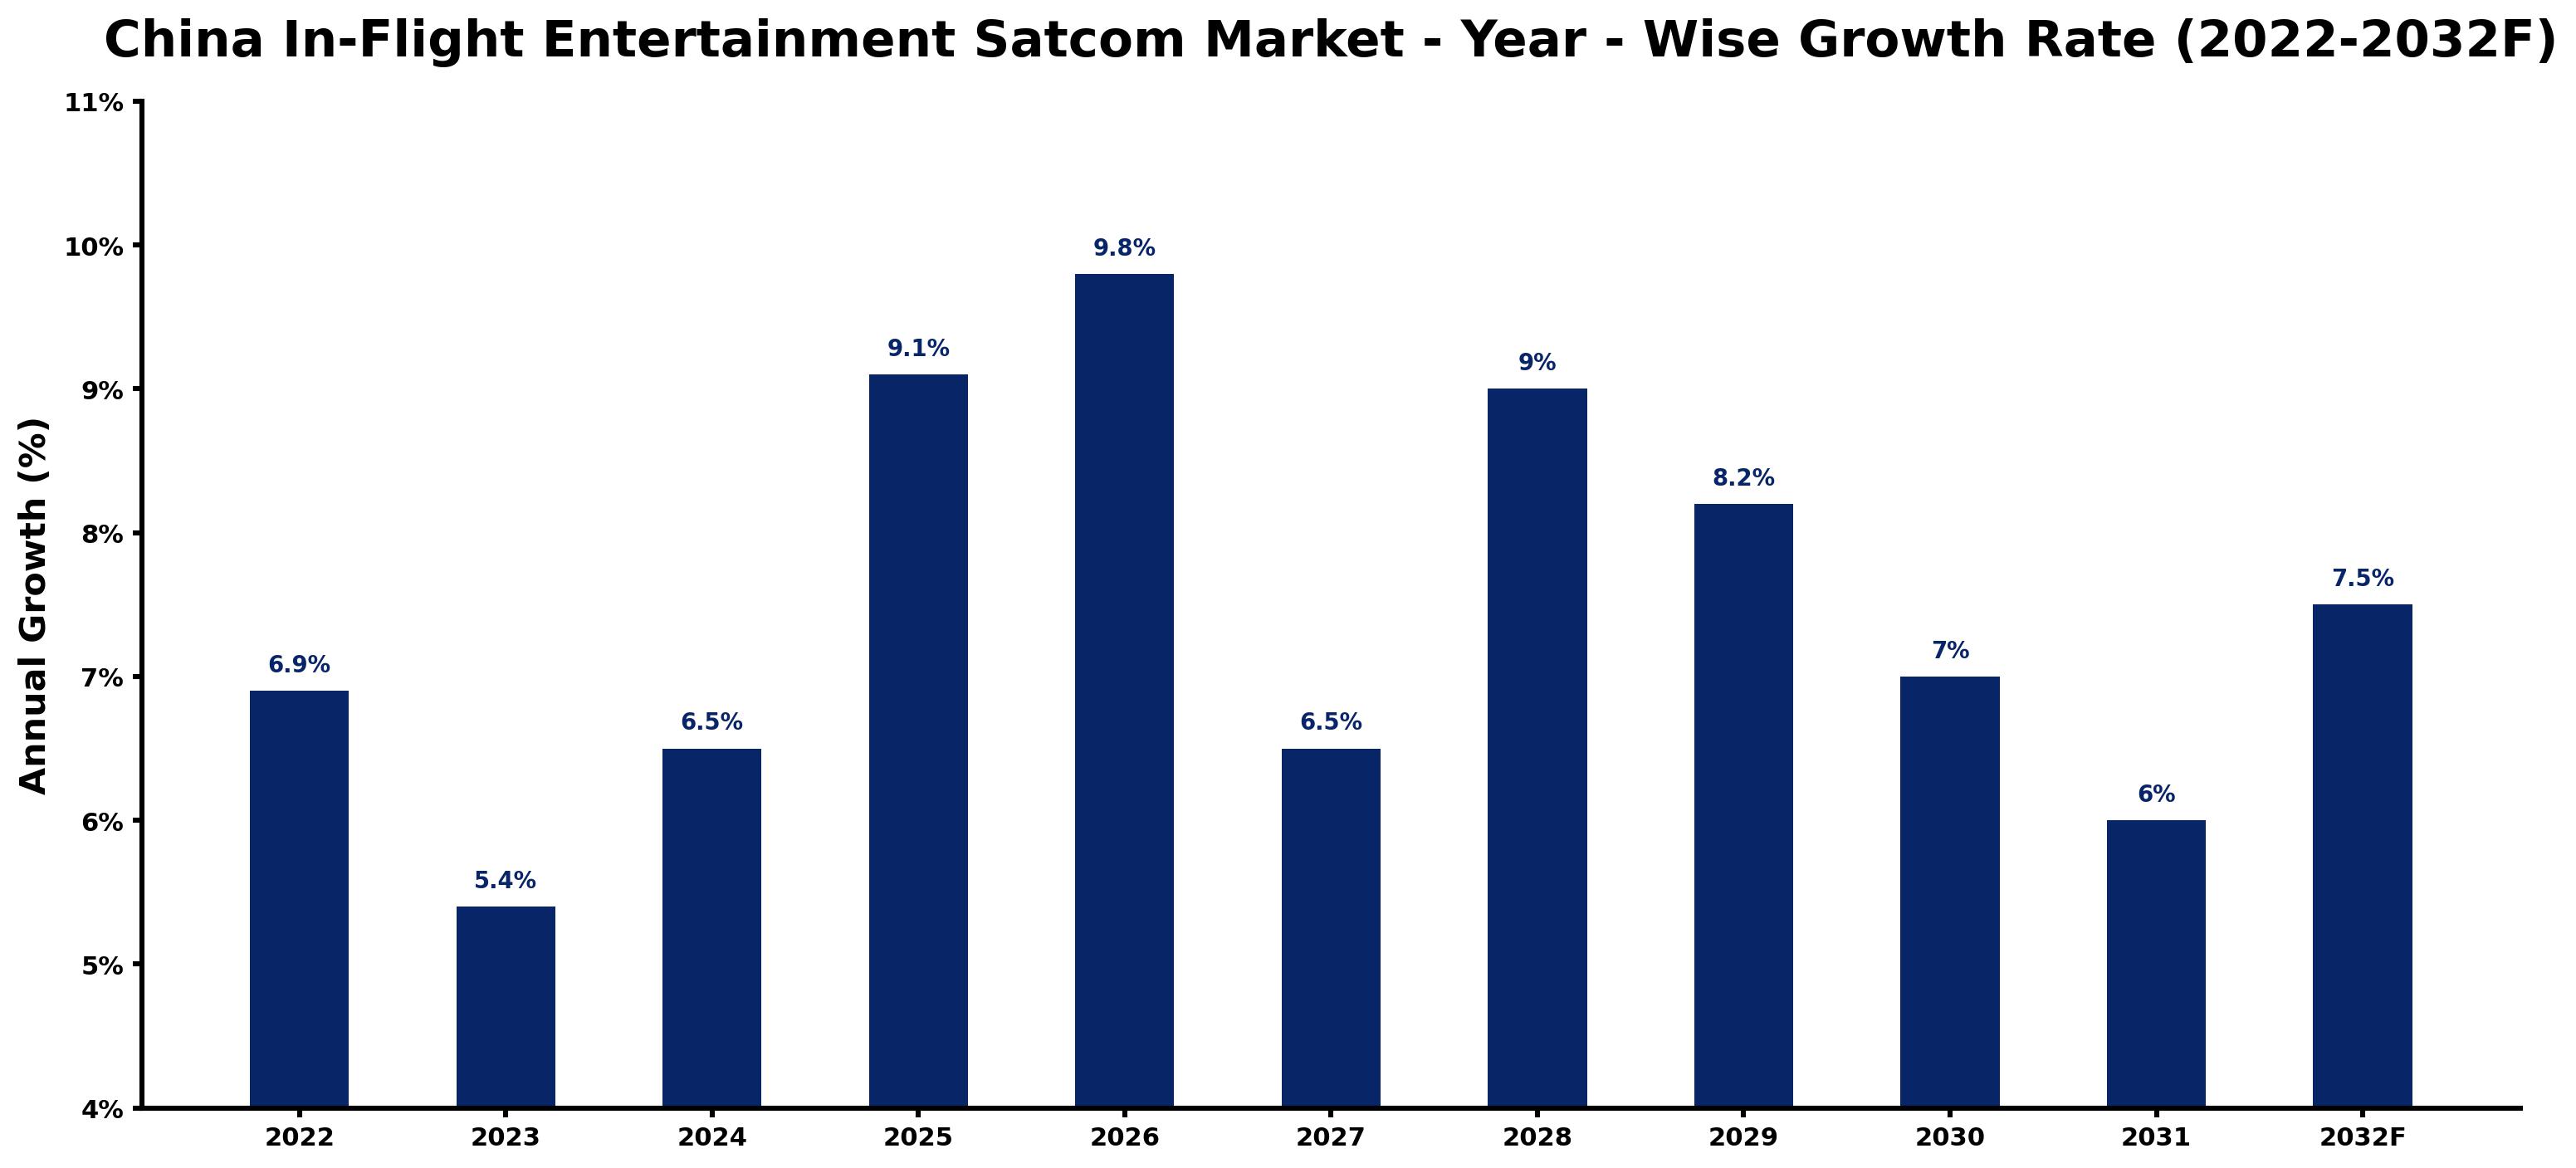
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.9 | The market experienced steady growth as airlines began enhancing passenger services with satellite technology. |
| 2023 | 5.4 | Growth slowed due to increased installation costs, impacting airlines' ability to upgrade entertainment systems. |
| 2024 | 6.5 | Demand rose as airlines invested in improved in-flight experiences, responding to passenger expectations. |
| 2025 | 9.1 | A surge in passenger numbers drove significant growth, with airlines prioritising advanced entertainment systems. |
| 2026 | 9.8 | The market peaked as airlines capitalised on technological advancements and increased connectivity options. |
| 2027 | 6.5 | Growth slowed as competition intensified, leading to challenges in maintaining service quality. |
| 2028 | 9.0 | Demand accelerated again as airlines focused on enhancing passenger engagement through innovative solutions. |
| 2029 | 8.2 | Growth decelerated slightly as regulatory hurdles continued to affect the deployment of new technologies. |
| 2030 | 7.0 | The market saw a slowdown as airlines adjusted to evolving passenger preferences and technological changes. |
| 2031 | 6.0 | Growth moderated as the industry stabilised, focusing on sustainable service improvements. |
| 2032 | 7.5 | Demand is expected to rise as new satellite launches enhance connectivity and service offerings. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China In-Flight Entertainment Satcom Market Synopsis
In-Flight Entertainment Satcom in China involves satellite communication systems providing entertainment services to passengers on aircraft. These systems enable video streaming, gaming, and internet connectivity during flights. The China In-Flight Entertainment Satcom Market is expanding, driven by the aviation sector's recovery and increasing passenger numbers. Key factors include investments in satellite technology and the expansion of connectivity services across domestic and international flights.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing passenger traffic and demand for connectivity during flights. | Driver | High | Video Streaming |
| Significant investments in satellite communication infrastructure by the government. | Driver | High | GEO Satcom |
| Growing demand for low-latency internet solutions for real-time applications. | Opportunity | Medium | Low-Latency Internet |
| Expansion of the aviation sector, particularly in key regions like Beijing-Tianjin-Hebei. | Opportunity | High | Hybrid Satcom Systems |
| High costs associated with satellite technology development and implementation. | Restraint | High | GEO Satcom |
| Regulatory challenges in meeting evolving in-flight connectivity standards. | Restraint | Medium | Video Streaming |
| Limited availability of advanced satellite technology in certain regions. | Challenge | High | LEO Satcom |
| Competition among service providers leading to pricing pressures. | Challenge | Medium | Fixed / Mobile |
Evaluation of Drivers in China In-Flight Entertainment Satcom Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increasing passenger numbers in the aviation sector. | Video Streaming | The Chinese aviation market is expected to serve over 700 million passengers by 2025, driving demand for in-flight entertainment. |
| Government investments in satellite communication infrastructure. | GEO Satcom | The National Development and Reform Commission approved a budget of $500 million in 2023 for satellite communication development. |
| Rising demand for low-latency internet for streaming services. | Low-Latency Internet | The average flight time in China is around 2.5 hours, increasing the need for real-time entertainment services. |
| Expansion of satellite technology partnerships with global providers. | Hybrid Satcom Systems | China has established partnerships with global satellite providers to improve connectivity for in-flight services. |
| Increased installation of entertainment systems in new aircraft deliveries. | Video Streaming | In-flight entertainment systems are installed in over 60% of new aircraft deliveries in China, boosting demand. |
The In-Flight Entertainment Satcom market in China is expanding due to substantial investments in satellite communication infrastructure, a surge in passenger numbers, and a growing demand for improved in-flight experiences. The Chinese aviation sector is anticipated to accommodate over 700 million passengers by 2025, stimulating the need for in-flight entertainment systems. In 2023, the National Development and Reform Commission sanctioned a budget of $500 million for satellite communication development, which will enhance connectivity options. With an average flight time of around 2.5 hours in China, there is an increasing demand for real-time entertainment services. As a result, airlines are incorporating advanced entertainment systems into over 60% of new aircraft deliveries, further propelling market growth.
Evaluation of Restraints in China In-Flight Entertainment Satcom Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs associated with satellite technology development. | GEO Satcom | Investment in satellite technology can be prohibitively expensive, limiting access for smaller airlines. |
| Regulatory challenges in meeting evolving in-flight connectivity standards. | Video Streaming | The CAAC has set guidelines for in-flight connectivity services, complicating compliance for providers. |
| Limited availability of advanced satellite technology in certain regions. | LEO Satcom | Some areas in China lack the infrastructure needed to support advanced satellite communication systems. |
| Competition among service providers leading to pricing pressures. | Fixed / Mobile | Intense competition may lead to lower prices, impacting profitability for satellite service providers. |
| Dependence on international partnerships for technology advancements. | Hybrid Satcom Systems | A leading supplier on global satellite providers can create vulnerabilities in service continuity and innovation. |
China In-Flight Entertainment Satcom Market Challenges
The China In-Flight Entertainment Satcom market encounters several challenges, beginning with the high installation costs for new systems, which can surpass $500,000 per aircraft, imposing a financial strain on airlines. This cost barrier limits domestic airlines' ability to invest in advanced entertainment options, leading to a lack of engaging experiences for passengers. Fierce competition among airlines complicates upgrades, as many struggle to afford the necessary technology, resulting in inconsistent service quality. Furthermore, regulatory obstacles from the Civil Aviation Administration of China hinder the adoption of satellite technologies, extending deployment timelines and restricting service availability for airlines and their customers.
Trends in the China In-Flight Entertainment Satcom Market
Four trends stand out in the China In-Flight Entertainment Satcom Market.
- Shift towards Improved Video Streaming Services: Airlines are increasingly prioritising enhancements in video streaming services for passengers, with the Civil Aviation Administration of China promoting better connectivity standards. By 2023, over 60% of new aircraft are equipped with advanced entertainment systems.
- Transition to Low-Latency Internet Solutions: The demand for low-latency internet solutions has escalated as airlines strive to offer real-time applications for passengers. The Low-Latency Internet segment is projected to grow at a CAGR of 10.5% through 2032.
- Emergence of Hybrid Satcom Systems: Hybrid Satcom Systems are gaining popularity as airlines seek to integrate multiple technologies for improved connectivity. This segment is expected to experience substantial growth, driven by the need for comprehensive in-flight services.
- Increased Focus on Gaming and Conferencing: Airlines are broadening their in-flight entertainment options to include gaming and conferencing services, reflecting evolving passenger preferences. The Gaming/Conferencing segment is projected to grow at a CAGR of 9.6% through 2032.
Investment Opportunities in the China In-Flight Entertainment Satcom Market
Some of the investment opportunities in the China In-Flight Entertainment Satcom Market are mentioned below.
- Investment in Satellite Communication Infrastructure: With the National Development and Reform Commission approving a budget of $500 million for satellite communication development, there is an opportunity to invest in infrastructure. This funding aims to improve connectivity for airlines across China.
- Supply of Low-Latency Internet Solutions: The growing demand for low-latency internet solutions presents an opportunity to supply advanced technologies. Airlines in the Beijing-Tianjin-Hebei region are particularly focused on improving in-flight connectivity.
- Development of Hybrid Satcom Systems: As airlines seek comprehensive in-flight services, there is a growing opportunity to develop hybrid Satcom systems. Investment in this technology is vital for improving passenger experience.
- Expansion of Video Streaming Services: The increasing focus on video streaming services offers a chance to supply advanced entertainment systems. Airlines are looking to upgrade their offerings to meet passenger expectations.
Government Initiatives in the China In-Flight Entertainment Satcom Market
In 2022, the Civil Aviation Administration of China (CAAC) initiated the 'In-Flight Connectivity Development Plan' to enhance passenger services through satellite communication technologies. This initiative aims to improve the quality and availability of in-flight entertainment systems across airlines. By establishing clear guidelines, the CAAC ensures that airlines can deliver reliable connectivity options for passengers during flights. The plan is part of a broader effort to modernise the aviation sector and elevate the overall travel experience for millions of passengers. The initiative supports the integration of advanced satellite technologies in aviation, promoting better service delivery.
In 2023, the National Development and Reform Commission (NDRC) approved a budget of $500 million for the development of satellite communication infrastructure in aviation. This funding is directed at enhancing the capabilities of in-flight connectivity systems. The Ministry of Industry and Information Technology (MIIT) is also involved, having updated the 'National Satellite Communication Development Strategy' in 2021 to focus on improving in-flight connectivity. These measures collectively support the integration of advanced satellite technologies in the aviation sector, enabling airlines to offer improved services to passengers.
Future Insight of the China In-Flight Entertainment Satcom Market
The China In-Flight Entertainment Satcom market is set to evolve significantly as advancements in satellite technology drive improvements in the coming years. The National Development and Reform Commission is backing initiatives that aim for a 10% annual increase in satellite launches, which will expand connectivity options for airlines. New guidelines from the Civil Aviation Administration of China will enhance in-flight internet access, raising service standards across the industry. Collaborations with global satellite providers will increase coverage and reliability, creating a more enjoyable experience for passengers.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Satcom Type – GEO Satcom Dominated, LEO Satcom Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, the largest satcom type category in 2025 was GEO Satcom, with a 51% share of total revenue. GEO Satcom holds the largest share because it provides global coverage essential for in-flight services, which is critical for passenger satisfaction. In China, over 60% of new aircraft deliveries are equipped with GEO Satcom systems to meet this demand. Over 2026–2032, LEO Satcom is expected to post the fastest growth, at a CAGR of 9.4%. LEO Satcom is experiencing rapid growth due to its low-latency solutions that are ideal for real-time applications like gaming and video conferencing. With passenger numbers projected to exceed 700 million by 2025, the demand for these services is expected to rise significantly. Suppliers should focus on enhancing their GEO Satcom offerings while also investing in LEO Satcom technologies to cater to the evolving needs of the aviation market.
By Orbit Type – Fixed / Mobile Dominated, Low-Latency Internet Expected to Grow Fastest
Fixed / Mobile took a 35% share of orbit type in 2025, more than any other category. The Fixed / Mobile segment leads the market as it accommodates various connectivity needs during flights, addressing the diverse preferences of passengers. This flexibility is essential for airlines looking to improve the travel experience for the expected 700 million passengers by 2025. The quickest growth will come from Low-Latency Internet, forecast to expand at a CAGR of 10.5% between 2026 and 2032. Low-Latency Internet is the fastest growing segment, driven by the pressing need for streaming and interactive services among passengers. The average flight duration of approximately 2.5 hours in China further intensifies the demand for such connectivity solutions. Buyers should focus on solutions that provide Fixed / Mobile capabilities while also considering the integration of Low-Latency Internet for improved passenger satisfaction.
By Connectivity Mode – Video Streaming Dominated, Gaming / Conferencing Expected to Grow Fastest
With a 45% revenue share in 2025, Video Streaming was the largest connectivity mode category. Video Streaming captures the largest market share as it is the primary application for passenger entertainment, aligning with travellers' preferences for engaging content during flights. The increasing installation of advanced in-flight entertainment systems in new aircraft supports this trend. Gaming / Conferencing is projected to grow fastest, at a CAGR of 9.6% during 2026–2032. Gaming / Conferencing is rapidly gaining traction among passengers seeking interactive experiences, indicating a shift in entertainment preferences. This growing interest suggests a significant market opportunity for suppliers to develop these services further. Suppliers must invest in technologies that enhance Video Streaming capabilities while also expanding their offerings to include Gaming / Conferencing solutions.
By Distribution Channel – Satellite Operators Dominated, OEM Aircraft Integrators Expected to Grow Fastest
Satellite Operators held a 52% share of the China In-Flight Entertainment Satcom Market by distribution channel in 2025. Satellite Operators lead the distribution channel as they are the main providers of satellite services necessary for in-flight entertainment systems. Their established infrastructure and expertise are crucial for supporting the expanding aviation market in China. OEM Aircraft Integrators are set to record the highest CAGR in this split, 9.1% over 2026–2032. OEM Aircraft Integrators are the fastest growing channel, as they are essential in integrating advanced in-flight entertainment systems into new aircraft. Their partnerships with airlines and manufacturers position them well to meet the increasing demand for connectivity solutions. Suppliers should strengthen collaborations with Satellite Operators and engage with OEM Aircraft Integrators to enhance their market presence.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China In-Flight Entertainment Satcom Market Outlook
- Market Size of China In-Flight Entertainment Satcom Market, 2025
- Forecast of China In-Flight Entertainment Satcom Market, 2032
- Historical Data and Forecast of China In-Flight Entertainment Satcom Revenues & Volume for the Period 2022 - 2032F
- China In-Flight Entertainment Satcom Market Trend Evolution
- China In-Flight Entertainment Satcom Market Drivers and Challenges
- China In-Flight Entertainment Satcom Price Trends
- China In-Flight Entertainment Satcom Porter's Five Forces
- China In-Flight Entertainment Satcom Industry Life Cycle
- Historical Data and Forecast of China In-Flight Entertainment Satcom Market Revenues & Volume By Satcom Type for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Entertainment Satcom Market Revenues & Volume By GEO Satcom for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Entertainment Satcom Market Revenues & Volume By LEO Satcom for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Entertainment Satcom Market Revenues & Volume By MEO Satcom for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Entertainment Satcom Market Revenues & Volume By Hybrid Satcom Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Entertainment Satcom Market Revenues & Volume By Orbit Type for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Entertainment Satcom Market Revenues & Volume By Fixed / Mobile for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Entertainment Satcom Market Revenues & Volume By Low-Latency Internet for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Entertainment Satcom Market Revenues & Volume By Mid-Range Coverage for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Entertainment Satcom Market Revenues & Volume By Multi-Orbit Links for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Entertainment Satcom Market Revenues & Volume By Connectivity Mode for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Entertainment Satcom Market Revenues & Volume By Video Streaming for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Entertainment Satcom Market Revenues & Volume By Gaming / Conferencing for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Entertainment Satcom Market Revenues & Volume By Social Media & VoIP for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Entertainment Satcom Market Revenues & Volume By Full Entertainment Stack for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Entertainment Satcom Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Entertainment Satcom Market Revenues & Volume By Satellite Operators for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Entertainment Satcom Market Revenues & Volume By OEM Aircraft Integrators for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Entertainment Satcom Market Revenues & Volume By Satcom Hardware Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Entertainment Satcom Market Revenues & Volume By Aircraft Connectivity Providers for the Period 2022 - 2032F
- China In-Flight Entertainment Satcom Import Export Trade Statistics
- Market Opportunity Assessment By Satcom Type
- Market Opportunity Assessment By Orbit Type
- Market Opportunity Assessment By Connectivity Mode
- Market Opportunity Assessment By Distribution Channel
- China In-Flight Entertainment Satcom Top Companies Market Share
- China In-Flight Entertainment Satcom Competitive Benchmarking By Technical and Operational Parameters
- China In-Flight Entertainment Satcom Company Profiles
- China In-Flight Entertainment Satcom Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Satcom Type
- GEO Satcom
- LEO Satcom
- MEO Satcom
- Hybrid Satcom Systems
By Orbit Type
- Fixed / Mobile
- Low-Latency Internet
- Mid-Range Coverage
- Multi-Orbit Links
By Connectivity Mode
- Video Streaming
- Gaming / Conferencing
- Social Media & VoIP
- Full Entertainment Stack
By Distribution Channel
- Satellite Operators
- OEM Aircraft Integrators
- Satcom Hardware Suppliers
- Aircraft Connectivity Providers































