China In-Flight Wi-Fi Provider Market Size & Growth Rate
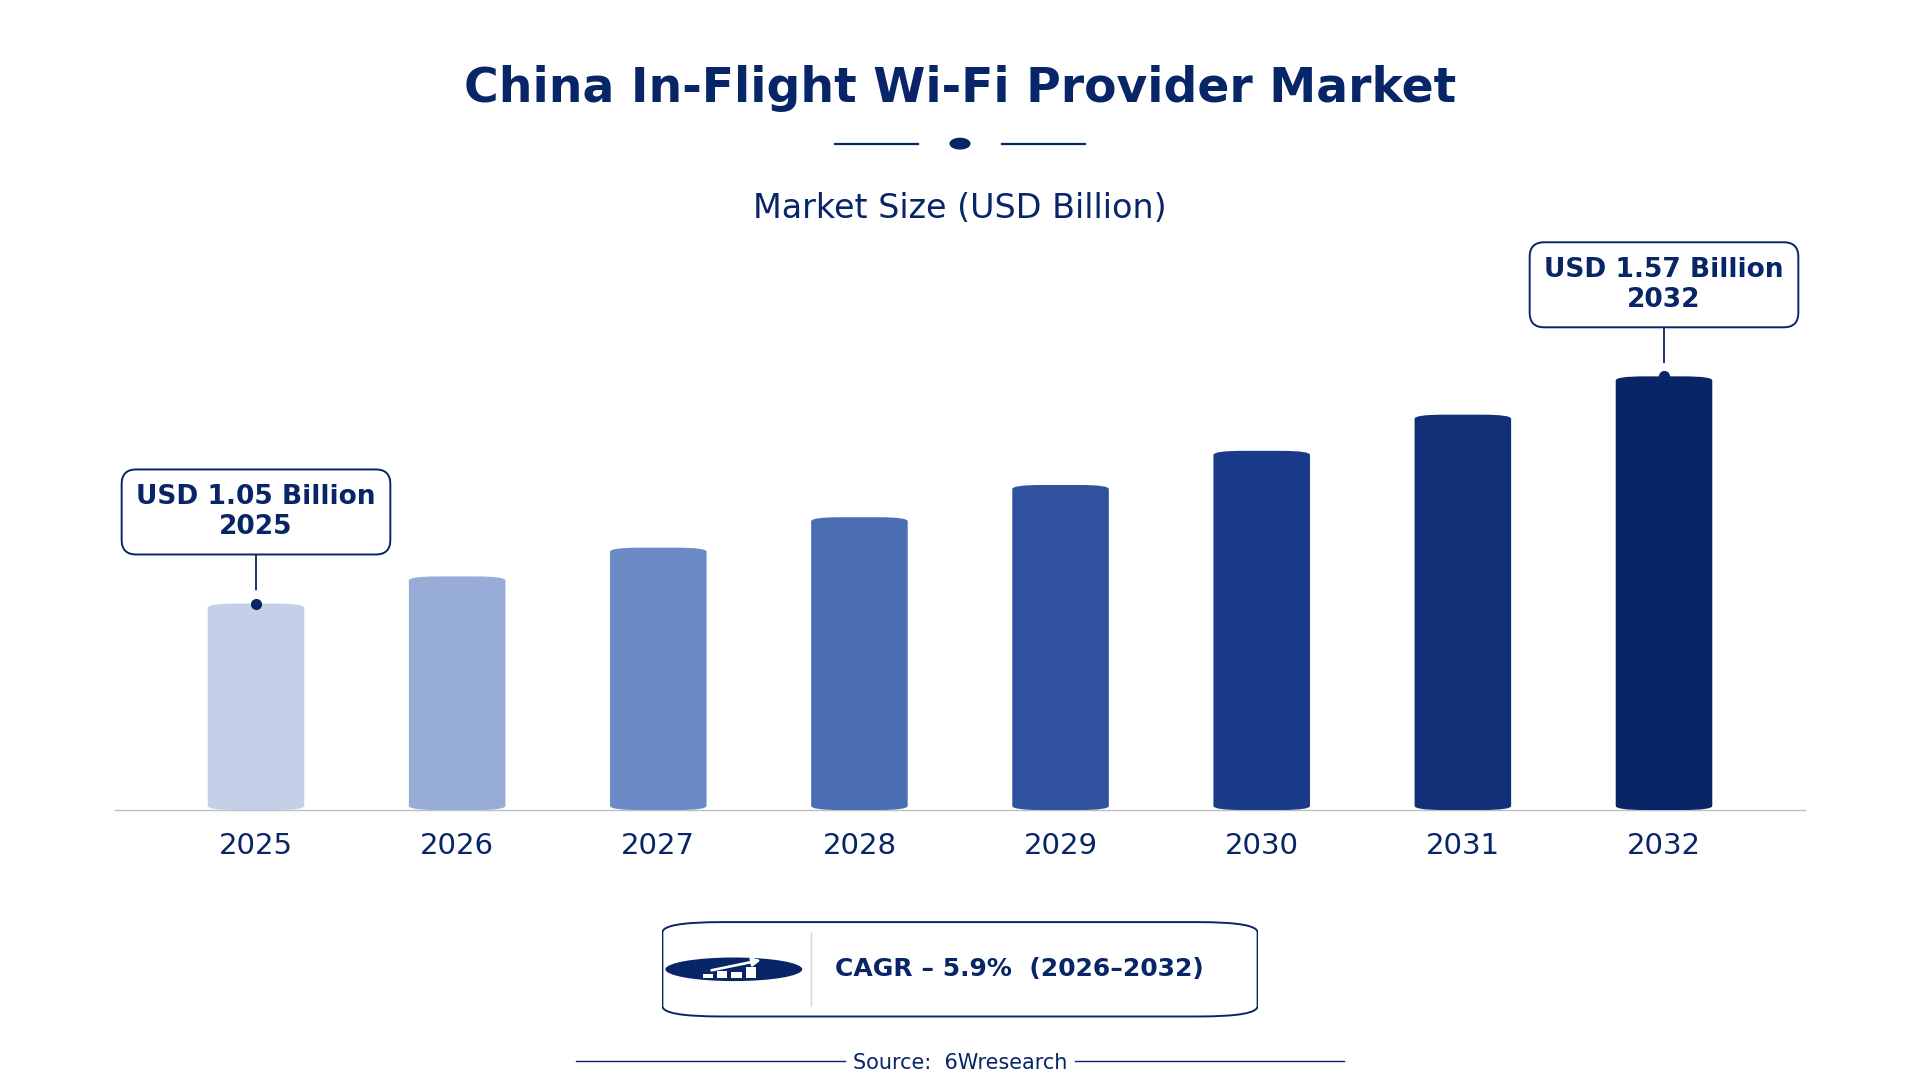
According to 6Wresearch internal database and industry insights, the China In-Flight Wi-Fi Provider Market was valued at USD 1.05 billion in 2025 and is projected to reach USD 1.57 billion by 2032, growing at a CAGR of approximately 5.9% during 2026–2032.
China In-Flight Wi-Fi Provider Market Highlights
| Report Metric | Details |
| Report Name | China In-Flight Wi-Fi Provider Market |
| Market Size 2025 | USD 1.05 billion |
| Market Size 2032 | USD 1.57 billion |
| Absolute Growth 2025–2032 | USD 0.52 billion |
| CAGR 2026–2032 | 5.9% |
| Peak Annual Growth | 8.2% in 2030 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Provider Type, 2025 | Global Satcom Providers (40% share) |
| Leading Connectivity Model, 2025 | Ka / Ku Band (55% share) |
| Leading Target Airline Class, 2025 | International Airlines (42% share) |
| Leading Distribution Channel, 2025 | Direct Airline Contracts (39% share) |
| Fastest-Growing Provider Type | Regional Wi-Fi Providers (8.4% CAGR) |
| Fastest-Growing Connectivity Model | ATG / LTE Hybrid (7.4% CAGR) |
| Fastest-Growing Target Airline Class | Regional Carriers (8.1% CAGR) |
| Fastest-Growing Distribution Channel | Telco Integrators (7.1% CAGR) |
| Growing Sector | Telco Integrators |
| Key End Users | Direct Airline Contracts, Telco Integrators, Subscription Platforms, Satellite Infrastructure |
China In-Flight Wi-Fi Provider Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
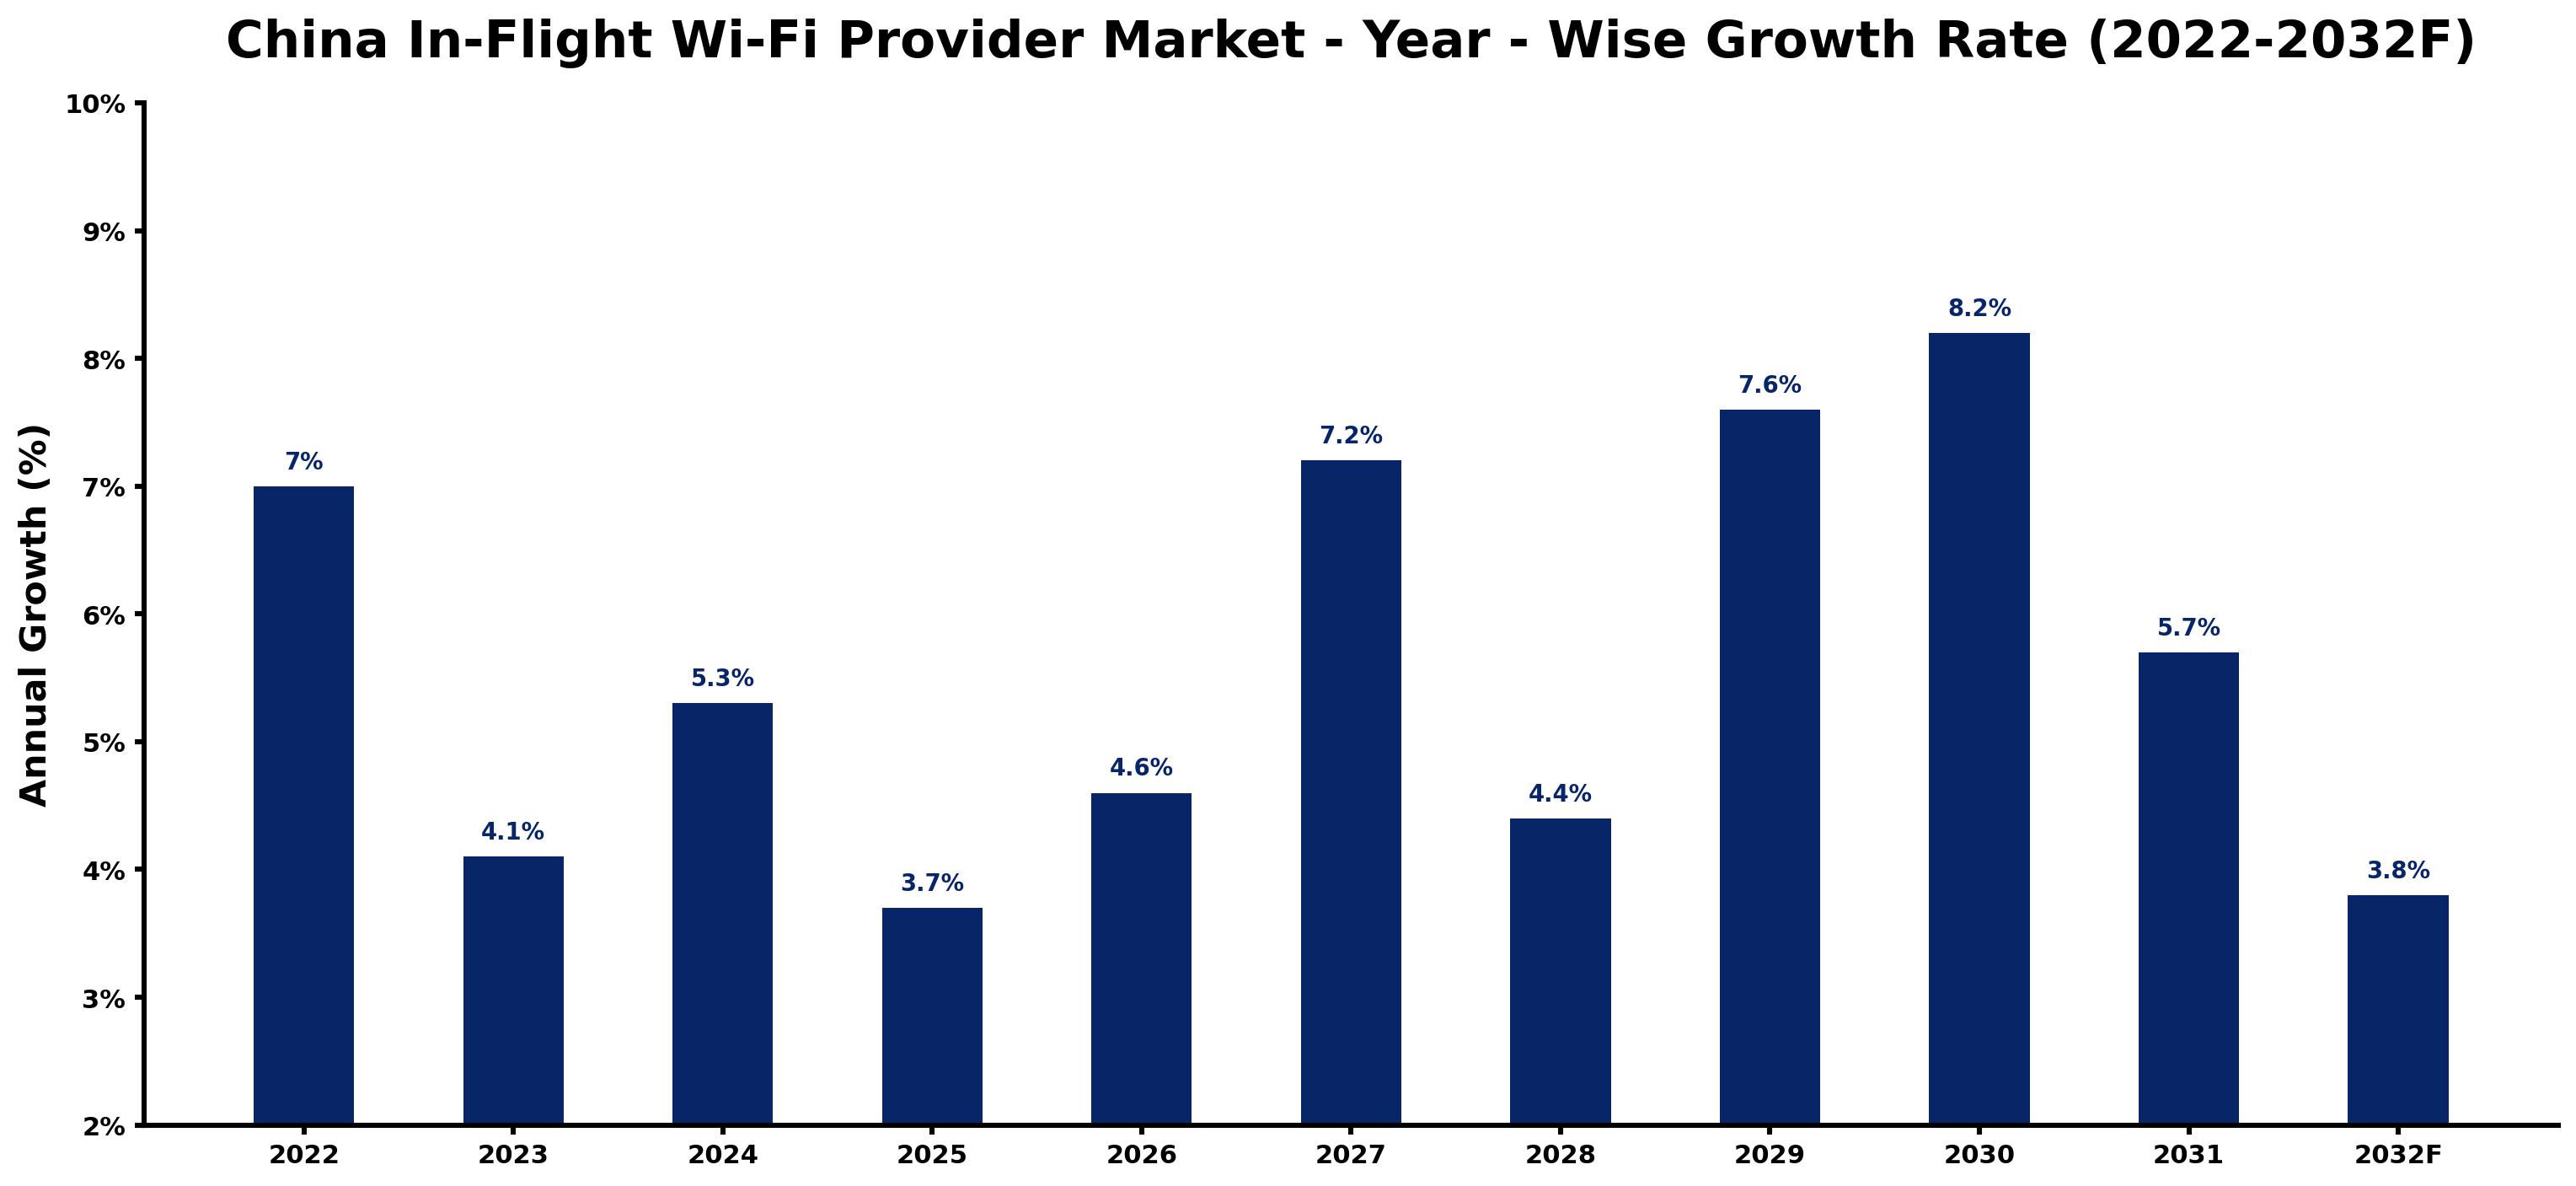
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.0 | The market experienced strong demand as 75% of international airlines provided Wi-Fi services. |
| 2023 | 4.1 | Growth slowed as airlines adjusted their offerings and the National Civil Aviation Administration implemented new regulations. |
| 2024 | 5.3 | Demand rose with more regional airlines adopting in-flight Wi-Fi to compete effectively. |
| 2025 | 3.7 | Growth slowed again as market saturation began to influence service expansion. |
| 2026 | 4.6 | An increase in technology investments led to a rise in service adoption rates, particularly in the Beijing-Tianjin-Hebei region. |
| 2027 | 7.2 | Growth accelerated as international travel resumed and demand for connectivity surged, especially among budget airlines. |
| 2028 | 4.4 | The market faced a slowdown as competition intensified among service providers in major hubs. |
| 2029 | 7.6 | Demand surged again as airlines upgraded fleets with advanced connectivity solutions, driven by the Smart Aviation Initiative. |
| 2030 | 8.2 | The market peaked with substantial investments in high-speed satellite services, particularly in the Ka band. |
| 2031 | 5.7 | Growth slowed as the market stabilised following peak adoption rates, with many airlines already offering Wi-Fi. |
| 2032 | 3.8 | The market continues to grow, albeit at a slower pace as saturation effects set in, particularly among international airlines. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China In-Flight Wi-Fi Provider Market Synopsis
The In-Flight Wi-Fi Provider Market in China encompasses technologies that deliver internet connectivity to passengers on aircraft. This service is primarily facilitated through satellite communication systems and air-to-ground networks, enabling browsing, streaming, and communication. The market is growing due to the increasing number of air passengers, with over 300 million annually, and a strong push from international airlines, as 75% of them offered Wi-Fi services in 2022. Initiatives like the 'Digital Aviation Development Plan' aim to improve connectivity services, driving further demand.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising number of air passengers annually drives demand for connectivity services. | Driver | High | International Airlines |
| Increased adoption of high-speed satellite services enhances service quality. | Driver | High | Ka / Ku Band |
| Investment in regional airline connectivity services presents new market opportunities. | Opportunity | High | Regional Wi-Fi Providers |
| Growing demand for in-flight Wi-Fi among budget airlines opens new avenues. | Opportunity | Medium | Budget Airlines |
| Regulatory complexities can delay service implementation for airlines. | Restraint | High | Direct Airline Contracts |
| High operational costs for maintaining connectivity infrastructure can limit profitability. | Restraint | Medium | OEM Hardware Providers |
| The In-Flight Wi-Fi Provider Market in China faces challenges from regulatory hurdles. | Challenge | High | Regional Wi-Fi Providers |
| Technological integration issues can hinder service delivery and reliability. | Challenge | Medium | B2B SaaS Providers |
Evaluation of Drivers in China In-Flight Wi-Fi Provider Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increasing air passenger numbers drive demand for in-flight connectivity. | International Airlines | With over 300 million passengers annually, airlines are investing more in Wi-Fi services. |
| Adoption of high-speed satellite services improves connectivity options. | Ka / Ku Band | The preference for Ka band services is growing, with a projected 55% market share by 2025. |
| Regional airlines are improving passenger experience with Wi-Fi services. | Regional Wi-Fi Providers | As competition intensifies, regional carriers are adopting Wi-Fi to attract customers. |
| Technological advancements in satellite communications improve service quality. | OEM Hardware Providers | Investments in new hardware are essential for maintaining competitive service offerings. |
| Government initiatives support infrastructure investment in aviation connectivity. | Direct Airline Contracts | The 'Digital Aviation Development Plan' aims to improve connectivity services. |
The In-Flight Wi-Fi Provider market in China is expanding as airlines invest heavily in connectivity solutions, driven by the growing number of air passengers. Over 300 million passengers travel annually, prompting airlines to upgrade their service offerings. The adoption of high-speed satellite services is increasing, with the Ka band projected to hold a 55% market share by 2025. Regional carriers are also enhancing their services to compete effectively with international airlines.
Evaluation of Restraints in China In-Flight Wi-Fi Provider Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Regulatory complexities can delay service implementation for airlines. | Direct Airline Contracts | The approval process for in-flight Wi-Fi services can be lengthy, affecting deployment timelines. |
| High operational costs for maintaining connectivity infrastructure can limit profitability. | OEM Hardware Providers | The average cost for in-flight Wi-Fi is around 50 RMB per hour, impacting service pricing. |
| Limited technological integration can hinder service delivery and reliability. | B2B SaaS Providers | Integration challenges can lead to inconsistent service quality, affecting user experience. |
| Intense competition among service providers can lead to price wars. | Regional Wi-Fi Providers | As more airlines offer Wi-Fi, pricing pressure increases, affecting margins. |
| Market saturation in major hubs can limit growth potential. | International Airlines | With 75% of international airlines already offering Wi-Fi, new entrants face challenges. |
China In-Flight Wi-Fi Provider Market Challenges
The China In-Flight Wi-Fi Provider Market faces fierce competition, as 75% of international airlines currently provide Wi-Fi services, pushing domestic carriers to invest heavily to remain competitive. High operational costs, averaging 50 RMB per hour for Wi-Fi, deter budget airlines from offering these services, limiting their appeal to price-sensitive travellers. A shortage of skilled technicians hampers the aviation sector's ability to implement advanced satellite communication systems, leading to delays in service rollouts for airlines. Supply chain challenges regarding technology imports obstruct timely upgrades, negatively impacting service quality for airlines and frustrating passengers seeking reliable connectivity.
Trends in the China In-Flight Wi-Fi Provider Market
Below mentioned are some of the trends shaping the China In-Flight Wi-Fi Provider Market growth.
- Shift to High-Speed Satellite Services: The 'Digital Aviation Development Plan' initiated in 2021 has accelerated the adoption of high-speed satellite services in China. By 2025, 50% of all flights are expected to offer Wi-Fi, improving passenger experience.
- Emergence of Regional Wi-Fi Providers: Since 2022, regional airlines have increasingly adopted in-flight Wi-Fi to compete with international carriers. This trend is driven by the need to improve passenger experience and attract more travelers.
- Increased Focus on Budget Airline Connectivity: Budget airlines are steadily adopting in-flight Wi-Fi, with many now offering basic connectivity options. This shift is essential for attracting price-sensitive travelers in a competitive market.
- Expansion of Direct Airline Contracts: Direct Airline Contracts have become the primary method for service provision, accounting for 39% of the market in 2025. This trend reflects airlines' preference for streamlined partnerships with service providers.
Investment Opportunities in the China In-Flight Wi-Fi Provider Market
Below are the investment opportunities with the strongest case in the China In-Flight Wi-Fi Provider Market.
- Investment in High-Speed Satellite Services: With the growing demand for connectivity, there is a strong opportunity to invest in high-speed satellite services. By 2025, 50% of flights are expected to offer Wi-Fi, creating a demand for advanced technology.
- Supply of Connectivity Infrastructure: The timing is ideal for investing in connectivity infrastructure as the aviation industry expands. Regional airlines are seeking partnerships to enhance their service offerings, particularly in competitive markets.
- Expansion of Wi-Fi Services in Budget Airlines: Now is the time to form partnerships with regional airlines looking to improve connectivity. By aligning with local carriers, suppliers can access a rapidly growing market.
- Enhancing Service Quality through Technological Upgrades: Investing in advanced satellite communication systems is crucial as demand for reliable connectivity rises. Airlines are keen to improve service quality, especially in major hubs.
Government Initiatives in the China In-Flight Wi-Fi Provider Market
In 2023, the Ministry of Industry and Information Technology launched the 'Smart Aviation Initiative' to promote the adoption of advanced technology in the aviation sector, including in-flight connectivity. This builds on the 2022 updates by the Civil Aviation Administration of China, which streamlined the approval process for in-flight Wi-Fi services, reducing timeframes for airlines. These measures improve the regulatory environment, encouraging more airlines to adopt Wi-Fi services.
The National Civil Aviation Administration oversees the implementation of in-flight connectivity standards, ensuring quality and safety in services. The agency also approves new technologies and infrastructure investments, facilitating the deployment of Wi-Fi services across airlines. With the 'Digital Aviation Development Plan' initiated in 2021, funding is directed towards improving connectivity services, benefiting both producers and consumers in the aviation sector.
Future Insight of the China In-Flight Wi-Fi Provider Market
The China In-Flight Wi-Fi Provider Market will experience notable changes by 2032, driven by a government initiative aimed at improving digital services in aviation by 2024. By 2025, 50% of all flights in China are expected to provide Wi-Fi, signalling a strong commitment to enhanced connectivity. Support from the National Development and Reform Commission for technological advancements will aid infrastructure development. As regional airlines increasingly adopt in-flight Wi-Fi, service quality is anticipated to rise, resulting in greater passenger satisfaction.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Provider Type – Global Satcom Providers Dominated, Regional Wi-Fi Providers Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, Global Satcom Providers held a 40% share of the China In-Flight Wi-Fi Provider Market by provider type in 2025. Global Satcom Providers dominate the China In-Flight Wi-Fi Provider Market due to their ability to deliver essential satellite connectivity, crucial for the vast number of air passengers. Their extensive infrastructure supports the 75% of international airlines operating in China that offer Wi-Fi services, reinforcing their leading position. Over 2026–2032, Regional Wi-Fi Providers are expected to post the fastest growth, at a CAGR of 8.4%. Regional Wi-Fi Providers are rapidly growing as they cater specifically to regional airlines, which are increasingly adopting in-flight Wi-Fi to enhance competitiveness. The rising demand for localized services indicates a significant shift towards improving passenger experience in the aviation sector. Suppliers should focus on partnerships with regional airlines to capitalise on the growing demand for in-flight connectivity.
By Connectivity Model – Ka / Ku Band Dominated, ATG / LTE Hybrid Expected to Grow Fastest
Ka / Ku Band took a 55% share of connectivity model in 2025, more than any other category. The Ka / Ku Band leads the connectivity model segment as it is vital for delivering high-speed satellite-based internet services, enhancing the in-flight experience for millions of passengers. This model effectively meets the increasing demand for reliable connectivity in a market with over 300 million air passengers annually. The quickest growth will come from ATG / LTE Hybrid, forecast to expand at a CAGR of 7.4% between 2026 and 2032. The ATG / LTE Hybrid model is gaining traction due to its cost-effectiveness and ability to provide reliable connectivity, making it attractive for airlines. With projections indicating that 50% of flights in China will offer Wi-Fi by 2025, this model is positioned for rapid adoption. Providers should explore ATG / LTE Hybrid solutions to align with the evolving connectivity needs of airlines and their passengers.
By Target Airline Class – International Airlines Dominated, Regional Carriers Expected to Grow Fastest
International Airlines accounted for a 42% market share by target airline class in 2025. International Airlines hold the largest market share as they are the primary users of in-flight Wi-Fi services, catering to a global clientele that demands connectivity during flights. Their established operations and extensive customer base create a strong need for reliable internet access while travelling. Regional Carriers are projected to grow fastest, at a CAGR of 8.1% during 2026–2032. Regional Carriers are experiencing the fastest growth in the market as they increasingly implement in-flight Wi-Fi to improve passenger experience and compete effectively with international airlines. This trend highlights a broader movement towards enhanced service offerings in aviation. Suppliers should tailor their offerings to meet the specific needs of regional carriers looking to enhance passenger satisfaction through connectivity.
By Distribution Channel – Direct Airline Contracts Dominated, Telco Integrators Expected to Grow Fastest
In 2025, Direct Airline Contracts led the distribution channel split with a 39% share. Direct Airline Contracts are the primary method for delivering in-flight Wi-Fi services, ensuring a streamlined approach to service provision that benefits both airlines and providers. This model fosters strong relationships, facilitating effective deployment of connectivity solutions across the aviation sector. Telco Integrators are set to record the highest CAGR in this split, 7.1% over 2026–2032. Telco Integrators are emerging as the fastest-growing channel, enabling partnerships between airlines and service providers that simplify the integration of in-flight connectivity solutions. This trend reflects the increasing complexity of service delivery in the aviation industry. Suppliers should pursue collaborations with telco integrators to enhance their market reach and improve service delivery.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China In-Flight Wi-Fi Provider Market Outlook
- Market Size of China In-Flight Wi-Fi Provider Market, 2025
- Forecast of China In-Flight Wi-Fi Provider Market, 2032
- Historical Data and Forecast of China In-Flight Wi-Fi Provider Revenues & Volume for the Period 2022 - 2032F
- China In-Flight Wi-Fi Provider Market Trend Evolution
- China In-Flight Wi-Fi Provider Market Drivers and Challenges
- China In-Flight Wi-Fi Provider Price Trends
- China In-Flight Wi-Fi Provider Porter's Five Forces
- China In-Flight Wi-Fi Provider Industry Life Cycle
- Historical Data and Forecast of China In-Flight Wi-Fi Provider Market Revenues & Volume By Provider Type for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Wi-Fi Provider Market Revenues & Volume By Global Satcom Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Wi-Fi Provider Market Revenues & Volume By Regional Wi-Fi Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Wi-Fi Provider Market Revenues & Volume By B2B SaaS Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Wi-Fi Provider Market Revenues & Volume By OEM Hardware Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Wi-Fi Provider Market Revenues & Volume By Connectivity Model for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Wi-Fi Provider Market Revenues & Volume By Ka / Ku Band for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Wi-Fi Provider Market Revenues & Volume By ATG / LTE Hybrid for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Wi-Fi Provider Market Revenues & Volume By White-Label Services for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Wi-Fi Provider Market Revenues & Volume By End-to-End Solutions for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Wi-Fi Provider Market Revenues & Volume By Target Airline Class for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Wi-Fi Provider Market Revenues & Volume By International Airlines for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Wi-Fi Provider Market Revenues & Volume By Regional Carriers for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Wi-Fi Provider Market Revenues & Volume By Budget Airlines for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Wi-Fi Provider Market Revenues & Volume By Widebody Aircraft for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Wi-Fi Provider Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Wi-Fi Provider Market Revenues & Volume By Direct Airline Contracts for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Wi-Fi Provider Market Revenues & Volume By Telco Integrators for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Wi-Fi Provider Market Revenues & Volume By Subscription Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Flight Wi-Fi Provider Market Revenues & Volume By Satellite Infrastructure for the Period 2022 - 2032F
- China In-Flight Wi-Fi Provider Import Export Trade Statistics
- Market Opportunity Assessment By Provider Type
- Market Opportunity Assessment By Connectivity Model
- Market Opportunity Assessment By Target Airline Class
- Market Opportunity Assessment By Distribution Channel
- China In-Flight Wi-Fi Provider Top Companies Market Share
- China In-Flight Wi-Fi Provider Competitive Benchmarking By Technical and Operational Parameters
- China In-Flight Wi-Fi Provider Company Profiles
- China In-Flight Wi-Fi Provider Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Provider Type
- Global Satcom Providers
- Regional Wi-Fi Providers
- B2B SaaS Providers
- OEM Hardware Providers
By Connectivity Model
- Ka / Ku Band
- ATG / LTE Hybrid
- White-Label Services
- End-to-End Solutions
By Target Airline Class
- International Airlines
- Regional Carriers
- Budget Airlines
- Widebody Aircraft
By Distribution Channel
- Direct Airline Contracts
- Telco Integrators
- Subscription Platforms
- Satellite Infrastructure































