China Industrial Assembly Solutions Market Size & Growth Rate
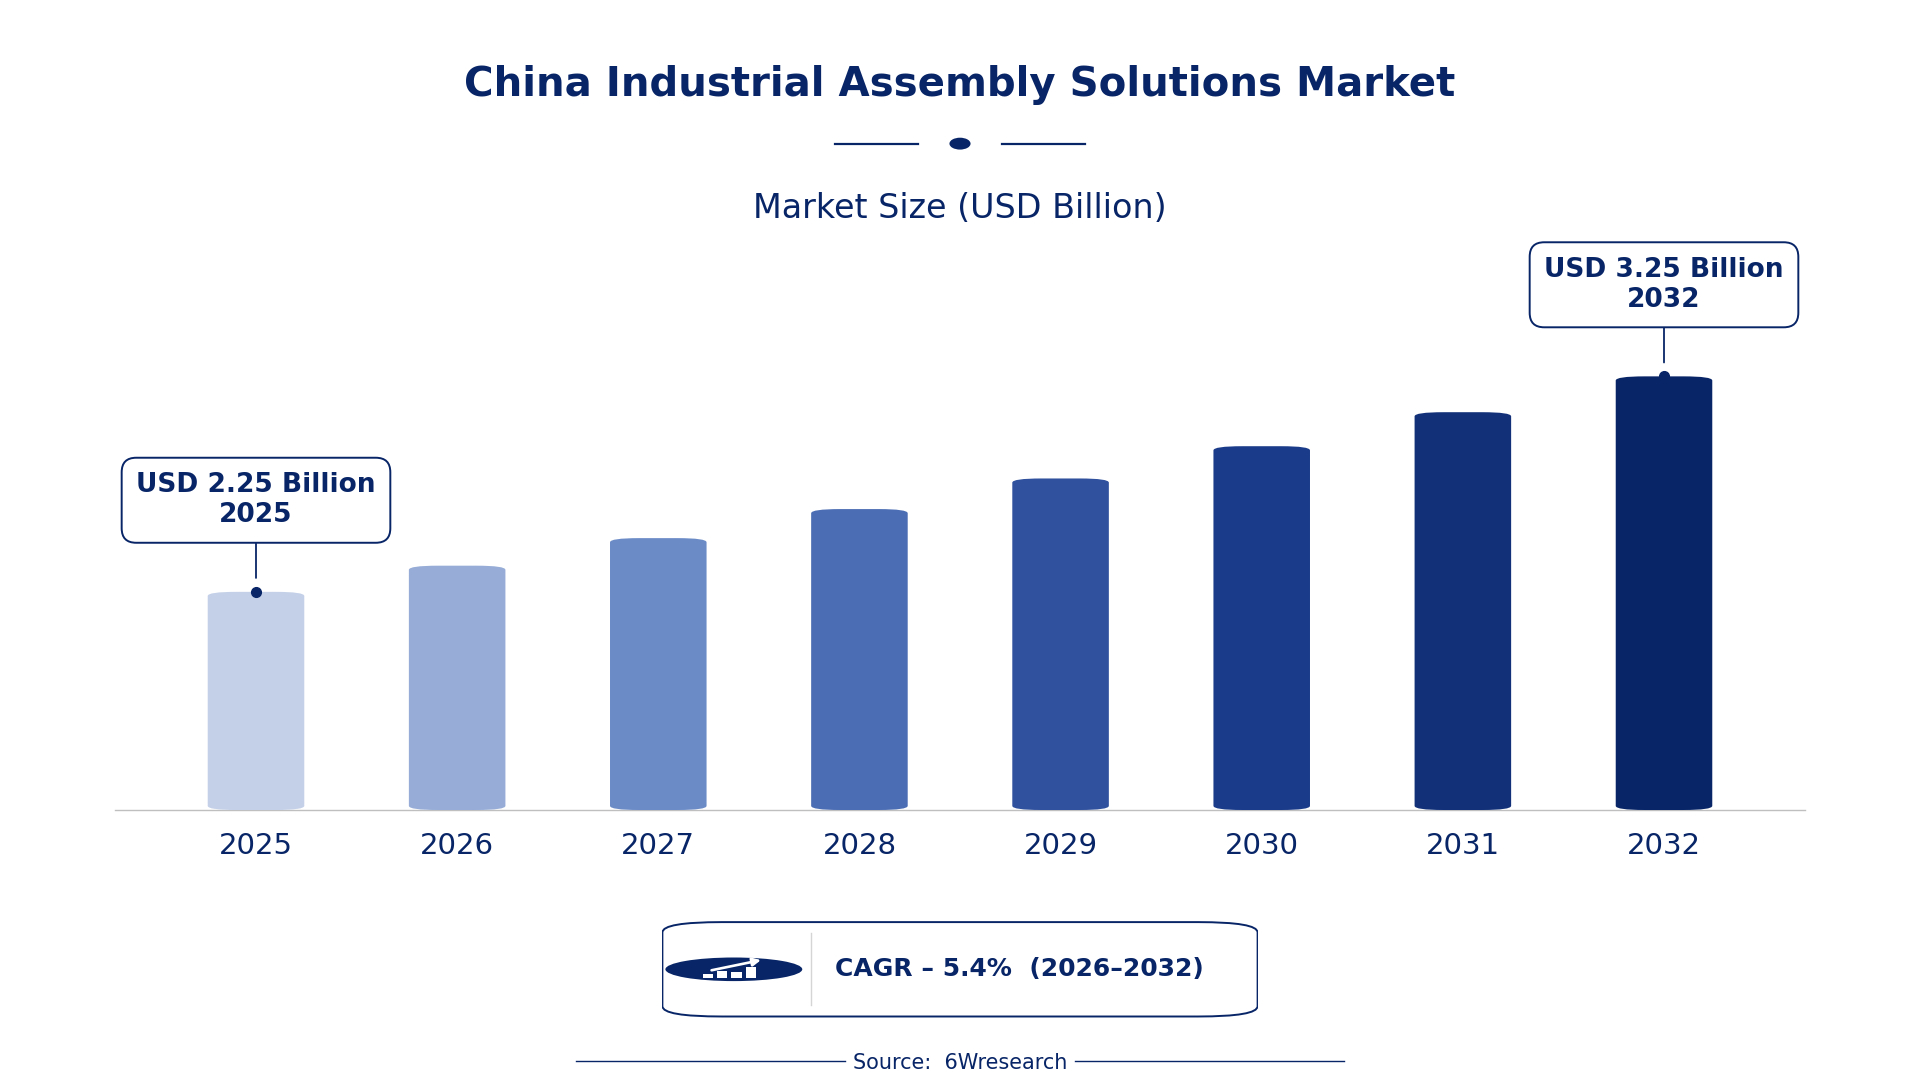
According to 6Wresearch internal database and industry insights, the China Industrial Assembly Solutions Market was valued at USD 2.25 billion in 2025 and is projected to reach USD 3.25 billion by 2032, growing at a CAGR of approximately 5.4% during 2026–2032.
China Industrial Assembly Solutions Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Assembly Solutions Market |
| Market Size 2025 | USD 2.25 billion |
| Market Size 2032 | USD 3.25 billion |
| Absolute Growth 2025–2032 | USD 1 billion |
| CAGR 2026–2032 | 5.4% |
| Peak Annual Growth | 7.0% in 2029 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Assembly Type, 2025 | Fully Automated Lines (47% share) |
| Leading Automation Level, 2025 | PLC + Robotics (41% share) |
| Leading Assembly Process, 2025 | Conveyor-Based (35% share) |
| Leading End User, 2025 | Automotive Assembly Plants (38% share) |
| Fastest-Growing Assembly Type | Flexible Assembly Cells (6.9% CAGR) |
| Fastest-Growing Assembly Process | High-Mix (7.0% CAGR) |
| Fastest-Growing End User | Electronics Manufacturers (6.9% CAGR) |
| Growing Sector | Automotive Assembly Plants |
| Key End Users | Automotive Assembly Plants, Electronics Manufacturers, Aerospace & Defense Firms, SME Workshops |
China Industrial Assembly Solutions Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
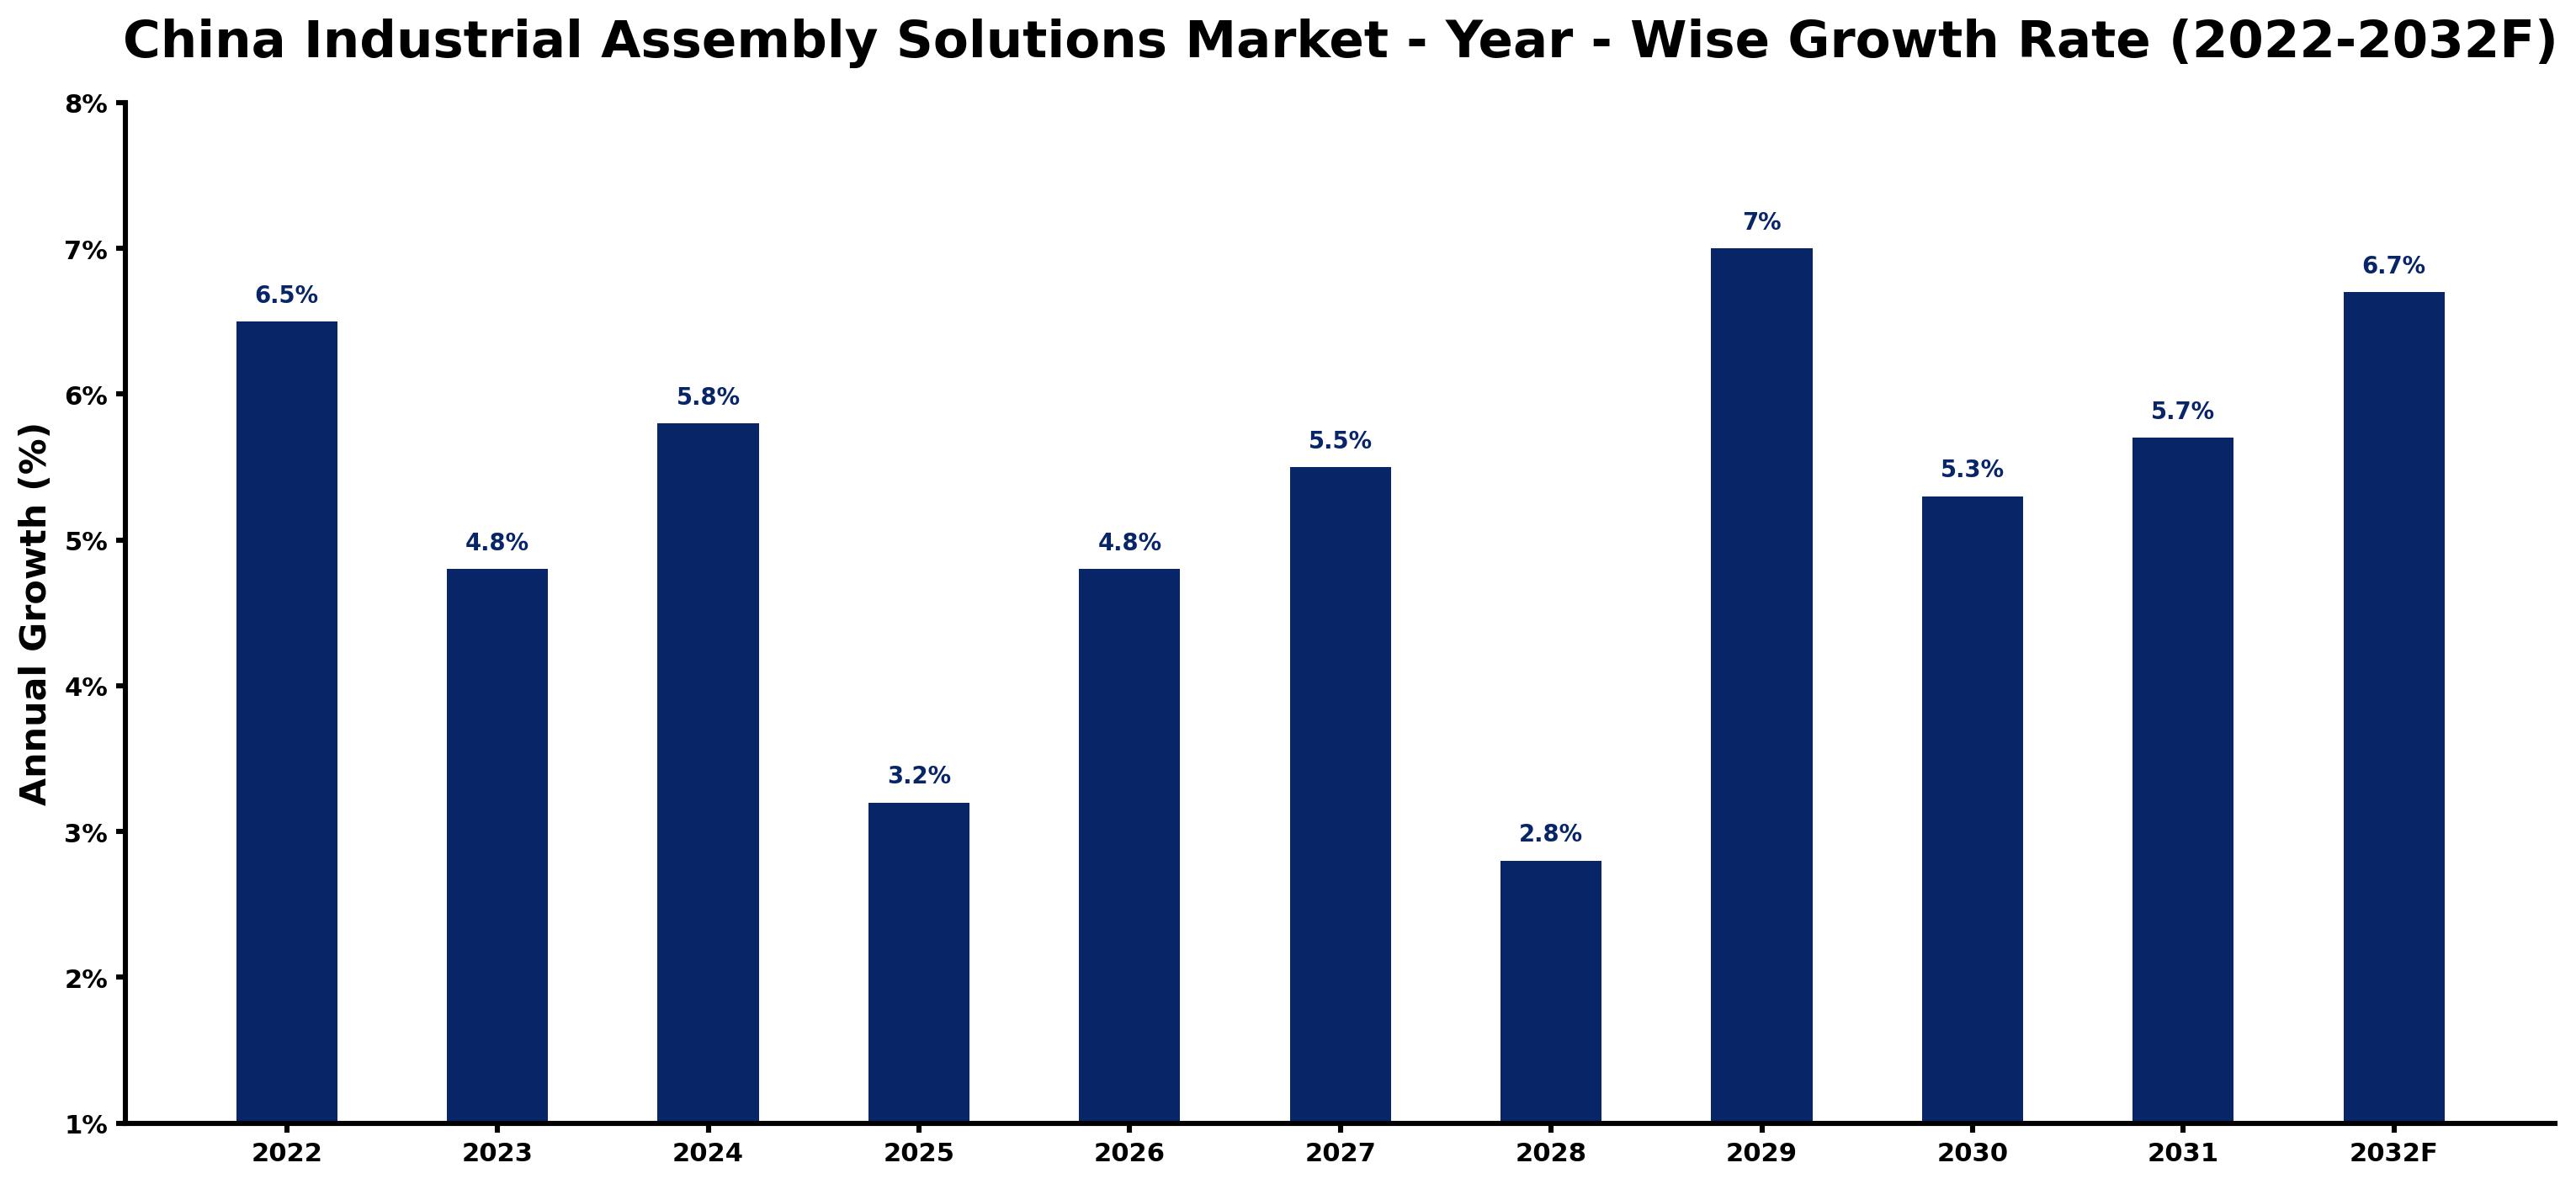
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.5 | The automotive sector produced 26 million vehicles, driving demand for assembly solutions. |
| 2023 | 4.8 | Growth slowed due to adjustments in the electronics manufacturing sector, affecting assembly needs. |
| 2024 | 5.8 | Increased production in the automotive sector boosted demand for assembly technologies. |
| 2025 | 3.2 | The market saw slower growth as manufacturers adapted to the 'Made in China 2025' standards. |
| 2026 | 4.8 | Rising investments in automation technologies are expected to increase demand for assembly solutions. |
| 2027 | 5.5 | The electronics manufacturing industry is projected to expand, driving further demand for assembly solutions. |
| 2028 | 2.8 | Growth is expected to slow as manufacturers face challenges integrating advanced technologies. |
| 2029 | 7.0 | The introduction of new automation standards is projected to spur demand for advanced assembly solutions. |
| 2030 | 5.3 | Demand is expected to stabilise as manufacturers adjust to the 'National Intelligent Manufacturing Standardization System'. |
| 2031 | 5.7 | Increased production capabilities in the automotive sector will lead to higher demand for assembly solutions. |
| 2032 | 6.7 | The aerospace industry is projected to reach $1 trillion, boosting demand for assembly technologies. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Assembly Solutions Market Synopsis
Industrial Assembly Solutions in China encompass a range of technologies and tools used to assemble products across various industries. These solutions improve efficiency and precision through mechanical engineering and automation technologies. The China Industrial Assembly Solutions Market is experiencing growth driven by the automotive and electronics sectors, with investments in advanced manufacturing technologies. The 'Made in China 2025' initiative and the 'Smart Manufacturing Innovation Action Plan' are key drivers of this expansion, promoting automation and innovation in assembly processes.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing demand from the automotive sector drives the need for advanced assembly solutions. | Driver | High | Fully Automated Lines |
| Rising investments in electronics manufacturing increase the demand for assembly technologies. | Driver | High | PLC + Robotics |
| The electronics manufacturing industry in China is valued at over $1 trillion, creating opportunities for assembly solutions. | Opportunity | High | Electronics Manufacturers |
| The Guangdong province is a major hub for electronics manufacturing, attracting assembly solution providers. | Opportunity | High | SME Workshops |
| Challenges in integrating advanced technologies can slow down growth in assembly solutions. | Restraint | Medium | Flexible Assembly Cells |
| Market adjustments in the automotive sector may limit immediate growth in assembly solutions. | Restraint | Medium | Automotive Assembly Plants |
| Buyers face delays in adopting new technologies due to high initial costs. | Challenge | High | Aerospace & Defense Firms |
| Suppliers struggle with meeting evolving quality standards in assembly solutions. | Challenge | Medium | Manual Assembly Tools |
Evaluation of Drivers in China Industrial Assembly Solutions Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased vehicle production in the automotive sector drives demand for automated assembly lines. | Fully Automated Lines | In 2022, the automotive sector produced 26 million vehicles, necessitating advanced assembly solutions. |
| Rising investments in electronics manufacturing boost the need for assembly technologies. | PLC + Robotics | The electronics manufacturing industry in China is valued at over $1 trillion, increasing demand. |
| The 'Made in China 2025' initiative promotes automation in manufacturing, boosting assembly solution demand. | Flexible Assembly Cells | This initiative aims to upgrade manufacturing capabilities, promoting efficiency. |
| The growing aerospace sector requires high-precision assembly solutions for complex systems. | Aerospace & Defense Firms | The aerospace industry in China is projected to reach $1 trillion by 2040, increasing demand. |
| The establishment of the 'National Intelligent Manufacturing Standardization System' encourages automation in assembly processes. | Conveyor-Based | This standardisation promotes the adoption of advanced assembly technologies. |
Expansion of the Industrial Assembly Solutions market in China is supported by increasing demand from the automotive and electronics sectors. In 2022, the automotive sector produced 26 million vehicles, creating a need for advanced assembly solutions. The electronics manufacturing industry, valued at over $1 trillion, relies heavily on assembly technologies. The 'Smart Manufacturing Innovation Action Plan' is also expected to improve efficiency and quality in assembly processes.
Evaluation of Restraints in China Industrial Assembly Solutions Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High initial costs of advanced assembly technologies can deter buyers in the market. | Flexible Assembly Cells | Investments in automation technologies require substantial capital, limiting adoption. |
| Market adjustments in the automotive sector may lead to slower growth in assembly solutions. | Automotive Assembly Plants | Changes in production strategies can impact the demand for assembly technologies. |
| Integration challenges with existing manufacturing processes can hinder efficiency gains. | PLC + Robotics | Manufacturers may struggle to adapt new technologies to legacy systems. |
| Quality standards in assembly solutions are evolving, posing challenges for suppliers. | Manual Assembly Tools | Suppliers must continuously adapt to meet new regulatory requirements. |
| Limited awareness of advanced assembly solutions among small manufacturers restricts market growth. | SME Workshops | Small manufacturers may lack knowledge of available technologies. |
China Industrial Assembly Solutions Market Challenges
Buyers and suppliers in the China Industrial Assembly Solutions market face immediate technology challenges as many struggle to implement advanced automation tools. This delay can extend production lead times by up to 30%, affecting delivery schedules for manufacturers. Compliance with the National Standard GB/T 19001-2016 introduces regulatory hurdles, costing suppliers around 15% of their annual budget for necessary upgrades. Rising raw material prices have increased assembly solution costs by 20%, squeezing profit margins for buyers. A persistent skills gap in the workforce, lacking training in modern assembly techniques, further hampers productivity for producers.
Trends in the China Industrial Assembly Solutions Market
Buyers and suppliers in the China Industrial Assembly Solutions Market are adjusting to the following trends.
- Shift towards Automation in Manufacturing: Since 2021, there has been a notable shift towards automation in manufacturing processes, particularly in the Guangdong province. The 'National Intelligent Manufacturing Standardization System' promotes this change, leading to increased efficiency in assembly lines.
- Transition from Manual to Automated Assembly: The transition from manual assembly tools to automated systems is occurring in automotive assembly plants. In 2022, the automotive sector produced 26 million vehicles, necessitating advanced assembly solutions for efficiency.
- Emergence of High-Mix Assembly Processes: High-mix assembly processes are becoming more prevalent, particularly in electronics manufacturing. The growing demand for varied products in smaller batches is driving this trend, with a projected CAGR of 7.0% for high-mix assembly.
- Prioritisation of Quality Management Standards: The introduction of GB/T 19001-2016 quality management standards in 2016 has prioritised quality in assembly solutions. This standard ensures that assembly processes meet stringent quality requirements, enhancing competitiveness.
Investment Opportunities in the China Industrial Assembly Solutions Market
Some of the investment opportunities in the China Industrial Assembly Solutions Market are mentioned below.
- $10 billion investment in advanced manufacturing technologies: With a $10 billion investment announced in 2023, there is a clear opportunity for suppliers of assembly solutions. Electronics manufacturers in China are seeking advanced technologies to improve production efficiency.
- Rising vehicle production presents opportunities: The automotive sector's production of 26 million vehicles in 2022 presents an opportunity for assembly solution providers. Partnering with automotive assembly plants can lead to increased sales.
- Need for automation in SME workshops: As small manufacturers seek to improve efficiency, there is a growing demand for assembly solutions. Collaborating with SME workshops can help suppliers tap into this emerging market.
- Entry through local partnerships: Establishing local partnerships can facilitate entry into the Chinese market for assembly solutions. This approach can help navigate regulatory requirements and enhance market presence.
Government Initiatives in the China Industrial Assembly Solutions Market
The '14th Five-Year Plan for Economic and Social Development', released by the National Development and Reform Commission in 2021, focuses on advanced manufacturing and automation. This plan encourages investment in assembly technologies, boosting the capabilities of local manufacturers. Additionally, the 'Smart Manufacturing Innovation Action Plan' launched by the Ministry of Industry and Information Technology in 2022 promotes the adoption of advanced assembly solutions, providing a framework for manufacturers to improve efficiency and quality in their processes. Furthermore, the 'Made in China 2025' program initiated in 2015 aims to upgrade the manufacturing sector with advanced assembly technologies, fostering innovation and competitiveness.
The Ministry of Industry and Information Technology oversees the implementation of various schemes to support the assembly solutions market. For instance, the government allocated $5 billion in 2023 to support the development of robotics and automation in manufacturing. This funding aims to improve the capabilities of manufacturers, enabling them to adopt advanced assembly technologies. Moreover, the annual China International Industry Fair showcases advancements in assembly technologies, providing a platform for manufacturers to explore new solutions.
Future Insight of the China Industrial Assembly Solutions Market
Several forward-looking factors are expected to support the China Industrial Assembly Solutions market in the coming years. The 'Made in China 2025' initiative will stimulate investment in advanced manufacturing technologies, enhancing production capabilities. A substantial government investment of $10 billion in advanced manufacturing technologies will foster innovation and improve efficiency in assembly processes. The establishment of the National Intelligent Manufacturing Standardization System will promote automation, benefiting both buyers and suppliers.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Assembly Type – Fully Automated Lines Dominated, Flexible Assembly Cells Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, with a 47% revenue share in 2025, Fully Automated Lines was the largest assembly type category. Fully Automated Lines command the largest market share due to their ability to deliver high efficiency and consistency in large-scale production. An example is the automotive sector, which produced 26 million vehicles in 2022, heavily relying on these lines for effective assembly. Over 2026–2032, Flexible Assembly Cells are expected to post the fastest growth, at a CAGR of 6.9%. Flexible Assembly Cells are experiencing rapid growth as they provide manufacturers with the ability to adapt efficiently to the production of diverse products. This adaptability is particularly critical in the electronics sector, valued at over $1 trillion, where demand for varied products is on the rise. Suppliers should focus on enhancing the adaptability of their assembly solutions to better meet the evolving requirements of manufacturers.
By Automation Level – PLC + Robotics Dominated and Is Expected to Record the Fastest Growth
In 2025, PLC + Robotics led the automation level split with a 41% share. PLC + Robotics holds the leading market share as it merges programmable logic controllers with robotics, offering advanced automation solutions. This integration is essential for industries looking to optimise production processes and lower labour costs significantly. The same category are also set to grow fastest, at a CAGR of 7.0% during 2026–2032. The growth of PLC + Robotics is set to continue as manufacturers increasingly embrace these advanced automation technologies to enhance operational efficiency. Furthermore, the government's $10 billion investment in advanced manufacturing technologies will likely accelerate this trend. Buyers should prioritise investments in PLC + Robotics to maintain competitiveness in a rapidly automating manufacturing landscape.
By Assembly Process – Conveyor-Based Dominated, High-Mix Expected to Grow Fastest
Conveyor-Based held a 35% share of the China Industrial Assembly Solutions Market by assembly process in 2025. Conveyor-Based systems dominate the market as they enable continuous assembly flow, making them particularly suitable for high-volume production. This method is extensively utilised in automotive assembly plants, which require seamless operations to achieve their production goals. The quickest growth will come from High-Mix, forecast to expand at a CAGR of 7.0% between 2026 and 2032. High-Mix processes are witnessing rapid growth since they facilitate the production of varied products in smaller batches, addressing the diverse needs of the electronics industry. As consumer preferences shift towards customised offerings, this segment is poised for further momentum. Suppliers need to develop versatile assembly solutions to cater to the increasing demand for high-mix production capabilities.
By End User – Automotive Assembly Plants Dominated, Electronics Manufacturers Expected to Grow Fastest
The largest end user category in 2025 was Automotive Assembly Plants, with a 38% share of total revenue. Automotive Assembly Plants command the largest market share as they heavily rely on advanced assembly solutions for vehicle production. With 26 million vehicles produced in 2022, the need for efficient assembly processes is critical in this sector. Electronics Manufacturers are projected to grow fastest, at a CAGR of 6.9% during 2026–2032. Electronics Manufacturers are the fastest-growing segment as they increasingly depend on assembly solutions for component assembly. The electronics manufacturing industry, valued at over $1 trillion, is driving this demand as it expands rapidly. Buyers in the electronics sector should prioritise advanced assembly solutions to improve their production capabilities and meet rising market demands.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Assembly Solutions Market Outlook
- Market Size of China Industrial Assembly Solutions Market, 2025
- Forecast of China Industrial Assembly Solutions Market, 2032
- Historical Data and Forecast of China Industrial Assembly Solutions Revenues & Volume for the Period 2022 - 2032F
- China Industrial Assembly Solutions Market Trend Evolution
- China Industrial Assembly Solutions Market Drivers and Challenges
- China Industrial Assembly Solutions Price Trends
- China Industrial Assembly Solutions Porter's Five Forces
- China Industrial Assembly Solutions Industry Life Cycle
- Historical Data and Forecast of China Industrial Assembly Solutions Market Revenues & Volume By Assembly Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Assembly Solutions Market Revenues & Volume By Manual Assembly Tools for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Assembly Solutions Market Revenues & Volume By Semi-Automated Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Assembly Solutions Market Revenues & Volume By Fully Automated Lines for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Assembly Solutions Market Revenues & Volume By Flexible Assembly Cells for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Assembly Solutions Market Revenues & Volume By Automation Level for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Assembly Solutions Market Revenues & Volume By Low Automation for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Assembly Solutions Market Revenues & Volume By Partially Integrated for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Assembly Solutions Market Revenues & Volume By PLC + Robotics for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Assembly Solutions Market Revenues & Volume By Reconfigurable Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Assembly Solutions Market Revenues & Volume By Assembly Process for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Assembly Solutions Market Revenues & Volume By Operator-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Assembly Solutions Market Revenues & Volume By Conveyor-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Assembly Solutions Market Revenues & Volume By Continuous Flow for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Assembly Solutions Market Revenues & Volume By High-Mix, Low-Volume for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Assembly Solutions Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Assembly Solutions Market Revenues & Volume By SME Workshops for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Assembly Solutions Market Revenues & Volume By Electronics Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Assembly Solutions Market Revenues & Volume By Automotive Assembly Plants for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Assembly Solutions Market Revenues & Volume By Aerospace & Defense Firms for the Period 2022 - 2032F
- China Industrial Assembly Solutions Import Export Trade Statistics
- Market Opportunity Assessment By Assembly Type
- Market Opportunity Assessment By Automation Level
- Market Opportunity Assessment By Assembly Process
- Market Opportunity Assessment By End User
- China Industrial Assembly Solutions Top Companies Market Share
- China Industrial Assembly Solutions Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Assembly Solutions Company Profiles
- China Industrial Assembly Solutions Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Assembly Type
- Manual Assembly Tools
- Semi-Automated Systems
- Fully Automated Lines
- Flexible Assembly Cells
By Automation Level
- Low Automation
- Partially Integrated
- PLC + Robotics
- Reconfigurable Systems
By Assembly Process
- Operator-Based
- Conveyor-Based
- Continuous Flow
- High-Mix
- Low-Volume
By End User
- SME Workshops
- Electronics Manufacturers
- Automotive Assembly Plants
- Aerospace & Defense Firms































