China Industrial Casting Market Size & Growth Rate
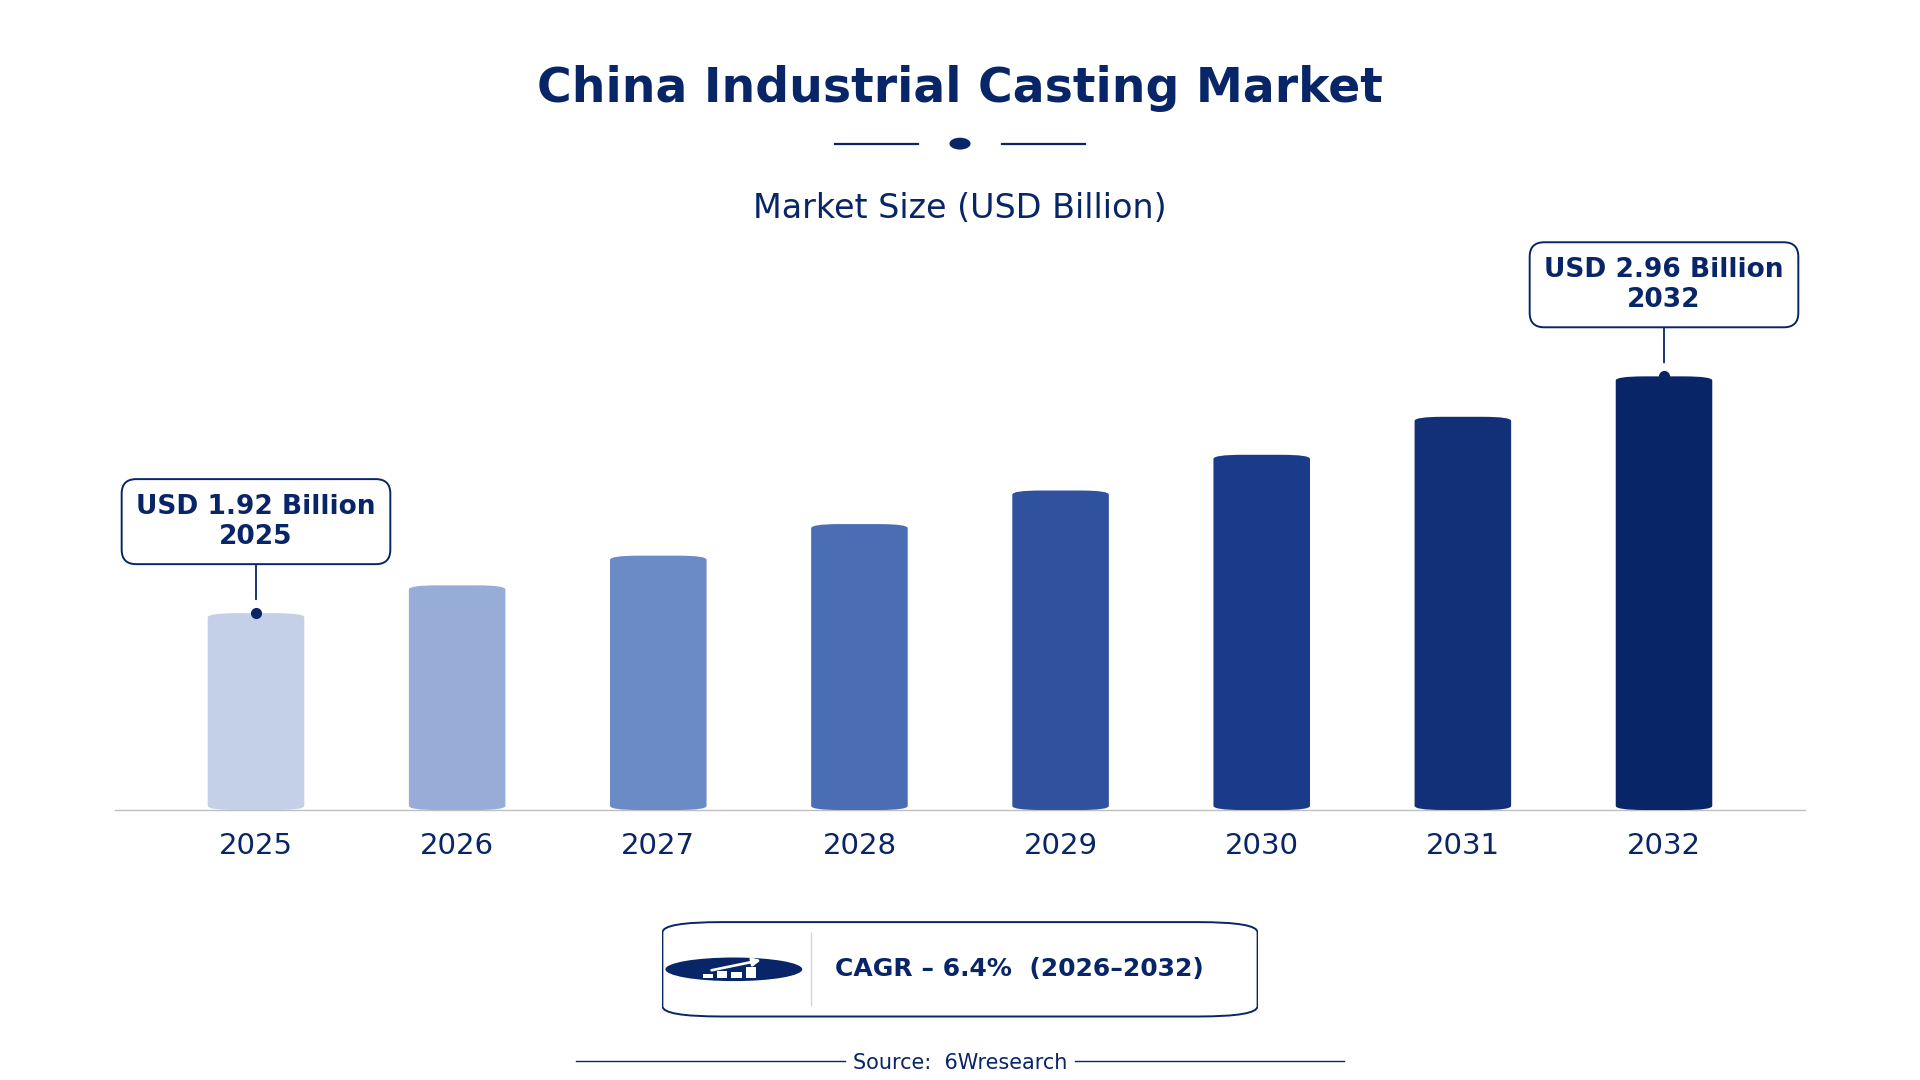
According to 6Wresearch internal database and industry insights, the China Industrial Casting Market was valued at USD 1.92 billion in 2025 and is projected to reach USD 2.96 billion by 2032, growing at a CAGR of approximately 6.4% during 2026–2032.
China Industrial Casting Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Casting Market |
| Market Size 2025 | USD 1.92 billion |
| Market Size 2032 | USD 2.96 billion |
| Absolute Growth 2025–2032 | USD 1.04 billion |
| CAGR 2026–2032 | 6.4% |
| Peak Annual Growth | 9.0% in 2030 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Casting Method, 2025 | Sand Casting (43% share) |
| Leading Metal Type, 2025 | Steel (28% share) |
| Leading End Process Use, 2025 | Engine Blocks (38% share) |
| Leading End User, 2025 | Automotive Industry (36% share) |
| Fastest-Growing Casting Method | Investment Casting (7.7% CAGR) |
| Fastest-Growing Metal Type | Aluminum (7.6% CAGR) |
| Fastest-Growing End Process Use | Aerospace Components (7.9% CAGR) |
| Fastest-Growing End User | Defense & Aviation Firms (9.1% CAGR) |
| Growing Sector | Defense & Aviation Firms |
| Key End Users | Automotive Industry, Industrial Machinery OEMs, Defense & Aviation Firms, Electronics Manufacturers |
China Industrial Casting Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
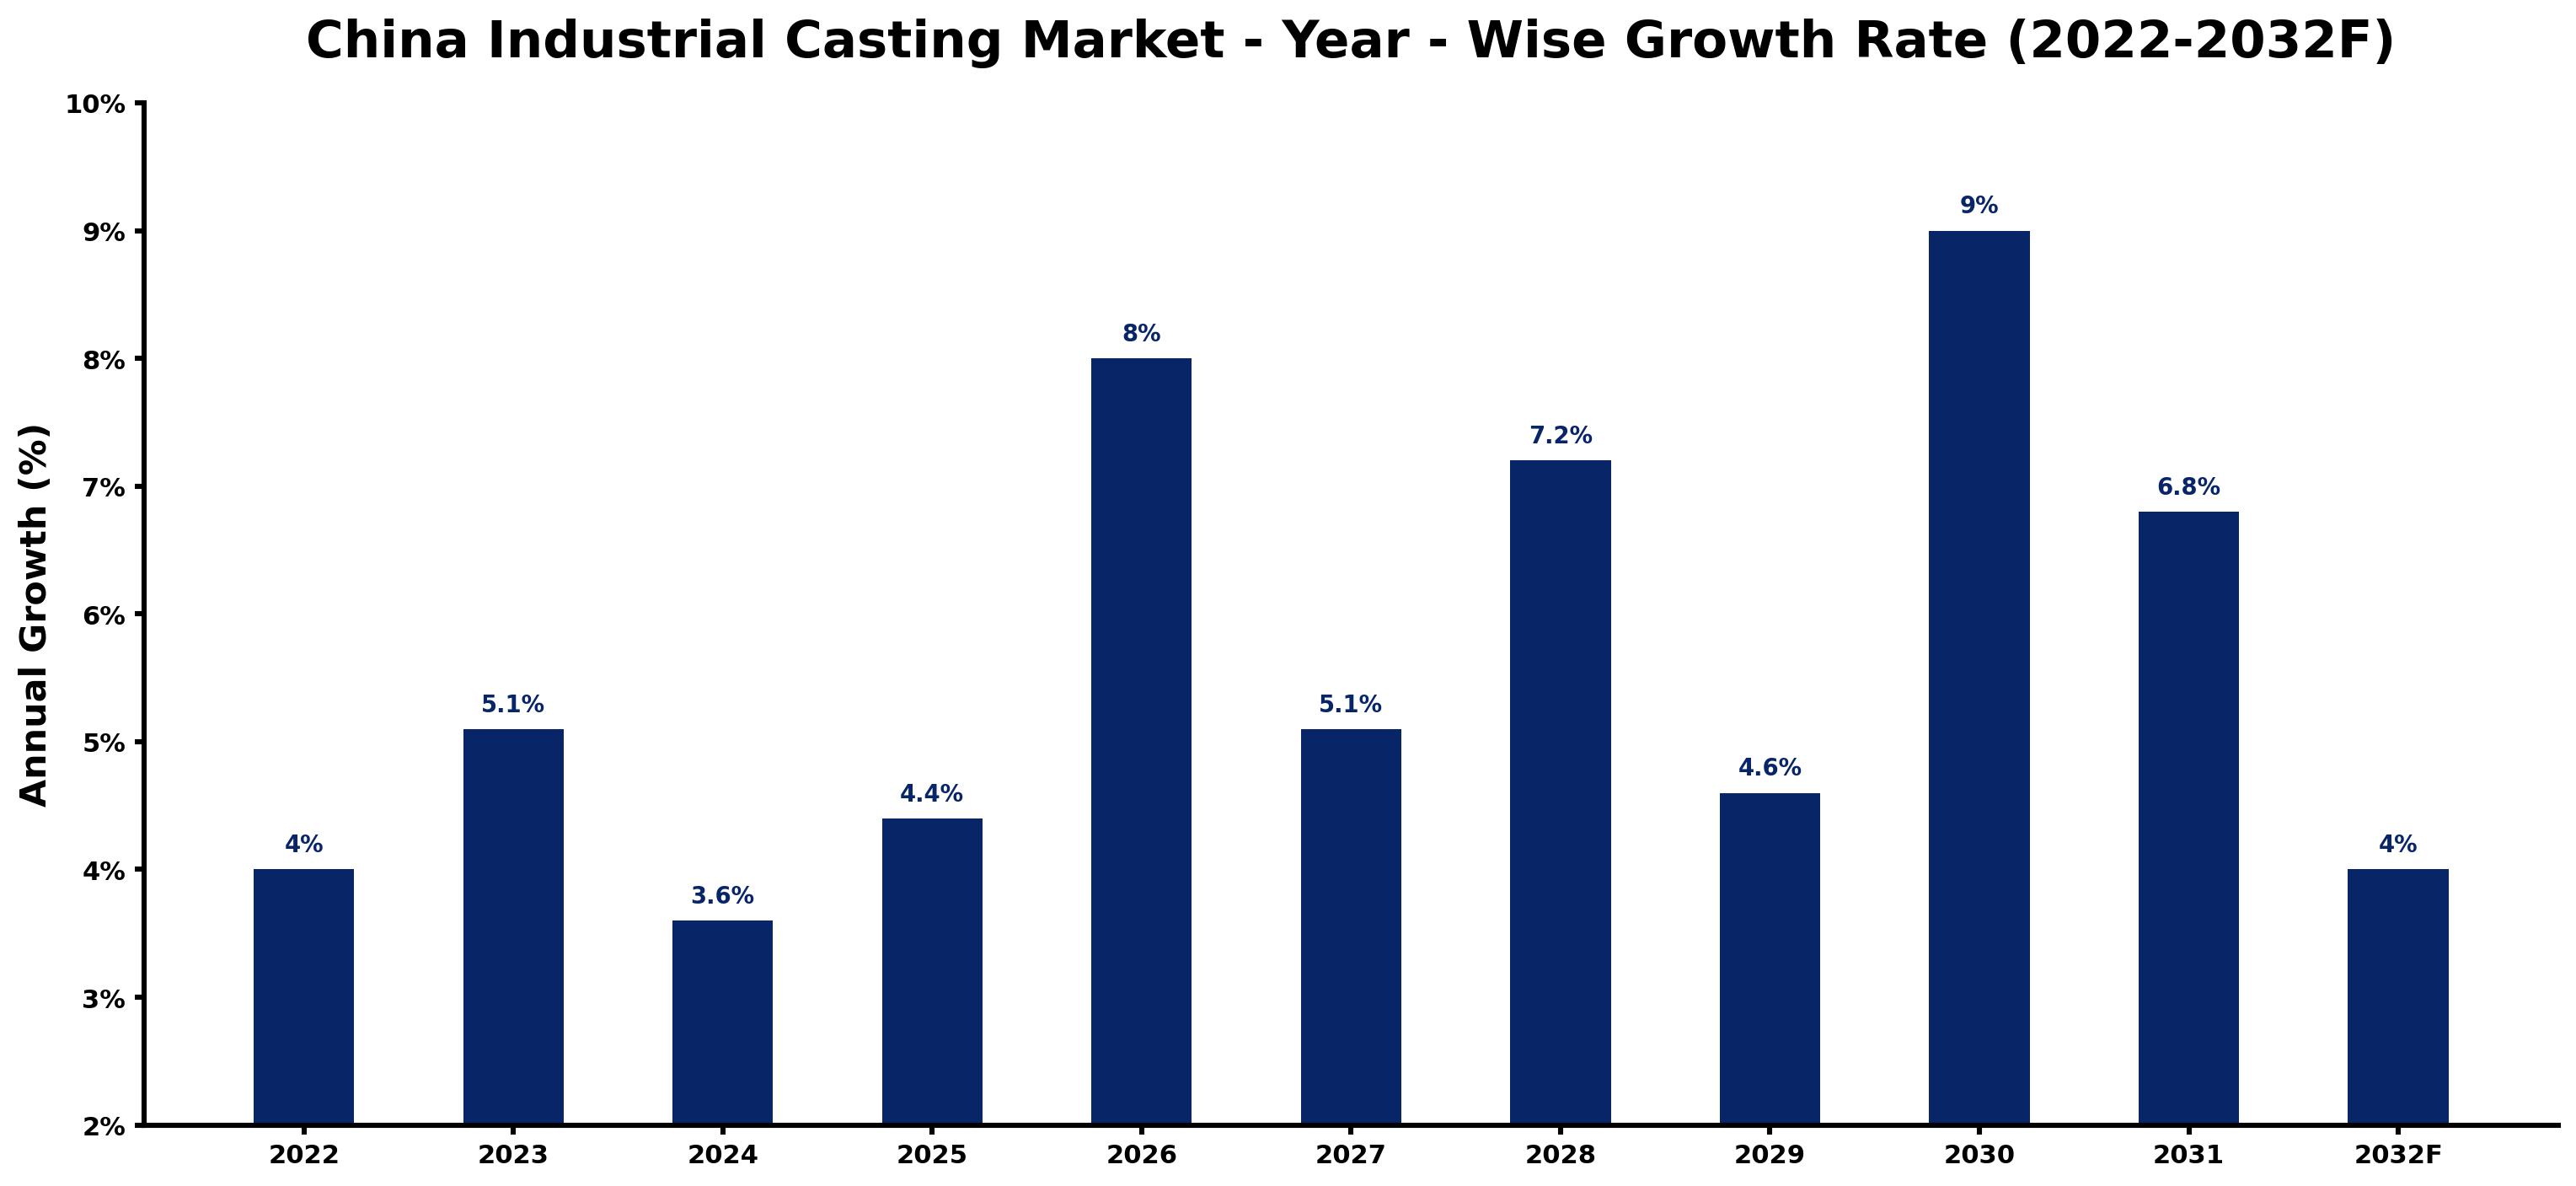
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.0 | The market experienced steady growth due to strong demand from the automotive industry and industrial machinery sectors. |
| 2023 | 5.1 | Growth was driven by increased automotive production and the need for high-quality cast components, particularly in Jiangsu province. |
| 2024 | 3.6 | A slowdown occurred as demand stabilised following the previous year's surge in production, influenced by the Green Manufacturing Program. |
| 2025 | 4.4 | Growth accelerated again, supported by rising investments in casting technologies and infrastructure, particularly in Guangdong province. |
| 2026 | 8.0 | The market is expected to see growth from increased aerospace demand for precision castings, bolstered by over 100 certified manufacturers. |
| 2027 | 5.1 | Demand growth is projected to slow as manufacturers adjust to market conditions and production capacities, following the National Standard for Foundry Processes. |
| 2028 | 7.2 | Growth is anticipated to pick up again, driven by advancements in die casting technologies and applications, particularly in automotive sectors. |
| 2029 | 4.6 | A slowdown is expected as the market adjusts to previous growth rates and demand levels, influenced by operational costs. |
| 2030 | 9.0 | The market is projected to peak with strong demand from the automotive sector and increased production capabilities due to the Made in China 2025 initiative. |
| 2031 | 6.8 | Growth is expected to slow as the market stabilises after reaching its peak in the previous year, particularly in the defense sector. |
| 2032 | 4.0 | The market will continue to grow, albeit at a slower pace, as industries adapt to new standards and regulations. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Casting Market Synopsis
The China Industrial Casting Market encompasses the manufacturing process of pouring molten metal into molds to create complex shapes. This process primarily uses methods like sand casting and die casting, producing components for automotive, aerospace, and industrial machinery sectors. The market is growing due to strong demand from the automotive industry, which accounts for approximately 70% of casting demand. The aerospace sector is also driving new demand through investment casting, with over 100 certified manufacturers supporting production capabilities.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased investment in casting technologies | Driver | High | Die Casting |
| Rising demand from the automotive sector | Driver | High | Engine Blocks |
| Growing need for precision components in aerospace | Opportunity | High | Investment Casting |
| Expansion of foundries in Jiangsu and Guangdong provinces | Opportunity | High | Sand Casting |
| High operational costs for foundries | Restraint | Medium | Sand Casting |
| Strict compliance with quality standards | Restraint | Medium | Sand Casting |
| Supply chain disruptions affecting raw material availability | Challenge | High | Sand Casting |
| Technological advancements requiring significant R&D investment | Challenge | Medium | Die Casting |
Evaluation of Drivers in China Industrial Casting Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased investment in die casting technology | Die Casting | Over 5 billion yuan allocated for R&D improves production efficiency and capacity. |
| Rising automotive production | Engine Blocks | The automotive sector accounted for approximately 70% of casting demand in 2022. |
| Growth in aerospace components production | Investment Casting | Investment casting is widely used in aerospace, with over 100 certified manufacturers supporting production. |
| Expansion of foundry capabilities in key provinces | Sand Casting | Foundries concentrated in Jiangsu and Guangdong provinces enable increased production. |
| Demand for lightweight materials in automotive applications | Aluminum | Aluminum castings are projected to reach 10 million tons by 2025, reflecting market shifts. |
Growth in the Industrial Casting market in China comes from increased investment in die casting technology, with over 5 billion yuan allocated for R&D to improve production efficiency. The automotive sector, responsible for approximately 70% of casting demand, continues to drive growth, particularly for engine blocks. Investment casting is gaining traction in aerospace, supported by over 100 certified manufacturers. Foundries in Jiangsu and Guangdong provinces are expanding their capabilities, further boosting production. Demand for lightweight materials, particularly aluminum, is projected to reach 10 million tons by 2025, creating additional opportunities for suppliers.
Evaluation of Restraints in China Industrial Casting Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High operational costs for foundries | Sand Casting | Operational costs remain high, impacting profitability for manufacturers across the board, particularly in Jiangsu province. |
| Strict compliance with national quality standards | Sand Casting | National Standard GB/T 1801-2020 requires investment in quality control, affecting smaller manufacturers. |
| Limited availability of raw materials | Sand Casting | Supply chain disruptions are affecting the availability of essential raw materials, leading to production delays. |
| Technological advancements requiring R&D investment | Sand Casting | The Green Manufacturing Program necessitates investment in environmentally friendly practices, raising operational costs. |
| Market fluctuations due to global demand shifts | Sand Casting | Changes in global demand for cast components can lead to unpredictable production schedules. |
China Industrial Casting Market Challenges
Buyers in the China Industrial Casting Market face supply chain delays due to the concentration of foundries in Jiangsu and Guangdong provinces, which can extend delivery times by up to four weeks and raise logistics costs for manufacturers in other regions. Rising compliance costs with National Standard GB/T 1801-2020 burden buyers, risking production halts and potential contract losses. Suppliers encounter challenges with technology adoption in die casting, necessitating over 5 billion yuan for R&D, which limits their ability to meet evolving manufacturing demands. Skills shortages in the workforce are expected to lead to a 15% increase in operational costs for producers by 2025, complicating their competitiveness.
Trends in the China Industrial Casting Market
Four trends stand out in the China Industrial Casting Market.
- Green Manufacturing Program Initiatives: The Green Manufacturing Program initiated in 2020 encourages foundries to adopt environmentally friendly practices. This shift is raising compliance costs, with many foundries investing in sustainable technologies to meet new standards.
- Transition to Lightweight Materials: The trend towards lightweight materials in automotive applications is gaining momentum, driven by demand for fuel efficiency. Aluminum castings are projected to reach 10 million tons by 2025, indicating a shift in material preferences.
- Investment Casting Growth in Aerospace: Investment casting has seen increased adoption in the aerospace sector, particularly since 2021. With over 100 certified manufacturers, this method is vital for producing high-precision components.
- Expansion of Foundries in Jiangsu and Guangdong: The concentration of foundries in Jiangsu and Guangdong provinces has facilitated regional growth. This trend supports increased production capacity and efficiency, benefiting local industries.
Investment Opportunities in the China Industrial Casting Market
The following opportunities in the China Industrial Casting Market pair current demand with a clear way in.
- Joint Ventures with Local Foundries: Partnering with local foundries presents an opportunity, particularly in Jiangsu and Guangdong provinces. This collaboration can improve production capabilities and meet the increasing need for cast components, with the market projected to grow significantly.
- Investment in Die Casting Technologies: Investing in advanced die casting technologies is essential now, as the sector will see over 5 billion yuan allocated for R&D. Suppliers can benefit from this trend by offering innovative solutions to manufacturers.
- Supply of Lightweight Aluminium Castings: With aluminium castings projected to reach 10 million tons by 2025, suppliers can focus on this growing segment. Targeting automotive manufacturers will be key to capturing market share in this expanding area.
- Exploring Opportunities in Aerospace Components: The aerospace sector is rapidly expanding, with investment casting becoming increasingly important. Suppliers should consider entering this market by aligning with certified manufacturers to meet the rising demand.
Government Initiatives in the China Industrial Casting Market
The '14th Five-Year Plan for the Foundry Industry' approved in 2021 aims for technological upgrades and sustainability in casting production. This plan sets specific targets for increasing efficiency and reducing environmental impact across the industry. In 2022, the 'National Standard for Foundry Processes' was updated to improve quality control measures, ensuring that manufacturers meet stringent production standards. Additionally, the 'Green Manufacturing Program' initiated in 2020 promotes environmentally friendly practices, encouraging foundries to invest in sustainable technologies. In 2023, the government allocated 2 billion yuan to support innovation in casting technologies under the 'High-Tech Manufacturing Initiative', enhancing production capabilities for manufacturers.
The China Foundry Association plays a crucial role in facilitating the adoption of new technologies among its members, supporting over 1,000 foundries nationwide. The Ministry of Industry and Information Technology oversees the implementation of various initiatives, including the allocation of funding to support innovation in casting technologies. This funding enables manufacturers to enhance production capabilities and ensure compliance with national standards, which is crucial for maintaining competitiveness in the market.
Future Insight of the China Industrial Casting Market
The China Industrial Casting Market will see considerable changes by 2032, driven by the 'Made in China 2025' initiative focusing on advanced manufacturing capabilities. Investment in modern casting technologies will improve production efficiency and quality, benefiting both buyers and suppliers. By 2025, aluminium castings are expected to reach 10 million tons, indicating a shift towards lighter materials in manufacturing. Additionally, the Defence Industry's target to boost domestic casting production by 15% will stimulate innovation and growth in the sector.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Casting Method – Sand Casting Dominated, Investment Casting Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, Sand Casting held a 43% share of the China Industrial Casting Market by casting method in 2025. Sand casting holds the largest share in the China Industrial Casting Market because it is cost-effective and widely used for producing large parts. This method is particularly prevalent in Jiangsu and Guangdong provinces, where many foundries operate to meet diverse industrial needs. Investment Casting is set to record the highest CAGR in this split, 7.7% over 2026–2032. Investment casting is witnessing rapid growth due to its precision capabilities, especially in the aerospace sector, which has over 100 certified manufacturers. As demand for high-precision components increases, investment casting's market share will likely expand further. Suppliers should enhance their sand casting capabilities while also exploring investment casting opportunities to align with market demands.
By Metal Type – Steel Dominated, Aluminum Expected to Grow Fastest
In 2025, Steel led the metal type split with a 28% share. Steel commands the largest market share as it is vital for structural components in various industries, including automotive and construction. Its essential role ensures robust demand, particularly from the automotive sector, which heavily relies on steel castings. Over 2026–2032, Aluminum is expected to post the fastest growth, at a CAGR of 7.6%. Aluminum is projected to experience rapid growth owing to its lightweight and corrosion-resistant properties, making it increasingly favoured in automotive and aerospace applications. With aluminum castings anticipated to reach 10 million tons by 2025, this segment is set for notable expansion. Buyers should consider increasing their sourcing of aluminum castings to take advantage of their benefits, while suppliers must invest in production capabilities to meet the expected demand.
By End Process Use – Engine Blocks Dominated, Aerospace Components Expected to Grow Fastest
Engine Blocks accounted for a 38% market share by end process use in 2025. Engine blocks account for the largest share as they are critical components in automotive manufacturing, driving considerable demand for industrial castings. The automotive industry's reliance on engine blocks underscores their importance in the overall market. The quickest growth will come from Aerospace Components, forecast to expand at a CAGR of 7.9% between 2026 and 2032. Aerospace components are experiencing the fastest growth due to the rising need for specialized and precision-required parts in aviation. As the aerospace sector continues to expand, the demand for these components is expected to increase significantly. Manufacturers should prioritise the production of aerospace components to seize emerging opportunities in the aviation market.
By End User – Automotive Industry Dominated, Defense & Aviation Firms Expected to Grow Fastest
Automotive Industry took a 36% share of end user in 2025, more than any other category. The automotive industry holds the largest market share as it is the primary consumer of industrial castings in China, accounting for around 70% of casting demand. This sector's strong growth ensures a consistent demand for various casting methods and materials. Defense & Aviation Firms are projected to grow fastest, at a CAGR of 9.1% during 2026–2032. Defense and aviation firms are rapidly increasing their use of specialized casting for military applications, reflecting a growing emphasis on domestic production. This trend is anticipated to drive substantial growth in this segment in the future. Suppliers should align their offerings with the specific needs of defense and aviation firms to capitalise on this expanding market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Casting Market Outlook
- Market Size of China Industrial Casting Market, 2025
- Forecast of China Industrial Casting Market, 2032
- Historical Data and Forecast of China Industrial Casting Revenues & Volume for the Period 2022 - 2032F
- China Industrial Casting Market Trend Evolution
- China Industrial Casting Market Drivers and Challenges
- China Industrial Casting Price Trends
- China Industrial Casting Porter's Five Forces
- China Industrial Casting Industry Life Cycle
- Historical Data and Forecast of China Industrial Casting Market Revenues & Volume By Casting Method for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Casting Market Revenues & Volume By Sand Casting for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Casting Market Revenues & Volume By Investment Casting for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Casting Market Revenues & Volume By Die Casting for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Casting Market Revenues & Volume By Permanent Mold Casting for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Casting Market Revenues & Volume By Metal Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Casting Market Revenues & Volume By Cast Iron, Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Casting Market Revenues & Volume By Aluminum, Titanium for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Casting Market Revenues & Volume By Zinc, Magnesium for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Casting Market Revenues & Volume By Copper Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Casting Market Revenues & Volume By End Process Use for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Casting Market Revenues & Volume By Engine Blocks, Gears for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Casting Market Revenues & Volume By Aerospace Components for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Casting Market Revenues & Volume By Housing & Casings for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Casting Market Revenues & Volume By Pumps, Valves for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Casting Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Casting Market Revenues & Volume By Automotive Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Casting Market Revenues & Volume By Defense & Aviation Firms for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Casting Market Revenues & Volume By Electronics Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Casting Market Revenues & Volume By Industrial Machinery OEMs for the Period 2022 - 2032F
- China Industrial Casting Import Export Trade Statistics
- Market Opportunity Assessment By Casting Method
- Market Opportunity Assessment By Metal Type
- Market Opportunity Assessment By End Process Use
- Market Opportunity Assessment By End User
- China Industrial Casting Top Companies Market Share
- China Industrial Casting Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Casting Company Profiles
- China Industrial Casting Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Casting Method
- Sand Casting
- Investment Casting
- Die Casting
- Permanent Mold Casting
By Metal Type
- Cast Iron
- Steel
- Aluminum
- Titanium
- Zinc
- Magnesium
- Copper Alloys
By End Process Use
- Engine Blocks
- Gears
- Aerospace Components
- Housing & Casings
- Pumps
- Valves
By End User
- Automotive Industry
- Defense & Aviation Firms
- Electronics Manufacturers
- Industrial Machinery OEMs































