China Industrial Collaborative Robots Market Size & Growth Rate
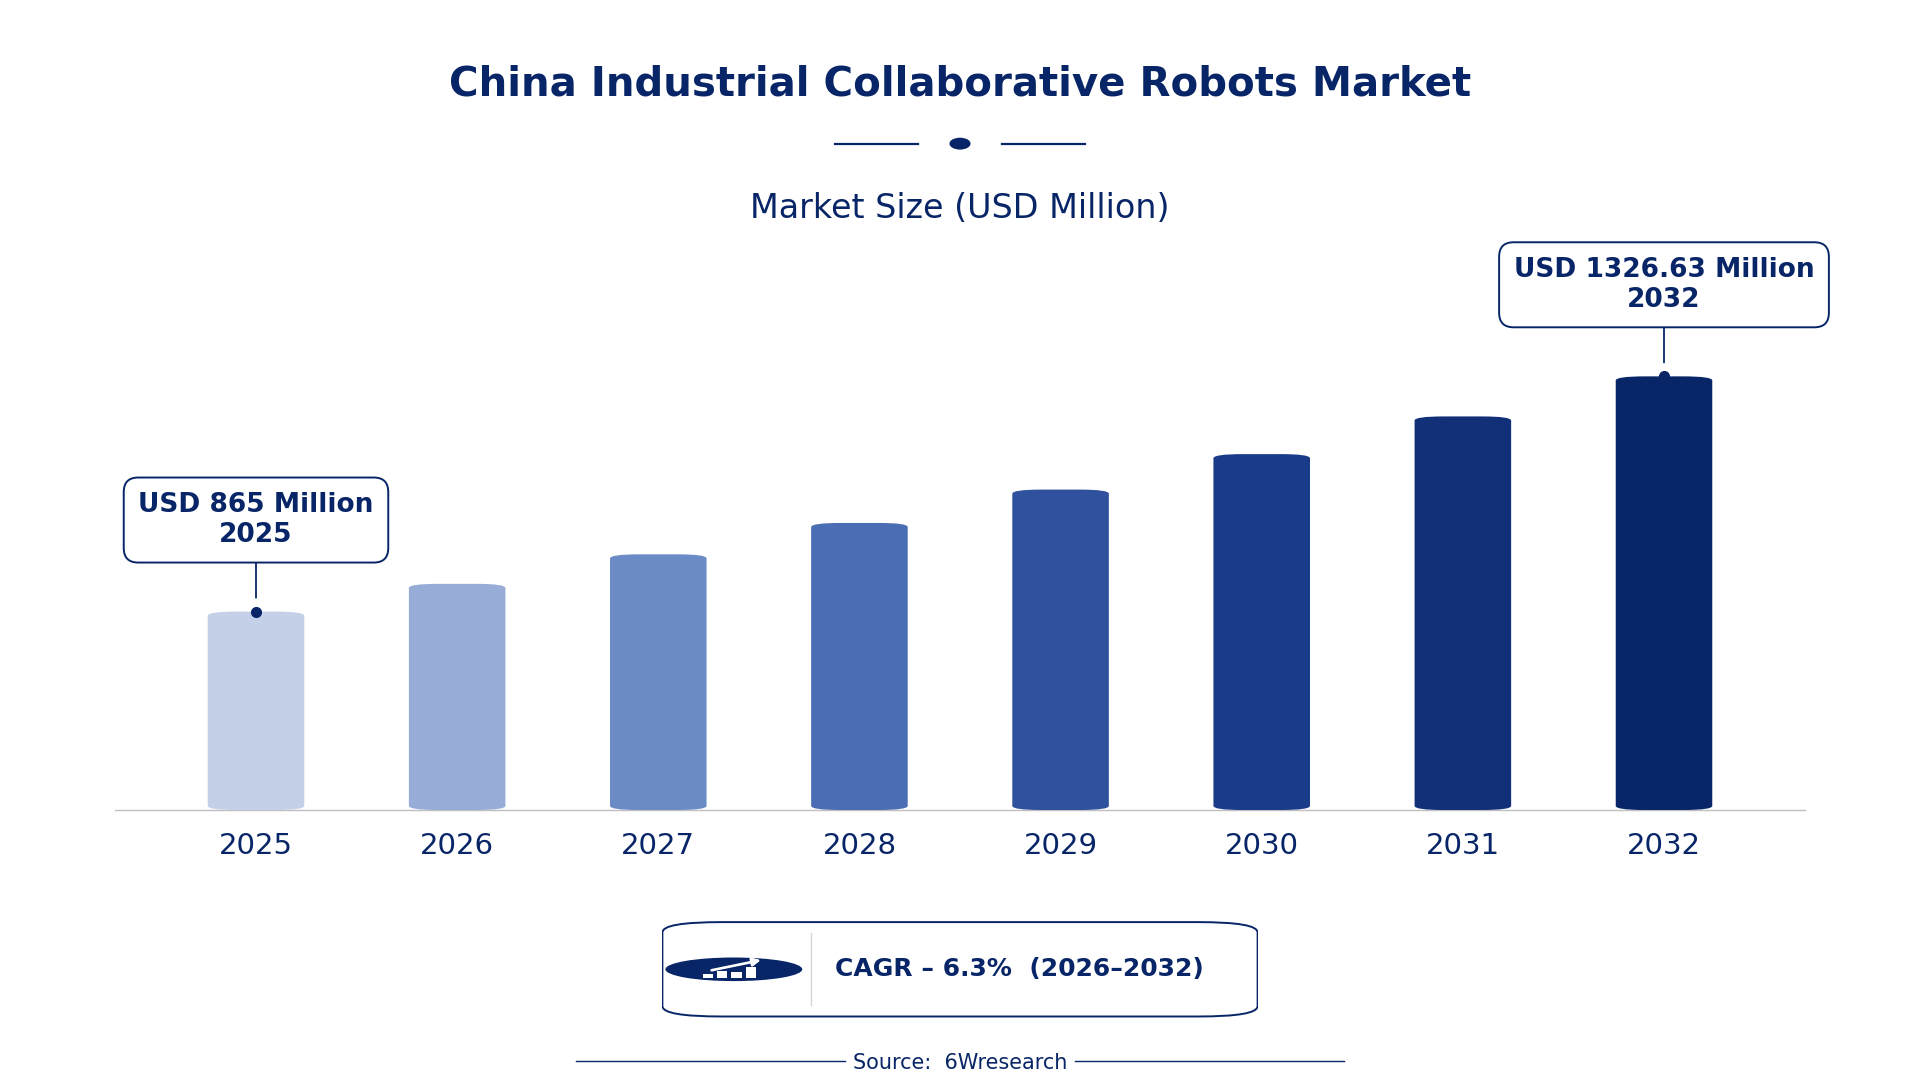
According to 6Wresearch internal database and industry insights, the China Industrial Collaborative Robots Market was valued at USD 865.0 million in 2025 and is projected to reach USD 1,326.63 million by 2032, growing at a CAGR of approximately 6.3% during 2026–2032.
China Industrial Collaborative Robots Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Collaborative Robots Market |
| Market Size 2025 | USD 865.0 million |
| Market Size 2032 | USD 1,326.63 million |
| Absolute Growth 2025–2032 | USD 461.63 million |
| CAGR 2026–2032 | 6.3% |
| Peak Annual Growth | 8.0% in 2027 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Robot Type, 2025 | Lightweight Cobots (38% share) |
| Leading Payload Range, 2025 | 15 kg (59% share) |
| Leading Application, 2025 | Lab & Electronics Assembly (32% share) |
| Leading End User, 2025 | Electronics Sector (44% share) |
| Fastest-Growing Robot Type | Medium Duty Cobots (9.1% CAGR) |
| Fastest-Growing Payload Range | Autonomous Navigation (8.0% CAGR) |
| Fastest-Growing Application | Logistics Collaboration (7.7% CAGR) |
| Fastest-Growing End User | Warehouse Automation Firms (8.9% CAGR) |
| Growing Sector | Logistics Collaboration |
| Key End Users | Lab & Electronics Assembly, Packaging, Sorting, Metal Handling |
China Industrial Collaborative Robots Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
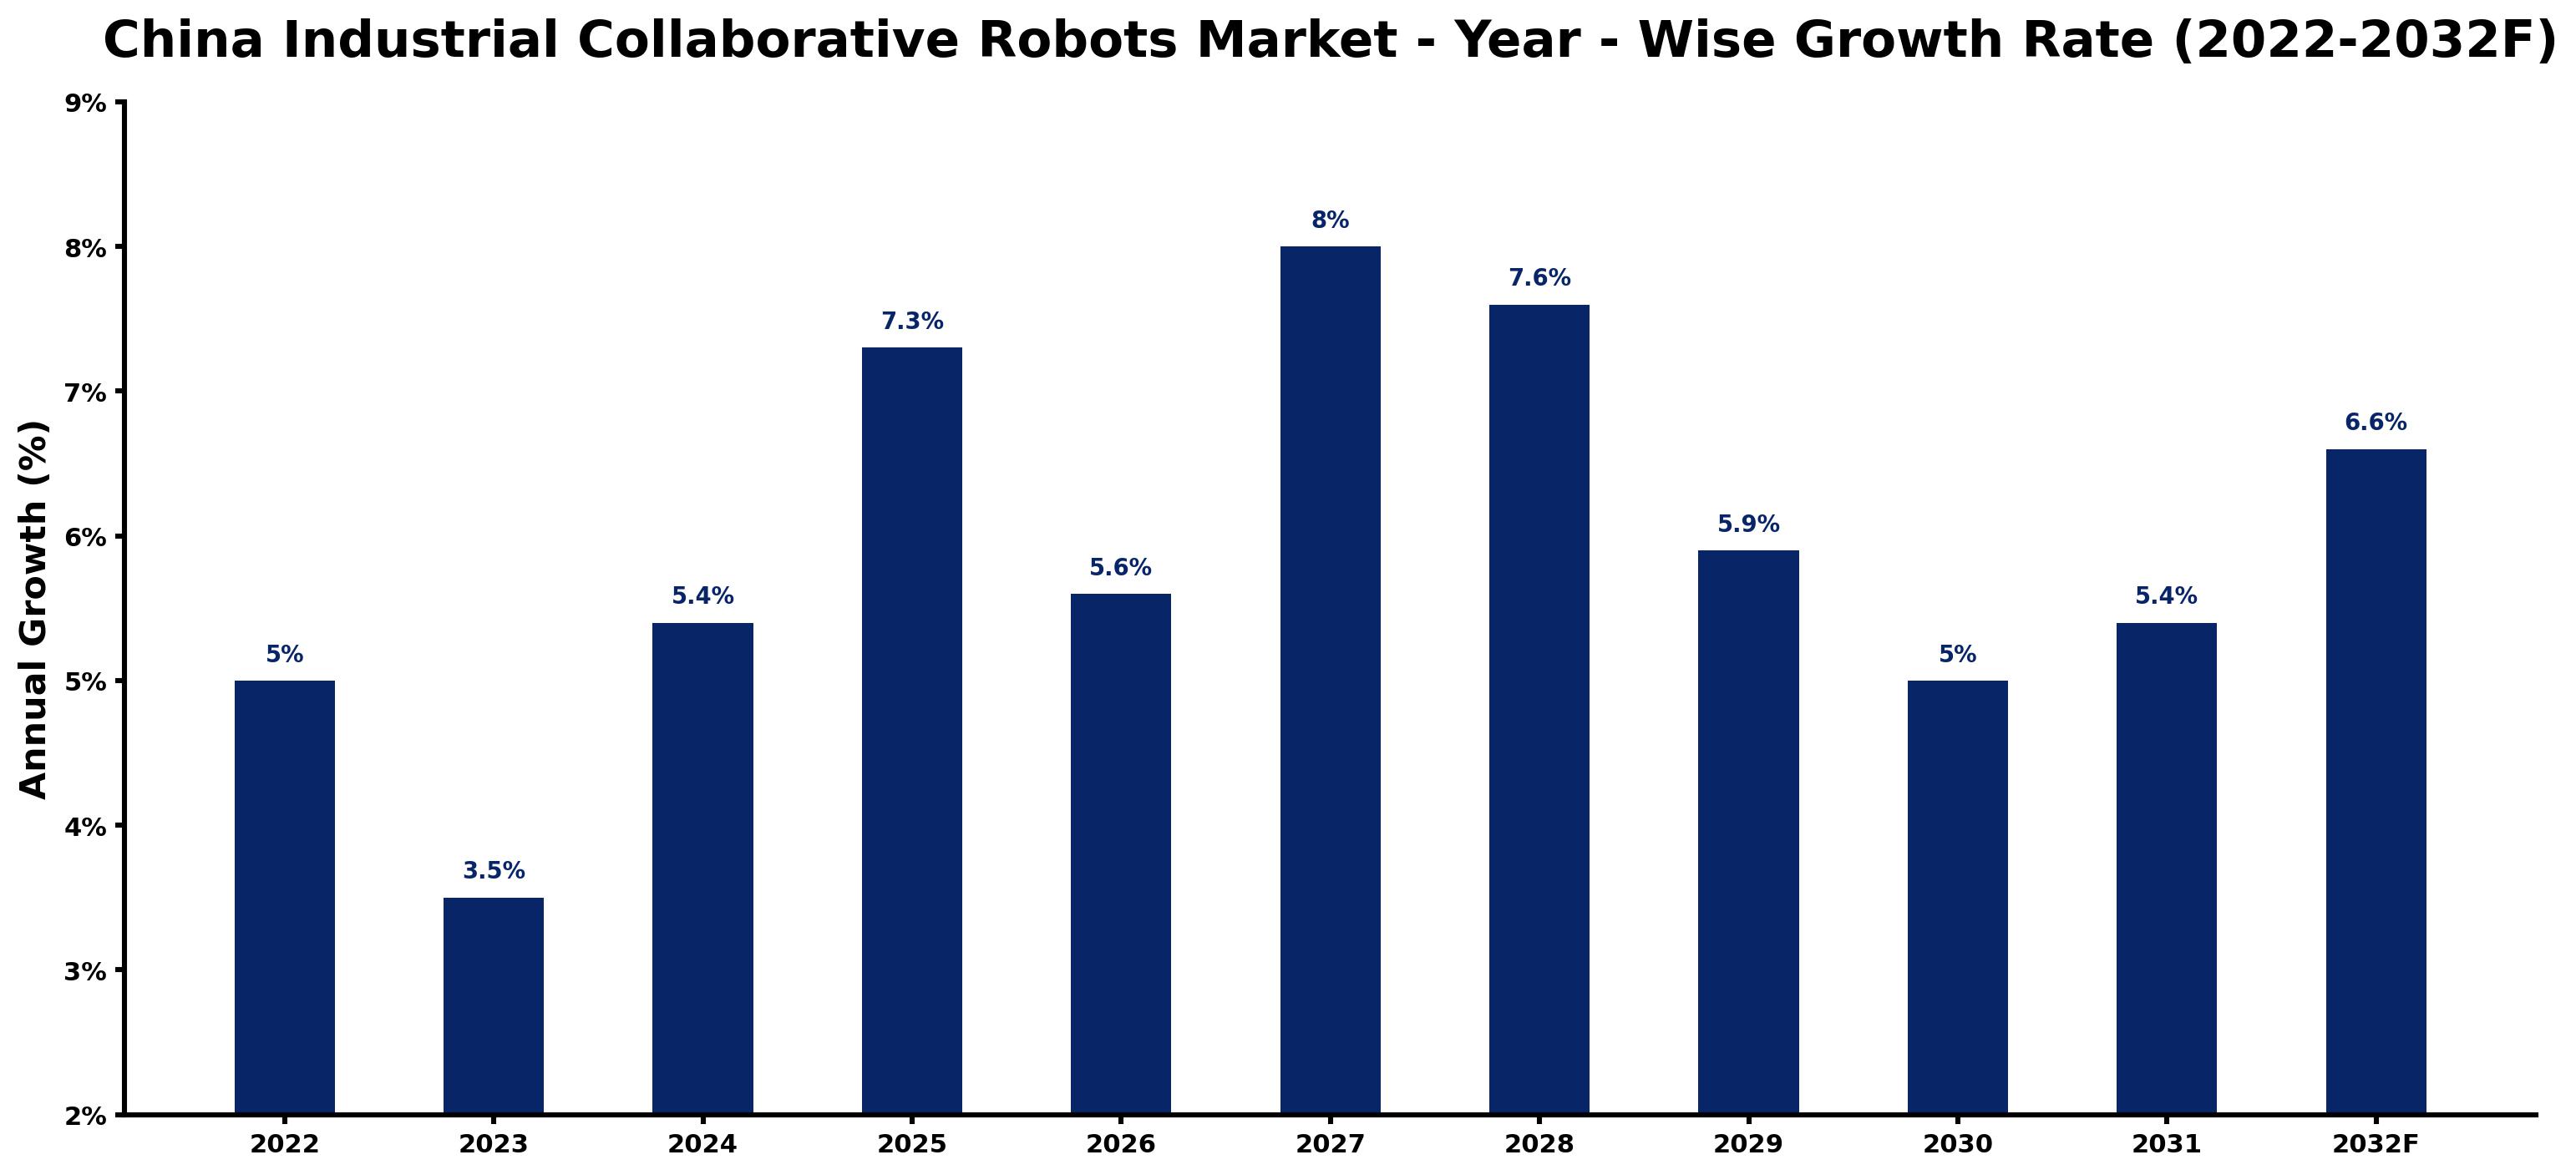
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.0 | The electronics sector accounted for over 30% of industrial robot usage in the country. |
| 2023 | 3.5 | Demand growth slowed as manufacturers adapted to increased automation requirements in production processes. |
| 2024 | 5.4 | The automotive sector is projected to adopt 20% more collaborative robots by 2024, boosting demand. |
| 2025 | 7.3 | The market experienced accelerated growth, driven by rising installations in logistics firms across Shanghai. |
| 2026 | 5.6 | Growth is expected to slow as the market stabilises following rapid expansions in previous years. |
| 2027 | 8.0 | Demand is anticipated to surge due to peak adoption of collaborative robots in various sectors. |
| 2028 | 7.6 | Growth is expected to decelerate as the market matures and demand stabilises. |
| 2029 | 5.9 | Demand will continue to slow, reflecting normalisation after previous peaks in adoption rates. |
| 2030 | 5.0 | Growth is projected to slow as manufacturers adapt to ongoing technological advancements in automation. |
| 2031 | 5.4 | Demand will rise as new applications for collaborative robots emerge in manufacturing processes. |
| 2032 | 6.6 | Growth is expected to accelerate as the National Robotics Industry Development Plan aims for a 30% increase in production. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Collaborative Robots Market Synopsis
Industrial Collaborative Robots in China are designed to work alongside humans in various applications such as assembly, packaging, and logistics. These robots utilise advanced robotics technology, including sensors and AI, to ensure safety and efficiency. The China Industrial Collaborative Robots Market is expanding due to rising demand from sectors like electronics and automotive. The Guangdong province is a major hub for electronics manufacturing, which drives further adoption. The automotive industry is also expected to increase its collaborative robot usage by 20% by 2024, propelling market growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased demand for automation in manufacturing processes | Driver | High | Lightweight Cobots |
| Growing adoption in logistics and material handling | Driver | High | Mobile Cobots |
| Rising investments in robotics technology | Opportunity | Medium | Medium Duty Cobots |
| Expansion of electronics manufacturing facilities | Opportunity | Medium | Lab & Electronics Assembly |
| High initial investment costs for small businesses | Restraint | High | Heavy Payload Cobots |
| Concerns regarding the integration of AI with existing systems | Restraint | Medium | Medium Duty Cobots |
| Shortage of skilled workforce for operating cobots | Challenge | High | Mobile Cobots |
| Rapid technological advancements leading to obsolescence | Challenge | Medium | Lightweight Cobots |
Evaluation of Drivers in China Industrial Collaborative Robots Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased automation in electronics manufacturing | Lab & Electronics Assembly | The electronics sector accounted for over 30% of total industrial robot usage in 2022, driving demand for cobots. |
| Rising demand in automotive production | Heavy Payload Cobots | The automotive industry is expected to reach a production volume of 30 million vehicles by 2025, increasing cobot usage. |
| Growing logistics operations in warehouses | Mobile Cobots | The Shanghai region has seen a 15% increase in cobot installations in logistics firms, enhancing operational efficiency. |
| Investment in collaborative robotics technology | Medium Duty Cobots | The National Robotics Industry Development Plan aims to increase robot production by 30% by 2025, boosting demand. |
| Focus on safety and efficiency in manufacturing | Lightweight Cobots | The National Standard for Industrial Robots (GB/T 20251-2019) governs safety requirements, encouraging adoption. |
The Industrial Collaborative Robots market in China is expanding as demand from electronics manufacturers, automotive producers, and logistics firms grows. In 2022, the electronics sector accounted for over 30% of total industrial robot usage, driving notable purchases of collaborative robots. The automotive industry is set to adopt 20% more collaborative robots by 2024, further increasing demand. The Shanghai region has experienced a 15% rise in cobot installations in logistics firms, improving productivity. The National Robotics Industry Development Plan aims to boost robot production by 30% by 2025, which will improve supply for manufacturers.
Evaluation of Restraints in China Industrial Collaborative Robots Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High initial investment costs for small businesses | Heavy Payload Cobots | Small manufacturers face challenges in affording the upfront costs associated with implementing cobots, limiting their adoption. |
| Integration challenges with existing systems | Medium Duty Cobots | Concerns about compatibility with current manufacturing systems can delay the adoption of new technologies. |
| Limited skilled workforce for cobot operation | Mobile Cobots | The shortage of trained personnel to operate and maintain collaborative robots can hinder their effective use. |
| Frequent updates in robotics technology | Lightweight Cobots | Rapid advancements can make existing systems outdated, discouraging investment from manufacturers. |
| Regulatory compliance costs for manufacturers | Lab & Electronics Assembly | Meeting safety and operational standards can impose additional costs on manufacturers, affecting their bottom line. |
China Industrial Collaborative Robots Market Challenges
The China Industrial Collaborative Robots market still has to solve a few problems, and the first is skills shortages. Many manufacturers struggle to find workers trained in advanced robotics and automation, which delays cobot integration and reduces productivity for producers. High costs present another challenge; the initial investment in cobots can reach up to 200,000 yuan, making it difficult for smaller firms to adopt these technologies. Intense competition among suppliers leads to price wars, which can compromise quality and safety standards for buyers. Supply chain disruptions can hinder the availability of components, causing delays in production timelines for manufacturers.
Trends in the China Industrial Collaborative Robots Market
Several trends are reshaping the China Industrial Collaborative Robots Market; the most important are set out below.
- Shift in Electronics Manufacturing to Automation: The Guangdong province is increasingly adopting collaborative robots in electronics manufacturing, with over 30% of industrial robot usage. This transition improves efficiency and precision in assembly tasks.
- Growing Adoption of Mobile Cobots in Logistics: Mobile Cobots are becoming essential in logistics, particularly in Shanghai, where installations have increased by 15%. This trend reflects a shift towards automation in material handling.
- Increase in Collaborative Robot Installations: In 2023, a program was launched to enhance automation in manufacturing, targeting a 30% increase in robot production by 2025, significantly impacting the market.
- Expansion of Collaborative Robots in Automotive Industry: The automotive sector is projected to adopt 20% more collaborative robots by 2024, significantly impacting assembly line efficiency and quality control.
Investment Opportunities in the China Industrial Collaborative Robots Market
Several openings in the China Industrial Collaborative Robots Market merit attention from investors.
- Electronics Manufacturers Seeking Automation: Electronics manufacturers in Guangdong are increasingly looking for collaborative robots to improve production efficiency, with over 30% of industrial robot usage in 2022 driving demand for new solutions.
- Logistics Firms Needing Efficient Solutions: Logistics firms in Shanghai are rapidly adopting mobile cobots, reflecting a 15% increase in installations, indicating a strong demand for efficient material handling solutions.
- Automotive Industry Expanding Production: The automotive sector is expected to reach a production volume of 30 million vehicles by 2025, creating opportunities for suppliers of collaborative robots to meet rising production demands.
- Investment in Robotics Technology: With the National Robotics Industry Development Plan targeting a 30% increase in robot production by 2025, there is a substantial investment opportunity for technology providers in this sector.
Government Initiatives in the China Industrial Collaborative Robots Market
The 'Robot Industry Development Plan (2021-2025)' was launched by the Ministry of Industry and Information Technology to boost domestic robotics capabilities. This initiative aims to improve the production and application of collaborative robots across various industries. In 2020, the National Development and Reform Commission initiated the 'Made in China 2025' strategy, focusing on automation in manufacturing sectors to position China as a leader in advanced manufacturing technologies, including robotics. The updated 'Guidelines for the Development of the Robotics Industry' in 2023 further promote the adoption of collaborative robots, ensuring compliance with safety standards and promoting industry growth.
In 2023, substantial funding was allocated to the 'Intelligent Manufacturing Innovation Program', which aims to integrate AI with robotics. This program supports manufacturers in adopting advanced technologies, improving operational efficiency. The National Development and Reform Commission oversees this initiative, ensuring that funding is directed towards projects that enhance automation in key sectors. These efforts are expected to drive the adoption of collaborative robots, benefiting producers and buyers alike.
Future Insight of the China Industrial Collaborative Robots Market
The China Industrial Collaborative Robots market is set for transformation by 2032, driven by several key factors. The National Robotics Industry Development Plan aims to increase robot production by 30% by 2025, which will improve supply for manufacturers. The Ministry of Industry and Information Technology's automation program will further promote cobot adoption across various sectors. The automotive sector's production volume is expected to reach 30 million vehicles by 2025, creating new opportunities for buyers and suppliers in assembly lines.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Robot Type – Lightweight Cobots Dominated, Medium Duty Cobots Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, in 2025, Lightweight Cobots led the robot type split with a 38% share. Lightweight Cobots command the largest market share due to their extensive application in tasks requiring close human-robot collaboration, particularly within the electronics sector. Their widespread adoption in the Guangdong province illustrates their essential role in enhancing productivity and operational efficiency in manufacturing environments. The quickest growth will come from Medium Duty Cobots, forecast to expand at a CAGR of 9.1% between 2026 and 2032. Medium Duty Cobots are experiencing rapid growth as they cater to a variety of manufacturing applications with moderate payloads, driven by the increasing demand for automation solutions. The anticipated rise in automotive production will further accelerate their integration across multiple industries. Suppliers should focus on developing Medium Duty Cobots to capitalise on the growing opportunities in diverse manufacturing applications.
By Payload Range – 15 kg Dominated, Autonomous Navigation Expected to Grow Fastest
15 kg took a 59% share of payload range in 2025, more than any other category. Cobots with a 15 kg payload capacity are preferred for their adaptability in various collaborative tasks, making them suitable for sectors like electronics and automotive. Their established presence in manufacturing highlights their critical contribution to improving operational efficiency. Autonomous Navigation is set to record the highest CAGR in this split, 8.0% over 2026–2032. The Autonomous Navigation segment is rapidly expanding as it allows cobots to autonomously navigate complex environments, significantly increasing their applicability in logistics and manufacturing. This capability is vital for companies seeking to streamline operations and reduce reliance on human labour. Buyers should consider investing in Autonomous Navigation technology to enhance operational efficiency and decrease labour costs.
By Application – Lab & Electronics Assembly Dominated, Logistics Collaboration Expected to Grow Fastest
Lab & Electronics Assembly accounted for a 32% market share by application in 2025. Lab & Electronics Assembly leads the application segment as it is extensively used in electronics manufacturing for precision tasks, reflecting the high demand for accuracy in this sector. The ongoing expansion of electronics production facilities further solidifies its market position. Logistics Collaboration is projected to grow fastest, at a CAGR of 7.7% during 2026–2032. Logistics Collaboration is rapidly growing due to its integral role in improving efficiency within logistics operations, especially with the rise of e-commerce. The 15% increase in cobot installations in logistics firms in Shanghai highlights this trend. Suppliers should prioritise solutions for Logistics Collaboration to meet the increasing demand for efficiency in supply chain operations.
By End User – Electronics Sector Dominated, Warehouse Automation Firms Expected to Grow Fastest
Electronics Sector held a 44% share of the China Industrial Collaborative Robots Market by end user in 2025. The Electronics Sector is the foremost end user of cobots, employing them extensively for assembly and testing processes essential for maintaining production quality. This sector's substantial market share underscores the importance of automation in electronics manufacturing. Over 2026–2032, Warehouse Automation Firms are expected to post the fastest growth, at a CAGR of 8.9%. Warehouse Automation Firms are witnessing the fastest growth as they aim to boost operational efficiency, a key factor in today’s competitive landscape. The push for automation in warehouses aligns with broader trends in logistics and supply chain optimisation. Suppliers must tailor their offerings to meet the specific needs of Warehouse Automation Firms to seize this rapidly expanding market segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Collaborative Robots Market Outlook
- Market Size of China Industrial Collaborative Robots Market, 2025
- Forecast of China Industrial Collaborative Robots Market, 2032
- Historical Data and Forecast of China Industrial Collaborative Robots Revenues & Volume for the Period 2022 - 2032F
- China Industrial Collaborative Robots Market Trend Evolution
- China Industrial Collaborative Robots Market Drivers and Challenges
- China Industrial Collaborative Robots Price Trends
- China Industrial Collaborative Robots Porter's Five Forces
- China Industrial Collaborative Robots Industry Life Cycle
- Historical Data and Forecast of China Industrial Collaborative Robots Market Revenues & Volume By Robot Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Collaborative Robots Market Revenues & Volume By Lightweight Cobots for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Collaborative Robots Market Revenues & Volume By Medium Duty Cobots for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Collaborative Robots Market Revenues & Volume By Heavy Payload Cobots for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Collaborative Robots Market Revenues & Volume By Mobile Cobots for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Collaborative Robots Market Revenues & Volume By Payload Range for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Collaborative Robots Market Revenues & Volume By 5 kg for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Collaborative Robots Market Revenues & Volume By 5 15 kg for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Collaborative Robots Market Revenues & Volume By 15 kg for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Collaborative Robots Market Revenues & Volume By Autonomous Navigation for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Collaborative Robots Market Revenues & Volume By Application for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Collaborative Robots Market Revenues & Volume By Lab & Electronics Assembly for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Collaborative Robots Market Revenues & Volume By Packaging, Sorting for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Collaborative Robots Market Revenues & Volume By Metal Handling for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Collaborative Robots Market Revenues & Volume By Logistics Collaboration for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Collaborative Robots Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Collaborative Robots Market Revenues & Volume By Electronics Sector for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Collaborative Robots Market Revenues & Volume By Consumer Goods Manufacturing for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Collaborative Robots Market Revenues & Volume By Automotive Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Collaborative Robots Market Revenues & Volume By Warehouse Automation Firms for the Period 2022 - 2032F
- China Industrial Collaborative Robots Import Export Trade Statistics
- Market Opportunity Assessment By Robot Type
- Market Opportunity Assessment By Payload Range
- Market Opportunity Assessment By Application
- Market Opportunity Assessment By End User
- China Industrial Collaborative Robots Top Companies Market Share
- China Industrial Collaborative Robots Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Collaborative Robots Company Profiles
- China Industrial Collaborative Robots Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Robot Type
- Lightweight Cobots
- Medium Duty Cobots
- Heavy Payload Cobots
- Mobile Cobots
By Payload Range
- 15 kg
- Autonomous Navigation
By Application
- Lab & Electronics Assembly
- Packaging
- Sorting
- Metal Handling
- Logistics Collaboration
By End User
- Electronics Sector
- Consumer Goods Manufacturing
- Automotive Industry
- Warehouse Automation Firms































