China Industrial Conductors Market Size & Growth Rate
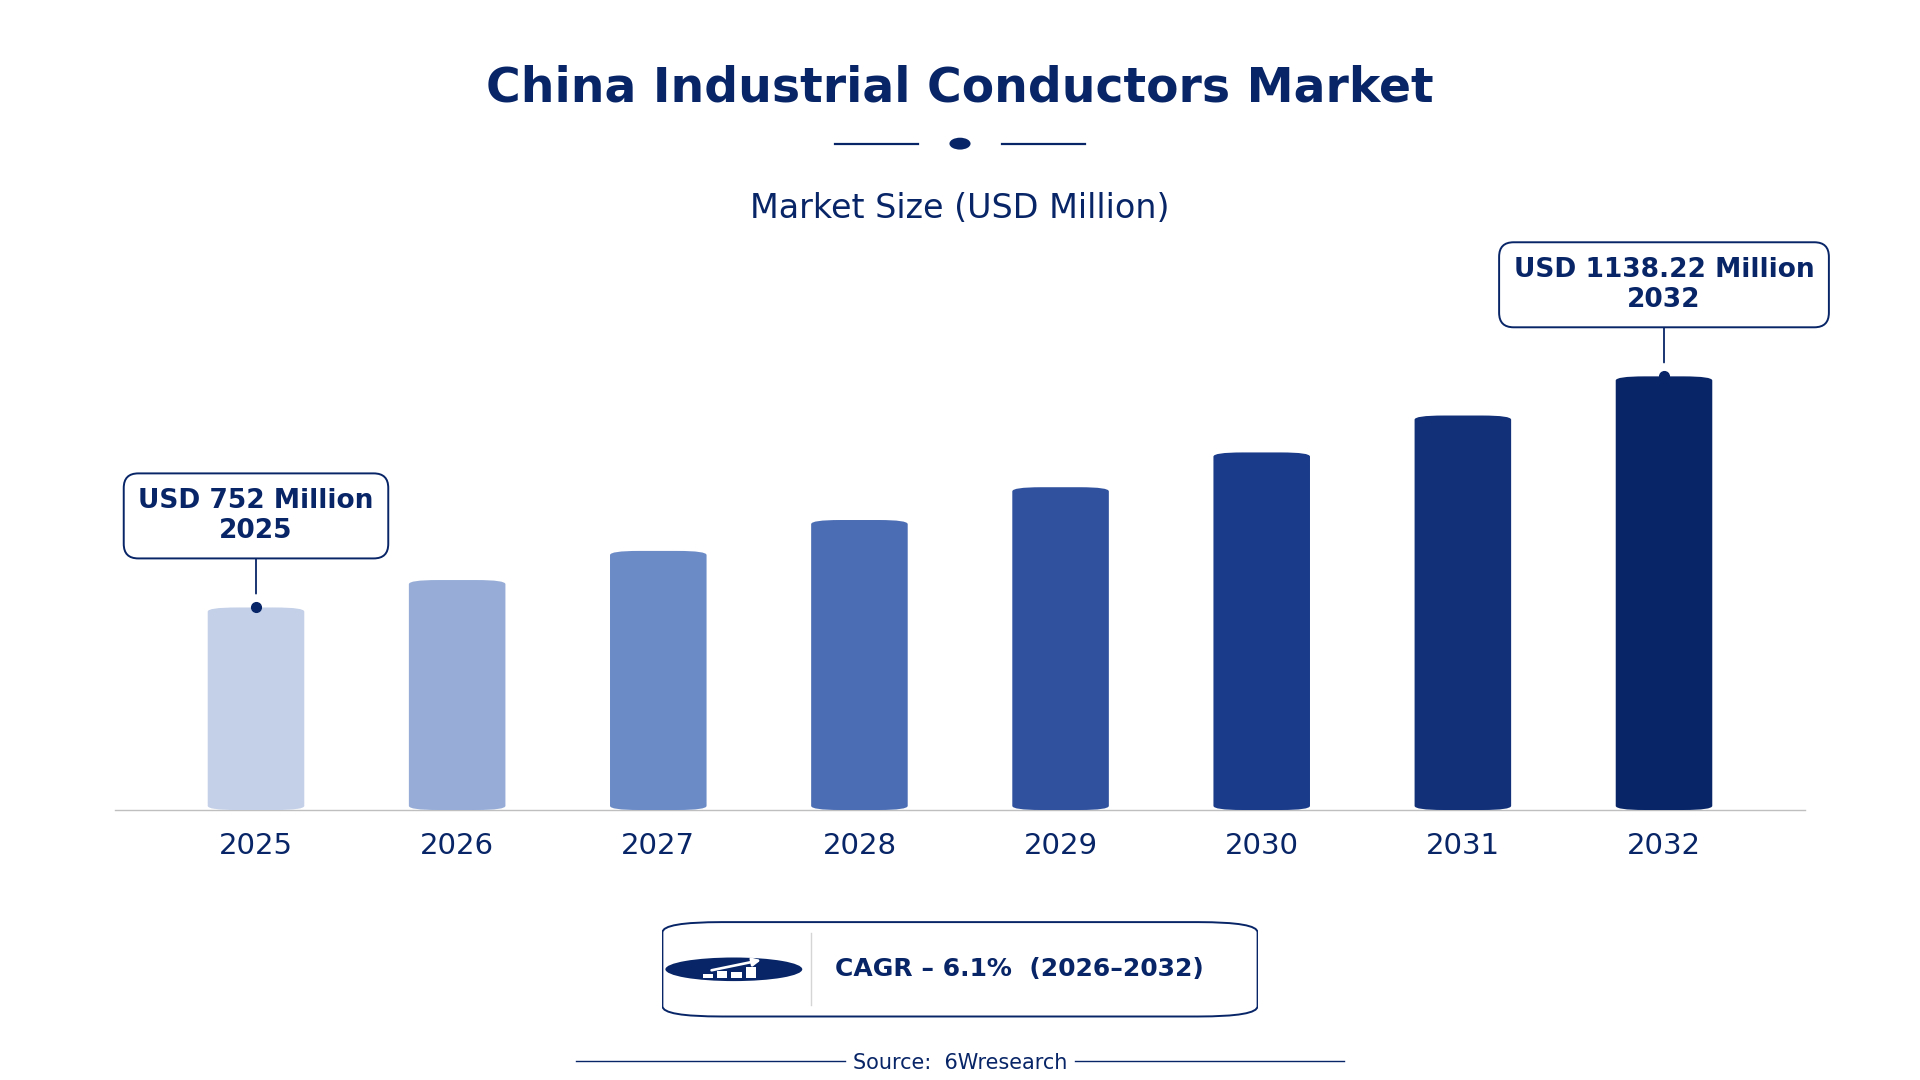
According to 6Wresearch internal database and industry insights, the China Industrial Conductors Market was valued at USD 752.0 million in 2025 and is projected to reach USD 1,138.22 million by 2032, growing at a CAGR of approximately 6.1% during 2026–2032.
China Industrial Conductors Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Conductors Market |
| Market Size 2025 | USD 752.0 million |
| Market Size 2032 | USD 1,138.22 million |
| Absolute Growth 2025–2032 | USD 386.22 million |
| CAGR 2026–2032 | 6.1% |
| Peak Annual Growth | 8.5% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Conductor Material, 2025 | Copper Conductors (46% share) |
| Leading Form Factor, 2025 | Wire/Strip (51% share) |
| Leading Usage Segment, 2025 | Electrical Systems (47% share) |
| Leading End User, 2025 | Power Grid & Cabling Firms (45% share) |
| Fastest-Growing Conductor Material | Aluminum Conductors (8.6% CAGR) |
| Fastest-Growing Form Factor | Busbars (7.6% CAGR) |
| Fastest-Growing Usage Segment | Lightweight Wiring (8.0% CAGR) |
| Fastest-Growing End User | Aerospace & Automotive OEMs (8.5% CAGR) |
| Growing Sector | Electrical Systems |
| Key End Users | Power Grid & Cabling Firms, Aerospace & Automotive OEMs, Utility Installers, Semiconductor Industry |
China Industrial Conductors Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
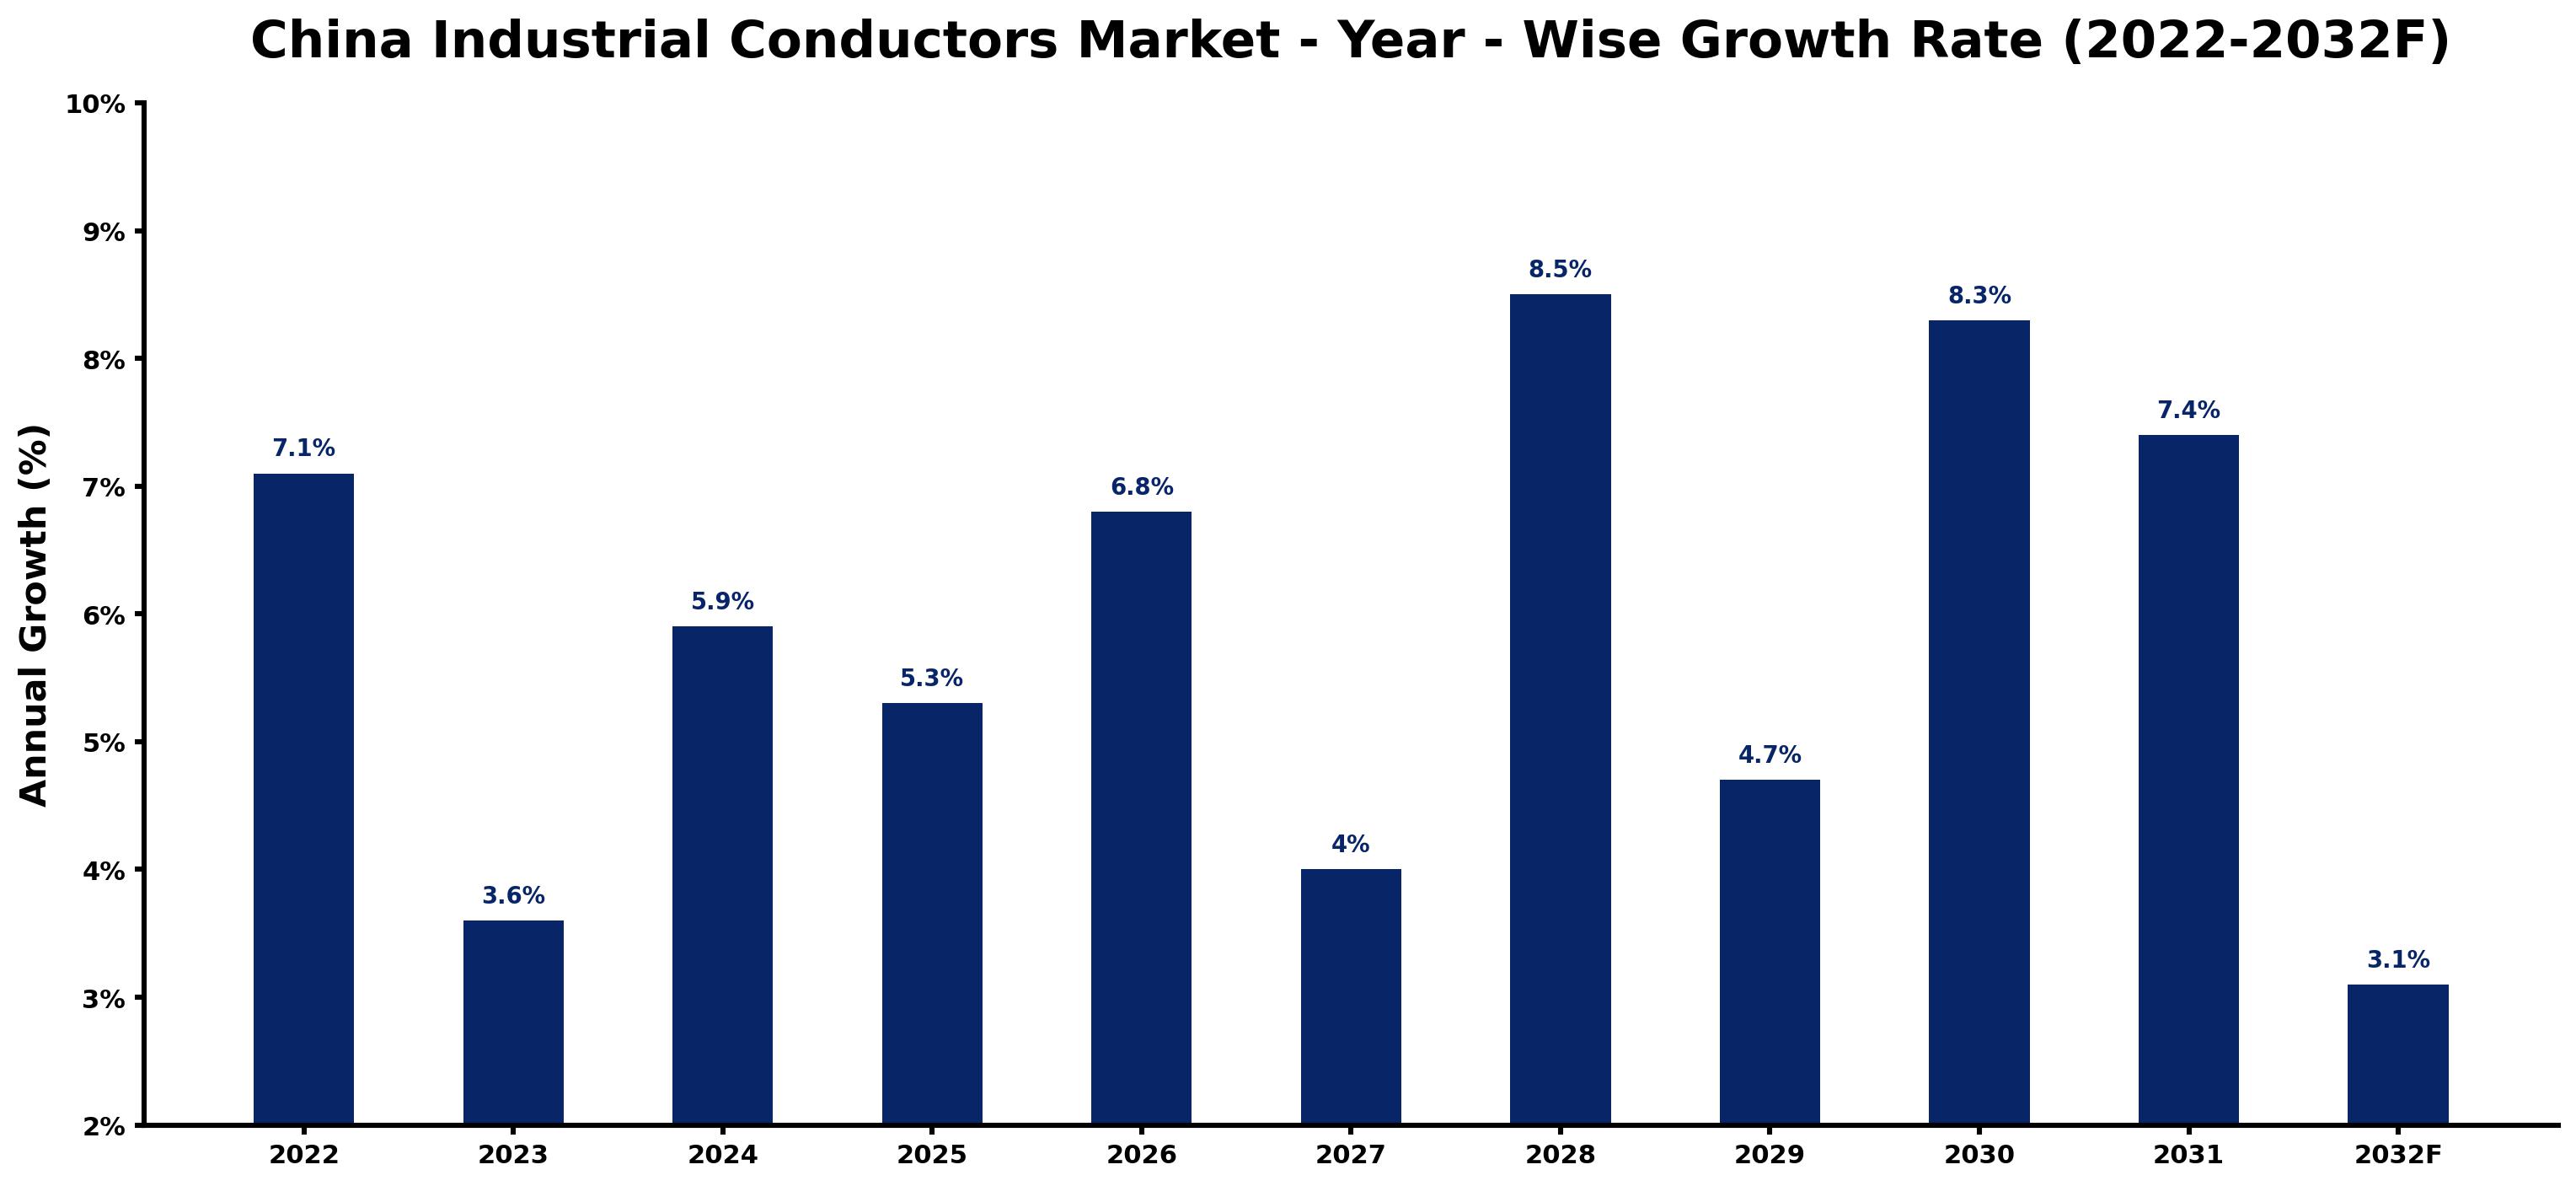
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.1 | The market experienced strong demand from the power grid sector due to infrastructure projects. |
| 2023 | 3.6 | Growth slowed as the semiconductor industry faced supply chain challenges impacting conductor needs. |
| 2024 | 5.9 | Increased investments in renewable energy projects spurred demand for electrical systems. |
| 2025 | 5.3 | A rise in construction activities led to higher requirements for efficient cabling solutions. |
| 2026 | 6.8 | The introduction of new standards for conductor quality is expected to boost buyer confidence and purchases. |
| 2027 | 4.0 | Demand will stabilise as manufacturers adjust to changing buyer preferences and standards. |
| 2028 | 8.5 | A surge in electric vehicle production is projected to create substantial demand for lightweight wiring solutions. |
| 2029 | 4.7 | Growth is expected to slow as market saturation in some segments leads to cautious purchasing decisions. |
| 2030 | 8.3 | The expansion of the semiconductor industry will drive renewed interest in high-purity wiring applications. |
| 2031 | 7.4 | Demand for efficient power distribution systems will continue to grow, but at a slower pace. |
| 2032 | 3.1 | The market is projected to stabilise as investments in infrastructure reach maturity, maintaining steady demand. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Conductors Market Synopsis
Industrial conductors in China are materials used for transmitting electricity, primarily made from metals like copper and aluminum. These conductors are produced through processes such as extrusion and drawing, serving crucial roles in electrical wiring for power distribution. The China Industrial Conductors Market is expanding due to increasing demand from sectors such as power grid and cabling firms, along with advancements in manufacturing technologies. In 2023, the demand for aluminum conductors reached 1 million tons, driven by infrastructure upgrades and the ongoing expansion of the semiconductor industry.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing investments in renewable energy projects are increasing the need for efficient electrical systems. | Driver | High | Electrical Systems |
| The rise of electric vehicles is creating demand for lightweight wiring solutions. | Driver | High | Lightweight Wiring |
| The semiconductor industry's projected growth to $200 billion by 2025 presents significant opportunities for high-purity wiring. | Opportunity | High | High-Purity Wiring |
| The ongoing modernization of power grid infrastructure creates a demand for advanced conductor technologies. | Opportunity | High | Power Grid & Cabling Firms |
| Environmental regulations are increasing production costs for manufacturers of industrial conductors. | Restraint | High | Copper Conductors |
| Market saturation in certain segments is leading to cautious purchasing decisions among buyers. | Restraint | Medium | Aluminum Conductors |
| Supply chain disruptions are causing delays in the availability of raw materials for production. | Challenge | High | Copper Conductors |
| Technological advancements require continuous investment, which can strain smaller manufacturers. | Challenge | Medium | Electrical Systems |
Evaluation of Drivers in China Industrial Conductors Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased investments in renewable energy projects drive demand for efficient electrical systems. | Electrical Systems | China's focus on clean energy has led to substantial infrastructure upgrades. |
| The rise of electric vehicles boosts demand for lightweight wiring solutions. | Lightweight Wiring | The automotive sector's transition to electric models necessitates efficient wiring. |
| The semiconductor industry's growth fuels demand for high-purity wiring applications. | High-Purity Wiring | With over 200 fabrication plants, China's semiconductor sector requires advanced conductors. |
| Modernization of power grid infrastructure increases the need for advanced conductor technologies. | Power Grid & Cabling Firms | Government initiatives aim to improve efficiency and reduce energy loss. |
| Growing construction activities lead to higher requirements for efficient cabling solutions. | Cost-Efficient Cabling | Infrastructure projects across China are driving demand for reliable electrical systems. |
The Industrial Conductors market in China is growing on the back of rising investments in renewable energy, increasing electric vehicle production, and the semiconductor industry's expansion. In 2023, the demand for aluminum conductors reached 1 million tons, driven by infrastructure upgrades. The focus on clean energy has led to substantial upgrades in electrical systems, while the automotive sector's transition to electric models necessitates efficient wiring solutions. China's semiconductor sector, with over 200 fabrication plants, requires advanced conductors, further boosting demand. Ongoing construction activities across the country are increasing requirements for reliable cabling solutions.
Evaluation of Restraints in China Industrial Conductors Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Environmental regulations are increasing production costs for manufacturers of industrial conductors. | Copper Conductors | Compliance with stricter emissions standards raises operational expenses for producers. |
| Market saturation in certain segments is leading to cautious purchasing decisions among buyers. | Aluminum Conductors | Increased competition has made buyers more selective in their sourcing. |
| Supply chain disruptions are causing delays in the availability of raw materials for production. | Copper Conductors | Global supply chain issues have affected the procurement of necessary metals. |
| Technological advancements require continuous investment, which can strain smaller manufacturers. | Electrical Systems | Smaller firms may struggle to keep pace with rapid technological changes. |
| Fluctuations in raw material prices can impact production costs and pricing strategies. | Aluminum Conductors | Volatility in metal markets affects the overall cost structure for producers. |
China Industrial Conductors Market Challenges
The China Industrial Conductors Market still has to solve a few problems, and the first is rising production costs. In 2023, the cost of raw materials surged, causing a 15% increase in prices for producers in the electrical sector. Supply chain disruptions also affect availability, with delays in sourcing metals leading to a 20% slowdown in production timelines for suppliers. Increased competition from foreign manufacturers pressures local producers to cut prices, which can compromise quality for buyers. Buyers also face challenges in adhering to strict quality standards, such as ISO 9001, which can extend project timelines by up to six months if compliance issues arise.
Trends in the China Industrial Conductors Market
Buyers and suppliers in the China Industrial Conductors Market are adjusting to the following trends.
- Shift in Focus to Lightweight Wiring Technologies: The Guangdong province is experiencing a shift towards lightweight wiring technologies, supported by the Aerospace Industry Association of China. In 2023, this sector saw a notable increase in demand, reflecting a growing trend towards efficiency.
- Transition from Copper to Aluminum Conductors: In recent years, the market has seen a transition from copper to aluminum conductors, particularly in overhead power lines. In 2023, aluminum conductors reached a demand of 1 million tons, highlighting this shift.
- Emergence of High-Purity Wiring in Electronics: The Jiangsu province is emerging as a hub for high-purity wiring production, driven by the semiconductor industry's needs. The government has promoted this sector, leading to increased investments in specialized conductor manufacturing.
- Prioritisation of Sustainable Manufacturing Practices: The implementation of the Green Manufacturing Initiative in 2021 has prioritised sustainable practices in conductor production. This initiative aims to reduce emissions and improve environmental impact, aligning with global sustainability trends.
Investment Opportunities in the China Industrial Conductors Market
The following opportunities in the China Industrial Conductors Market pair current demand with a clear way in.
- Power Grid & Cabling Firms: Power grid and cabling firms are actively seeking advanced conductor technologies to improve efficiency. In 2023, the government allocated $10 billion for upgrading power grid infrastructure, creating a notable opportunity for suppliers.
- High-Purity Wiring for Semiconductor Industry: The semiconductor industry requires high-purity wiring, presenting a lucrative opportunity for manufacturers. With projected growth to $200 billion by 2025, suppliers can enter this market through partnerships with local firms.
- Investment in Lightweight Wiring Solutions: Aerospace and automotive OEMs are increasingly investing in lightweight wiring solutions. The growing demand for electric vehicles supports this trend, providing opportunities for manufacturers to develop innovative products.
- Entry into the Electrical Systems Market: The electrical systems market is expanding, driven by infrastructure projects. Suppliers can enter this market by forming joint ventures with local firms or obtaining necessary certifications.
Government Initiatives in the China Industrial Conductors Market
The National Energy Administration launched the 'Power Grid Modernization Plan' in 2022, aiming to improve infrastructure efficiency and reliability. This plan targets a 20% reduction in energy loss by 2025, compelling manufacturers to adapt their products to meet new standards. Additionally, the 'Electronics Industry Development Plan' introduced by the Ministry of Industry and Information Technology in 2021 promotes the use of high-purity wiring in semiconductor manufacturing, encouraging innovation and quality improvements in conductor production.
The Ministry of Industry and Information Technology oversees the approval of new standards for electrical conductors. The 'National Electrical Equipment Standards Improvement Program' approved by the State Council in 2023 aims to update standards by 2025, enhancing the quality and safety of industrial conductors. Furthermore, the National Development and Reform Commission supports investments in the electrical sector, facilitating funding for infrastructure projects that require advanced conductor technologies.
Future Insight of the China Industrial Conductors Market
The China Industrial Conductors Market is poised for substantial changes by 2032, driven by several key factors. The Chinese government allocated $10 billion in 2023 for upgrading power grid infrastructure, which will enhance efficiency and reliability. The semiconductor industry's growth is expected to elevate demand for electrical conductors as it approaches a projected value of $200 billion by 2025. The implementation of the National Standard GB/T 11766 will improve product quality, benefiting both buyers and suppliers by streamlining compliance processes.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Conductor Material – Copper Conductors Dominated, Aluminum Conductors Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, with a 46% revenue share in 2025, Copper Conductors was the largest conductor material category. Copper conductors dominate the market as they are essential for efficient power transmission in electrical systems. With 1.5 million tons produced in 2022, their widespread application across various industries underscores their leading position. Aluminum Conductors are projected to grow fastest, at a CAGR of 8.6% during 2026–2032. Aluminum conductors are experiencing rapid growth due to their cost-effectiveness and lightweight nature, particularly beneficial for overhead power lines. The demand reaching 1 million tons in 2023 indicates a significant shift towards this material. Suppliers should enhance production capabilities for aluminum conductors to meet rising demand and maintain competitiveness.
By Form Factor – Wire/Strip Dominated, Busbars Expected to Grow Fastest
Wire/Strip took a 51% share of form factor in 2025, more than any other category. Wire and strip conductors hold the largest market share as they are vital for general electrical wiring applications across numerous industries. Their versatility and extensive usage solidify their dominant market position. Busbars are set to record the highest CAGR in this split, 7.6% over 2026–2032. Busbars are the fastest-growing segment, driven by their crucial role in power distribution within substations and industrial settings. The increasing need for efficient power management systems is propelling their adoption. Manufacturers should invest in busbar technologies to capitalise on the growing demand for effective power distribution solutions.
By Usage Segment – Electrical Systems Dominated, Lightweight Wiring Expected to Grow Fastest
Electrical Systems held a 47% share of the China Industrial Conductors Market by usage segment in 2025. Electrical systems represent the largest market share, being essential for power generation and distribution across various sectors. Their fundamental importance in maintaining electrical infrastructure ensures consistent demand. Over 2026–2032, Lightweight Wiring is expected to post the fastest growth, at a CAGR of 8.0%. Lightweight wiring is rapidly gaining traction, particularly in the automotive and aerospace industries, where efficiency and weight reduction are critical. This segment's growth aligns with the increasing focus on energy-efficient technologies. Suppliers should prioritise lightweight wiring solutions to align with industry trends and meet the evolving needs of key sectors.
By End User – Power Grid & Cabling Firms Dominated, Aerospace & Automotive OEMs Expected to Grow Fastest
In 2025, Power Grid & Cabling Firms led the end user split with a 45% share. Power grid and cabling firms are the main consumers of industrial conductors, highlighting their critical role in electrical infrastructure. Their extensive operations necessitate a reliable supply of high-quality conductor materials. The quickest growth will come from Aerospace & Automotive OEMs, forecast to expand at a CAGR of 8.5% between 2026 and 2032. Aerospace and automotive OEMs are the fastest-growing end users, driven by the rising demand for lightweight and efficient wiring solutions in their products. This trend is expected to accelerate as these industries emphasise innovation and performance. Suppliers must tailor their offerings to meet the specific needs of aerospace and automotive OEMs to seize emerging market opportunities.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Conductors Market Outlook
- Market Size of China Industrial Conductors Market, 2025
- Forecast of China Industrial Conductors Market, 2032
- Historical Data and Forecast of China Industrial Conductors Revenues & Volume for the Period 2022 - 2032F
- China Industrial Conductors Market Trend Evolution
- China Industrial Conductors Market Drivers and Challenges
- China Industrial Conductors Price Trends
- China Industrial Conductors Porter's Five Forces
- China Industrial Conductors Industry Life Cycle
- Historical Data and Forecast of China Industrial Conductors Market Revenues & Volume By Conductor Material for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Conductors Market Revenues & Volume By Copper Conductors for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Conductors Market Revenues & Volume By Aluminum Conductors for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Conductors Market Revenues & Volume By Silver-Plated Conductors for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Conductors Market Revenues & Volume By Bimetallic Conductors for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Conductors Market Revenues & Volume By Form Factor for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Conductors Market Revenues & Volume By Wire/Strip for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Conductors Market Revenues & Volume By Busbars, Rods for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Conductors Market Revenues & Volume By High-Purity Wiring for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Conductors Market Revenues & Volume By Copper-Clad Aluminum for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Conductors Market Revenues & Volume By Usage Segment for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Conductors Market Revenues & Volume By Electrical Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Conductors Market Revenues & Volume By Lightweight Wiring for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Conductors Market Revenues & Volume By Sensitive Electronics for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Conductors Market Revenues & Volume By Cost-Efficient Cabling for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Conductors Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Conductors Market Revenues & Volume By Power Grid & Cabling Firms for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Conductors Market Revenues & Volume By Aerospace & Automotive OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Conductors Market Revenues & Volume By Semiconductor Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Conductors Market Revenues & Volume By Utility Installers for the Period 2022 - 2032F
- China Industrial Conductors Import Export Trade Statistics
- Market Opportunity Assessment By Conductor Material
- Market Opportunity Assessment By Form Factor
- Market Opportunity Assessment By Usage Segment
- Market Opportunity Assessment By End User
- China Industrial Conductors Top Companies Market Share
- China Industrial Conductors Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Conductors Company Profiles
- China Industrial Conductors Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Conductor Material
- Copper Conductors
- Aluminum Conductors
- Silver-Plated Conductors
- Bimetallic Conductors
By Form Factor
- Wire/Strip
- Busbars
- Rods
- High-Purity Wiring
- Copper-Clad Aluminum
By Usage Segment
- Electrical Systems
- Lightweight Wiring
- Sensitive Electronics
- Cost-Efficient Cabling
By End User
- Power Grid & Cabling Firms
- Aerospace & Automotive OEMs
- Semiconductor Industry
- Utility Installers































