China industrial control components Market Size & Growth Rate
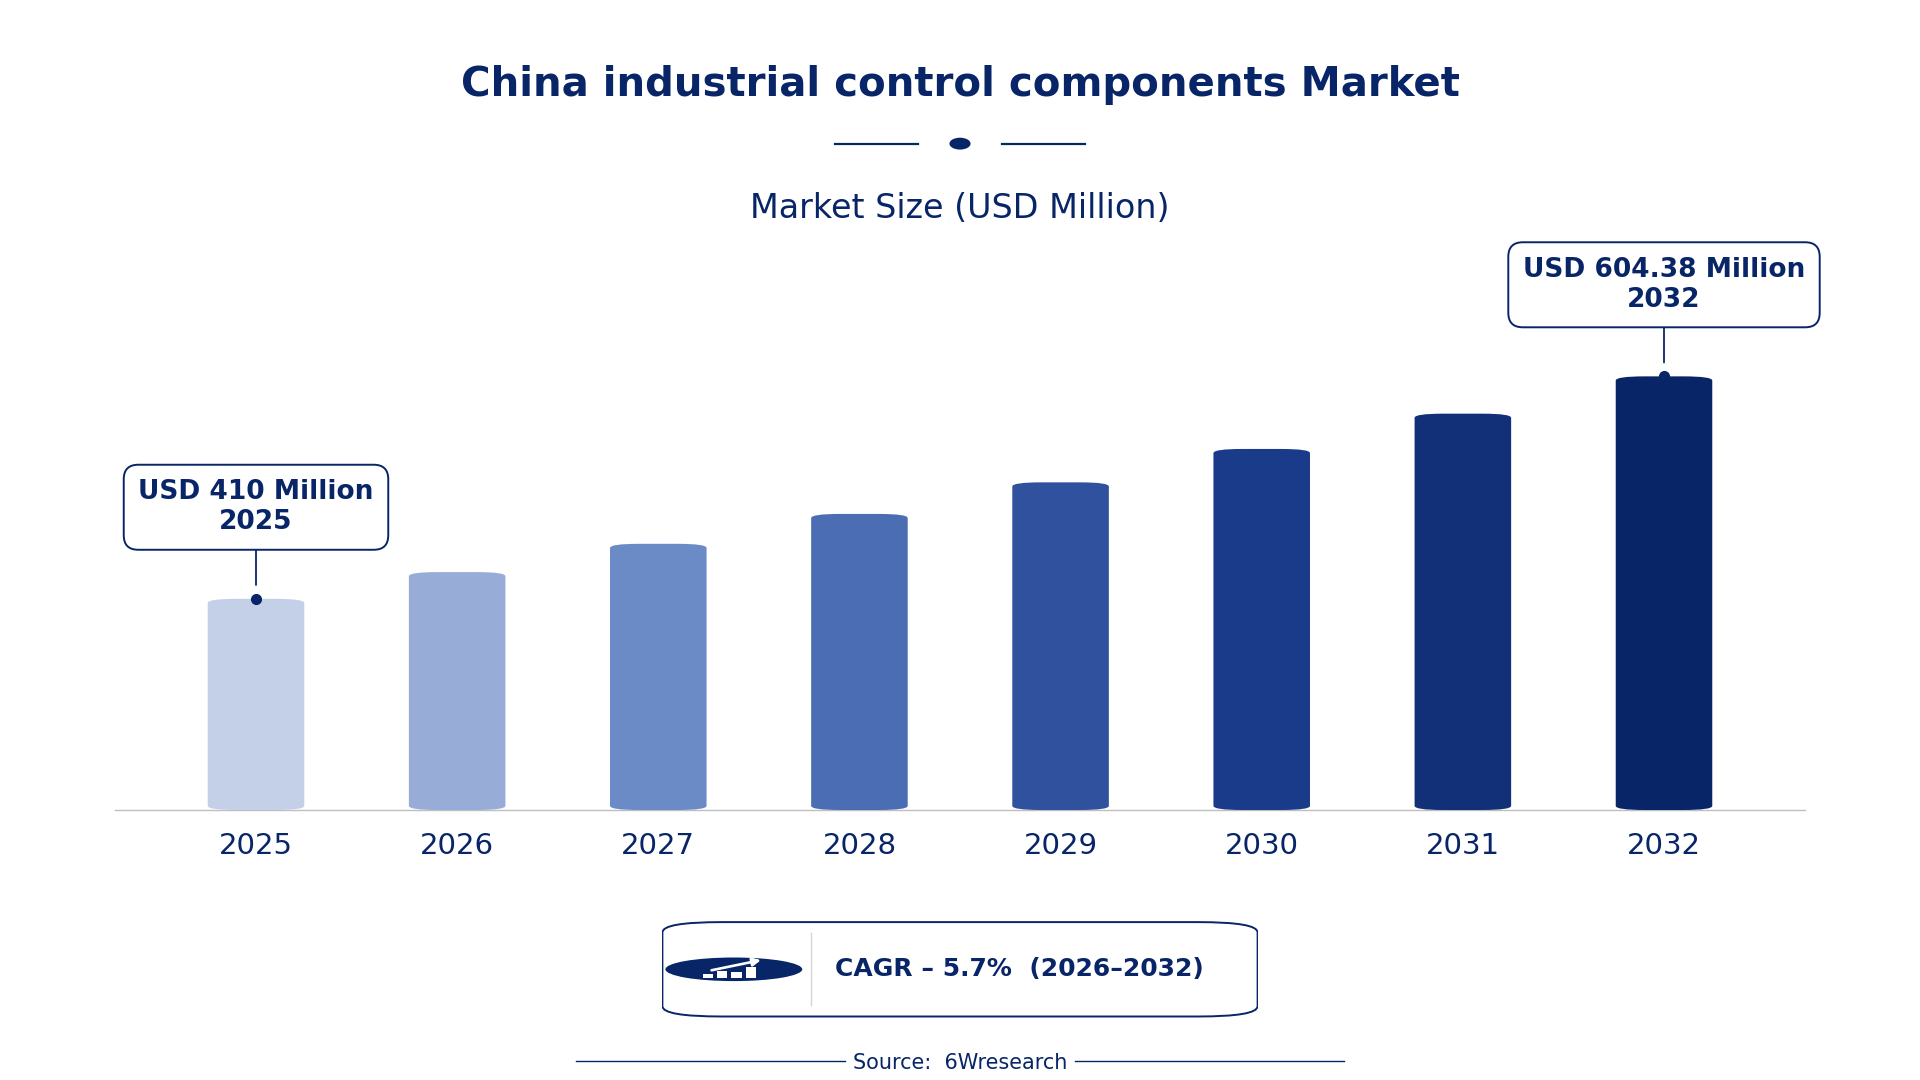
According to 6Wresearch internal database and industry insights, the China industrial control components Market was valued at USD 410.0 million in 2025 and is projected to reach USD 604.38 million by 2032, growing at a CAGR of approximately 5.7% during 2026–2032.
China industrial control components Market Highlights
| Report Metric | Details |
| Report Name | China industrial control components Market |
| Market Size 2025 | USD 410.0 million |
| Market Size 2032 | USD 604.38 million |
| Absolute Growth 2025–2032 | USD 194.38 million |
| CAGR 2026–2032 | 5.7% |
| Peak Annual Growth | 7.8% in 2026 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Component Type, 2025 | Relays (48% share) |
| Leading Function, 2025 | Switching (53% share) |
| Leading Mounting Method, 2025 | DIN Rail (38% share) |
| Leading End User, 2025 | Panel Builders (42% share) |
| Fastest-Growing Component Type | Timers (8.2% CAGR) |
| Fastest-Growing Function | Sequential Control (8.4% CAGR) |
| Fastest-Growing Mounting Method | PCB/Panel (7.5% CAGR) |
| Fastest-Growing End User | Automation OEMs (8.4% CAGR) |
| Growing Sector | automation |
| Key End Users | manufacturers, panel builders, automation OEMs, energy management firms |
China industrial control components Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
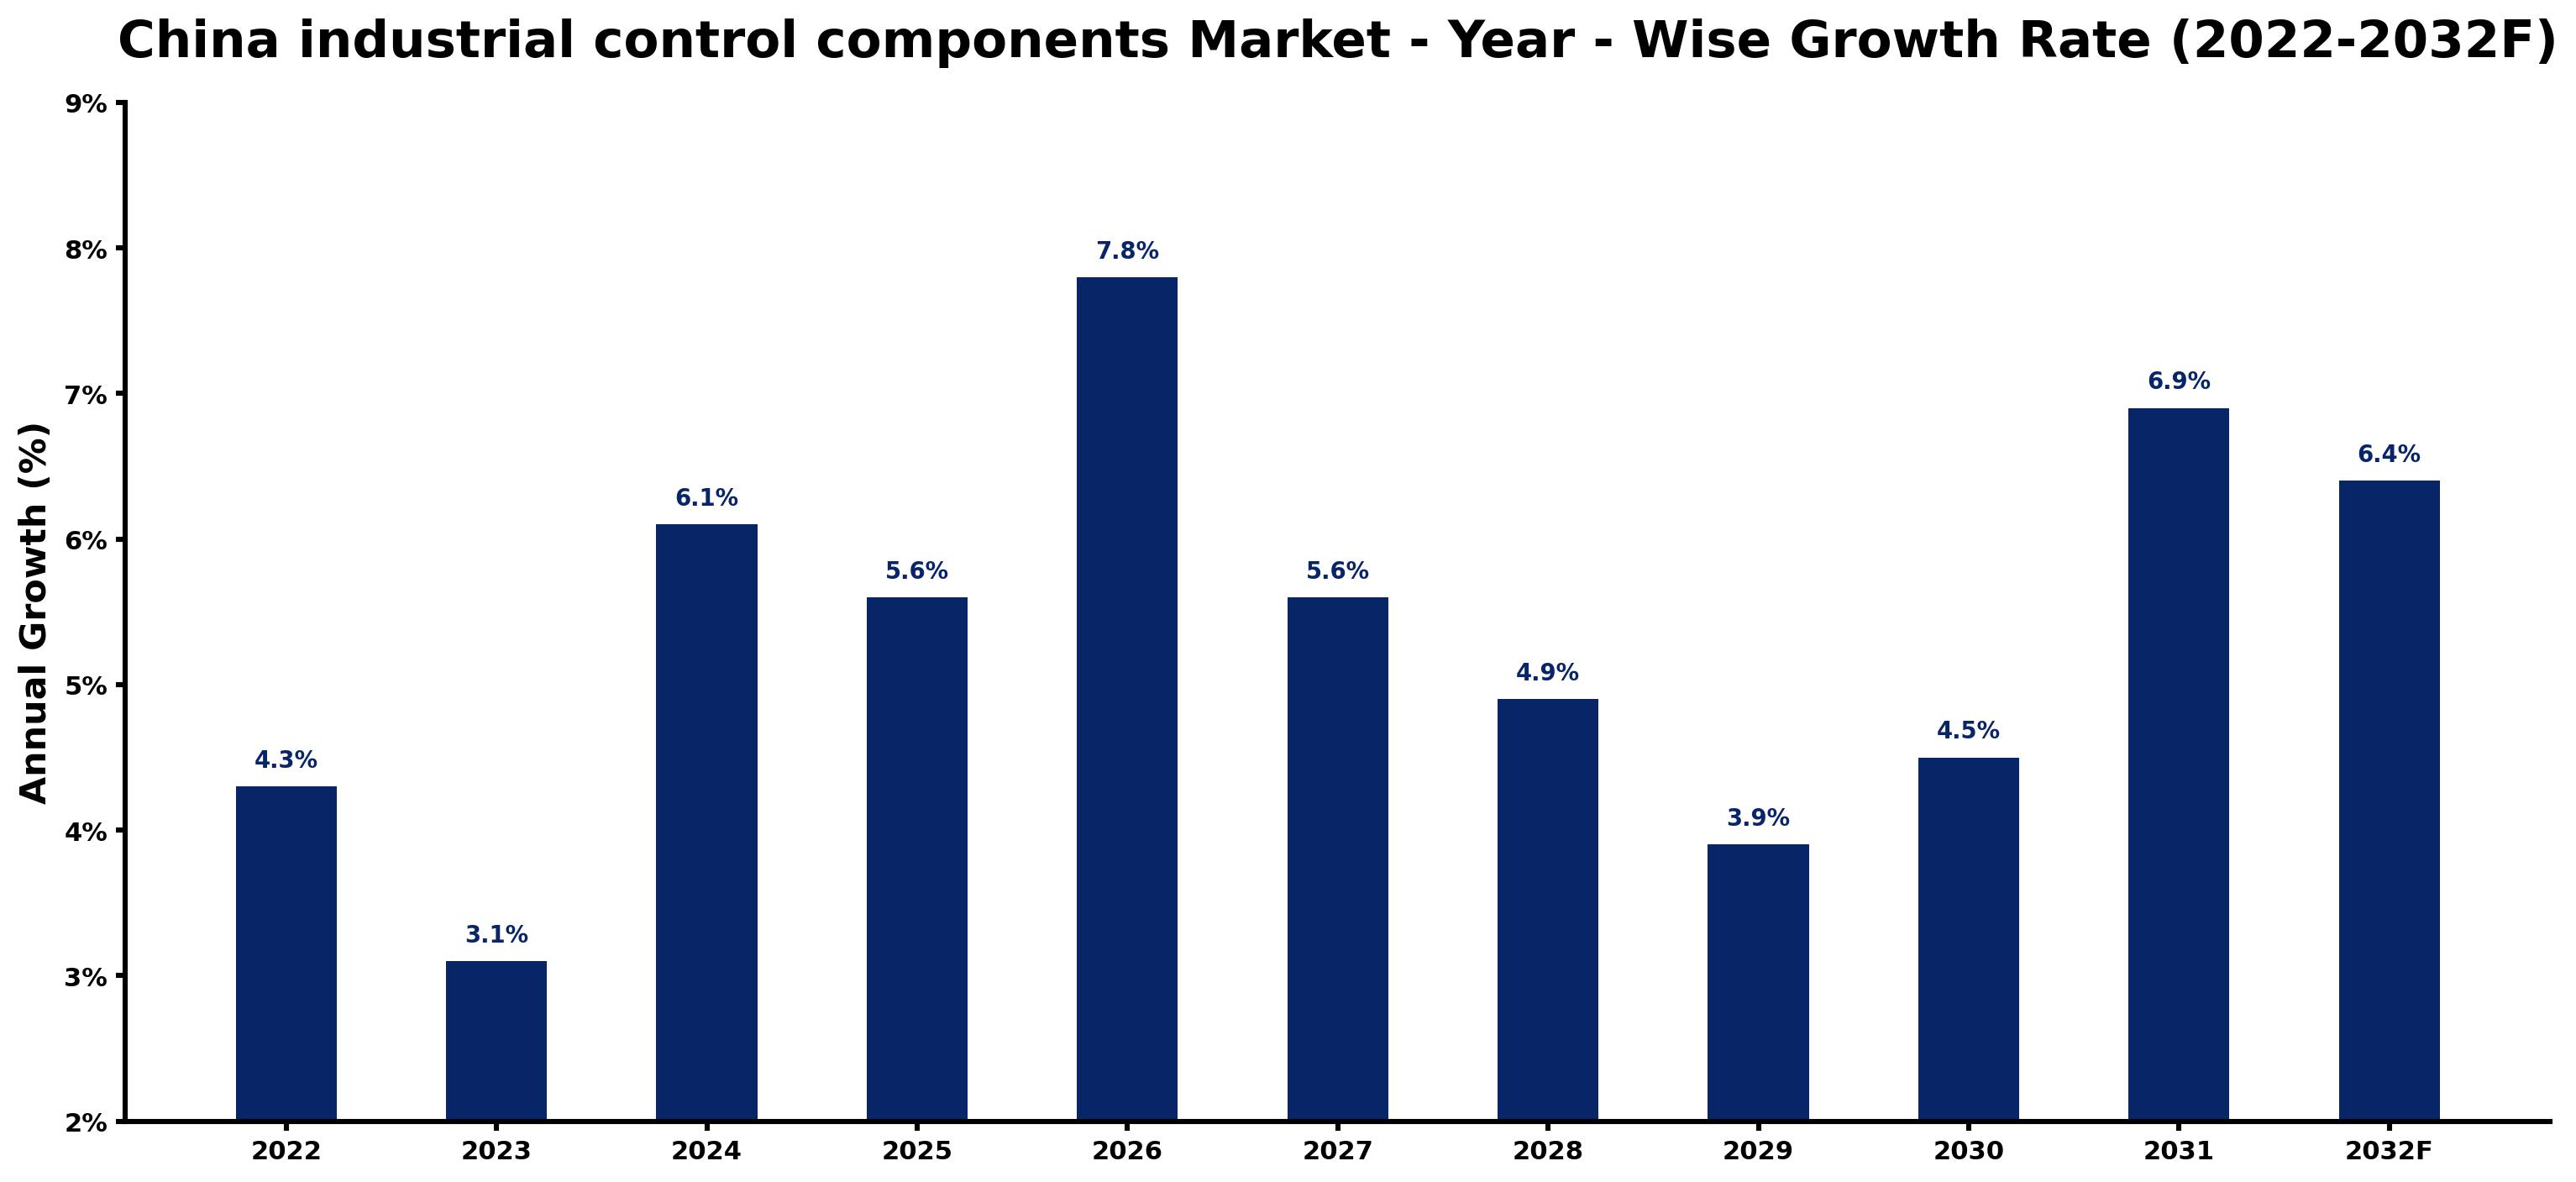
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.3 | The market experienced steady growth, driven by high demand from manufacturing facilities. |
| 2023 | 3.1 | Growth slowed due to adjustments in response to supply chain challenges faced by factories. |
| 2024 | 6.1 | Demand surged as factories ramped up automation efforts under the 'Made in China 2025' initiative. |
| 2025 | 5.6 | Growth slowed again as the market stabilised after rapid expansion in previous years. |
| 2026 | 7.8 | The market is expected to peak as investments in automation technologies accelerate. |
| 2027 | 5.6 | Growth slows as the market adjusts to the high levels of previous years. |
| 2028 | 4.9 | Demand continues to decelerate as the market matures and the installed base increases. |
| 2029 | 3.9 | Growth slows further as the market approaches saturation in key segments like switching. |
| 2030 | 4.5 | Demand is expected to rise again as new technologies emerge and drive investment in automation. |
| 2031 | 6.9 | Growth accelerates as automation becomes integral to more industries, particularly in energy management applications. |
| 2032 | 6.4 | The market continues to grow, albeit at a slower rate as it stabilises after reaching maturity. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China industrial control components Market Synopsis
The industrial control components market in China encompasses essential devices used in automation and control systems. These components, primarily made from metals and plastics, manage machinery and electrical loads. The market is growing due to the thriving industrial sector, with over 30 million manufacturing facilities driving demand. Key initiatives like the 'Made in China 2025' programme and the GB/T 14048 standard are boosting automation and control systems, further increasing investments in this sector.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| High demand from over 30 million manufacturing facilities drives component usage. | Driver | High | Relays |
| The GB/T 14048 standard enhances product reliability and safety, increasing adoption. | Driver | High | Circuit Breakers |
| The installed base of 1.5 million industrial automation systems presents a supply gap. | Opportunity | High | Timers |
| The National Development and Reform Commission's 500 billion CNY investment in automation technologies creates opportunities. | Opportunity | High | Contactors |
| Supply chain disruptions affect timely availability of components. | Restraint | Medium | Switching |
| Competition from international manufacturers may limit market share for local producers. | Restraint | Medium | Protection |
| Technological advancements require continuous investment, posing a financial burden. | Challenge | High | Sequential Control |
| Rapid changes in technology may outpace existing production capabilities. | Challenge | Medium | High Load Switching |
Evaluation of Drivers in China industrial control components Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| High demand from factories for automation solutions increases component sales. | Relays | With over 30 million manufacturing facilities, the need for reliable switching applications drives demand. |
| The GB/T 14048 standard ensures safety and reliability in low-voltage applications. | Circuit Breakers | This standard encourages manufacturers to adopt high-quality components, boosting sales significantly. |
| The installed base of 1.5 million industrial automation systems creates a steady demand for control components. | Timers | As more systems are installed, the need for time-based control increases substantially. |
| The 'Made in China 2025' initiative promotes advanced manufacturing technologies. | Contactors | This initiative encourages investment in automation, leading to higher component demand across sectors. |
| Growing awareness of energy management applications drives the adoption of control components. | Switching | As industries focus on efficiency, the need for effective electrical load management rises. |
Growth in the industrial control components market in China stems from high demand from manufacturing facilities, the rollout of the GB/T 14048 standard, and a rising installed base of automation systems. The flourishing industrial sector, with over 30 million manufacturing facilities, fuels the need for dependable switching applications, particularly relays. The GB/T 14048 standard improves safety and reliability, encouraging manufacturers to invest in quality circuit breakers. In 2022, the installed base of industrial automation systems reached 1.5 million units, generating consistent demand for timers.
Evaluation of Restraints in China industrial control components Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions hinder timely access to essential components. | Switching | Manufacturers face delays in sourcing materials, affecting production schedules and increasing lead times. |
| Intense competition from international players pressures local pricing strategies. | Protection | Local producers may struggle to maintain market share against lower-priced imports, impacting profitability. |
| Technological advancements require continuous investment in R&D. | Sequential Control | Producers must allocate resources to keep up with evolving technologies, straining budgets. |
| Regulatory compliance can increase operational costs for manufacturers. | High Load Switching | Meeting safety standards requires additional investments in testing and certification, raising overall costs. |
| Market saturation in key segments limits growth potential. | Timers | As the market matures, the number of new customers decreases, constraining sales opportunities. |
China industrial control components Market Challenges
The China industrial control components market encounters several practical issues, starting with supply chain disruptions. Concentration of manufacturing in the Yangtze River Delta region leads to lead times extending by as much as 30% for buyers. Fierce competition among local manufacturers drives prices down, squeezing profit margins for suppliers and limiting their capacity to invest in quality improvements. A shortage of skilled workers in automation technology hampers factories from fully utilising advanced control systems, resulting in operational inefficiencies that can cost them 15% in productivity. Rapid technological advancements pose challenges for suppliers who struggle to keep pace, risking product obsolescence within a year of launch.
Trends in the China industrial control components Market
Several trends are reshaping the China industrial control components Market; the most important are set out below.
- Integration of Automation Standards: The GB/T 14048 standard is being widely adopted to ensure safety and reliability in low-voltage applications, with over 1 million units compliant by 2023. This trend encourages manufacturers to improve product quality.
- Rising Demand for Energy Management Solutions: In 2023, the National Development and Reform Commission's investment of 500 billion CNY in automation technologies is driving the adoption of energy-efficient control components. This shift is prompting industries to invest more in automation solutions.
- Shift Towards Modular Control Systems: The Yangtze River Delta region is witnessing a transition to modular control systems, with a 15% increase in modular component sales in 2023. This trend allows for greater flexibility and scalability in industrial applications.
- Growth of Smart Manufacturing Initiatives: The 'Internet Plus' strategy is integrating internet technologies with manufacturing, resulting in a significant increase in demand for smart control components. This trend is reshaping how industries approach automation.
Investment Opportunities in the China industrial control components Market
Investors looking at the China industrial control components Market should consider the following areas.
- 500 billion CNY Investment in Automation: The National Development and Reform Commission's commitment to invest 500 billion CNY in automation technologies creates a strong opportunity for suppliers of industrial control components, particularly in the Yangtze River Delta region.
- Increasing Need for Timers in Automation: With the installed base of automation systems reaching 1.5 million units, there is a growing need for timers. Suppliers can target panel builders to meet this demand effectively.
- Emerging Demand from Automation OEMs: As Automation OEMs expand their product lines, they require more control components. This presents a timely opportunity for manufacturers to partner with these OEMs to supply necessary components.
- Expansion of Energy Management Applications: The focus on energy efficiency is creating a demand gap for switching components. Suppliers can enter this market by offering innovative solutions that cater to energy management needs.
Government Initiatives in the China industrial control components Market
The GB/T 14048 standard for low-voltage switchgear and controlgear, implemented in 2020, mandates compliance for manufacturers, ensuring product safety and reliability. This regulation has led to increased investments in quality control measures among producers, improving overall market standards and benefiting buyers through enhanced product offerings.
The Ministry of Industry and Information Technology oversees the 'Made in China 2025' initiative, which funds projects aimed at advancing automation across various sectors. This initiative supports manufacturers in upgrading their technologies and processes, ultimately benefiting buyers through improved product offerings and increased efficiency.
Future Insight of the China industrial control components Market
By 2032, the industrial control components market in China will undergo significant transformation, primarily driven by the 'Made in China 2025' initiative. This programme will boost automation across various sectors, with the installed base of industrial automation systems projected to exceed 3 million units. The integration of internet technologies through the 'Internet Plus' strategy will further heighten demand for advanced control components. Consequently, buyers will gain access to more efficient solutions, while suppliers must prioritise continuous innovation to remain competitive.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Component Type – Relays Dominated, Timers Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, in 2025, Relays led the component type split with a 48% share. Relays hold the largest market share as they are crucial for switching applications in control systems. Their widespread utilisation in over 30 million manufacturing facilities across China underscores their importance in the industrial automation sector. Timers are set to record the highest CAGR in this split, 8.2% over 2026–2032. Timers are witnessing rapid growth due to their increasing role in time-based control within automation processes, particularly as the installed base of industrial automation systems reached 1.5 million units in 2022. This growth indicates that as automation expands, the demand for timers will likely continue to increase. Suppliers should enhance their relay and timer offerings to effectively address the rising demands of the automation sector.
By Function – Switching Dominated, Sequential Control Expected to Grow Fastest
Switching accounted for a 53% market share by function in 2025. Switching functions dominate the market share as they are fundamental for controlling electrical power in various industrial applications. The implementation of standards like GB/T 14048 for low-voltage switchgear reinforces the reliance on switching components. Sequential Control is projected to grow fastest, at a CAGR of 8.4% during 2026–2032. Sequential Control is the fastest-growing function, driven by the increasing complexity of automation processes that require precise control sequences. The 'Internet Plus' strategy further fuels this growth as it integrates internet technologies into manufacturing. Buyers will benefit from investing in advanced switching and sequential control solutions to optimise their automation processes.
By Mounting Method – DIN Rail Dominated, PCB/Panel Expected to Grow Fastest
With a 38% revenue share in 2025, DIN Rail was the largest mounting method category. DIN Rail mounting commands the largest market share because it serves as the standard method for installing industrial components, providing ease of use and flexibility across various setups. Its prevalent adoption in numerous manufacturing facilities in China reinforces its dominant position in the market. Over 2026–2032, PCB/Panel is expected to post the fastest growth, at a CAGR of 7.5%. PCB/Panel mounting is rapidly gaining traction as it allows for the seamless integration of components into automation systems, meeting the growing demand for compact and efficient designs. This trend aligns with the industry's focus on innovation and efficiency. Suppliers should focus on developing DIN Rail and PCB/Panel solutions to align with market trends and customer preferences.
By End User – Panel Builders Dominated, Automation OEMs Expected to Grow Fastest
Panel Builders took a 42% share of end user in 2025, more than any other category. Panel Builders represent the largest market share as they are the primary users of control components in diverse systems, ensuring consistent demand. Their engagement in various industrial projects guarantees a steady requirement for these components. The quickest growth will come from Automation OEMs, forecast to expand at a CAGR of 8.4% between 2026 and 2032. Automation OEMs are the fastest-growing end user segment, increasingly incorporating control components into their automation solutions, driven by initiatives like 'Made in China 2025' that advocate for enhanced automation. This trend signifies a shift towards more advanced automation technologies. Suppliers must engage with both Panel Builders and Automation OEMs to seize the expanding opportunities within the industrial control components market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China industrial control components Market Outlook
- Market Size of China industrial control components Market, 2025
- Forecast of China industrial control components Market, 2032
- Historical Data and Forecast of China industrial control components Revenues & Volume for the Period 2022 - 2032F
- China industrial control components Market Trend Evolution
- China industrial control components Market Drivers and Challenges
- China industrial control components Price Trends
- China industrial control components Porter's Five Forces
- China industrial control components Industry Life Cycle
- Historical Data and Forecast of China industrial control components Market Revenues & Volume By Component Type for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control components Market Revenues & Volume By Relays for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control components Market Revenues & Volume By Timers for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control components Market Revenues & Volume By Contactors for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control components Market Revenues & Volume By Circuit Breakers for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control components Market Revenues & Volume By Function for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control components Market Revenues & Volume By Switching for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control components Market Revenues & Volume By Sequential Control for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control components Market Revenues & Volume By High Load Switching for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control components Market Revenues & Volume By Protection for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control components Market Revenues & Volume By Mounting Method for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control components Market Revenues & Volume By DIN Rail for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control components Market Revenues & Volume By PCB/Panel for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control components Market Revenues & Volume By Screw-Mounted for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control components Market Revenues & Volume By Enclosed/Standalone for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control components Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control components Market Revenues & Volume By Panel Builders for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control components Market Revenues & Volume By Automation OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control components Market Revenues & Volume By Motor Control Centers for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control components Market Revenues & Volume By Distribution Panels for the Period 2022 - 2032F
- China industrial control components Import Export Trade Statistics
- Market Opportunity Assessment By Component Type
- Market Opportunity Assessment By Function
- Market Opportunity Assessment By Mounting Method
- Market Opportunity Assessment By End User
- China industrial control components Top Companies Market Share
- China industrial control components Competitive Benchmarking By Technical and Operational Parameters
- China industrial control components Company Profiles
- China industrial control components Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Component Type
- Relays
- Timers
- Contactors
- Circuit Breakers
By Function
- Switching
- Sequential Control
- High Load Switching
- Protection
By Mounting Method
- DIN Rail
- PCB/Panel
- Screw-Mounted
- Enclosed/Standalone
By End User
- Panel Builders
- Automation OEMs
- Motor Control Centers
- Distribution Panels































