China industrial control software Market Size & Growth Rate
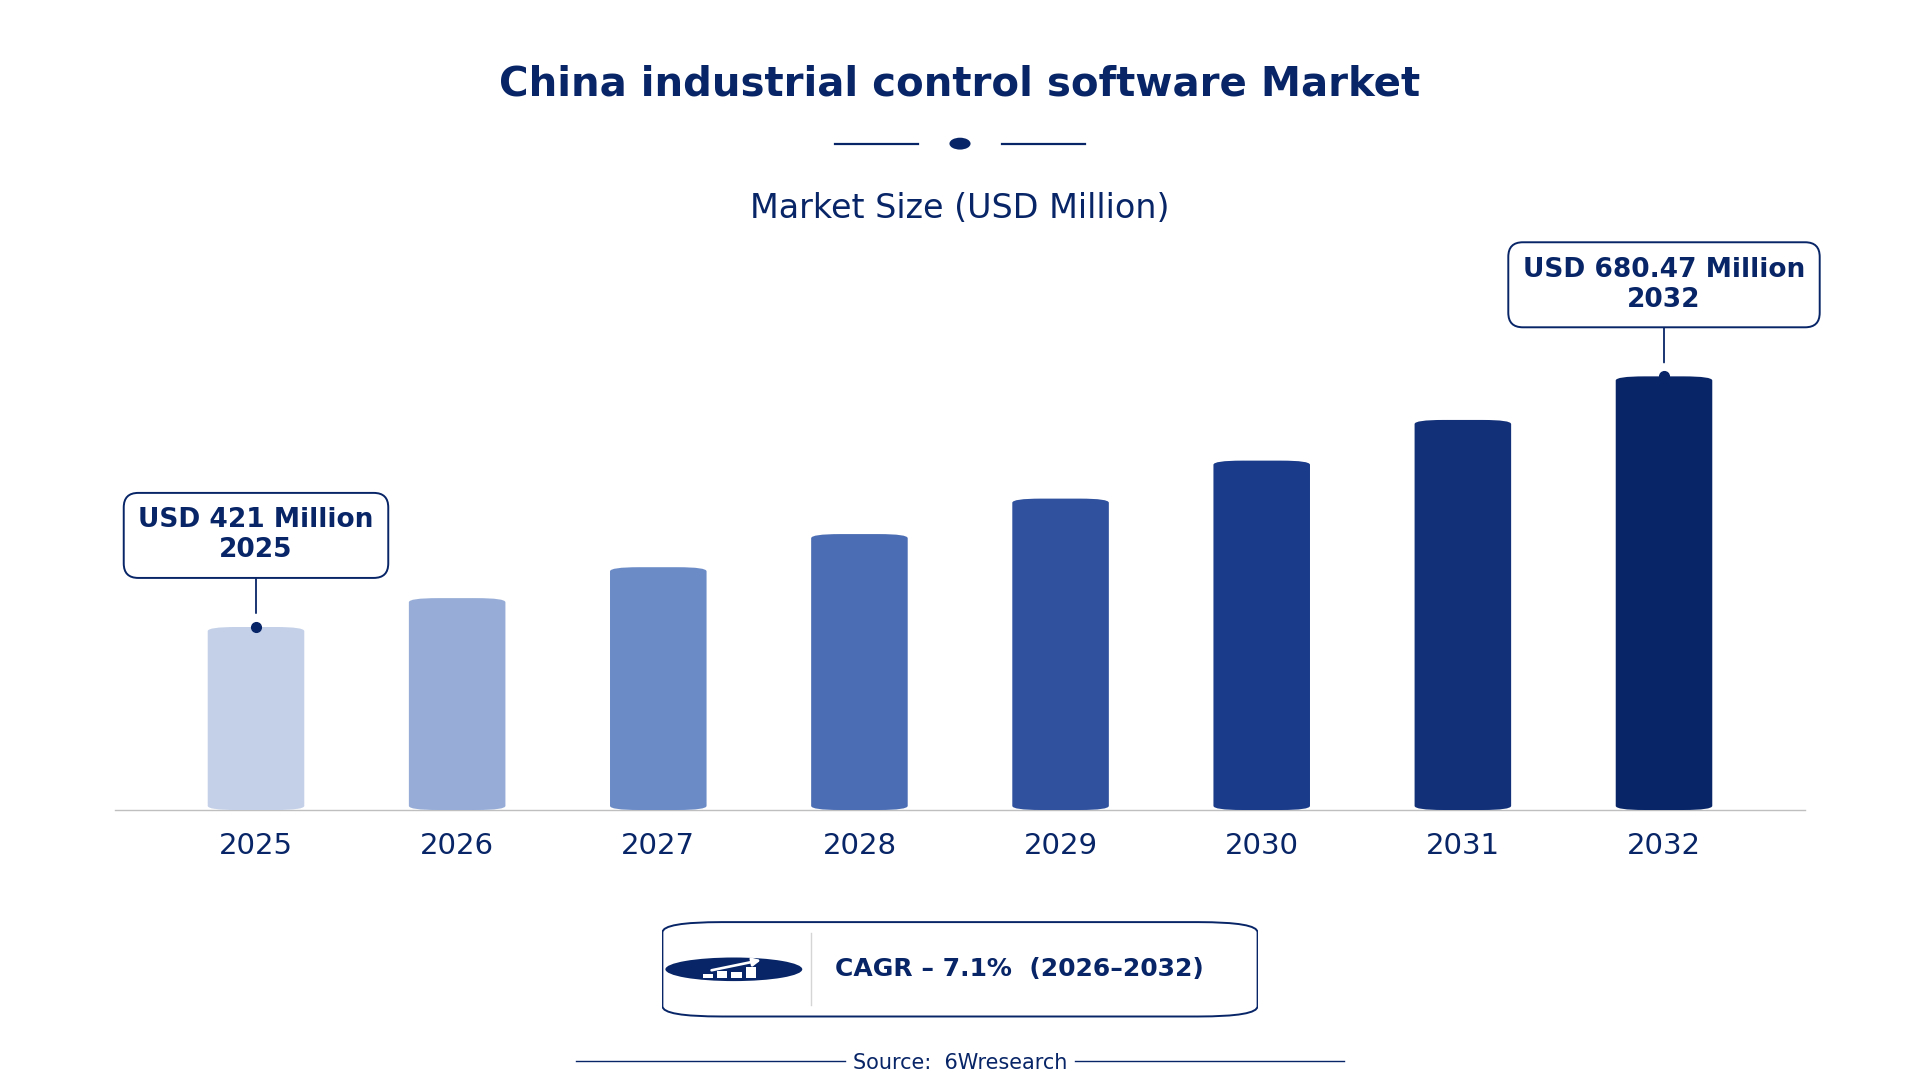
According to 6Wresearch internal database and industry insights, the China industrial control software Market was valued at USD 421.0 million in 2025 and is projected to reach USD 680.47 million by 2032, growing at a CAGR of approximately 7.1% during 2026–2032.
China industrial control software Market Highlights
| Report Metric | Details |
| Report Name | China industrial control software Market |
| Market Size 2025 | USD 421.0 million |
| Market Size 2032 | USD 680.47 million |
| Absolute Growth 2025–2032 | USD 259.47 million |
| CAGR 2026–2032 | 7.1% |
| Peak Annual Growth | 9.6% in 2026 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Software Type, 2025 | SCADA Software (41% share) |
| Leading Platform Support, 2025 | Windows/Linux (46% share) |
| Leading Feature Set, 2025 | Real-Time Monitoring (40% share) |
| Leading End User, 2025 | Utility & Process Plants (46% share) |
| Fastest-Growing Software Type | Industrial Middleware (9.4% CAGR) |
| Fastest-Growing Platform Support | Cross-Platform (9.7% CAGR) |
| Fastest-Growing Feature Set | UI Visualization (8.8% CAGR) |
| Fastest-Growing End User | System Integrators (8.7% CAGR) |
| Growing Sector | Manufacturing |
| Key End Users | Utility & Process Plants, Machine Builders, System Integrators |
China industrial control software Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
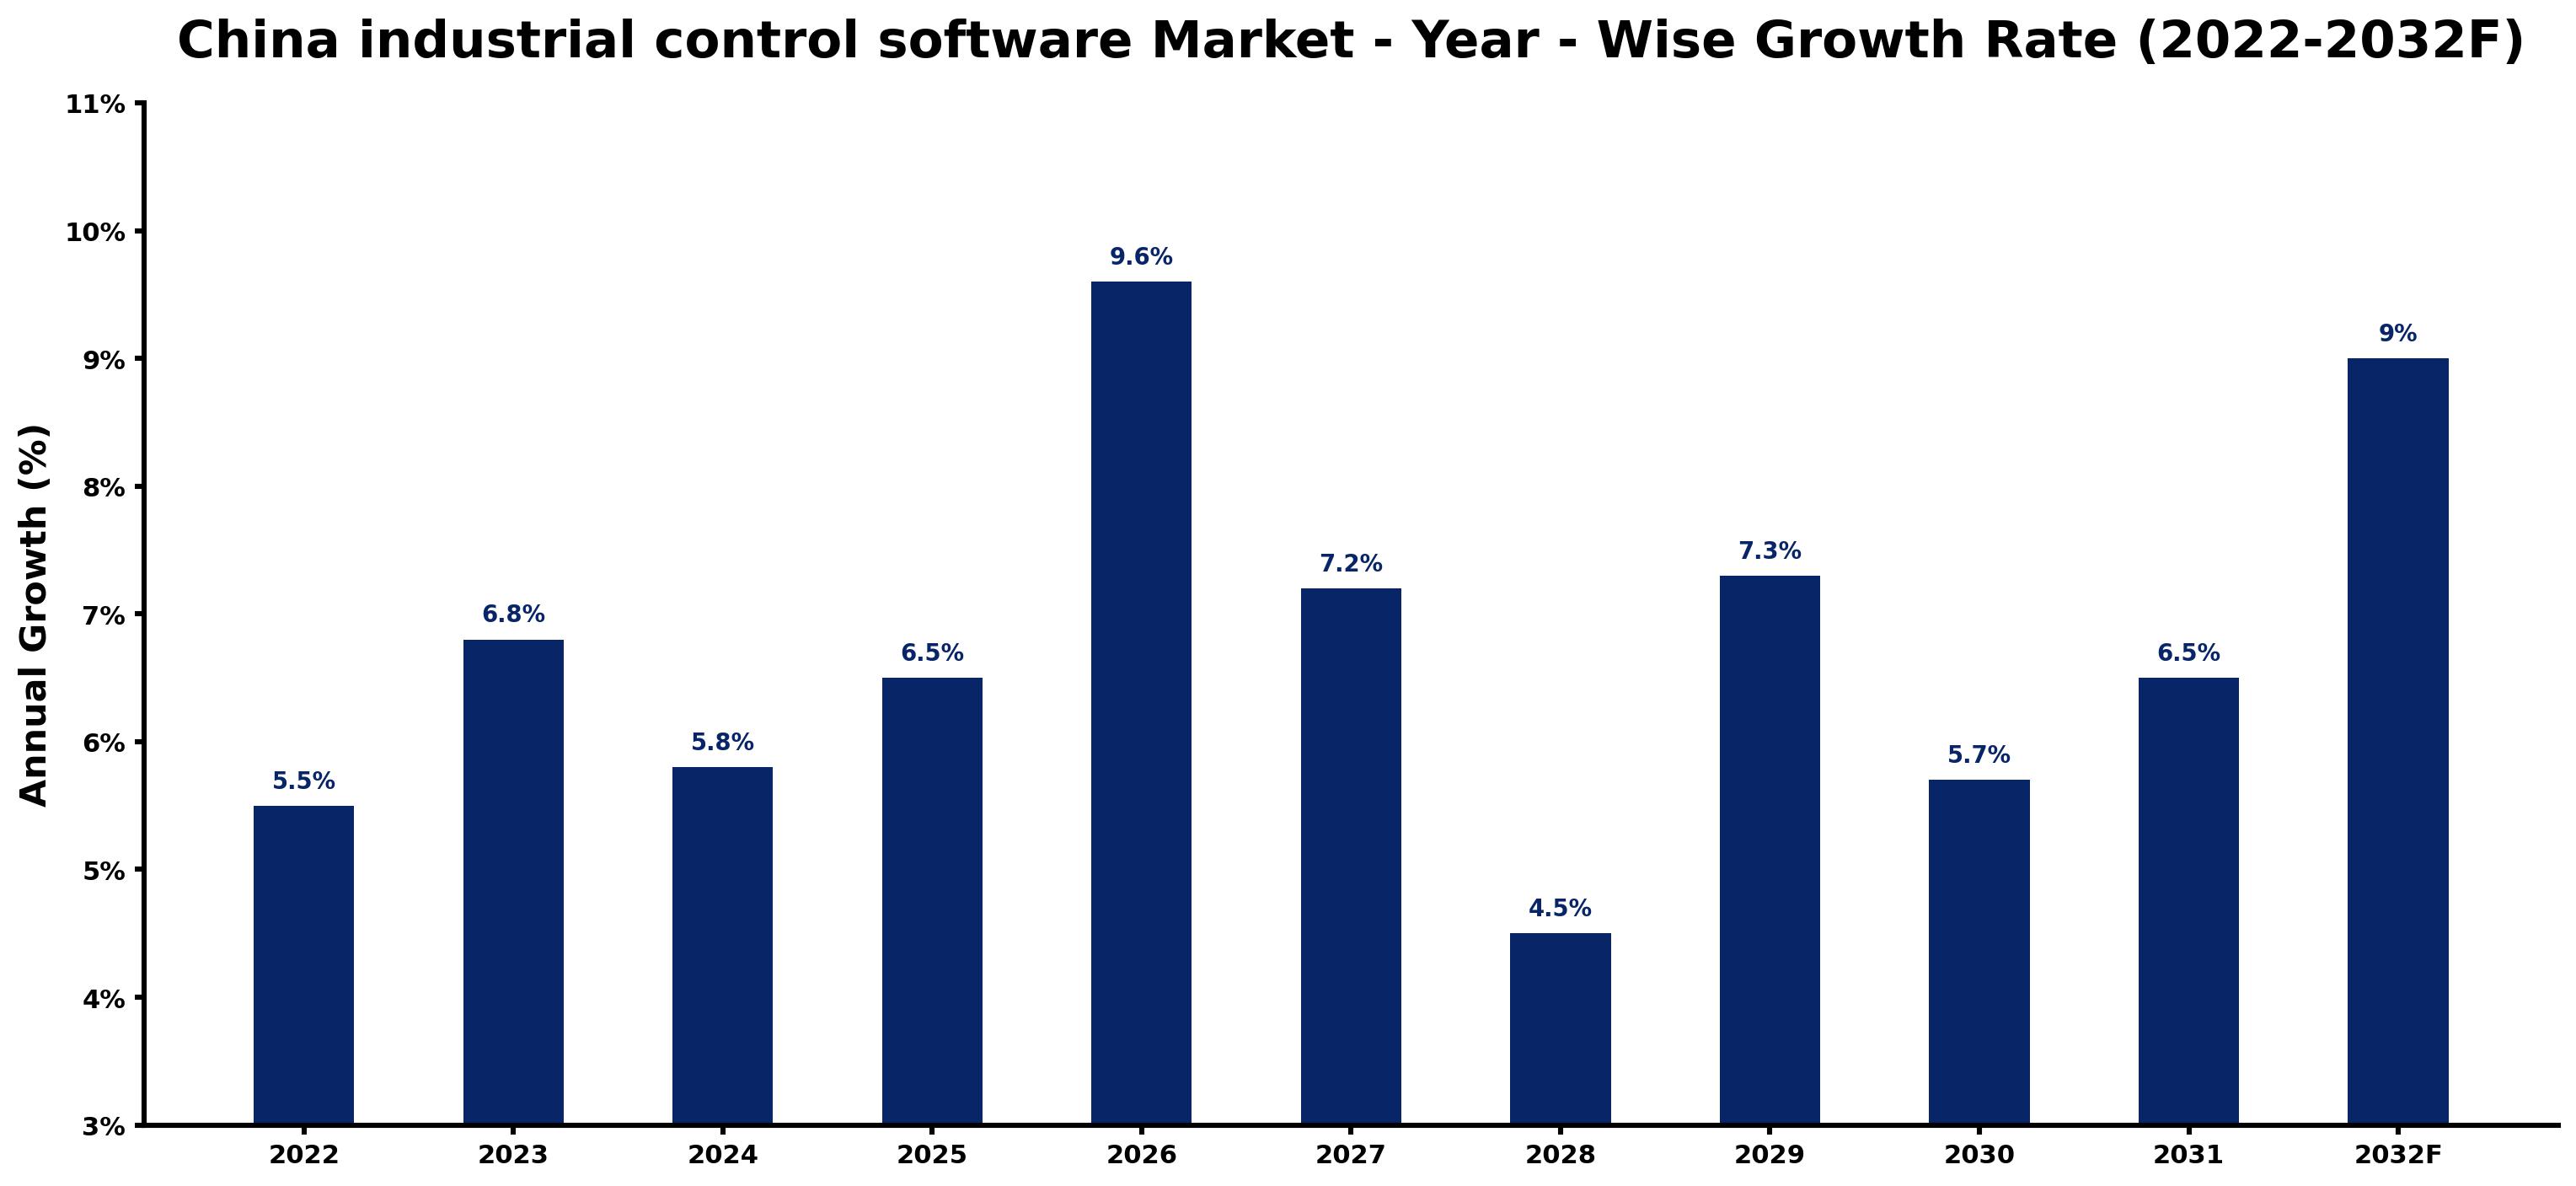
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.5 | The market experienced steady growth due to increased automation in various sectors. |
| 2023 | 6.8 | Demand surged as industries sought to improve operational efficiency through automation. |
| 2024 | 5.8 | Growth slowed as companies adjusted to previous investments in automation technologies. |
| 2025 | 6.5 | A renewed focus on smart manufacturing initiatives spurred further investment in control software. |
| 2026 | 9.6 | The market peaked as the government set ambitious automation targets under its initiatives. |
| 2027 | 7.2 | Growth decelerated as market participants began to consolidate their gains from earlier investments. |
| 2028 | 4.5 | A further slowdown occurred as market dynamics shifted towards mature technologies. |
| 2029 | 7.3 | Demand rebounded as new applications for industrial control software emerged in smart manufacturing. |
| 2030 | 5.7 | Growth slowed again as market saturation began to affect new software adoption. |
| 2031 | 6.5 | An uptick in demand occurred as industries focused on upgrading existing systems. |
| 2032 | 9.0 | The market is projected to grow as cybersecurity measures enhance confidence in software adoption. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China industrial control software Market Synopsis
Industrial control software in China encompasses solutions that monitor and control industrial processes, developed for automation and real-time monitoring. In 2021, the market was valued at approximately 10 billion USD, reflecting a strong demand for automation across various sectors. The growth of this market is driven by initiatives like the Made in China 2025 programme, aiming to boost automation in manufacturing by 30% by 2025. Additionally, the rising number of registered system integrators supports increased demand for these software solutions.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing investment in automation technologies is driving demand for SCADA Software. | Driver | High | SCADA Software |
| The growing need for real-time monitoring in manufacturing processes boosts demand for HMI Software. | Driver | High | HMI Software |
| The rise of IoT applications in manufacturing creates opportunities for Industrial Middleware. | Opportunity | High | Industrial Middleware |
| The government's subsidy programme for SMEs to adopt automation technologies opens new markets for PLC Programming Tools. | Opportunity | High | PLC Programming Tools |
| Challenges in cybersecurity measures may hinder the adoption of Industrial Middleware. | Restraint | Medium | Industrial Middleware |
| The complexity of integrating new software with existing systems can slow down HMI Software adoption. | Restraint | Medium | HMI Software |
| The industrial control software market in China faces significant cybersecurity challenges. | Challenge | High | Industrial Middleware |
| The high cost of advanced automation technologies can limit access for smaller manufacturers. | Challenge | Medium | PLC Programming Tools |
Evaluation of Drivers in China industrial control software Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Investment in automation technologies | PLC Programming Tools | This investment drives demand as manufacturers seek advanced programming solutions, with the installed base of PLCs reaching 1.5 million units by the end of 2022. |
| Government initiatives promoting automation | SCADA Software | The Made in China 2025 initiative aims to increase automation in manufacturing by 30% by 2025, boosting demand for SCADA systems in various sectors. |
| Rising adoption of IoT applications | Industrial Middleware | The increasing integration of IoT in manufacturing creates a demand for middleware solutions, enhancing connectivity and operational efficiency. |
| Growing number of system integrators | HMI Software | With over 1,000 registered system integrators, the demand for HMI software is increasing as they implement user interfaces for operators in diverse industries. |
| Focus on real-time monitoring | Real-Time Monitoring | The critical need for real-time monitoring in sectors like chemical manufacturing drives demand for software solutions that ensure operational efficiency and safety. |
The industrial control software market in China is expanding as investment in automation technologies, coupled with increasing end-use demand, drives growth. The installed base of PLCs reached 1.5 million units by the end of 2022, prompting manufacturers to seek advanced control solutions. The average investment in automation technologies per manufacturing plant is around 2 million CNY, indicating strong spending in this area. As industries adopt IoT applications, the need for industrial middleware solutions is rising, creating new opportunities for software providers.
Evaluation of Restraints in China industrial control software Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Cybersecurity challenges hinder the adoption of Industrial Middleware. | Industrial Middleware | In 2023, a new initiative was introduced to improve cybersecurity measures in industrial control systems, impacting adoption rates. |
| Integration complexities can slow down HMI Software adoption. | HMI Software | Over 1,000 registered system integrators in China specialize in industrial automation solutions, affecting deployment timelines. |
| High costs associated with advanced automation technologies limit access for smaller manufacturers. | PLC Programming Tools | The average investment in automation technologies per manufacturing plant is around 2 million CNY, posing a barrier for smaller firms. |
| Regulatory compliance requirements can delay the deployment of SCADA Software. | SCADA Software | The National Standard GB/T 12345 specifies requirements for industrial control systems in China, complicating implementation. |
| Limited awareness of the benefits of automation can restrict market growth for Industrial Middleware. | Industrial Middleware | The population of industrial control software users in China is estimated to be over 100,000 enterprises, indicating a need for education. |
China industrial control software Market Challenges
In China, the industrial control software market encounters a cost challenge, as producers typically invest around 2 million CNY per manufacturing plant on automation technologies, limiting their capacity to expand. Regulatory compliance with the National Standard GB/T 12345 causes delays for over 1,000 system integrators, affecting their project timelines and ability to meet client needs. Competition from local firms intensifies, as they provide lower-priced alternatives, compelling established suppliers to reduce margins and profitability. Buyers struggle to keep pace with rapidly evolving technologies, leading to inefficiencies that can result in lost automation opportunities.
Trends in the China industrial control software Market
Four trends stand out in the China industrial control software Market.
- Shift Towards Smart Manufacturing: China is increasingly adopting smart manufacturing practices, guided by the Smart Manufacturing Development Plan launched in 2022 with a budget of 1 billion CNY. This shift is leading to higher demand for advanced industrial control software solutions, particularly in manufacturing sectors.
- Rise of Cross-Platform Solutions: Cross-platform industrial control software is gaining traction in China, especially among industries with diverse IT environments. By 2026, the growth rate for Cross-Platform solutions is projected to reach 9.7%, indicating a shift in deployment strategies across various sectors.
- Increased Focus on Cybersecurity: The introduction of enhanced cybersecurity measures for industrial control systems in 2023 reflects a growing concern for security in automation. This trend is anticipated to drive demand for compliant software solutions, ensuring safer operational environments.
- Emphasis on Real-Time Monitoring: Real-time monitoring capabilities are becoming essential in various sectors, particularly in chemical manufacturing. The demand for Real-Time Monitoring software is critical, with significant applications noted in Guangdong province, ensuring operational efficiency.
Investment Opportunities in the China industrial control software Market
Some of the investment opportunities in the China industrial control software Market are mentioned below.
- Partnerships with System Integrators: Collaborating with system integrators can facilitate entry into the industrial control software market. The average investment in automation technologies per manufacturing plant is around 2 million CNY, indicating a promising market for suppliers looking to partner with local experts.
- Supply of Industrial Middleware Solutions: With the rise of IoT applications in manufacturing, there is a growing need for Industrial Middleware solutions. The demand for such solutions is increasing, particularly among system integrators in China, who are seeking to improve connectivity.
- Investment in Real-Time Monitoring Technologies: The market for Real-Time Monitoring software is expanding, especially in the chemical manufacturing sector. This sector is critical, with real-time monitoring features being essential for operational efficiency and safety compliance.
- Focus on HMI Software for Food Processing: The food and beverage processing sector in Jiangsu province presents an opportunity for HMI software suppliers. This sector's extensive use of HMI software indicates a strong demand for user-friendly interfaces, improving operational management.
Government Initiatives in the China industrial control software Market
The regulatory framework for industrial control software in China has evolved in recent years. The National Development and Reform Commission approved the 'Industrial Internet Innovation and Development Strategy' in 2021, aimed at enhancing digital transformation across industries. Following this, the Ministry of Industry and Information Technology introduced the 'Guidelines for the Development of Industrial Software' in 2020, which supports the growth of domestic software solutions. Additionally, the 'Regulations on the Safety of Industrial Control Systems' implemented by the State Administration for Market Regulation in 2021 focus on improving cybersecurity measures in industrial control systems, ensuring safer operations for manufacturers.
In 2022, the Ministry of Industry and Information Technology launched the 'Smart Manufacturing Development Plan' with a budget of 1 billion CNY to promote automation technologies. This plan aims to support manufacturers in adopting advanced technologies. The Ministry of Science and Technology initiated the 'National Key Research and Development Program' in 2023, focusing on advanced manufacturing technologies, including industrial control software. These initiatives are essential for ensuring that producers meet the evolving demands of the market while enhancing their technological capabilities.
Future Insight of the China industrial control software Market
Several forward-looking factors should support the industrial control software market in China over the coming years. The government's smart manufacturing initiative, backed by a 500 million CNY technology upgrade fund, will drive demand for advanced software solutions. By 2025, the installed base of SCADA systems in utility companies is expected to exceed 20,000 installations, enhancing operational efficiency. Increasing focus on cybersecurity measures will build user trust, while the rise of IoT applications will encourage the adoption of versatile software solutions across diverse industries.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Software Type – SCADA Software Dominated, Industrial Middleware Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, SCADA Software took a 41% share of software type in 2025, more than any other category. SCADA software holds the largest market share in the China industrial control software market due to its essential role in real-time monitoring and control, particularly in the oil and gas sector. Its extensive use in Xinjiang and Sichuan provinces exemplifies its importance for operational efficiency in critical industries. Industrial Middleware is projected to grow fastest, at a CAGR of 9.4% during 2026–2032. Industrial middleware is rapidly growing, driven by the increasing demand for seamless integration of diverse software and hardware systems, especially with the rise of IoT applications in manufacturing. The expected increase in SCADA installations, projected to surpass 20,000 by 2025, highlights the need for advanced middleware solutions. Suppliers should focus on developing middleware solutions to address the growing integration needs of industrial users.
By Platform Support – Windows/Linux Dominated, Cross-Platform Expected to Grow Fastest
Windows/Linux accounted for a 46% market share by platform support in 2025. Windows/Linux platforms dominate the market share for industrial control software because they are the most common operating systems used for running these applications in various industries. Their widespread adoption ensures compatibility and reliability, making them the preferred choice for many enterprises. Cross-Platform is set to record the highest CAGR in this split, 9.7% over 2026–2032. Cross-platform support is the fastest-growing segment, as it allows flexibility in deployment across different systems, catering to diverse IT environments in Chinese industries. This trend is driven by the need for adaptable solutions that can function seamlessly across various platforms. Buyers should consider cross-platform solutions to ensure compatibility with existing systems and to future-proof their investments.
By Feature Set – Real-Time Monitoring Dominated, UI Visualization Expected to Grow Fastest
With a 40% revenue share in 2025, Real-Time Monitoring was the largest feature set category. Real-time monitoring features dominate the market as they are crucial for maintaining operational efficiency and safety in industrial processes. This is especially vital in sectors such as chemical manufacturing, where timely data is necessary for effective decision-making. The quickest growth will come from UI Visualization, forecast to expand at a CAGR of 8.8% between 2026 and 2032. UI visualization is the fastest-growing feature set because it significantly enhances user interaction with control systems, enabling operators to manage complex processes more effectively. The increasing complexity of industrial environments drives the demand for advanced visualisation tools. Suppliers must prioritise the development of user-friendly visualisation tools to meet the changing needs of operators.
By End User – Utility & Process Plants Dominated, System Integrators Expected to Grow Fastest
Utility & Process Plants held a 46% share of the China industrial control software Market by end user in 2025. Utility and process plants represent the largest user group of industrial control software, relying heavily on these solutions for effective operational management. Their significant investments in automation technologies underscore their critical role in the market. Over 2026–2032, System Integrators are expected to post the fastest growth, at a CAGR of 8.7%. System integrators are the fastest-growing end-user segment, as they play a vital role in integrating various systems using industrial control software, particularly in the context of smart manufacturing initiatives. Their growth is supported by government programs that encourage the adoption of automation technologies. Suppliers should collaborate with system integrators to expand their market reach and tailor offerings to meet integration demands.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China industrial control software Market Outlook
- Market Size of China industrial control software Market, 2025
- Forecast of China industrial control software Market, 2032
- Historical Data and Forecast of China industrial control software Revenues & Volume for the Period 2022 - 2032F
- China industrial control software Market Trend Evolution
- China industrial control software Market Drivers and Challenges
- China industrial control software Price Trends
- China industrial control software Porter's Five Forces
- China industrial control software Industry Life Cycle
- Historical Data and Forecast of China industrial control software Market Revenues & Volume By Software Type for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control software Market Revenues & Volume By SCADA Software for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control software Market Revenues & Volume By HMI Software for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control software Market Revenues & Volume By PLC Programming Tools for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control software Market Revenues & Volume By Industrial Middleware for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control software Market Revenues & Volume By Platform Support for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control software Market Revenues & Volume By Windows/Linux for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control software Market Revenues & Volume By Cross-Platform for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control software Market Revenues & Volume By IEC 61131 Languages for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control software Market Revenues & Volume By API-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control software Market Revenues & Volume By Feature Set for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control software Market Revenues & Volume By Real-Time Monitoring for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control software Market Revenues & Volume By UI Visualization for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control software Market Revenues & Volume By Ladder/FBD/C Codes for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control software Market Revenues & Volume By Device Interfacing for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control software Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control software Market Revenues & Volume By Utility & Process Plants for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control software Market Revenues & Volume By Machine Builders for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control software Market Revenues & Volume By System Integrators for the Period 2022 - 2032F
- Historical Data and Forecast of China industrial control software Market Revenues & Volume By IoT Control Systems for the Period 2022 - 2032F
- China industrial control software Import Export Trade Statistics
- Market Opportunity Assessment By Software Type
- Market Opportunity Assessment By Platform Support
- Market Opportunity Assessment By Feature Set
- Market Opportunity Assessment By End User
- China industrial control software Top Companies Market Share
- China industrial control software Competitive Benchmarking By Technical and Operational Parameters
- China industrial control software Company Profiles
- China industrial control software Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Software Type
- SCADA Software
- HMI Software
- PLC Programming Tools
- Industrial Middleware
By Platform Support
- Windows/Linux
- Cross-Platform
- IEC 61131 Languages
- API-Based
By Feature Set
- Real-Time Monitoring
- UI Visualization
- Ladder/FBD/C Codes
- Device Interfacing
By End User
- Utility & Process Plants
- Machine Builders
- System Integrators
- IoT Control Systems































