China Industrial Drives Market Size & Growth Rate
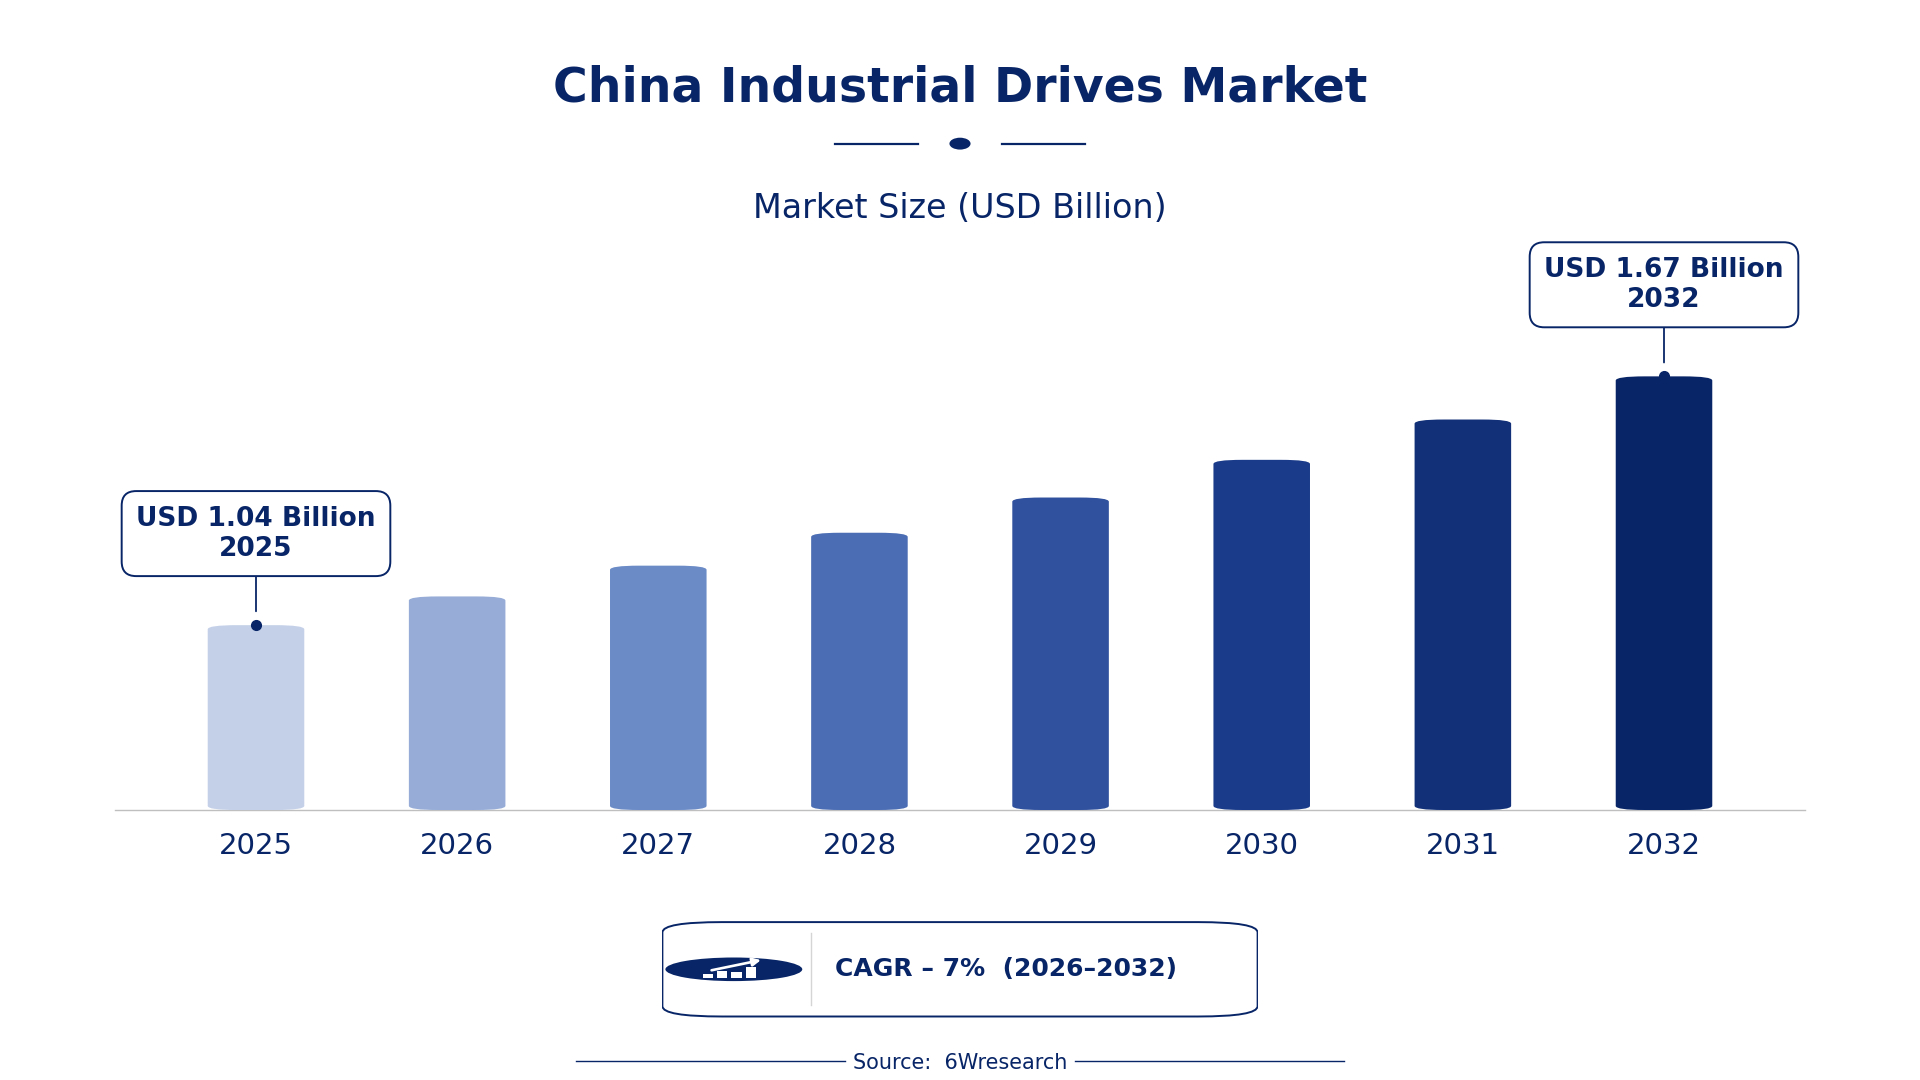
According to 6Wresearch internal database and industry insights, the China Industrial Drives Market was valued at USD 1.04 billion in 2025 and is projected to reach USD 1.67 billion by 2032, growing at a CAGR of approximately 7% during 2026–2032.
China Industrial Drives Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Drives Market |
| Market Size 2025 | USD 1.04 billion |
| Market Size 2032 | USD 1.67 billion |
| Absolute Growth 2025–2032 | USD 0.63 billion |
| CAGR 2026–2032 | 7% |
| Peak Annual Growth | 8.4% in 2030 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Drive Type, 2025 | Variable Frequency Drives (44% share) |
| Leading Motor Control, 2025 | Speed Regulation (43% share) |
| Leading Voltage Rating, 2025 | Low/Medium Voltage (43% share) |
| Leading End User, 2025 | Conveyor Systems (52% share) |
| Fastest-Growing Drive Type | Servo Drives (8.6% CAGR) |
| Fastest-Growing Motor Control | Precision Control (8.3% CAGR) |
| Fastest-Growing Voltage Rating | High Torque (9.3% CAGR) |
| Fastest-Growing End User | Robotics Equipment (8.7% CAGR) |
| Growing Sector | Robotics Equipment |
| Key End Users | Conveyor Systems, Robotics Equipment, Pump & Fan Systems, Printing & Textile |
China Industrial Drives Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
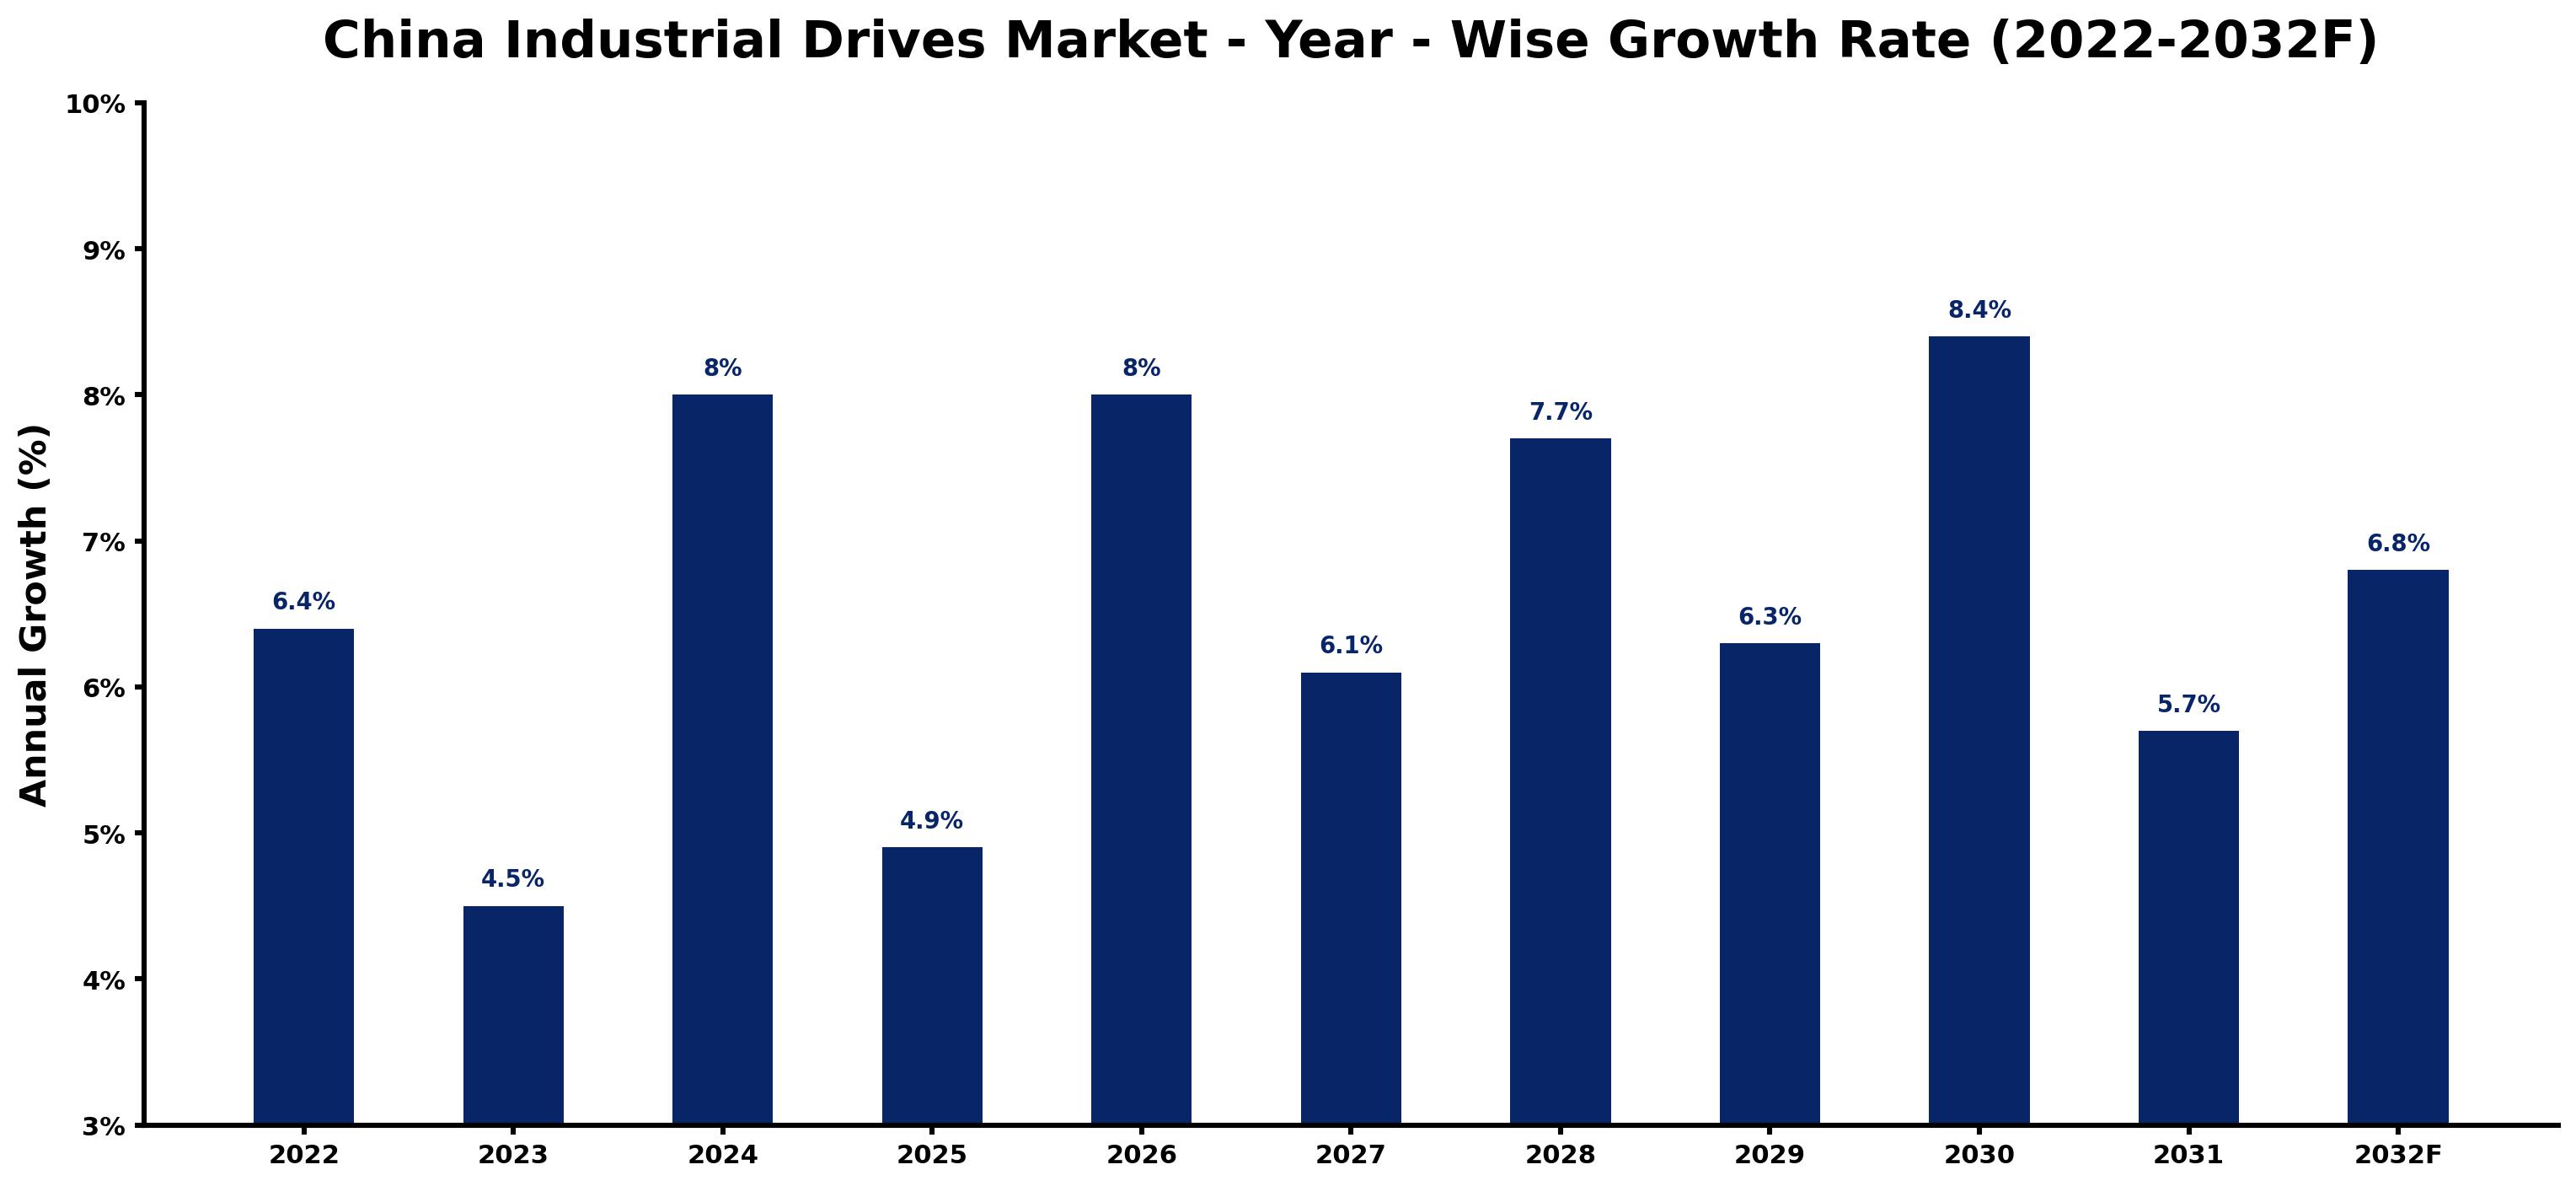
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.4 | The market showed steady growth due to strong domestic manufacturing activity. |
| 2023 | 4.5 | Growth slowed as the market adjusted to previous high levels of investment in automation technologies. |
| 2024 | 8.0 | Demand surged as the automotive sector embraced advanced manufacturing practices and automation. |
| 2025 | 4.9 | Growth slowed again, reflecting a temporary market correction after rapid expansion in various sectors. |
| 2026 | 8.0 | An increase in smart manufacturing initiatives is expected to drive demand for advanced drive technologies. |
| 2027 | 6.1 | Growth is projected to slow as the automotive sector stabilises following rapid advancements. |
| 2028 | 7.7 | Demand is expected to rise as energy efficiency becomes a priority in manufacturing processes. |
| 2029 | 6.3 | Growth is anticipated to slow slightly as adjustments in the textile industry continue to take effect. |
| 2030 | 8.4 | A peak in demand is expected as automation technologies advance across multiple sectors. |
| 2031 | 5.7 | Growth is anticipated to slow as the market approaches maturity in the automotive sector. |
| 2032 | 6.8 | Demand is projected to rise again as new technologies and applications emerge in robotics and automation. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Drives Market Synopsis
Industrial Drives in China are electromechanical devices that control machinery speed, torque, and position. These devices play a crucial role in automation across manufacturing, robotics, and energy management. The China Industrial Drives Market is on an upward path, driven by the 'Made in China 2025' initiative, which encourages automation and advanced technologies. Demand for variable frequency drives is on the rise, with over 60% of new motor installations now incorporating them. Key sectors such as automotive and textiles are major contributors to this growth, reflecting a broader trend towards improved efficiency and productivity.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Strong domestic manufacturing activity drives demand for automation solutions. | Driver | High | Variable Frequency Drives |
| The push for energy efficiency promotes the adoption of advanced drive technologies. | Driver | High | Servo Drives |
| Increasing automation in the textile industry presents a significant investment opportunity. | Opportunity | High | Printing & Textile |
| The automotive sector's shift towards precision manufacturing creates demand for advanced drives. | Opportunity | High | Robotics Equipment |
| High initial costs of advanced drive systems can deter smaller manufacturers. | Restraint | Medium | DC Drives |
| Limited awareness of energy-efficient technologies restricts market growth. | Restraint | Medium | Soft Starters |
| The Industrial Drives market in China faces significant competition from international brands. | Challenge | High | Servo Drives |
| Rapid technological advancements can outpace local manufacturers' capabilities. | Challenge | Medium | Variable Frequency Drives |
Evaluation of Drivers in China Industrial Drives Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased adoption of automation technologies in manufacturing sectors drives demand for industrial drives. | Variable Frequency Drives | Variable frequency drives are used in over 60% of new industrial motor installations, leading to higher sales. |
| The push for energy efficiency leads to a rise in variable frequency drive installations. | Servo Drives | The National Energy Administration promotes energy-efficient technologies, increasing demand for servo drives. |
| The automotive industry's focus on precision manufacturing boosts the need for advanced drive systems. | Servo Drives | The automotive sector is increasingly adopting servo drives, improving production accuracy and efficiency. |
| The textile industry's growth in automation drives demand for industrial drives. | Printing & Textile | The textile industry is one of the largest consumers of industrial drives, particularly in weaving and printing. |
| The 'Made in China 2025' initiative encourages investment in automation technologies. | Variable Frequency Drives | This initiative aims to enhance manufacturing competitiveness, driving demand for advanced drive solutions. |
Expansion of the Industrial Drives market in China is backed by rising end-use demand across manufacturing and textiles. The automotive industry increasingly adopts servo drives for precision manufacturing, with installations projected to reach 1 million units by 2025. The push for energy efficiency promotes variable frequency drives, which are now used in over 60% of new motor installations. The textile sector, a major consumer of industrial drives, continues to grow, particularly in weaving and printing applications.
Evaluation of Restraints in China Industrial Drives Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High initial costs of advanced drive technologies can deter investment from smaller manufacturers. | DC Drives | Smaller manufacturers often struggle to afford advanced drive systems, limiting their adoption. |
| Limited awareness of energy-efficient technologies restricts market growth. | Soft Starters | Many manufacturers are unaware of the benefits of energy-efficient soft starters, hindering their uptake. |
| Intense competition from international brands impacts local manufacturers' market share. | Servo Drives | Local manufacturers face challenges competing with established international brands, affecting their growth. |
| Technological advancements can outpace local manufacturers' capabilities, limiting their competitiveness. | Variable Frequency Drives | Rapid changes in technology may leave some local manufacturers unable to keep up, affecting sales. |
| Regulatory compliance costs can be burdensome for smaller firms. | Variable Frequency Drives | Smaller firms may struggle with the costs associated with meeting regulatory standards, limiting their market presence. |
China Industrial Drives Market Challenges
The China Industrial Drives Market encounters a notable technological challenge, as many manufacturers depend on outdated control algorithms, inflating operational costs by up to 15% for producers. Compliance with ISO 9001 standards adds regulatory complexities that can delay product launches, hindering suppliers' ability to meet market demand. Intense competition among local manufacturers drives prices down, potentially squeezing profit margins for producers by as much as 10%, limiting their capacity for innovation. Additionally, rising raw material costs have increased production expenses by approximately 20%, prompting buyers to reassess procurement strategies and potentially extending project timelines.
Trends in the China Industrial Drives Market
Buyers and suppliers in the China Industrial Drives Market are adjusting to the following trends.
- Shift towards Energy-Efficient Technologies: China is prioritising energy-efficient technologies in industrial drives, influenced by the National Energy Administration's initiatives. The adoption of variable frequency drives is expected to rise, with over 60% of new installations projected to incorporate these technologies.
- Growing Demand for Robotics Equipment: The demand for robotics equipment in China is accelerating, particularly in the automotive sector. Installations are projected to reach 1 million units by 2025, reflecting a strong trend towards automation in manufacturing.
- Increasing Automation in Textile Manufacturing: The textile industry is embracing automation at a rapid pace, significantly increasing its consumption of industrial drives. This sector is one of the largest consumers, particularly in weaving and printing processes, driving further demand.
- Expansion of Smart Manufacturing Initiatives: Smart manufacturing initiatives are gaining traction in China, particularly in the Jiangsu province. The 'Made in China 2025' initiative supports this trend, leading to a higher adoption of advanced drive technologies.
Investment Opportunities in the China Industrial Drives Market
The following opportunities in the China Industrial Drives Market pair current demand with a clear way in.
- Manufacturers in the Automotive Sector: With a projected increase in installations, automotive manufacturers are seeking advanced drive solutions. The Jiangsu province is a key area for investment, and local partnerships can facilitate market entry.
- Local Partnerships for Automation: The growing demand for automation technologies presents an opportunity for joint ventures with local firms. Collaborating with manufacturers in Guangdong can enhance market presence and drive sales.
- Investment in Robotics Equipment: The robotics equipment sector is experiencing significant growth, with installations projected to reach 1 million units by 2025. Suppliers can enter this market through partnerships with local automation firms.
- Energy Efficiency Solutions for Textile Manufacturers: Textile manufacturers are increasingly focused on energy efficiency, creating demand for advanced drive technologies. Suppliers can engage with the textile industry in Shanghai to meet this need.
Government Initiatives in the China Industrial Drives Market
The 'Made in China 2025' initiative, launched by the Ministry of Industry and Information Technology in 2015, aims to boost the competitiveness of Chinese manufacturing through automation and advanced technologies. This initiative encourages investment in industrial drives, promoting growth in the sector. The National Energy Administration's 'Energy Efficiency Action Plan' (2021) supports the adoption of energy-efficient technologies, including variable frequency drives, to reduce energy consumption in industrial sectors. This plan sets benchmarks for energy efficiency, influencing manufacturers to adopt advanced drive solutions.
The 'Guideline for the Development of Industrial Internet' (2021) encourages the integration of industrial drives in smart manufacturing environments. This guideline supports manufacturers in adopting advanced technologies, improving operational efficiency. The China Machinery Industry Federation plays a role in funding projects that develop advanced manufacturing technologies, benefiting local producers. These initiatives collectively aim to improve the competitiveness of the industrial drives market in China.
Future Insight of the China Industrial Drives Market
Several forward-looking factors should support the China Industrial Drives Market over the coming years. The 'Made in China 2025' initiative will facilitate automation adoption, boosting demand for advanced industrial drives. By 2025, installations of robotics equipment are projected to reach 1 million units, necessitating efficient drive technologies. The government's target to reduce energy consumption per unit of GDP by 13.5% will promote the adoption of energy-efficient technologies, benefiting both buyers and suppliers. Advances in semiconductor technology will enhance the performance of industrial drives, further propelling market growth.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Drive Type – Variable Frequency Drives Dominated, Servo Drives Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, the largest drive type category in 2025 was Variable Frequency Drives, with a 44% share of total revenue. Variable frequency drives command the largest market share due to their extensive use in over 60% of new industrial motor installations across various sectors. Their significant application is particularly evident in the Jiangsu province, a hub for industrial automation. Over 2026–2032, Servo Drives are expected to post the fastest growth, at a CAGR of 8.6%. Servo drives are experiencing rapid growth as the demand for precision control in robotics and CNC machines increases, with installations projected to reach 1 million units by 2025. The focus on smart manufacturing in the '13th Five-Year Plan' will further accelerate this trend. Suppliers should prioritise their servo drive offerings to effectively meet the rising demand for precision automation solutions.
By Motor Control – Speed Regulation Dominated, Precision Control Expected to Grow Fastest
Speed Regulation held a 43% share of the China Industrial Drives Market by motor control in 2025. Speed regulation holds the largest share as it is critical for maintaining consistent operational speeds in diverse industrial applications. This is particularly vital in sectors where operational efficiency directly impacts productivity. The quickest growth will come from Precision Control, forecast to expand at a CAGR of 8.3% between 2026 and 2032. Precision control is the fastest-growing segment, driven by the increasing need for high-accuracy applications in manufacturing processes. As industries continue to automate, the demand for precise control technologies will only intensify. Buyers should prioritise suppliers that offer advanced precision control solutions to meet their automation needs.
By Voltage Rating – Low/Medium Voltage Dominated, High Torque Expected to Grow Fastest
Low/Medium Voltage took a 43% share of voltage rating in 2025, more than any other category. Low/medium voltage drives dominate the market as they are widely used in a variety of industrial applications, addressing diverse machinery requirements. Their versatility makes them a preferred choice across numerous operational environments. High Torque is projected to grow fastest, at a CAGR of 9.3% during 2026–2032. High torque drives are witnessing the fastest growth, essential for heavy machinery operations crucial to sectors like construction and manufacturing. This trend aligns with governmental initiatives aimed at enhancing energy efficiency and operational performance. Suppliers should consider expanding their high torque drive product lines to meet the growing demands of heavy machinery applications.
By End User – Conveyor Systems Dominated, Robotics Equipment Expected to Grow Fastest
In 2025, Conveyor Systems led the end user split with a 52% share. Conveyor systems represent the largest end users of industrial drives, playing a vital role in material handling within manufacturing processes. Their significance in boosting operational efficiency ensures a steady demand for related drive technologies. Robotics Equipment is set to record the highest CAGR in this split, 8.7% over 2026–2032. Robotics equipment is the fastest-growing end user, driven by the increasing automation in industries that require precise tasks. This growth is bolstered by initiatives aimed at enhancing manufacturing efficiency and productivity. Suppliers must adjust their strategies to effectively cater to the expanding needs of the robotics equipment market to maintain competitiveness.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Drives Market Outlook
- Market Size of China Industrial Drives Market, 2025
- Forecast of China Industrial Drives Market, 2032
- Historical Data and Forecast of China Industrial Drives Revenues & Volume for the Period 2022 - 2032F
- China Industrial Drives Market Trend Evolution
- China Industrial Drives Market Drivers and Challenges
- China Industrial Drives Price Trends
- China Industrial Drives Porter's Five Forces
- China Industrial Drives Industry Life Cycle
- Historical Data and Forecast of China Industrial Drives Market Revenues & Volume By Drive Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Drives Market Revenues & Volume By Variable Frequency Drives for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Drives Market Revenues & Volume By Servo Drives for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Drives Market Revenues & Volume By DC Drives for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Drives Market Revenues & Volume By Soft Starters for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Drives Market Revenues & Volume By Motor Control for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Drives Market Revenues & Volume By Speed Regulation for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Drives Market Revenues & Volume By Precision Control for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Drives Market Revenues & Volume By Torque Control for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Drives Market Revenues & Volume By Reduced Inrush Current for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Drives Market Revenues & Volume By Voltage Rating for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Drives Market Revenues & Volume By Low/Medium Voltage for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Drives Market Revenues & Volume By Multi-Axis Capability for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Drives Market Revenues & Volume By High Torque for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Drives Market Revenues & Volume By Voltage Limiting for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Drives Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Drives Market Revenues & Volume By Conveyor Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Drives Market Revenues & Volume By Robotics Equipment for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Drives Market Revenues & Volume By Printing & Textile for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Drives Market Revenues & Volume By Pump & Fan Systems for the Period 2022 - 2032F
- China Industrial Drives Import Export Trade Statistics
- Market Opportunity Assessment By Drive Type
- Market Opportunity Assessment By Motor Control
- Market Opportunity Assessment By Voltage Rating
- Market Opportunity Assessment By End User
- China Industrial Drives Top Companies Market Share
- China Industrial Drives Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Drives Company Profiles
- China Industrial Drives Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Drive Type
- Variable Frequency Drives
- Servo Drives
- DC Drives
- Soft Starters
By Motor Control
- Speed Regulation
- Precision Control
- Torque Control
- Reduced Inrush Current
By Voltage Rating
- Low/Medium Voltage
- Multi-Axis Capability
- High Torque
- Voltage Limiting
By End User
- Conveyor Systems
- Robotics Equipment
- Printing & Textile
- Pump & Fan Systems































