China Industrial Emission Monitoring Market Size & Growth Rate
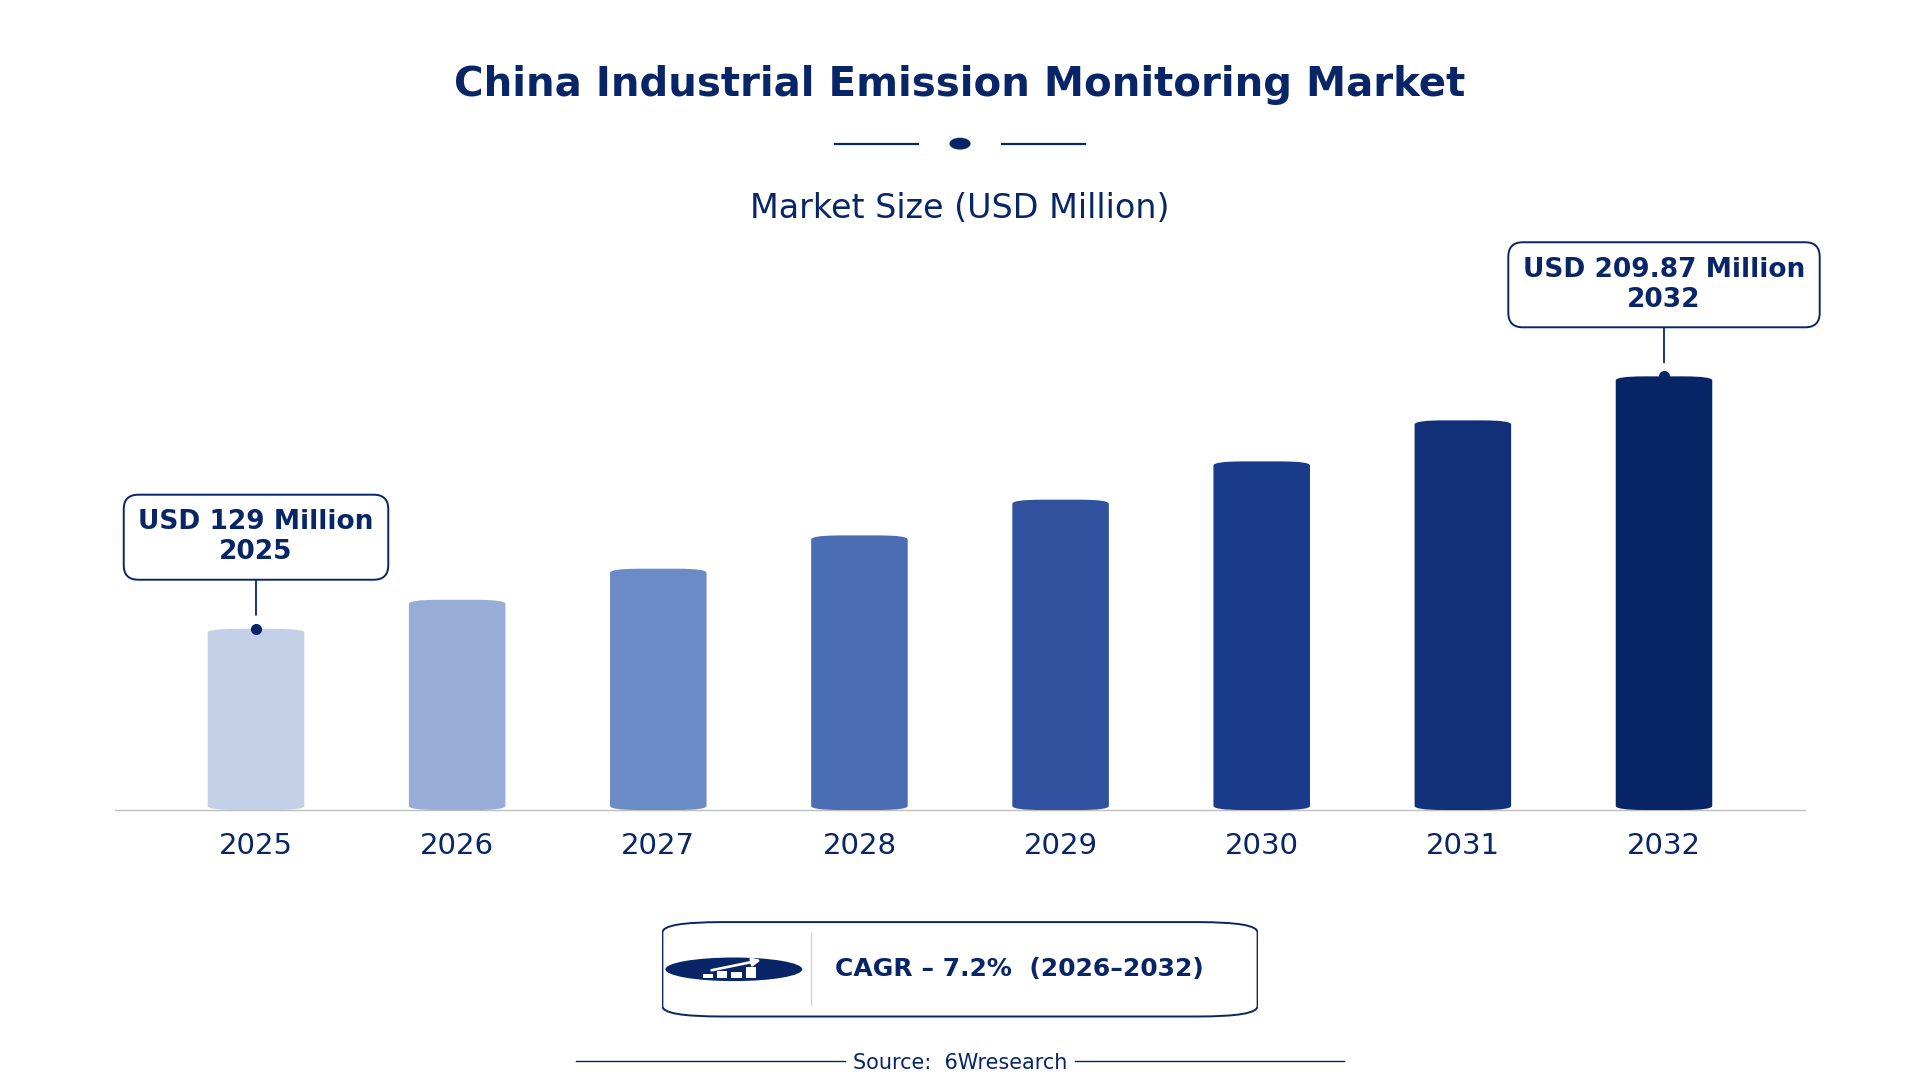
According to 6Wresearch internal database and industry insights, the China Industrial Emission Monitoring Market was valued at USD 129.0 million in 2025 and is projected to reach USD 209.87 million by 2032, growing at a CAGR of approximately 7.2% during 2026–2032.
China Industrial Emission Monitoring Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Emission Monitoring Market |
| Market Size 2025 | USD 129.0 million |
| Market Size 2032 | USD 209.87 million |
| Absolute Growth 2025–2032 | USD 80.87 million |
| CAGR 2026–2032 | 7.2% |
| Peak Annual Growth | 9.5% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Monitoring System Type, 2025 | CEMS (Continuous) (42% share) |
| Leading Sensor Technology, 2025 | NDIR/FTIR Sensors (44% share) |
| Leading Data Output Format, 2025 | Real-Time Dashboard (38% share) |
| Leading End User, 2025 | Industrial Boilers (43% share) |
| Fastest-Growing Monitoring System Type | Portable Emission Monitors (9.8% CAGR) |
| Fastest-Growing Sensor Technology | Electrochemical (8.8% CAGR) |
| Fastest-Growing Data Output Format | USB/Cloud Sync (9.7% CAGR) |
| Fastest-Growing End User | On-Site Inspectors (8.3% CAGR) |
| Growing Sector | Industrial Boilers |
| Key End Users | Manufacturers, On-Site Inspectors, Cement Producers, Refineries |
China Industrial Emission Monitoring Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
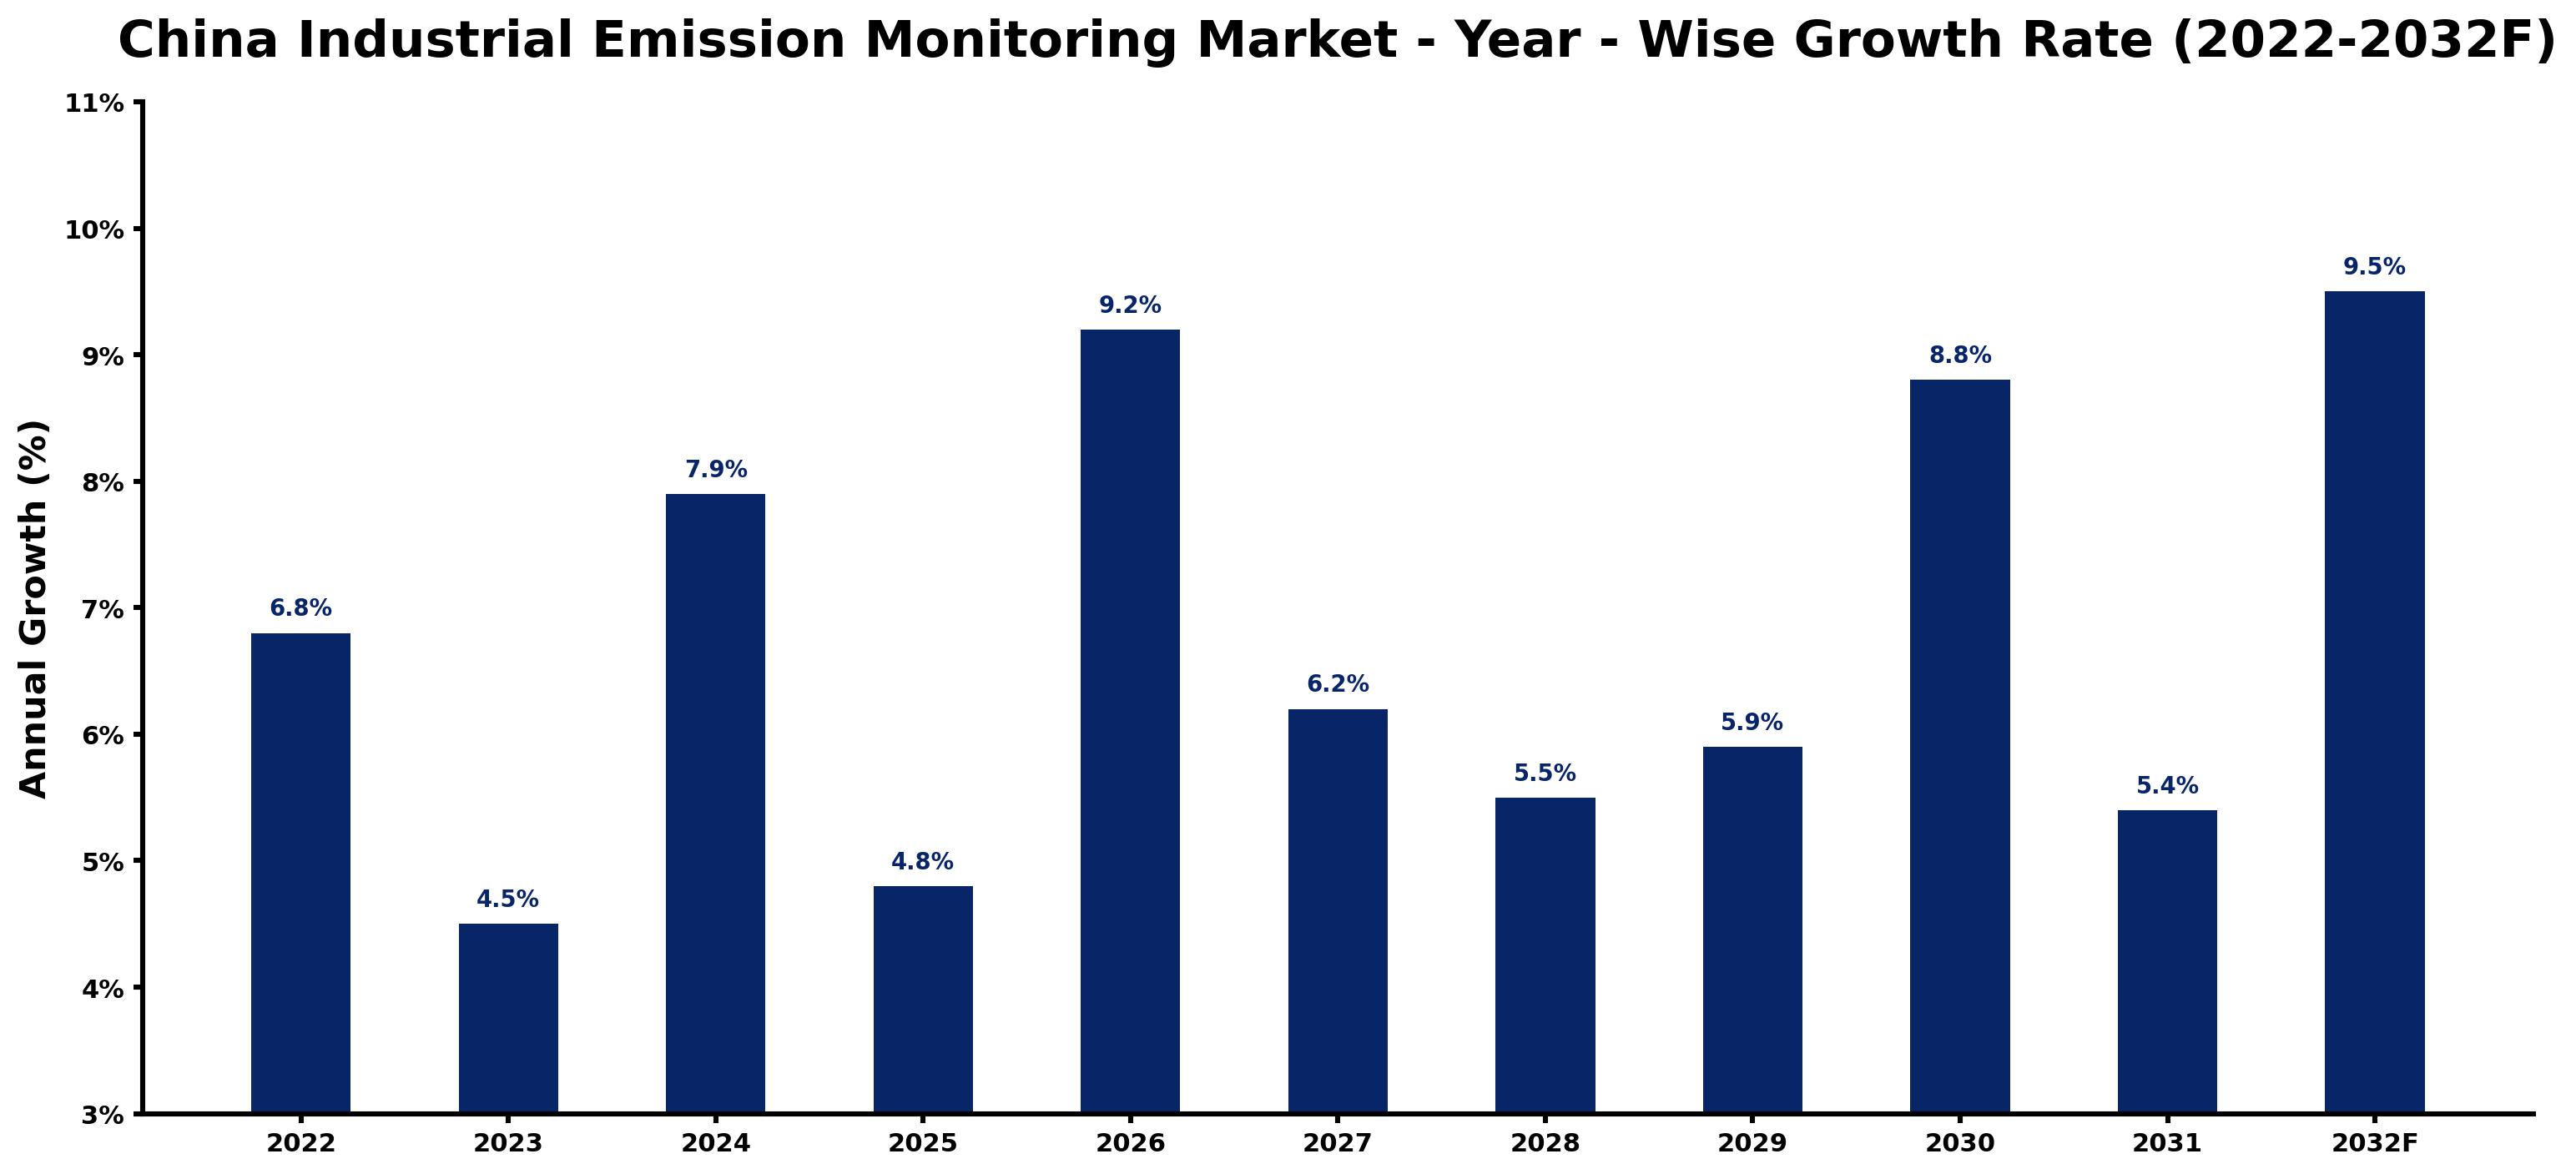
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.8 | The market experienced steady growth due to ongoing industrial operations and regulatory compliance needs. |
| 2023 | 4.5 | Growth slowed as local regulations began to take effect, impacting investment decisions across sectors. |
| 2024 | 7.9 | Demand increased as industries adapted to stricter emission standards and monitoring requirements. |
| 2025 | 4.8 | The market saw a slowdown as companies adjusted to new compliance measures and technologies. |
| 2026 | 9.2 | Growth accelerated with rising investments in continuous monitoring systems across major industries. |
| 2027 | 6.2 | The market slowed as companies faced challenges in integrating new technologies effectively. |
| 2028 | 5.5 | Demand moderated as industries focused on optimising existing monitoring systems rather than new purchases. |
| 2029 | 5.9 | Growth resumed with increased focus on real-time data and compliance from industrial users. |
| 2030 | 8.8 | Demand surged as new regulations were introduced, driving the need for advanced monitoring solutions. |
| 2031 | 5.4 | The market slowed as companies consolidated their investments in emission monitoring technologies. |
| 2032 | 9.5 | Growth peaked as industries fully embraced advanced monitoring systems to meet stringent standards. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Emission Monitoring Market Synopsis
Industrial Emission Monitoring in China involves advanced technologies to measure pollutants from industrial processes. These systems are essential for compliance with environmental regulations and improving air quality. The China Industrial Emission Monitoring Market is expanding due to the stringent emission standards set by local authorities and the increasing operational efficiency demands from heavy industries. As of 2023, over 30 provinces have implemented local regulations, further driving demand for effective monitoring solutions.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Stringent emission regulations drive demand for compliance monitoring systems. | Driver | High | CEMS (Continuous) |
| Increased investment in real-time monitoring technologies enhances operational efficiency. | Driver | High | Portable Emission Monitors |
| Growing need for compliance among industrial users creates opportunities for new entrants. | Opportunity | High | In-Situ Monitors |
| Rising demand for portable solutions among on-site inspectors opens new markets. | Opportunity | Medium | Extractive Monitors |
| High costs of advanced monitoring systems can limit adoption among smaller enterprises. | Restraint | High | CEMS (Continuous) |
| Complexity of integrating new technologies may hinder market growth. | Restraint | Medium | Portable Emission Monitors |
| Supply chain disruptions can delay the availability of essential monitoring equipment. | Challenge | High | In-Situ Monitors |
| Regulatory changes may create uncertainty for manufacturers and buyers alike. | Challenge | Medium | Extractive Monitors |
Evaluation of Drivers in China Industrial Emission Monitoring Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Stringent emission standards require continuous monitoring systems for compliance. | CEMS (Continuous) | With over 10,000 systems installed nationwide, industries are compelled to invest in monitoring solutions to avoid penalties. |
| Real-time data capabilities improve operational efficiency across sectors. | Portable Emission Monitors | The installed base reached over 5,000 units in 2023, indicating strong demand from end-users for precise data. |
| Increased focus on air quality improvement drives technology adoption. | In-Situ Monitors | As industries face pressure to reduce emissions, the need for accurate monitoring grows, leading to higher investments. |
| Government initiatives promote investment in emission monitoring technologies. | Extractive Monitors | The 'Air Pollution Prevention and Control Action Plan' launched in 2022 emphasises the need for regular compliance checks. |
| Rising awareness of environmental impact encourages compliance among industrial users. | NDIR/FTIR Sensors | These sensors are essential for precise measurement, resulting in increased installations across various industries. |
The focus on improving air quality is prompting industries to embrace advanced in-situ monitoring solutions, especially in high-emission sectors such as cement production. The allocation of 1 billion yuan for upgrading monitoring infrastructure encourages the adoption of advanced technologies. This increasing emphasis on compliance is driving demand for effective monitoring systems across various industries.
Evaluation of Restraints in China Industrial Emission Monitoring Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs of advanced monitoring systems limit adoption among smaller enterprises. | CEMS (Continuous) | Many small manufacturers struggle to invest in necessary compliance technologies, affecting market penetration. |
| Integration challenges with existing systems hinder market growth. | Portable Emission Monitors | Companies face difficulties in adopting new technologies alongside legacy systems, slowing down implementation. |
| Supply chain disruptions can delay the availability of essential monitoring equipment. | In-Situ Monitors | Manufacturers experience delays in sourcing components, impacting project timelines and delivery. |
| Regulatory changes may create uncertainty for manufacturers and buyers alike. | Extractive Monitors | Frequent updates in emission standards can lead to confusion and hesitance in investment decisions. |
| Limited awareness of advanced monitoring technologies among smaller firms restricts market growth. | NDIR/FTIR Sensors | Smaller enterprises often lack the resources to stay informed about technological advancements. |
China Industrial Emission Monitoring Market Challenges
The China Industrial Emission Monitoring Market encounters high costs associated with advanced emission measurement technologies, which can strain budgets for manufacturers and delay compliance efforts. Buyers find it challenging to keep up with rapid regulatory changes, as over 30 provinces have introduced local regulations requiring immediate compliance, risking fines that can exceed 500,000 yuan. Stringent emission standards set by the Ministry of Ecology and Environment require costly upgrades to existing systems, affecting operational budgets for various industries. Skills shortages in the workforce hinder the effective deployment of monitoring technologies, resulting in operational inefficiencies for industries that depend on accurate emissions data.
Trends in the China Industrial Emission Monitoring Market
Several trends are reshaping the China Industrial Emission Monitoring Market; the most important are set out below.
- Shift towards Real-Time Monitoring: Industrial users are increasingly adopting real-time monitoring systems to improve compliance and operational efficiency. As of 2023, the installed base of such systems in cement kilns reached over 1,500 units, reflecting a growing trend towards immediate data access.
- Transition from Traditional to Advanced Sensors: Since 2022, there has been a notable shift towards advanced sensor technologies like NDIR/FTIR Sensors, which offer greater accuracy. This change is evident as these sensors captured a 44% market share in 2025, highlighting their growing importance.
- Emergence of Cloud-Based Data Solutions: The rise of USB/Cloud Sync technologies is transforming data management in emission monitoring. As of 2026, this segment is projected to grow at a CAGR of 9.7%, indicating a shift towards more integrated data solutions.
- Increased Focus on Compliance Among On-Site Inspectors: On-site inspectors have become more reliant on emission monitoring data to ensure compliance. This trend is supported by an 8.3% CAGR for this segment from 2026 to 2032, reflecting heightened regulatory scrutiny.
Investment Opportunities in the China Industrial Emission Monitoring Market
Some of the investment opportunities in the China Industrial Emission Monitoring Market are mentioned below.
- Partnerships for Technology Integration: With a growing demand for effective monitoring solutions, partnerships with local firms can facilitate technology integration. The market gap is clear as over 30 provinces have implemented local regulations, creating demand for compliance solutions.
- Supply of Portable Emission Monitors: The rising need for portable solutions among on-site inspectors presents a significant opportunity. With over 5,000 units installed in 2023, suppliers can target this growing segment by forming local partnerships.
- Investment in Advanced Sensor Technologies: The market gap for advanced sensor technologies is substantial, with NDIR/FTIR Sensors leading at 44% market share. Suppliers can enter by collaborating with local manufacturers to improve distribution.
- Development of Cloud-Based Monitoring Solutions: The shift towards USB/Cloud Sync technologies indicates a growing opportunity for suppliers. As this segment is projected to grow at 9.7%, entering through local partnerships can be advantageous.
Government Initiatives in the China Industrial Emission Monitoring Market
The National Standard GB 12348-2008 sets strict emission limits for industrial enterprises, directly impacting producers and buyers of monitoring systems. Compliance with these standards is mandatory, requiring industries to invest in advanced monitoring technologies to avoid penalties. The 'Air Pollution Prevention and Control Action Plan' launched in 2022 further emphasises the importance of emission monitoring, mandating regular reporting and compliance checks. As a result, industries must upgrade their monitoring capabilities to align with these regulations, driving demand for advanced systems.
The National Environmental Monitoring Center oversees the implementation of emission standards and monitoring regulations in China. This agency approves various monitoring technologies and allocates funding for upgrading infrastructure. In 2023, the government allocated 1 billion yuan to enhance emission monitoring across key industries, supporting the adoption of advanced technologies. Additionally, the Ministry of Ecology and Environment plays a significant role in overseeing compliance and ensuring that industries meet the required standards.
Future Insight of the China Industrial Emission Monitoring Market
The China Industrial Emission Monitoring Market will evolve significantly by 2032, driven by the government's strong focus on environmental protection and technological advancements. The allocation of 1 billion yuan for upgrading emission monitoring infrastructure will improve capabilities across key industries. Real-time monitoring systems will become standard, particularly in high-emission sectors like cement production. The ongoing rollout of the 'Air Pollution Prevention and Control Action Plan' will further highlight the need for effective monitoring, ensuring compliance and contributing to better air quality.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Monitoring System Type – CEMS (Continuous) Dominated, Portable Emission Monitors Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, with a 42% revenue share in 2025, CEMS (Continuous) was the largest monitoring system type category. CEMS holds the largest market share as it is mandated for continuous monitoring across major industrial sources, ensuring compliance with strict emission standards. With over 10,000 systems installed nationwide, it plays a crucial role in sectors like manufacturing and energy production. Over 2026–2032, Portable Emission Monitors are expected to post the fastest growth, at a CAGR of 9.8%. The portable emission monitors segment is growing rapidly as industries adopt these systems for on-site inspections and spot checks. An installed base of over 5,000 units indicates a strong demand for flexible monitoring solutions that can adapt to various operational needs. Suppliers should enhance portable systems to capture the increasing market interest effectively.
By Sensor Technology – NDIR/FTIR Sensors Dominated, Electrochemical Expected to Grow Fastest
NDIR/FTIR Sensors took a 44% share of sensor technology in 2025, more than any other category. NDIR/FTIR sensors command the largest market share due to their ability to provide precise measurements of gas concentrations, essential for meeting environmental regulations. Their widespread use across different industries reinforces their status as the preferred choice for emission monitoring. Electrochemical is projected to grow fastest, at a CAGR of 8.8% during 2026–2032. Electrochemical sensors are seeing the fastest growth as they excel in detecting specific gas pollutants. This effectiveness aligns with the heightened regulatory focus on targeted emissions, driving demand for these advanced sensors. Buyers will benefit from investing in electrochemical sensors to comply with stringent regulatory requirements more efficiently.
By Data Output Format – Real-Time Dashboard Dominated, USB/Cloud Sync Expected to Grow Fastest
Real-Time Dashboard accounted for a 38% market share by data output format in 2025. The real-time dashboard format captures the largest market share as it offers immediate visualisation of emissions data, critical for timely decision-making in compliance monitoring. Its integration into various monitoring systems significantly enhances operational efficiency across industries. USB/Cloud Sync is set to record the highest CAGR in this split, 9.7% over 2026–2032. USB/cloud sync formats are rapidly gaining popularity as they facilitate easy data transfer and accessibility, meeting the growing need for remote monitoring solutions. This trend is particularly relevant as industries aim to streamline their data management processes. Suppliers should focus on developing user-friendly data output solutions to address the rising demand for efficient data management.
By End User – Industrial Boilers Dominated, On-Site Inspectors Expected to Grow Fastest
Industrial Boilers held a 43% share of the China Industrial Emission Monitoring Market by end user in 2025. Industrial boilers represent a substantial share of emissions in China, making them the primary end user of emission monitoring systems. Their significant contribution to national emissions necessitates stringent monitoring to comply with environmental regulations. The quickest growth will come from On-Site Inspectors, forecast to expand at a CAGR of 8.3% between 2026 and 2032. On-site inspectors are experiencing the fastest growth as they increasingly rely on real-time monitoring data for compliance checks. This trend is driven by the need for more effective enforcement of emission standards across various industries. Suppliers should tailor their offerings to meet the needs of on-site inspectors, ensuring access to reliable and accurate monitoring data.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Emission Monitoring Market Outlook
- Market Size of China Industrial Emission Monitoring Market, 2025
- Forecast of China Industrial Emission Monitoring Market, 2032
- Historical Data and Forecast of China Industrial Emission Monitoring Revenues & Volume for the Period 2022 - 2032F
- China Industrial Emission Monitoring Market Trend Evolution
- China Industrial Emission Monitoring Market Drivers and Challenges
- China Industrial Emission Monitoring Price Trends
- China Industrial Emission Monitoring Porter's Five Forces
- China Industrial Emission Monitoring Industry Life Cycle
- Historical Data and Forecast of China Industrial Emission Monitoring Market Revenues & Volume By Monitoring System Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Emission Monitoring Market Revenues & Volume By CEMS (Continuous) for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Emission Monitoring Market Revenues & Volume By Portable Emission Monitors for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Emission Monitoring Market Revenues & Volume By In-Situ Monitors for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Emission Monitoring Market Revenues & Volume By Extractive Monitors for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Emission Monitoring Market Revenues & Volume By Sensor Technology for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Emission Monitoring Market Revenues & Volume By NDIR/FTIR Sensors for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Emission Monitoring Market Revenues & Volume By Electrochemical for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Emission Monitoring Market Revenues & Volume By Laser-Based Detection for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Emission Monitoring Market Revenues & Volume By Sample Line Monitoring for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Emission Monitoring Market Revenues & Volume By Data Output Format for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Emission Monitoring Market Revenues & Volume By Real-Time Dashboard for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Emission Monitoring Market Revenues & Volume By USB/Cloud Sync for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Emission Monitoring Market Revenues & Volume By Analog/Digital for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Emission Monitoring Market Revenues & Volume By SCADA-Linked for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Emission Monitoring Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Emission Monitoring Market Revenues & Volume By Industrial Boilers for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Emission Monitoring Market Revenues & Volume By On-Site Inspectors for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Emission Monitoring Market Revenues & Volume By Cement Kilns for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Emission Monitoring Market Revenues & Volume By Refineries for the Period 2022 - 2032F
- China Industrial Emission Monitoring Import Export Trade Statistics
- Market Opportunity Assessment By Monitoring System Type
- Market Opportunity Assessment By Sensor Technology
- Market Opportunity Assessment By Data Output Format
- Market Opportunity Assessment By End User
- China Industrial Emission Monitoring Top Companies Market Share
- China Industrial Emission Monitoring Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Emission Monitoring Company Profiles
- China Industrial Emission Monitoring Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Monitoring System Type
- CEMS (Continuous)
- Portable Emission Monitors
- In-Situ Monitors
- Extractive Monitors
By Sensor Technology
- NDIR/FTIR Sensors
- Electrochemical
- Laser-Based Detection
- Sample Line Monitoring
By Data Output Format
- Real-Time Dashboard
- USB/Cloud Sync
- Analog/Digital
- SCADA-Linked
By End User
- Industrial Boilers
- On-Site Inspectors
- Cement Kilns
- Refineries































