China Industrial Paints Market Size & Growth Rate
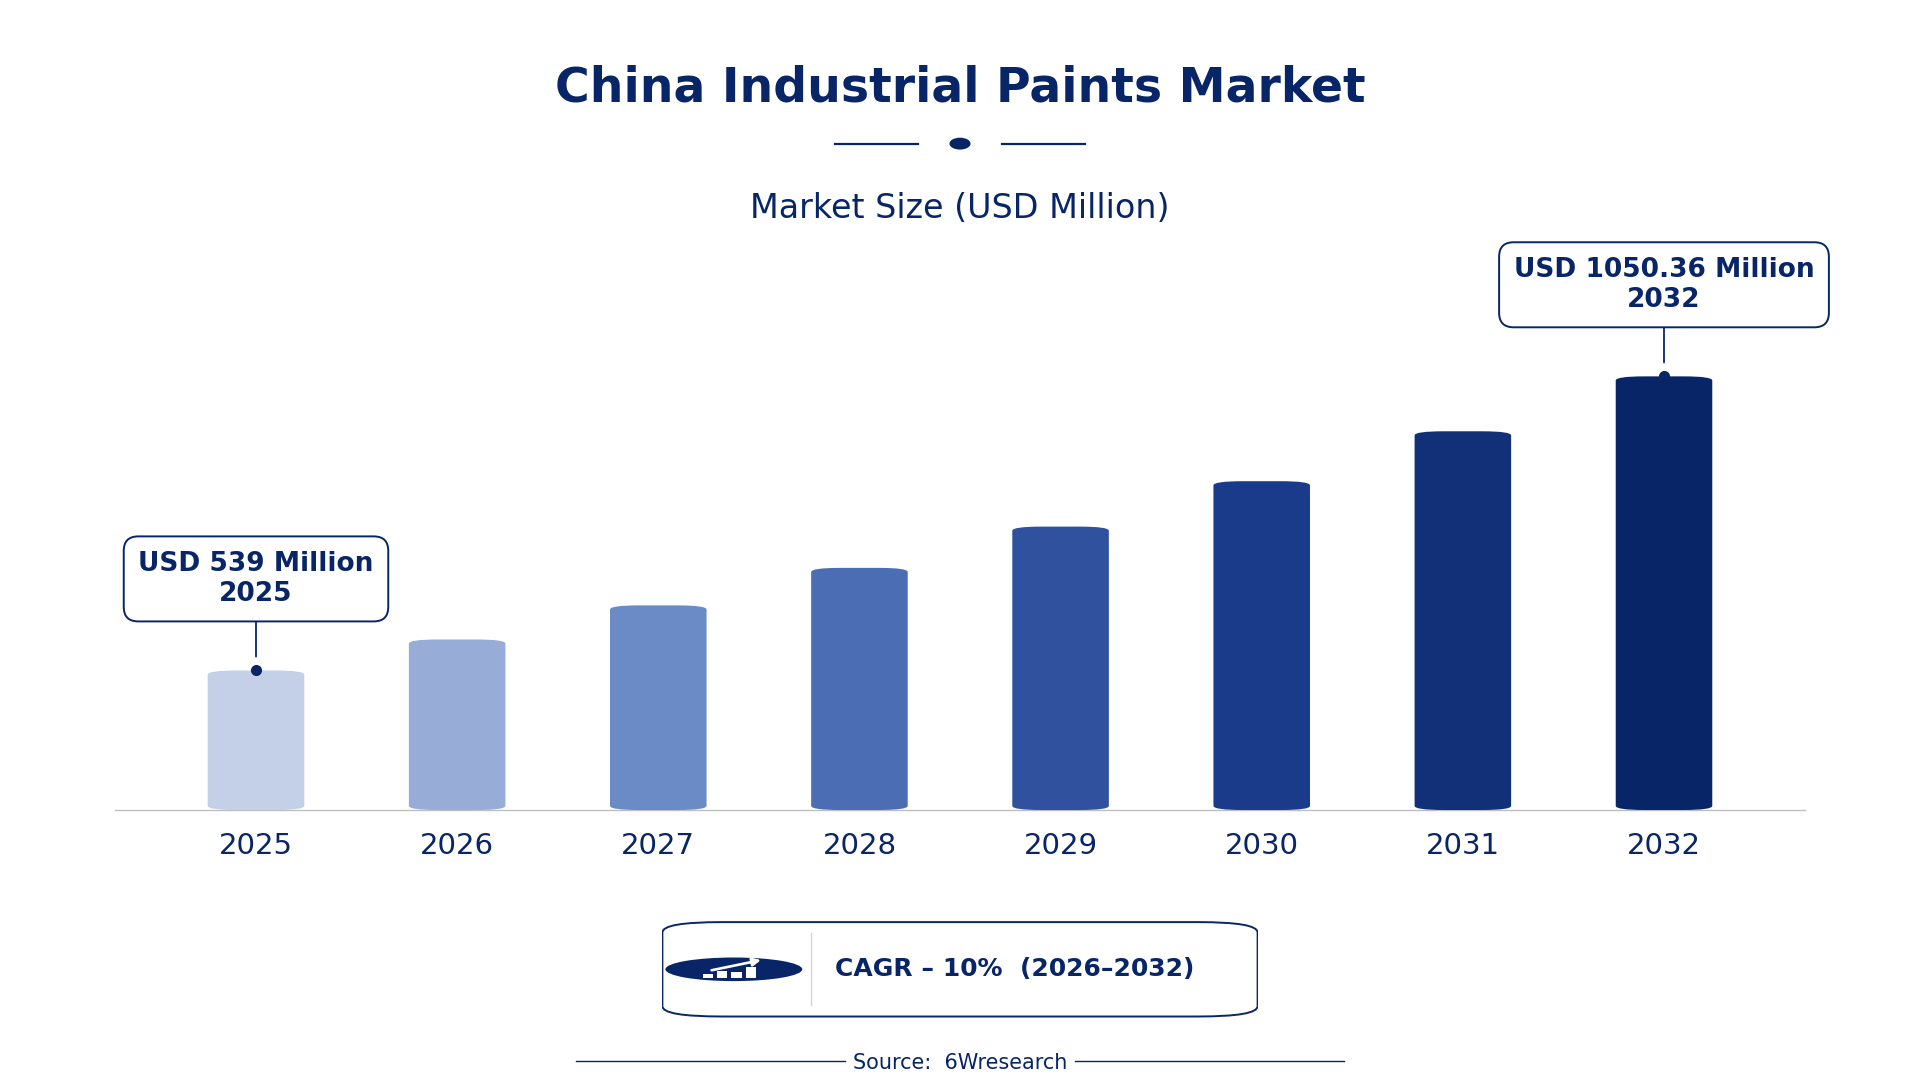
According to 6Wresearch internal database and industry insights, the China Industrial Paints Market was valued at USD 539.0 million in 2025 and is projected to reach USD 1,050.36 million by 2032, growing at a CAGR of approximately 10% during 2026–2032.
China Industrial Paints Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Paints Market |
| Market Size 2025 | USD 539.0 million |
| Market Size 2032 | USD 1,050.36 million |
| Absolute Growth 2025–2032 | USD 511.36 million |
| CAGR 2026–2032 | 10% |
| Peak Annual Growth | 12.6% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Paint Type, 2025 | Epoxy Paints (41% share) |
| Leading Base Type, 2025 | Solvent-Based (46% share) |
| Leading Coating Technology, 2025 | Spray Coating (43% share) |
| Leading Application, 2025 | Equipment Protection (45% share) |
| Leading End User Industry, 2025 | Heavy Industry (48% share) |
| Fastest-Growing Paint Type | Polyurethane Paints (12.5% CAGR) |
| Fastest-Growing Base Type | Water-Based (11.0% CAGR) |
| Fastest-Growing Coating Technology | Roller Application (11.8% CAGR) |
| Fastest-Growing Application | Surface Finishing (12.0% CAGR) |
| Fastest-Growing End User Industry | Automotive (12.5% CAGR) |
| Growing Sector | Automotive |
| Key End Users | Heavy Industry, Automotive, Construction, Consumer Products |
China Industrial Paints Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
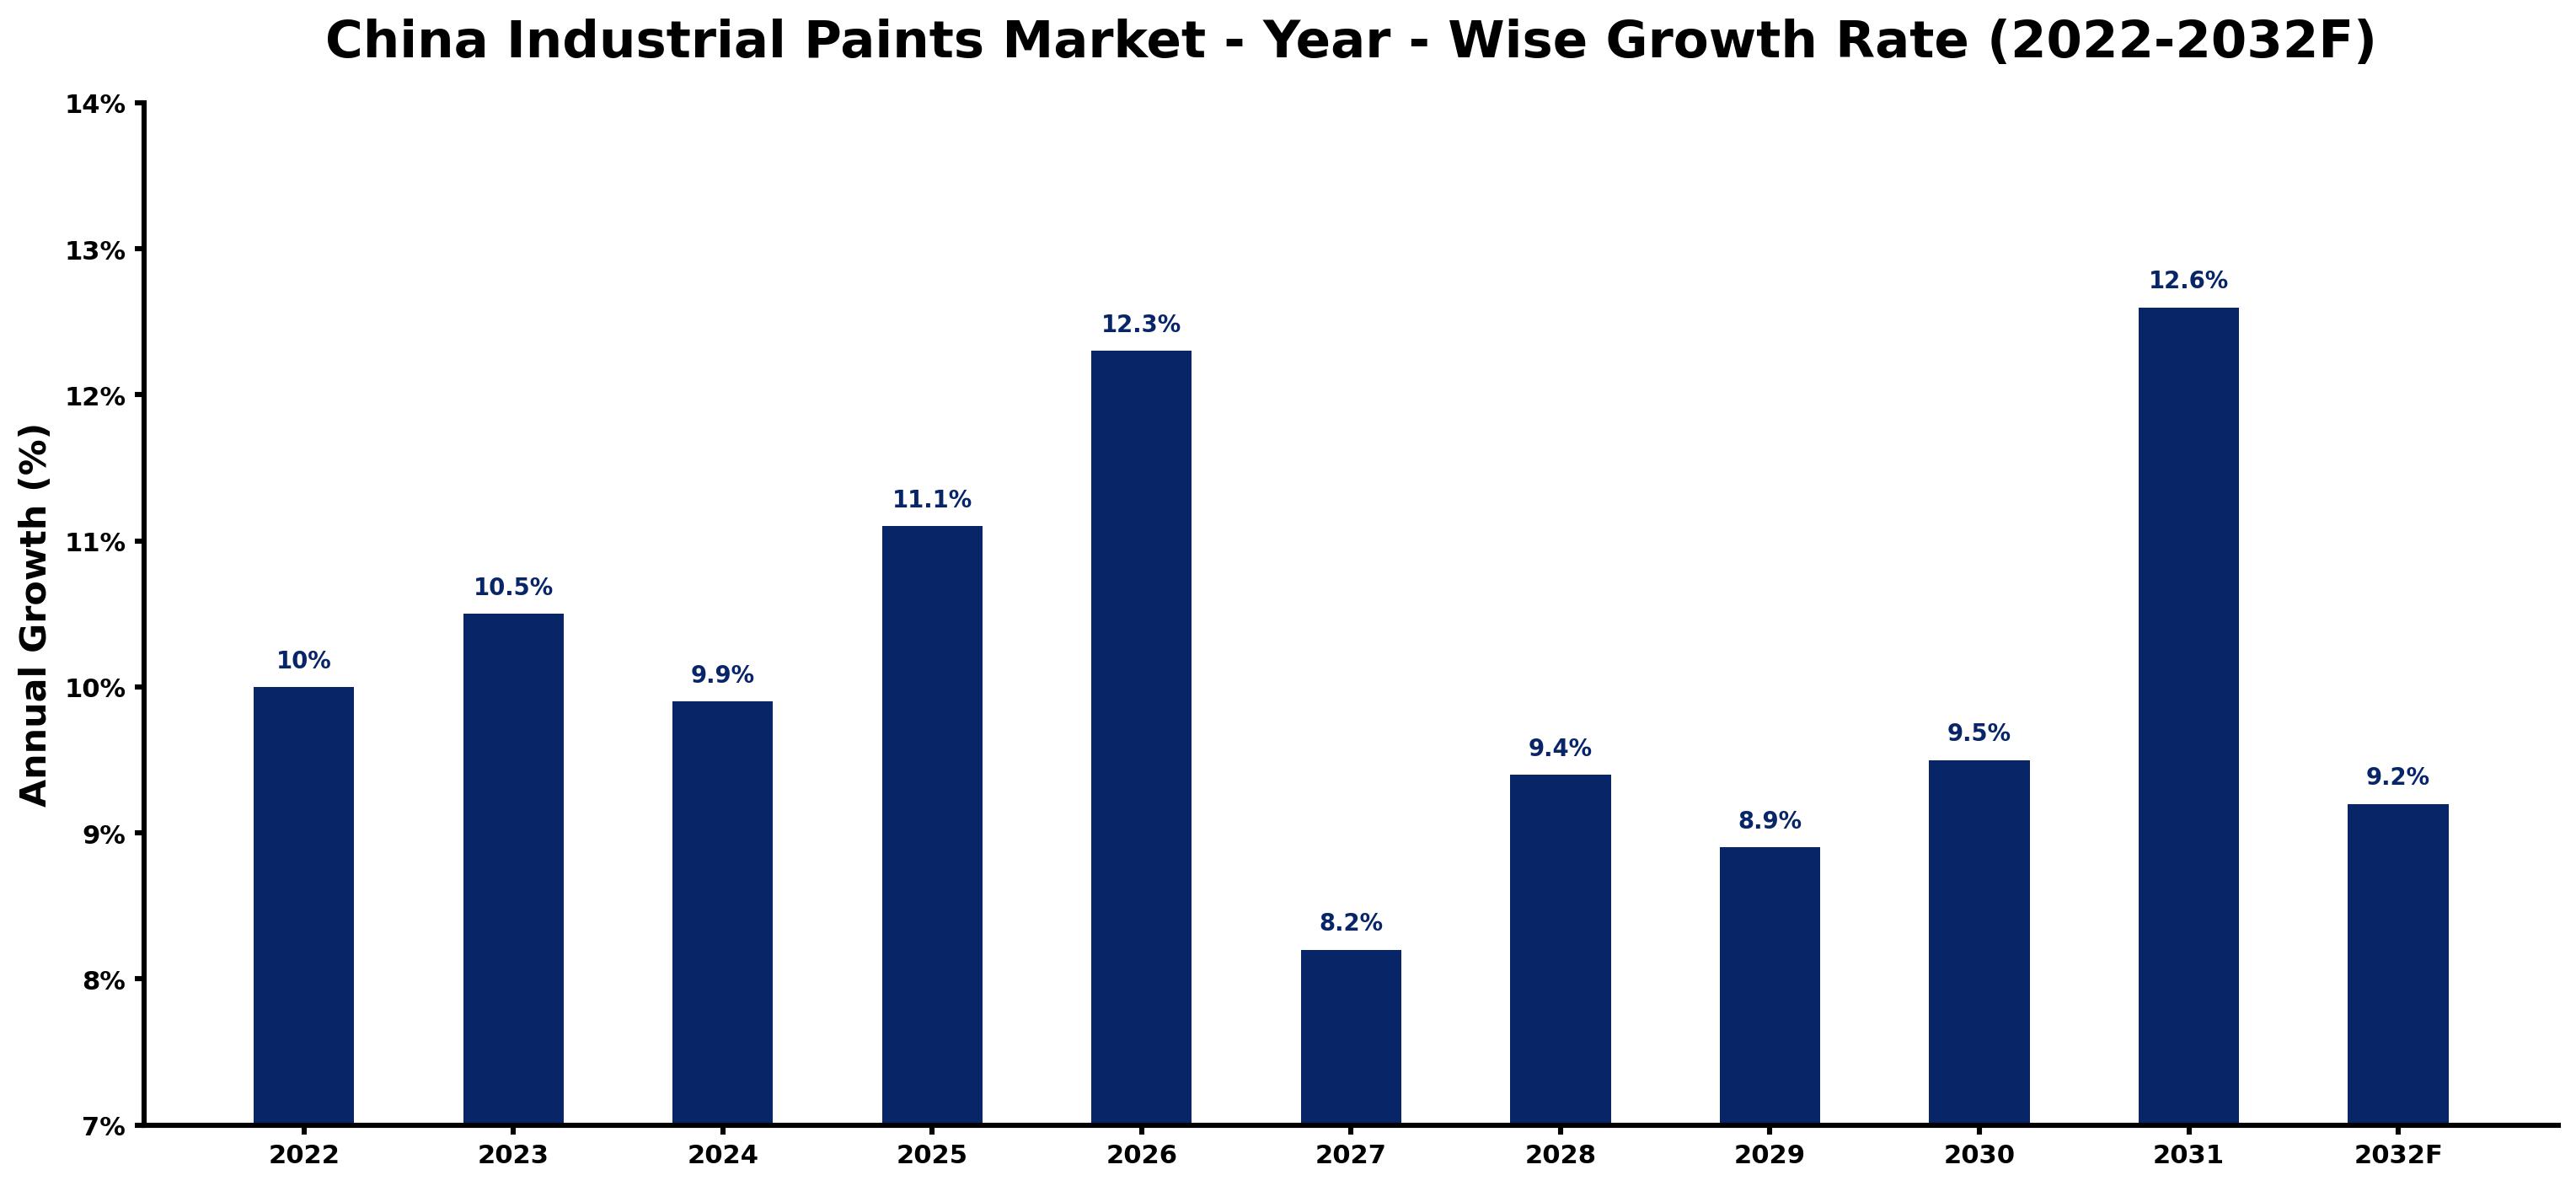
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 10.0 | The market experienced steady growth due to ongoing industrial activities. |
| 2023 | 10.5 | Increased production in the automotive sector further boosted paint demand. |
| 2024 | 9.9 | Growth slowed slightly as manufacturers adjusted to market conditions. |
| 2025 | 11.1 | A surge in construction projects led to heightened demand for industrial paints. |
| 2026 | 12.3 | The automotive industry's expansion continued to drive higher paint consumption. |
| 2027 | 8.2 | Growth decelerated as supply chain issues began to surface. |
| 2028 | 9.4 | A recovery in construction activities spurred renewed interest in paint applications. |
| 2029 | 8.9 | Demand growth slowed as market saturation began to set in. |
| 2030 | 9.5 | Increased focus on eco-friendly products revitalised interest in certain paint types. |
| 2031 | 12.6 | A peak in growth occurred as new manufacturing technologies were adopted. |
| 2032 | 9.2 | Growth slowed as the market began to stabilise after rapid expansion. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Paints Market Synopsis
Industrial Paints in China include chemical coatings designed for protection and aesthetics. These paints, made from resins, pigments, and additives, find primary applications in heavy industry, automotive, and construction. The China Industrial Paints Market is expanding due to increasing demand from sectors such as automotive, which produced over 25 million vehicles in 2023. Furthermore, the construction industry is projected to require over 10 million tons of industrial paints annually by 2025, further driving consumption.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising automotive production | Driver | High | Automotive |
| Increasing construction activities | Driver | High | Construction |
| Emerging demand for eco-friendly coatings | Opportunity | High | Water-Based |
| Growth in the heavy industry sector | Opportunity | Medium | Heavy Industry |
| Regulatory compliance costs | Restraint | High | Epoxy Paints |
| Supply chain disruptions | Restraint | Medium | Epoxy Paints |
| Competition from low-cost imports | Challenge | High | Epoxy Paints |
| Technological adaptation costs | Challenge | Medium | Epoxy Paints |
Evaluation of Drivers in China Industrial Paints Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased vehicle production drives demand for high-performance coatings. | Automotive | The automotive industry produced over 25 million vehicles in 2023, leading to higher paint consumption. |
| Growing construction projects require protective coatings. | Construction | The construction sector is expected to need over 10 million tons of industrial paints annually by 2025. |
| Rising demand for eco-friendly products is influenced by regulations. | Heavy Industry | Heavy industry remains a key user of industrial paints, driving consistent demand for sustainable options. |
| Technological advancements improve coating efficiency. | Powder-Based | Powder coatings are projected to grow rapidly due to their environmental benefits and efficiency. |
| The shift towards sustainable practices is gaining momentum. | Water-Based | Water-based paints accounted for approximately 30% of the total industrial paint market in 2022, reflecting changing preferences. |
Expansion of the Industrial Paints market in China is backed by increasing demand from various sectors. In 2023, the automotive industry produced over 25 million vehicles, driving higher paint consumption. The construction sector is projected to require over 10 million tons of industrial paints annually by 2025, creating further demand. Technological advancements in powder coatings improve efficiency and environmental performance, attracting more buyers across industries.
Evaluation of Restraints in China Industrial Paints Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Compliance with stringent environmental regulations raises costs. | Epoxy Paints | Meeting standards like GB/T 19250-2019 increases production expenses for manufacturers. |
| Supply chain disruptions affect material availability. | Epoxy Paints | Recent global supply chain issues have led to delays in material procurement, impacting production schedules. |
| Competition from low-cost imports limits pricing power. | Epoxy Paints | Imported paints often come at lower prices, challenging local manufacturers to maintain profitability. |
| Technological adaptation costs can be high. | Epoxy Paints | Investing in new technologies for eco-friendly production requires substantial capital investment from manufacturers. |
| Market saturation in certain segments slows growth. | Epoxy Paints | As the market matures, demand in established sectors begins to stabilise, limiting growth potential. |
China Industrial Paints Market Challenges
The China Industrial Paints Market still has to solve a few problems, and the first is rising raw material costs. In 2023, prices for key ingredients surged by 15%, impacting buyers in the automotive and construction sectors, who face increased production expenses. Another issue is the slow adoption of eco-friendly technologies; despite the 'Green Coating' initiative, only 30% of manufacturers have transitioned to sustainable practices, delaying compliance for suppliers. Competition from low-cost imports is intensifying, forcing local producers to reduce prices, which can compromise quality and innovation. Finally, rapid technological advancements in coating applications create a skills gap, making it hard for manufacturers to keep pace with industry standards.
Trends in the China Industrial Paints Market
Four trends stand out in the China Industrial Paints Market.
- Shift Towards Eco-Friendly Coatings: The construction sector is increasingly embracing eco-friendly coatings, driven by the 'Green Coating' initiative. In 2023, the government allocated 300 million CNY for subsidies to promote these products.
- Emergence of Powder Coatings: Powder coatings are gaining popularity due to their efficiency and environmental advantages. The market for powder coatings is expected to expand rapidly, reflecting a shift in buyer preferences towards sustainable solutions.
- Increased Adoption of Electrostatic Coating: Electrostatic coating technology is becoming prevalent in the automotive sector for its efficiency. This trend is bolstered by the automotive industry's production of over 25 million vehicles in 2023, increasing the demand for high-performance coatings.
- Growth in Water-Based Paints: Water-based paints are becoming more popular due to environmental regulations. They represented approximately 30% of the total industrial paint market in 2022, showing a notable shift towards sustainable products.
Investment Opportunities in the China Industrial Paints Market
Some of the investment opportunities in the China Industrial Paints Market are mentioned below.
- Investment in Eco-Friendly Facilities: The push for sustainable practices creates opportunities for eco-friendly paint production facilities. The Ministry of Finance allocated 300 million CNY in 2023 for subsidies in this area, encouraging manufacturers to invest in greener technologies.
- Expansion in Heavy Industry Regions: With heavy industry as a major user, there is a need for supply expansion in industrial regions like Shanghai and Guangdong. Investing in local manufacturing can meet this demand effectively, ensuring timely delivery of products.
- Partnerships for Technological Advancements: Collaborating with local firms can facilitate the adoption of advanced coating technologies. This is essential as manufacturers seek to improve competitiveness in a rapidly evolving market, particularly in the automotive sector.
- Focus on Automotive Coatings: The automotive sector, accounting for 40% of total paint demand, presents significant investment opportunities. Suppliers can enter this market by developing high-performance coatings tailored to automotive needs, responding to increasing production volumes.
Government Initiatives in the China Industrial Paints Market
The National Standard GB/T 19250-2019, updated in 2020, established quality control measures for industrial paints, impacting both manufacturers and consumers. This regulation ensures that products meet safety and performance standards, building consumer confidence in domestic offerings. The 'Made in China 2025' strategy, revised in 2021, prioritises advancements in the coatings sector, aiming for improved technology and environmental standards to boost competitiveness.
In 2021, the Ministry of Ecology and Environment launched the 'Green Coating' initiative to promote eco-friendly paint products, focusing on reducing VOC emissions. This programme encourages manufacturers to adopt sustainable practices and enhance product offerings. The Ministry of Industry and Information Technology introduced the 'Coatings Industry Development Plan' in 2022 to stimulate innovation and sustainability in paint production, providing a framework for funding and support to ensure the industry's growth aligns with environmental objectives.
Future Insight of the China Industrial Paints Market
The China Industrial Paints Market is expected to evolve significantly by 2032, driven by several key factors. The construction sector will require over 10 million tons of industrial paints annually, ensuring steady demand for suppliers. The government's allocation of 500 million CNY for eco-friendly paint technologies will spur innovation, benefiting buyers seeking sustainable solutions. The growing adoption of advanced coating technologies in the automotive industry will improve production efficiency, allowing manufacturers to meet rising consumer expectations. The focus on advanced manufacturing under the 'Made in China 2025' initiative will strengthen the competitive edge of local producers.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Paint Type – Epoxy Paints Dominated, Polyurethane Paints Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, with a 41% revenue share in 2025, Epoxy Paints was the largest paint type category. Epoxy paints dominate the market as they offer superior corrosion resistance, making them indispensable in various industrial applications. Their extensive use in sectors like heavy machinery and infrastructure within key regions such as Shanghai and Guangdong solidifies their leading position. Over 2026–2032, Polyurethane Paints are expected to post the fastest growth, at a CAGR of 12.5%. Polyurethane paints are experiencing swift growth due to their ability to deliver durable finishes that meet the rigorous requirements of the automotive industry. With over 25 million vehicles produced in 2023, this segment is set to expand significantly. Suppliers should focus on enhancing their polyurethane paint offerings to meet the rising demand from the automotive sector.
By Base Type – Solvent-Based Dominated, Water-Based Expected to Grow Fastest
Solvent-Based accounted for a 46% market share by base type in 2025. Solvent-based paints hold the largest market share, having been the traditional choice for numerous industrial applications due to their reliable performance. Their established role in sectors like heavy industry ensures sustained demand and continued relevance. Water-Based is projected to grow fastest, at a CAGR of 11.0% during 2026–2032. Water-based paints are rapidly gaining traction as manufacturers respond to increasing environmental regulations and safety concerns, making them an appealing choice for sustainable practices. This shift is prompting innovation and adaptation in the market. Buyers should explore water-based alternatives to comply with environmental standards and improve workplace safety.
By Coating Technology – Spray Coating Dominated, Roller Application Expected to Grow Fastest
Spray Coating took a 43% share of coating technology in 2025, more than any other category. Spray coating is the dominant technology, recognised for its efficiency in application across diverse industries, making it the go-to choice for large-scale projects. Its extensive use in manufacturing facilities boosts both productivity and finish quality. The quickest growth will come from Roller Application, forecast to expand at a CAGR of 11.8% between 2026 and 2032. Roller application is becoming increasingly popular, particularly for DIY projects, due to its user-friendly nature and cost-effectiveness for smaller applications. This trend reflects a shift towards more accessible coating methods for consumers. Suppliers should explore opportunities in roller application products to meet the rising demand from the DIY market.
By Application – Equipment Protection Dominated, Surface Finishing Expected to Grow Fastest
The largest application category in 2025 was Equipment Protection, with a 45% share of total revenue. Equipment protection is the leading application segment, crucial for prolonging the lifespan of industrial machinery and maintaining operational efficiency. This need is particularly pronounced in heavy industries, where equipment reliability is essential to avoid costly downtimes. Surface Finishing is set to record the highest CAGR in this split, 12.0% over 2026–2032. Surface finishing is growing quickly as manufacturers prioritise aesthetic appeal alongside protective features in their products. This trend highlights the increasing importance of visual quality in competitive markets. Manufacturers should invest in advanced surface finishing solutions to meet changing consumer expectations.
By End User Industry – Heavy Industry Dominated, Automotive Expected to Grow Fastest
In 2025, Heavy Industry led the end user industry split with a 48% share. Heavy industry remains the largest end-user of industrial paints, as these coatings are essential for machinery and structural applications. The ongoing operations in sectors like manufacturing and energy ensure a steady demand for these products. Over 2026–2032, Automotive is expected to post the fastest growth, at a CAGR of 12.5%. The automotive sector is the fastest-growing end user, driven by the need for high-performance coatings that can withstand rigorous conditions. With production numbers soaring, this segment is likely to expand further. Suppliers should align their product offerings with the automotive industry's requirements to capitalise on this growth.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Paints Market Outlook
- Market Size of China Industrial Paints Market, 2025
- Forecast of China Industrial Paints Market, 2032
- Historical Data and Forecast of China Industrial Paints Revenues & Volume for the Period 2022 - 2032F
- China Industrial Paints Market Trend Evolution
- China Industrial Paints Market Drivers and Challenges
- China Industrial Paints Price Trends
- China Industrial Paints Porter's Five Forces
- China Industrial Paints Industry Life Cycle
- Historical Data and Forecast of China Industrial Paints Market Revenues & Volume By Paint Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Paints Market Revenues & Volume By Epoxy Paints for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Paints Market Revenues & Volume By Polyurethane Paints for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Paints Market Revenues & Volume By Acrylic Paints for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Paints Market Revenues & Volume By Alkyd Paints for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Paints Market Revenues & Volume By Base Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Paints Market Revenues & Volume By Solvent-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Paints Market Revenues & Volume By Water-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Paints Market Revenues & Volume By Powder-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Paints Market Revenues & Volume By Oil-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Paints Market Revenues & Volume By Coating Technology for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Paints Market Revenues & Volume By Spray Coating for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Paints Market Revenues & Volume By Roller Application for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Paints Market Revenues & Volume By Electrostatic Coating for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Paints Market Revenues & Volume By Brushing Application for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Paints Market Revenues & Volume By Application for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Paints Market Revenues & Volume By Equipment Protection for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Paints Market Revenues & Volume By Surface Finishing for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Paints Market Revenues & Volume By Decorative Finishing for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Paints Market Revenues & Volume By Metal Surfaces for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Paints Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Paints Market Revenues & Volume By Heavy Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Paints Market Revenues & Volume By Automotive for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Paints Market Revenues & Volume By Consumer Products for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Paints Market Revenues & Volume By Construction for the Period 2022 - 2032F
- China Industrial Paints Import Export Trade Statistics
- Market Opportunity Assessment By Paint Type
- Market Opportunity Assessment By Base Type
- Market Opportunity Assessment By Coating Technology
- Market Opportunity Assessment By Application
- Market Opportunity Assessment By End User Industry
- China Industrial Paints Top Companies Market Share
- China Industrial Paints Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Paints Company Profiles
- China Industrial Paints Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Paint Type
- Epoxy Paints
- Polyurethane Paints
- Acrylic Paints
- Alkyd Paints
By Base Type
- Solvent-Based
- Water-Based
- Powder-Based
- Oil-Based
By Coating Technology
- Spray Coating
- Roller Application
- Electrostatic Coating
- Brushing Application
By Application
- Equipment Protection
- Surface Finishing
- Decorative Finishing
- Metal Surfaces
By End User Industry
- Heavy Industry
- Automotive
- Consumer Products
- Construction































