China Industrial Process Control Market Size & Growth Rate
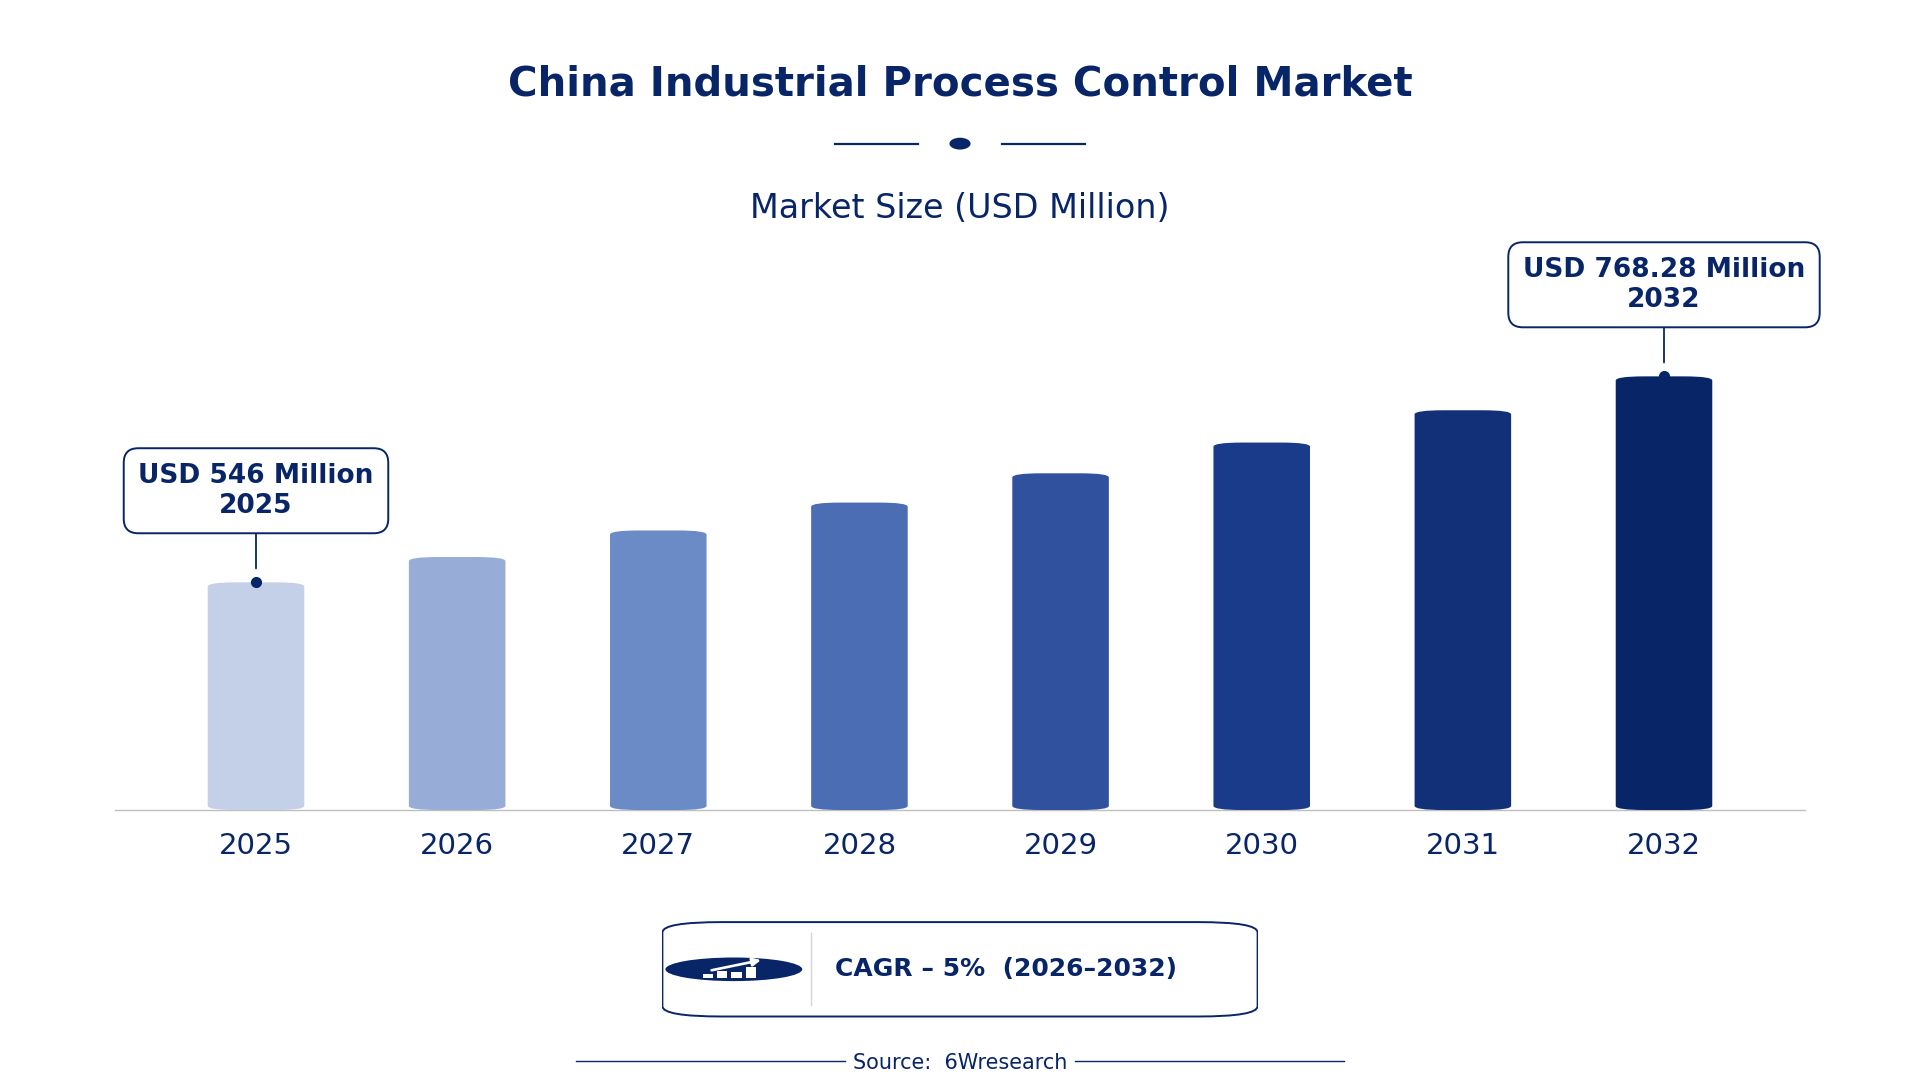
According to 6Wresearch internal database and industry insights, the China Industrial Process Control Market was valued at USD 546.0 million in 2025 and is projected to reach USD 768.28 million by 2032, growing at a CAGR of approximately 5% during 2026–2032.
China Industrial Process Control Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Process Control Market |
| Market Size 2025 | USD 546.0 million |
| Market Size 2032 | USD 768.28 million |
| Absolute Growth 2025–2032 | USD 222.28 million |
| CAGR 2026–2032 | 5% |
| Peak Annual Growth | 7.6% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Control Type, 2025 | PLC Systems (42% share) |
| Leading System Type, 2025 | Programmable Logic (52% share) |
| Leading Interface, 2025 | HMI (51% share) |
| Leading Application, 2025 | Automated Production (45% share) |
| Leading End User Industry, 2025 | Automotive (40% share) |
| Fastest-Growing Control Type | SCADA Systems (6.5% CAGR) |
| Fastest-Growing System Type | Supervisory (7.7% CAGR) |
| Fastest-Growing Interface | Remote Monitoring (7.2% CAGR) |
| Fastest-Growing Application | Utility Grid Management (6.6% CAGR) |
| Fastest-Growing End User Industry | Energy Sector (6.0% CAGR) |
| Growing Sector | Automotive |
| Key End Users | Manufacturers, Energy Providers, Chemical Processors, Automotive Companies |
China Industrial Process Control Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
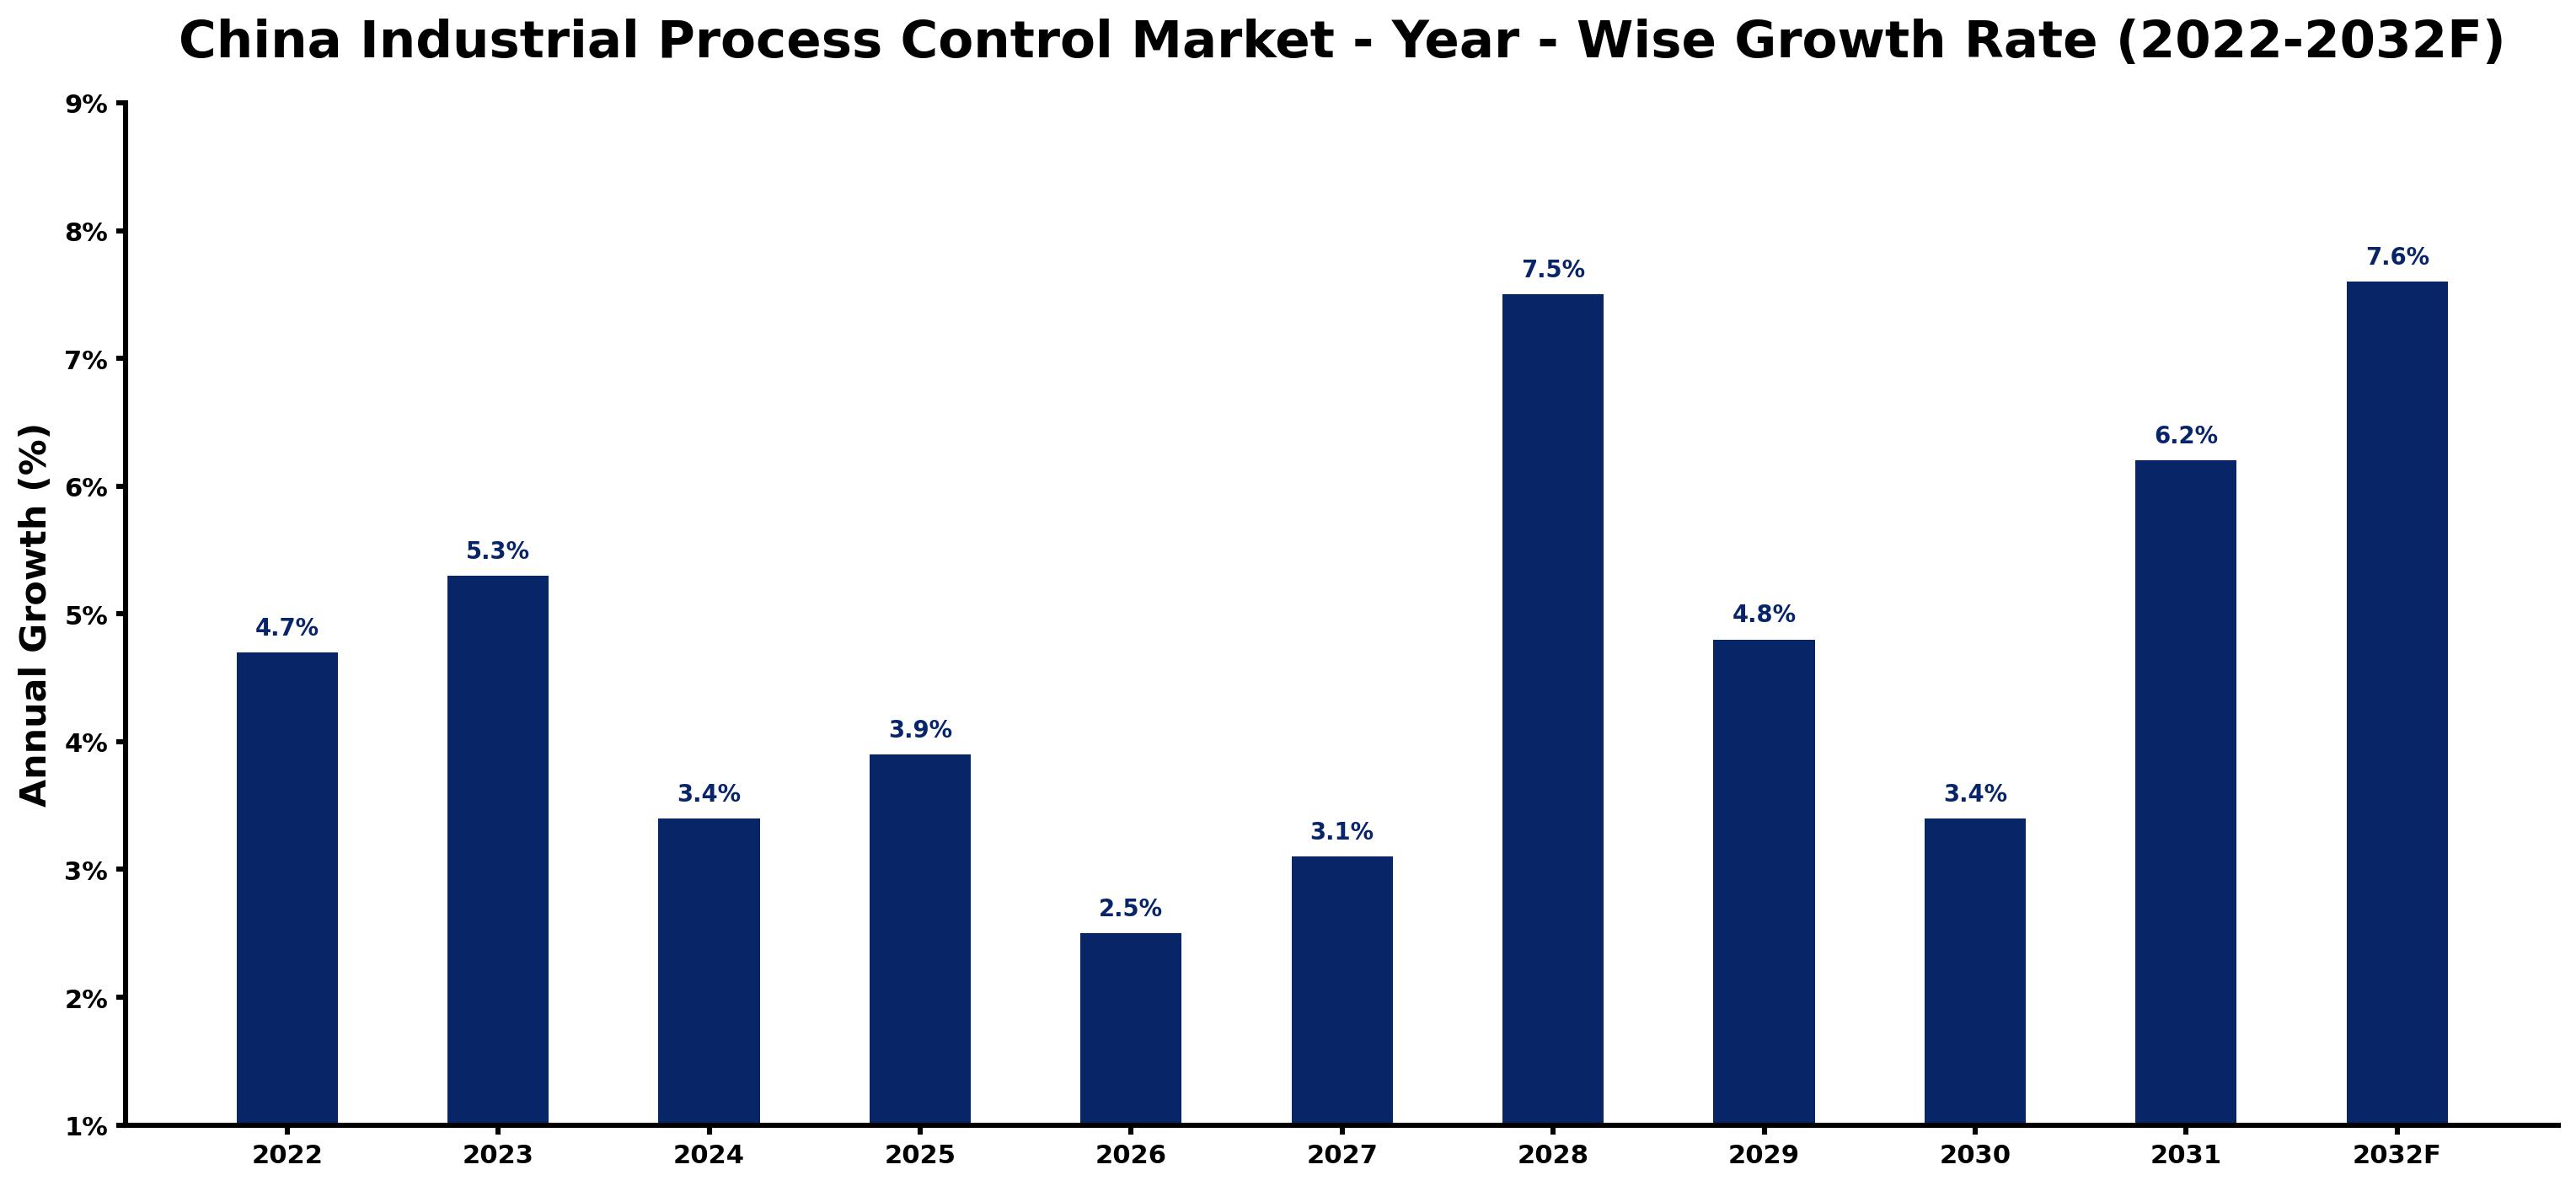
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.7 | The automotive industry produced over 26 million vehicles, driving demand for process control systems. |
| 2023 | 5.3 | Investment in smart grid technologies exceeded $100 billion, improving utility grid management capabilities. |
| 2024 | 3.4 | Growth slowed as the market adjusted to new automation standards in various sectors. |
| 2025 | 3.9 | The automotive sector projected a 20% increase in PLC systems usage, boosting demand for automation solutions. |
| 2026 | 2.5 | A slowdown is expected as the market faces challenges in integrating new technologies effectively. |
| 2027 | 3.1 | Demand will rise again as the energy sector adopts more SCADA systems for improved monitoring. |
| 2028 | 7.5 | The market is projected to experience a surge due to a 15% increase in SCADA system adoption in energy management. |
| 2029 | 4.8 | Growth will slow as industries face challenges in meeting updated automation standards. |
| 2030 | 3.4 | The market is expected to continue growing as manufacturers adapt to evolving process control technologies. |
| 2031 | 6.2 | A strong increase in demand will be driven by new standards for process control systems. |
| 2032 | 7.6 | The market is projected to peak as investments in automation reach new heights, particularly in energy management. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Process Control Market Synopsis
The China Industrial Process Control Market includes automated systems that optimise industrial operations, integrating hardware and software to enhance efficiency, safety, and energy management. Key sectors such as automotive and energy are driving demand, significantly impacting market growth. The market is expanding due to considerable investments in smart grid technologies and the 'Smart Manufacturing 2025' initiative, which promotes advanced automation. The automotive industry alone produced over 26 million vehicles in 2022, further increasing the need for process control solutions.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased investment in automation technologies | Driver | High | PLC Systems |
| Growing demand for energy efficiency in industrial operations | Driver | High | SCADA Systems |
| Rising need for advanced manufacturing solutions | Opportunity | High | DCS Systems |
| Expansion of the automotive sector requiring automation | Opportunity | High | Automated Production |
| Integration challenges with new technologies | Restraint | Medium | Programmable Logic |
| High costs associated with upgrading existing systems | Restraint | Medium | HMI |
| Limited skilled workforce for advanced automation | Challenge | High | Supervisory |
| Regulatory compliance costs for safety standards | Challenge | Medium | Centralized Control |
Evaluation of Drivers in China Industrial Process Control Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Investment in smart grid technologies exceeding $100 billion | SCADA Systems | This investment improves utility grid management, leading to increased purchases of SCADA systems by energy providers. |
| Projected 20% increase in PLC systems usage by 2025 | PLC Systems | This growth in the automotive sector drives demand for automation solutions, prompting manufacturers to invest in PLC systems. |
| Adoption of the 'Smart Manufacturing 2025' initiative | DCS Systems | This initiative encourages industries to adopt advanced automation, increasing purchases of DCS systems for complex operations. |
| Growing reliance on automated production in the automotive sector | Automated Production | As the automotive industry expands, the need for automated production systems rises, boosting demand for process control solutions. |
| Increased focus on energy efficiency in manufacturing | HMI | This focus drives manufacturers to invest in HMI systems for better operator interaction and process control. |
Growth in the Industrial Process Control market in China comes from substantial investments in smart grid technologies and rising end-use demand from key sectors. The energy sector's investment of over $100 billion improves utility grid management, leading to increased purchases of SCADA systems. The automotive industry is projected to see a 20% increase in PLC systems usage by 2025, driving demand for automation solutions. As industries focus on energy efficiency, investments in HMI systems are also rising, supporting overall market growth. The push for advanced manufacturing technologies further boosts the need for DCS systems, ensuring that manufacturers remain competitive in a rapidly evolving environment.
Evaluation of Restraints in China Industrial Process Control Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Integration challenges with new automation technologies | Programmable Logic | These challenges hinder the adoption of advanced systems, causing delays in purchases and implementations. |
| High costs associated with upgrading existing systems | HMI | These costs deter some manufacturers from investing in new technologies, limiting market growth. |
| Limited skilled workforce for advanced automation | Supervisory | A shortage of trained personnel affects the implementation of sophisticated process control systems, delaying projects. |
| Regulatory compliance costs for safety standards | Centralized Control | These costs can delay investments as companies navigate complex compliance requirements, affecting their operations. |
| Market saturation in certain sectors | DCS Systems | Saturation leads to slower growth as existing systems meet current demands, limiting new investments. |
China Industrial Process Control Market Challenges
The China Industrial Process Control Market faces several practical problems, beginning with fierce competition. Many producers find it challenging to differentiate themselves, leading to price wars that erode profit margins for suppliers. Buyers encounter rising costs due to rapid technological advancements, which can result in expenses of up to 15% for system upgrades. A skills shortage exacerbates these issues, as a lack of qualified personnel delays the implementation of advanced process control systems, pushing back project timelines for manufacturers. Compliance with over 300 established standards complicates operations, making it difficult for companies to ensure safety and efficiency.
Trends in the China Industrial Process Control Market
Several trends are reshaping the China Industrial Process Control Market; the most important are set out below.
- Shift towards Smart Manufacturing: The 'Smart Manufacturing 2025' initiative is driving a transition towards more automated and efficient manufacturing processes across China. This trend is evident as over 60% of industrial facilities have adopted automated production systems, improving productivity.
- Increasing Adoption of SCADA Systems: A notable rise in SCADA system adoption is occurring in the energy sector, with a reported 15% increase in 2023. This shift reflects the growing need for real-time monitoring and control of energy distribution, improving operational efficiency.
- Growth in Utility Grid Management: Utility grid management is evolving as the energy sector invests heavily in process control technologies. The sector's investment of over $100 billion in smart grid technologies clearly indicates this trend, enhancing overall system reliability.
- Expansion of Automation in Automotive Manufacturing: The automotive industry is increasingly adopting automation, with a projected 20% increase in PLC systems usage by 2025. This expansion highlights the sector's commitment to improving manufacturing efficiency and reducing operational costs.
Investment Opportunities in the China Industrial Process Control Market
Investors looking at the China Industrial Process Control Market should consider the following areas.
- Investment in Advanced Automation Solutions: There is an opportunity to supply advanced automation solutions, with the automotive sector projected to see a 20% increase in PLC systems usage by 2025. Entering through local partnerships can facilitate market entry and improve competitiveness.
- Supply of SCADA Systems for Energy Management: With a 15% increase in SCADA system adoption in the energy sector, suppliers can target this growing demand. Collaborating with energy providers can improve market penetration and service delivery.
- Development of DCS Systems for Chemical Processing: The chemical processing industry, valued at over $1 trillion, presents a promising opportunity for DCS systems. Establishing joint ventures with local manufacturers can aid in capturing this market and driving innovation.
- Provision of HMI Systems for Enhanced Interaction: As industries focus on energy efficiency, there is a growing need for HMI systems. Suppliers can enter the market by obtaining necessary certifications and partnering with local firms to improve their offerings.
Government Initiatives in the China Industrial Process Control Market
The 'Smart Manufacturing 2025' initiative by the Ministry of Industry and Information Technology aims to promote automation in manufacturing, encouraging the adoption of advanced process control technologies. This initiative has led to increased funding for automation projects, benefiting various industries reliant on process control systems. Additionally, the initiative supports compliance with new standards, improving operational efficiency across sectors. The program is expected to drive investments in automation, enhancing competitiveness in the industrial sector.
In 2021, the National Development and Reform Commission approved a $200 million subsidy program to support the adoption of advanced industrial automation solutions. This funding assists manufacturers in upgrading their systems to meet new standards. The program aims to improve overall efficiency and competitiveness in the industrial sector by facilitating technology adoption, allowing producers to enhance their operational capabilities.
Future Insight of the China Industrial Process Control Market
Several forward-looking factors should drive growth in the China Industrial Process Control Market over the coming years. The 'Smart Manufacturing 2025' initiative will enhance automation, improving operational efficiency for buyers across various sectors. By 2025, the automotive sector is projected to increase its use of advanced control systems by 20%, streamlining production processes. Investments exceeding $100 billion in smart grid technologies will improve utility management in the energy sector, benefiting both suppliers and consumers. The industrial automation market will witness increased adoption rates, reflecting a shift towards more integrated and efficient systems.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Control Type – PLC Systems Dominated, SCADA Systems Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, with a 42% revenue share in 2025, PLC Systems was the largest control type category. PLC systems dominate the market share due to their essential role in automating machinery and processes across various sectors. The automotive industry, which produced over 26 million vehicles in 2022, exemplifies the strong demand for these systems. SCADA Systems are set to record the highest CAGR in this split, 6.5% over 2026–2032. SCADA systems are experiencing rapid growth, particularly driven by a 15% increase in adoption within the energy sector, highlighting the need for effective real-time monitoring. As industries increasingly embrace automation, the demand for SCADA systems will continue to rise, reinforcing the lead of PLC systems. Suppliers should focus on enhancing PLC systems while also investing in SCADA technologies to align with the growing market demand.
By System Type – Programmable Logic Dominated, Supervisory Expected to Grow Fastest
The largest system type category in 2025 was Programmable Logic, with a 52% share of total revenue. Programmable Logic systems are fundamental to programmable automation solutions, making them the preferred choice for many manufacturers. Their extensive application across various industries contributes to a robust market share in China's industrial process control sector. The quickest growth will come from Supervisory, forecast to expand at a CAGR of 7.7% between 2026 and 2032. Supervisory systems are witnessing accelerated growth due to their critical function in overseeing and controlling industrial processes, particularly as automation becomes more prevalent. This trend indicates that Programmable Logic systems will maintain their lead as they adapt to the evolving supervisory landscape. Buyers should invest in Programmable Logic systems to future-proof their operations while monitoring advancements in Supervisory technologies.
By Interface – HMI Dominated, Remote Monitoring Expected to Grow Fastest
HMI took a 51% share of interface in 2025, more than any other category. HMI interfaces are vital for operator interaction with control systems, establishing their necessity in industrial environments. Their widespread integration across numerous facilities in China reinforces their dominant market share in the sector. Remote Monitoring is projected to grow fastest, at a CAGR of 7.2% during 2026–2032. Remote Monitoring interfaces are rapidly gaining traction as industries increasingly require management capabilities from a distance, especially in energy and manufacturing. This growth suggests that HMI systems will continue to thrive as they incorporate remote functionalities. Suppliers must prioritise the development of HMI solutions while exploring remote monitoring capabilities to meet evolving user demands.
By Application – Automated Production Dominated, Utility Grid Management Expected to Grow Fastest
Automated Production held a 45% share of the China Industrial Process Control Market by application in 2025. Automated Production is the primary application for process control systems, driven by the need for efficiency in manufacturing processes. The automotive sector's strong reliance on automation significantly supports the market share of this application. Over 2026–2032, Utility Grid Management is expected to post the fastest growth, at a CAGR of 6.6%. Utility Grid Management is emerging as the fastest-growing application, particularly due to substantial investments in smart grid technologies within the energy sector. This trend indicates that Automated Production will maintain its lead while adapting to the increasing complexity of utility management. Buyers should focus on integrating automated production systems while exploring solutions for utility grid management to optimise their operations.
By End User Industry – Automotive Dominated, Energy Sector Expected to Grow Fastest
Automotive accounted for a 40% market share by end user industry in 2025. The automotive industry is a key user of process control technologies, extensively employing them to enhance manufacturing efficiency. With over 26 million vehicles produced in 2022, this sector commands a significant market share in the industrial process control landscape. Energy Sector is set to record the highest CAGR in this split, 6.0% over 2026–2032. The energy sector is rapidly adopting process control technologies, driven by investments in smart grid solutions and a focus on energy efficiency. This growth suggests that the automotive sector will continue to lead while adapting to the energy sector's increasing technological demands. Suppliers should tailor their offerings to meet the specific needs of the automotive industry while also considering the emerging requirements of the energy sector.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Process Control Market Outlook
- Market Size of China Industrial Process Control Market, 2025
- Forecast of China Industrial Process Control Market, 2032
- Historical Data and Forecast of China Industrial Process Control Revenues & Volume for the Period 2022 - 2032F
- China Industrial Process Control Market Trend Evolution
- China Industrial Process Control Market Drivers and Challenges
- China Industrial Process Control Price Trends
- China Industrial Process Control Porter's Five Forces
- China Industrial Process Control Industry Life Cycle
- Historical Data and Forecast of China Industrial Process Control Market Revenues & Volume By Control Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Control Market Revenues & Volume By PLC Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Control Market Revenues & Volume By SCADA Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Control Market Revenues & Volume By DCS Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Control Market Revenues & Volume By Loop Controllers for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Control Market Revenues & Volume By System Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Control Market Revenues & Volume By Programmable Logic for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Control Market Revenues & Volume By Supervisory for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Control Market Revenues & Volume By Distributed for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Control Market Revenues & Volume By Analog/Digital for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Control Market Revenues & Volume By Interface for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Control Market Revenues & Volume By HMI for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Control Market Revenues & Volume By Remote Monitoring for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Control Market Revenues & Volume By Centralized Control for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Control Market Revenues & Volume By PID Interface for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Control Market Revenues & Volume By Application for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Control Market Revenues & Volume By Automated Production for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Control Market Revenues & Volume By Utility Grid Management for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Control Market Revenues & Volume By Chemical Processing for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Control Market Revenues & Volume By Temperature/Flow Control for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Control Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Control Market Revenues & Volume By Automotive for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Control Market Revenues & Volume By Energy Sector for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Control Market Revenues & Volume By Chemicals and Materials for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Control Market Revenues & Volume By Metal Industry for the Period 2022 - 2032F
- China Industrial Process Control Import Export Trade Statistics
- Market Opportunity Assessment By Control Type
- Market Opportunity Assessment By System Type
- Market Opportunity Assessment By Interface
- Market Opportunity Assessment By Application
- Market Opportunity Assessment By End User Industry
- China Industrial Process Control Top Companies Market Share
- China Industrial Process Control Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Process Control Company Profiles
- China Industrial Process Control Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Control Type
- PLC Systems
- SCADA Systems
- DCS Systems
- Loop Controllers
By System Type
- Programmable Logic
- Supervisory
- Distributed
- Analog/Digital
By Interface
- HMI
- Remote Monitoring
- Centralized Control
- PID Interface
By Application
- Automated Production
- Utility Grid Management
- Chemical Processing
- Temperature/Flow Control
By End User Industry
- Automotive
- Energy Sector
- Chemicals and Materials
- Metal Industry































