China Industrial Process Oils Market Size & Growth Rate
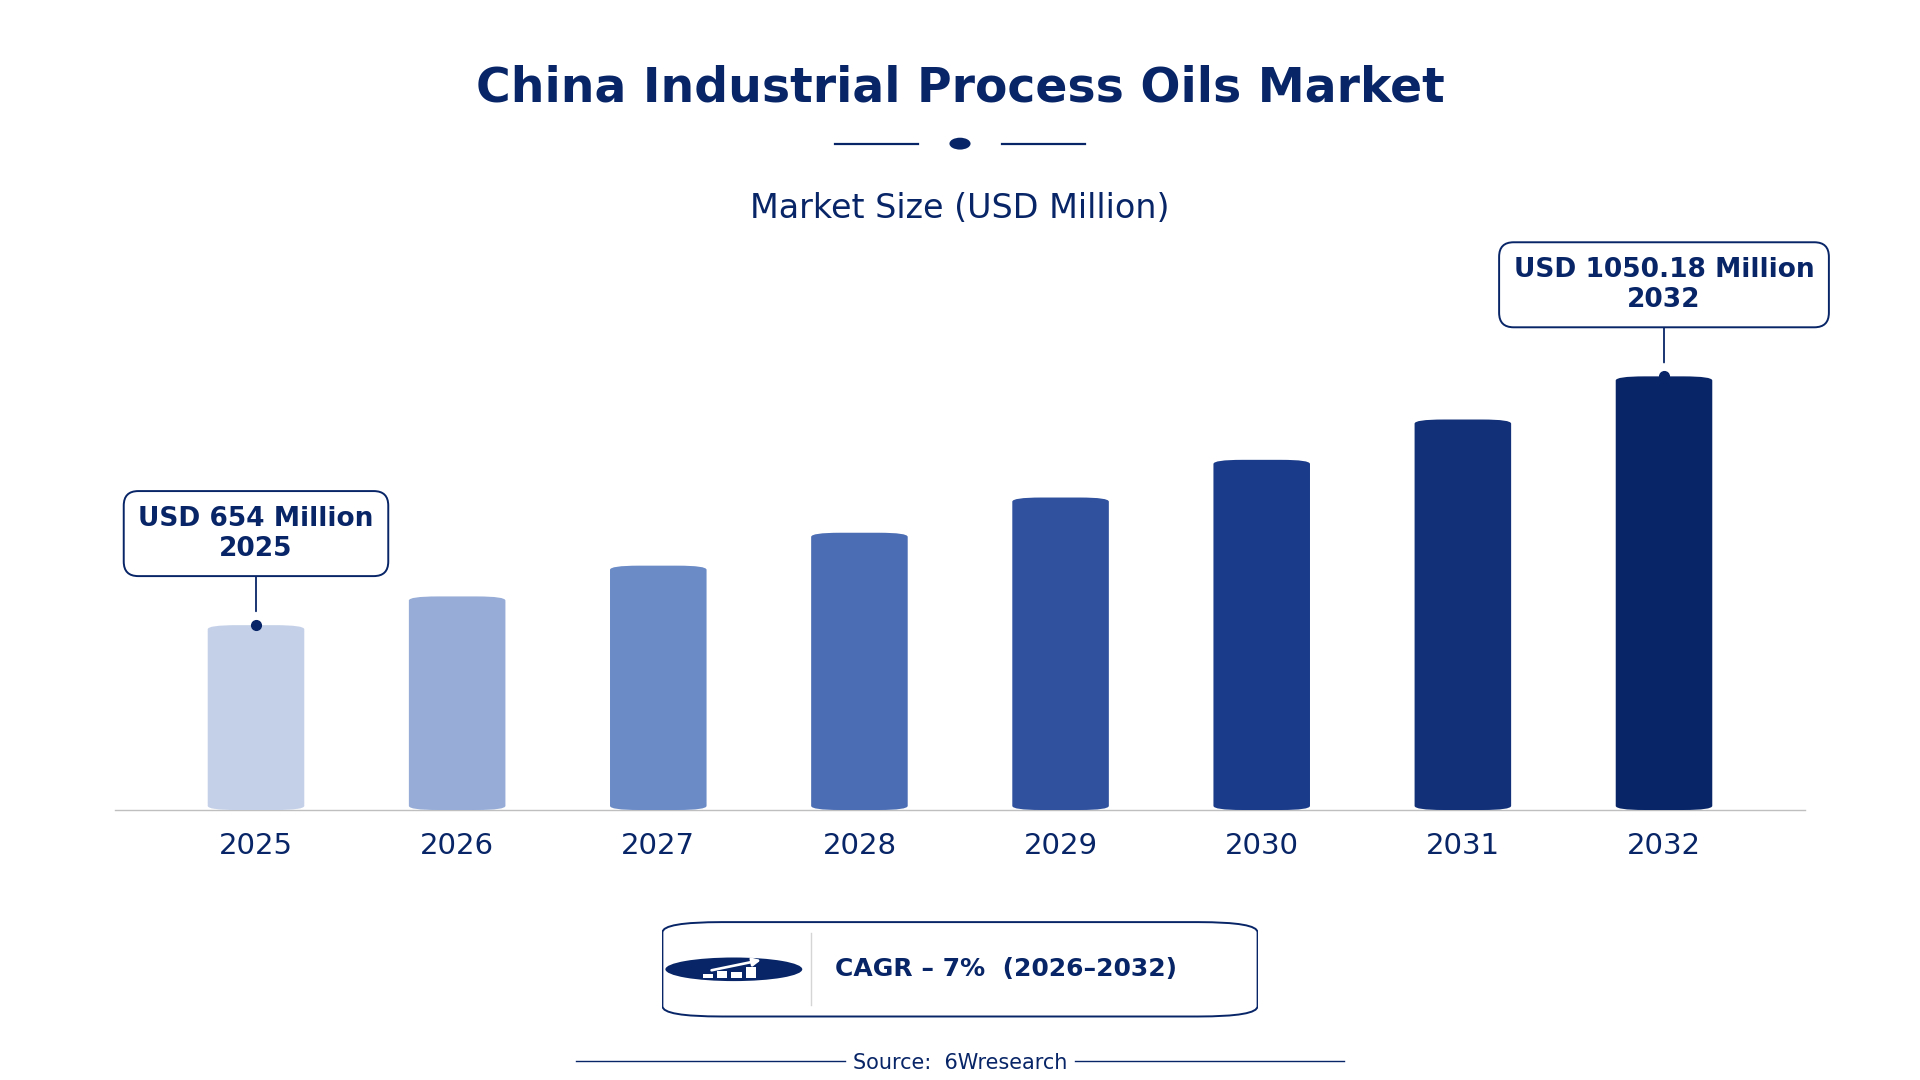
According to 6Wresearch internal database and industry insights, the China Industrial Process Oils Market was valued at USD 654.0 million in 2025 and is projected to reach USD 1,050.18 million by 2032, growing at a CAGR of approximately 7% during 2026–2032.
China Industrial Process Oils Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Process Oils Market |
| Market Size 2025 | USD 654.0 million |
| Market Size 2032 | USD 1,050.18 million |
| Absolute Growth 2025–2032 | USD 396.18 million |
| CAGR 2026–2032 | 7% |
| Peak Annual Growth | 9.7% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Oil Type, 2025 | Paraffinic Oils (39% share) |
| Leading Source Type, 2025 | Petroleum-Based (50% share) |
| Leading Viscosity Grade, 2025 | Medium (40% share) |
| Leading Application, 2025 | Rubber Processing (41% share) |
| Leading End User Industry, 2025 | Automotive (43% share) |
| Fastest-Growing Oil Type | Bio-Based Oils (8.3% CAGR) |
| Fastest-Growing Source Type | Plant-Based (9.4% CAGR) |
| Fastest-Growing Viscosity Grade | Low (9.0% CAGR) |
| Fastest-Growing Application | Eco-Friendly Additives (8.8% CAGR) |
| Fastest-Growing End User Industry | Chemicals and Materials (8.6% CAGR) |
| Growing Sector | Automotive |
| Key End Users | Automotive, Textile Manufacturing, Chemicals and Materials, Rubber Processing |
China Industrial Process Oils Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
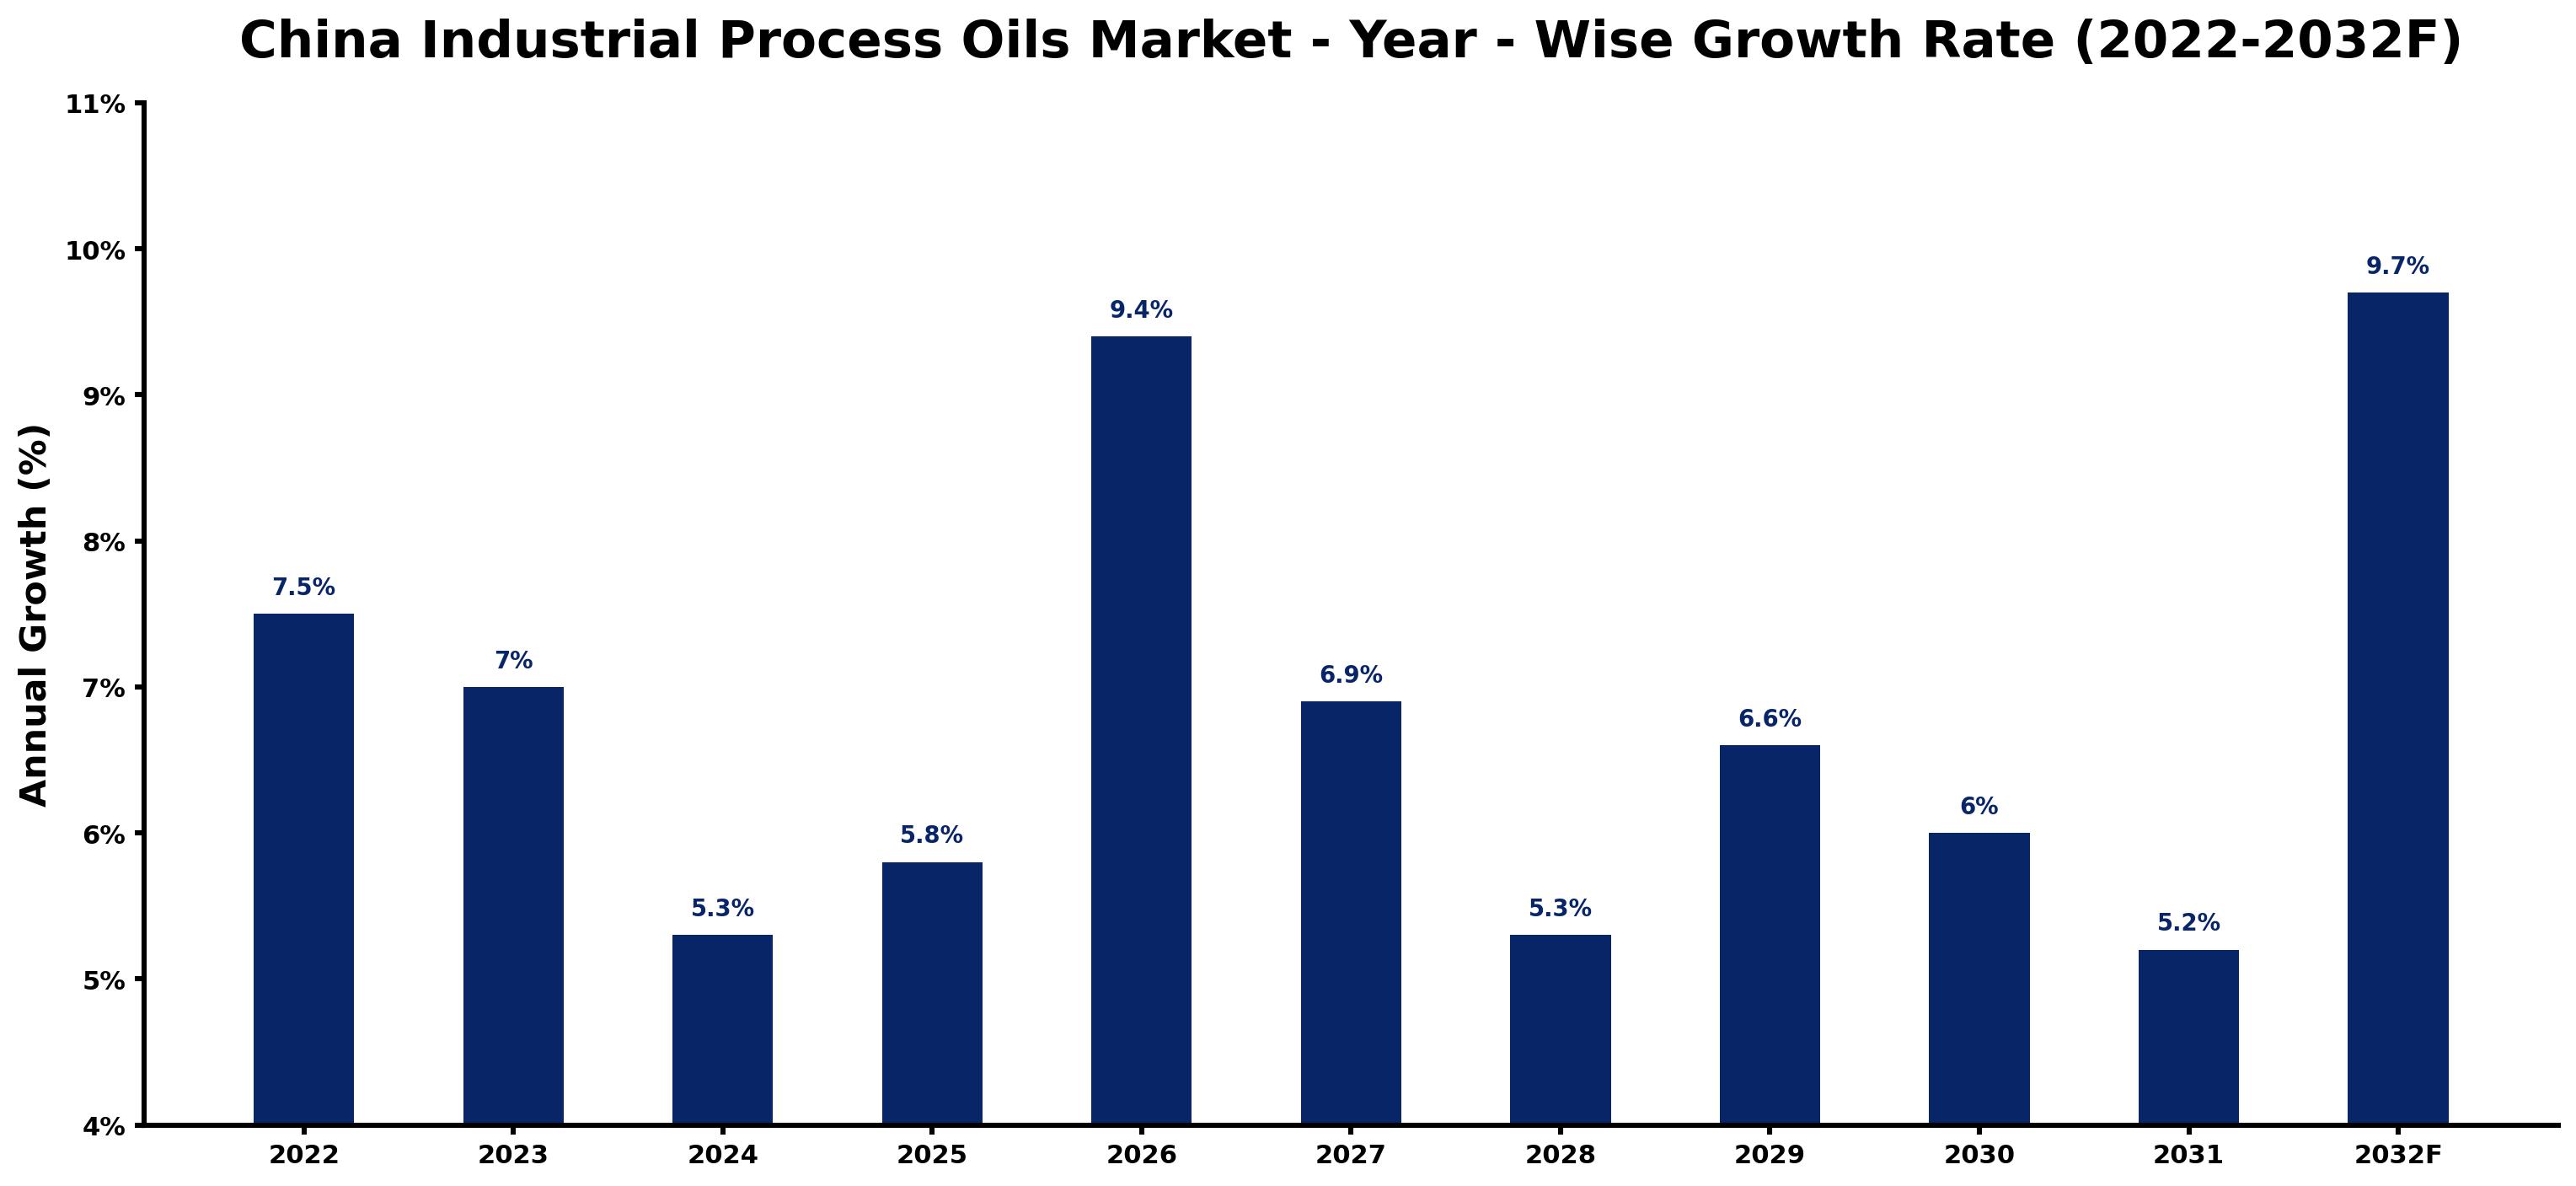
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.5 | The market experienced strong demand from the automotive sector, which accounted for a large portion of consumption. |
| 2023 | 7.0 | Demand growth slowed as the automotive sector faced temporary production challenges due to supply chain issues. |
| 2024 | 5.3 | The textile manufacturing industry continued to drive demand, albeit at a slower pace than previous years. |
| 2025 | 5.8 | An increase in production capacity in the automotive sector led to a rebound in demand for industrial process oils. |
| 2026 | 9.4 | The introduction of eco-friendly additives is expected to spur demand growth across various applications, particularly in rubber processing. |
| 2027 | 6.9 | The automotive sector's growth will face constraints from rising raw material costs, impacting overall demand. |
| 2028 | 5.3 | Demand growth is projected to slow as the market adjusts to new environmental regulations affecting production. |
| 2029 | 6.6 | A resurgence in the chemicals and materials sector is expected to contribute to an uptick in demand for industrial process oils. |
| 2030 | 6.0 | The textile manufacturing industry is projected to begin recovering, boosting demand for naphthenic oils used in production. |
| 2031 | 5.2 | The market will experience a slowdown as the automotive industry faces challenges from changing consumer preferences. |
| 2032 | 9.7 | The peak growth year will be driven by increased investments in eco-friendly production practices and rising demand from multiple sectors. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Process Oils Market Synopsis
Industrial Process Oils in China are petroleum-derived fluids used in various industrial applications, including rubber processing and textile manufacturing. These oils are produced through refining crude oil and can be tailored for specific uses. The China Industrial Process Oils Market is growing due to strong demand from the automotive sector, which accounts for 30% of total consumption. The textile manufacturing industry is a major user, with over 1,000 mills operating. The introduction of eco-friendly additives under the Green Manufacturing Program is driving demand.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Strong demand from the automotive sector drives consumption. | Driver | High | Automotive |
| The introduction of eco-friendly additives presents new opportunities. | Opportunity | High | Eco-Friendly Additives |
| Increasing production in the textile manufacturing industry supports growth. | Driver | High | Textile Manufacturing |
| The growing chemicals and materials sector creates demand for industrial oils. | Opportunity | High | Chemicals and Materials |
| Rising raw material costs constrain market growth. | Restraint | Medium | Petroleum-Based |
| Environmental regulations impose stricter quality controls on production. | Restraint | High | Naphthenic Oils |
| Supply chain disruptions in the automotive sector hinder growth. | Challenge | High | Automotive |
| Competition from bio-based oils challenges traditional petroleum-based products. | Challenge | Medium | Bio-Based Oils |
Evaluation of Drivers in China Industrial Process Oils Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased automotive production | Automotive | Rising vehicle manufacturing in China drives demand for lubricants, with the automotive sector accounting for 30% of total consumption. |
| Expansion of textile manufacturing | Textile Manufacturing | The presence of over 1,000 textile mills in China increases the need for naphthenic oils, essential for fabric production. |
| Growth in chemicals and materials sector | Chemicals and Materials | The rapid expansion of the chemicals sector boosts the demand for industrial process oils used in various chemical products. |
| Adoption of eco-friendly additives | Eco-Friendly Additives | The Green Manufacturing Program promotes the use of sustainable practices, increasing demand for bio-based oils and eco-friendly additives. |
| Rising printing and packaging industry | Printing & Packaging | The projected growth in the printing and packaging industry enhances the need for aromatic oils, vital for ink formulation. |
Expansion of the Industrial Process Oils market in China is supported by rising investment in automotive production and increasing end-use demand from various sectors. The automotive sector accounts for a large share of total consumption, driving the need for lubricants. The textile manufacturing industry, with over 1,000 operational mills, relies heavily on naphthenic oils for production. The chemicals and materials sector is growing rapidly, increasing the need for industrial process oils.
Evaluation of Restraints in China Industrial Process Oils Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Rising raw material costs impact production expenses. | Petroleum-Based | Increased costs for crude oil affect the pricing of petroleum-based industrial process oils. |
| Stricter environmental regulations impose compliance costs. | Naphthenic Oils | The updated National Standard for Industrial Process Oils requires adherence to stricter quality controls. |
| Supply chain disruptions affect automotive production schedules. | Automotive | Recent global supply chain issues have delayed automotive manufacturing, impacting oil demand. |
| Competition from bio-based oils limits market share for traditional oils. | Bio-Based Oils | Bio-based oils are gaining traction under the Sustainable Development Strategy, affecting petroleum-based products. |
| Market saturation in certain applications limits growth potential. | Rubber Processing | The rubber processing sector is facing saturation, slowing demand for industrial process oils. |
China Industrial Process Oils Market Challenges
The China Industrial Process Oils market faces high technology costs that burden producers as they invest in advanced refining processes. This investment is crucial due to the need for improved oil quality, resulting in a 15% increase in production expenses over the past year. Distributors experience fluctuating raw material prices, which can raise costs by up to 20%, complicating supply chain management. Skills shortages in the workforce hinder production efficiency, causing delays that can extend lead times by several weeks for buyers in the automotive sector. Buyers also face inconsistent supply, impacting production schedules and raising operational costs.
Trends in the China Industrial Process Oils Market
Below mentioned are some of the trends shaping the China Industrial Process Oils Market growth.
- Shift towards Eco-Friendly Additives in Industrial Processes: China is increasingly adopting eco-friendly additives in industrial processes, driven by the Green Manufacturing Program. This initiative aims to promote sustainability in manufacturing, with a projected increase in demand for eco-friendly products by 20%.
- Growth of the Chemicals and Materials Sector: The chemicals and materials sector is expanding rapidly, significantly increasing the demand for industrial process oils. With a growth rate of 8% projected for 2023, this sector is a key driver for oil consumption.
- Rising Demand for Naphthenic Oils in Textiles: Textile manufacturing in China is projected to grow, leading to increased demand for naphthenic oils. With over 1,000 textile mills, this sector is vital for oil consumption, contributing to a 10% increase in demand.
- Expansion of Rubber Processing Facilities: The rubber processing industry is expanding with new facilities being established across China. This growth is expected to boost demand for industrial process oils by 15% over the next two years.
Investment Opportunities in the China Industrial Process Oils Market
Below are the investment opportunities with the strongest case in the China Industrial Process Oils Market.
- Joint Ventures for Eco-Friendly Oil Production: Partnerships with local firms can facilitate entry into the eco-friendly oil market, which is projected to grow by 20%. Collaborating with automotive manufacturers can improve product offerings.
- Investment in Textile Manufacturing Facilities: With over 1,000 textile mills, investing in production facilities can meet rising demand. Establishing a local presence in regions like Jiangsu can enhance market access.
- Expansion into Bio-Based Oils: The market for bio-based oils is on the rise, with significant growth potential. Targeting automotive and textile sectors for bio-based oil applications can yield substantial returns.
- Development of New Rubber Processing Technologies: Investing in innovative rubber processing technologies can capture market share. The automotive sector's demand for advanced lubricants presents a lucrative opportunity.
Government Initiatives in the China Industrial Process Oils Market
The National Standard for Industrial Process Oils, updated in 2022, imposes stricter environmental regulations and quality controls, impacting producers. This measure ensures that industrial process oils meet safety and environmental standards, thereby enhancing consumer confidence and marketability. Compliance with these standards is essential for manufacturers to maintain their market position and avoid penalties. The Green Manufacturing Program, launched in 2021, promotes eco-friendly practices in the production of industrial oils, encouraging companies to adopt sustainable methods and practices.
In 2023, the State Administration for Market Regulation introduced guidelines for labeling industrial oils, improving consumer awareness and ensuring transparency in the market. The Ministry of Industry and Information Technology oversees the implementation of the Green Manufacturing Program, which has a budget of 500 million yuan to support eco-friendly initiatives. This funding aims to assist companies transitioning to bio-based oils, fostering innovation and sustainability in the sector. These measures collectively enhance the regulatory framework for industrial process oils, promoting responsible production and consumption.
Future Insight of the China Industrial Process Oils Market
By 2032, transformative changes will reshape the China Industrial Process Oils market, driven by the Green Manufacturing Program promoting eco-friendly additives. The ISO 6743-99 standard will ensure consistent product quality and safety, fostering consumer trust. The push for bio-based oils under the Sustainable Development Strategy will broaden product offerings, allowing suppliers to meet evolving market needs more effectively.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Oil Type – Paraffinic Oils Dominated, Bio-Based Oils Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, in 2025, Paraffinic Oils led the oil type split with a 39% share. Paraffinic oils dominate the market share in China because they are extensively utilised in rubber processing and as lubricants across various industries. Their broad application ensures a steady demand from manufacturers who rely on these oils for efficient operations. Over 2026–2032, Bio-Based Oils are expected to post the fastest growth, at a CAGR of 8.3%. Bio-based oils are experiencing rapid growth, spurred by the 'Sustainable Development Strategy' initiated in 2021, which encourages the adoption of eco-friendly alternatives. This increasing focus on sustainability is attracting interest from environmentally conscious buyers, further driving the market forward. Suppliers must prioritise the development of bio-based oils to align with the growing demand for sustainable solutions in the industrial process oils market.
By Source Type – Petroleum-Based Dominated, Plant-Based Expected to Grow Fastest
Petroleum-Based took a 50% share of source type in 2025, more than any other category. Petroleum-based oils dominate the market share in China as they are the primary source for industrial process oils, widely utilised across various applications. Their established supply chain and production capabilities ensure a steady flow to meet industrial needs. Plant-Based is projected to grow fastest, at a CAGR of 9.4% during 2026–2032. Plant-based oils are gaining traction, particularly as industries seek greener alternatives, spurred by government initiatives promoting eco-friendly practices. This growing interest indicates a shift in consumer preferences towards sustainable sourcing. Buyers may increasingly seek plant-based options, prompting suppliers to diversify their offerings to include more sustainable sources.
By Viscosity Grade – Medium Dominated, Low Expected to Grow Fastest
The largest viscosity grade category in 2025 was Medium, with a 40% share of total revenue. Medium viscosity oils dominate the market share in China due to their adaptability across various industrial applications. Their balanced characteristics make them a reliable choice for manufacturers, ensuring widespread usage in processes like rubber and textile production. Low is set to record the highest CAGR in this split, 9.0% over 2026–2032. Low viscosity oils are experiencing rapid growth as they cater to specific applications requiring reduced viscosity, driven by advancements in technology and changing industrial preferences. This trend indicates a shift towards more tailored oil solutions, allowing suppliers to capture niche markets. Suppliers should enhance their low viscosity oil product lines to align with the growing demand for specialised industrial applications.
By Application – Rubber Processing Dominated, Eco-Friendly Additives Expected to Grow Fastest
Rubber Processing accounted for a 41% market share by application in 2025. Rubber processing is the leading application for industrial process oils in China, holding a substantial market share due to its critical role in manufacturing rubber products. The automotive sector's reliance on rubber components further boosts this segment's demand. The quickest growth will come from Eco-Friendly Additives, forecast to expand at a CAGR of 8.8% between 2026 and 2032. Eco-friendly additives are emerging as a fast-growing application, spurred by the government's push for sustainable manufacturing practices. As industries adopt greener processes, this segment is expected to gain more traction in the coming years. Suppliers should invest in developing eco-friendly additives to align with the market's shift towards sustainability and meet regulatory demands.
By End User Industry – Automotive Dominated, Chemicals and Materials Expected to Grow Fastest
Automotive held a 43% share of the China Industrial Process Oils Market by end user industry in 2025. The automotive sector commands the largest market share of industrial process oils in China, primarily due to its extensive lubrication requirements across various vehicle types. This sector's robust growth directly influences the demand for a wide array of oil types essential for vehicle performance. Over 2026–2032, Chemicals and Materials are expected to post the fastest growth, at a CAGR of 8.6%. The chemicals and materials sector is rapidly expanding, leading to a surge in demand for industrial process oils crucial for the production of diverse chemical products. This growth presents significant opportunities for suppliers to penetrate a lucrative and evolving market segment. Suppliers should strategically target the chemicals and materials sector to capitalise on its growth potential and improve their market share in the industrial process oils market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Process Oils Market Outlook
- Market Size of China Industrial Process Oils Market, 2025
- Forecast of China Industrial Process Oils Market, 2032
- Historical Data and Forecast of China Industrial Process Oils Revenues & Volume for the Period 2022 - 2032F
- China Industrial Process Oils Market Trend Evolution
- China Industrial Process Oils Market Drivers and Challenges
- China Industrial Process Oils Price Trends
- China Industrial Process Oils Porter's Five Forces
- China Industrial Process Oils Industry Life Cycle
- Historical Data and Forecast of China Industrial Process Oils Market Revenues & Volume By Oil Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Oils Market Revenues & Volume By Paraffinic Oils for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Oils Market Revenues & Volume By Naphthenic Oils for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Oils Market Revenues & Volume By Aromatic Oils for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Oils Market Revenues & Volume By Bio-Based Oils for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Oils Market Revenues & Volume By Source Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Oils Market Revenues & Volume By Mineral-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Oils Market Revenues & Volume By Petroleum-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Oils Market Revenues & Volume By Petroleum-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Oils Market Revenues & Volume By Plant-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Oils Market Revenues & Volume By Viscosity Grade for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Oils Market Revenues & Volume By Medium for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Oils Market Revenues & Volume By Low for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Oils Market Revenues & Volume By High for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Oils Market Revenues & Volume By Variable for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Oils Market Revenues & Volume By Application for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Oils Market Revenues & Volume By Rubber Processing for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Oils Market Revenues & Volume By Textile Manufacturing for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Oils Market Revenues & Volume By Ink & Adhesive Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Oils Market Revenues & Volume By Eco-Friendly Additives for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Oils Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Oils Market Revenues & Volume By Automotive for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Oils Market Revenues & Volume By Consumer Staples for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Oils Market Revenues & Volume By Printing & Packaging for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Process Oils Market Revenues & Volume By Chemicals and Materials for the Period 2022 - 2032F
- China Industrial Process Oils Import Export Trade Statistics
- Market Opportunity Assessment By Oil Type
- Market Opportunity Assessment By Source Type
- Market Opportunity Assessment By Viscosity Grade
- Market Opportunity Assessment By Application
- Market Opportunity Assessment By End User Industry
- China Industrial Process Oils Top Companies Market Share
- China Industrial Process Oils Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Process Oils Company Profiles
- China Industrial Process Oils Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Oil Type
- Paraffinic Oils
- Naphthenic Oils
- Aromatic Oils
- Bio-Based Oils
By Source Type
- Mineral-Based
- Petroleum-Based
- Plant-Based
By Viscosity Grade
- Medium
- Low
- High
- Variable
By Application
- Rubber Processing
- Textile Manufacturing
- Ink & Adhesive Industry
- Eco-Friendly Additives
By End User Industry
- Automotive
- Consumer Staples
- Printing & Packaging
- Chemicals and Materials































