China Industrial Resin Market Size & Growth Rate
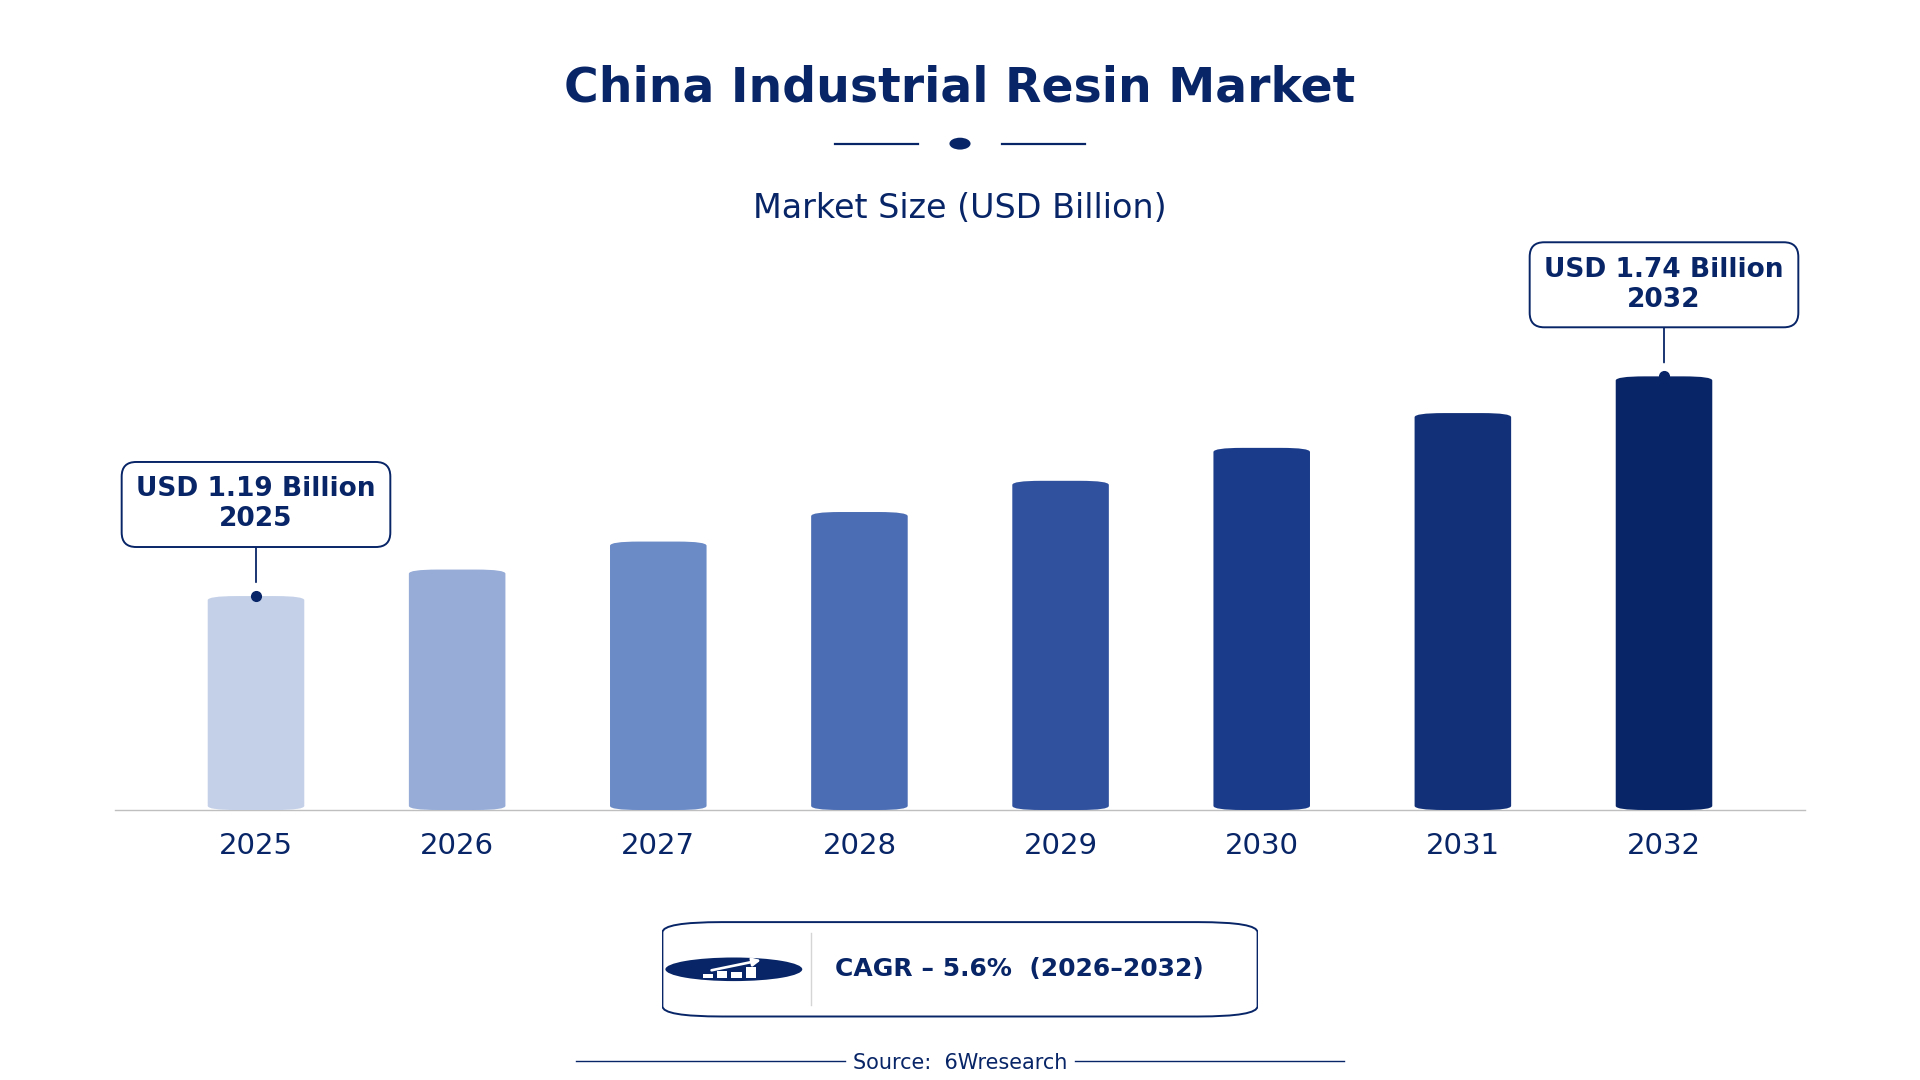
According to 6Wresearch internal database and industry insights, the China Industrial Resin Market was valued at USD 1.19 billion in 2025 and is projected to reach USD 1.74 billion by 2032, growing at a CAGR of approximately 5.6% during 2026–2032.
China Industrial Resin Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Resin Market |
| Market Size 2025 | USD 1.19 billion |
| Market Size 2032 | USD 1.74 billion |
| Absolute Growth 2025–2032 | USD 0.55 billion |
| CAGR 2026–2032 | 5.6% |
| Peak Annual Growth | 6.8% in 2029 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Resin Type, 2025 | Epoxy Resin (46% share) |
| Leading Base Material, 2025 | Thermosetting (51% share) |
| Leading Form, 2025 | Liquid (49% share) |
| Leading Application, 2025 | Adhesives & Sealants (41% share) |
| Leading End User Industry, 2025 | Automotive (41% share) |
| Fastest-Growing Resin Type | Polyurethane Resin (8.3% CAGR) |
| Fastest-Growing Base Material | Polyol & Isocyanate (6.7% CAGR) |
| Fastest-Growing Form | Foam (7.0% CAGR) |
| Fastest-Growing Application | Coatings & Insulation (7.0% CAGR) |
| Fastest-Growing End User Industry | Construction (6.7% CAGR) |
| Growing Sector | Construction |
| Key End Users | Automotive, Construction, Packaging, Marine & Aerospace |
China Industrial Resin Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
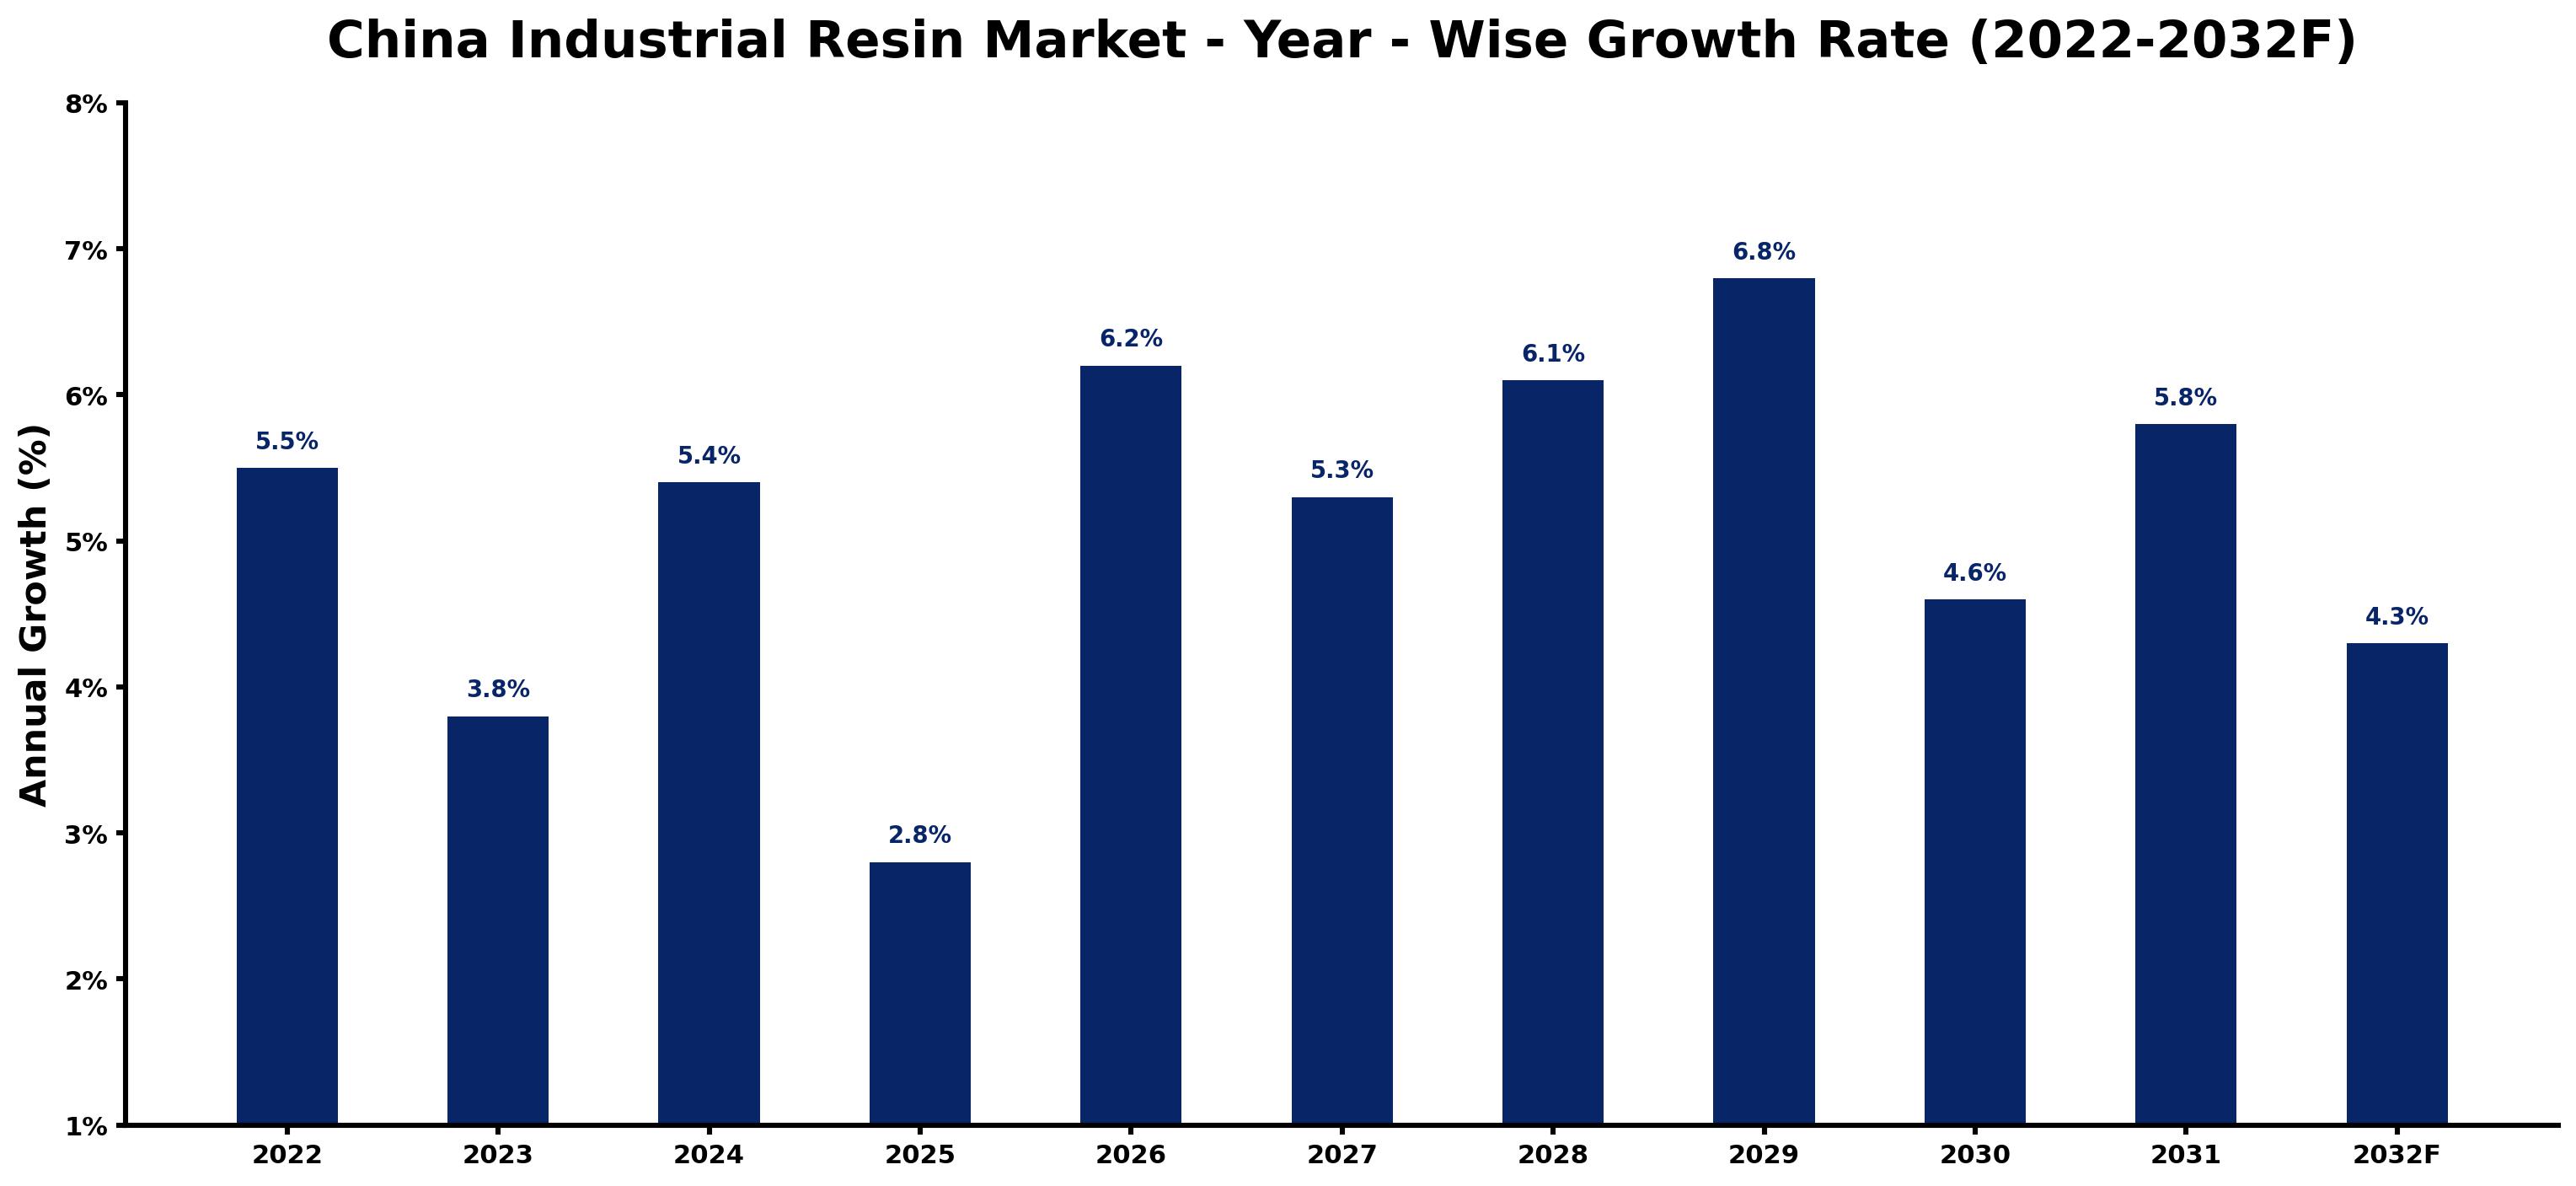
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.5 | The automotive industry continued to be the largest consumer of industrial resins, driving demand. |
| 2023 | 3.8 | Demand growth slowed as the construction sector faced challenges in project initiation. |
| 2024 | 5.4 | The automotive sector's recovery led to increased resin consumption, boosting market growth. |
| 2025 | 2.8 | A slowdown in growth was observed as the market adjusted to changing demand patterns. |
| 2026 | 6.2 | The introduction of advanced resin technologies is expected to spur increased investment and demand. |
| 2027 | 5.3 | Demand for eco-friendly resins is projected to grow, influencing purchasing decisions in various sectors. |
| 2028 | 6.1 | The construction industry's expansion will lead to higher consumption of industrial resins. |
| 2029 | 6.8 | A peak in growth is expected as the automotive sector ramps up production and demand. |
| 2030 | 4.6 | Growth is anticipated to decelerate as the automotive sector faces increased competition. |
| 2031 | 5.8 | Increased demand for sustainable materials will revitalise interest in industrial resins. |
| 2032 | 4.3 | The market is expected to stabilise as industries adapt to new environmental regulations. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Resin Market Synopsis
Industrial resin in China refers to synthetic polymers used in coatings, adhesives, and composite materials. These resins are produced through chemical reactions and are essential for durable goods and construction applications. The China Industrial Resin Market is growing due to strong demand from the automotive sector, which accounted for approximately 30% of total consumption in 2022, and the construction sector, projected to consume around 25% of the total market in 2023. The 'New Materials Industry Development Plan' launched in 2023 is driving investment in advanced resin technologies, further supporting market growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing demand from the automotive sector for durable components and coatings. | Driver | High | Automotive |
| Increased investment in eco-friendly resin production methods. | Driver | High | Polyurethane Resin |
| Expansion of the construction sector creating a need for adhesives and sealants. | Opportunity | High | Construction |
| Rising demand for acrylic and polyester resins in the packaging industry. | Opportunity | Medium | Packaging & Printing |
| Environmental regulations impacting production methods and material choices. | Restraint | High | Acrylic Resin |
| Market saturation in certain resin types leading to competitive pressures. | Restraint | Medium | Epoxy Resin |
| The Industrial Resin Market in China faces challenges from fluctuating raw material prices. | Challenge | High | Epoxy Resin |
| Supply chain disruptions affecting the timely availability of resins. | Challenge | Medium | Epoxy Resin |
Evaluation of Drivers in China Industrial Resin Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased production of automotive components requiring durable resins. | Automotive | The automotive industry accounted for approximately 30% of total demand in 2022. |
| Growing adoption of eco-friendly production methods among manufacturers. | Polyurethane Resin | The National Development and Reform Commission supports eco-friendly resin production methods. |
| Rising construction activities leading to higher demand for adhesives. | Construction | The construction sector is projected to consume around 25% of the total industrial resin market in 2023. |
| Expansion of the packaging industry driving demand for acrylic resins. | Packaging & Printing | The packaging industry is expected to grow, increasing demand for acrylic and polyester resins. |
| Technological advancements in resin production improving product quality. | Epoxy Resin | ISO 9001 is widely adopted among resin manufacturers, ensuring quality management. |
Growth in the Industrial Resin market in China comes from rising demand in the automotive and construction sectors, which are major consumers of these materials. The automotive industry accounted for approximately 30% of total demand in 2022, resulting in increased production of durable components. The construction sector is projected to consume around 25% of the total market in 2023, driving further demand for adhesives and sealants. Support for eco-friendly production methods is influencing manufacturers to adopt sustainable practices. The packaging industry is experiencing growth, increasing the need for acrylic and polyester resins.
Evaluation of Restraints in China Industrial Resin Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Fluctuating raw material prices affecting production costs. | Epoxy Resin | Volatility in raw material prices can increase costs for manufacturers. |
| Environmental regulations requiring compliance can limit production capabilities. | Acrylic Resin | Manufacturers must adapt to stringent environmental regulations, impacting production timelines. |
| Market saturation in certain resin segments leading to increased competition. | Polyester Resin | High competition in the polyester resin market pressures profit margins. |
| Supply chain disruptions affecting timely resin availability. | Epoxy Resin | Disruptions in supply chains can delay production schedules and increase costs. |
| Technological barriers for small manufacturers in adopting new methods. | Polyurethane Resin | Smaller manufacturers may struggle to invest in advanced production technologies. |
China Industrial Resin Market Challenges
The China Industrial Resin Market encounters high raw material costs, which inflate production expenses for buyers. This challenge stems from volatile petrochemical prices, causing a 15% rise in operational costs for manufacturers. Technological limitations hinder suppliers from adopting advanced resin production methods, resulting in a 20% gap in market competitiveness. Workforce skills shortages restrict manufacturers' ability to implement new technologies, leading to production delays that affect buyers' timelines. Compliance with stringent environmental regulations increases operational costs, impacting profit margins for producers by around 10%.
Trends in the China Industrial Resin Market
Buyers and suppliers in the China Industrial Resin Market are adjusting to the following trends.
- Shift towards Eco-Friendly Resin Production: China is progressively embracing eco-friendly resin production methods, motivated by environmental regulations. In 2023, the National Development and Reform Commission launched a programme supporting sustainable practices, encouraging manufacturers to invest in greener technologies.
- Growth in the Packaging Sector: The packaging industry is flourishing, leading to increased demand for acrylic and polyester resins. In 2023, the market for these resins is projected to grow as companies pursue sustainable packaging solutions.
- Rise of Advanced Resin Technologies: The introduction of the 'New Materials Industry Development Plan' in 2023 aims to promote advanced resin technologies. This initiative is expected to stimulate innovation and investment in the industrial resin sector.
- Expansion of Construction Activities: The construction sector in China is growing, resulting in higher consumption of industrial resins. In 2023, it is predicted to consume around 25% of the total industrial resin market.
Investment Opportunities in the China Industrial Resin Market
Several openings in the China Industrial Resin Market merit attention from investors.
- Joint Ventures for Eco-Friendly Production: Now is an ideal time for joint ventures focusing on eco-friendly resin production, with the National Development and Reform Commission supporting such initiatives. The automotive sector is a key buyer group, seeking sustainable materials.
- Investment in Advanced Resin Technologies: Investment in advanced resin technologies is essential as the market is projected to reach USD 1.74 billion by 2032. The construction sector is a major consumer, providing opportunities for suppliers.
- Supply of Acrylic Resins for Packaging: The growing packaging industry presents an opportunity to supply acrylic resins, which are in high demand. The projected growth in this sector makes it a strategic focus for manufacturers.
- Certification for Sustainable Practices: Obtaining certifications for sustainable production methods is essential now, as regulations tighten. The construction industry is increasingly prioritising eco-friendly materials, creating a demand for certified products.
Government Initiatives in the China Industrial Resin Market
The 'New Materials Industry Development Plan' launched by the Ministry of Industry and Information Technology in 2023 builds on previous laws by promoting advanced resin technologies. This initiative aims to assist manufacturers in adopting eco-friendly practices and enhancing product quality standards. It establishes clear targets for innovation and sustainability within the industrial resin sector, encouraging investment in research and development.
The construction sector benefits from the Ministry of Ecology and Environment's promotion of sustainable practices under the 14th Five-Year Plan. This plan allocates funding for projects that focus on eco-friendly resin production methods, enabling buyers to access greener materials. Additionally, the National Development and Reform Commission supports initiatives that align with these sustainable practices, ensuring compliance and encouraging innovation in the resin industry.
Future Insight of the China Industrial Resin Market
By 2032, buyers and suppliers in the China Industrial Resin Market can anticipate substantial advancements driven by the 'New Materials Industry Development Plan' and eco-friendly initiatives. The automotive sector will continue to be a key driver, with demand for industrial resins projected to rise by 30%. Innovations in resin technologies will improve manufacturing efficiency, allowing suppliers to respond to market needs more promptly. The growth of the packaging industry will further boost demand for acrylic and polyester resins, creating new opportunities for market participants.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Resin Type – Epoxy Resin Dominated, Polyurethane Resin Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, Epoxy Resin accounted for a 46% market share by resin type in 2025. Epoxy resin holds the largest share in the China Industrial Resin Market due to its extensive use in coatings and adhesives, particularly in automotive applications. This segment's dominance is underscored by the production of over 2 million tons in 2022, showcasing its critical role in manufacturing. Polyurethane Resin is set to record the highest CAGR in this split, 8.3% over 2026–2032. Polyurethane resin is experiencing rapid growth driven by its rising demand in flexible foams and coatings, especially within the automotive sector. The total demand for polyurethane resins reached 1.5 million tons in 2022, indicating a strong upward trend in this segment. Suppliers should focus on epoxy and polyurethane resins to cater to the growing needs of the automotive and construction industries.
By Base Material – Thermosetting Dominated, Polyol & Isocyanate Expected to Grow Fastest
With a 51% revenue share in 2025, Thermosetting was the largest base material category. Thermosetting resins dominate the market share in China as they are essential for applications requiring heat resistance and durability, particularly in automotive and construction sectors. Their capability to create long-lasting products that withstand extreme conditions makes them highly valued by manufacturers. Over 2026–2032, Polyol & Isocyanate is expected to post the fastest growth, at a CAGR of 6.7%. Polyol and isocyanate are the fastest-growing base materials, primarily due to their critical role in the production of polyurethane resins. The increasing preference for flexible and durable materials is driving significant growth in this segment. Buyers and suppliers must adjust to the rising demand for thermosetting materials while investing in polyol and isocyanate technologies.
By Form – Liquid Dominated, Foam Expected to Grow Fastest
Liquid held a 49% share of the China Industrial Resin Market by form in 2025. Liquid form resins command the largest market share in China, primarily because they are the preferred choice for applications in coatings and adhesives. Their versatility makes them essential for various industries, including automotive and construction. Foam is projected to grow fastest, at a CAGR of 7.0% during 2026–2032. Foam form resins are growing rapidly, largely due to their widespread use in insulation and cushioning applications, particularly in the construction sector. The demand for energy-efficient building materials is driving this growth. Suppliers should prioritise the development of liquid and foam resin products to cater to the evolving needs of the construction and automotive industries.
By Application – Adhesives & Sealants Dominated, Coatings & Insulation Expected to Grow Fastest
Adhesives & Sealants took a 41% share of application in 2025, more than any other category. Adhesives and sealants capture the largest market share as they are vital for bonding in construction and automotive applications. Their crucial role in ensuring structural integrity makes them indispensable across these industries. The quickest growth will come from Coatings & Insulation, forecast to expand at a CAGR of 7.0% between 2026 and 2032. Coatings and insulation are the fastest-growing applications, propelled by the increasing need for protective materials in construction and automotive sectors. This trend reflects a broader movement towards enhanced durability and energy efficiency in product offerings. Suppliers need to innovate in adhesives and coatings to meet the rising demand for high-performance materials in construction and automotive sectors.
By End User Industry – Automotive Dominated, Construction Expected to Grow Fastest
The largest end user industry category in 2025 was Automotive, with a 41% share of total revenue. The automotive industry is the largest consumer of industrial resins, accounting for approximately 30% of total demand, as it relies heavily on these materials for parts and coatings. The sector's continuous growth ensures a steady demand for resins. Construction is set to record the highest CAGR in this split, 6.7% over 2026–2032. The construction industry is experiencing the fastest growth in resin consumption, driven by a surge in infrastructure projects and the need for durable building materials. This trend is expected to continue as urbanisation accelerates. Suppliers should align their strategies to capture the growing opportunities in the construction sector while maintaining strong ties with the automotive industry.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Resin Market Outlook
- Market Size of China Industrial Resin Market, 2025
- Forecast of China Industrial Resin Market, 2032
- Historical Data and Forecast of China Industrial Resin Revenues & Volume for the Period 2022 - 2032F
- China Industrial Resin Market Trend Evolution
- China Industrial Resin Market Drivers and Challenges
- China Industrial Resin Price Trends
- China Industrial Resin Porter's Five Forces
- China Industrial Resin Industry Life Cycle
- Historical Data and Forecast of China Industrial Resin Market Revenues & Volume By Resin Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Resin Market Revenues & Volume By Epoxy Resin for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Resin Market Revenues & Volume By Polyurethane Resin for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Resin Market Revenues & Volume By Polyester Resin for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Resin Market Revenues & Volume By Acrylic Resin for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Resin Market Revenues & Volume By Base Material for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Resin Market Revenues & Volume By Thermosetting for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Resin Market Revenues & Volume By Polyol & Isocyanate for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Resin Market Revenues & Volume By Unsaturated Polyester for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Resin Market Revenues & Volume By Acrylic Polymer for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Resin Market Revenues & Volume By Form for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Resin Market Revenues & Volume By Liquid for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Resin Market Revenues & Volume By Foam for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Resin Market Revenues & Volume By Gelcoat for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Resin Market Revenues & Volume By Emulsion for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Resin Market Revenues & Volume By Application for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Resin Market Revenues & Volume By Adhesives & Sealants for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Resin Market Revenues & Volume By Coatings & Insulation for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Resin Market Revenues & Volume By Molded Components for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Resin Market Revenues & Volume By Paints & Inks for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Resin Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Resin Market Revenues & Volume By Automotive for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Resin Market Revenues & Volume By Construction for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Resin Market Revenues & Volume By Marine & Aerospace for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Resin Market Revenues & Volume By Packaging & Printing for the Period 2022 - 2032F
- China Industrial Resin Import Export Trade Statistics
- Market Opportunity Assessment By Resin Type
- Market Opportunity Assessment By Base Material
- Market Opportunity Assessment By Form
- Market Opportunity Assessment By Application
- Market Opportunity Assessment By End User Industry
- China Industrial Resin Top Companies Market Share
- China Industrial Resin Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Resin Company Profiles
- China Industrial Resin Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Resin Type
- Epoxy Resin
- Polyurethane Resin
- Polyester Resin
- Acrylic Resin
By Base Material
- Thermosetting
- Polyol & Isocyanate
- Unsaturated Polyester
- Acrylic Polymer
By Form
- Liquid
- Foam
- Gelcoat
- Emulsion
By Application
- Adhesives & Sealants
- Coatings & Insulation
- Molded Components
- Paints & Inks
By End User Industry
- Automotive
- Construction
- Marine & Aerospace
- Packaging & Printing































