China Industrial Scrap Recycling Market Size & Growth Rate
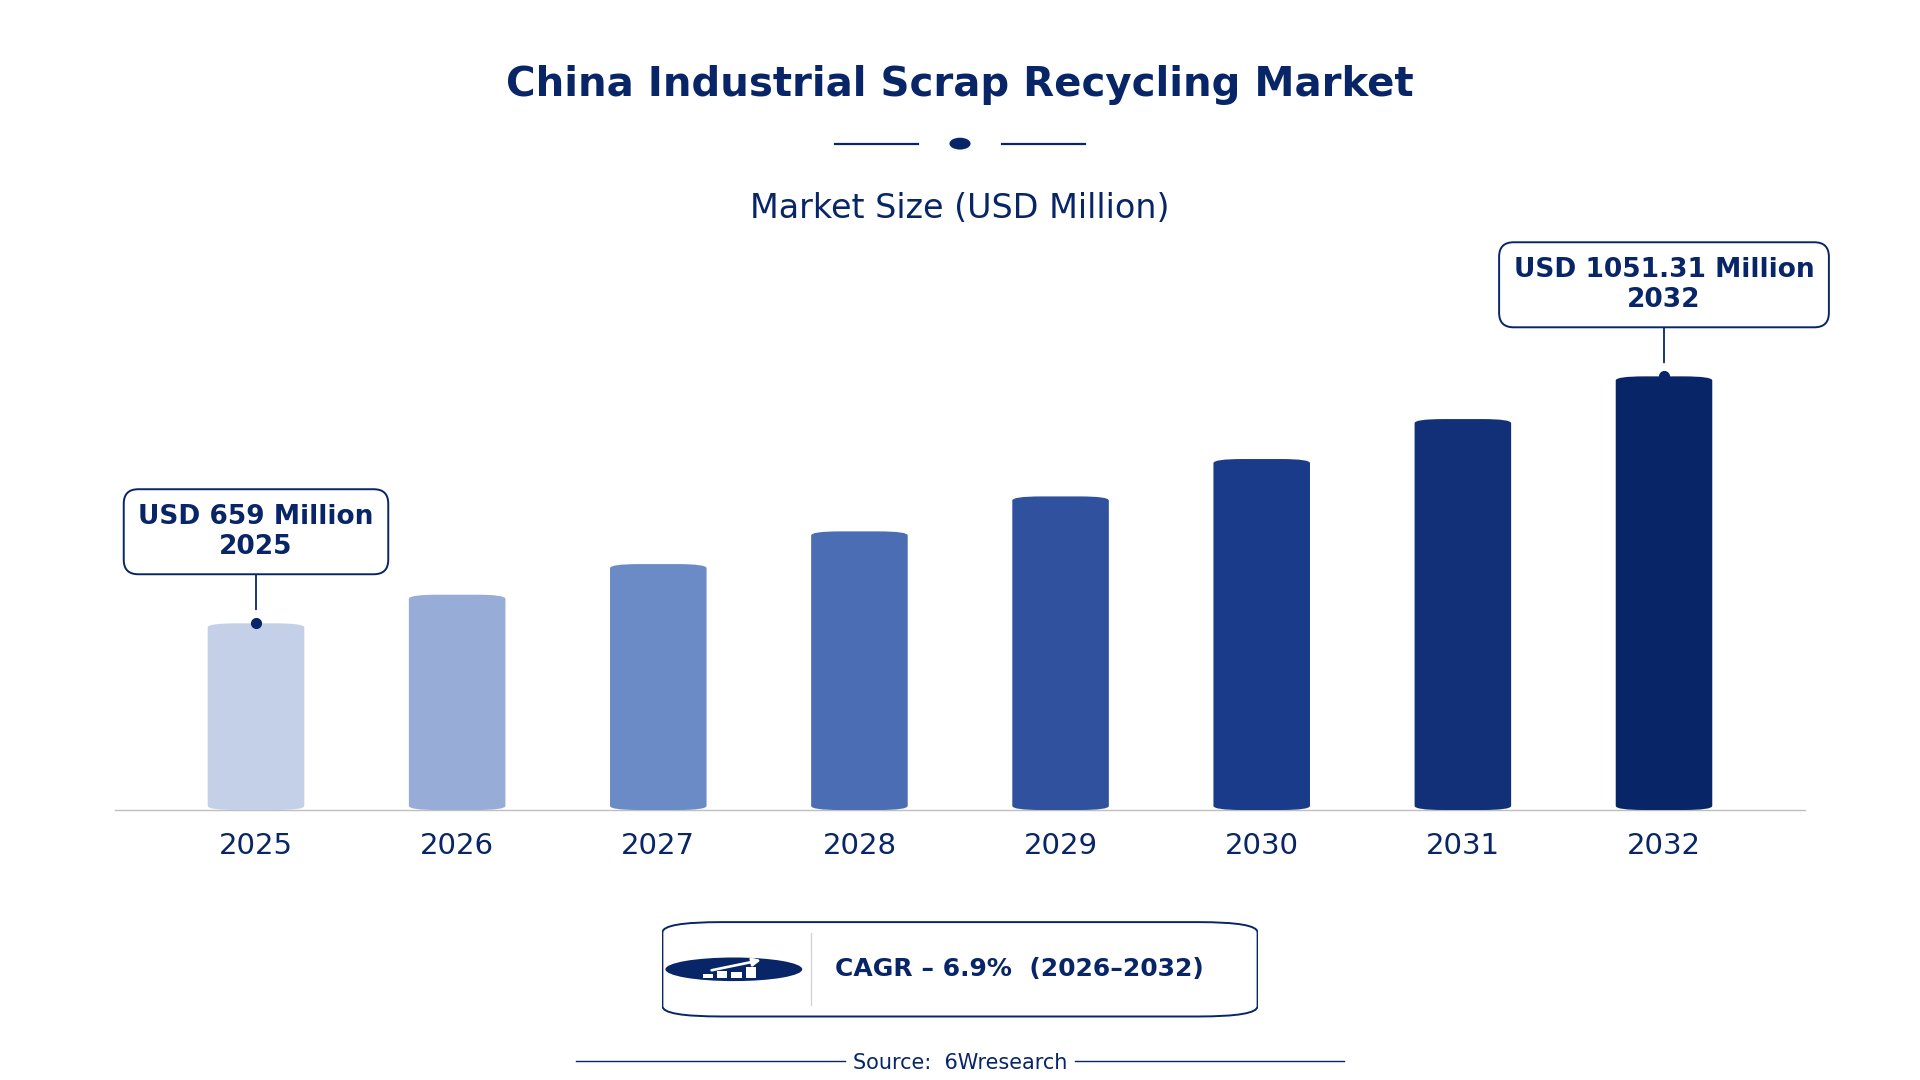
According to 6Wresearch internal database and industry insights, the China Industrial Scrap Recycling Market was valued at USD 659.0 million in 2025 and is projected to reach USD 1,051.31 million by 2032, growing at a CAGR of approximately 6.9% during 2026–2032.
China Industrial Scrap Recycling Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Scrap Recycling Market |
| Market Size 2025 | USD 659.0 million |
| Market Size 2032 | USD 1,051.31 million |
| Absolute Growth 2025–2032 | USD 392.31 million |
| CAGR 2026–2032 | 6.9% |
| Peak Annual Growth | 8.6% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Scrap Type, 2025 | Ferrous Scrap (44% share) |
| Leading Process Type, 2025 | Melting & Refining (36% share) |
| Leading End Use Industry, 2025 | Steel Manufacturing (36% share) |
| Leading Distribution Channel, 2025 | Direct Collection (47% share) |
| Fastest-Growing Scrap Type | E-waste (9.1% CAGR) |
| Fastest-Growing Process Type | Shredding (8.2% CAGR) |
| Fastest-Growing End Use Industry | Electronics Recycling (8.0% CAGR) |
| Fastest-Growing Distribution Channel | Online Aggregators (9.4% CAGR) |
| Growing Sector | E-waste Recycling |
| Key End Users | Steel manufacturers, aluminum producers, electronics recyclers |
China Industrial Scrap Recycling Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
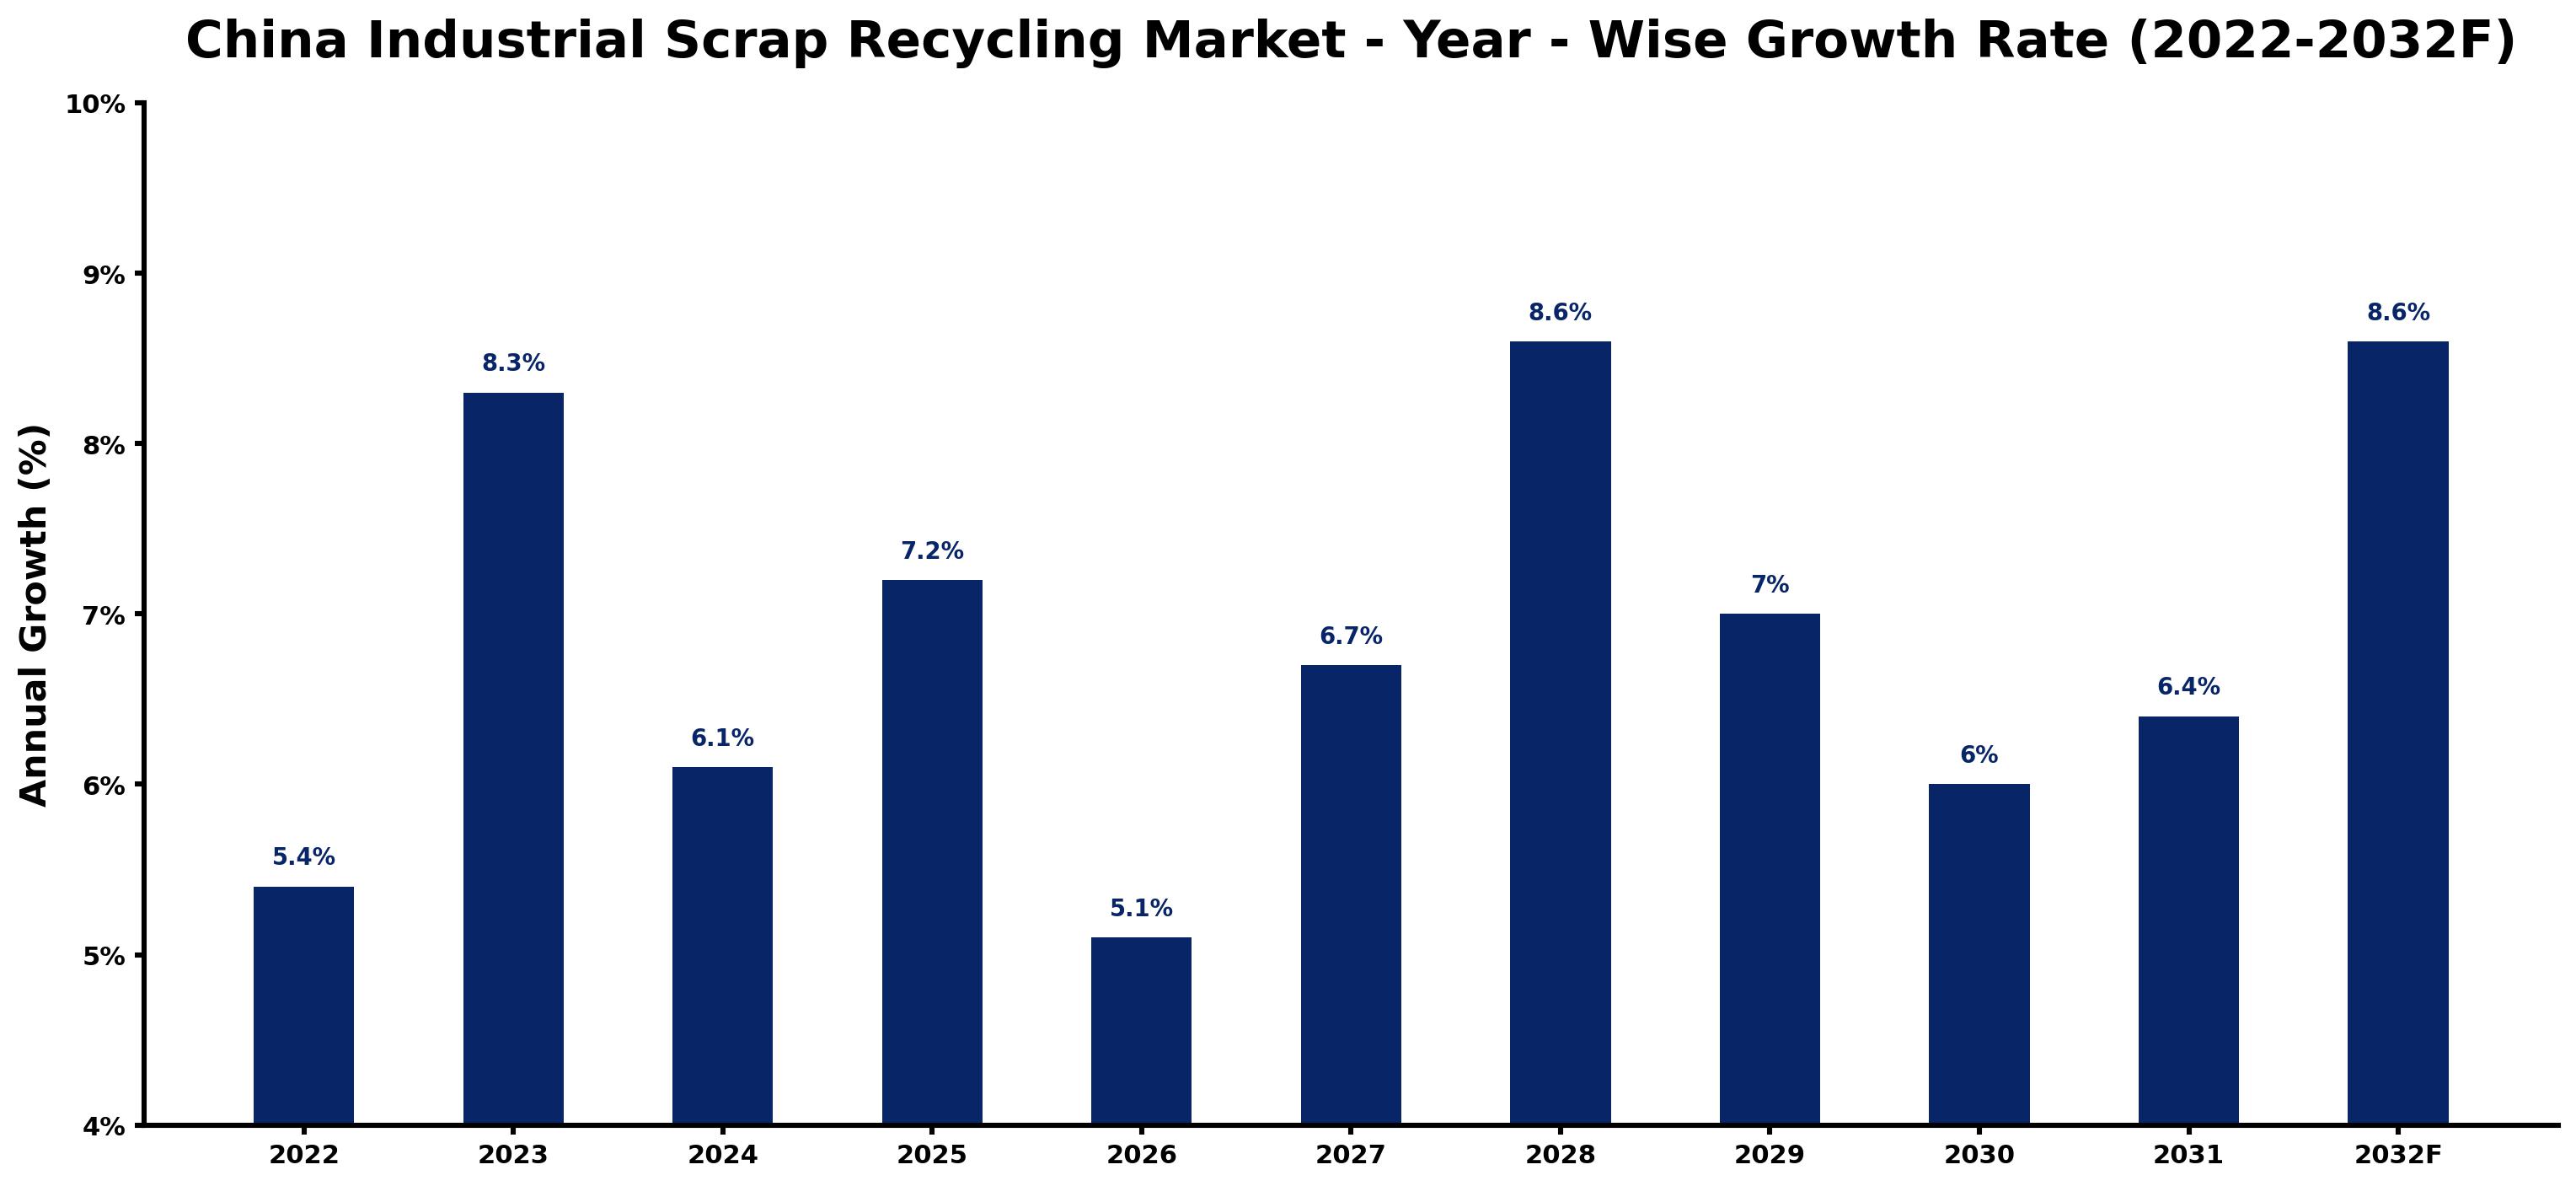
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.4 | The market experienced steady demand from steel manufacturing and e-waste recycling initiatives. |
| 2023 | 8.3 | Growth accelerated due to increased steel production and enhanced e-waste recycling regulations. |
| 2024 | 6.1 | Demand growth slowed as the market adjusted to previous high levels of activity. |
| 2025 | 7.2 | The market rebounded as steel manufacturing continued to rely heavily on recycled ferrous scrap. |
| 2026 | 5.1 | Growth slowed again as the market stabilised after rapid increases in previous years. |
| 2027 | 6.7 | Demand rose due to expanding recycling capacities and investments in processing technologies. |
| 2028 | 8.6 | The market peaked with significant demand from steel and aluminum sectors driving growth. |
| 2029 | 7.0 | Growth moderated as the market adjusted to the high levels of recycling capacity. |
| 2030 | 6.0 | Demand growth slowed further as market conditions stabilised post-peak. |
| 2031 | 6.4 | A slight increase in growth occurred as new recycling initiatives were implemented. |
| 2032 | 8.6 | The market is expected to experience robust growth driven by increasing recycling rates. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Scrap Recycling Market Synopsis
Industrial Scrap Recycling in China involves the collection and processing of scrap materials to recover valuable metals. This process includes shredding, melting, and refining, primarily serving steel manufacturing, aluminium production, and electronics recycling. The China Industrial Scrap Recycling Market is expanding due to rising demand from domestic manufacturers and regulatory support for recycling initiatives. In 2023, 25% of steel production was sourced from recycled materials. Growth is further supported by the Circular Economy Development Strategy launched in 2021, which aims to improve recycling efforts across the country.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing demand for recycled metals in steel manufacturing | Driver | High | Ferrous Scrap |
| Regulatory support for e-waste recycling | Driver | High | E-waste |
| Expansion of online recycling platforms for scrap collection | Opportunity | Medium | Ferrous Scrap |
| Growing demand for recycled aluminum in manufacturing | Opportunity | High | Non-Ferrous Scrap |
| Limited recycling of rubber waste due to low demand | Restraint | Medium | Rubber Scrap |
| Challenges in processing e-waste efficiently | Restraint | High | E-waste |
| High operational costs for recycling facilities | Challenge | High | Melting & Refining |
| Technological barriers in advanced recycling processes | Challenge | Medium | Chemical Recovery |
Evaluation of Drivers in China Industrial Scrap Recycling Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising steel production requiring recycled ferrous scrap | Ferrous Scrap | In 2022, China produced 700 million tons of steel, heavily relying on ferrous scrap. |
| New e-waste regulations driving recycling rates | E-waste | In 2023, the e-waste recycling rate in China reached 20%, spurred by updated regulations. |
| Investment in recycling technologies improving processing efficiency | Melting & Refining | The Ministry of Ecology and Environment reported that 50% of aluminum production comes from recycled sources. |
| Growing consumer electronics market increasing e-waste | E-waste | The increasing electronics consumption in China has led to a higher volume of e-waste. |
| Increased engagement on online recycling platforms | Ferrous Scrap | China's online recycling platforms have seen a 40% increase in user engagement since 2021. |
Growth in the Industrial Scrap Recycling market in China comes from rising steel production and significant investments in recycling technologies. In 2022, China produced 700 million tons of steel, heavily relying on ferrous scrap. The consumer electronics market is expanding, resulting in increased e-waste generation. Online recycling platforms have experienced a 40% increase in user engagement since 2021, improving scrap collection efforts.
Evaluation of Restraints in China Industrial Scrap Recycling Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Low recycling rates for rubber waste due to limited applications | Rubber Scrap | In 2022, 120 million tons of rubber waste were generated in China, with limited recycling. |
| Inefficiencies in e-waste processing affecting recovery rates | E-waste | Challenges in processing e-waste efficiently hinder recovery of valuable materials. |
| High operational costs for recycling facilities limiting profitability | Melting & Refining | Operational costs for recycling facilities remain elevated, impacting their viability. |
| Technological barriers in advanced recycling processes | Chemical Recovery | Limited adoption of advanced technologies restricts the efficiency of chemical recovery. |
| Market fluctuations affecting scrap pricing and availability | Ferrous Scrap | Volatility in scrap pricing impacts the availability and sourcing of ferrous scrap. |
China Industrial Scrap Recycling Market Challenges
A major supply challenge in the China Industrial Scrap Recycling market arises from the heavy reliance on ferrous scrap, which can create shortages for producers during peak demand. This situation disrupts manufacturers who need a consistent supply of raw materials for steel production, potentially delaying their output schedules. Importers face rising costs due to the updated E-waste Management Regulation, which can inflate operational expenses by up to 15%. Limited recycling of rubber waste, which generated 120 million tons in 2022, restricts buyers' access to sustainable materials. Skills shortages in advanced recycling techniques hinder producers' efficiency, leading to reduced recovery rates and lost revenue opportunities.
Trends in the China Industrial Scrap Recycling Market
Buyers and suppliers in the China Industrial Scrap Recycling Market are adjusting to the following trends.
- Growth of Online Recycling Platforms: The rise of online recycling platforms is transforming scrap collection methods in China, with user engagement increasing by 40% since 2021. This trend facilitates better connections between suppliers and buyers.
- Increased Focus on Circular Economy: The Circular Economy Development Strategy launched in 2021 is promoting sustainable practices in recycling. This initiative aims to improve resource recovery and recycling rates across various sectors.
- Expansion of Melting & Refining Processes: Melting & Refining processes are gaining traction, projected to hold a 36% share by 2025. This growth is driven by increasing demand for recycled metals in manufacturing.
- Shift towards E-waste Recycling: China is experiencing a shift towards e-waste recycling, with the e-waste recycling rate reaching 20% in 2023. This change is driven by the updated E-waste Management Regulation, which improves collection practices.
Investment Opportunities in the China Industrial Scrap Recycling Market
Several openings in the China Industrial Scrap Recycling Market merit attention from investors.
- Investing in Advanced Recycling Technologies: Investing in advanced recycling technologies is timely now, as the market seeks efficiency. The Guangdong province, leading in scrap metal recycling, offers opportunities for technology providers.
- Expanding into E-waste Recycling: The growing e-waste sector presents opportunities for investment, especially with the 20% recycling rate in 2023. Engaging with specialised recyclers can facilitate market entry.
- Developing Online Aggregators: Developing online aggregator platforms can capture the growing demand for scrap collection. With a 40% increase in user engagement, this is a timely opportunity for investment.
- Establishing Partnerships with Local Recyclers: Collaborating with local recyclers is essential for entering the Chinese market. With the non-ferrous metal recycling industry projected to reach 30 million tons by 2025, partnerships can improve supply chains.
Government Initiatives in the China Industrial Scrap Recycling Market
The 'Circular Economy Promotion Law', updated in 2021, mandates enhanced recycling efforts and resource efficiency in the industrial scrap recycling sector. This law requires producers to adopt sustainable practices and improve waste management systems, ensuring compliance with national recycling targets. Additionally, the 'Green Manufacturing Action Plan' enacted in 2021 encourages the use of recycled materials in manufacturing processes, promoting a circular economy and reducing reliance on virgin resources.
The Ministry of Ecology and Environment oversees the implementation of the 'E-Waste Recycling System', initiated in 2022, which aims to improve collection and processing rates for electronic waste. This system provides funding for recycling facilities and supports initiatives that enhance e-waste recovery. Furthermore, the 'National Strategy for Resource Recycling', launched in 2023, sets a target to increase recycling rates to 35% by 2025, ensuring that producers meet regulatory standards.
Future Insight of the China Industrial Scrap Recycling Market
The China Industrial Scrap Recycling market is expected to undergo significant changes by 2032, driven by the Circular Economy Development Strategy which aims to boost recycling efforts. This initiative will support a projected 30 million tons of non-ferrous metal recycling by 2025, improving resource recovery. Increased user engagement on online recycling platforms will facilitate better material distribution and recovery. The growing adoption of ISO 14001 certification among facilities will improve environmental management, benefiting both buyers and suppliers in the long term.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Scrap Type – Ferrous Scrap Dominated, E-waste Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, the largest scrap type category in 2025 was Ferrous Scrap, with a 44% share of total revenue. Ferrous scrap holds the largest market share in China due to its extensive use in steel manufacturing, which produced 700 million tons in 2022. The high demand for ferrous scrap is particularly evident in Guangdong, the leading region for scrap metal recycling. The quickest growth will come from E-waste, forecast to expand at a CAGR of 9.1% between 2026 and 2032. E-waste is the fastest-growing segment, fuelled by the rising consumption of electronics and the implementation of updated e-waste management regulations in 2022. With a recycling rate of 20% in 2023, this sector is expanding rapidly as consumers increasingly dispose of electronic devices. This indicates that suppliers must enhance their e-waste recycling capabilities to meet regulatory demands and changing consumer behaviour.
By Process Type – Melting & Refining Dominated, Shredding Expected to Grow Fastest
Melting & Refining held a 36% share of the China Industrial Scrap Recycling Market by process type in 2025. Melting and refining processes dominate the market due to their essential role in recovering metals from scrap materials. These processes are vital for converting ferrous and non-ferrous scrap into usable raw materials, ensuring a reliable supply for manufacturing sectors. Shredding is set to record the highest CAGR in this split, 8.2% over 2026–2032. Shredding is the fastest-growing process type, as it is crucial for size reduction before further processing of scrap materials. The increasing emphasis on efficiency in recycling operations is driving this segment, with facilities aiming to optimise their processing capabilities. This suggests that suppliers should invest in advanced shredding technologies to enhance processing efficiency and meet rising demand.
By End Use Industry – Steel Manufacturing Dominated, Electronics Recycling Expected to Grow Fastest
Steel Manufacturing accounted for a 36% market share by end use industry in 2025. Steel manufacturing is the largest consumer of recycled ferrous scrap in China, commanding a significant portion of the market share. The industry's reliance on recycled materials is highlighted by the fact that 25% of steel production in 2023 was sourced from recycled materials, showcasing a commitment to sustainability. Electronics Recycling is projected to grow fastest, at a CAGR of 8.0% during 2026–2032. Electronics recycling is the fastest-growing end-use industry, propelled by increasing regulatory pressures and the necessity to manage e-waste effectively. As regulations tighten, the demand for recycling electronic devices is expected to surge, creating growth opportunities in this sector. This highlights the need for suppliers to adapt their strategies to capture the growing demand in electronics recycling.
By Distribution Channel – Direct Collection Dominated, Online Aggregators Expected to Grow Fastest
In 2025, Direct Collection led the distribution channel split with a 47% share. Direct collection remains the primary method for sourcing scrap materials, securing the largest market share in the distribution channel. This approach enables efficient procurement of scrap directly from consumers and businesses, ensuring a consistent supply for recycling operations. Over 2026–2032, Online Aggregators are expected to post the fastest growth, at a CAGR of 9.4%. Online aggregators are the fastest-growing distribution channel, offering a convenient platform for connecting suppliers and buyers. The 40% increase in user engagement since 2021 illustrates the shift towards digital solutions in the recycling market. This means that suppliers should consider leveraging online platforms to enhance their market reach and streamline operations.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Scrap Recycling Market Outlook
- Market Size of China Industrial Scrap Recycling Market, 2025
- Forecast of China Industrial Scrap Recycling Market, 2032
- Historical Data and Forecast of China Industrial Scrap Recycling Revenues & Volume for the Period 2022 - 2032F
- China Industrial Scrap Recycling Market Trend Evolution
- China Industrial Scrap Recycling Market Drivers and Challenges
- China Industrial Scrap Recycling Price Trends
- China Industrial Scrap Recycling Porter's Five Forces
- China Industrial Scrap Recycling Industry Life Cycle
- Historical Data and Forecast of China Industrial Scrap Recycling Market Revenues & Volume By Scrap Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Scrap Recycling Market Revenues & Volume By Ferrous Scrap for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Scrap Recycling Market Revenues & Volume By Non-Ferrous Scrap for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Scrap Recycling Market Revenues & Volume By E-waste for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Scrap Recycling Market Revenues & Volume By Rubber Scrap for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Scrap Recycling Market Revenues & Volume By Process Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Scrap Recycling Market Revenues & Volume By Shredding for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Scrap Recycling Market Revenues & Volume By Melting & Refining for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Scrap Recycling Market Revenues & Volume By Chemical Recovery for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Scrap Recycling Market Revenues & Volume By Pyrolysis for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Scrap Recycling Market Revenues & Volume By End Use Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Scrap Recycling Market Revenues & Volume By Steel Manufacturing for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Scrap Recycling Market Revenues & Volume By Aluminum Products for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Scrap Recycling Market Revenues & Volume By Electronics Recycling for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Scrap Recycling Market Revenues & Volume By Cement Kilns for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Scrap Recycling Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Scrap Recycling Market Revenues & Volume By Direct Collection for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Scrap Recycling Market Revenues & Volume By Online Aggregators for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Scrap Recycling Market Revenues & Volume By Specialized Recyclers for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Scrap Recycling Market Revenues & Volume By Industrial Brokers for the Period 2022 - 2032F
- China Industrial Scrap Recycling Import Export Trade Statistics
- Market Opportunity Assessment By Scrap Type
- Market Opportunity Assessment By Process Type
- Market Opportunity Assessment By End Use Industry
- Market Opportunity Assessment By Distribution Channel
- China Industrial Scrap Recycling Top Companies Market Share
- China Industrial Scrap Recycling Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Scrap Recycling Company Profiles
- China Industrial Scrap Recycling Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Scrap Type
- Ferrous Scrap
- Non-Ferrous Scrap
- E-waste
- Rubber Scrap
By Process Type
- Shredding
- Melting & Refining
- Chemical Recovery
- Pyrolysis
By End Use Industry
- Steel Manufacturing
- Aluminum Products
- Electronics Recycling
- Cement Kilns
By Distribution Channel
- Direct Collection
- Online Aggregators
- Specialized Recyclers
- Industrial Brokers































