China Industrial Supply Chain Services Market Size & Growth Rate
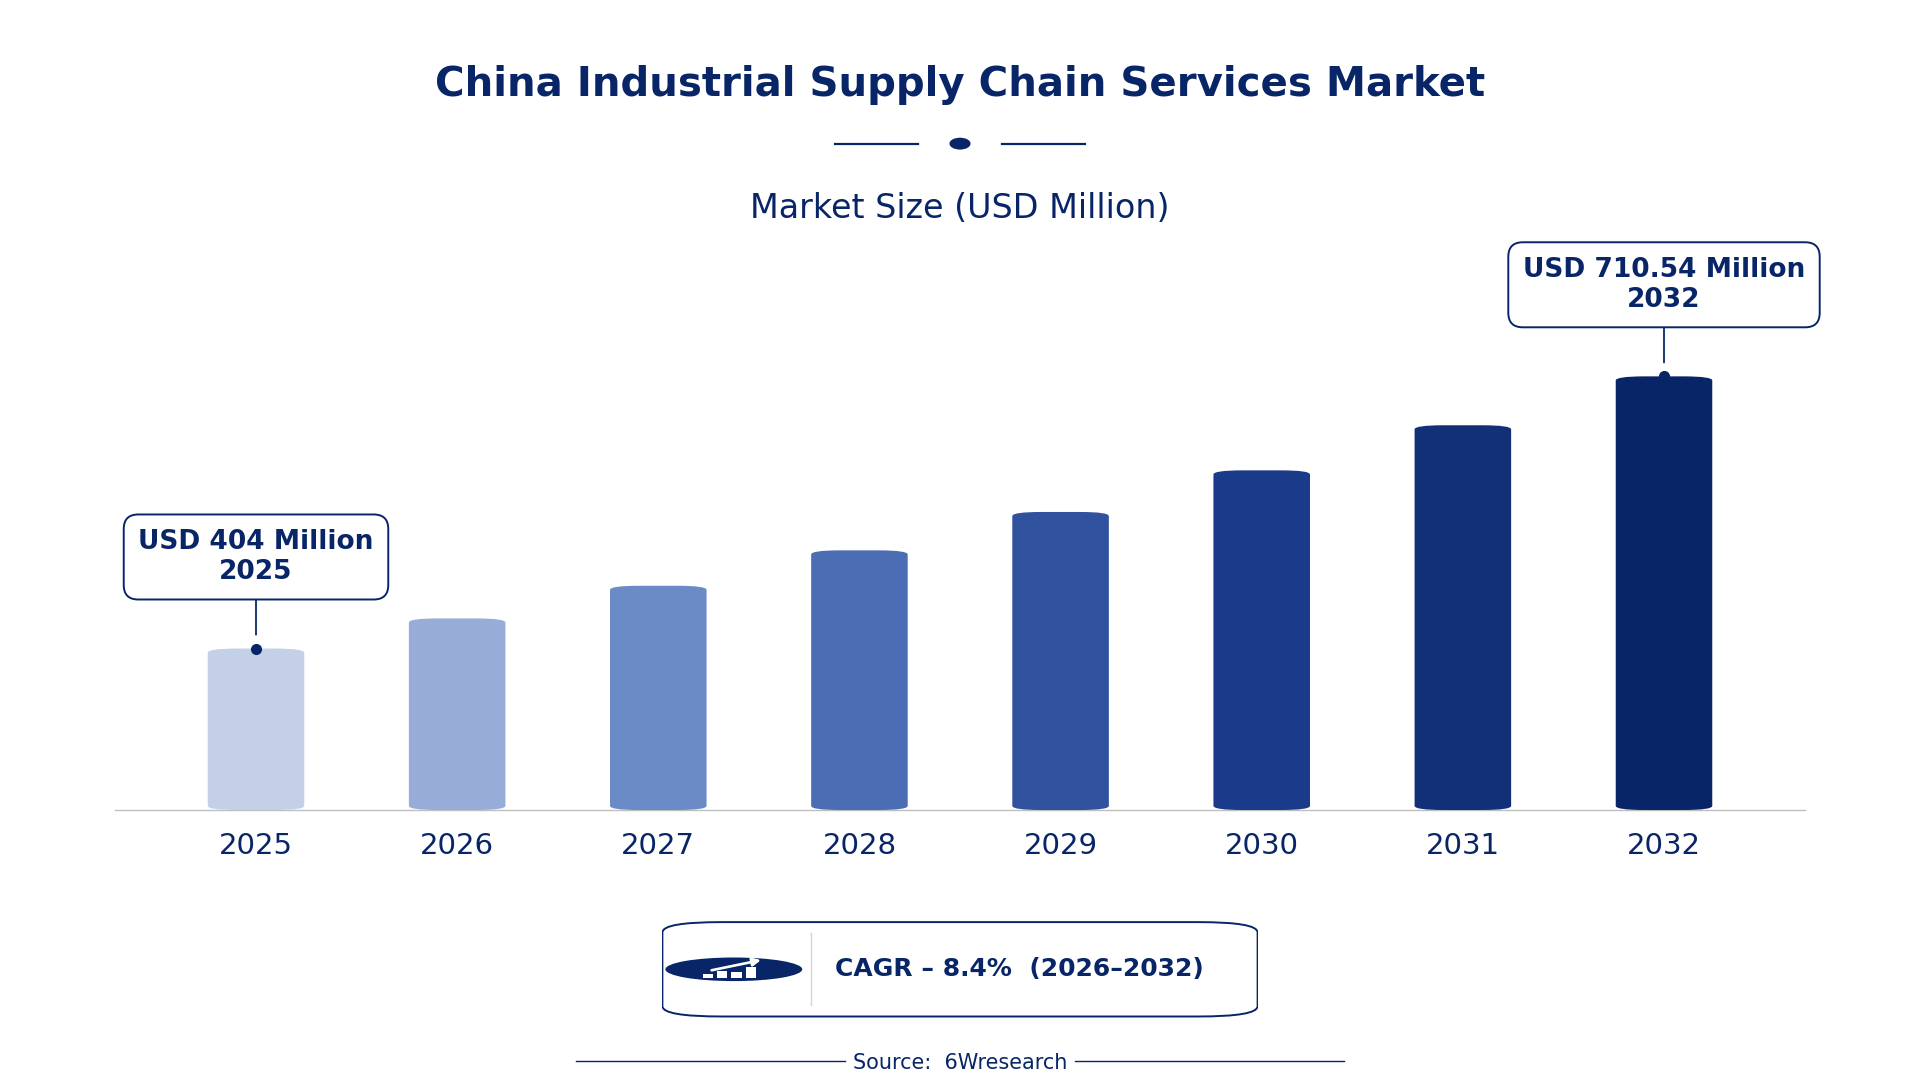
According to 6Wresearch internal database and industry insights, the China Industrial Supply Chain Services Market was valued at USD 404.0 million in 2025 and is projected to reach USD 710.54 million by 2032, growing at a CAGR of approximately 8.4% during 2026–2032.
China Industrial Supply Chain Services Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Supply Chain Services Market |
| Market Size 2025 | USD 404.0 million |
| Market Size 2032 | USD 710.54 million |
| Absolute Growth 2025–2032 | USD 306.54 million |
| CAGR 2026–2032 | 8.4% |
| Peak Annual Growth | 11.4% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Service Type, 2025 | Freight & Logistics (45% share) |
| Leading Technology Support, 2025 | Cloud-Based (47% share) |
| Leading End User, 2025 | Electronics Distributors (42% share) |
| Leading Distribution Channel, 2025 | Direct Contracts (48% share) |
| Fastest-Growing Service Type | Procurement Services (9.6% CAGR) |
| Fastest-Growing End User | Semiconductor Plants (10.5% CAGR) |
| Fastest-Growing Distribution Channel | SaaS Platforms (11.0% CAGR) |
| Growing Sector | Electronics |
| Key End Users | Electronics Distributors, Semiconductor Plants, Telecom Equipment |
China Industrial Supply Chain Services Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
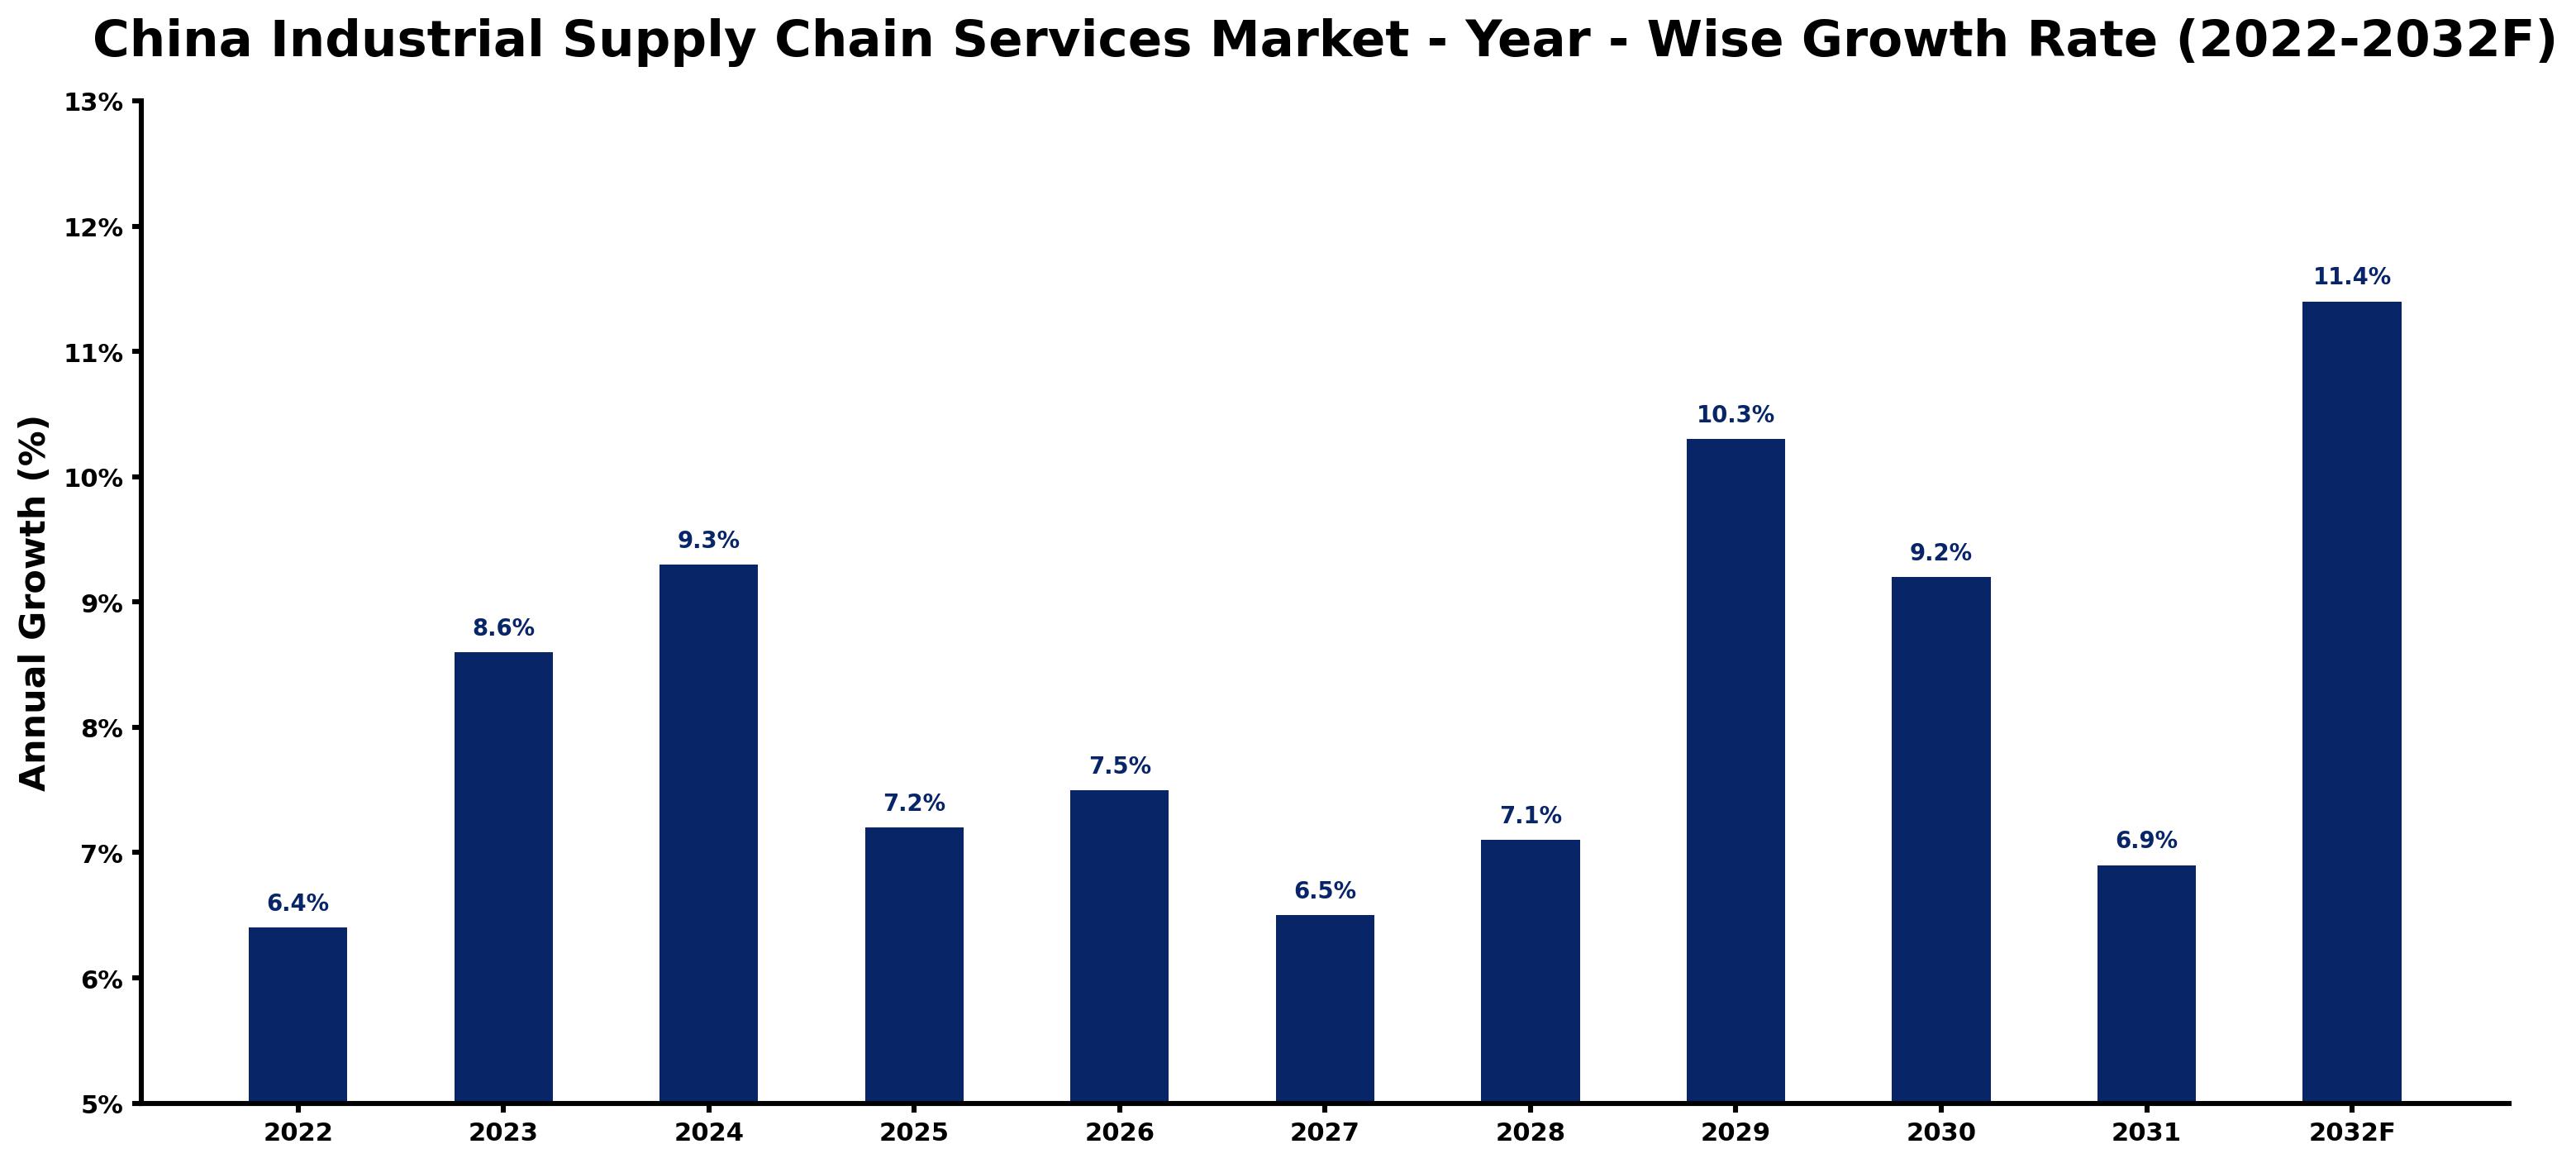
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.4 | The market experienced steady growth due to increased logistics demand from the electronics sector. |
| 2023 | 8.6 | Growth accelerated as the electronics sector expanded its logistics needs, particularly in warehousing. |
| 2024 | 9.3 | The rise in demand for efficient supply chains contributed to faster growth rates, driven by the ICT sector. |
| 2025 | 7.2 | Growth slowed as logistics infrastructure investments began to stabilise under the National Logistics Development Plan. |
| 2026 | 7.5 | Increased adoption of cloud-based solutions is expected to drive a resurgence in growth. |
| 2027 | 6.5 | Growth is projected to slow again as market adjustments occur following rapid expansion in previous years. |
| 2028 | 7.1 | A renewed focus on technology integration is expected to boost growth rates once more. |
| 2029 | 10.3 | Demand is projected to surge as the semiconductor industry expands its logistics requirements significantly. |
| 2030 | 9.2 | Growth is expected to slow as the market adjusts to previous peaks in demand for logistics services. |
| 2031 | 6.9 | A further slowdown is anticipated as logistics capacity reaches near saturation levels. |
| 2032 | 11.4 | The market is projected to peak due to substantial investments in logistics infrastructure and technology. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Supply Chain Services Market Synopsis
Industrial Supply Chain Services in China encompass logistics, warehousing, procurement, and inventory management solutions. These services utilise advanced technologies to optimise supply chains across various industries, improving operational efficiency and reducing costs. The China Industrial Supply Chain Services Market is experiencing growth due to rising demand from sectors like electronics, which accounts for over 30% of total logistics needs. Significant investments in logistics infrastructure, exceeding 1 trillion yuan from 2021 to 2025, further support this growth. The ongoing 'Digital Silk Road' initiative aims to improve logistics efficiency through technology, contributing to the market's expansion.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising demand from the electronics sector for efficient logistics solutions | Driver | High | Freight & Logistics |
| Increased adoption of cloud-based technologies for supply chain management | Driver | High | Cloud-Based |
| Growing logistics needs from the semiconductor industry due to expansion | Opportunity | High | Freight & Logistics |
| The push for sustainable practices in logistics operations | Opportunity | Medium | Freight & Logistics |
| Infrastructure bottlenecks impacting logistics efficiency | Restraint | High | Warehousing |
| Regulatory compliance costs affecting operational expenses | Restraint | Medium | Procurement Services |
| High operational costs due to fluctuating fuel prices | Challenge | High | Freight & Logistics |
| Delays in regulatory approvals for new logistics facilities | Challenge | Medium | Warehousing |
Evaluation of Drivers in China Industrial Supply Chain Services Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising demand from the electronics sector | Electronics Distributors | This sector accounts for over 30% of total logistics needs, driving increased purchases of supply chain services. |
| Significant investments in logistics infrastructure | Freight & Logistics | With projected growth to 17 trillion yuan by 2025, these investments enhance service delivery and operational capacity. |
| Growth in the semiconductor industry | Semiconductor Plants | Expected to reach $300 billion by 2030, this growth increases logistics requirements for efficient supply chain management. |
| Adoption of cloud-based solutions | Cloud-Based | These solutions improve operational efficiency, leading to higher demand for integrated supply chain services. |
| Expansion of e-commerce | Warehousing | The growing need for additional warehousing space supports timely deliveries, essential for meeting consumer expectations. |
Growth across the Industrial Supply Chain Services market in China is anchored in rising demand from the electronics sector, which accounts for over 30% of total logistics needs. The logistics industry is projected to reach 17 trillion yuan by 2025, driven by investments in infrastructure exceeding 1 trillion yuan from 2021 to 2025. The semiconductor industry is expected to grow to $300 billion by 2030, increasing logistics requirements. The adoption of cloud-based solutions is improving operational efficiency, leading to more purchases from various sectors. Demand from e-commerce is driving the need for additional warehousing space, which is crucial for meeting consumer expectations.
Evaluation of Restraints in China Industrial Supply Chain Services Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Infrastructure bottlenecks impacting logistics efficiency | Warehousing | Logistics infrastructure bottlenecks can delay service delivery, increasing operational costs for providers by up to 15%. |
| Regulatory compliance costs affecting operational expenses | Procurement Services | Compliance with national standards can add costs, impacting service pricing for buyers and limiting competitiveness. |
| High operational costs due to fluctuating fuel prices | Freight & Logistics | Rising fuel prices increase transportation costs, affecting overall pricing for logistics services and reducing margins. |
| Limited availability of skilled workforce in logistics | Inventory Management | A shortage of skilled workers can slow down service delivery and reduce operational efficiency, impacting service quality. |
| Delays in regulatory approvals for new logistics facilities | Warehousing | Prolonged approval processes can hinder the establishment of new facilities, affecting service availability and market responsiveness. |
China Industrial Supply Chain Services Market Challenges
China's logistics industry faces an average delivery time of 1.5 days, causing delays for buyers reliant on prompt shipments. This inefficiency compels producers to hold larger inventories, raising operational costs by 15% for many manufacturers. Compliance with national standards like GB/T 32868-2016 complicates processes for suppliers, necessitating significant investments that detract from core business activities. Skills shortages in logistics and supply chain management restrict producers' capacity to optimise operations, resulting in missed opportunities to meet the growing demands of a competitive market.
Trends in the China Industrial Supply Chain Services Market
Four trends stand out in the China Industrial Supply Chain Services Market.
- Shift towards Digital Logistics Solutions: Since 2020, there has been a notable shift towards digital logistics solutions in China. The 'Smart Logistics Pilot Program' has been initiated to support this transition, with over 1 trillion yuan invested in logistics infrastructure.
- Transition to Sustainable Logistics Practices: The logistics sector is increasingly adopting sustainable practices, driven by the 'Green Logistics Development Action Plan' launched in 2021. This initiative aims to promote eco-friendly logistics operations, enhancing service offerings across the industry.
- Emergence of Cloud-Based Supply Chain Solutions: The demand for cloud-based supply chain solutions has surged, particularly in the warehousing segment. By 2025, cloud-based services are expected to capture 47% of the market share, reflecting their growing importance in logistics.
- Increase in Logistics Automation: Since 2021, automation in logistics has been on the rise, driven by the need for efficiency. The average delivery time for logistics services has decreased to 1.5 days, showcasing the impact of technology on service delivery.
Investment Opportunities in the China Industrial Supply Chain Services Market
Several openings in the China Industrial Supply Chain Services Market merit attention from investors.
- Investment in Smart Warehousing Facilities: With the warehousing space in China exceeding 1.5 billion square meters, there is a pressing need for smart warehousing solutions. Electronics distributors are actively seeking these services to improve operational efficiency.
- Expansion of Logistics Services in the Semiconductor Sector: The semiconductor industry's projected growth to $300 billion by 2030 creates a significant opportunity for logistics services. Companies in semiconductor manufacturing are looking to partner with local providers for efficient supply chain management.
- Development of Green Logistics Solutions: The push for sustainable logistics practices presents an opportunity to develop green logistics solutions. The 'Green Logistics Development Action Plan' provides a framework for companies to innovate in this space and attract eco-conscious buyers.
- Enhancement of Last-Mile Delivery Services: As e-commerce continues to grow, there is a need for improved last-mile delivery services. Logistics vendors are investing in technology to streamline these operations, responding to increasing consumer demand.
Government Initiatives in the China Industrial Supply Chain Services Market
The 'National Logistics Development Plan', approved in 2022, aims to improve logistics efficiency by 30% by 2025. This plan outlines specific targets for enhancing infrastructure and service delivery across the logistics sector. Additionally, the 'Green Logistics Development Action Plan', launched in 2021, promotes sustainable practices in logistics operations, encouraging companies to adopt eco-friendly methods. These measures collectively aim to improve the overall efficiency and sustainability of logistics services in China.
In 2023, the National Development and Reform Commission introduced the 'Logistics Modernization Strategy', which integrates digital technologies into supply chains. This strategy is supported by the Ministry of Transport, which oversees the implementation of various logistics initiatives. The 'Smart Logistics Pilot Program', initiated in 2020, funds projects aimed at adopting advanced technologies in logistics, improving overall service efficiency. These government efforts are essential for driving innovation and enhancing logistics capabilities in the country.
Future Insight of the China Industrial Supply Chain Services Market
The China Industrial Supply Chain Services Market is set for evolution by 2032, driven by the 'Digital Silk Road' initiative which will leverage technology to improve logistics efficiency. Government investments in logistics infrastructure will modernise facilities and streamline operations across the sector. With the semiconductor industry projected to reach $300 billion, the demand for integrated supply chain solutions will intensify. The 'Made in China 2025' initiative will further promote logistics integration in advanced manufacturing, opening new avenues for both buyers and suppliers.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Service Type – Freight & Logistics Dominated, Procurement Services Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, with a 45% revenue share in 2025, Freight & Logistics was the largest service type category. Freight & Logistics holds the largest share as it is critical for transporting goods efficiently across China's vast regions. The electronics sector's contribution of over 30% to logistics demand highlights its importance in ensuring timely deliveries and operational effectiveness. Procurement Services are projected to grow fastest, at a CAGR of 9.6% during 2026–2032. Procurement Services is experiencing rapid growth due to the increasing emphasis on efficient sourcing of materials. The government's focus on advanced procurement strategies through initiatives like 'Made in China 2025' is propelling this segment forward. Suppliers must enhance procurement capabilities to meet the growing demand from various industries.
By Technology Support – Cloud-Based Dominated and Is Expected to Record the Fastest Growth
Cloud-Based took a 47% share of technology support in 2025, more than any other category. Cloud-Based solutions dominate the market share as they offer scalable support for diverse supply chain operations. Their widespread adoption across various sectors facilitates streamlined processes and boosts overall efficiency. The same category is also set to grow fastest, at a CAGR of 9.9% during 2026–2032. The growth of Cloud-Based technology is propelled by its ability to provide flexible and scalable solutions tailored to supply chain management needs. This trend is likely to further solidify its leading position in the market. Suppliers should invest in cloud technologies to remain competitive and address the evolving demands of supply chain operations.
By End User – Electronics Distributors Dominated, Semiconductor Plants Expected to Grow Fastest
Electronics Distributors accounted for a 42% market share by end user in 2025. Electronics Distributors command the largest share as they heavily rely on supply chain services for efficient management of their logistics. This sector accounts for over 30% of total logistics demand in China, indicating its significance. Over 2026–2032, Semiconductor Plants are expected to post the fastest growth, at a CAGR of 10.5%. Semiconductor Plants are the fastest-growing segment, driven by the surge in demand for semiconductor products, projected to reach $300 billion by 2030. This growth necessitates advanced supply chain solutions to manage complex operations. Suppliers must tailor their services to meet the specific needs of semiconductor plants to capitalise on this growth opportunity.
By Distribution Channel – Direct Contracts Dominated, SaaS Platforms Expected to Grow Fastest
Direct Contracts held a 48% share of the China Industrial Supply Chain Services Market by distribution channel in 2025. Direct Contracts capture the largest share as they are essential for establishing reliable service agreements with clients across multiple sectors. This approach ensures that tailored solutions effectively address specific client needs. The quickest growth will come from SaaS Platforms, forecast to expand at a CAGR of 11.0% between 2026 and 2032. SaaS Platforms are rapidly gaining traction due to their capability to streamline supply chain operations and enhance management efficiency. This shift indicates a growing preference for digital solutions in logistics. Suppliers should focus on developing or improving SaaS offerings to align with the increasing trend towards digital supply chain management.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Supply Chain Services Market Outlook
- Market Size of China Industrial Supply Chain Services Market, 2025
- Forecast of China Industrial Supply Chain Services Market, 2032
- Historical Data and Forecast of China Industrial Supply Chain Services Revenues & Volume for the Period 2022 - 2032F
- China Industrial Supply Chain Services Market Trend Evolution
- China Industrial Supply Chain Services Market Drivers and Challenges
- China Industrial Supply Chain Services Price Trends
- China Industrial Supply Chain Services Porter's Five Forces
- China Industrial Supply Chain Services Industry Life Cycle
- Historical Data and Forecast of China Industrial Supply Chain Services Market Revenues & Volume By Service Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Supply Chain Services Market Revenues & Volume By Warehousing for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Supply Chain Services Market Revenues & Volume By Freight & Logistics for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Supply Chain Services Market Revenues & Volume By Procurement Services for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Supply Chain Services Market Revenues & Volume By Inventory Management for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Supply Chain Services Market Revenues & Volume By Technology Support for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Supply Chain Services Market Revenues & Volume By RFID/Barcode for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Supply Chain Services Market Revenues & Volume By GPS Fleet Tracking for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Supply Chain Services Market Revenues & Volume By EDI Integration for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Supply Chain Services Market Revenues & Volume By Cloud-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Supply Chain Services Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Supply Chain Services Market Revenues & Volume By Electronics Distributors for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Supply Chain Services Market Revenues & Volume By Telecom Equipment for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Supply Chain Services Market Revenues & Volume By ICT Sector for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Supply Chain Services Market Revenues & Volume By Semiconductor Plants for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Supply Chain Services Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Supply Chain Services Market Revenues & Volume By Direct Contracts for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Supply Chain Services Market Revenues & Volume By Logistics Vendors for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Supply Chain Services Market Revenues & Volume By B2B Portals for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Supply Chain Services Market Revenues & Volume By SaaS Platforms for the Period 2022 - 2032F
- China Industrial Supply Chain Services Import Export Trade Statistics
- Market Opportunity Assessment By Service Type
- Market Opportunity Assessment By Technology Support
- Market Opportunity Assessment By End User
- Market Opportunity Assessment By Distribution Channel
- China Industrial Supply Chain Services Top Companies Market Share
- China Industrial Supply Chain Services Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Supply Chain Services Company Profiles
- China Industrial Supply Chain Services Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Service Type
- Warehousing
- Freight & Logistics
- Procurement Services
- Inventory Management
By Technology Support
- RFID/Barcode
- GPS Fleet Tracking
- EDI Integration
- Cloud-Based
By End User
- Electronics Distributors
- Telecom Equipment
- ICT Sector
- Semiconductor Plants
By Distribution Channel
- Direct Contracts
- Logistics Vendors
- B2B Portals
- SaaS Platforms































