China Industrial Tank Market Size & Growth Rate
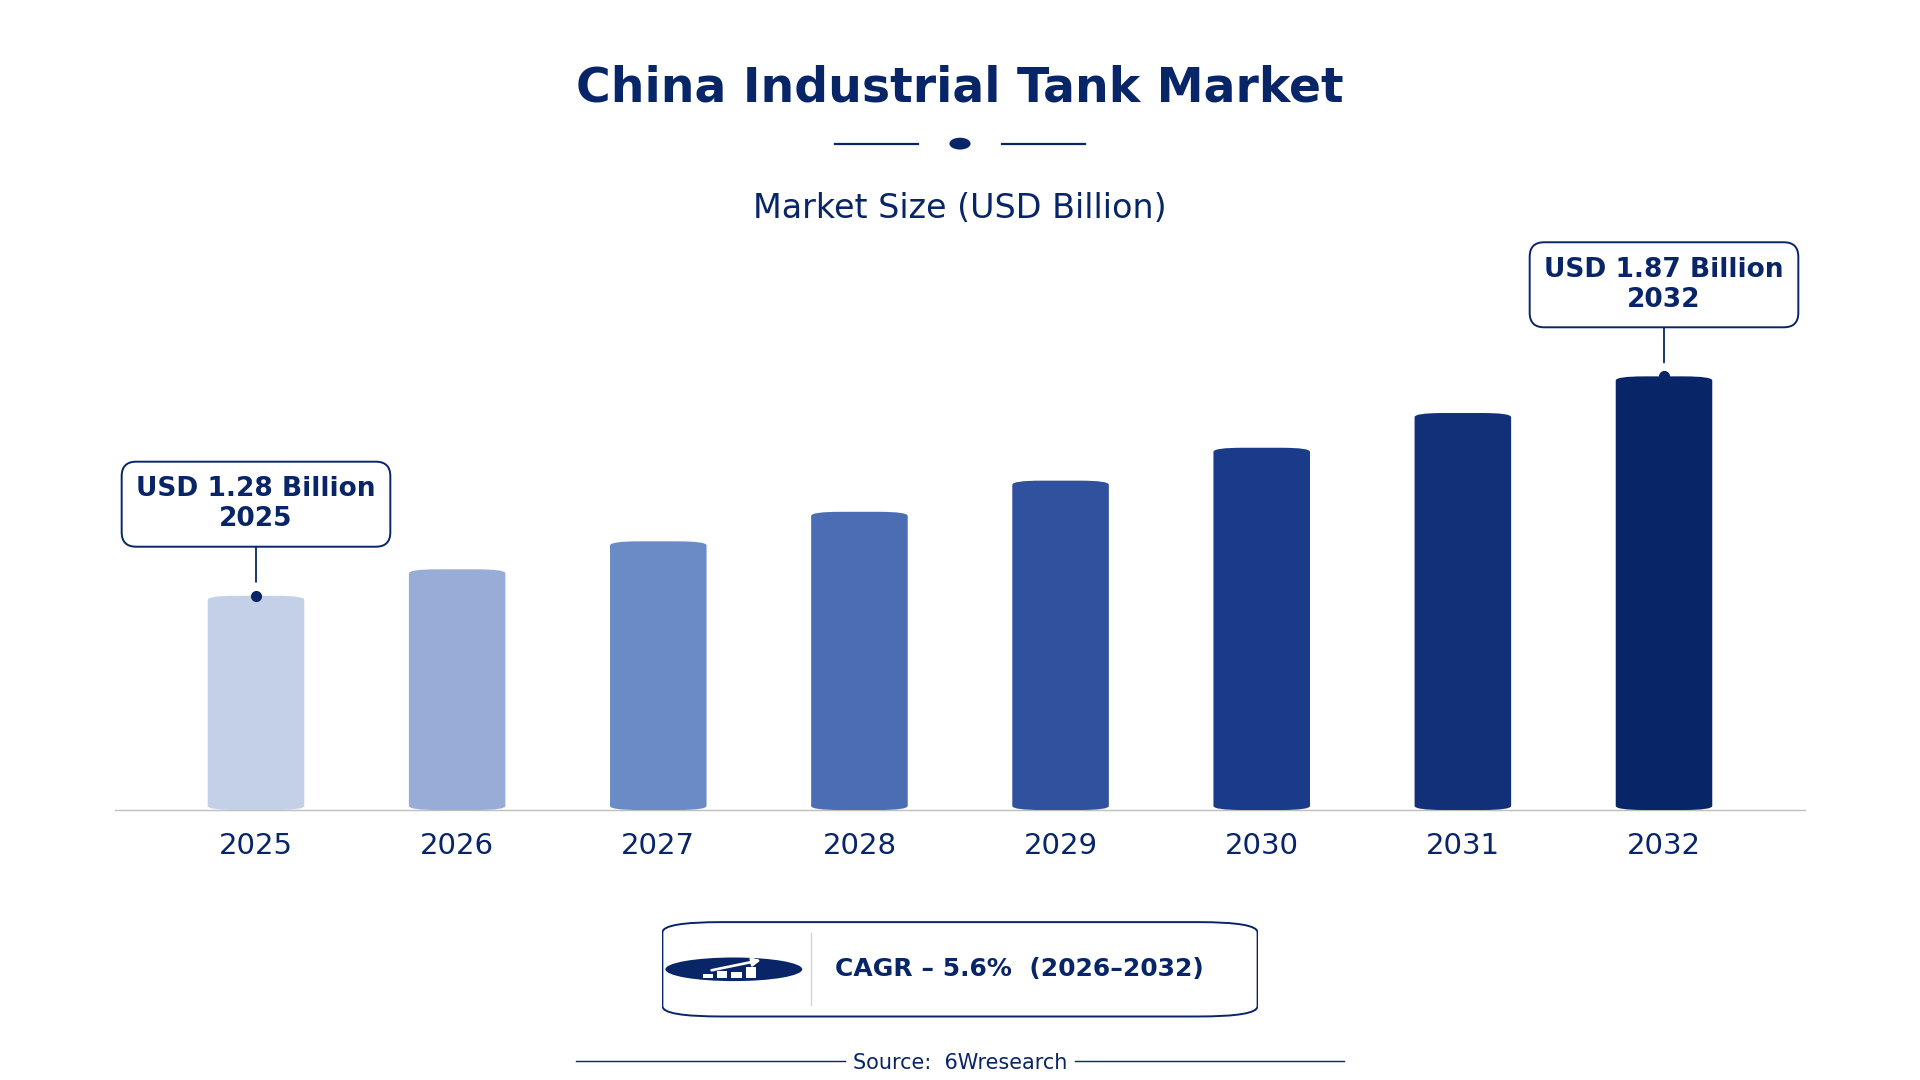
According to 6Wresearch internal database and industry insights, the China Industrial Tank Market was valued at USD 1.28 billion in 2025 and is projected to reach USD 1.87 billion by 2032, growing at a CAGR of approximately 5.6% during 2026–2032.
China Industrial Tank Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Tank Market |
| Market Size 2025 | USD 1.28 billion |
| Market Size 2032 | USD 1.87 billion |
| Absolute Growth 2025–2032 | USD 0.59 billion |
| CAGR 2026–2032 | 5.6% |
| Peak Annual Growth | 8.0% in 2029 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Tank Type, 2025 | Storage Tanks (38% share) |
| Leading Material Type, 2025 | Stainless Steel (45% share) |
| Leading Application, 2025 | Oil & Chemical Storage (49% share) |
| Leading Distribution Channel, 2025 | Direct Manufacturer Sales (52% share) |
| Fastest-Growing Tank Type | Mixing Tanks (7.2% CAGR) |
| Fastest-Growing Material Type | Polypropylene (8.1% CAGR) |
| Fastest-Growing Application | Water Treatment Plants (7.4% CAGR) |
| Fastest-Growing Distribution Channel | Engineering Suppliers (7.1% CAGR) |
| Growing Sector | Water Treatment |
| Key End Users | Oil and chemical producers, water treatment facilities, pharmaceutical manufacturers, LNG storage operators |
China Industrial Tank Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
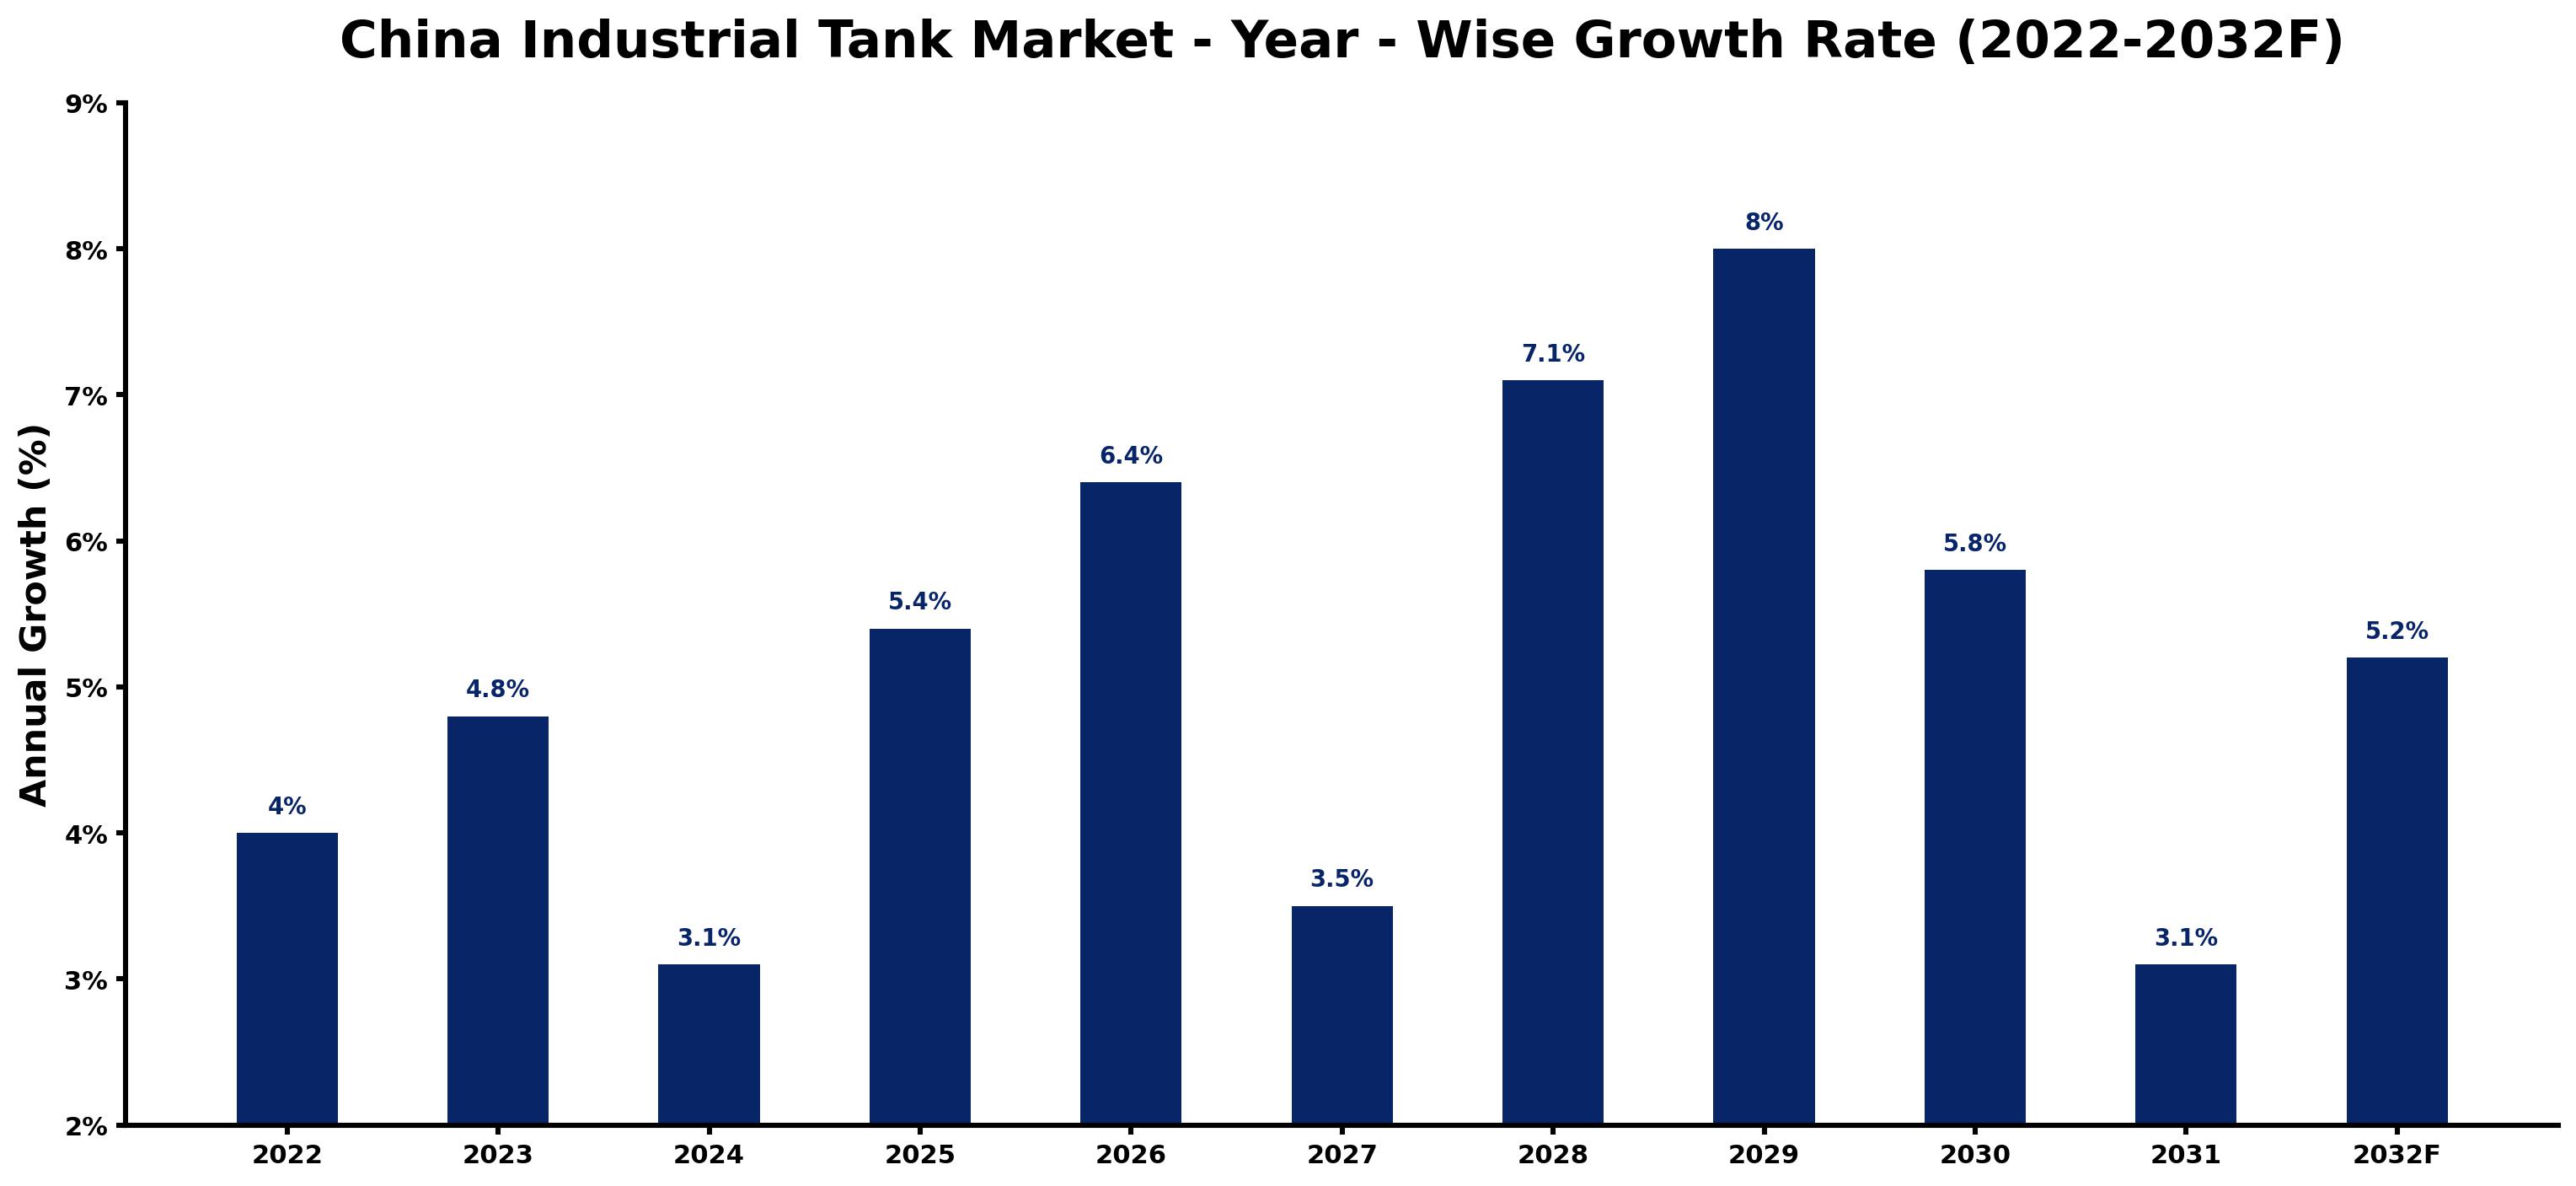
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.0 | The market showed stable growth, driven by consistent demand from various industries, particularly oil and chemical storage. |
| 2023 | 4.8 | Growth accelerated due to increased investments in industrial infrastructure and water treatment facilities, supporting tank production. |
| 2024 | 3.1 | Demand slowed as manufacturers adjusted to new regulations and market conditions affecting production timelines. |
| 2025 | 5.4 | A resurgence in growth occurred, supported by rising oil and chemical storage needs from local refineries. |
| 2026 | 6.4 | Expansion is expected to be driven by the National Industrial Transformation and Upgrade Plan, improving manufacturing standards. |
| 2027 | 3.5 | Growth is projected to decelerate as manufacturers adapt to compliance requirements following peak demand periods. |
| 2028 | 7.1 | An uptick in demand is anticipated as investments in water treatment projects increase due to the Water Pollution Prevention and Control Action Plan. |
| 2029 | 8.0 | The market is expected to peak with growth driven by LNG infrastructure expansion and energy needs from coastal regions. |
| 2030 | 5.8 | Growth is projected to slow as the market stabilises after the previous peak in demand for storage solutions. |
| 2031 | 3.1 | A further slowdown is expected as manufacturers face challenges in meeting updated compliance requirements for pressure vessels. |
| 2032 | 5.2 | Demand is anticipated to increase again as new projects in water treatment and gas storage emerge, driven by government initiatives. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Tank Market Synopsis
The China Industrial Tank Market encompasses large containers designed for storing liquids and gases, primarily made from stainless or carbon steel. These tanks are essential for applications such as oil and chemical storage, water treatment, and industrial gas storage. The market is expanding, driven by investments in infrastructure and increasing demand from downstream processing industries. The water treatment sector accounted for 25% of tank demand in 2022, underscoring the importance of sustainable practices in growth. Initiatives like the Water Pollution Prevention and Control Action Plan are supporting the market's potential.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising investments in water treatment facilities | Driver | High | Water Treatment Plants |
| Increased demand for LNG storage due to energy needs | Driver | High | LNG & Oxygen Handling |
| Growing need for environmentally friendly tank solutions | Opportunity | High | Storage Tanks |
| Expansion of LNG infrastructure in coastal regions | Opportunity | High | LNG & Oxygen Handling |
| Compliance with stringent safety regulations | Restraint | High | Pressure Tanks |
| High manufacturing costs for advanced materials | Restraint | Medium | Stainless Steel |
| Supply chain disruptions affecting material availability | Challenge | High | Storage Tanks |
| Competition from alternative storage solutions | Challenge | Medium | Mixing Tanks |
Evaluation of Drivers in China Industrial Tank Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased investments in water treatment projects | Water Treatment Plants | This demand is driven by the need for improved urban water management, with the sector accounting for 25% of tank demand in 2022. |
| Rising LNG storage requirements | LNG & Oxygen Handling | The National Development and Reform Commission's LNG Infrastructure Development Plan aims to increase storage capacity by 50% by 2025, stimulating market growth. |
| Growing production in pharmaceuticals | Mixing Tanks | The demand for mixing tanks is rising due to increased production in the pharmaceutical sector, which requires efficient mixing solutions to meet market needs. |
| Expansion of oil and chemical industries | Oil & Chemical Storage | Carbon steel tanks are commonly used in oil refineries across China, reflecting the sector's ongoing growth and investment in infrastructure. |
| Government initiatives promoting green manufacturing | Storage Tanks | The Green Manufacturing Program targets a 30% reduction in emissions by 2030, encouraging sustainable tank production and compliance among manufacturers. |
The Industrial Tank market in China is growing due to increased investments in water treatment facilities, heightened LNG storage requirements, and expanded production in pharmaceuticals. In 2022, the water treatment sector accounted for 25% of tank demand, underscoring the necessity for improved urban water management. A substantial increase in LNG storage capacity is anticipated, further driving market growth. The pharmaceutical sector's rising production is also generating a demand for efficient mixing solutions.
Evaluation of Restraints in China Industrial Tank Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Compliance with updated safety regulations | Pressure Tanks | The updated regulations from the State Administration for Market Regulation increase compliance costs for manufacturers, impacting pricing strategies and market competitiveness. |
| High costs of advanced materials | Stainless Steel | The preference for stainless steel due to its durability leads to higher production costs, affecting pricing strategies for producers in the oil sector. |
| Supply chain disruptions | Storage Tanks | Material shortages from global supply chain issues delay production timelines and increase costs for manufacturers, particularly in the chemical industry. |
| Competition from alternative storage solutions | Mixing Tanks | Emerging technologies in storage solutions create competitive pressure, affecting market share for traditional tank manufacturers in pharmaceuticals. |
| Limited access to financing for smaller manufacturers | Storage Tanks | Smaller manufacturers struggle to secure funding for compliance upgrades, limiting their market competitiveness and ability to innovate. |
China Industrial Tank Market Challenges
China's industrial tank market faces supply chain delays, as over 1,000 registered manufacturers struggle to meet rising demand, leading to project delays for buyers in the oil and chemical sectors. Technological limitations impede the adoption of advanced materials, resulting in inefficiencies that raise production costs for manufacturers reliant on outdated methods. A shortage of skilled workers in the tank manufacturing industry leads to extended training periods, increasing operational costs for suppliers and prolonging production timelines. Buyers in the pharmaceutical sector are contending with price hikes for mixing tanks, which can inflate project budgets by up to 15%.
Trends in the China Industrial Tank Market
Several trends are reshaping the China Industrial Tank Market; the most important are set out below.
- Launch of the Green Manufacturing Program: In 2023, the Ministry of Ecology and Environment initiated the Green Manufacturing Program, targeting a 30% reduction in emissions by 2030. This shift encourages manufacturers to adopt sustainable practices, promoting innovation in tank production and compliance.
- Increase in LNG storage capacity: The National Development and Reform Commission's LNG Infrastructure Development Plan aims to boost storage capacity by 50% by 2025. This initiative is driving demand for LNG storage tanks, particularly in coastal provinces like Guangdong, enhancing supply security.
- Growing demand for mixing tanks in pharmaceuticals: The pharmaceutical sector is increasingly relying on mixing tanks, with a projected CAGR of 7.2% from 2026 to 2032. This trend reflects the industry's expansion and need for efficient production processes, pushing manufacturers to innovate.
- Shift towards environmentally friendly materials: Manufacturers are prioritising the use of advanced materials in tank production, spurred by government initiatives. This trend is evident in the rising adoption of sustainable practices across the industry, improving overall efficiency.
Investment Opportunities in the China Industrial Tank Market
The following opportunities in the China Industrial Tank Market pair current demand with a clear way in.
- Investment gap in green tank solutions: With a projected 30% reduction in emissions by 2030, there is a growing opportunity for investment in environmentally friendly tank solutions, particularly among manufacturers in urban areas seeking to comply with regulations.
- Timing aligns with infrastructure expansion: As the National Development and Reform Commission targets a 50% increase in LNG storage capacity by 2025, opportunities arise for suppliers to enter the market with innovative solutions tailored to new infrastructure needs.
- Focus on coastal regions for LNG storage: Coastal provinces like Guangdong present significant opportunities for LNG storage tank suppliers, given the government's investment in infrastructure and energy needs, creating a favourable market environment.
- Partnerships for advanced material adoption: Manufacturers can explore joint ventures to adopt advanced materials in tank production, supported by government initiatives for sustainable practices, enhancing their competitive edge.
Government Initiatives in the China Industrial Tank Market
In 2023, the Ministry of Ecology and Environment launched the Green Manufacturing Program, targeting a 30% reduction in emissions by 2030. This measure complements existing regulations by promoting sustainable practices in tank production, benefiting both producers and end-users. The National Industrial Transformation and Upgrade Plan aims to improve manufacturing standards, ensuring compliance and enhancing overall quality for manufacturers in the sector.
The State Administration for Market Regulation oversees the implementation of safety regulations for pressure vessels, ensuring compliance among manufacturers. This agency also approves certifications for new tank designs, promoting innovation in the industry. Additionally, the Ministry of Ecology and Environment funds initiatives aimed at improving water treatment facilities, supporting the industrial tank market by enhancing infrastructure and compliance.
Future Insight of the China Industrial Tank Market
The industrial tank market in China is poised for substantial changes by 2032, driven by the government's 10 billion RMB investment in LNG infrastructure and initiatives promoting eco-friendly manufacturing practices. The shift towards advanced materials will improve tank durability and lower maintenance costs for suppliers. The "Water Pollution Prevention and Control Action Plan" is expected to boost demand for water treatment tanks, projected to account for 25% of total tank demand. Growth in the pharmaceutical sector will further elevate the need for mixing tanks, presenting new opportunities for manufacturers.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Tank Type – Storage Tanks Dominated, Mixing Tanks Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, Storage Tanks took a 38% share of tank type in 2025, more than any other category. Storage tanks hold the largest share in China's industrial tank market due to their essential role in safely storing liquids and chemicals across various sectors. Their extensive use in oil and chemical storage highlights their critical importance in supporting industrial operations. Mixing Tanks are projected to grow fastest, at a CAGR of 7.2% during 2026–2032. Mixing tanks are witnessing rapid growth as the pharmaceutical sector expands, requiring efficient solutions for combining substances. This trend is further supported by the industry's shift towards advanced manufacturing practices, ensuring continued demand for mixing tanks. Suppliers should focus on developing mixing tanks to capitalise on the rising demand from the pharmaceutical industry.
By Material Type – Stainless Steel Dominated, Polypropylene Expected to Grow Fastest
The largest material type category in 2025 was Stainless Steel, with a 45% share of total revenue. Stainless steel tanks dominate the market share due to their superior corrosion resistance and durability, making them ideal for the food and beverage industry. Their reliability in diverse applications ensures a steady demand from manufacturers across various sectors. Over 2026–2032, Polypropylene is expected to post the fastest growth, at a CAGR of 8.1%. Polypropylene tanks are gaining traction as they cater to specific applications, particularly in niche markets that require lightweight and chemical-resistant options. This growth is driven by the increasing need for versatile materials in tank production. Manufacturers should consider expanding their product lines to include polypropylene tanks to meet the evolving needs of niche markets.
By Application – Oil & Chemical Storage Dominated, Water Treatment Plants Expected to Grow Fastest
In 2025, Oil & Chemical Storage led the application split with a 49% share. Oil and chemical storage commands the largest share of the industrial tank market, driven by robust activities in China's petroleum and chemical sectors. The significant volume of materials stored in these tanks underscores their vital role in facilitating essential industrial processes. Water Treatment Plants are set to record the highest CAGR in this split, 7.4% over 2026–2032. Water treatment plants are experiencing the highest growth due to government initiatives aimed at enhancing water quality and treatment infrastructure. This focus on environmental sustainability is significantly increasing the demand for tanks designed for water treatment applications. Suppliers must align their products with government initiatives to effectively participate in the growing market for water treatment tanks.
By Distribution Channel – Direct Manufacturer Sales Dominated, Engineering Suppliers Expected to Grow Fastest
Direct Manufacturer Sales accounted for a 52% market share by distribution channel in 2025. Direct manufacturer sales dominate the market share as they offer customers direct access to a wide range of industrial tanks, ensuring competitive pricing and tailored solutions. This channel is preferred by buyers seeking reliability and quality assurance in their purchases. The quickest growth will come from Engineering Suppliers, forecast to expand at a CAGR of 7.1% between 2026 and 2032. Engineering suppliers are rapidly increasing their market share by integrating tanks into larger systems, appealing to industries that prefer comprehensive solutions. Their ability to provide value-added services is driving growth in this distribution segment. Suppliers should explore partnerships with engineering suppliers to expand their market presence and offer integrated solutions.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Tank Market Outlook
- Market Size of China Industrial Tank Market, 2025
- Forecast of China Industrial Tank Market, 2032
- Historical Data and Forecast of China Industrial Tank Revenues & Volume for the Period 2022 - 2032F
- China Industrial Tank Market Trend Evolution
- China Industrial Tank Market Drivers and Challenges
- China Industrial Tank Price Trends
- China Industrial Tank Porter's Five Forces
- China Industrial Tank Industry Life Cycle
- Historical Data and Forecast of China Industrial Tank Market Revenues & Volume By Tank Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tank Market Revenues & Volume By Storage Tanks for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tank Market Revenues & Volume By Mixing Tanks for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tank Market Revenues & Volume By Pressure Tanks for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tank Market Revenues & Volume By Cryogenic Tanks for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tank Market Revenues & Volume By Material Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tank Market Revenues & Volume By Stainless Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tank Market Revenues & Volume By Polypropylene for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tank Market Revenues & Volume By Carbon Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tank Market Revenues & Volume By Insulated Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tank Market Revenues & Volume By Application for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tank Market Revenues & Volume By Oil & Chemical Storage for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tank Market Revenues & Volume By Water Treatment Plants for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tank Market Revenues & Volume By Industrial Gas Storage for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tank Market Revenues & Volume By LNG & Oxygen Handling for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tank Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tank Market Revenues & Volume By Direct Manufacturer Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tank Market Revenues & Volume By Engineering Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tank Market Revenues & Volume By Industrial Distributors for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tank Market Revenues & Volume By Online B2B Platforms for the Period 2022 - 2032F
- China Industrial Tank Import Export Trade Statistics
- Market Opportunity Assessment By Tank Type
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By Application
- Market Opportunity Assessment By Distribution Channel
- China Industrial Tank Top Companies Market Share
- China Industrial Tank Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Tank Company Profiles
- China Industrial Tank Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Tank Type
- Storage Tanks
- Mixing Tanks
- Pressure Tanks
- Cryogenic Tanks
By Material Type
- Stainless Steel
- Polypropylene
- Carbon Steel
- Insulated Steel
By Application
- Oil & Chemical Storage
- Water Treatment Plants
- Industrial Gas Storage
- LNG & Oxygen Handling
By Distribution Channel
- Direct Manufacturer Sales
- Engineering Suppliers
- Industrial Distributors
- Online B2B Platforms































