China Industrial Water Solutions Market Size & Growth Rate
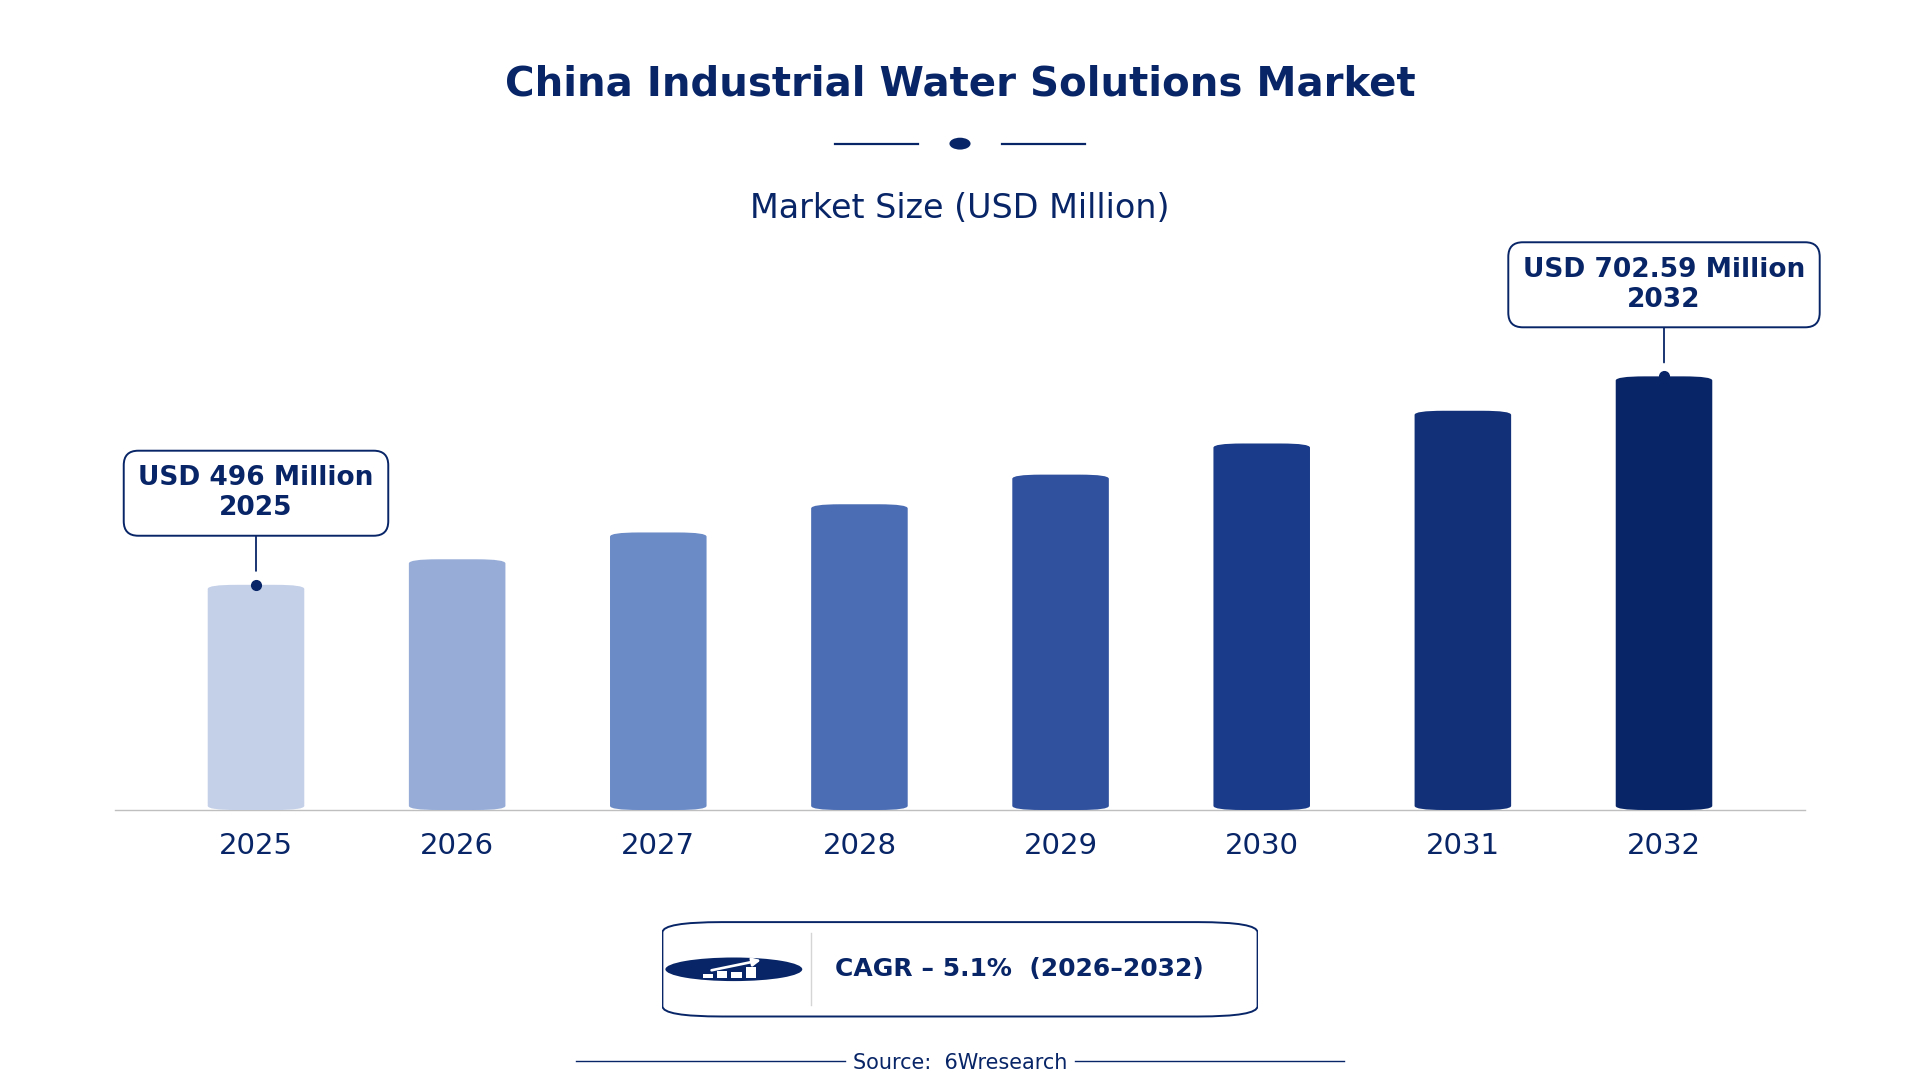
According to 6Wresearch internal database and industry insights, the China Industrial Water Solutions Market was valued at USD 496.0 million in 2025 and is projected to reach USD 702.59 million by 2032, growing at a CAGR of approximately 5.1% during 2026–2032.
China Industrial Water Solutions Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Water Solutions Market |
| Market Size 2025 | USD 496.0 million |
| Market Size 2032 | USD 702.59 million |
| Absolute Growth 2025–2032 | USD 206.59 million |
| CAGR 2026–2032 | 5.1% |
| Peak Annual Growth | 7.9% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Industrial Water Solutions, 2025 | Water Recycling Systems (37% share) |
| Leading Solution Type, 2025 | Zero Liquid Discharge (42% share) |
| Leading Treatment Process, 2025 | Filtration & Evaporation (35% share) |
| Leading Technology Used, 2025 | RO Desalination (49% share) |
| Leading End User Application, 2025 | Petrochemical Refineries (41% share) |
| Fastest-Growing Industrial Water Solutions | Desalination Systems (6.1% CAGR) |
| Fastest-Growing Treatment Process | Chemical Dosing (6.5% CAGR) |
| Fastest-Growing Technology Used | Membrane Bioreactor (7.5% CAGR) |
| Fastest-Growing End User Application | Fertilizer Manufacturing (7.6% CAGR) |
| Growing Sector | Fertilizer Manufacturing |
| Key End Users | Petrochemical Refineries, Chemical Plants, Paper & Pulp Industry, Fertilizer Manufacturing |
China Industrial Water Solutions Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
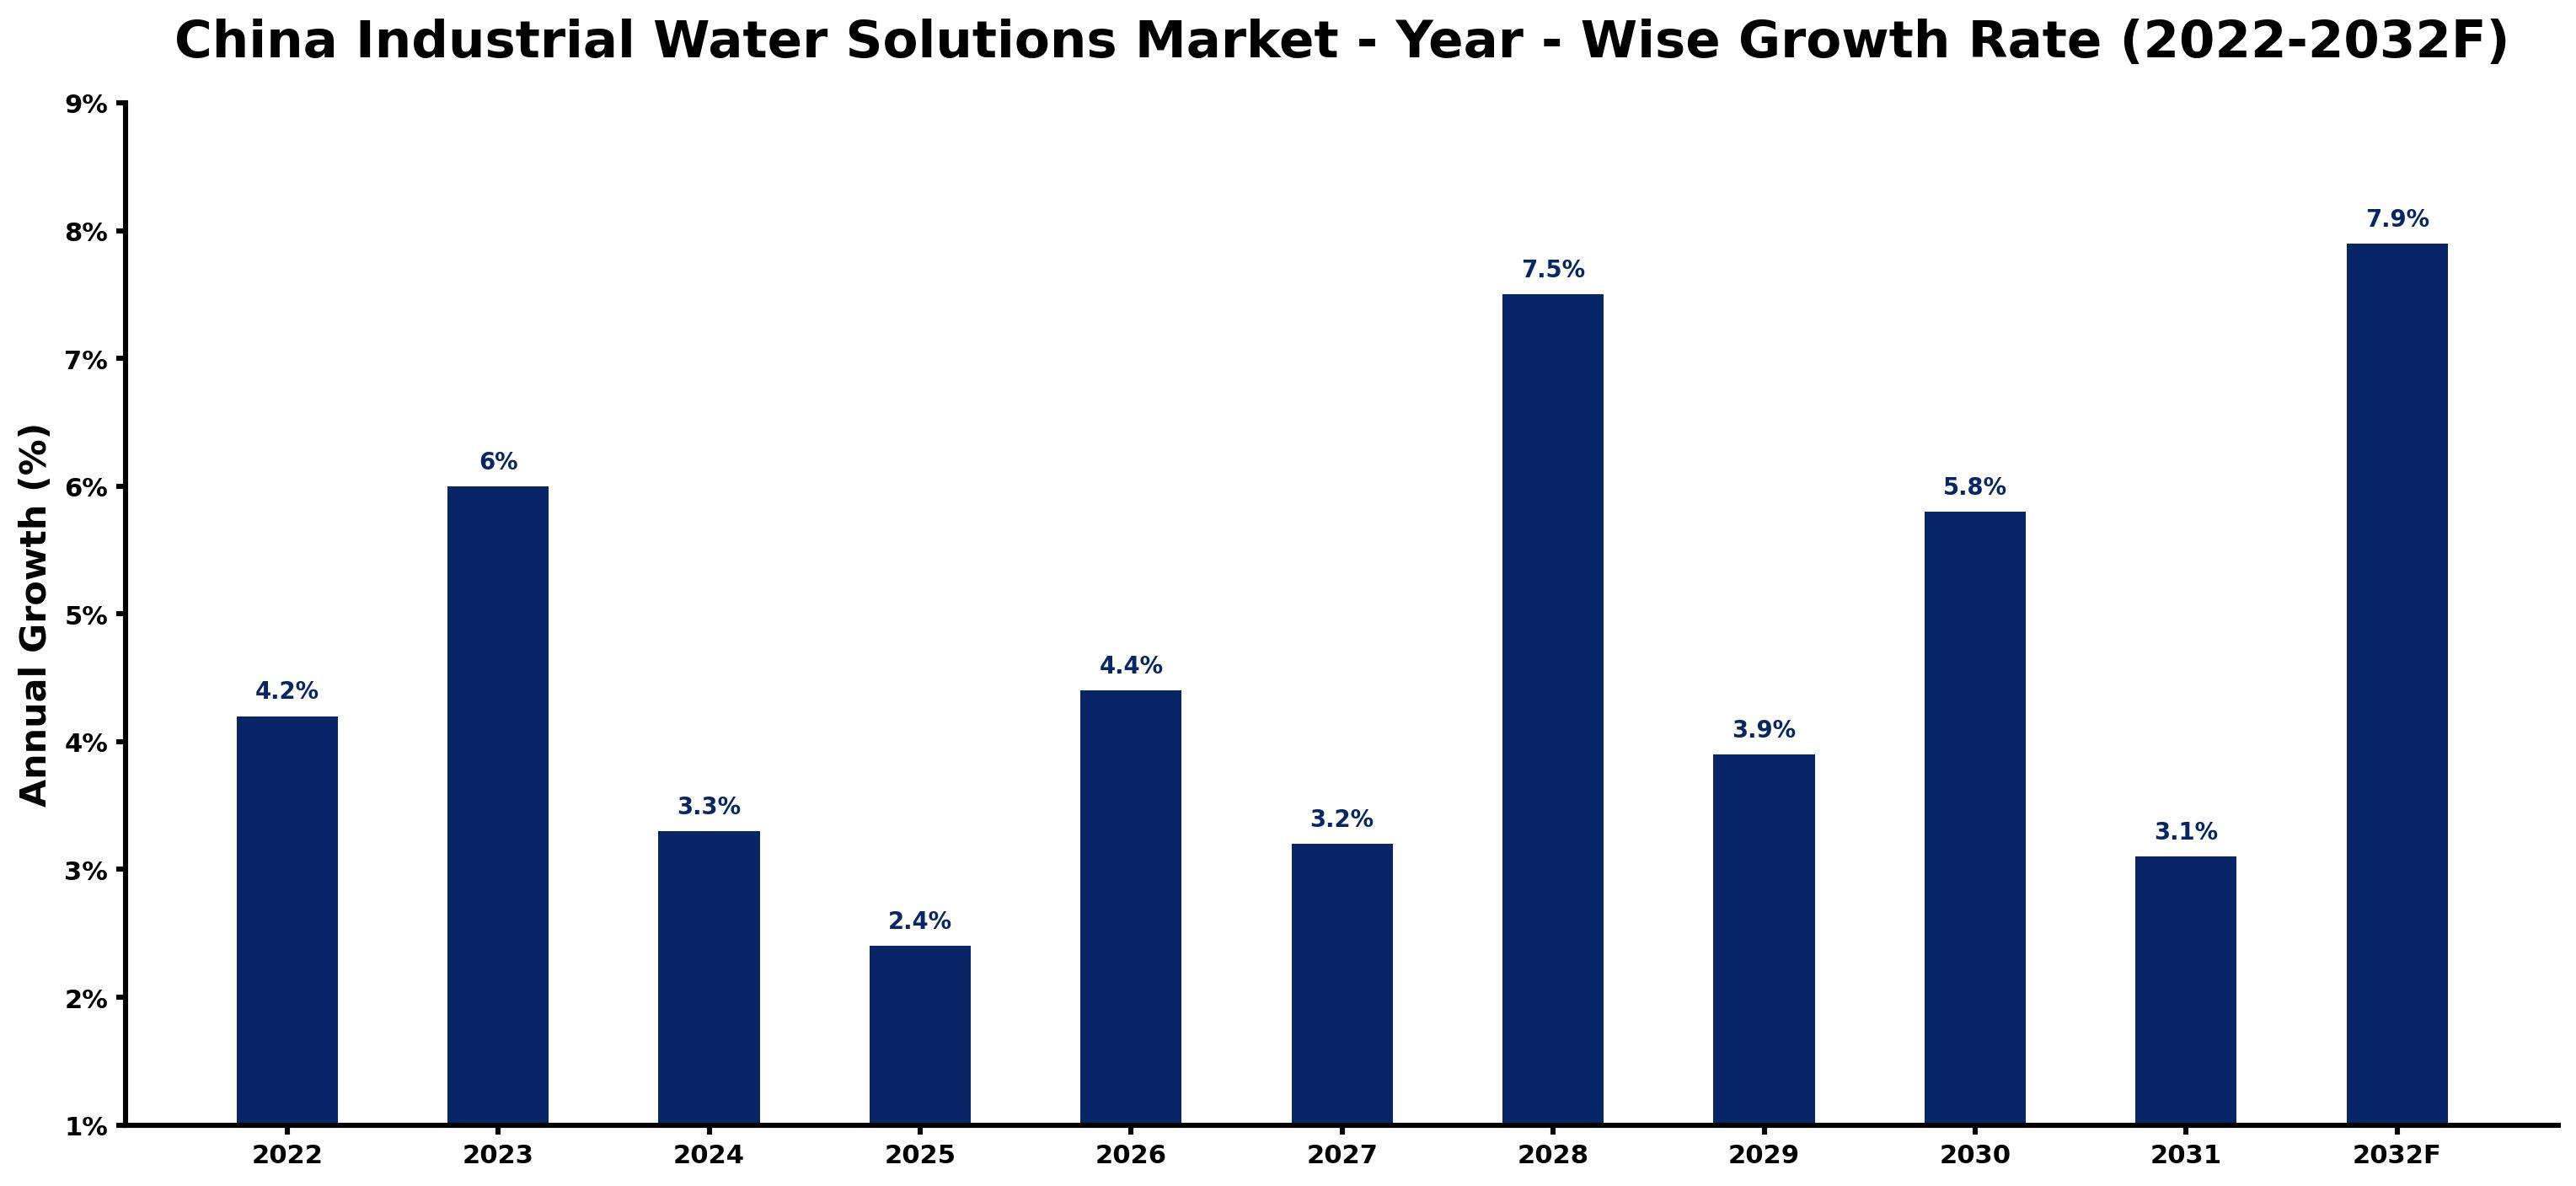
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.2 | The market experienced steady growth, driven by the National Development and Reform Commission's Water Resource Management Plan promoting water efficiency. |
| 2023 | 6.0 | Demand surged due to the implementation of the Industrial Water Conservation Initiative, which encouraged advanced water treatment technologies. |
| 2024 | 3.3 | Growth slowed as industries adjusted to the updated National Water Quality Standards in wastewater discharge. |
| 2025 | 2.4 | The market continued to grow, albeit at a slower pace, reflecting ongoing efforts to achieve a 15% reduction in industrial water consumption by 2025. |
| 2026 | 4.4 | An uptick in demand occurred as industries adopted more efficient water recycling systems under the Green Manufacturing Program. |
| 2027 | 3.2 | Growth decelerated as the market faced challenges in meeting stricter regulations from the Water Pollution Prevention and Control Action Plan. |
| 2028 | 7.5 | Demand is expected to rise significantly as industries expand desalination capacities in coastal regions. |
| 2029 | 3.9 | Growth is projected to slow as industries consolidate their water management practices amid rising operational costs. |
| 2030 | 5.8 | An increase in demand is anticipated as the fertilizer manufacturing sector expands operations, requiring more water solutions. |
| 2031 | 3.1 | The market will see a slowdown as industries face rising operational costs due to compliance with new regulations. |
| 2032 | 7.9 | Demand is expected to peak, driven by the government's zero liquid discharge initiative and increasing investments in water treatment technologies. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Water Solutions Market Synopsis
Industrial Water Solutions in China focus on advanced technologies for treating and recycling water for industrial applications. These solutions are essential for manufacturing processes, cooling systems, and boiler operations. The China Industrial Water Solutions Market reached a value of 20 billion USD in 2022, driven by increasing industrial activities and ongoing water conservation initiatives. Key demand sources include major industrial regions like the Yangtze River Delta, which further stimulate market growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing adoption of water recycling technologies | Driver | High | Water Recycling Systems |
| Growing demand for fresh water in industrial processes | Driver | High | Desalination Systems |
| Investment in water-efficient technologies | Opportunity | High | Boiler Water Treatment |
| Expansion of industrial operations in urban areas | Opportunity | Medium | Cooling Water Treatment |
| Stricter regulations on wastewater discharge | Restraint | High | Water Recycling Systems |
| High initial investment costs for advanced systems | Restraint | Medium | Desalination Systems |
| The Industrial Water Solutions market in China faces regulatory challenges | Challenge | High | Boiler Water Treatment |
| Competition from alternative water sourcing methods | Challenge | Medium | Cooling Water Treatment |
Evaluation of Drivers in China Industrial Water Solutions Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased industrial activities | Water Recycling Systems | This drives demand for solutions that reduce water consumption, with a recycling rate of 70% reported in 2022. |
| Expansion of desalination capacities | Desalination Systems | The total installed capacity reached 2.5 million cubic meters per day in 2023, meeting fresh water needs. |
| Government initiatives promoting water conservation | Boiler Water Treatment | The State Administration for Market Regulation mandates treatment to maintain boiler efficiency, influencing procurement decisions. |
| Rising demand from the petrochemical sector | Cooling Water Treatment | Petrochemical refineries accounted for 41% of industrial water usage in 2025, boosting demand for treatment solutions. |
| Technological advancements in water treatment | Chemical Dosing | Investment in this area is increasing due to stricter regulations on water quality, prompting upgrades. |
The petrochemical sector, a major user of cooling water treatment solutions, accounted for 41% of industrial water usage in 2025. The total installed capacity of desalination plants reached 2.5 million cubic meters per day in 2023, addressing fresh water needs. These factors stimulate demand for effective water treatment solutions across various industries, particularly in the Yangtze River Delta region.
Evaluation of Restraints in China Industrial Water Solutions Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High initial investment costs for advanced water treatment systems | Desalination Systems | This limits adoption among smaller enterprises, affecting overall market growth. |
| Stricter regulations on wastewater discharge | Water Recycling Systems | Compliance requires considerable investment in technology upgrades, straining budgets. |
| Limited awareness of water conservation technologies | Boiler Water Treatment | This hinders market penetration for newer, more efficient solutions, affecting adoption rates. |
| Challenges in integrating new technologies into existing systems | Chemical Dosing | This can delay implementation and increase operational costs for suppliers and buyers. |
| Competition from alternative water sourcing methods | Cooling Water Treatment | This diverts investment away from traditional water treatment solutions, impacting market share. |
China Industrial Water Solutions Market Challenges
Buyers in the China Industrial Water Solutions market face technological challenges, as many existing systems struggle to keep pace with the demands of the rapidly growing manufacturing sector. This issue stems from outdated infrastructure, leading to treatment delays that disrupt production timelines for manufacturers. Additionally, varying quality standards enforced by the Ministry of Ecology and Environment complicate compliance for suppliers, raising operational costs by as much as 10%. High costs associated with upgrading to advanced treatment technologies can burden buyers, with estimates suggesting these investments may take up to 15% of their annual budgets.
Trends in the China Industrial Water Solutions Market
Four trends stand out in the China Industrial Water Solutions Market.
- Shift towards Zero Liquid Discharge: Since 2021, industries in China have been adopting Zero Liquid Discharge systems to minimize wastewater disposal. This shift is supported by the government's goal to achieve zero liquid discharge by 2025, promoting sustainability in manufacturing.
- Growing focus on Chemical Dosing technologies: The chemical dosing market is experiencing increased investment due to stricter regulations on water quality. In 2023, the annual water treatment technology conference highlighted advancements in this area, driving demand for effective solutions.
- Expansion of Desalination capacities: The total installed capacity of desalination plants in China reached 2.5 million cubic meters per day in 2023. This expansion is vital for addressing fresh water scarcity in industrial regions, particularly in coastal areas.
- Increased emphasis on water recycling in Petrochemical sector: The petrochemical industry is prioritizing water recycling solutions, accounting for 41% of industrial water usage in 2025. This focus aligns with national goals for sustainable water management.
Investment Opportunities in the China Industrial Water Solutions Market
Several openings in the China Industrial Water Solutions Market merit attention from investors.
- Investment in Water Recycling Systems: With a recycling rate of 70% in 2022, there is potential for investment in water recycling technologies. The petrochemical sector is a key buyer group, seeking efficient solutions to reduce water consumption.
- Supply of Desalination Technologies: The total installed capacity of desalination plants reached 2.5 million cubic meters per day in 2023, indicating a growing need for advanced desalination technologies. Coastal industrial hubs are ideal locations for investment.
- Development of Boiler Water Treatment Solutions: The government's mandate for boiler water treatment presents an opportunity for suppliers. The chemical industry is a major buyer group, requiring efficient systems to maintain operations.
- Expansion of Cooling Water Treatment Services: The petrochemical industry, a significant user of cooling water treatment, is projected to grow. This sector's demand for efficient solutions creates opportunities for service providers.
Government Initiatives in the China Industrial Water Solutions Market
The National Development and Reform Commission approved the 'Water Resource Management Plan' in 2021, which aims to improve water efficiency in industrial sectors. This measure requires industries to adopt advanced water treatment technologies, ensuring compliance with new standards. The plan targets a reduction in overall water consumption by 15% by 2025, promoting sustainable practices across various sectors. Additionally, the Ministry of Ecology and Environment launched the 'Industrial Water Conservation Initiative' in 2022, focusing on urban industries and encouraging the adoption of water recycling technologies.
The Ministry of Ecology and Environment oversees the implementation of various water management initiatives, including the 'Water Pollution Prevention and Control Action Plan' introduced in 2023. This plan strengthens regulations on wastewater treatment in industrial applications, ensuring compliance with updated standards. The Ministry also funds projects aimed at improving water quality and efficiency, supporting industries in adopting sustainable practices. Furthermore, the State Administration for Market Regulation plays a vital role in enforcing compliance with water treatment standards.
Future Insight of the China Industrial Water Solutions Market
Several forward-looking factors should support the China Industrial Water Solutions market over the coming years. The government's ambitious water conservation program aims to reduce industrial water consumption by 15% by 2025, driving demand for efficient treatment solutions. The total installed capacity of desalination plants is expected to reach 3 million cubic meters per day by 2025, enhancing supply capabilities. As the fertilizer manufacturing sector expands, suppliers will need to innovate to meet the rising demand for effective water solutions.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Industrial Water Solutions – Water Recycling Systems Dominated, Desalination Systems Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, Water Recycling Systems held a 37% share of the China Industrial Water Solutions Market by industrial water solutions in 2025. Water Recycling Systems hold the largest market share due to their critical role in reducing water consumption across various industries. For example, the Yangtze River Delta, a major industrial region, relies heavily on these systems to support its extensive manufacturing activities. Desalination Systems are set to record the highest CAGR in this split, 6.1% over 2026–2032. Desalination Systems are projected to grow rapidly, fuelled by the increasing demand for fresh water in water-scarce regions, with the total installed capacity of desalination plants reaching 2.5 million cubic meters per day in 2023. As industrial activities expand, the need for reliable water sources will further accelerate this segment's growth. Suppliers should prioritise the development of desalination technologies to cater to the rising demand from various industrial sectors.
By Solution Type – Zero Liquid Discharge Dominated and Is Expected to Record the Fastest Growth
The largest solution type category in 2025 was Zero Liquid Discharge, with a 42% share of total revenue. Zero Liquid Discharge holds the largest share as it is required for minimizing wastewater disposal, aligning with government regulations and sustainability goals. This method is increasingly adopted across various industries to comply with stringent environmental standards. Its lead should widen, with a projected CAGR of 6.7% during 2026–2032, the highest in this split. Zero Liquid Discharge is also the fastest-growing solution type, as industries strive to achieve zero liquid discharge by 2025, driven by regulatory pressures and environmental commitments. This dual role reinforces its market dominance and growth potential. Suppliers must invest in Zero Liquid Discharge technologies to stay competitive in a market that prioritises sustainability.
By Treatment Process – Filtration & Evaporation Dominated, Chemical Dosing Expected to Grow Fastest
Filtration & Evaporation accounted for a 35% market share by treatment process in 2025. Filtration & Evaporation hold the largest market share due to their established role in water purification across various industrial sectors. Their widespread application in regions like the Yangtze River Delta ensures a strong demand for these methods. Chemical Dosing is projected to grow fastest, at a CAGR of 6.5% during 2026–2032. Chemical Dosing is witnessing rapid growth as industries increasingly focus on water quality amidst tightening regulations. This trend is exemplified by the government's subsidy program for water-efficient technologies launched in 2022, which is expected to boost demand. Suppliers must prioritise the development of advanced chemical dosing solutions to meet the rising standards for water quality management.
By Technology Used – RO Desalination Dominated, Membrane Bioreactor Expected to Grow Fastest
In 2025, RO Desalination led the technology used split with a 49% share. RO Desalination leads the market as a popular method for converting seawater into potable water, which is essential for industries located in coastal areas. Its established technology and efficiency contribute to a substantial market share. The quickest growth will come from Membrane Bioreactor, forecast to expand at a CAGR of 7.5% between 2026 and 2032. Membrane Bioreactor technology is rapidly gaining traction due to its effectiveness in wastewater treatment, which is increasingly important as industries face stricter discharge regulations. The growing environmental awareness will further drive its adoption in the market. Suppliers should invest in advancing membrane bioreactor technologies to meet the surging demand for efficient wastewater treatment solutions.
By End User Application – Petrochemical Refineries Dominated, Fertilizer Manufacturing Expected to Grow Fastest
Petrochemical Refineries took a 41% share of end user application in 2025, more than any other category. Petrochemical Refineries dominate the market share as they are essential for cooling and processing operations that require substantial volumes of industrial water solutions. The continuous expansion of this sector in China guarantees ongoing demand for these applications. Fertilizer Manufacturing is set to record the highest CAGR in this split, 7.6% over 2026–2032. Fertilizer Manufacturing is the fastest-growing application, driven by its high water consumption needs as production ramps up. This growth is indicative of a broader trend towards more efficient water solutions in agriculture-related industries. Suppliers should focus on the fertilizer manufacturing sector to capture the increasing demand for effective industrial water solutions.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Water Solutions Market Outlook
- Market Size of China Industrial Water Solutions Market, 2025
- Forecast of China Industrial Water Solutions Market, 2032
- Historical Data and Forecast of China Industrial Water Solutions Revenues & Volume for the Period 2022 - 2032F
- China Industrial Water Solutions Market Trend Evolution
- China Industrial Water Solutions Market Drivers and Challenges
- China Industrial Water Solutions Price Trends
- China Industrial Water Solutions Porter's Five Forces
- China Industrial Water Solutions Industry Life Cycle
- Historical Data and Forecast of China Industrial Water Solutions Market Revenues & Volume By Industrial Water Solutions for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Water Solutions Market Revenues & Volume By Water Recycling Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Water Solutions Market Revenues & Volume By Desalination Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Water Solutions Market Revenues & Volume By Boiler Water Treatment for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Water Solutions Market Revenues & Volume By Cooling Water Treatment for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Water Solutions Market Revenues & Volume By Solution Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Water Solutions Market Revenues & Volume By Zero Liquid Discharge for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Water Solutions Market Revenues & Volume By Brine Treatment for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Water Solutions Market Revenues & Volume By Scale Prevention for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Water Solutions Market Revenues & Volume By Corrosion Control for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Water Solutions Market Revenues & Volume By Treatment Process for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Water Solutions Market Revenues & Volume By Filtration & Evaporation for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Water Solutions Market Revenues & Volume By Ion Exchange for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Water Solutions Market Revenues & Volume By Chemical Dosing for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Water Solutions Market Revenues & Volume By UV Disinfection for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Water Solutions Market Revenues & Volume By Technology Used for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Water Solutions Market Revenues & Volume By Membrane Bioreactor for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Water Solutions Market Revenues & Volume By RO Desalination for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Water Solutions Market Revenues & Volume By Thermal Deaeration for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Water Solutions Market Revenues & Volume By Ozonation for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Water Solutions Market Revenues & Volume By End User Application for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Water Solutions Market Revenues & Volume By Fertilizer Manufacturing for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Water Solutions Market Revenues & Volume By Paper & Pulp Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Water Solutions Market Revenues & Volume By Chemical Plants for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Water Solutions Market Revenues & Volume By Petrochemical Refineries for the Period 2022 - 2032F
- China Industrial Water Solutions Import Export Trade Statistics
- Market Opportunity Assessment By Industrial Water Solutions
- Market Opportunity Assessment By Solution Type
- Market Opportunity Assessment By Treatment Process
- Market Opportunity Assessment By Technology Used
- Market Opportunity Assessment By End User Application
- China Industrial Water Solutions Top Companies Market Share
- China Industrial Water Solutions Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Water Solutions Company Profiles
- China Industrial Water Solutions Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Industrial Water Solutions
- Water Recycling Systems
- Desalination Systems
- Boiler Water Treatment
- Cooling Water Treatment
By Solution Type
- Zero Liquid Discharge
- Brine Treatment
- Scale Prevention
- Corrosion Control
By Treatment Process
- Filtration & Evaporation
- Ion Exchange
- Chemical Dosing
- UV Disinfection
By Technology Used
- Membrane Bioreactor
- RO Desalination
- Thermal Deaeration
- Ozonation
By End User Application
- Fertilizer Manufacturing
- Paper & Pulp Industry
- Chemical Plants
- Petrochemical Refineries































