China Industrial Welding Market Size & Growth Rate
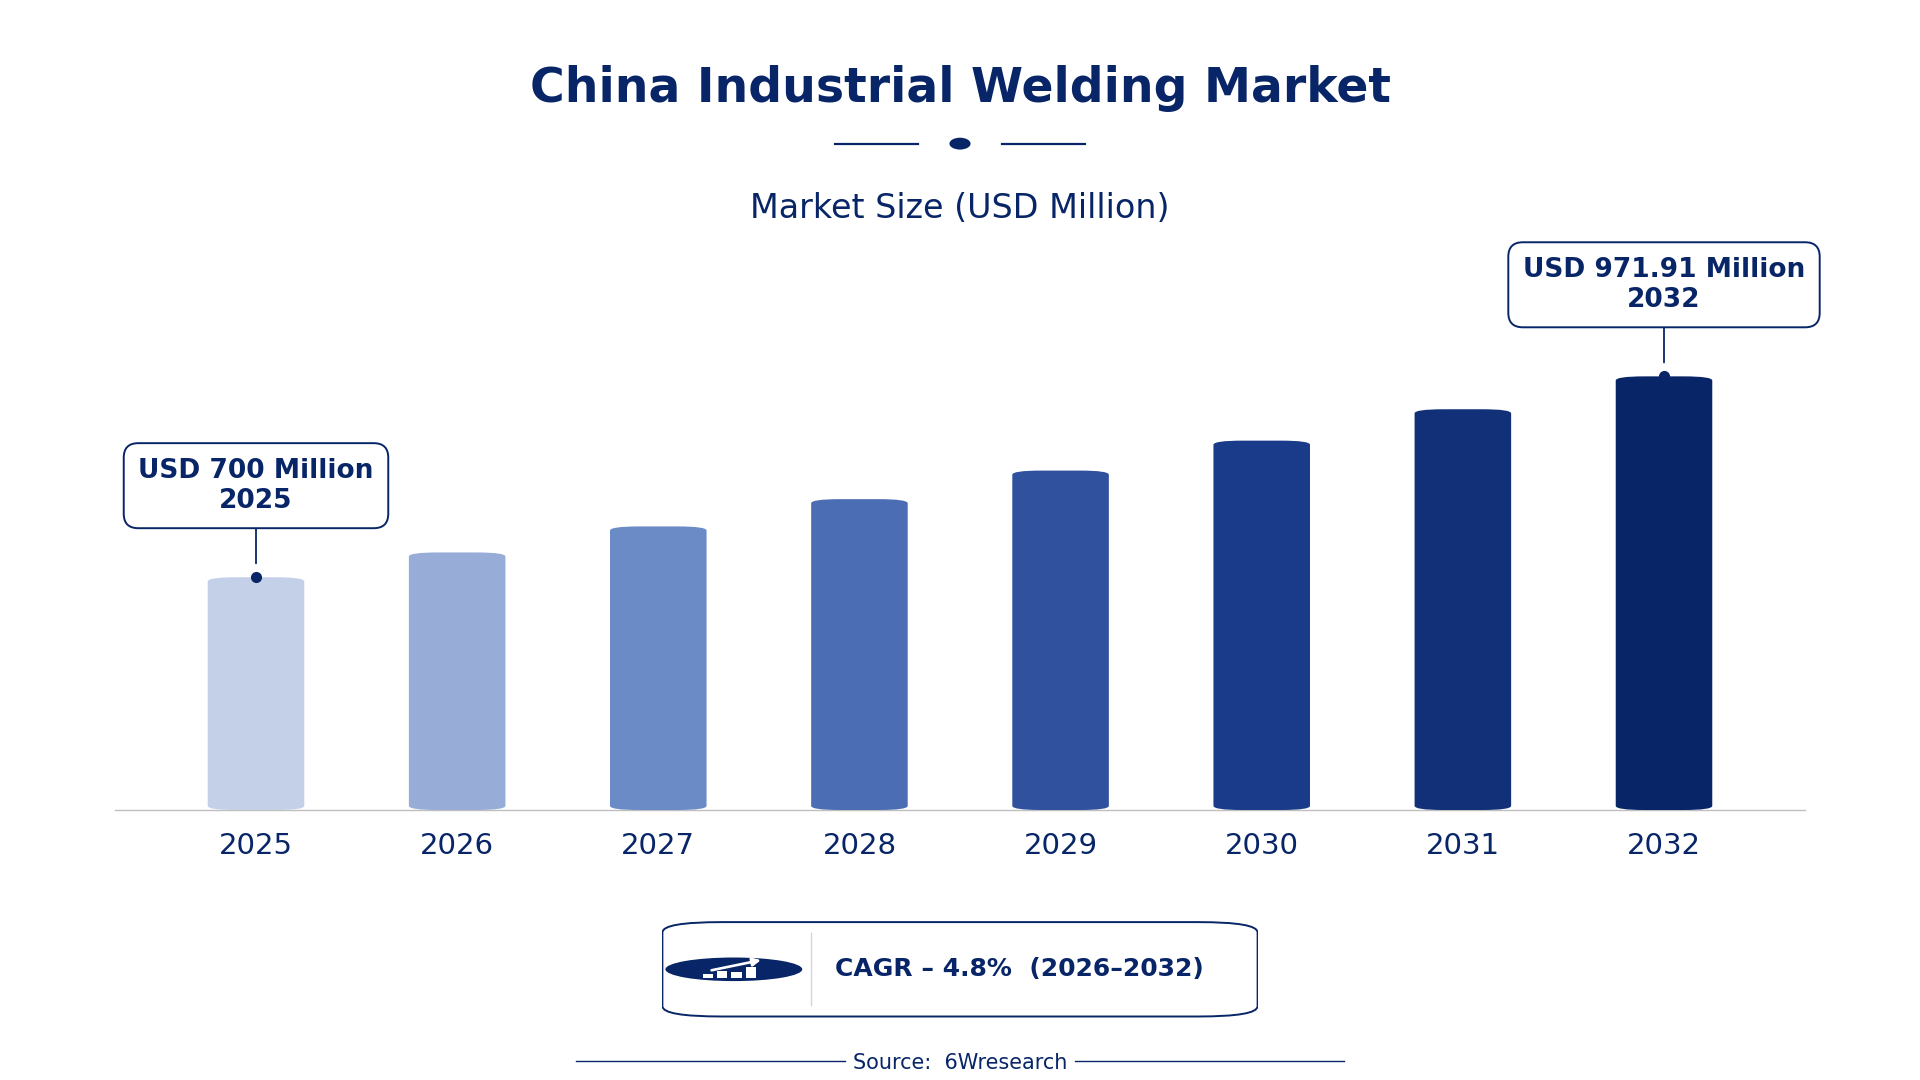
According to 6Wresearch internal database and industry insights, the China Industrial Welding Market was valued at USD 700.0 million in 2025 and is projected to reach USD 971.91 million by 2032, growing at a CAGR of approximately 4.8% during 2026–2032.
China Industrial Welding Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Welding Market |
| Market Size 2025 | USD 700.0 million |
| Market Size 2032 | USD 971.91 million |
| Absolute Growth 2025–2032 | USD 271.91 million |
| CAGR 2026–2032 | 4.8% |
| Peak Annual Growth | 7.3% in 2026 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Industrial Welding, 2025 | Arc Welding (42% share) |
| Leading Welding Type, 2025 | Gas Metal Arc (36% share) |
| Leading Equipment Type, 2025 | Semi-Automatic Welder (35% share) |
| Leading Application Area, 2025 | Automotive Assemblies (46% share) |
| Leading End User Industry, 2025 | Construction Sector (41% share) |
| Fastest-Growing Industrial Welding | Laser Welding (6.9% CAGR) |
| Fastest-Growing Welding Type | Gas Tungsten Arc (6.9% CAGR) |
| Fastest-Growing Equipment Type | CNC Laser Welder (6.5% CAGR) |
| Fastest-Growing Application Area | Aerospace Components (6.8% CAGR) |
| Fastest-Growing End User Industry | Shipbuilding Industry (6.2% CAGR) |
| Growing Sector | Construction Sector |
| Key End Users | Construction, Automotive, Shipbuilding, Machinery Manufacturers |
China Industrial Welding Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
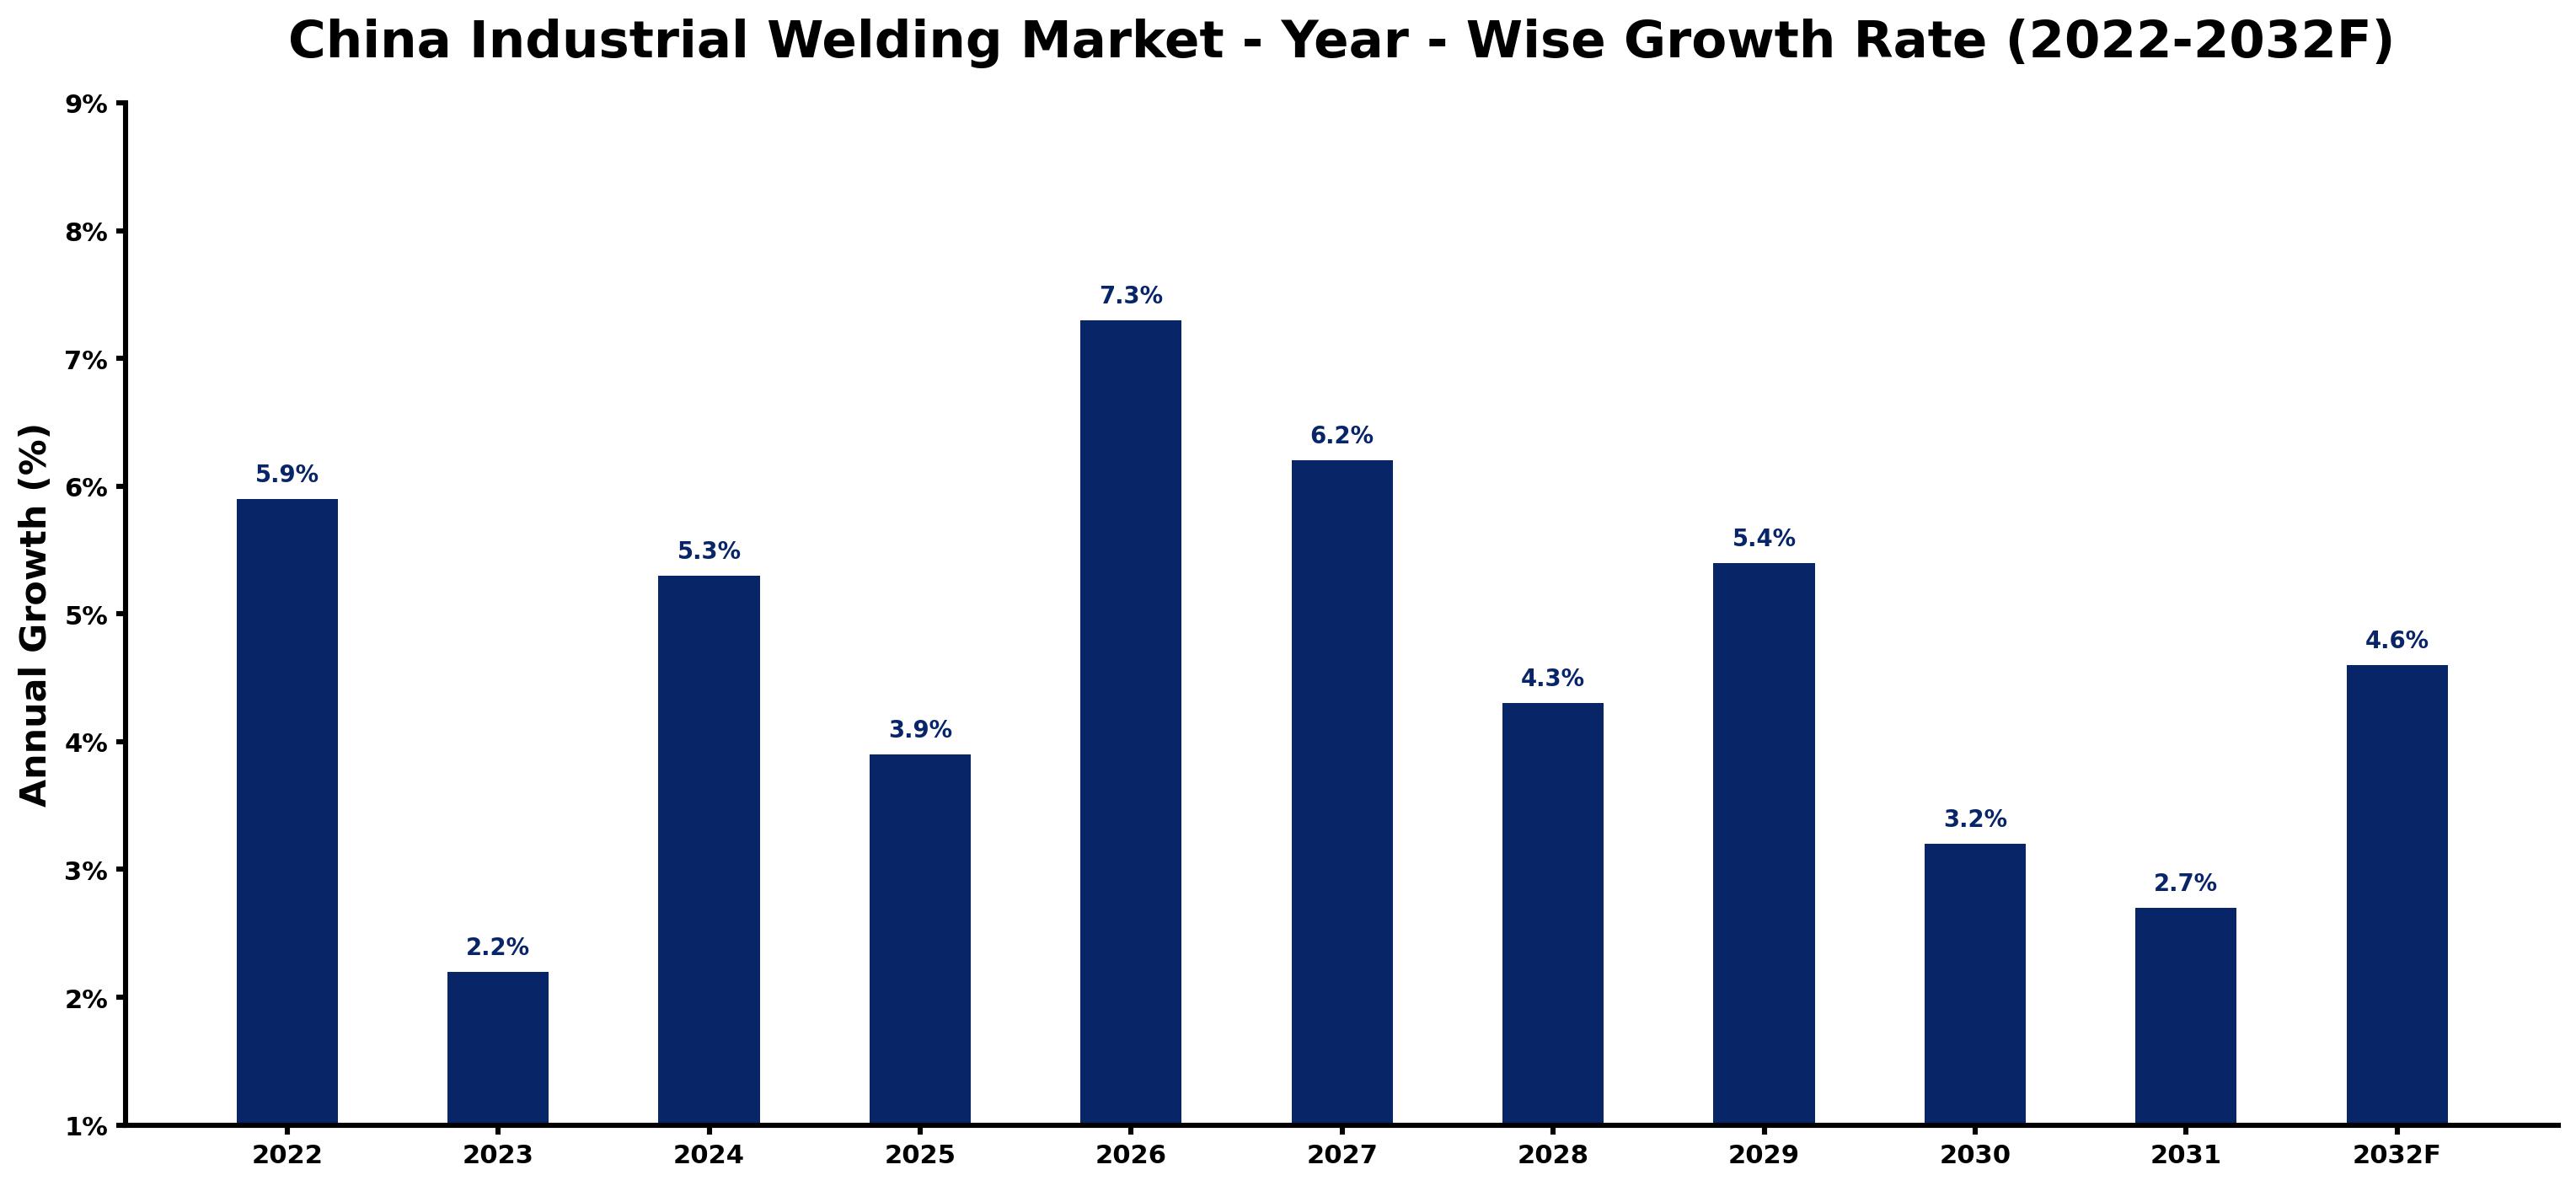
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.9 | The market experienced strong demand due to infrastructure projects and a growing workforce. |
| 2023 | 2.2 | Growth slowed as construction activity faced challenges from regulatory changes and the 'National Standard for Welding Equipment Safety'. |
| 2024 | 5.3 | A rebound in construction and automotive sectors contributed to increased welding demand. |
| 2025 | 3.9 | Demand remained steady but growth slowed as the market adjusted to the 'Made in China 2025' initiative. |
| 2026 | 7.3 | A surge in advanced manufacturing initiatives boosted demand for welding technologies. |
| 2027 | 6.2 | Growth slowed as the market stabilised after the previous year's surge in demand for welding. |
| 2028 | 4.3 | Continued investment in infrastructure projects led to a further slowdown in growth. |
| 2029 | 5.4 | A recovery in automotive production increased demand for welding applications. |
| 2030 | 3.2 | Growth slowed again as the market faced saturation in certain sectors. |
| 2031 | 2.7 | Demand continued to slow as the market adjusted to evolving technological standards. |
| 2032 | 4.6 | A resurgence in infrastructure projects is expected to drive growth in the coming years. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Welding Market Synopsis
The China Industrial Welding Market includes a range of welding processes used to join materials, primarily metals. Techniques such as arc welding, MIG, TIG, and laser welding are employed in sectors like construction, automotive, and shipbuilding. Growth in this market is driven by a workforce of over 800 million and substantial infrastructure investments, with the construction sector representing 30% of total welding demand in 2023. The 'Advanced Manufacturing 2025' initiative is encouraging automation and advanced welding technologies, leading to increased purchases across various industries.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| A growing workforce of over 800 million people drives demand for welding services across multiple sectors. | Driver | High | Arc Welding |
| The automotive industry is projected to require 5 million tons of welding materials annually by 2025, boosting demand. | Driver | High | Arc Welding |
| The construction sector's significant share of welding demand presents opportunities for suppliers to meet rising needs. | Opportunity | High | Construction Sector |
| Investment in advanced welding technologies creates openings for suppliers to offer innovative solutions. | Opportunity | High | Arc Welding |
| Regulatory updates may impose additional costs on manufacturers, affecting their pricing strategies. | Restraint | Medium | Arc Welding |
| The need for skilled labour in welding remains a challenge, limiting operational capacity in some regions. | Restraint | Medium | Arc Welding |
| The market still has to solve a few problems, including the need for skilled labour and regulatory compliance. | Challenge | High | Arc Welding |
| Technological advancements require continuous investment, which can strain smaller manufacturers' resources. | Challenge | Medium | Arc Welding |
Evaluation of Drivers in China Industrial Welding Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| A workforce exceeding 800 million people drives demand for welding services across multiple sectors. | Arc Welding | This large workforce supports various industries, increasing the need for welding applications. |
| The automotive industry is projected to require 5 million tons of welding materials annually by 2025, boosting demand. | Arc Welding | This demand surge is driven by the increasing production of vehicles and components. |
| The construction sector's substantial share of welding demand presents opportunities for suppliers to meet rising needs. | Construction Sector | With 30% of total welding demand in 2023, construction projects are a key driver. |
| Investment in advanced welding technologies creates openings for suppliers to offer new solutions. | Arc Welding | The 'Made in China 2025' strategy emphasises modern welding technologies, enhancing market opportunities. |
| The expansion of the shipbuilding industry necessitates advanced welding techniques and materials. | Shipbuilding Industry | China's shipbuilding sector is one of the largest globally, driving demand for high-quality welding. |
Growth in the Industrial Welding market in China stems from a large workforce that supports diverse industries and boosts demand for welding applications. The automotive sector is expected to require 5 million tons of welding materials annually by 2025, driving purchasing activities. The construction sector accounted for 30% of total welding demand in 2023, fuelled by ongoing infrastructure projects. Investment in advanced welding technologies, particularly under the 'Made in China 2025' strategy, opens up opportunities for suppliers to innovate and expand their offerings. The shipbuilding industry, one of the largest globally, requires advanced welding techniques, further stimulating market growth.
Evaluation of Restraints in China Industrial Welding Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Regulatory updates may impose additional costs on manufacturers, affecting their pricing strategies. | Arc Welding | The updated 'National Standard for Welding Equipment Safety' can lead to increased compliance costs. |
| The need for skilled labour in welding remains a challenge, limiting operational capacity in some regions. | Arc Welding | The 'Vocational Training Program for Welding' aims to improve skills but is still in progress. |
| Market saturation in certain sectors can limit growth opportunities for new entrants. | Arc Welding | As the market matures, competition increases, making it harder for new players to gain traction. |
| Technological advancements require continuous investment, which can strain smaller manufacturers' resources. | Arc Welding | Smaller manufacturers may struggle to keep up with the rapid pace of technological change. |
| The fluctuating prices of raw materials can affect the profitability of welding operations. | Arc Welding | The production of approximately 30 million tons of steel in 2022 impacts material costs for welding. |
China Industrial Welding Market Challenges
The China Industrial Welding Market still has to solve a few problems, and the first is intense competition among producers. This saturation forces many to lower prices, eroding profit margins and limiting investment in quality improvements for suppliers. Buyers struggle to secure consistent quality due to varying standards, which can lead to project delays, particularly in construction, accounting for 30% of total demand in 2023. Rising raw material costs, especially steel, which was produced at approximately 30 million tons in 2022, strain budgets for buyers, while supply chain disruptions delay the delivery of essential equipment, complicating timelines for contractors.
Trends in the China Industrial Welding Market
Four trends stand out in the China Industrial Welding Market.
- Shift towards Automation in Welding Processes: The market is increasingly adopting automated welding technologies, supported by the 'Advanced Manufacturing 2025' initiative. This shift is expected to result in a 20% increase in automation adoption by 2026.
- Growing Demand for Laser Welding: Laser welding is becoming more popular in the manufacturing sector, especially for high-precision applications. This method's efficiency is reflected in its projected CAGR of 6.9% from 2026 to 2032, indicating a notable shift in welding preferences.
- Increased Focus on Sustainable Practices: The 'Green Manufacturing' initiative promotes environmentally friendly welding technologies. This trend is anticipated to lead to a 20% increase in the adoption of sustainable welding practices by 2025, aligning with global sustainability goals.
- Expansion of Training Programs for Welders: The Ministry of Education's 'Vocational Training Program for Welding' aims to improve skills for over 100,000 workers by 2025. This initiative is crucial for addressing the skills gap in the welding industry, ensuring a qualified workforce.
Investment Opportunities in the China Industrial Welding Market
Several openings in the China Industrial Welding Market merit attention from investors.
- Partnerships with Local Training Institutions: Collaborating with vocational training institutions can help address the skills gap in welding. With a projected need for over 100,000 trained welders by 2025, local partnerships can strengthen workforce capabilities.
- Investment in Advanced Welding Technologies: The market gap for advanced welding solutions presents opportunities for suppliers. With the automotive sector requiring 5 million tons of welding materials annually by 2025, suppliers can meet this demand through new technologies.
- Expansion into Emerging Markets: The shipbuilding industry is expanding, creating demand for high-quality welding techniques. Suppliers can enter this market by establishing partnerships in coastal regions, capitalising on the industry's growth.
- Development of Sustainable Welding Solutions: The 'Green Manufacturing' initiative encourages environmentally friendly practices. Suppliers can invest in sustainable welding technologies to meet the rising demand for eco-friendly solutions.
Government Initiatives in the China Industrial Welding Market
The 'National Plan for Advanced Manufacturing', launched in 2021 by the Ministry of Industry and Information Technology, improves welding technology capabilities across industries. This measure builds on the 'Made in China 2025' initiative, which emphasises advanced welding technologies. The updated policies aim to enhance the overall quality and efficiency of welding processes, ensuring compliance with international standards and encouraging innovation in the sector. The 'National Standard for Welding Equipment Safety', updated in 2022, ensures manufacturers comply with stringent safety protocols, improving the working environment for welders. The Ministry of Education's 'Vocational Training Program for Welding', initiated in 2020, targets skill enhancement for over 100,000 workers by 2025, ensuring a skilled workforce to meet industry demands.
In 2022, the State Administration for Market Regulation updated the 'National Standard for Welding Equipment Safety', enhancing safety measures for welding operators. This update ensures that manufacturers comply with stringent safety protocols, improving the working environment for welders. The Ministry of Education's 'Vocational Training Program for Welding', initiated in 2020, targets skill enhancement for over 100,000 workers by 2025, ensuring a skilled workforce to meet industry demands. The 'Green Manufacturing' initiative promotes environmentally friendly practices, allowing producers to adopt sustainable technologies.
Future Insight of the China Industrial Welding Market
The China Industrial Welding Market is projected to evolve significantly by 2032, driven by key factors. Government investments in infrastructure projects, amounting to 50 billion CNY in 2023, will create sustained demand for welding services across various sectors. The 'Made in China 2025' strategy will encourage the adoption of modern welding technologies, improving production efficiency for suppliers. The aerospace sector's anticipated 20% increase in welding applications by 2026 will present new opportunities for both buyers and producers, while the implementation of ISO 3834 standards will ensure higher quality across the market.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Industrial Welding – Arc Welding Dominated, Laser Welding Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, the largest industrial welding category in 2025 was Arc Welding, with a 42% share of total revenue. Arc welding holds the largest share in the China industrial welding market due to its extensive application in construction and manufacturing, where versatility is essential. A notable example is the construction of the Beijing Daxing International Airport, showcasing the widespread use of arc welding techniques. Over 2026–2032, Laser Welding is expected to post the fastest growth, at a CAGR of 6.9%. Laser welding is experiencing rapid growth, driven by its adoption for high-precision applications, particularly in the automotive sector. As industries increasingly seek advanced welding solutions, this trend is set to accelerate further, allowing arc welding to maintain its lead. Suppliers should enhance their offerings in laser welding technologies to align with the rising demand for precision applications.
By Welding Type – Gas Metal Arc Dominated, Gas Tungsten Arc Expected to Grow Fastest
With a 36% revenue share in 2025, Gas Metal Arc was the largest welding type category. Gas metal arc welding dominates the market as it is favoured for its speed and efficiency in manufacturing processes, making it a go-to choice for many production lines. Its ability to deliver high-quality welds quickly is a key factor in its popularity among manufacturers. Gas Tungsten Arc is set to record the highest CAGR in this split, 6.9% over 2026–2032. Gas tungsten arc welding is seeing the fastest growth due to its application in high-quality welds for specialized projects, particularly in sectors like aerospace. As industries increasingly prioritise quality, this segment's growth will likely accelerate. Buyers should consider investing in gas tungsten arc welding solutions to ensure high-quality outcomes in specialised applications.
By Equipment Type – Semi-Automatic Welder Dominated, CNC Laser Welder Expected to Grow Fastest
In 2025, Semi-Automatic Welder led the equipment type split with a 35% share. Semi-automatic welders lead the market as they are extensively used in medium to large-scale manufacturing, providing a balance of efficiency and control. Their adaptability across various manufacturing processes contributes to their dominant market share. The quickest growth will come from CNC Laser Welder, forecast to expand at a CAGR of 6.5% between 2026 and 2032. CNC laser welders are rapidly gaining traction as automation becomes more prevalent in manufacturing, allowing for increased precision and reduced labour costs. This trend is likely to expand as more manufacturers adopt automated solutions. Suppliers must innovate and offer advanced CNC laser welding equipment to cater to the growing demand for automated manufacturing processes.
By Application Area – Automotive Assemblies Dominated, Aerospace Components Expected to Grow Fastest
Automotive Assemblies took a 46% share of application area in 2025, more than any other category. Automotive assemblies dominate the application area for welding, as they are crucial for assembling various automotive components that require strong, durable connections. The substantial demand from this sector reinforces its leading position in the market. Aerospace Components are projected to grow fastest, at a CAGR of 6.8% during 2026–2032. Aerospace components are the fastest-growing application area, propelled by the need for high-precision welding in this specialised field. As the aerospace sector expands, the demand for advanced welding techniques is expected to increase significantly. Manufacturers should focus on developing welding solutions tailored for the aerospace industry to capitalise on this growing market.
By End User Industry – Construction Sector Dominated, Shipbuilding Industry Expected to Grow Fastest
Construction Sector held a 41% share of the China Industrial Welding Market by end user industry in 2025. The construction sector is the largest end user of welding technologies, employing them for structural integrity across various projects. With the Chinese government's substantial investment in infrastructure, the demand for welding in this sector remains strong. Over 2026–2032, Shipbuilding Industry is expected to post the fastest growth, at a CAGR of 6.2%. The shipbuilding industry is experiencing the fastest growth as it increasingly adopts advanced welding technologies for hull construction. This trend is likely to continue as global demand for ships rises. Suppliers should strategically target the shipbuilding industry to leverage its rapid growth and increasing need for advanced welding solutions.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Welding Market Outlook
- Market Size of China Industrial Welding Market, 2025
- Forecast of China Industrial Welding Market, 2032
- Historical Data and Forecast of China Industrial Welding Revenues & Volume for the Period 2022 - 2032F
- China Industrial Welding Market Trend Evolution
- China Industrial Welding Market Drivers and Challenges
- China Industrial Welding Price Trends
- China Industrial Welding Porter's Five Forces
- China Industrial Welding Industry Life Cycle
- Historical Data and Forecast of China Industrial Welding Market Revenues & Volume By Industrial Welding for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Welding Market Revenues & Volume By Arc Welding for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Welding Market Revenues & Volume By MIG Welding for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Welding Market Revenues & Volume By TIG Welding for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Welding Market Revenues & Volume By Laser Welding for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Welding Market Revenues & Volume By Welding Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Welding Market Revenues & Volume By Shielded Arc for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Welding Market Revenues & Volume By Gas Metal Arc for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Welding Market Revenues & Volume By Gas Tungsten Arc for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Welding Market Revenues & Volume By Fusion Welding for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Welding Market Revenues & Volume By Equipment Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Welding Market Revenues & Volume By Manual Welding Machine for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Welding Market Revenues & Volume By Semi-Automatic Welder for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Welding Market Revenues & Volume By Precision Welding Unit for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Welding Market Revenues & Volume By CNC Laser Welder for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Welding Market Revenues & Volume By Application Area for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Welding Market Revenues & Volume By Steel Structures for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Welding Market Revenues & Volume By Automotive Assemblies for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Welding Market Revenues & Volume By Aerospace Components for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Welding Market Revenues & Volume By Micro-Welding Jobs for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Welding Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Welding Market Revenues & Volume By Shipbuilding Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Welding Market Revenues & Volume By Construction Sector for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Welding Market Revenues & Volume By Machinery Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Welding Market Revenues & Volume By Fabrication Workshops for the Period 2022 - 2032F
- China Industrial Welding Import Export Trade Statistics
- Market Opportunity Assessment By Industrial Welding
- Market Opportunity Assessment By Welding Type
- Market Opportunity Assessment By Equipment Type
- Market Opportunity Assessment By Application Area
- Market Opportunity Assessment By End User Industry
- China Industrial Welding Top Companies Market Share
- China Industrial Welding Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Welding Company Profiles
- China Industrial Welding Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Industrial Welding
- Arc Welding
- MIG Welding
- TIG Welding
- Laser Welding
By Welding Type
- Shielded Arc
- Gas Metal Arc
- Gas Tungsten Arc
- Fusion Welding
By Equipment Type
- Manual Welding Machine
- Semi-Automatic Welder
- Precision Welding Unit
- CNC Laser Welder
By Application Area
- Steel Structures
- Automotive Assemblies
- Aerospace Components
- Micro-Welding Jobs
By End User Industry
- Shipbuilding Industry
- Construction Sector
- Machinery Manufacturers
- Fabrication Workshops































