China Inflight Entertainment Market Size & Growth Rate
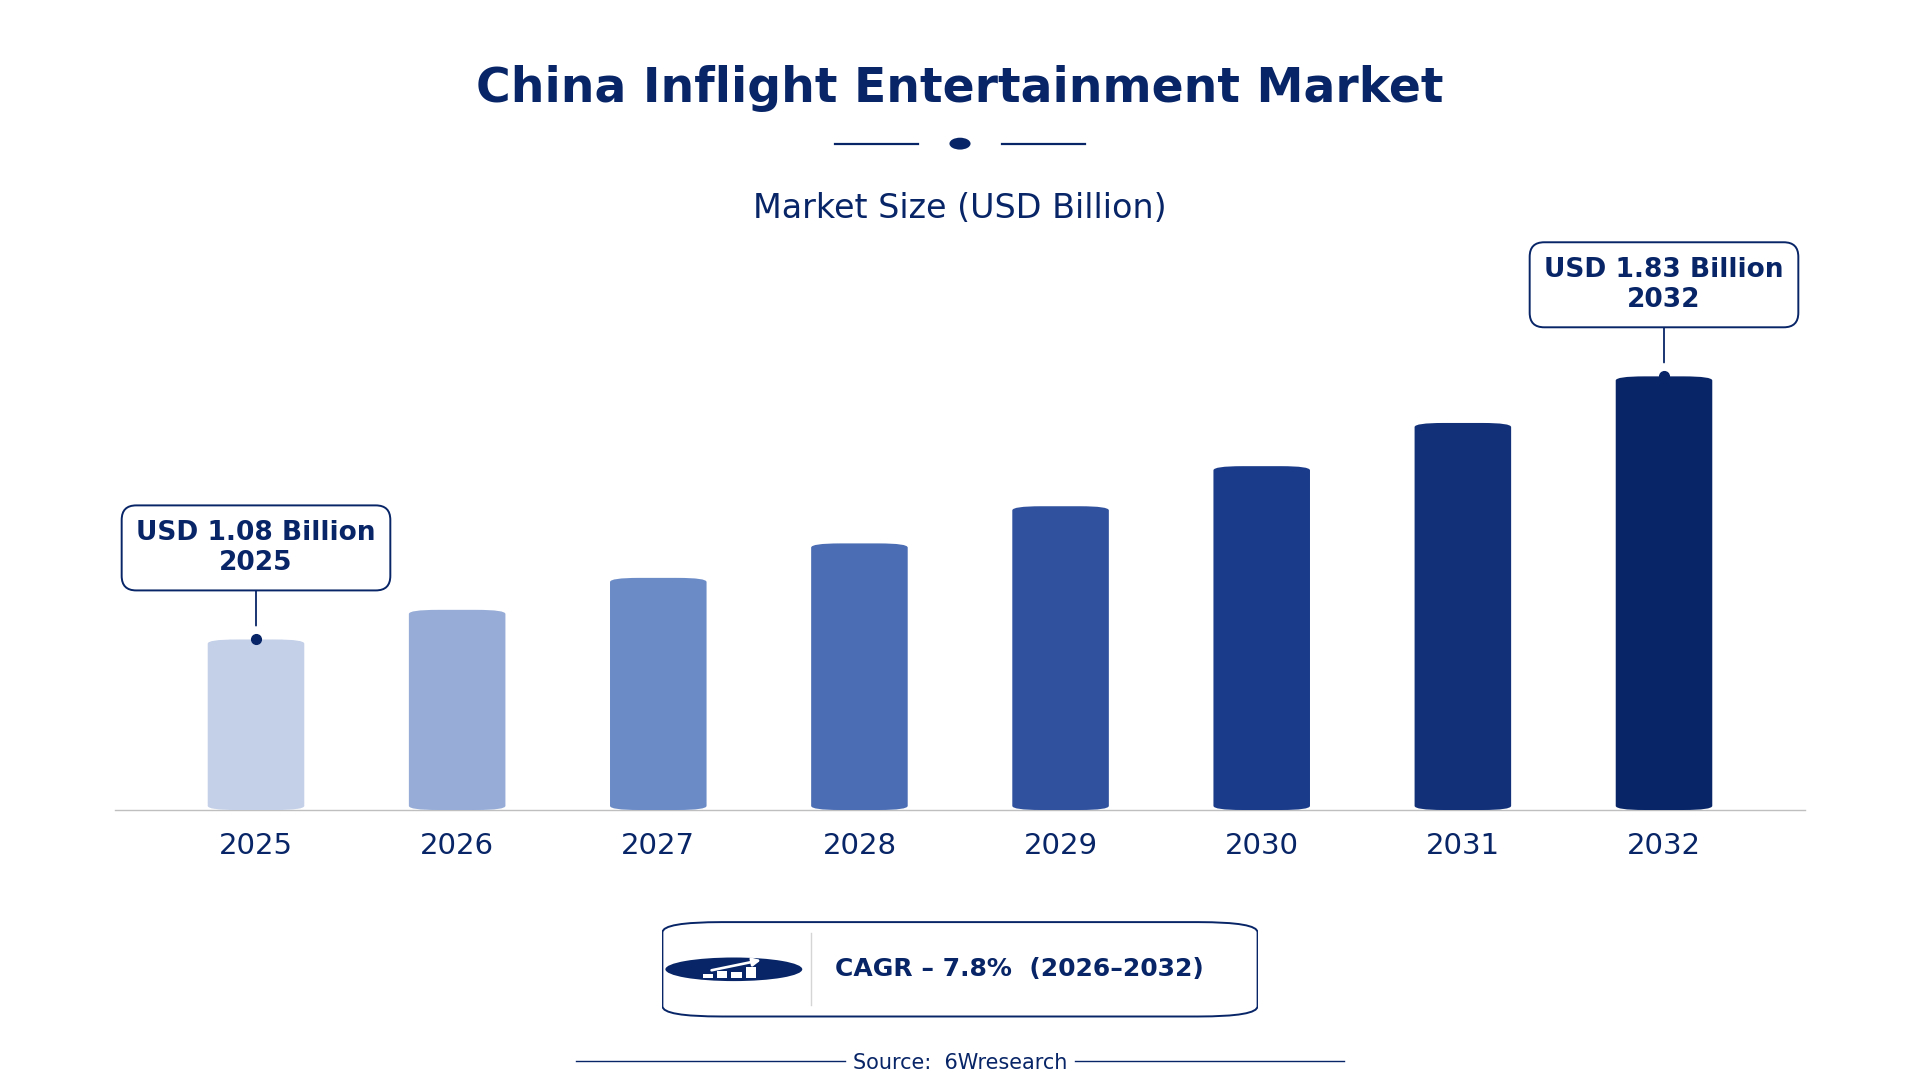
According to 6Wresearch internal database and industry insights, the China Inflight Entertainment Market was valued at USD 1.08 billion in 2025 and is projected to reach USD 1.83 billion by 2032, growing at a CAGR of approximately 7.8% during 2026–2032.
China Inflight Entertainment Market Highlights
| Report Metric | Details |
| Report Name | China Inflight Entertainment Market |
| Market Size 2025 | USD 1.08 billion |
| Market Size 2032 | USD 1.83 billion |
| Absolute Growth 2025–2032 | USD 0.75 billion |
| CAGR 2026–2032 | 7.8% |
| Peak Annual Growth | 10.3% in 2027 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Content Type, 2025 | Video on Demand (39% share) |
| Leading Delivery Mode, 2025 | Personal Screens (43% share) |
| Leading Passenger Class, 2025 | Economy / Business (49% share) |
| Leading Distribution Channel, 2025 | Entertainment Providers (49% share) |
| Fastest-Growing Content Type | Streaming Platforms (9.0% CAGR) |
| Fastest-Growing Delivery Mode | App-Based Access (9.1% CAGR) |
| Fastest-Growing Passenger Class | Premium Cabins (10.4% CAGR) |
| Fastest-Growing Distribution Channel | Digital Solution Vendors (9.7% CAGR) |
| Growing Sector | Digital Solution Vendors |
| Key End Users | Entertainment Providers, Content Aggregators, Digital Solution Vendors, Airline OEMs |
China Inflight Entertainment Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
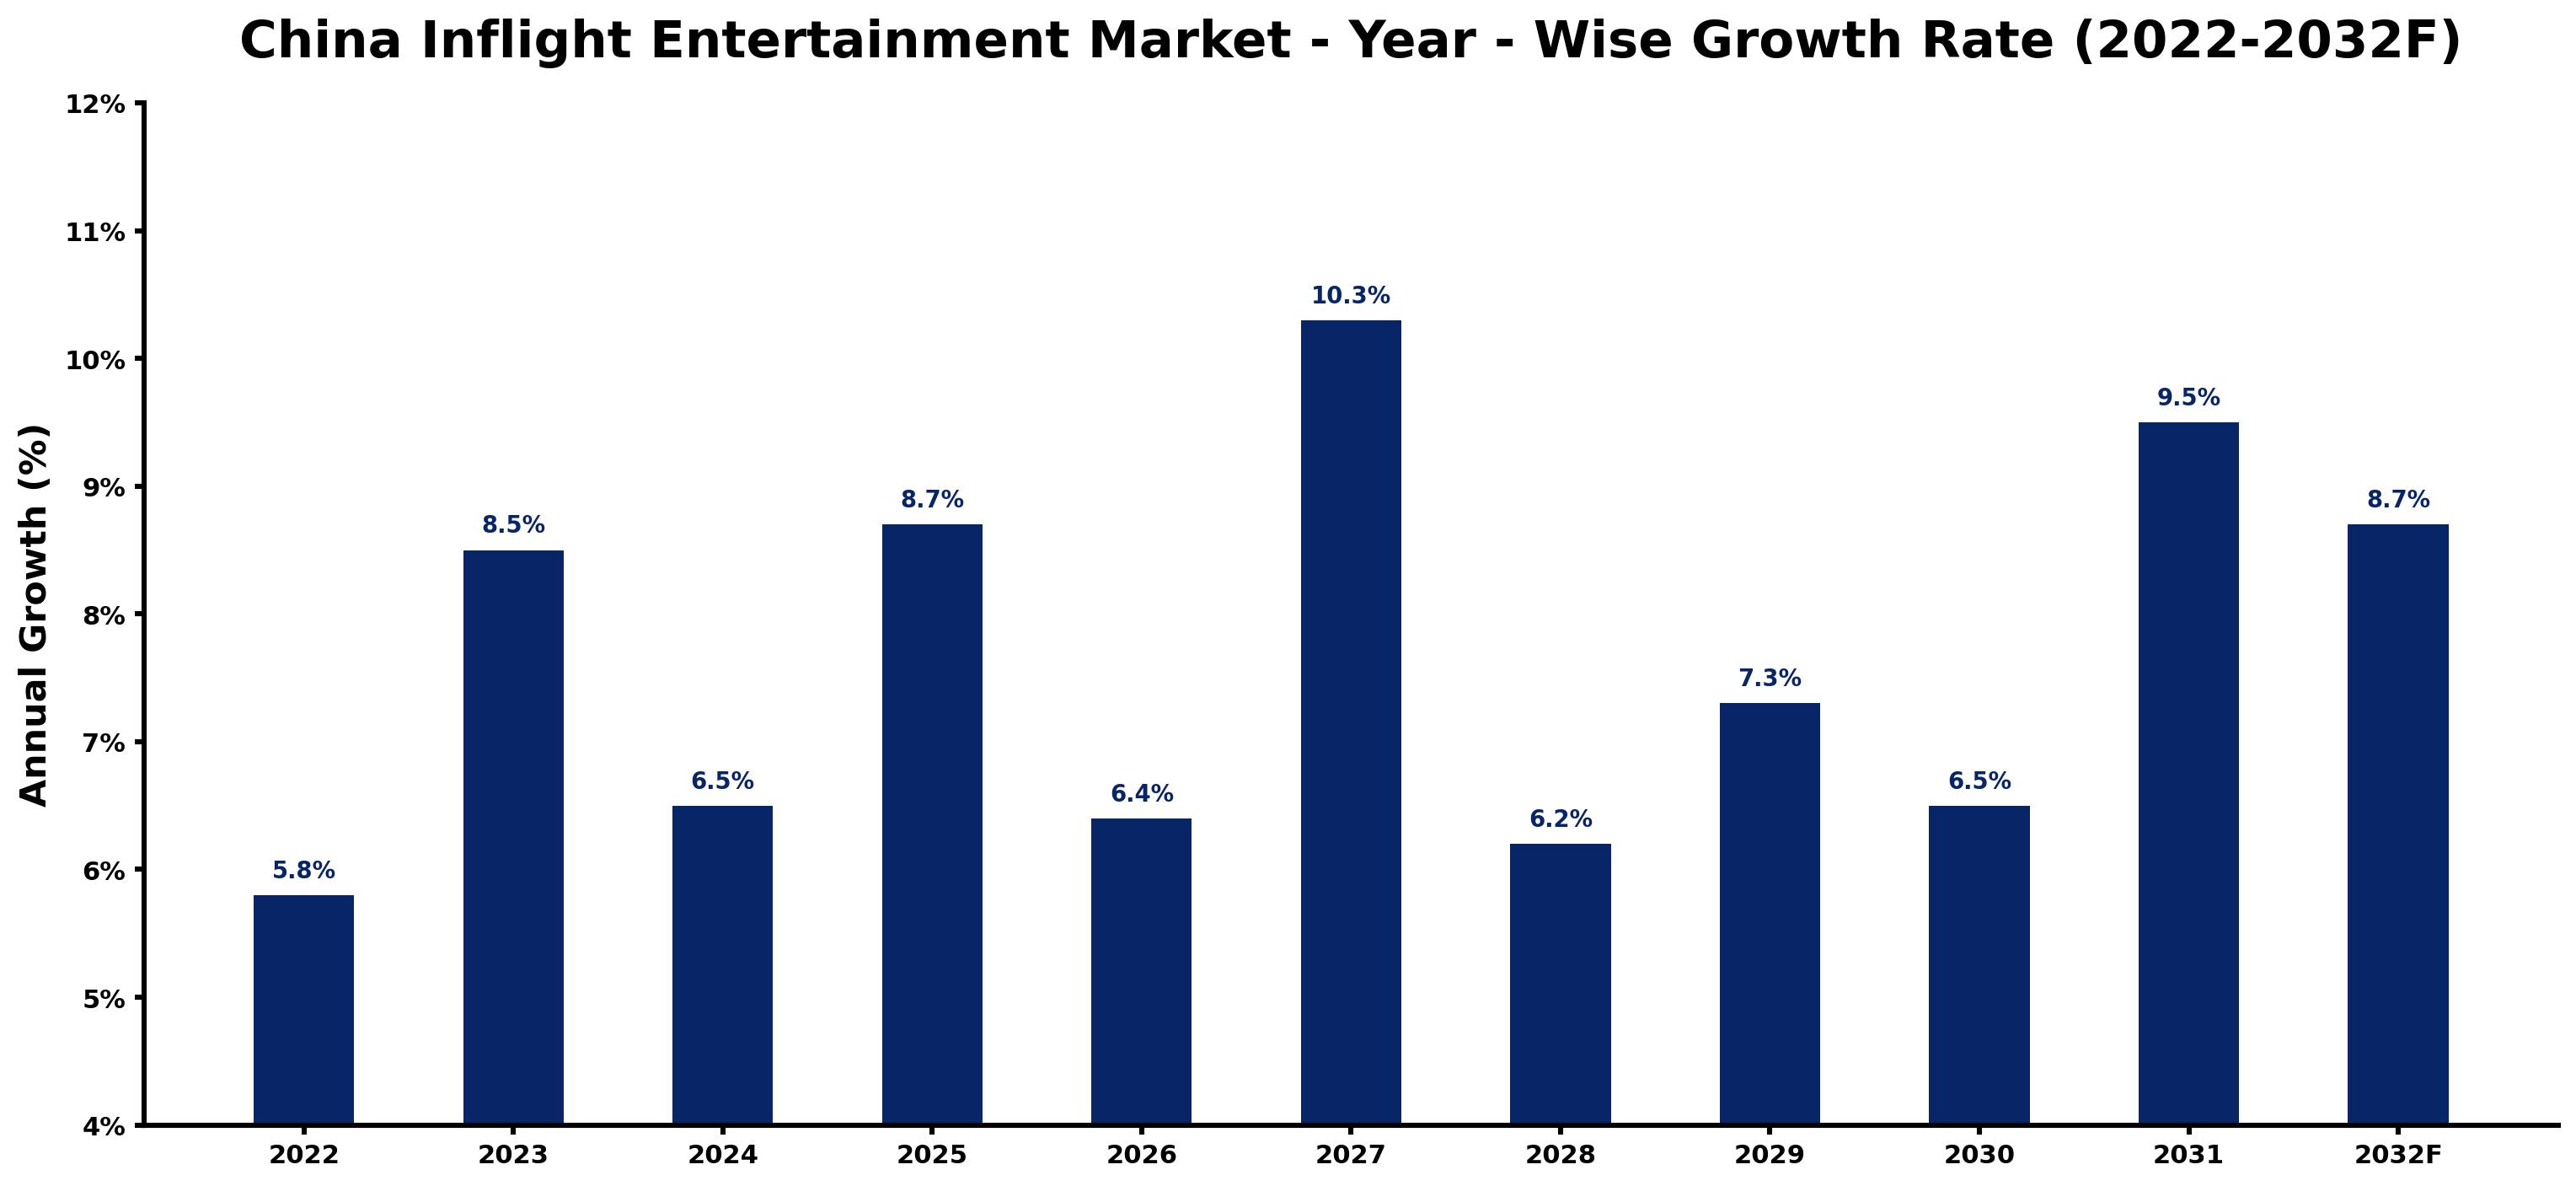
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.8 | The aviation industry transported over 610 million passengers, indicating strong demand for inflight services. |
| 2023 | 8.5 | The demand for streaming services in inflight entertainment increased by 30% since 2020, boosting market growth. |
| 2024 | 6.5 | The market is expected to slow as airlines adjust service offerings and technology upgrades. |
| 2025 | 8.7 | The Civil Aviation Administration of China initiated a program to improve passenger experience, driving inflight entertainment demand. |
| 2026 | 6.4 | The market growth is projected to slow as airlines focus on integrating advanced systems and meeting new standards. |
| 2027 | 10.3 | The adoption of interactive inflight entertainment systems is expected to surge, leading to substantial growth. |
| 2028 | 6.2 | The market growth is anticipated to slow as airlines continue to adapt to evolving passenger preferences and technological changes. |
| 2029 | 7.3 | The demand for premium inflight entertainment options is expected to rise, particularly among younger travelers. |
| 2030 | 6.5 | The market growth is projected to slow as airlines face challenges in implementing new technologies and services. |
| 2031 | 9.5 | The market is expected to grow faster as the focus on passenger comfort and entertainment intensifies. |
| 2032 | 8.7 | The market growth is projected to slow as airlines consolidate their offerings and refine entertainment systems. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Inflight Entertainment Market Synopsis
Inflight Entertainment in China encompasses audio-visual content and interactive services provided to passengers during flights. It includes personal screens and seat-back systems, offering video on demand, streaming platforms, and gaming. The China Inflight Entertainment Market is growing due to the strong aviation industry, which transported over 610 million passengers in 2022. Demand is driven by both domestic airlines and international carriers, with over 80% of airlines offering inflight entertainment. The 'Digital Aviation Development Plan' aims to improve passenger experience through technology upgrades, further supporting market expansion.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing passenger numbers driving demand for inflight entertainment services | Driver | High | All Aircraft |
| Growing preference for streaming services among travelers | Driver | High | Video on Demand |
| Investment in advanced inflight entertainment systems by airlines | Opportunity | High | Personal Screens |
| Expansion of premium inflight services to attract high-value travelers | Opportunity | High | Premium Cabins |
| High investment costs for upgrading inflight entertainment systems | Restraint | Medium | Seat-Back Systems |
| Regulatory compliance requirements for inflight entertainment systems | Restraint | Medium | Entertainment Providers |
| Inflight Entertainment market in China faces challenges from rapid technological changes | Challenge | High | All Aircraft |
| Competition among airlines to offer superior entertainment experiences | Challenge | Medium | Economy / Business |
Evaluation of Drivers in China Inflight Entertainment Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising passenger numbers | All Aircraft | The aviation industry transported over 610 million passengers in 2022, increasing demand for inflight entertainment. |
| Growing preference for streaming services | Video on Demand | The demand for streaming services in inflight entertainment has surged, prompting airlines to improve offerings. |
| Investment in advanced inflight entertainment systems | Personal Screens | The average investment in inflight entertainment systems per aircraft is around $200,000, leading to upgraded services. |
| Expansion of premium inflight services | Premium Cabins | The Guangdong province is a major hub for airlines focusing on premium inflight services, attracting high-value travelers. |
| Technological advancements in inflight entertainment | Streaming Platforms | The 'Smart Aviation' initiative aims to modernise inflight services, encouraging airlines to adopt new technologies. |
The Inflight Entertainment market in China is growing on the back of rising passenger numbers, increasing preference for streaming services, and substantial investments in advanced systems. In 2022, the aviation industry transported over 610 million passengers, which directly boosts demand for inflight entertainment. The average investment in inflight entertainment systems per aircraft is around $200,000, allowing airlines to upgrade their offerings. The demand for streaming services in inflight entertainment has surged by 30% since 2020, prompting airlines to expand their systems. The focus on premium inflight services is increasing, particularly in the Guangdong province, attracting high-value travelers and driving market growth.
Evaluation of Restraints in China Inflight Entertainment Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High investment costs for upgrading inflight entertainment systems | Seat-Back Systems | The average investment in inflight entertainment systems per aircraft is around $200,000, which can limit upgrades. |
| Regulatory compliance requirements for inflight entertainment systems | Entertainment Providers | The Civil Aviation Administration of China oversees regulations, requiring compliance that can delay system updates. |
| Rapid technological changes in inflight entertainment | All Aircraft | The fast pace of technology can outstrip airlines' ability to adapt, affecting service offerings. |
| Intense competition among airlines | Economy / Business | Airlines must continuously innovate to retain passengers, increasing operational pressures. |
| Limited availability of skilled personnel for system integration | Personal Screens | The demand for skilled technicians exceeds supply, delaying system upgrades. |
China Inflight Entertainment Market Challenges
Over 610 million passengers travelled through China's aviation industry in 2022, yet regulatory hurdles from the Civil Aviation Administration of China (CAAC) slow the deployment of advanced inflight entertainment systems, affecting airlines' ability to improve passenger satisfaction. Price competition among airlines drives down service quality, which can lead to dissatisfaction among travellers seeking engaging inflight experiences. The need for rapid technological upgrades demands substantial investments, with the average inflight entertainment system costing around $200,000 per aircraft, putting financial pressure on smaller operators. A lack of skilled professionals in aviation technology hampers the integration of new digital solutions, delaying enhancements in services that could elevate the passenger experience.
Trends in the China Inflight Entertainment Market
Several trends are reshaping the China Inflight Entertainment Market; the most important are set out below.
- Shift from Traditional to Interactive Systems: Airlines in China are increasingly adopting interactive inflight entertainment systems, improving passenger engagement. In 2023, the CAAC initiated a program to promote these systems, aiming for 50% adoption by 2025.
- Surge in Streaming Services Usage: The demand for streaming services in inflight entertainment has surged, with a 30% increase since 2020. This trend is reflected as more airlines integrate streaming options into their offerings.
- Growth of Premium Cabins: Premium cabins are seeing a rise in demand for enhanced inflight entertainment options. The fastest-growing segment, Premium Cabins, is projected to grow at a CAGR of 10.4% from 2026 to 2032.
- Adoption of Digital Solutions: The integration of digital solutions in inflight services is becoming standard practice. The CAAC issued a guideline in 2023 to facilitate this integration, aiming to improve passenger experiences.
Investment Opportunities in the China Inflight Entertainment Market
Below are the investment opportunities with the strongest case in the China Inflight Entertainment Market.
- Investment in Advanced Inflight Entertainment Systems: Airlines are looking to upgrade inflight entertainment systems, with an average investment of around $200,000 per aircraft. Partnering with technology providers can facilitate these upgrades.
- Development of Streaming Platforms: The growing demand for streaming services presents opportunities for content providers. Collaboration with airlines can improve service offerings and capture the increasing passenger interest.
- Expansion of Premium Inflight Services: The increasing focus on premium services creates opportunities for airlines to invest in improved entertainment options. The Guangdong province is a key region for this investment.
- Integration of Interactive Systems: The CAAC's initiative for interactive inflight entertainment systems aims for 50% adoption by 2025. This presents opportunities for suppliers of interactive technology solutions.
Government Initiatives in the China Inflight Entertainment Market
The 'Digital Aviation Development Plan' launched by the Civil Aviation Administration of China (CAAC) in 2021 focuses on improving inflight services through technology integration. This plan aims to increase passenger satisfaction ratings by 20% by 2024. Additionally, the updated 'Aviation Safety and Technology Innovation Plan' in 2022 includes guidelines for inflight entertainment systems, ensuring compliance with safety standards. These measures compel airlines to invest in modern systems to meet regulatory requirements.
The CAAC oversees the implementation of various programs aimed at improving inflight entertainment. The 'Passenger Experience Enhancement Program' funds initiatives that improve inflight entertainment options, targeting a 20% increase in satisfaction ratings by 2024. Furthermore, the CAAC promotes the use of interactive inflight entertainment systems across all domestic airlines, aiming for 50% adoption by 2025. These initiatives support the development of advanced inflight entertainment technologies.
Future Insight of the China Inflight Entertainment Market
Several forward-looking factors should support the inflight entertainment market in China over the coming years. The CAAC's 2023 initiative to improve passenger experience through technology upgrades will drive innovation across the sector. With the demand for gaming options rising among younger travellers, airlines will likely invest more in diverse entertainment offerings. The 'Smart Aviation' initiative aims to modernise inflight services, allowing airlines to better cater to tech-savvy passengers and improve overall satisfaction.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Content Type – Video on Demand Dominated, Streaming Platforms Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, Video on Demand took a 39% share of content type in 2025, more than any other category. Video on Demand holds the largest share in the China inflight entertainment market as it is the primary choice for passenger entertainment during flights. With over 80% of airlines providing this service, it has become a standard expectation among travellers, ensuring widespread adoption. Streaming Platforms are set to record the highest CAGR in this split, 9.0% over 2026–2032. The growth of Streaming Platforms is propelled by a 30% increase in demand for streaming services since 2020, reflecting passengers' desire for real-time content access. This trend suggests that as technology evolves, Video on Demand will maintain its lead due to its established presence. Suppliers should enhance Video on Demand offerings to meet the growing expectations of passengers.
By Delivery Mode – Personal Screens Dominated, App-Based Access Expected to Grow Fastest
Personal Screens held a 43% share of the China Inflight Entertainment Market by delivery mode in 2025. Personal Screens dominate the market as they are the primary method for delivering content to passengers during flights. Airlines prioritise this delivery mode to provide a consistent and engaging entertainment experience for their customers, reinforcing its dominance. App-Based Access is projected to grow fastest, at a CAGR of 9.1% during 2026–2032. App-Based Access is rapidly growing as it allows passengers to access content on their devices, supplementing traditional systems. As airlines upgrade their technology, Personal Screens will continue to lead by offering a more reliable experience. Providers must consider integrating app-based solutions to enhance the passenger experience while ensuring the reliability of personal screens.
By Passenger Class – Economy / Business Dominated, Premium Cabins Expected to Grow Fastest
The largest passenger class category in 2025 was Economy / Business, with a 49% share of total revenue. Economy / Business class captures the largest share in inflight entertainment as both classes extensively utilise these services. The significant passenger volume in these classes guarantees a steady demand for entertainment options during flights, solidifying their market position. The quickest growth will come from Premium Cabins, forecast to expand at a CAGR of 10.4% between 2026 and 2032. Premium Cabins are experiencing the fastest growth due to enhanced entertainment options available, appealing to affluent travellers seeking superior experiences. This trend indicates that as airlines improve their offerings, Economy / Business will maintain its dominance. Airlines should invest in premium entertainment options to attract and retain high-value passengers in Premium Cabins.
By Distribution Channel – Entertainment Providers Dominated, Digital Solution Vendors Expected to Grow Fastest
In 2025, Entertainment Providers led the distribution channel split with a 49% share. Entertainment Providers lead the market as they are key players supplying content for inflight systems, ensuring a diverse range of options for airlines. Their established relationships with airlines facilitate the integration of high-quality entertainment solutions. Over 2026–2032, Digital Solution Vendors are expected to post the fastest growth, at a CAGR of 9.7%. Digital Solution Vendors are experiencing rapid growth as they support the technology behind inflight entertainment systems, reflecting the industry's shift towards digitalisation. This growth indicates that Entertainment Providers will maintain their lead by continuously adapting to new content demands. Suppliers should collaborate with Digital Solution Vendors to stay ahead in the competitive inflight entertainment market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Inflight Entertainment Market Outlook
- Market Size of China Inflight Entertainment Market, 2025
- Forecast of China Inflight Entertainment Market, 2032
- Historical Data and Forecast of China Inflight Entertainment Revenues & Volume for the Period 2022 - 2032F
- China Inflight Entertainment Market Trend Evolution
- China Inflight Entertainment Market Drivers and Challenges
- China Inflight Entertainment Price Trends
- China Inflight Entertainment Porter's Five Forces
- China Inflight Entertainment Industry Life Cycle
- Historical Data and Forecast of China Inflight Entertainment Market Revenues & Volume By Content Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Inflight Entertainment Market Revenues & Volume By Video on Demand for the Period 2022 - 2032F
- Historical Data and Forecast of China Inflight Entertainment Market Revenues & Volume By Streaming Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China Inflight Entertainment Market Revenues & Volume By Audio / Podcasts for the Period 2022 - 2032F
- Historical Data and Forecast of China Inflight Entertainment Market Revenues & Volume By Gaming and Interactivity for the Period 2022 - 2032F
- Historical Data and Forecast of China Inflight Entertainment Market Revenues & Volume By Delivery Mode for the Period 2022 - 2032F
- Historical Data and Forecast of China Inflight Entertainment Market Revenues & Volume By Personal Screens for the Period 2022 - 2032F
- Historical Data and Forecast of China Inflight Entertainment Market Revenues & Volume By Wi-Fi Dependent for the Period 2022 - 2032F
- Historical Data and Forecast of China Inflight Entertainment Market Revenues & Volume By Seat-Back Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Inflight Entertainment Market Revenues & Volume By App-Based Access for the Period 2022 - 2032F
- Historical Data and Forecast of China Inflight Entertainment Market Revenues & Volume By Passenger Class for the Period 2022 - 2032F
- Historical Data and Forecast of China Inflight Entertainment Market Revenues & Volume By Economy / Business for the Period 2022 - 2032F
- Historical Data and Forecast of China Inflight Entertainment Market Revenues & Volume By All Aircraft for the Period 2022 - 2032F
- Historical Data and Forecast of China Inflight Entertainment Market Revenues & Volume By Long Haul Routes for the Period 2022 - 2032F
- Historical Data and Forecast of China Inflight Entertainment Market Revenues & Volume By Premium Cabins for the Period 2022 - 2032F
- Historical Data and Forecast of China Inflight Entertainment Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Inflight Entertainment Market Revenues & Volume By Content Aggregators for the Period 2022 - 2032F
- Historical Data and Forecast of China Inflight Entertainment Market Revenues & Volume By Entertainment Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China Inflight Entertainment Market Revenues & Volume By Airline OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Inflight Entertainment Market Revenues & Volume By Digital Solution Vendors for the Period 2022 - 2032F
- China Inflight Entertainment Import Export Trade Statistics
- Market Opportunity Assessment By Content Type
- Market Opportunity Assessment By Delivery Mode
- Market Opportunity Assessment By Passenger Class
- Market Opportunity Assessment By Distribution Channel
- China Inflight Entertainment Top Companies Market Share
- China Inflight Entertainment Competitive Benchmarking By Technical and Operational Parameters
- China Inflight Entertainment Company Profiles
- China Inflight Entertainment Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Content Type
- Video on Demand
- Streaming Platforms
- Audio / Podcasts
- Gaming and Interactivity
By Delivery Mode
- Personal Screens
- Wi-Fi Dependent
- Seat-Back Systems
- App-Based Access
By Passenger Class
- Economy / Business
- All Aircraft
- Long Haul Routes
- Premium Cabins
By Distribution Channel
- Content Aggregators
- Entertainment Providers
- Airline OEMs
- Digital Solution Vendors































