China Inpatient Care Market Size & Growth Rate
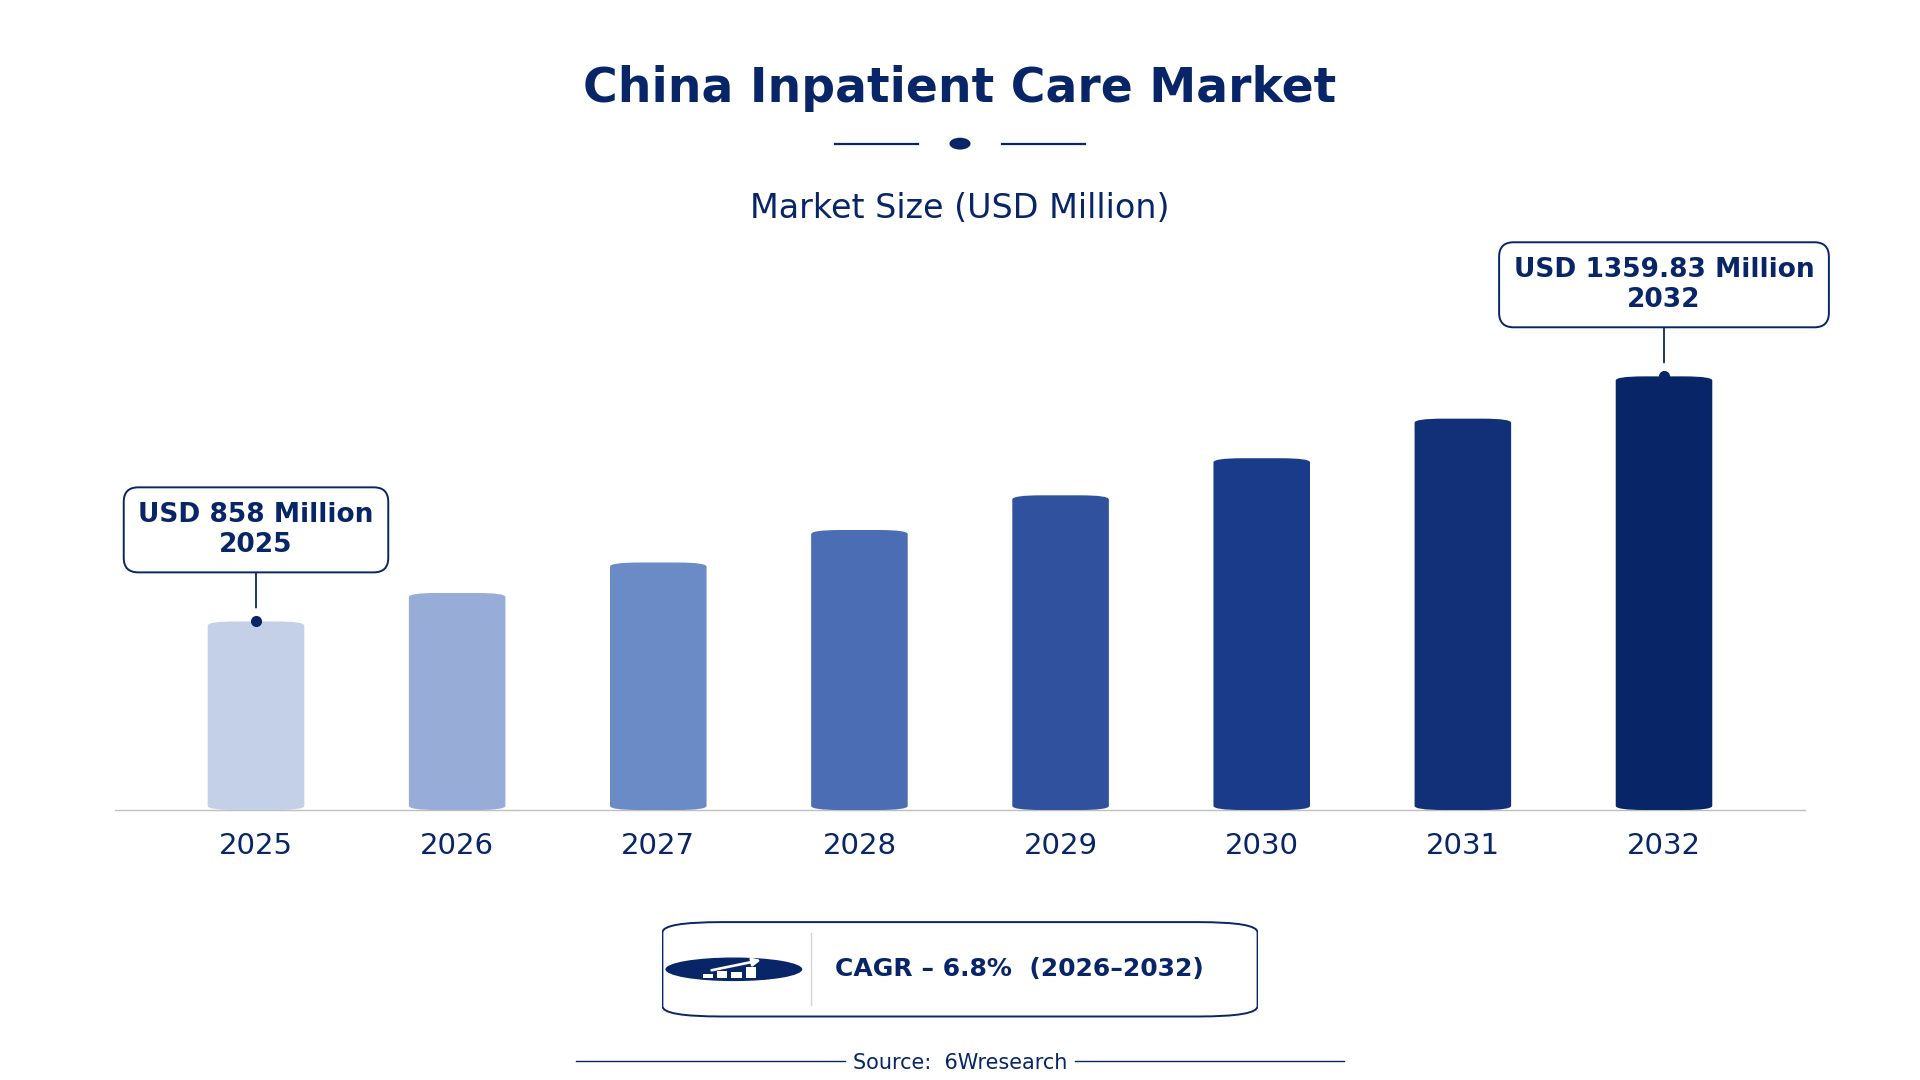
According to 6Wresearch internal database and industry insights, the China Inpatient Care Market was valued at USD 858.0 million in 2025 and is projected to reach USD 1,359.83 million by 2032, growing at a CAGR of approximately 6.8% during 2026–2032.
China Inpatient Care Market Highlights
| Report Metric | Details |
| Report Name | China Inpatient Care Market |
| Market Size 2025 | USD 858.0 million |
| Market Size 2032 | USD 1,359.83 million |
| Absolute Growth 2025–2032 | USD 501.83 million |
| CAGR 2026–2032 | 6.8% |
| Peak Annual Growth | 8.9% in 2030 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Care Type, 2025 | Acute Inpatient (50% share) |
| Leading Facility Type, 2025 | Multispecialty Hospital (36% share) |
| Leading Duration, 2025 | 3–7 Days (43% share) |
| Leading Treatment Area, 2025 | Surgery (35% share) |
| Leading Insurance Coverage, 2025 | Covered (39% share) |
| Fastest-Growing Care Type | Long-Term Care (9.4% CAGR) |
| Fastest-Growing Facility Type | Rehabilitation Centers (9.1% CAGR) |
| Fastest-Growing Duration | 1–4 Weeks (8.4% CAGR) |
| Fastest-Growing Treatment Area | Behavioral Disorders (8.7% CAGR) |
| Growing Sector | Elderly Care |
| Key End Users | Hospitals, Rehabilitation Centers, Mental Health Facilities, Birthing Centers |
China Inpatient Care Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
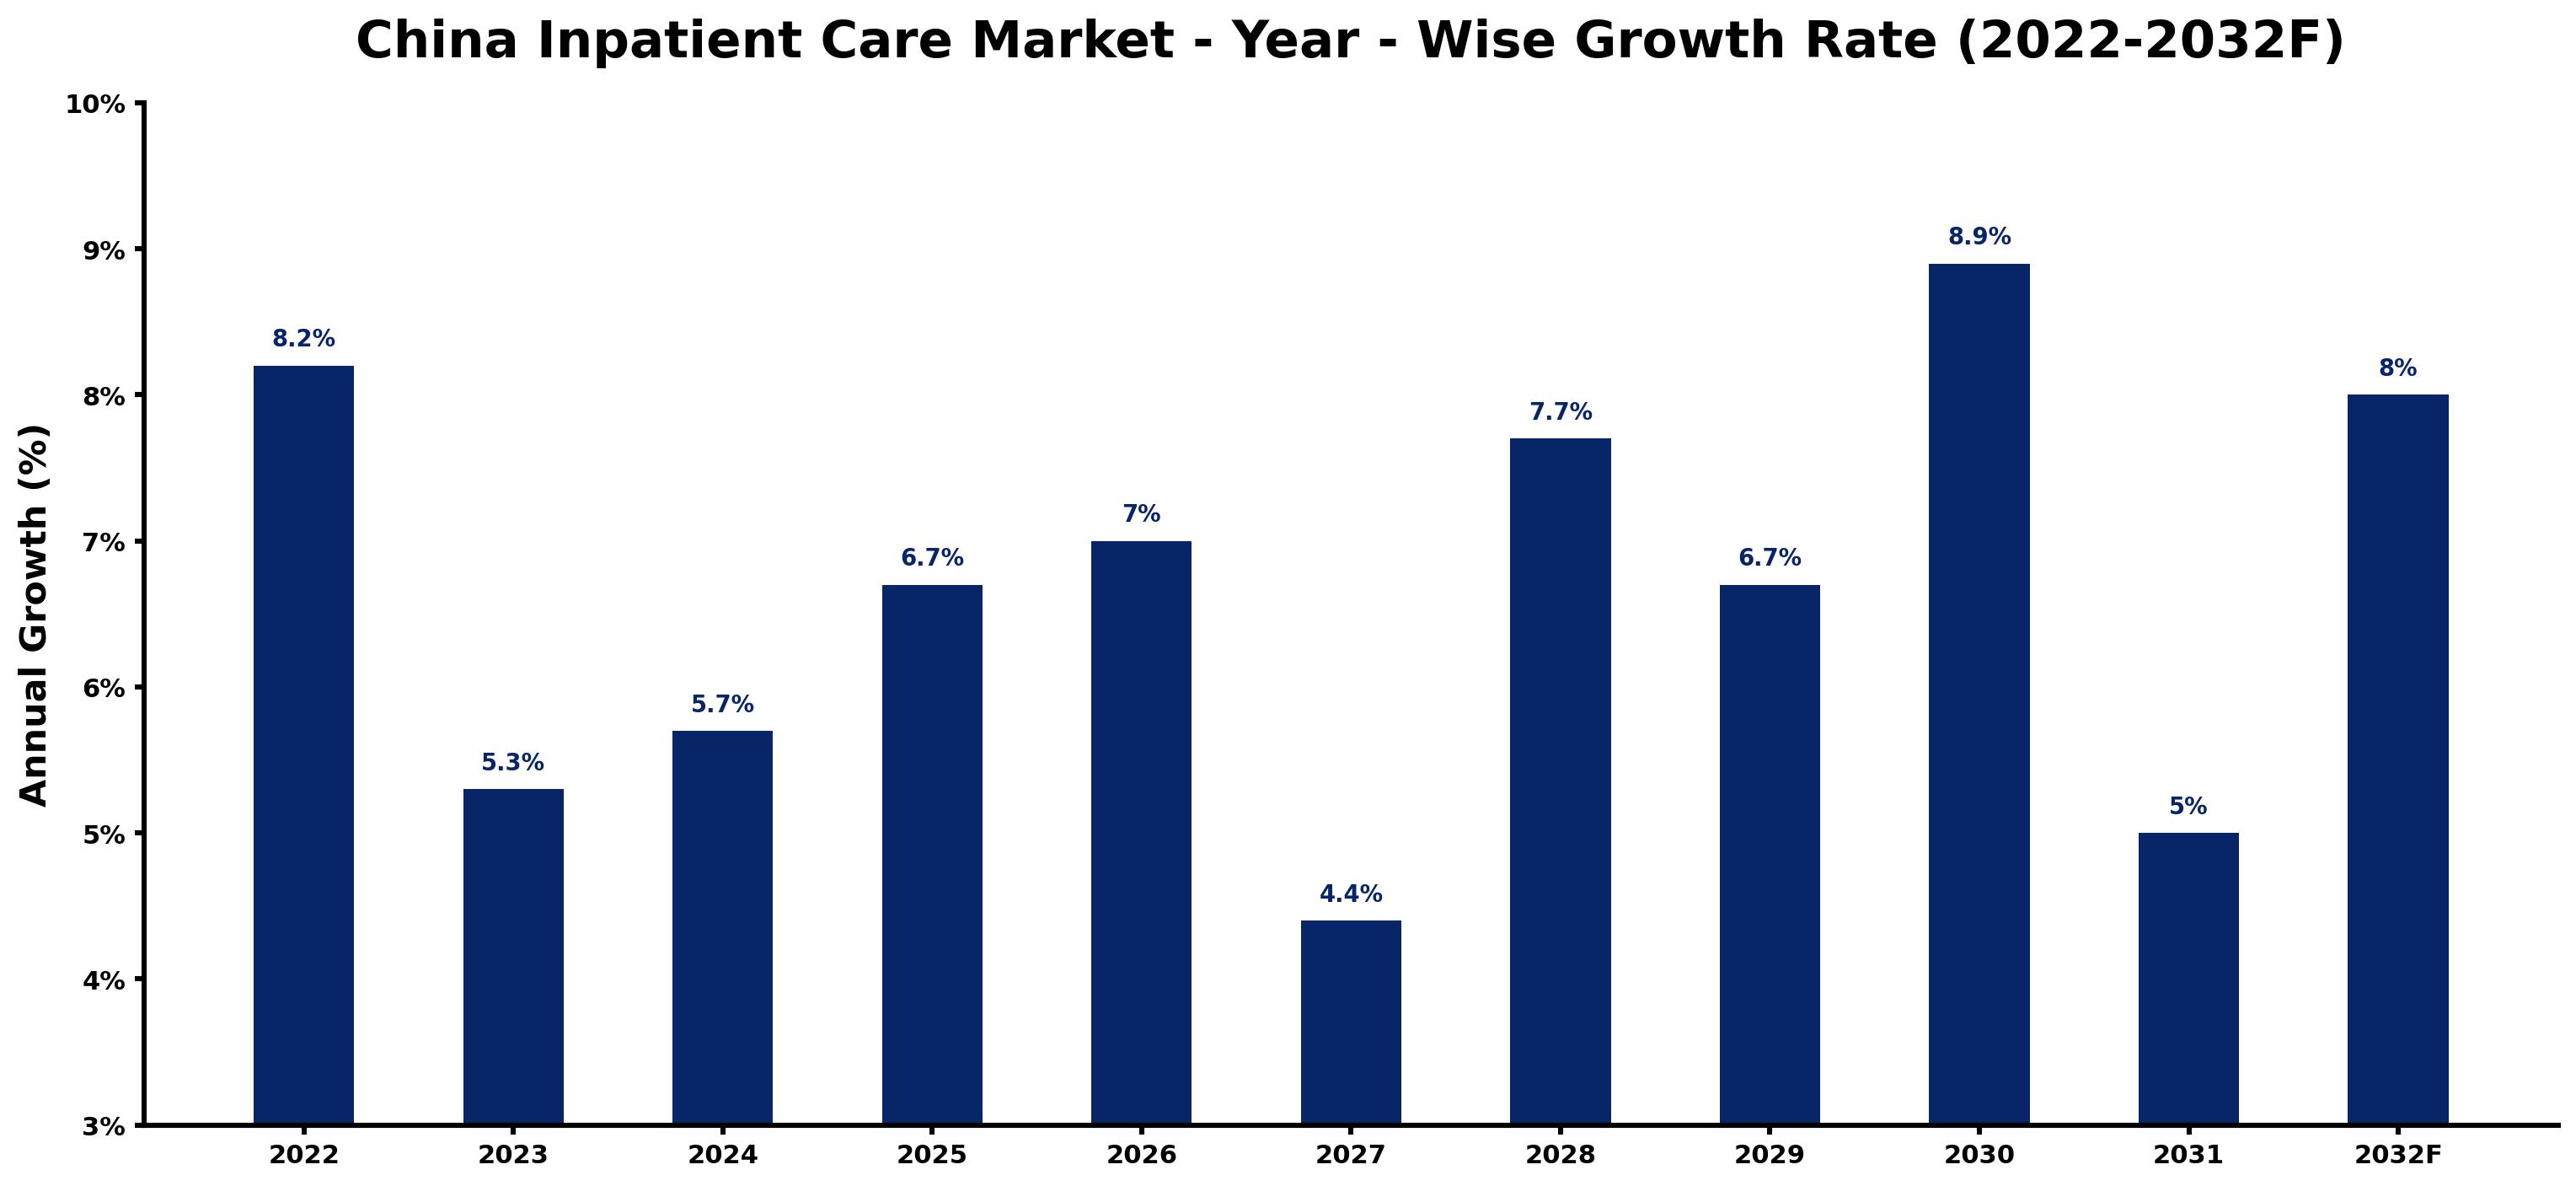
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 8.2 | Demand for inpatient care surged due to increased healthcare spending and a growing elderly population. |
| 2023 | 5.3 | The market experienced slower growth as hospitals adjusted to new regulations and patient management challenges. |
| 2024 | 5.7 | A rise in acute inpatient admissions contributed to faster growth as healthcare facilities expanded their services. |
| 2025 | 6.7 | Increased investments in hospital infrastructure supported growth as more patients sought inpatient care. |
| 2026 | 7.0 | Government initiatives to enhance healthcare access are expected to drive further demand for inpatient services. |
| 2027 | 4.4 | Growth slowed as hospitals faced challenges in integrating telemedicine solutions effectively. |
| 2028 | 7.7 | A renewed focus on mental health services is anticipated to boost inpatient admissions in facilities nationwide. |
| 2029 | 6.7 | The market experienced slower growth as competition intensified among existing hospitals in urban areas. |
| 2030 | 8.9 | Significant investments in healthcare infrastructure are projected to drive peak growth in inpatient care services. |
| 2031 | 5.0 | Growth is expected to slow as hospitals focus on optimising operations and managing costs effectively. |
| 2032 | 8.0 | Increased funding for healthcare services will enhance access and quality of inpatient care across the country. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Inpatient Care Market Synopsis
Inpatient care in China encompasses medical services for patients requiring hospital admission for treatment. This care is primarily provided through multispecialty hospitals and rehabilitation centres, addressing acute illnesses, surgical procedures, and chronic conditions. The China Inpatient Care Market is growing due to rising healthcare expenditure, which reached 6.6% of GDP in 2022, along with an increasing elderly population of over 250 million aged 60 and above. The 'Healthy China 2030' initiative aims to improve healthcare access and quality, further boosting demand for inpatient services.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing elderly population requiring inpatient services | Driver | High | Acute Inpatient |
| Increased healthcare funding for infrastructure development | Driver | High | Multispecialty Hospital |
| Rising demand for rehabilitation services in urban areas | Opportunity | Medium | Rehabilitation Centers |
| Expansion of mental health facilities to accommodate more patients | Opportunity | Medium | Psychiatric Inpatient |
| High operational costs limiting facility expansions | Restraint | High | Multispecialty Hospital |
| Staffing shortages affecting service delivery in hospitals | Restraint | Medium | Acute Inpatient |
| Increased competition among healthcare providers | Challenge | High | Rehabilitation Centers |
| Regulatory compliance costs impacting facility operations | Challenge | Medium | Psychiatric Inpatient |
Evaluation of Drivers in China Inpatient Care Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising healthcare expenditure | Acute Inpatient | Healthcare expenditure reached 6.6% of GDP in 2022, increasing hospital admissions. |
| Government initiatives for healthcare access | Multispecialty Hospital | The 'Healthy China 2030' initiative aims to improve healthcare quality and accessibility. |
| Growing elderly population | Long-Term Care | Over 250 million people aged 60 and above are driving demand for inpatient services. |
| Expansion of mental health services | Psychiatric Inpatient | The Ministry of Health's program increases psychiatric care, boosting bed availability. |
| Increased patient volume in emergency departments | Emergency | Rising patient volumes necessitate more inpatient admissions in hospitals. |
The Inpatient Care market in China is expanding as rising healthcare expenditure, driven by a growing elderly population and increased patient volumes, stimulates hospital admissions. In 2022, healthcare expenditure reached 6.6% of GDP, prompting hospitals to expand their services to accommodate more patients. The focus on mental health services has resulted in a 15% increase in psychiatric inpatient beds, further supporting market growth.
Evaluation of Restraints in China Inpatient Care Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High operational costs limiting facility expansions | Multispecialty Hospital | Urban hospitals face high operational costs, restricting their ability to expand services. |
| Staffing shortages affecting service delivery | Acute Inpatient | Healthcare facilities struggle to hire qualified staff, impacting patient care quality. |
| Regulatory compliance costs impacting operations | Psychiatric Inpatient | Compliance with updated standards increases operational costs for mental health facilities. |
| Intense competition among healthcare providers | Rehabilitation Centers | Increased competition leads to pricing pressures, affecting profitability for providers. |
| Limited funding for new healthcare projects | Long-Term Care | Budget constraints hinder the development of new long-term care facilities. |
China Inpatient Care Market Challenges
Buyers and suppliers in the China inpatient care market encounter considerable regulatory hurdles, as strict standards set by the National Health Commission can delay hospital accreditation, affecting patient access to timely services. Technology integration presents another challenge; many hospitals struggle to implement telemedicine solutions effectively, resulting in longer wait times for patients needing urgent care. Increased competition from new hospitals in urban areas raises operational costs for existing facilities, compelling them to invest heavily in upgrades. The average cost of inpatient care in urban hospitals can be up to 30% higher than in rural facilities, limiting access for lower-income patients seeking essential treatment.
Trends in the China Inpatient Care Market
Four trends stand out in the China Inpatient Care Market.
- Increase in Telemedicine Adoption: In 2023, the number of inpatient care facilities adopting telemedicine solutions increased by 20%, improving patient management and access to care.
- Shift Towards Rehabilitation Services: The government’s initiative to subsidise rehabilitation centres led to a 5 billion yuan investment in 2022, supporting the growth of rehabilitation services in urban areas.
- Growth in Mental Health Facilities: Since the update of the Mental Health Law in 2022, there has been a 15% increase in psychiatric inpatient beds, reflecting a growing focus on mental health care.
- Expansion of Birthing Centers: The number of birthing centres increased by 20% over the past five years, addressing the rising demand for maternity care services in urban regions.
Investment Opportunities in the China Inpatient Care Market
Below are the investment opportunities with the strongest case in the China Inpatient Care Market.
- Elderly Care Facilities: With over 250 million elderly individuals, there is a pressing need for more long-term care facilities. Investing in these centres can meet the growing demand for elderly care services.
- Rehabilitation Services: The government’s 5 billion yuan budget for new rehabilitation centres presents an opportunity for investment. Targeting urban areas can yield substantial returns as demand rises.
- Mental Health Services: The increase in psychiatric beds indicates a need for better mental health services. Investing in facilities that comply with the updated Mental Health Law can capture this growing market.
- Telemedicine Solutions: The rise in telemedicine adoption offers a gap for technology providers. Partnering with healthcare facilities to implement these solutions can improve service delivery.
Government Initiatives in the China Inpatient Care Market
The '14th Five-Year Plan for Health' launched in 2021 aims to improve inpatient care services nationwide. This plan focuses on enhancing hospital infrastructure and increasing access to care, benefiting both patients and providers. Additionally, the 'Mental Health Law' updated in 2022 improves psychiatric inpatient care standards and patient rights, ensuring better treatment for mental health patients. The 'National Health Emergency Response Plan' revised in 2023 ensures better preparedness for inpatient care during crises, improving resource allocation.
In 2022, the government initiated a programme to subsidise the construction of new rehabilitation centres, with a budget of 5 billion yuan. The National Health Commission oversees this funding, which aims to improve the availability of rehabilitation services across the country. Furthermore, the 'National Health Emergency Response Plan' revised in 2023 ensures better preparedness for inpatient care during crises, improving resource allocation.
Future Insight of the China Inpatient Care Market
The China inpatient care market will undergo substantial changes by 2032, driven by the 'Healthy China 2030' initiative aimed at improving healthcare access across the nation. Increased government funding will facilitate the construction of new hospitals in underserved regions, enhancing patient access and reducing wait times. Advancements in telemedicine will optimise patient management, allowing facilities to operate more efficiently. By 2025, healthcare funding is expected to grow by 10% annually, supporting the expansion of mental health services and increasing the number of available psychiatric inpatient beds.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Care Type – Acute Inpatient Dominated, Long-Term Care Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, Acute Inpatient took a 50% share of care type in 2025, more than any other category. Acute inpatient care commands the largest share in China as it is essential for treating urgent medical conditions, with around 40% of total hospital admissions attributed to this segment. The high demand for immediate medical intervention, especially in urban centres, solidifies its leading position in the market. Over 2026–2032, Long-Term Care is expected to post the fastest growth, at a CAGR of 9.4%. Long-term care is experiencing rapid growth driven by the increasing elderly population, which exceeds 250 million, requiring ongoing management of chronic illnesses. This demographic trend will likely lead to a widening gap between long-term care and acute care segments as demand escalates. Suppliers should prioritise the development of long-term care solutions to address the growing needs of an ageing population.
By Facility Type – Multispecialty Hospital Dominated, Rehabilitation Centers Expected to Grow Fastest
Multispecialty Hospital held a 36% share of the China Inpatient Care Market by facility type in 2025. Multispecialty hospitals dominate the market share because they provide comprehensive inpatient services, catering to a wide range of medical needs. Their ability to deliver specialised care across various disciplines makes them the preferred choice for patients seeking extensive treatment. The quickest growth will come from Rehabilitation Centers, forecast to expand at a CAGR of 9.1% between 2026 and 2032. Rehabilitation centers are experiencing rapid growth as they focus on recovery and rehabilitation, especially after surgeries or serious illnesses. The increasing emphasis on post-acute care is leading more patients to seek extended recovery options in these facilities. Suppliers should consider partnerships with rehabilitation centers to create comprehensive care pathways for patients.
By Duration – 3–7 Days Dominated, 1–4 Weeks Expected to Grow Fastest
The largest duration category in 2025 was 3–7 Days, with a 43% share of total revenue. The 3–7 days duration segment leads the market as it represents the typical length of stay for surgical recovery, aligning with standard practices in urban hospitals. This duration reflects average treatment protocols for various surgical procedures, ensuring optimal patient recovery. 1–4 Weeks are set to record the highest CAGR in this split, 8.4% over 2026–2032. The 1–4 weeks duration segment is growing quickly due to the rising need for extended recovery periods for patients with serious health conditions. As more patients require longer stays for effective treatment, this segment is set for significant expansion. Providers must adapt their services to accommodate the increasing demand for longer inpatient stays.
By Treatment Area – Surgery Dominated, Behavioral Disorders Expected to Grow Fastest
Surgery accounted for a 35% market share by treatment area in 2025. Surgery is the leading treatment area within the inpatient care market, representing a major focus for hospitals as it encompasses a wide range of procedures vital for patient health. The high volume of surgical admissions underscores the critical importance of this treatment area in healthcare delivery. Behavioral Disorders are projected to grow fastest, at a CAGR of 8.7% during 2026–2032. The treatment area for behavioural disorders is witnessing rapid growth as awareness of mental health issues increases, leading to more admissions for psychiatric care. This shift reflects a societal recognition of the importance of mental health services within inpatient settings. Healthcare facilities should invest in expanding their capabilities to address the rising demand for mental health treatment.
By Insurance Coverage – Covered Dominated and Is Expected to Record the Fastest Growth
In 2025, Covered led the insurance coverage split with a 39% share. The covered insurance segment leads the market, as most inpatient services are included in insurance plans, enhancing healthcare accessibility for patients. This extensive coverage promotes higher hospital admissions and supports the overall growth of the inpatient care market. The same category is also set to grow fastest, at a CAGR of 8.1% during 2026–2032. The covered insurance segment is also the fastest-growing due to government initiatives aimed at increasing healthcare funding and access, which broadens the range of services covered. As funding improves, more services are likely to be included, further stimulating growth. Suppliers must ensure their offerings align with trends in insurance coverage to maximise market opportunities.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Inpatient Care Market Outlook
- Market Size of China Inpatient Care Market, 2025
- Forecast of China Inpatient Care Market, 2032
- Historical Data and Forecast of China Inpatient Care Revenues & Volume for the Period 2022 - 2032F
- China Inpatient Care Market Trend Evolution
- China Inpatient Care Market Drivers and Challenges
- China Inpatient Care Price Trends
- China Inpatient Care Porter's Five Forces
- China Inpatient Care Industry Life Cycle
- Historical Data and Forecast of China Inpatient Care Market Revenues & Volume By Care Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Inpatient Care Market Revenues & Volume By Acute Inpatient for the Period 2022 - 2032F
- Historical Data and Forecast of China Inpatient Care Market Revenues & Volume By Long-Term Care for the Period 2022 - 2032F
- Historical Data and Forecast of China Inpatient Care Market Revenues & Volume By Maternity & Neonatal for the Period 2022 - 2032F
- Historical Data and Forecast of China Inpatient Care Market Revenues & Volume By Psychiatric Inpatient for the Period 2022 - 2032F
- Historical Data and Forecast of China Inpatient Care Market Revenues & Volume By Facility Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Inpatient Care Market Revenues & Volume By Multispecialty Hospital for the Period 2022 - 2032F
- Historical Data and Forecast of China Inpatient Care Market Revenues & Volume By Rehabilitation Centers for the Period 2022 - 2032F
- Historical Data and Forecast of China Inpatient Care Market Revenues & Volume By Birthing Centers for the Period 2022 - 2032F
- Historical Data and Forecast of China Inpatient Care Market Revenues & Volume By Mental Health Facilities for the Period 2022 - 2032F
- Historical Data and Forecast of China Inpatient Care Market Revenues & Volume By Duration for the Period 2022 - 2032F
- Historical Data and Forecast of China Inpatient Care Market Revenues & Volume By 3 7 Days for the Period 2022 - 2032F
- Historical Data and Forecast of China Inpatient Care Market Revenues & Volume By Weeks Months for the Period 2022 - 2032F
- Historical Data and Forecast of China Inpatient Care Market Revenues & Volume By 2 5 Days for the Period 2022 - 2032F
- Historical Data and Forecast of China Inpatient Care Market Revenues & Volume By 1 4 Weeks for the Period 2022 - 2032F
- Historical Data and Forecast of China Inpatient Care Market Revenues & Volume By Treatment Area for the Period 2022 - 2032F
- Historical Data and Forecast of China Inpatient Care Market Revenues & Volume By Surgery, Emergency for the Period 2022 - 2032F
- Historical Data and Forecast of China Inpatient Care Market Revenues & Volume By Stroke, Elderly Care for the Period 2022 - 2032F
- Historical Data and Forecast of China Inpatient Care Market Revenues & Volume By Pregnancy, Infants for the Period 2022 - 2032F
- Historical Data and Forecast of China Inpatient Care Market Revenues & Volume By Behavioral Disorders for the Period 2022 - 2032F
- Historical Data and Forecast of China Inpatient Care Market Revenues & Volume By Insurance Coverage for the Period 2022 - 2032F
- Historical Data and Forecast of China Inpatient Care Market Revenues & Volume By Covered for the Period 2022 - 2032F
- Historical Data and Forecast of China Inpatient Care Market Revenues & Volume By Partial for the Period 2022 - 2032F
- Historical Data and Forecast of China Inpatient Care Market Revenues & Volume By Full for the Period 2022 - 2032F
- Historical Data and Forecast of China Inpatient Care Market Revenues & Volume By Government & Private for the Period 2022 - 2032F
- China Inpatient Care Import Export Trade Statistics
- Market Opportunity Assessment By Care Type
- Market Opportunity Assessment By Facility Type
- Market Opportunity Assessment By Duration
- Market Opportunity Assessment By Treatment Area
- Market Opportunity Assessment By Insurance Coverage
- China Inpatient Care Top Companies Market Share
- China Inpatient Care Competitive Benchmarking By Technical and Operational Parameters
- China Inpatient Care Company Profiles
- China Inpatient Care Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Care Type
- Acute Inpatient
- Long-Term Care
- Maternity & Neonatal
- Psychiatric Inpatient
By Facility Type
- Multispecialty Hospital
- Rehabilitation Centers
- Birthing Centers
- Mental Health Facilities
By Duration
- 3–7 Days
- Weeks–Months
- 2–5 Days
- 1–4 Weeks
By Treatment Area
- Surgery
- Emergency
- Stroke
- Elderly Care
- Pregnancy
- Infants
- Behavioral Disorders
By Insurance Coverage
- Covered
- Partial
- Full
- Government & Private































