China Instrument Cluster Display Market Size & Growth Rate
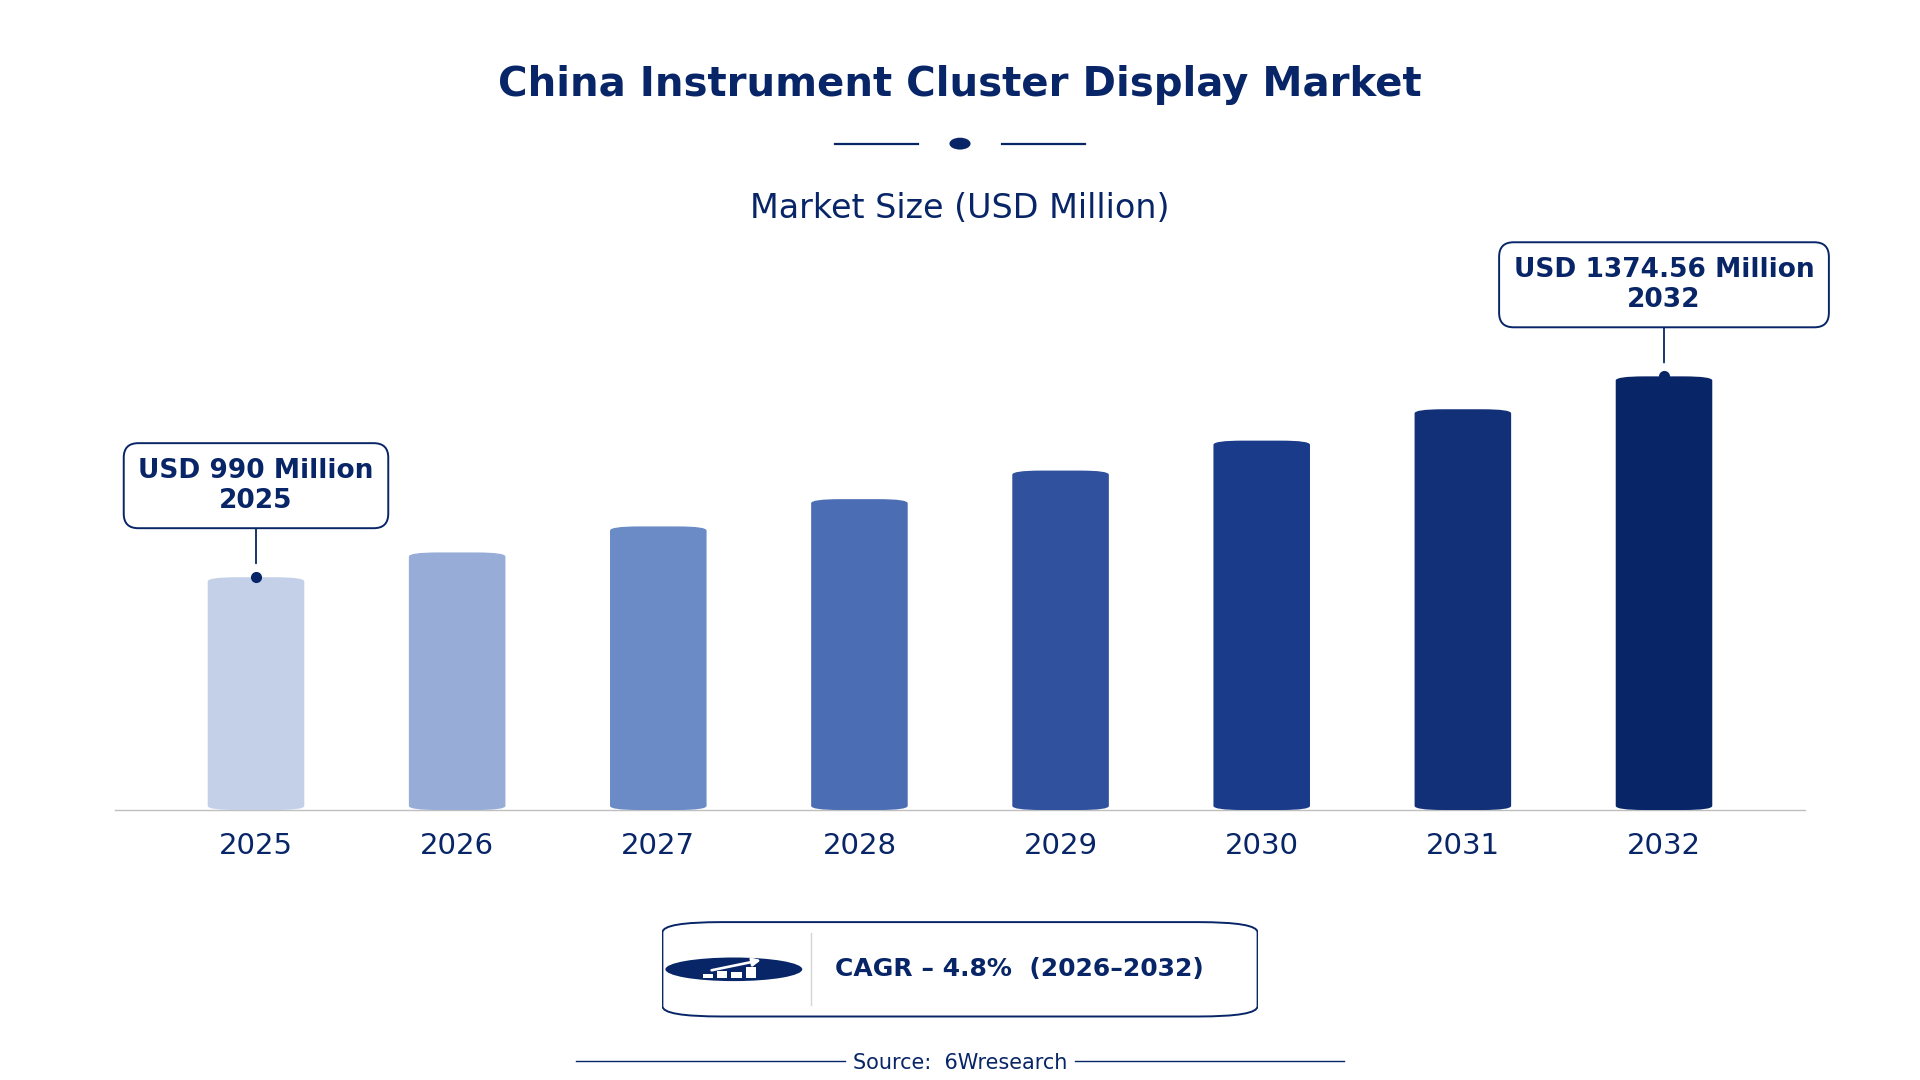
According to 6Wresearch internal database and industry insights, the China Instrument Cluster Display Market was valued at USD 990.0 million in 2025 and is projected to reach USD 1,374.56 million by 2032, growing at a CAGR of approximately 4.8% during 2026–2032.
China Instrument Cluster Display Market Highlights
| Report Metric | Details |
| Report Name | China Instrument Cluster Display Market |
| Market Size 2025 | USD 990.0 million |
| Market Size 2032 | USD 1,374.56 million |
| Absolute Growth 2025–2032 | USD 384.56 million |
| CAGR 2026–2032 | 4.8% |
| Peak Annual Growth | 7.0% in 2026 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Display Type, 2025 | LCD Cluster Display (43% share) |
| Leading Screen Technology, 2025 | TFT (41% share) |
| Leading Vehicle Type, 2025 | Passenger Cars (44% share) |
| Leading Distribution Channel, 2025 | OEMs (43% share) |
| Leading End User, 2025 | Automotive Manufacturers (38% share) |
| Fastest-Growing Display Type | OLED Cluster Display (6.8% CAGR) |
| Fastest-Growing Screen Technology | AMOLED (7.0% CAGR) |
| Fastest-Growing Vehicle Type | Electric Vehicles (7.3% CAGR) |
| Fastest-Growing Distribution Channel | Aftermarket (6.6% CAGR) |
| Fastest-Growing End User | EV Manufacturers (6.6% CAGR) |
| Growing Sector | Electric Vehicles |
| Key End Users | Automotive Manufacturers, EV Manufacturers, Dashboard Retrofitters |
China Instrument Cluster Display Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
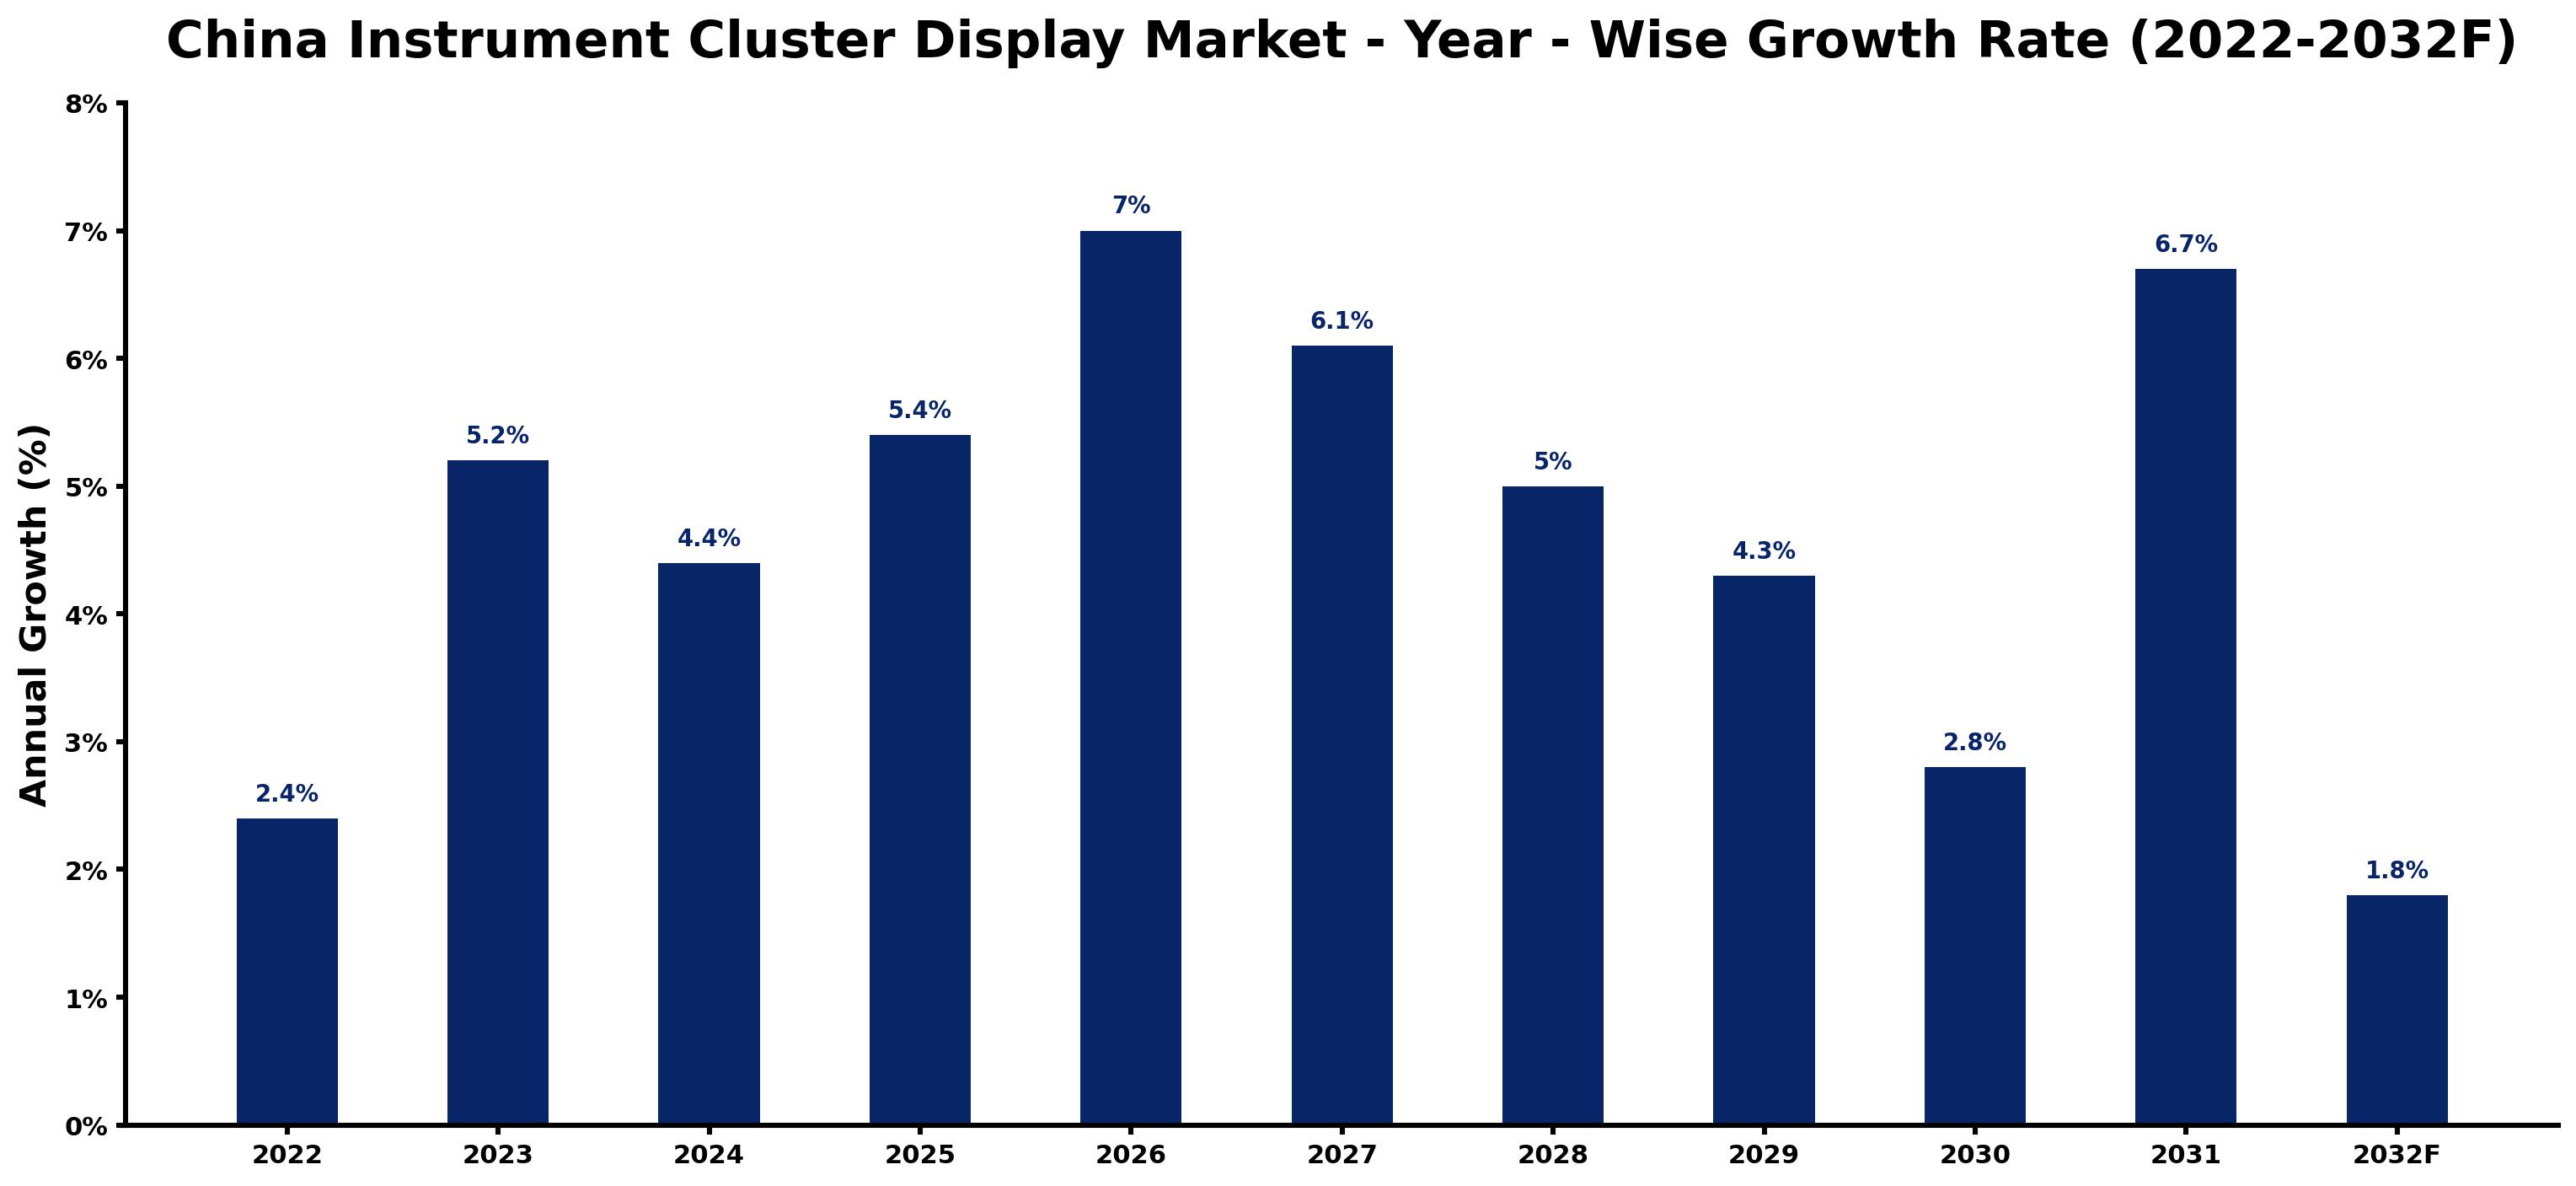
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 2.4 | The automotive sector produced 25 million vehicles, driving demand for instrument clusters. |
| 2023 | 5.2 | The average vehicle features a digital instrument cluster, with over 70% adoption in new models. |
| 2024 | 4.4 | LCD displays remain popular, but competition from OLED technology is increasing. |
| 2025 | 5.4 | The 'Automotive Electronics Development Plan' was launched to improve local manufacturing capabilities. |
| 2026 | 7.0 | The market peaks as production of electric vehicles rises, increasing demand for advanced displays. |
| 2027 | 6.1 | Growth is expected to slow as the market stabilises after peak demand. |
| 2028 | 5.0 | Demand is projected to remain steady, supported by investments in automotive electronics. |
| 2029 | 4.3 | The market will continue to grow, but at a slower pace as some segments reach saturation. |
| 2030 | 2.8 | The average age of vehicles indicates a growing market for dashboard retrofitting solutions. |
| 2031 | 6.7 | Electric vehicle manufacturers will drive renewed interest in advanced display technologies. |
| 2032 | 1.8 | Growth is expected to slow as the market adjusts to changing consumer preferences. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Instrument Cluster Display Market Synopsis
The China Instrument Cluster Display Market encompasses electronic interfaces that provide essential vehicle performance and navigation information. These displays, including LCD and OLED technologies, are vital for modern vehicles. The market is experiencing growth due to the booming automotive sector, which produced 25 million vehicles in 2022. Demand from domestic automotive manufacturers and electric vehicle producers is driving investments in advanced display technologies. Initiatives like the 'Automotive Electronics Development Plan' further improve local manufacturing capabilities, supporting this expanding market.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising production of electric vehicles increases demand for advanced displays. | Driver | High | Electric Vehicles |
| Growing adoption of digital instrument clusters in new vehicles drives market expansion. | Driver | High | Passenger Cars |
| Investment in electric vehicle infrastructure creates opportunities for innovative display solutions. | Opportunity | High | EV Manufacturers |
| The automotive aftermarket is expanding, providing avenues for retrofitting existing vehicles. | Opportunity | Medium | Dashboard Retrofitters |
| Competition from alternative display technologies may limit market share for existing products. | Restraint | High | LCD Cluster Display |
| Regulatory compliance costs can hinder smaller manufacturers from entering the market. | Restraint | Medium | OLED Cluster Display |
| The Instrument Cluster Display Market in China faces supply chain disruptions affecting production timelines. | Challenge | High | TFT-LCD Display |
| Technological advancements may outpace existing manufacturers' capabilities, impacting competitiveness. | Challenge | Medium | HUD-Integrated Display |
Evaluation of Drivers in China Instrument Cluster Display Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased production of electric vehicles drives demand for advanced display technologies. | Electric Vehicles | In 2022, the Chinese government invested $10 billion in electric vehicle infrastructure, increasing demand for innovative instrument clusters. |
| The growing adoption of digital instrument clusters in new vehicles supports market growth. | Passenger Cars | With over 70% of new models featuring digital clusters, automotive manufacturers are increasingly purchasing these displays. |
| Investment in automotive electronics enhances local manufacturing capabilities. | LCD Cluster Display | The 'Automotive Electronics Development Plan' launched in 2023 aims to boost local production and innovation. |
| The expanding automotive aftermarket creates demand for retrofitting solutions. | Dashboard Retrofitters | The automotive aftermarket in China is valued at $50 billion, with a portion dedicated to instrument clusters. |
| Technological advancements in display technologies lead to increased consumer interest. | OLED Cluster Display | The average vehicle age of 5.5 years indicates a growing market for upgraded display solutions. |
Expansion of the Instrument Cluster Display market in China is supported by the rising production of electric vehicles, increasing adoption of digital instrument clusters, and investments in automotive electronics. Over 70% of new vehicles now feature digital instrument clusters, prompting automotive manufacturers to procure more displays. The 'Automotive Electronics Development Plan' launched in 2023 aims to improve local manufacturing capabilities, further propelling market growth. The automotive aftermarket, valued at $50 billion, offers opportunities for retrofitting existing vehicles with modern displays.
Evaluation of Restraints in China Instrument Cluster Display Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Competition from alternative display technologies may limit market share. | LCD Cluster Display | LCD displays account for approximately 60% of the market share, but OLED technology is gaining traction. |
| Regulatory compliance costs can hinder smaller manufacturers from entering the market. | OLED Cluster Display | National standards like GB/T 34590-2017 impose testing and certification requirements that may be costly. |
| Supply chain disruptions can affect production timelines and availability of components. | TFT-LCD Display | Global supply chain issues have impacted the availability of key components for display manufacturing, causing delays. |
| Market saturation in certain segments may limit growth opportunities for existing players. | HUD-Integrated Display | The average age of vehicles in China indicates a growing market for retrofitting, but competition is increasing. |
| Technological advancements may outpace existing manufacturers' capabilities, impacting competitiveness. | AMOLED | The rapid development of display technologies requires constant innovation to meet consumer expectations. |
China Instrument Cluster Display Market Challenges
The China Instrument Cluster Display market encounters a notable technology challenge, as many producers face difficulties in integrating advanced display technologies, which can delay product launches for automotive manufacturers. Intense competition among local suppliers results in price wars, shrinking profit margins and compromising display quality for buyers. Frequent supply chain disruptions in Guangdong province lead to delays in sourcing components, halting production for instrument cluster makers and impacting delivery timelines for automotive producers. A shortage of skilled workers in the automotive electronics sector stifles innovation, forcing companies to rely on outdated technologies that do not meet the evolving needs of buyers.
Trends in the China Instrument Cluster Display Market
Several trends are reshaping the China Instrument Cluster Display Market; the most important are set out below.
- Shift from LCD to OLED Displays: The trend towards OLED displays is gaining traction as manufacturers seek superior colour and contrast. In 2023, the average vehicle in China features a digital instrument cluster, with over 70% adoption in new models.
- Integration of HUD Technology: The integration of Head-Up Display (HUD) technology is becoming more prevalent in modern vehicles, improving driver safety. The Shanghai International Automotive Industry Exhibition in 2023 showcased several innovations in HUD technology.
- Growth of Electric Vehicle Instrument Clusters: The demand for advanced instrument clusters in electric vehicles is rapidly increasing as production rises. In 2022, the Chinese government invested $10 billion in electric vehicle infrastructure, boosting display demand.
- Expansion of the Automotive Aftermarket: The automotive aftermarket is expanding significantly, with a portion dedicated to instrument clusters. The market is valued at $50 billion, indicating opportunities for dashboard retrofitting solutions.
Investment Opportunities in the China Instrument Cluster Display Market
The following opportunities in the China Instrument Cluster Display Market pair current demand with a clear way in.
- Collaborations with Local Manufacturers: Now is an ideal time to partner with local manufacturers in Guangdong province, a major hub for automotive electronics, to improve production capabilities. The automotive sector produced 25 million vehicles in 2022, driving demand for displays.
- Investment in Electric Vehicle Displays: Investing in advanced display technologies for electric vehicles is essential as production increases. The 'New Energy Vehicle Industry Development Plan' aims to boost EV production, impacting display demand significantly.
- Focus on Dashboard Retrofitting Solutions: The growing average age of vehicles presents an opportunity for dashboard retrofitting solutions. The automotive aftermarket in China is valued at $50 billion, with a portion dedicated to instrument clusters.
- Entering the Aftermarket Segment: The aftermarket segment is expanding, providing avenues for retrofitting existing vehicles. The average age of vehicles in China is 5.5 years, indicating a growing market for upgrades.
Government Initiatives in the China Instrument Cluster Display Market
The 'Automotive Electronics Development Plan' launched by the Ministry of Industry and Information Technology in 2023 aims to improve local manufacturing capabilities and innovation in the automotive electronics sector. This measure encourages investment in advanced display technologies and supports the growth of the Instrument Cluster Display market. Additionally, the 'Made in China 2025' initiative, implemented in 2020, focuses on upgrading the automotive electronics industry to improve competitiveness and drive technological advancements.
The National Development and Reform Commission approved a $10 billion subsidy program for electric vehicle manufacturers in 2022, promoting advanced display technologies. This program allows EV manufacturers to access funding for display solutions, thereby increasing demand for instrument clusters. Furthermore, the Ministry of Transport's 'Smart Transportation Development Strategy' introduced in 2021 promotes the integration of advanced displays in vehicles, improving safety and performance.
Future Insight of the China Instrument Cluster Display Market
The China Instrument Cluster Display market will experience notable changes by 2032, driven by advancements in display technology and supportive government initiatives. The 'Automotive Electronics Development Plan' will strengthen local manufacturing capabilities, enabling suppliers to produce high-quality displays more efficiently. By 2025, the 'Made in China 2025' initiative will enhance the competitiveness of the automotive electronics sector, encouraging innovation among producers. The Chinese government's investment of $10 billion in electric vehicle infrastructure will significantly boost demand for instrument clusters, particularly for electric vehicles, creating new opportunities for suppliers.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Display Type – LCD Cluster Display Dominated, OLED Cluster Display Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, the largest display type category in 2025 was LCD Cluster Display, with a 43% share of total revenue. LCD Cluster Displays dominate the market as they are widely integrated into modern vehicles, with over 70% adoption in new models. Their effectiveness in delivering clear and essential driving information solidifies their position among automotive manufacturers. Over 2026–2032, OLED Cluster Display is expected to post the fastest growth, at a CAGR of 6.8%. OLED Cluster Displays are experiencing rapid growth, particularly in premium vehicle models where superior colour and contrast are increasingly demanded. The surge in electric vehicle investments is likely to further accelerate this trend, enhancing their market position. Suppliers should focus on expanding their OLED product lines to cater to the growing interest from premium automotive manufacturers.
By Screen Technology – TFT Dominated, AMOLED Expected to Grow Fastest
TFT took a 41% share of screen technology in 2025, more than any other category. TFT technology holds the largest market share as it is essential for various display types in automotive applications, ensuring clarity and functionality. Its established presence in the industry makes it a preferred choice among manufacturers. AMOLED is set to record the highest CAGR in this split, 7.0% over 2026–2032. AMOLED technology is rapidly growing, particularly in high-end vehicles that require advanced displays with vibrant visuals. This trend is expected to continue as consumer preferences shift towards more sophisticated display options. Manufacturers should consider investing in AMOLED technology to capture the growing segment of high-end automotive displays.
By Vehicle Type – Passenger Cars Dominated, Electric Vehicles Expected to Grow Fastest
In 2025, Passenger Cars led the vehicle type split with a 44% share. Passenger Cars hold the largest share of the instrument cluster market, driven by the production of 25 million vehicles in 2022, creating a robust demand for reliable display solutions. This segment's prominence reflects the everyday reliance on instrument clusters in personal transportation. The quickest growth will come from Electric Vehicles, forecast to expand at a CAGR of 7.3% between 2026 and 2032. Electric Vehicles are the fastest-growing segment, necessitating advanced displays to support their innovative features. The recent $10 billion investment in electric vehicle infrastructure is expected to significantly enhance this segment's growth trajectory. Suppliers must tailor their offerings to meet the specific display needs of the expanding electric vehicle market.
By Distribution Channel – OEMs Dominated, Aftermarket Expected to Grow Fastest
With a 43% revenue share in 2025, OEMs was the largest distribution channel category. OEMs are the primary buyers of instrument clusters for new vehicles, ensuring consistent demand as the automotive sector thrives. Their substantial market share underscores their critical role in the supply chain for automotive displays. Aftermarket is projected to grow fastest, at a CAGR of 6.6% during 2026–2032. The Aftermarket is rapidly expanding as vehicle owners increasingly seek to retrofit existing vehicles with modern displays. The average vehicle age of 5.5 years indicates a strong demand for upgrades, propelling this segment's growth. Suppliers should develop targeted strategies to engage with the aftermarket, addressing the needs of consumers looking to enhance their vehicle displays.
By End User – Automotive Manufacturers Dominated, EV Manufacturers Expected to Grow Fastest
Automotive Manufacturers held a 38% share of the China Instrument Cluster Display Market by end user in 2025. Automotive Manufacturers are the leading end users of instrument clusters, as they are the primary producers and users of these essential components. Their significant market share highlights their pivotal role in the automotive supply chain. Over 2026–2032, EV Manufacturers are expected to post the fastest growth, at a CAGR of 6.6%. EV Manufacturers are driving rapid growth in demand for innovative display solutions, reflecting the unique requirements of electric vehicles. This trend aligns with the broader shift towards electrification in the automotive industry. Suppliers should prioritise partnerships with EV manufacturers to stay competitive in the evolving display technology market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Instrument Cluster Display Market Outlook
- Market Size of China Instrument Cluster Display Market, 2025
- Forecast of China Instrument Cluster Display Market, 2032
- Historical Data and Forecast of China Instrument Cluster Display Revenues & Volume for the Period 2022 - 2032F
- China Instrument Cluster Display Market Trend Evolution
- China Instrument Cluster Display Market Drivers and Challenges
- China Instrument Cluster Display Price Trends
- China Instrument Cluster Display Porter's Five Forces
- China Instrument Cluster Display Industry Life Cycle
- Historical Data and Forecast of China Instrument Cluster Display Market Revenues & Volume By Display Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Instrument Cluster Display Market Revenues & Volume By LCD Cluster Display for the Period 2022 - 2032F
- Historical Data and Forecast of China Instrument Cluster Display Market Revenues & Volume By OLED Cluster Display for the Period 2022 - 2032F
- Historical Data and Forecast of China Instrument Cluster Display Market Revenues & Volume By TFT-LCD Display for the Period 2022 - 2032F
- Historical Data and Forecast of China Instrument Cluster Display Market Revenues & Volume By HUD-Integrated Display for the Period 2022 - 2032F
- Historical Data and Forecast of China Instrument Cluster Display Market Revenues & Volume By Screen Technology for the Period 2022 - 2032F
- Historical Data and Forecast of China Instrument Cluster Display Market Revenues & Volume By TFT for the Period 2022 - 2032F
- Historical Data and Forecast of China Instrument Cluster Display Market Revenues & Volume By AMOLED for the Period 2022 - 2032F
- Historical Data and Forecast of China Instrument Cluster Display Market Revenues & Volume By IPS for the Period 2022 - 2032F
- Historical Data and Forecast of China Instrument Cluster Display Market Revenues & Volume By Projection for the Period 2022 - 2032F
- Historical Data and Forecast of China Instrument Cluster Display Market Revenues & Volume By Vehicle Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Instrument Cluster Display Market Revenues & Volume By Passenger Cars for the Period 2022 - 2032F
- Historical Data and Forecast of China Instrument Cluster Display Market Revenues & Volume By Commercial Vehicles for the Period 2022 - 2032F
- Historical Data and Forecast of China Instrument Cluster Display Market Revenues & Volume By Electric Vehicles for the Period 2022 - 2032F
- Historical Data and Forecast of China Instrument Cluster Display Market Revenues & Volume By Two-Wheelers for the Period 2022 - 2032F
- Historical Data and Forecast of China Instrument Cluster Display Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Instrument Cluster Display Market Revenues & Volume By OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Instrument Cluster Display Market Revenues & Volume By Aftermarket for the Period 2022 - 2032F
- Historical Data and Forecast of China Instrument Cluster Display Market Revenues & Volume By Retail Stores for the Period 2022 - 2032F
- Historical Data and Forecast of China Instrument Cluster Display Market Revenues & Volume By Online Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China Instrument Cluster Display Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Instrument Cluster Display Market Revenues & Volume By Automotive Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Instrument Cluster Display Market Revenues & Volume By Dashboard Retrofitters for the Period 2022 - 2032F
- Historical Data and Forecast of China Instrument Cluster Display Market Revenues & Volume By EV Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Instrument Cluster Display Market Revenues & Volume By Specialty Installers for the Period 2022 - 2032F
- China Instrument Cluster Display Import Export Trade Statistics
- Market Opportunity Assessment By Display Type
- Market Opportunity Assessment By Screen Technology
- Market Opportunity Assessment By Vehicle Type
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China Instrument Cluster Display Top Companies Market Share
- China Instrument Cluster Display Competitive Benchmarking By Technical and Operational Parameters
- China Instrument Cluster Display Company Profiles
- China Instrument Cluster Display Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Display Type
- LCD Cluster Display
- OLED Cluster Display
- TFT-LCD Display
- HUD-Integrated Display
By Screen Technology
- TFT
- AMOLED
- IPS
- Projection
By Vehicle Type
- Passenger Cars
- Commercial Vehicles
- Electric Vehicles
- Two-Wheelers
By Distribution Channel
- OEMs
- Aftermarket
- Retail Stores
- Online Platforms
By End User
- Automotive Manufacturers
- Dashboard Retrofitters
- EV Manufacturers
- Specialty Installers































