China Insurance Distribution Market Size & Growth Rate
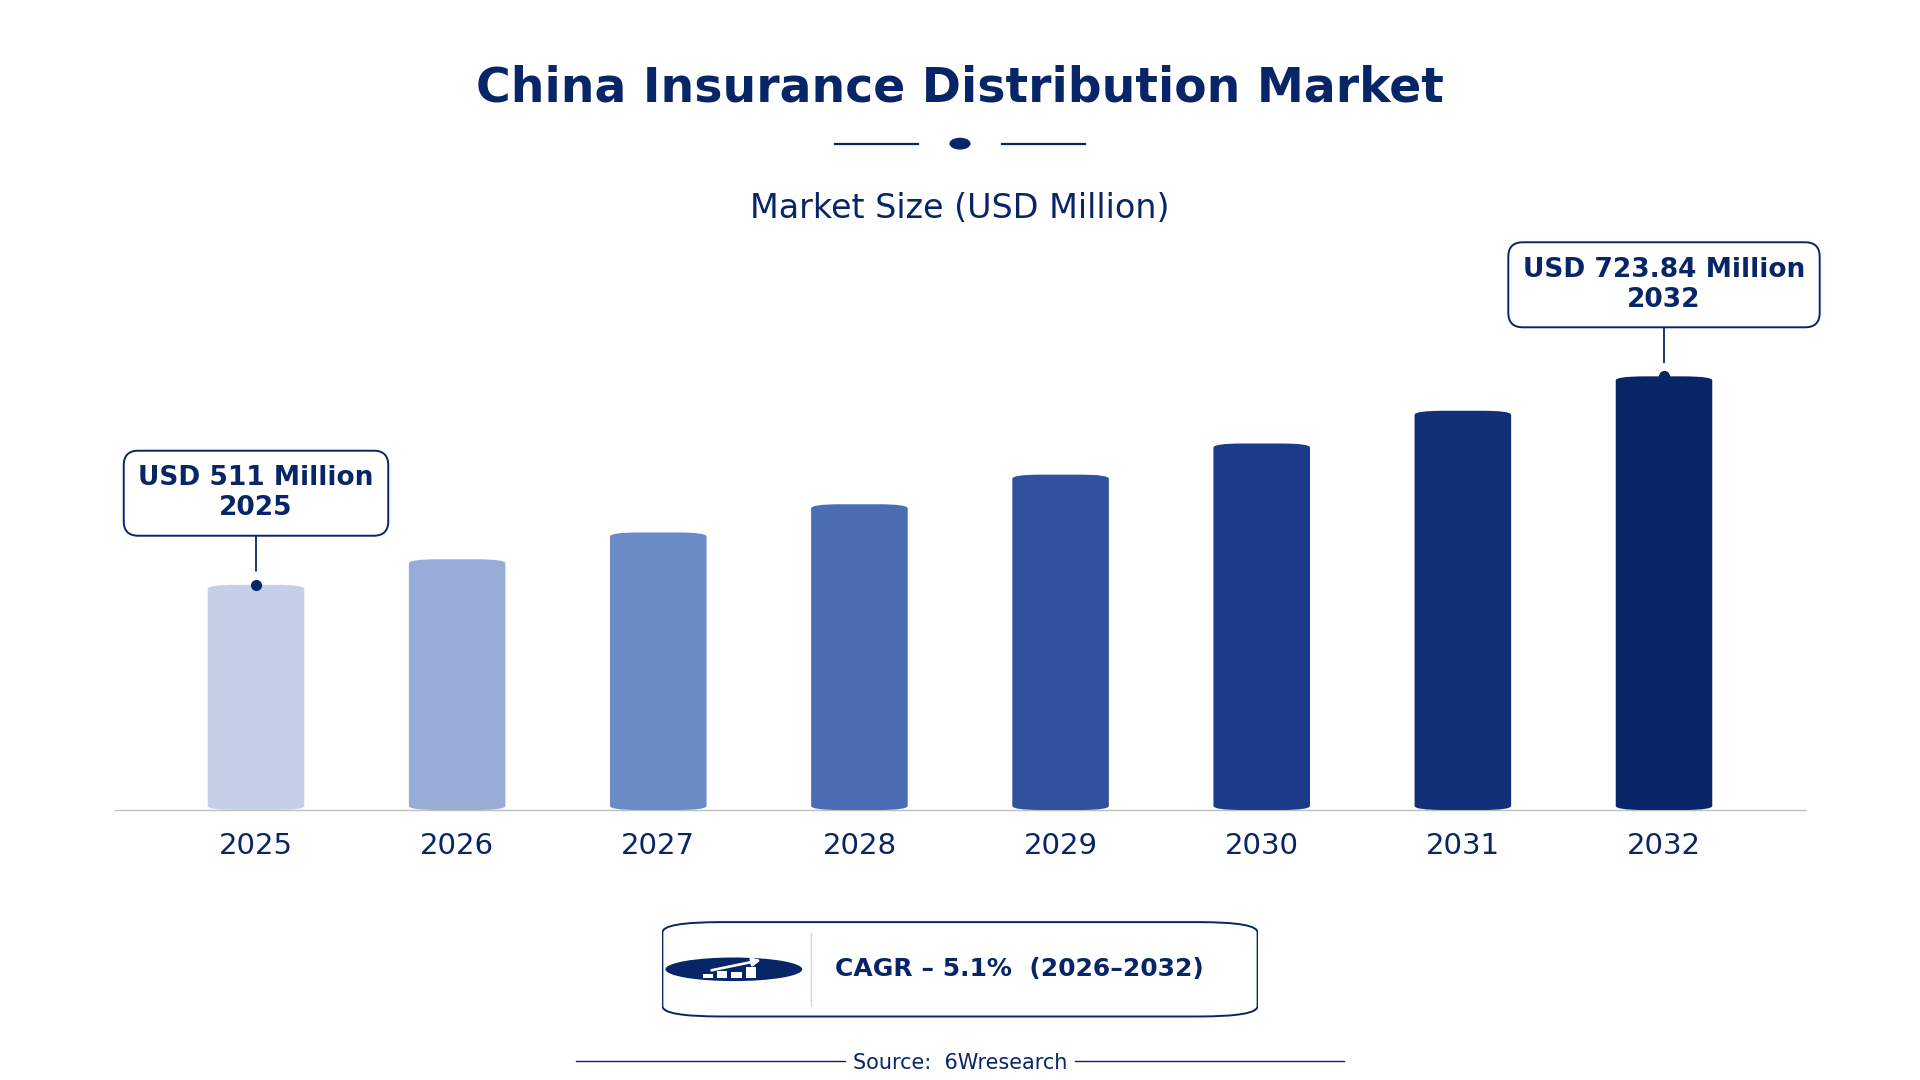
According to 6Wresearch internal database and industry insights, the China Insurance Distribution Market was valued at USD 511.0 million in 2025 and is projected to reach USD 723.84 million by 2032, growing at a CAGR of approximately 5.1% during 2026–2032.
China Insurance Distribution Market Highlights
| Report Metric | Details |
| Report Name | China Insurance Distribution Market |
| Market Size 2025 | USD 511.0 million |
| Market Size 2032 | USD 723.84 million |
| Absolute Growth 2025–2032 | USD 212.84 million |
| CAGR 2026–2032 | 5.1% |
| Peak Annual Growth | 7.6% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Channel Type, 2025 | Direct Online (36% share) |
| Leading Product Type, 2025 | Life Insurance (45% share) |
| Leading Customer Segment, 2025 | Individual (40% share) |
| Leading Technology Mode, 2025 | Digital (45% share) |
| Leading End User, 2025 | General Public (51% share) |
| Fastest-Growing Product Type | Health Insurance (7.6% CAGR) |
| Fastest-Growing Customer Segment | Corporate (7.4% CAGR) |
| Fastest-Growing Technology Mode | Assisted Digital (7.7% CAGR) |
| Fastest-Growing End User | Enterprises (6.5% CAGR) |
| Growing Sector | Health Insurance |
| Key End Users | General Public, Individual Consumers, Corporates, Retail Customers |
China Insurance Distribution Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
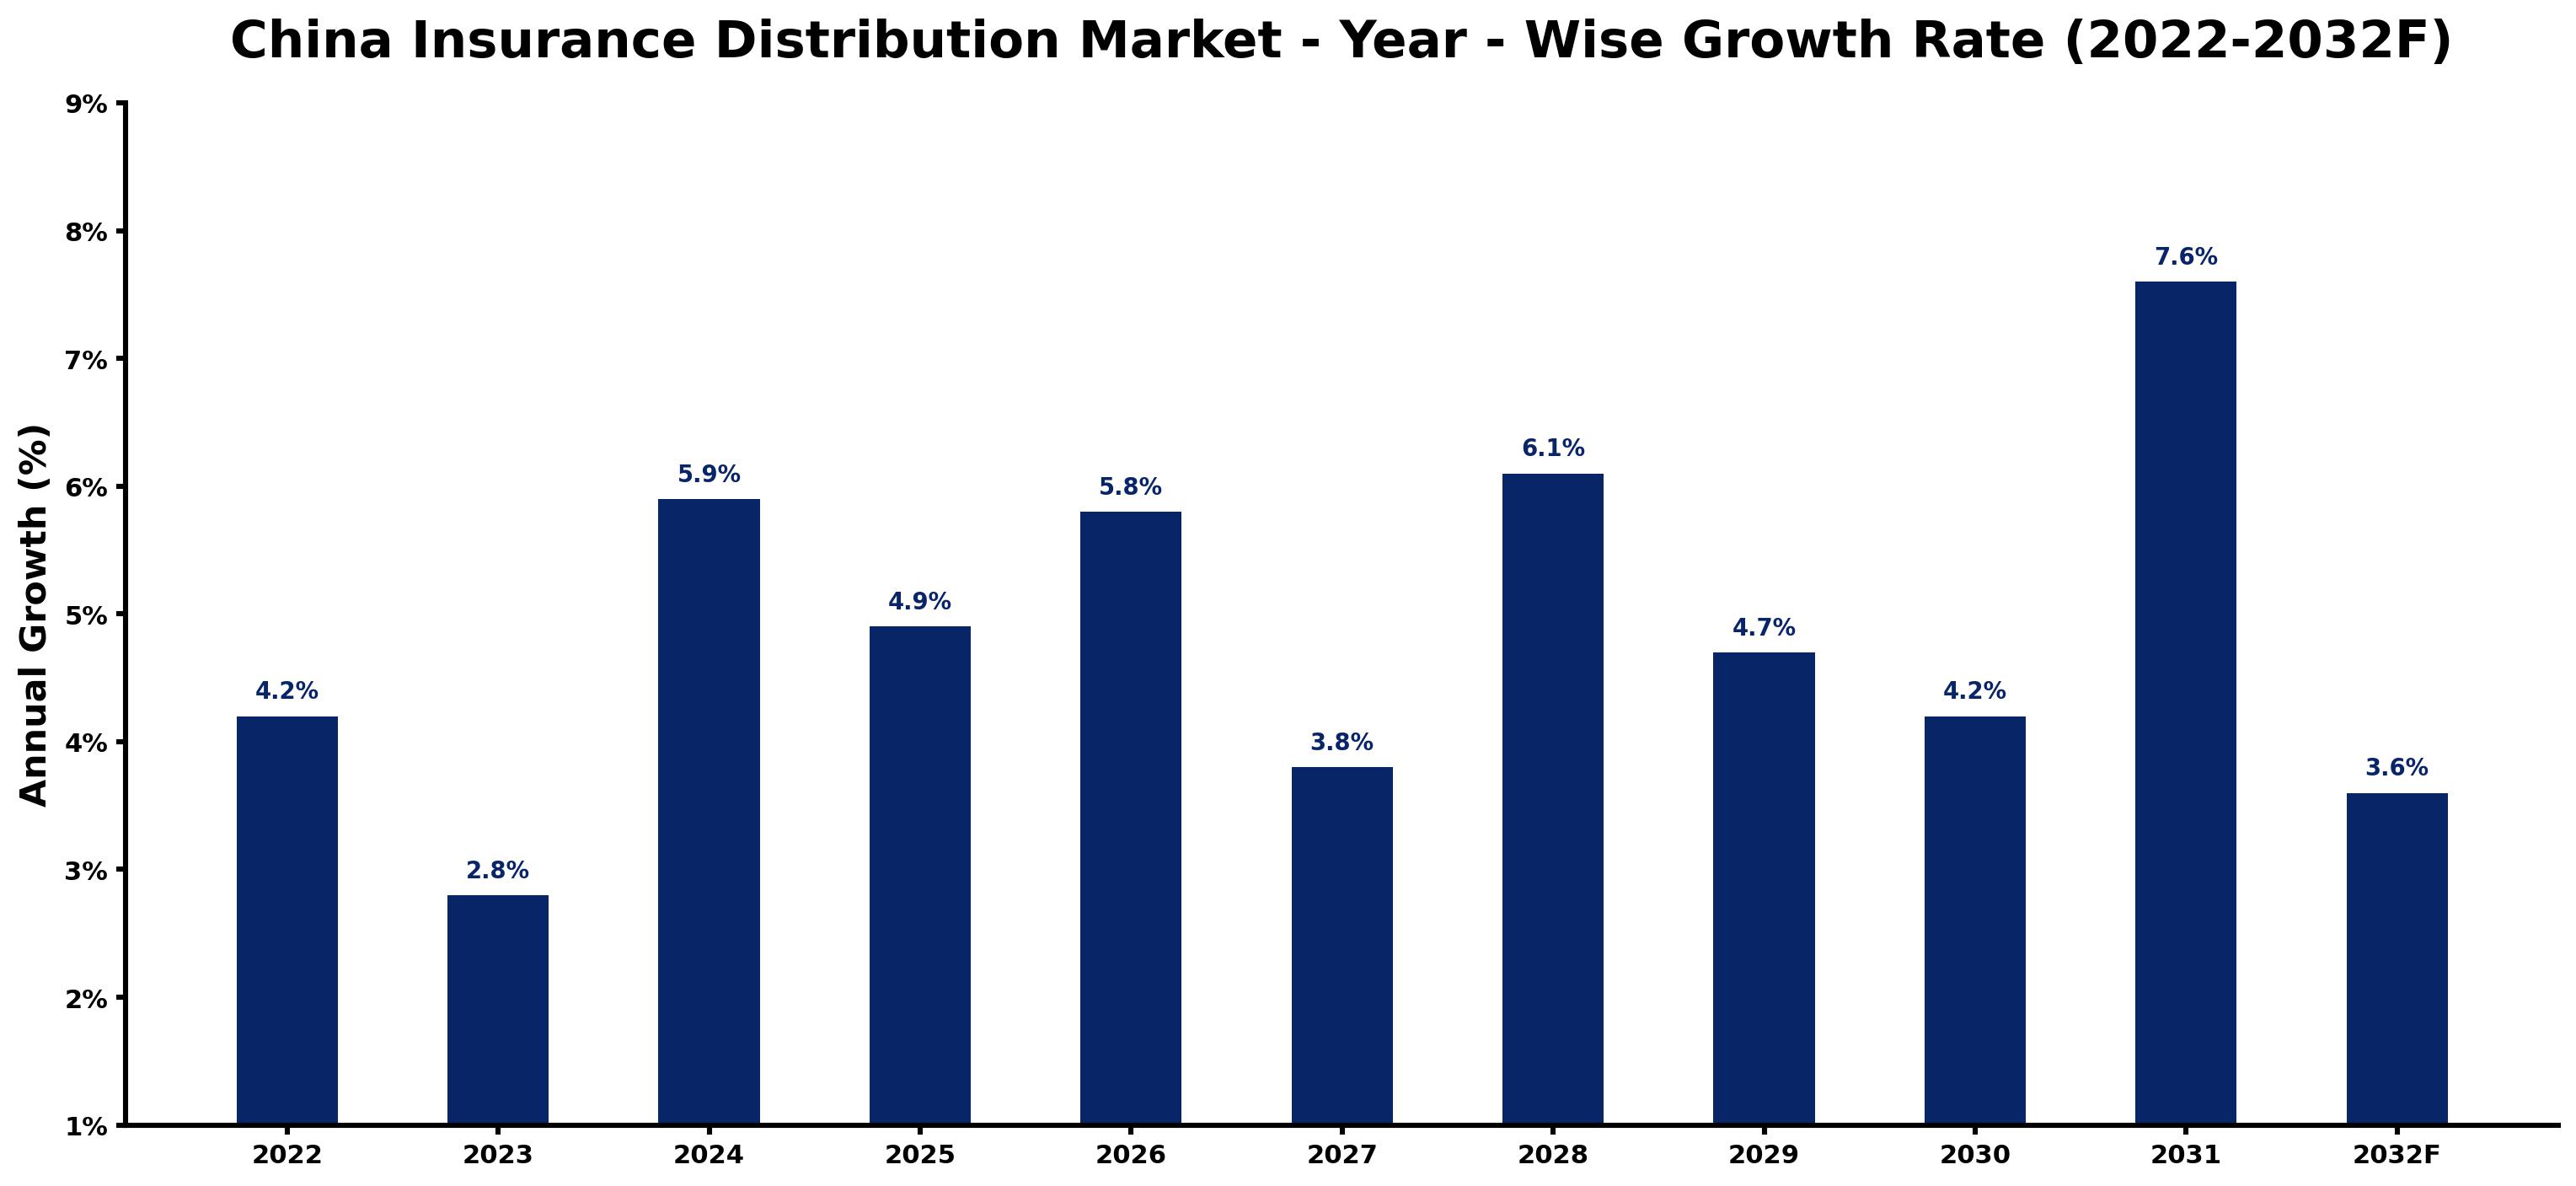
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.2 | The insurance penetration rate reached 5.4%, indicating strong market activity. |
| 2023 | 2.8 | Growth slowed due to the 'Digital Insurance Development Plan' promoting digital transformation in insurance. |
| 2024 | 5.9 | Demand surged as health insurance premiums grew by 20%, reflecting rising healthcare costs. |
| 2025 | 4.9 | Market growth slowed again as the industry adjusted to new digital trends and consumer needs. |
| 2026 | 5.8 | Investment in technology for customer experience is expected to boost overall market demand. |
| 2027 | 3.8 | Growth is projected to slow as the market stabilises following rapid digital adoption and competition. |
| 2028 | 6.1 | Health insurance demand is expected to rise, driven by urbanisation and increased healthcare awareness. |
| 2029 | 4.7 | Market growth is anticipated to slow as the industry faces challenges in meeting evolving consumer expectations. |
| 2030 | 4.2 | Continued investment in digital platforms is expected to support steady growth in insurance distribution. |
| 2031 | 7.6 | A peak in growth is expected as the e-commerce sector drives a notable increase in insurance distribution. |
| 2032 | 3.6 | Growth is projected to slow as the market stabilises, reflecting ongoing digital transformation efforts. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Insurance Distribution Market Synopsis
Insurance Distribution in China encompasses the processes and channels through which insurance products are sold to consumers. The market is expanding due to rising health insurance premiums and a shift towards digital distribution. The 'Insurance for All' initiative aims to improve coverage for rural residents, contributing to increased demand. With over 1.6 billion policies in force, the sector is attracting substantial investment and innovation.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising health insurance premiums driven by increased healthcare costs | Driver | High | Health Insurance |
| Digital distribution channels expanding due to consumer preferences | Driver | High | Direct Online |
| Growing demand for life insurance products among individuals | Opportunity | High | Life Insurance |
| Increased investment in technology for better service delivery | Opportunity | Medium | Digital |
| Challenges in meeting regulatory requirements for new products | Restraint | High | Direct Online |
| Competition from emerging digital platforms affecting traditional channels | Restraint | Medium | Agency-Based |
| Buyers face delays in policy approvals due to regulatory scrutiny | Challenge | High | Direct Online |
| Suppliers struggle with adapting to rapid technological changes | Challenge | Medium | Direct Online |
Evaluation of Drivers in China Insurance Distribution Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increase in health insurance premiums due to rising healthcare costs | Health Insurance | Health insurance premiums grew by 20% in 2022, prompting more consumers to seek coverage. |
| Expansion of digital distribution channels | Direct Online | The e-commerce sector is projected to drive a 15% increase in insurance distribution by 2025, reflecting changing consumer preferences. |
| Growing individual demand for life insurance | Life Insurance | The life insurance sector accounted for approximately 54% of total insurance premiums in 2022, highlighting its significance in consumer financial planning. |
| Investment in technology for improved customer experience | Digital | The 'Digital Insurance Development Plan' promotes technology adoption in the insurance sector, improving service delivery. |
| Increased focus on consumer protection regulations | Direct Online | The updated 'Insurance Consumer Protection Regulation' improves transparency and consumer rights, fostering trust in the market. |
Growth across the Insurance Distribution market in China is anchored in expanding digital distribution channels, increasing individual demand for life insurance, and rising health insurance premiums. The e-commerce sector is projected to drive a 15% increase in insurance distribution by 2025, reflecting changing consumer preferences. Health insurance premiums grew by 20% in 2022, prompting more consumers to seek coverage. The life insurance sector accounted for approximately 54% of total insurance premiums in 2022, underscoring its importance for long-term financial security. Investment in technology is improving customer experience and service delivery, enabling insurers to better meet consumer needs.
Evaluation of Restraints in China Insurance Distribution Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Regulatory scrutiny delaying policy approvals | Direct Online | Buyers face delays in policy approvals due to stringent regulatory requirements, which can extend the time to secure coverage. |
| Competition from emerging digital platforms | Agency-Based | Traditional channels are affected as digital platforms gain market share, leading to a decline in consumer engagement with conventional methods. |
| Challenges in adapting to rapid technological changes | Direct Online | Suppliers struggle to keep pace with evolving technologies, making it difficult to meet consumer expectations effectively. |
| High costs associated with compliance and consumer protection regulations | Direct Online | Producers must invest significantly to meet regulatory standards, impacting their operational budgets. |
| Limited access to insurance products in rural areas | Direct Online | The 'Insurance for All' initiative aims to improve accessibility for 100 million rural residents, addressing the gap in coverage. |
China Insurance Distribution Market Challenges
The China Insurance Distribution Market encounters a notable skills shortage, as the rapid shift towards digital platforms outpaces workforce training, resulting in slower service delivery for agencies. Many distributors face challenges with technology adoption; inadequate infrastructure hampers their ability to effectively use online channels, which delays consumer access to vital insurance products. Regulatory complexities arise from stringent guidelines set by the China Banking and Insurance Regulatory Commission, which can extend product launch timelines and inflate operational costs for insurers. Competition from new digital entrants compels traditional distributors to reduce prices, squeezing profit margins and limiting funds for necessary innovation.
Trends in the China Insurance Distribution Market
Buyers and suppliers in the China Insurance Distribution Market are adjusting to the following trends.
- Shift towards Digital Distribution: Insurance distribution in China is increasingly moving towards digital platforms, reflecting consumer preferences for convenience. The e-commerce sector is projected to drive a 15% increase in insurance distribution by 2025.
- Growth of Health Insurance Products: Health insurance is gaining traction as urbanisation and healthcare costs rise. In 2022, health insurance premiums grew by 20%, indicating strong demand for coverage.
- Increased Focus on Consumer Protection: The updated 'Insurance Consumer Protection Regulation' improves transparency in insurance transactions. This regulation, effective since 2022, aims to build consumer trust and rights.
- Expansion of the Individual Insurance Market: The individual insurance segment is experiencing growth, driven by increasing awareness of financial security. In 2022, individuals accounted for 40% of the insurance market.
Investment Opportunities in the China Insurance Distribution Market
Investors looking at the China Insurance Distribution Market should consider the following areas.
- Investment in Digital Platforms: Urban areas are experiencing a surge in digital insurance platforms, with a projected 15% increase in distribution by 2025. Investing in these platforms can attract a wider customer base.
- Targeting Health Insurance for Urban Consumers: Health insurance demand is rising in urban areas, driven by increased healthcare costs. Focusing on this segment can yield substantial returns for insurers.
- Partnerships with E-Commerce Platforms: E-commerce users represent a growing market segment for insurance products. Collaborating with e-commerce platforms can improve distribution and reach.
- Expansion of Insurance Coverage in Rural Areas: The 'Insurance for All' initiative aims to improve accessibility for 100 million rural residents by 2025. This presents an opportunity for insurers to expand their reach.
Government Initiatives in the China Insurance Distribution Market
The 'Insurance for All' initiative, launched by the China Banking and Insurance Regulatory Commission in 2023, aims to improve insurance accessibility for 100 million rural residents by 2025. This initiative is projected to increase the number of policies in force and improve coverage in underserved areas. Additionally, the 'Digital Insurance Development Plan' introduced in 2021 promotes digital transformation in the insurance sector, encouraging investment in technology and innovation. These measures aim to improve the overall insurance framework in China, benefiting both producers and consumers.
The Insurance Association of China oversees various schemes, including the 'Health Insurance Reform Plan' approved in 2020, which expands coverage for 1.4 billion citizens. Furthermore, the association promotes industry standards and best practices, ensuring that consumers receive quality services. These agencies play a key role in funding initiatives that improve insurance accessibility and consumer protection, enabling producers to better serve their clients.
Future Insight of the China Insurance Distribution Market
The China Insurance Distribution Market will experience transformative changes by 2032, primarily driven by the 'Insurance for All' initiative aimed at enhancing coverage in rural areas. E-commerce is expected to contribute to a projected increase of 5 trillion CNY in total insurance premium income by 2025, improving accessibility for consumers. Technological advancements will facilitate streamlined operations, allowing for quicker policy issuance and enhanced customer service. The rising demand for health insurance, spurred by escalating healthcare costs, will further motivate the development of diverse distribution channels.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Channel Type – Direct Online Dominated and Is Expected to Record the Fastest Growth
According to Shubham Deep, Research Manager at 6Wresearch, with a 36% revenue share in 2025, Direct Online was the largest channel type category. Direct online channels dominate the market due to their convenience, allowing consumers to easily purchase insurance products from the comfort of their homes. This shift towards digital platforms reflects a significant change in consumer behaviour, particularly among tech-savvy individuals seeking quick and efficient solutions. The same category is also set to grow fastest, at a CAGR of 6.8% during 2026–2032. The direct online segment is expected to sustain its rapid growth, as the e-commerce sector is projected to drive a 15% increase in insurance distribution by 2025. This trend highlights a growing preference for the efficiency and accessibility of online insurance solutions, further solidifying its market position. Suppliers must enhance their digital strategies to effectively capture the expanding share of online consumers.
By Product Type – Life Insurance Dominated, Health Insurance Expected to Grow Fastest
Life Insurance took a 45% share of product type in 2025, more than any other category. Life insurance holds a substantial share of the market, addressing the long-term financial security needs of individuals. With approximately 54% of total insurance premiums attributed to life insurance, it reflects a strong consumer preference for these products. Over 2026–2032, Health Insurance is expected to post the fastest growth, at a CAGR of 7.6%. Health insurance is experiencing rapid growth, with premiums increasing by 20% in 2022 due to rising healthcare costs. This surge indicates a heightened awareness and demand for health coverage among consumers, particularly in urban areas. Buyers may benefit from exploring diverse health insurance options as the market adapts to rising healthcare costs.
By Customer Segment – Individual Dominated, Corporate Expected to Grow Fastest
Individual held a 40% share of the China Insurance Distribution Market by customer segment in 2025. The individual customer segment holds a substantial share of the market, primarily due to the rising demand for personal insurance solutions. This segment reflects the widespread need for financial protection against various risks, making it a focal point for insurers aiming to cater to personal needs. Corporate is set to record the highest CAGR in this split, 7.4% over 2026–2032. Corporate customers are emerging as the fastest-growing segment, driven by the need for comprehensive insurance solutions for employee benefits and risk management. This shift signifies an increasing focus of businesses on securing their workforce against potential risks, which could lead to a larger market share for corporate offerings. Suppliers should customise their offerings to meet the specific requirements of corporate clients to seize this growing market share.
By Technology Mode – Digital Dominated, Assisted Digital Expected to Grow Fastest
In 2025, Digital led the technology mode split with a 45% share. Digital channels lead the market, aligning with consumer preferences for online purchasing and showcasing a broader trend towards digital solutions. The rapid growth in digital distribution indicates a shift towards more accessible and user-friendly insurance purchasing options, appealing to a wide range of consumers. Assisted Digital is projected to grow fastest, at a CAGR of 7.7% during 2026–2032. Assisted digital methods are gaining traction, significantly enhancing customer experience during the insurance purchasing process. This growth suggests that consumers appreciate the added support when navigating online insurance options, which may result in higher conversion rates and customer satisfaction. Suppliers should invest in assisted digital technologies to improve customer engagement and satisfaction in the insurance distribution process.
By End User – General Public Dominated, Enterprises Expected to Grow Fastest
The largest end user category in 2025 was General Public, with a 51% share of total revenue. The general public represents the largest share of the insurance market, as most products are designed for individual consumers seeking financial protection. This broad target audience drives substantial demand across various insurance types, reinforcing the importance of catering to this segment. The quickest growth will come from Enterprises, forecast to expand at a CAGR of 6.5% between 2026 and 2032. Enterprises are the fastest-growing end-user segment, as they require comprehensive insurance solutions to manage diverse risks effectively. This trend underscores the increasing significance of risk management in corporate strategies, highlighting a shift in focus towards enterprise needs and the potential for growth in this area. Suppliers should develop tailored insurance solutions for enterprises to capitalise on this expanding market segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Insurance Distribution Market Outlook
- Market Size of China Insurance Distribution Market, 2025
- Forecast of China Insurance Distribution Market, 2032
- Historical Data and Forecast of China Insurance Distribution Revenues & Volume for the Period 2022 - 2032F
- China Insurance Distribution Market Trend Evolution
- China Insurance Distribution Market Drivers and Challenges
- China Insurance Distribution Price Trends
- China Insurance Distribution Porter's Five Forces
- China Insurance Distribution Industry Life Cycle
- Historical Data and Forecast of China Insurance Distribution Market Revenues & Volume By Channel Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurance Distribution Market Revenues & Volume By Agency-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurance Distribution Market Revenues & Volume By Bancassurance for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurance Distribution Market Revenues & Volume By Direct Online for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurance Distribution Market Revenues & Volume By Broker Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurance Distribution Market Revenues & Volume By Product Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurance Distribution Market Revenues & Volume By Life Insurance for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurance Distribution Market Revenues & Volume By Health Insurance for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurance Distribution Market Revenues & Volume By Auto/Home Insurance for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurance Distribution Market Revenues & Volume By Travel/Property Insurance for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurance Distribution Market Revenues & Volume By Customer Segment for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurance Distribution Market Revenues & Volume By Individual for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurance Distribution Market Revenues & Volume By Corporate for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurance Distribution Market Revenues & Volume By Retail Customers for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurance Distribution Market Revenues & Volume By SMEs for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurance Distribution Market Revenues & Volume By Technology Mode for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurance Distribution Market Revenues & Volume By Manual for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurance Distribution Market Revenues & Volume By Assisted Digital for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurance Distribution Market Revenues & Volume By Digital for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurance Distribution Market Revenues & Volume By Hybrid for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurance Distribution Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurance Distribution Market Revenues & Volume By General Public for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurance Distribution Market Revenues & Volume By Enterprises for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurance Distribution Market Revenues & Volume By E-Commerce Users for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurance Distribution Market Revenues & Volume By SMEs for the Period 2022 - 2032F
- China Insurance Distribution Import Export Trade Statistics
- Market Opportunity Assessment By Channel Type
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Customer Segment
- Market Opportunity Assessment By Technology Mode
- Market Opportunity Assessment By End User
- China Insurance Distribution Top Companies Market Share
- China Insurance Distribution Competitive Benchmarking By Technical and Operational Parameters
- China Insurance Distribution Company Profiles
- China Insurance Distribution Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Channel Type
- Agency-Based
- Bancassurance
- Direct Online
- Broker Channel
By Product Type
- Life Insurance
- Health Insurance
- Auto/Home Insurance
- Travel/Property Insurance
By Customer Segment
- Individual
- Corporate
- Retail Customers
- SMEs
By Technology Mode
- Manual
- Assisted Digital
- Digital
- Hybrid
By End User
- General Public
- Enterprises
- E-Commerce Users
- SMEs































