China Insurtech SaaS Market Size & Growth Rate
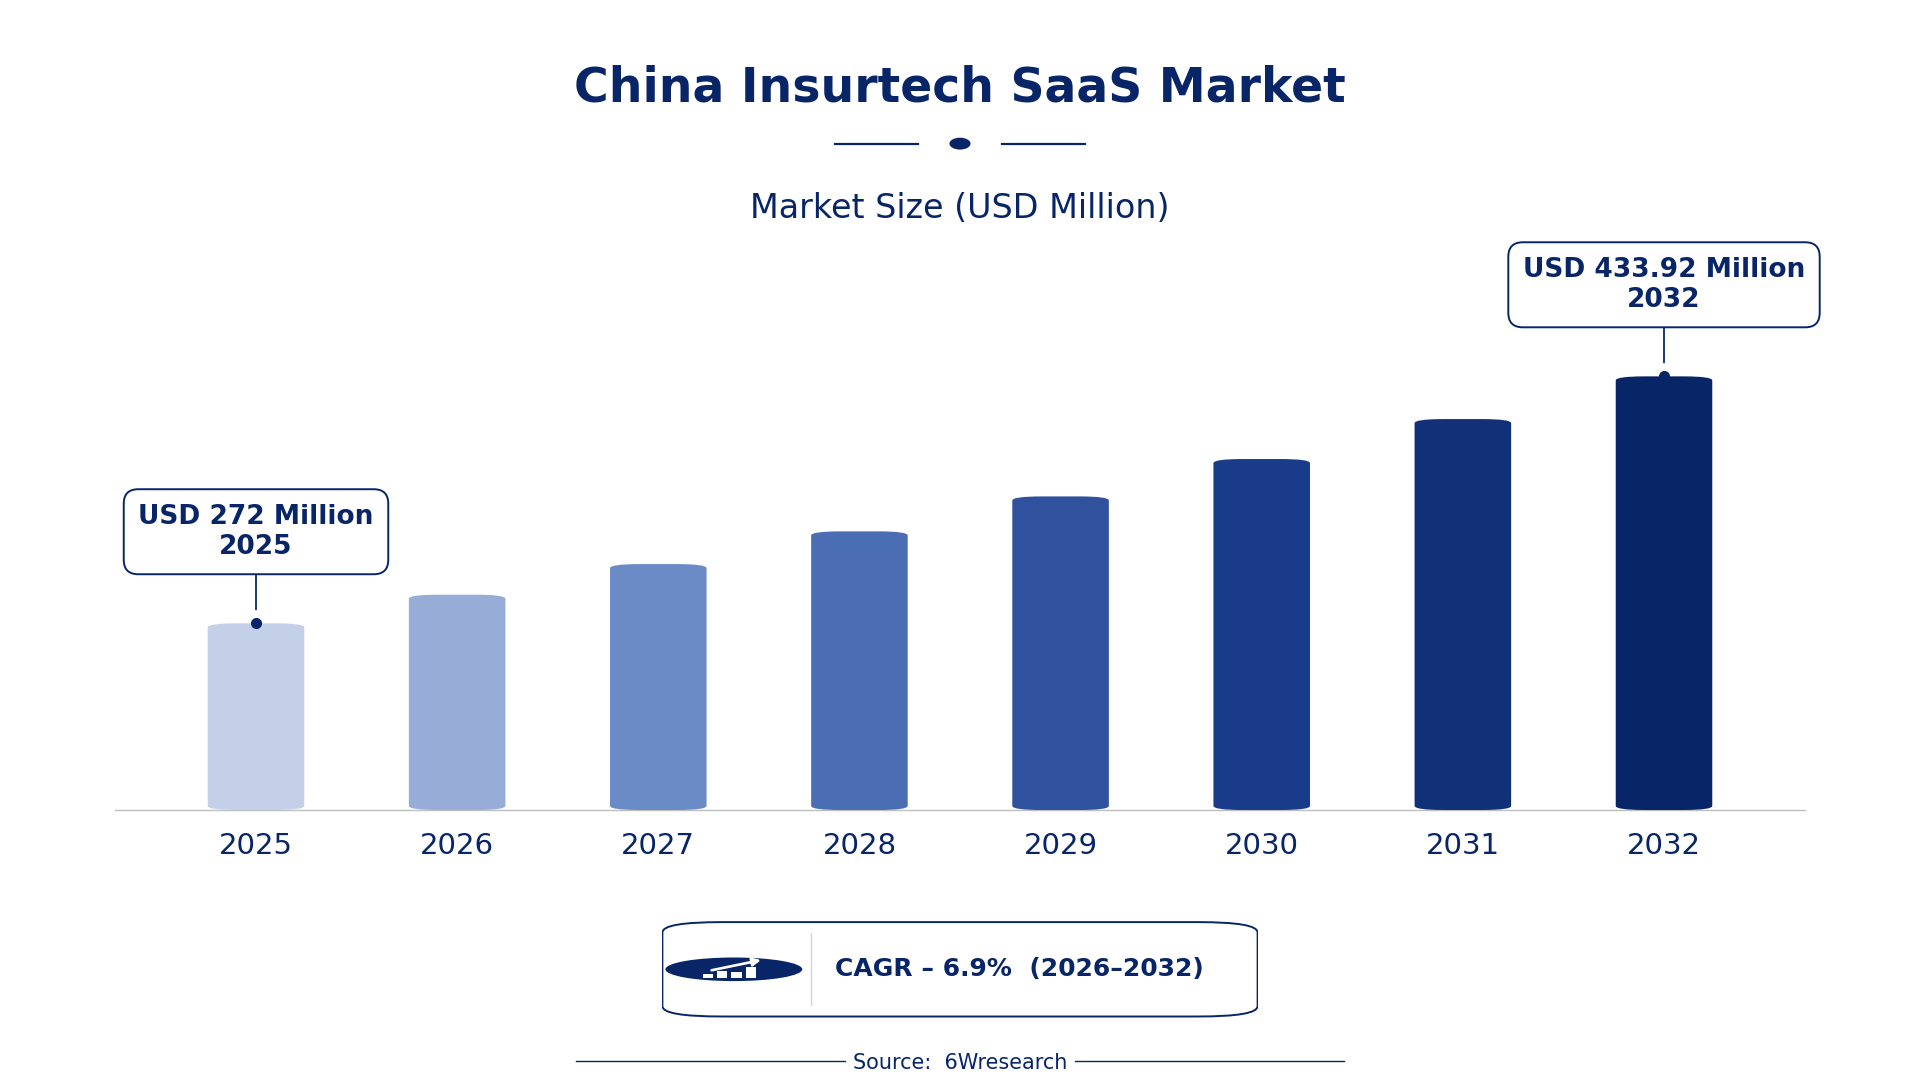
According to 6Wresearch internal database and industry insights, the China Insurtech SaaS Market was valued at USD 272.0 million in 2025 and is projected to reach USD 433.92 million by 2032, growing at a CAGR of approximately 6.9% during 2026–2032.
China Insurtech SaaS Market Highlights
| Report Metric | Details |
| Report Name | China Insurtech SaaS Market |
| Market Size 2025 | USD 272.0 million |
| Market Size 2032 | USD 433.92 million |
| Absolute Growth 2025–2032 | USD 161.92 million |
| CAGR 2026–2032 | 6.9% |
| Peak Annual Growth | 9.2% in 2029 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Software Type, 2025 | Policy Management (35% share) |
| Leading Deployment Mode, 2025 | Cloud-Based (48% share) |
| Leading Application Area, 2025 | Life & Health Insurance (43% share) |
| Leading End User Type, 2025 | Insurers (43% share) |
| Leading Distribution Channel, 2025 | SaaS Platforms (45% share) |
| Fastest-Growing Software Type | Claims Automation (7.9% CAGR) |
| Fastest-Growing Deployment Mode | On-Premise (7.9% CAGR) |
| Fastest-Growing Application Area | Auto & Property (8.1% CAGR) |
| Fastest-Growing End User Type | Brokers (8.6% CAGR) |
| Fastest-Growing Distribution Channel | IT Solution Providers (8.2% CAGR) |
| Growing Sector | Life & Health Insurance |
| Key End Users | Insurers, Brokers, TPAs, Agents/Agencies |
China Insurtech SaaS Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
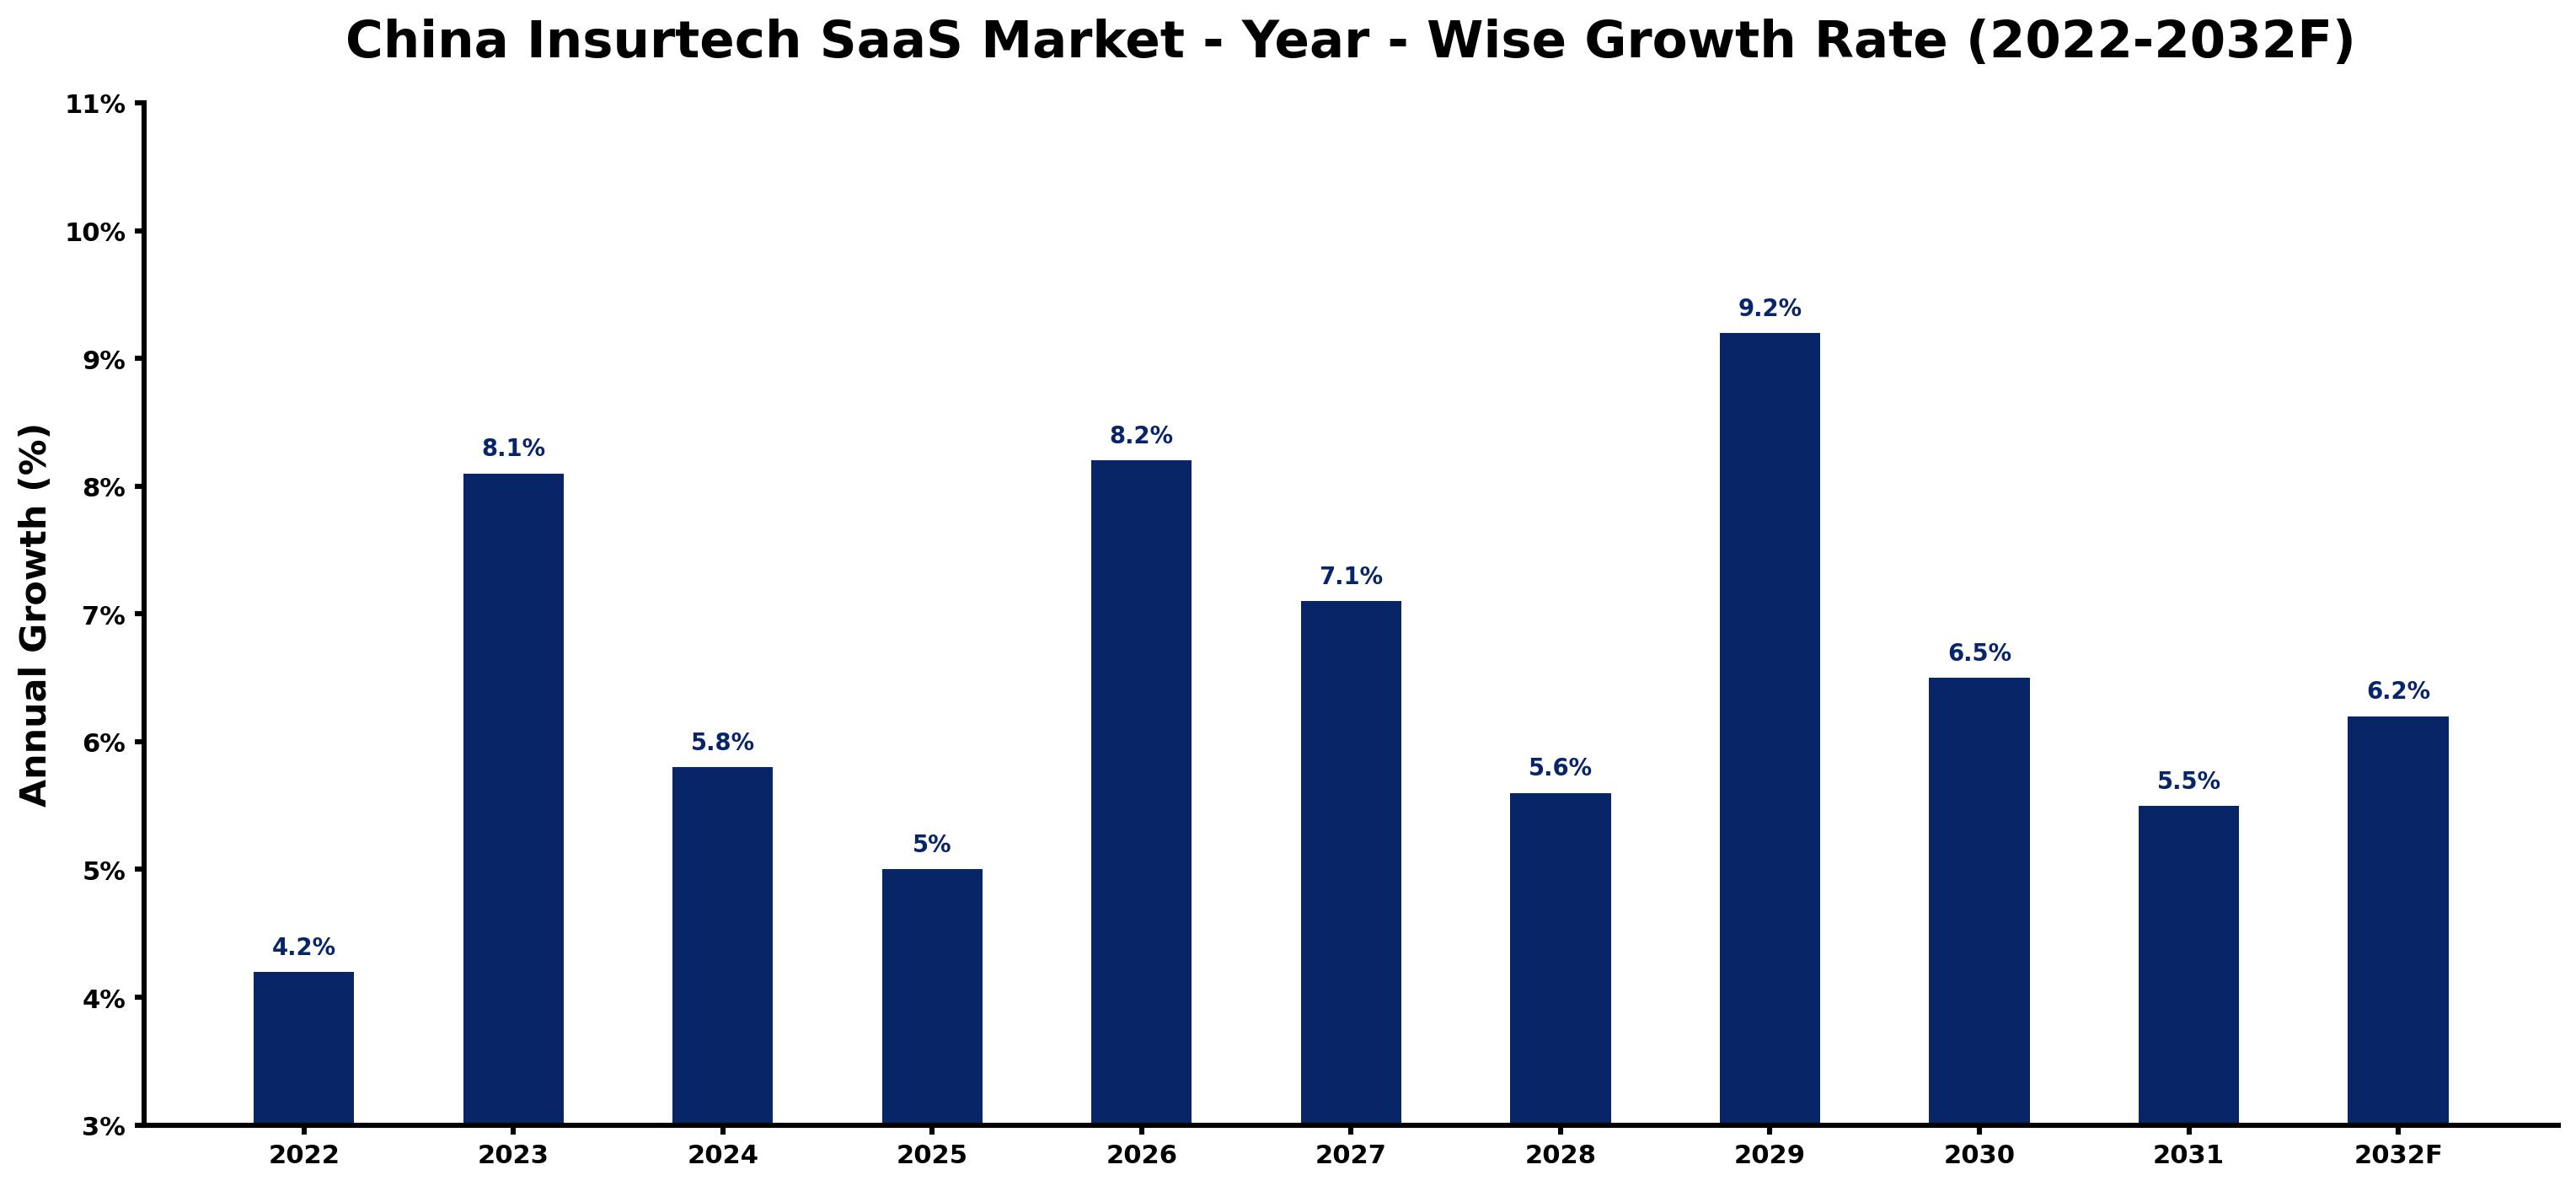
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.2 | The market showed steady activity with insurers beginning to adopt SaaS solutions. |
| 2023 | 8.1 | Growth accelerated as over 70% of insurers invested in digital transformation initiatives. |
| 2024 | 5.8 | A slowdown occurred as the market adjusted to the rapid changes in technology adoption. |
| 2025 | 5.0 | Continued growth was observed as insurers focused on enhancing operational efficiency. |
| 2026 | 8.2 | The market rebounded with increased demand for automated claims processing solutions. |
| 2027 | 7.1 | Growth slowed again as insurers evaluated their technology investments and strategies. |
| 2028 | 5.6 | The market continued to grow, albeit at a slower pace, as competition intensified. |
| 2029 | 9.2 | A peak in growth was reached due to the rising adoption of innovative SaaS solutions. |
| 2030 | 6.5 | The market experienced a slowdown as insurers consolidated their technology platforms. |
| 2031 | 5.5 | Growth continued to decelerate as the market matured and competition increased. |
| 2032 | 6.2 | Demand is expected to rise again as new technologies are integrated into existing systems. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Insurtech SaaS Market Synopsis
Insurtech SaaS in China encompasses software solutions that optimise insurance processes through technology. This includes applications for policy management, claims processing, and customer engagement, all developed with cloud computing and analytics. The China Insurtech SaaS Market is expanding as domestic insurers and brokers increasingly embrace digital solutions. Investments in technology and a strong push for digital transformation are propelling demand. The life insurance sector stands out as the largest consumer, representing 50% of the market.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased investment in digital transformation initiatives among insurers | Driver | High | Insurers |
| Growing demand for automated claims processing solutions | Driver | High | Claims Automation |
| Rising adoption of SaaS solutions among small and medium insurers | Opportunity | Medium | Insurers |
| Expansion of the digital insurance market driven by consumer demand | Opportunity | High | Life & Health Insurance |
| Challenges in integrating new technologies with existing systems | Restraint | High | Claims Automation |
| Limited awareness of insurtech benefits among traditional insurers | Restraint | Medium | Insurers |
| The need for ISO 27001 certification for data security compliance | Challenge | High | SaaS Platforms |
| High competition among insurtech providers leading to pricing pressures | Challenge | Medium | IT Solution Providers |
Evaluation of Drivers in China Insurtech SaaS Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Investment in technology for operational efficiency | Insurers | Over 70% of insurers in China are investing in digital transformation initiatives, enhancing their operational capabilities. |
| Demand for automated claims processing | Claims Automation | In 2022, 40% of insurance claims in China were processed using automated systems, streamlining operations for insurers. |
| Focus on customer experience enhancement | Customer Experience Tools | The average customer satisfaction score for digital insurance services in China is 85%, driving demand for better engagement tools. |
| Cloud-based solutions adoption | Cloud-Based | Cloud-based solutions account for approximately 60% of the insurtech SaaS market in China, providing scalability for insurers. |
| Support from government initiatives | Insurers | The 'Digital Insurance Innovation Initiative' launched in 2023 promotes technology adoption, encouraging insurers to invest in SaaS solutions. |
The Insurtech SaaS market in China is expanding as investment in technology for operational efficiency, demand for automated claims processing, and a focus on improving customer experience drive growth. In 2022, 40% of insurance claims were processed using automated systems, streamlining operations for insurers. The life insurance sector is the largest consumer of insurtech SaaS, accounting for 50% of the market.
Evaluation of Restraints in China Insurtech SaaS Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Integration challenges with existing systems | Claims Automation | Insurers face difficulties in integrating new technology with legacy systems, delaying implementation and increasing costs. |
| Limited awareness of insurtech benefits | Insurers | Many traditional insurers lack awareness of the advantages of insurtech solutions, hindering their adoption. |
| Need for compliance with data security standards | SaaS Platforms | Insurtech providers must obtain ISO 27001 certification, which requires substantial investment and time. |
| High competition leading to pricing pressures | IT Solution Providers | Intense competition among providers forces prices down, affecting profitability and investment in innovation. |
| Slow decision-making processes in traditional insurers | Insurers | Traditional insurers often have lengthy approval processes, delaying the adoption of new technologies. |
China Insurtech SaaS Market Challenges
The China Insurtech SaaS market still has to solve a few problems, and one major issue is intense competition among over 200 insurance companies. This saturation leads to price wars, driving down profit margins for suppliers and forcing them to innovate rapidly. Another challenge is the skills gap; many insurers struggle to find qualified professionals proficient in advanced analytics and cloud computing, which delays digital transformation initiatives for buyers. Buyers also encounter difficulties integrating new technologies with existing systems, resulting in implementation times that can extend up to six months. The rapid pace of technological change pressures providers to continuously upgrade their offerings, which increases operational costs for smaller firms.
Trends in the China Insurtech SaaS Market
Buyers and suppliers in the China Insurtech SaaS Market are adjusting to the following trends.
- Shift towards Automated Claims Processing: In 2022, 40% of insurance claims in China were processed using automated systems, reducing processing times. This trend is prevalent among insurers as they seek efficiency and customer satisfaction.
- Rise of Cloud-Based Solutions: Cloud-based solutions dominate the insurtech SaaS market in China, accounting for approximately 60% of the market. This shift is particularly strong in the Guangdong province, where many startups are emerging.
- Increased Focus on Customer Experience: The average customer satisfaction score for digital insurance services in China is 85% as of 2023. Insurers are prioritising customer experience tools to improve engagement and retention.
- Growing Investment in Digital Transformation: Over 70% of insurers in China are investing in digital transformation initiatives, reflecting a shift in the industry. This investment is expected to drive further adoption of insurtech solutions.
Investment Opportunities in the China Insurtech SaaS Market
The following opportunities in the China Insurtech SaaS Market pair current demand with a clear way in.
- Insurers Seeking Digital Solutions: Insurers are increasingly pursuing digital solutions to enhance operational efficiency, with over 70% investing in technology. This creates opportunities for SaaS providers to deliver tailored solutions.
- Timing for Small and Medium Insurers: As small and medium insurers adopt technology at a rising pace, a market gap has emerged. These insurers are actively seeking partners to bolster their technology capabilities.
- Emerging Hub in Guangdong Province: Guangdong province is evolving into a prominent centre for insurtech startups and innovation. Investing in local partnerships can facilitate entry into this expanding market.
- Growing Demand for Claims Automation: Automation technologies have reduced the average time to process a claim by 30%. This trend presents opportunities for providers of claims automation solutions.
Government Initiatives in the China Insurtech SaaS Market
The 'Digital Insurance Innovation Initiative' launched by the China Banking and Insurance Regulatory Commission in 2023 aims to promote technology adoption in the insurance sector. This initiative builds on the 'Insurance Industry Development Plan (2021-2025)', which encourages digital transformation and innovation. Together, these measures support insurers in integrating advanced technologies into their operations, improving efficiency and customer service. The 'Fintech Development Plan' introduced in 2021 by the Ministry of Industry and Information Technology fosters collaboration between fintech and insurance sectors, enhancing technology use in operations.
The China Banking and Insurance Regulatory Commission oversees the implementation of these initiatives, approving projects that improve digital capabilities. The 'Insurance Technology Innovation Fund', established in 2021 with an initial budget of 500 million CNY, supports startups developing innovative insurtech solutions. This funding is essential for fostering innovation and ensuring that insurers can access the latest technologies. The 'Best Practices in Insurtech' program launched by the China Insurtech Association in 2022 promotes successful case studies and encourages technology adoption among insurers.
Future Insight of the China Insurtech SaaS Market
The China Insurtech SaaS market is set for notable changes by 2032, driven by initiatives like the 'Digital Insurance Innovation Initiative' and the 'Insurance Industry Development Plan (2021-2025)'. Cloud-based solutions will account for around 60% of the market, enhancing efficiency in claims processing. The rise of automated systems will further streamline operations, with 40% of claims processed automatically. Collaboration between fintech and insurance sectors will create new opportunities for both buyers and suppliers, promoting a more integrated and innovative market.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Software Type – Policy Management Dominated, Claims Automation Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, in 2025, Policy Management led the software type split with a 35% share. Policy Management commands the largest share as it is vital for insurers to efficiently manage their policies. This software is particularly important for the over 200 insurance companies in China, ensuring streamlined operations. The quickest growth will come from Claims Automation, forecast to expand at a CAGR of 7.9% between 2026 and 2032. Claims Automation is rapidly growing due to the rising demand for efficient claims processes, with 40% of claims processed using automated systems in 2022. This trend is expected to continue as insurers aim to improve operational efficiency and customer satisfaction. Suppliers should focus on developing advanced claims automation solutions to meet the increasing demand from insurers.
By Deployment Mode – Cloud-Based Dominated, On-Premise Expected to Grow Fastest
Cloud-Based accounted for a 48% market share by deployment mode in 2025. Cloud-Based solutions dominate the market due to their scalability and flexibility, making them the go-to choice for insurers aiming to improve operations. This deployment type accounts for approximately 60% of the insurtech SaaS market in China, reflecting its widespread acceptance among users. On-Premise is projected to grow fastest, at a CAGR of 7.9% during 2026–2032. On-Premise deployment is experiencing rapid growth as traditional insurers focus on data control and security, particularly in light of increasing regulatory scrutiny. This trend indicates a shift towards customised solutions that cater to specific insurer requirements. Buyers should evaluate their deployment strategies to ensure alignment with evolving market trends and regulatory demands.
By Application Area – Life & Health Insurance Dominated, Auto & Property Expected to Grow Fastest
Life & Health Insurance took a 43% share of application area in 2025, more than any other category. Life & Health Insurance commands the largest share as it serves as a primary application area for insurtech solutions, addressing a vast consumer base in China. The strong demand for policy management and claims processing within this sector significantly contributes to its market share. Auto & Property is set to record the highest CAGR in this split, 8.1% over 2026–2032. Auto & Property insurance is the fastest-growing segment, driven by a notable demand for claims automation and policy management solutions. The increasing number of digital insurance policies sold online indicates a shift in consumer preferences towards these digital solutions. Suppliers should consider broadening their offerings to cater to the rising needs of the auto and property insurance sectors.
By End User Type – Insurers Dominated, Brokers Expected to Grow Fastest
With a 43% revenue share in 2025, Insurers was the largest end user type category. Insurers hold the largest market share as the main users of insurtech solutions, seeking operational efficiency in a competitive environment. Their considerable investments in digital transformation initiatives underscore their pivotal role in the market. Over 2026–2032, Brokers are expected to post the fastest growth, at a CAGR of 8.6%. Brokers represent the fastest-growing segment as they increasingly adopt SaaS solutions to manage client interactions and policies more efficiently. The surge in digital insurance adoption among brokers highlights a transition towards technology-driven operations. Suppliers should customise their solutions to address the specific needs of brokers, who are becoming essential players in the insurtech market.
By Distribution Channel – SaaS Platforms Dominated, IT Solution Providers Expected to Grow Fastest
The largest distribution channel category in 2025 was SaaS Platforms, with a 45% share of total revenue. SaaS Platforms lead the distribution channel as they provide the core delivery model for insurtech solutions, allowing insurers to easily access vital software. This model aligns seamlessly with the industry's ongoing digitalisation efforts. The quickest growth will come from IT Solution Providers, forecast to expand at a CAGR of 8.2% between 2026 and 2032. IT Solution Providers are rapidly growing as they facilitate the integration of insurtech solutions into existing systems for insurers. The increasing complexity of technology adoption fuels demand for the expertise offered by these providers. Suppliers should explore partnerships with IT solution providers to enhance their market presence and ensure smoother integrations for their clients.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Insurtech SaaS Market Outlook
- Market Size of China Insurtech SaaS Market, 2025
- Forecast of China Insurtech SaaS Market, 2032
- Historical Data and Forecast of China Insurtech SaaS Revenues & Volume for the Period 2022 - 2032F
- China Insurtech SaaS Market Trend Evolution
- China Insurtech SaaS Market Drivers and Challenges
- China Insurtech SaaS Price Trends
- China Insurtech SaaS Porter's Five Forces
- China Insurtech SaaS Industry Life Cycle
- Historical Data and Forecast of China Insurtech SaaS Market Revenues & Volume By Software Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurtech SaaS Market Revenues & Volume By Policy Management for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurtech SaaS Market Revenues & Volume By Claims Automation for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurtech SaaS Market Revenues & Volume By Risk & Fraud Analytics for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurtech SaaS Market Revenues & Volume By Customer Experience Tools for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurtech SaaS Market Revenues & Volume By Deployment Mode for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurtech SaaS Market Revenues & Volume By Cloud-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurtech SaaS Market Revenues & Volume By On-Premise for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurtech SaaS Market Revenues & Volume By Hybrid for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurtech SaaS Market Revenues & Volume By Web-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurtech SaaS Market Revenues & Volume By Application Area for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurtech SaaS Market Revenues & Volume By Life & Health Insurance for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurtech SaaS Market Revenues & Volume By Auto & Property for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurtech SaaS Market Revenues & Volume By General Insurance for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurtech SaaS Market Revenues & Volume By Omnichannel Support for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurtech SaaS Market Revenues & Volume By End User Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurtech SaaS Market Revenues & Volume By Insurers for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurtech SaaS Market Revenues & Volume By Brokers for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurtech SaaS Market Revenues & Volume By TPAs for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurtech SaaS Market Revenues & Volume By Agents/Agencies for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurtech SaaS Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurtech SaaS Market Revenues & Volume By SaaS Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurtech SaaS Market Revenues & Volume By IT Solution Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurtech SaaS Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China Insurtech SaaS Market Revenues & Volume By Digital Marketplaces for the Period 2022 - 2032F
- China Insurtech SaaS Import Export Trade Statistics
- Market Opportunity Assessment By Software Type
- Market Opportunity Assessment By Deployment Mode
- Market Opportunity Assessment By Application Area
- Market Opportunity Assessment By End User Type
- Market Opportunity Assessment By Distribution Channel
- China Insurtech SaaS Top Companies Market Share
- China Insurtech SaaS Competitive Benchmarking By Technical and Operational Parameters
- China Insurtech SaaS Company Profiles
- China Insurtech SaaS Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Software Type
- Policy Management
- Claims Automation
- Risk & Fraud Analytics
- Customer Experience Tools
By Deployment Mode
- Cloud-Based
- On-Premise
- Hybrid
- Web-Based
By Application Area
- Life & Health Insurance
- Auto & Property
- General Insurance
- Omnichannel Support
By End User Type
- Insurers
- Brokers
- TPAs
- Agents/Agencies
By Distribution Channel
- SaaS Platforms
- IT Solution Providers
- Direct Sales
- Digital Marketplaces































