China Integrated Avionics Safety System Market Size & Growth Rate
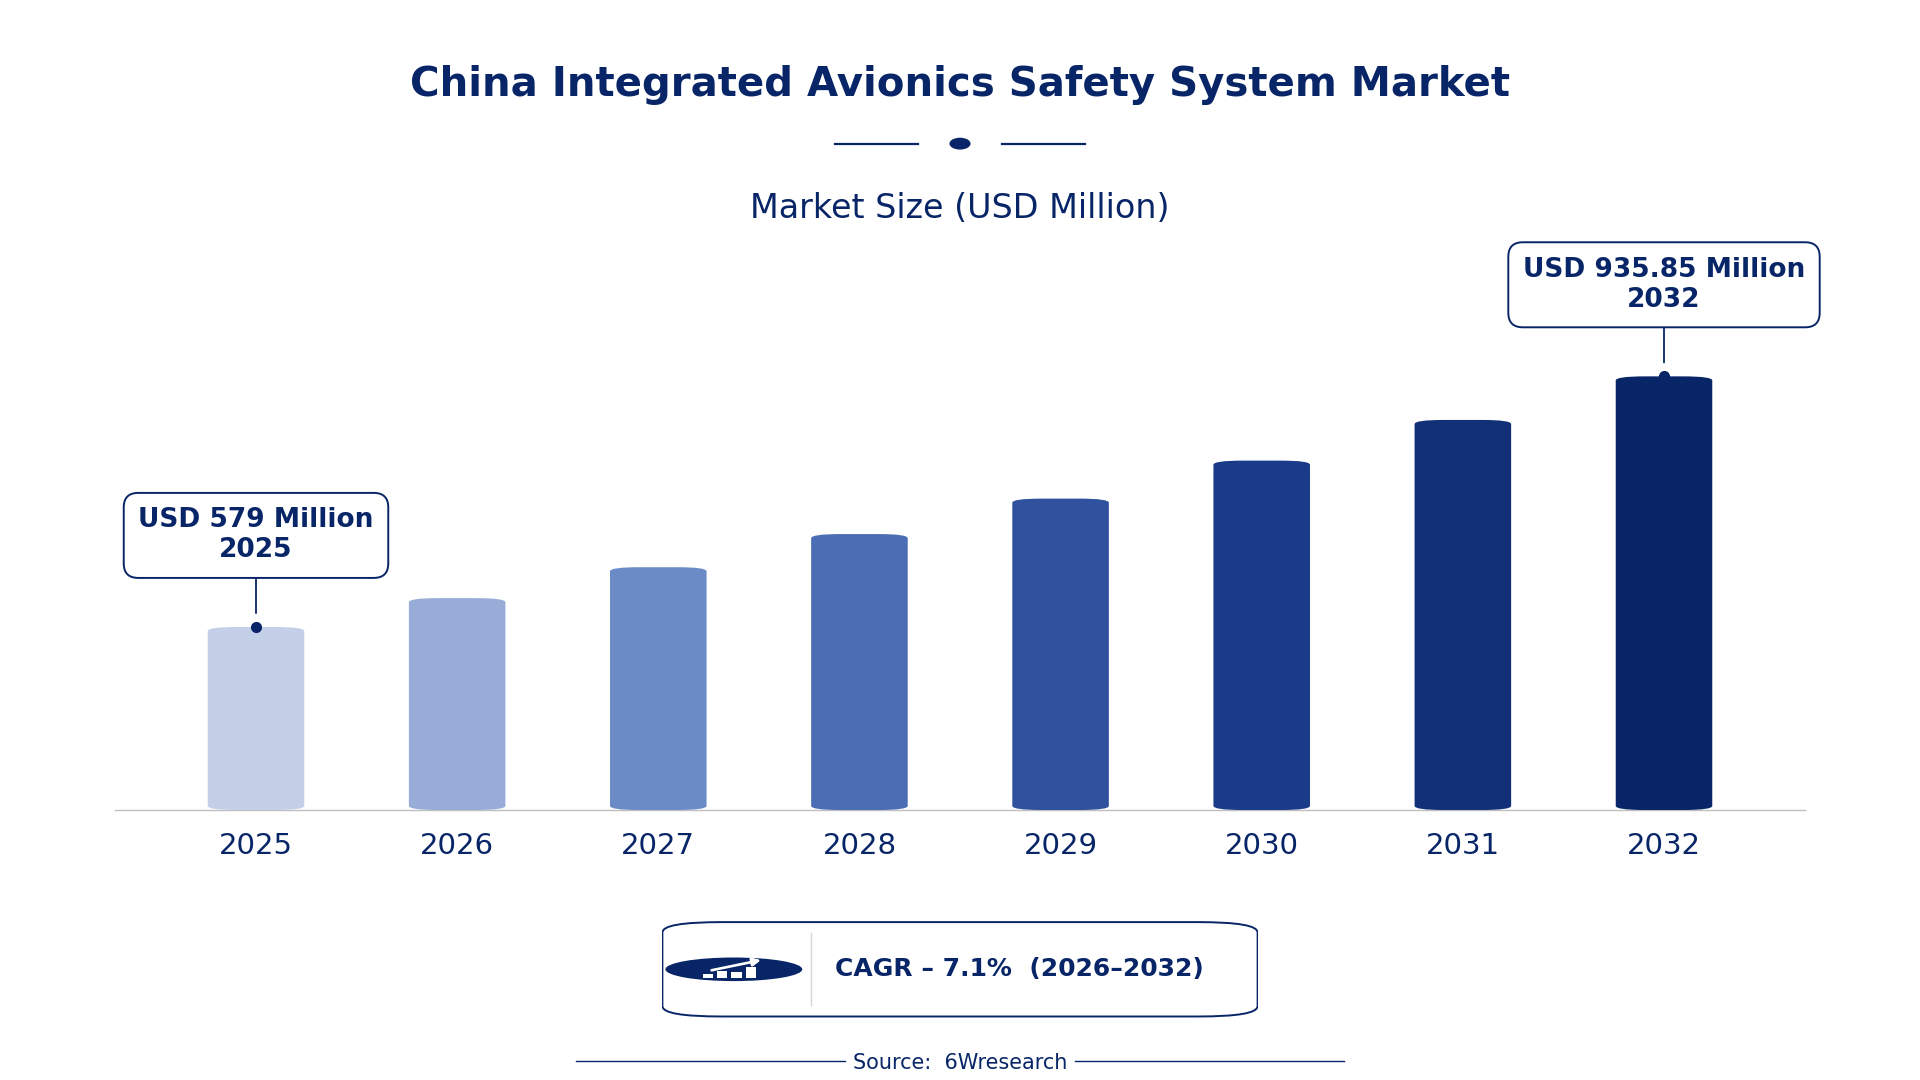
According to 6Wresearch internal database and industry insights, the China Integrated Avionics Safety System Market was valued at USD 579.0 million in 2025 and is projected to reach USD 935.85 million by 2032, growing at a CAGR of approximately 7.1% during 2026–2032.
China Integrated Avionics Safety System Market Highlights
| Report Metric | Details |
| Report Name | China Integrated Avionics Safety System Market |
| Market Size 2025 | USD 579.0 million |
| Market Size 2032 | USD 935.85 million |
| Absolute Growth 2025–2032 | USD 356.85 million |
| CAGR 2026–2032 | 7.1% |
| Peak Annual Growth | 9.1% in 2027 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Safety Feature, 2025 | Redundant Flight Data (42% share) |
| Leading System Type, 2025 | Triplex Systems (38% share) |
| Leading Aircraft Type, 2025 | Passenger Jets (43% share) |
| Leading Certification Level, 2025 | DO-178C (40% share) |
| Leading End User, 2025 | Avionics Integrators (41% share) |
| Fastest-Growing Safety Feature | Crash Avoidance (9.6% CAGR) |
| Fastest-Growing System Type | Ground Proximity Warning (9.7% CAGR) |
| Fastest-Growing Aircraft Type | Military Aircraft (8.3% CAGR) |
| Fastest-Growing Certification Level | MIL-STD Compliant (9.5% CAGR) |
| Fastest-Growing End User | Defense Procurement (8.3% CAGR) |
| Growing Sector | Military Aircraft |
| Key End Users | Avionics Integrators, Aircraft OEMs, Defense Procurement, Drone Manufacturers |
China Integrated Avionics Safety System Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
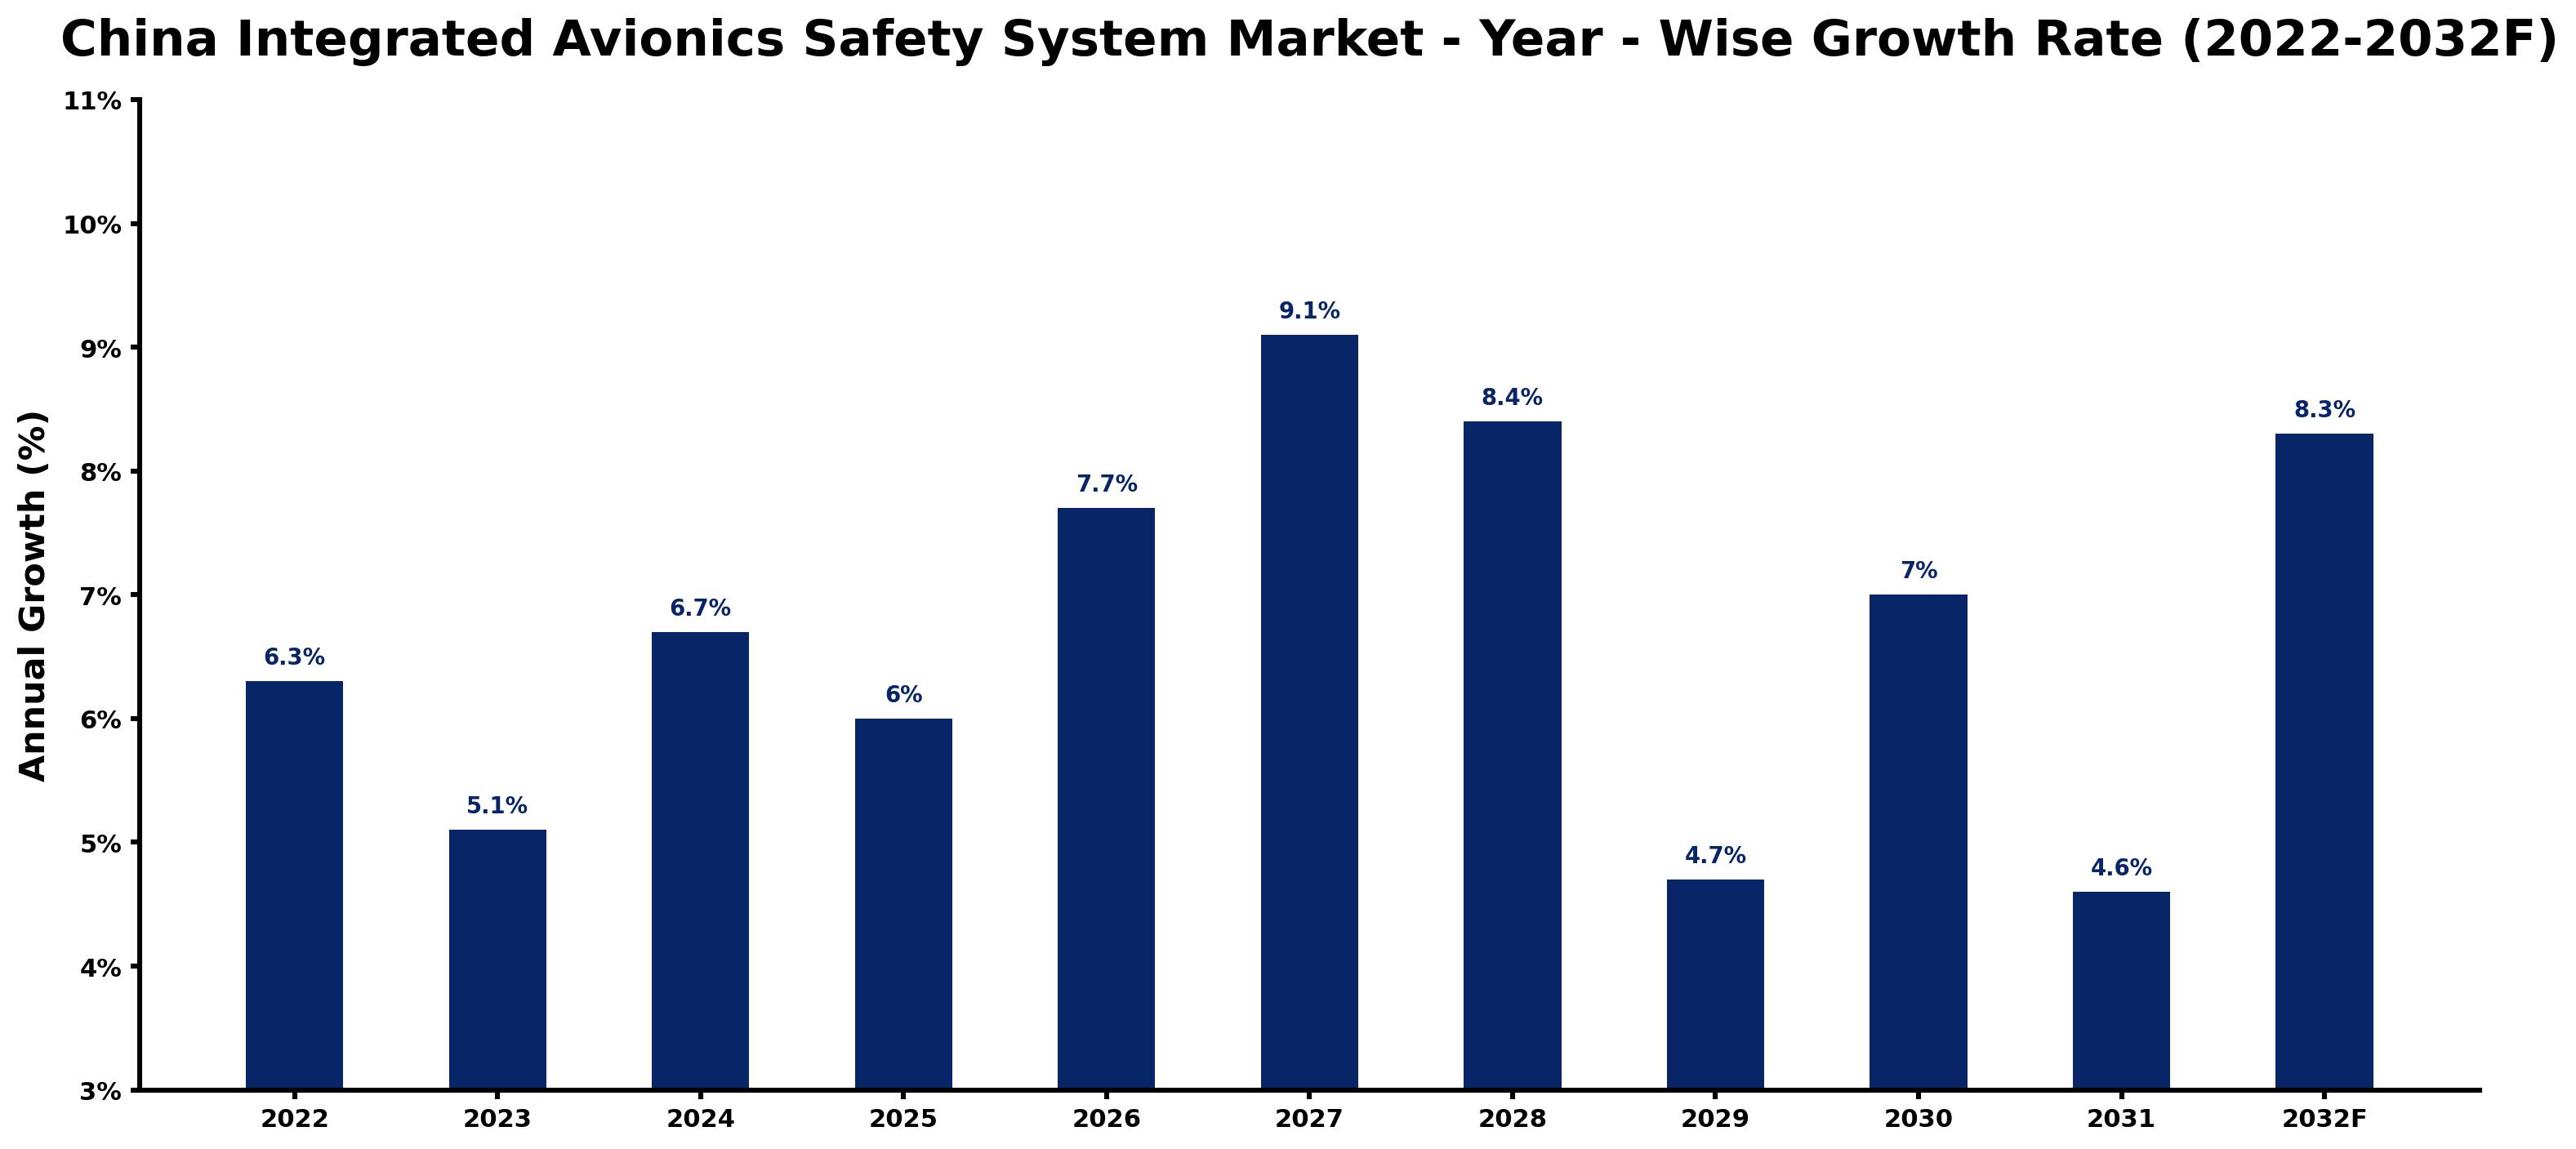
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.3 | The market experienced steady growth driven by increased production of commercial aircraft. |
| 2023 | 5.1 | Demand growth slowed as the aviation sector faced supply chain disruptions. |
| 2024 | 6.7 | A recovery in production rates boosted growth as manufacturers ramped up output. |
| 2025 | 6.0 | The market saw a slowdown as manufacturers adjusted to new safety standards. |
| 2026 | 7.7 | Increased military budget allocations for aviation technology is expected to spur demand. |
| 2027 | 9.1 | The market peaked with heightened defense procurement and modernization efforts. |
| 2028 | 8.4 | Growth is projected to slow as the market adjusts to peak demand levels. |
| 2029 | 4.7 | Demand is expected to continue slowing as the market stabilises after rapid growth. |
| 2030 | 7.0 | A resurgence in passenger traffic will contribute to renewed demand for advanced avionics systems. |
| 2031 | 4.6 | The market growth rate is projected to slow as demand stabilises in the aviation sector. |
| 2032 | 8.3 | Demand is projected to rise again as more aircraft are equipped with advanced avionics systems. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Integrated Avionics Safety System Market Synopsis
Integrated Avionics Safety System in China includes advanced solutions that improve aircraft safety and reliability. These systems undergo thorough testing and comply with international standards, primarily aimed at enhancing flight safety and preventing accidents. The China Integrated Avionics Safety System Market is expanding due to a rise in domestic aircraft production and military procurement. By 2030, the aviation market is set to accommodate 1.5 billion passengers, which will drive demand for advanced avionics. The adoption of the DO-178C standard for avionics software safety is also propelling market growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased military budget allocations for aviation technology | Driver | High | Military Aircraft |
| Growing demand for safety features in commercial aviation | Driver | High | Passenger Jets |
| Investment in UAV safety systems due to rising drone usage | Opportunity | High | UAVs |
| Expansion of aviation manufacturing hubs in the Beijing-Tianjin-Hebei region | Opportunity | Medium | Commercial Aircraft |
| High costs associated with implementing advanced avionics systems | Restraint | High | Redundant Flight Data |
| Regulatory compliance challenges for new entrants in the market | Restraint | Medium | Redundant Flight Data |
| Talent shortages in avionics engineering and development | Challenge | High | Redundant Flight Data |
| Competition from international avionics suppliers | Challenge | Medium | Redundant Flight Data |
Evaluation of Drivers in China Integrated Avionics Safety System Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased military budget allocations for aviation technology | Military Aircraft | The military budget for aviation technology in 2023 is approximately $200 billion, driving demand for advanced avionics. |
| Growing demand for safety features in commercial aviation | Passenger Jets | China produced 1,000 commercial aircraft in 2022, increasing the need for integrated safety systems. |
| Expansion of UAV applications in various sectors | UAVs | The UAV market in China is expected to grow by 15% annually through 2025, boosting demand for safety systems. |
| Implementation of DO-178C standard for avionics safety | DO-178C | The DO-178C standard, implemented since 2021, enhances software safety and reliability in avionics systems. |
| Growth in passenger traffic and airport expansions | Commercial Aircraft | China's aviation market is projected to reach 1.5 billion passengers by 2030, increasing the demand for advanced avionics. |
The Integrated Avionics Safety System market in China is growing on the back of increased military budget allocations, rising interest in safety features for commercial aviation, and the expansion of UAV applications. The military budget for aviation technology in 2023 is approximately $200 billion, which drives demand for advanced avionics in military aircraft. In 2022, China produced 1,000 commercial aircraft, increasing the need for integrated safety systems in passenger jets. The UAV market in China is expected to grow by 15% annually through 2025, boosting the demand for safety systems. The implementation of the DO-178C standard since 2021 improves software safety and reliability in avionics systems.
Evaluation of Restraints in China Integrated Avionics Safety System Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs associated with implementing advanced avionics systems | Redundant Flight Data | The investment required for advanced avionics systems can be prohibitive for smaller manufacturers. |
| Regulatory compliance challenges for new entrants in the market | Redundant Flight Data | Navigating complex regulations can delay market entry for new avionics suppliers. |
| Limited availability of skilled workforce in avionics engineering | Redundant Flight Data | The shortage of qualified engineers can hinder the development and implementation of new systems. |
| Dependence on international suppliers for certain components | Redundant Flight Data | A leading supplier on foreign suppliers can create vulnerabilities in the supply chain. |
| Stringent certification processes for new technologies | Redundant Flight Data | The lengthy certification process can delay the introduction of new avionics solutions. |
China Integrated Avionics Safety System Market Challenges
The China Integrated Avionics Safety System market still has to solve a few problems, starting with buyers facing high costs due to strict compliance with the DO-178C standard, which can increase system prices by up to 30%. Suppliers struggle with sourcing advanced components, as the local supply chain lacks maturity, causing delays in production timelines for manufacturers. A shortage of skilled avionics engineers exists, with over 100,000 professionals needed to meet industry demands, impacting project completion rates for producers. Competition from foreign suppliers remains intense, as they often provide more advanced technologies, making it challenging for domestic manufacturers to secure contracts.
Trends in the China Integrated Avionics Safety System Market
The trends below show where the China Integrated Avionics Safety System Market is heading.
- Shift towards Improved Safety Protocols: The implementation of the DO-178C standard since 2021 has resulted in better safety protocols in avionics systems, ensuring greater reliability. This standard is anticipated to influence 40% of certification levels by 2025.
- Transition from Traditional to Advanced Systems: The aviation industry is moving from traditional avionics systems to advanced integrated solutions. This transition is highlighted by the military's modernisation programme, which includes upgrading avionics systems through 2025.
- Emergence of UAV Safety Systems: The UAV market is increasingly prioritising safety systems, with a projected growth of 15% annually through 2025. This trend reflects the rising demand for drone applications across various sectors.
- Focus on Passenger Safety Improvements: With the aviation market expected to reach 1.5 billion passengers by 2030, there is a growing focus on enhancing passenger safety through advanced avionics systems.
Investment Opportunities in the China Integrated Avionics Safety System Market
Several openings in the China Integrated Avionics Safety System Market merit attention from investors.
- Establish Partnerships with Local Manufacturers: Now is the time to form joint ventures with local manufacturers in the Beijing-Tianjin-Hebei region, where aviation technology is rapidly advancing. This area has seen substantial investment, making it an attractive opportunity.
- Supply of Advanced Safety Systems: With the military budget for aviation technology at approximately $200 billion, there is a pressing need for advanced safety systems. Suppliers can target military aircraft manufacturers to meet this demand.
- Investment in UAV Safety Solutions: The UAV market's projected growth of 15% annually through 2025 presents an opportunity to supply safety systems. Targeting drone manufacturers will be essential for capturing this market.
- Certification Support Services: As the DO-178C standard becomes more prevalent, offering certification support services will be important. Avionics integrators are key buyers who will require assistance in meeting compliance.
Government Initiatives in the China Integrated Avionics Safety System Market
The Civil Aviation Administration of China (CAAC) has established regulations for UAVs since 2021, ensuring that UAV manufacturers adhere to strict safety standards, which is critical for the growing drone market. Additionally, the National Development and Reform Commission (NDRC) supports aviation technology advancements through various initiatives aimed at fostering innovation and improving safety standards in the industry. This includes funding for research and development projects that enhance safety protocols.
The Ministry of Industry and Information Technology (MIIT) plays a vital role in approving new avionics technologies and funding research and development projects. This agency has been instrumental in promoting innovation in avionics systems, ensuring that manufacturers can access the necessary resources to develop advanced safety solutions. Furthermore, the CAAC oversees the certification of avionics systems, ensuring compliance with safety regulations.
Future Insight of the China Integrated Avionics Safety System Market
The China Integrated Avionics Safety System market is set to evolve significantly by 2032, driven by technological advancements and regulatory support. The military budget for aviation technology is projected to be around $200 billion in 2023, facilitating upgrades in avionics systems. The National Development and Reform Commission will continue to promote innovation, ensuring domestic suppliers can compete effectively. As the aviation market aims to equip 20% of its fleet with advanced avionics by 2025, opportunities for integrated systems will grow, benefiting both buyers and suppliers.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Safety Feature – Redundant Flight Data Dominated, Crash Avoidance Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, Redundant Flight Data accounted for a 42% market share by safety feature in 2025. Redundant Flight Data captures the largest share due to its critical role in safety monitoring for aircraft operations. This feature is essential for compliance with the Civil Aviation Administration of China's stringent safety regulations, ensuring dependable performance across the aviation sector. Over 2026–2032, Crash Avoidance is expected to post the fastest growth, at a CAGR of 9.6%. Crash Avoidance is witnessing rapid growth as it addresses the pressing need for accident prevention in aviation. With China's aviation market projected to reach 1.5 billion passengers by 2030, the demand for this technology will continue to surge. Suppliers should prioritise the development of Crash Avoidance technologies to align with the increasing safety expectations in the aviation market.
By System Type – Triplex Systems Dominated, Ground Proximity Warning Expected to Grow Fastest
In 2025, Triplex Systems led the system type split with a 38% share. Triplex Systems lead the market share as they offer exceptional reliability through redundancy, which is vital for maintaining aircraft safety. Their extensive adoption in commercial aviation is driven by the rising production of aircraft in China. The quickest growth will come from Ground Proximity Warning, forecast to expand at a CAGR of 9.7% between 2026 and 2032. Ground Proximity Warning systems are gaining momentum due to the critical need to alert pilots about terrain risks, particularly in busy airspace. As new airports are built, the demand for these systems will expand significantly. Suppliers must focus on enhancing Ground Proximity Warning systems to leverage the growing aviation infrastructure.
By Aircraft Type – Passenger Jets Dominated, Military Aircraft Expected to Grow Fastest
Passenger Jets took a 43% share of aircraft type in 2025, more than any other category. Passenger Jets represent the largest share in the market as they are the primary application in commercial aviation, constituting a significant portion of integrated avionics systems. The presence of over 500 airports in China generates substantial demand for these systems. Military Aircraft is projected to grow fastest, at a CAGR of 8.3% during 2026–2032. Military Aircraft are experiencing the fastest growth due to ongoing modernisation efforts within China's defence sector, which prioritises advanced avionics systems. The military's aviation technology budget is projected at $200 billion in 2023, fuelling this demand. Suppliers should align their offerings to meet the increasing needs of Military Aircraft to capitalise on opportunities in the defence sector.
By Certification Level – DO-178C Dominated, MIL-STD Compliant Expected to Grow Fastest
DO-178C held a 40% share of the China Integrated Avionics Safety System Market by certification level in 2025. DO-178C certification dominates the market as it is the recognised standard for software safety in avionics systems, ensuring compliance with national regulations. This certification is crucial for avionics integrators committed to maintaining safety and reliability in their systems. MIL-STD Compliant is set to record the highest CAGR in this split, 9.5% over 2026–2032. MIL-STD Compliant systems are rapidly increasing in market share as they ensure military-grade reliability, which is essential for defence applications. The emphasis on advancements in military technology further accelerates this growth trajectory. Suppliers must ensure their products achieve MIL-STD compliance to attract government contracts and strengthen their market position.
By End User – Avionics Integrators Dominated, Defense Procurement Expected to Grow Fastest
The largest end user category in 2025 was Avionics Integrators, with a 41% share of total revenue. Avionics Integrators hold the largest share as they are pivotal in implementing integrated avionics systems across various aircraft types. Their expertise is vital for adhering to the stringent standards set by regulatory authorities in the aviation industry. Over 2026–2032, Defense Procurement is expected to post the fastest growth, at a CAGR of 8.3%. Defense Procurement is the fastest growing segment, driven by government contracts that favour domestic avionics suppliers. The military's commitment to upgrading avionics systems will continue to propel this demand forward. Suppliers should cultivate strong relationships with defense procurement entities to secure contracts and enhance their market presence.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Integrated Avionics Safety System Market Outlook
- Market Size of China Integrated Avionics Safety System Market, 2025
- Forecast of China Integrated Avionics Safety System Market, 2032
- Historical Data and Forecast of China Integrated Avionics Safety System Revenues & Volume for the Period 2022 - 2032F
- China Integrated Avionics Safety System Market Trend Evolution
- China Integrated Avionics Safety System Market Drivers and Challenges
- China Integrated Avionics Safety System Price Trends
- China Integrated Avionics Safety System Porter's Five Forces
- China Integrated Avionics Safety System Industry Life Cycle
- Historical Data and Forecast of China Integrated Avionics Safety System Market Revenues & Volume By Safety Feature for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Avionics Safety System Market Revenues & Volume By Redundant Flight Data for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Avionics Safety System Market Revenues & Volume By Crash Avoidance for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Avionics Safety System Market Revenues & Volume By Flight Envelope Protection for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Avionics Safety System Market Revenues & Volume By Emergency Autopilot for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Avionics Safety System Market Revenues & Volume By System Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Avionics Safety System Market Revenues & Volume By Triplex Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Avionics Safety System Market Revenues & Volume By Ground Proximity Warning for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Avionics Safety System Market Revenues & Volume By Auto Stabilization for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Avionics Safety System Market Revenues & Volume By Autonomous Recovery for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Avionics Safety System Market Revenues & Volume By Aircraft Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Avionics Safety System Market Revenues & Volume By Passenger Jets for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Avionics Safety System Market Revenues & Volume By Military Aircraft for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Avionics Safety System Market Revenues & Volume By Commercial Aircraft for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Avionics Safety System Market Revenues & Volume By UAVs for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Avionics Safety System Market Revenues & Volume By Certification Level for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Avionics Safety System Market Revenues & Volume By DO-178C for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Avionics Safety System Market Revenues & Volume By MIL-STD Compliant for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Avionics Safety System Market Revenues & Volume By FAA Approved for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Avionics Safety System Market Revenues & Volume By COTS for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Avionics Safety System Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Avionics Safety System Market Revenues & Volume By Avionics Integrators for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Avionics Safety System Market Revenues & Volume By Defense Procurement for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Avionics Safety System Market Revenues & Volume By Aircraft OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Avionics Safety System Market Revenues & Volume By Drone Manufacturers for the Period 2022 - 2032F
- China Integrated Avionics Safety System Import Export Trade Statistics
- Market Opportunity Assessment By Safety Feature
- Market Opportunity Assessment By System Type
- Market Opportunity Assessment By Aircraft Type
- Market Opportunity Assessment By Certification Level
- Market Opportunity Assessment By End User
- China Integrated Avionics Safety System Top Companies Market Share
- China Integrated Avionics Safety System Competitive Benchmarking By Technical and Operational Parameters
- China Integrated Avionics Safety System Company Profiles
- China Integrated Avionics Safety System Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Safety Feature
- Redundant Flight Data
- Crash Avoidance
- Flight Envelope Protection
- Emergency Autopilot
By System Type
- Triplex Systems
- Ground Proximity Warning
- Auto Stabilization
- Autonomous Recovery
By Aircraft Type
- Passenger Jets
- Military Aircraft
- Commercial Aircraft
- UAVs
By Certification Level
- DO-178C
- MIL-STD Compliant
- FAA Approved
- COTS
By End User
- Avionics Integrators
- Defense Procurement
- Aircraft OEMs
- Drone Manufacturers































