China Integrated Circuit Automotive Application Market Size & Growth Rate
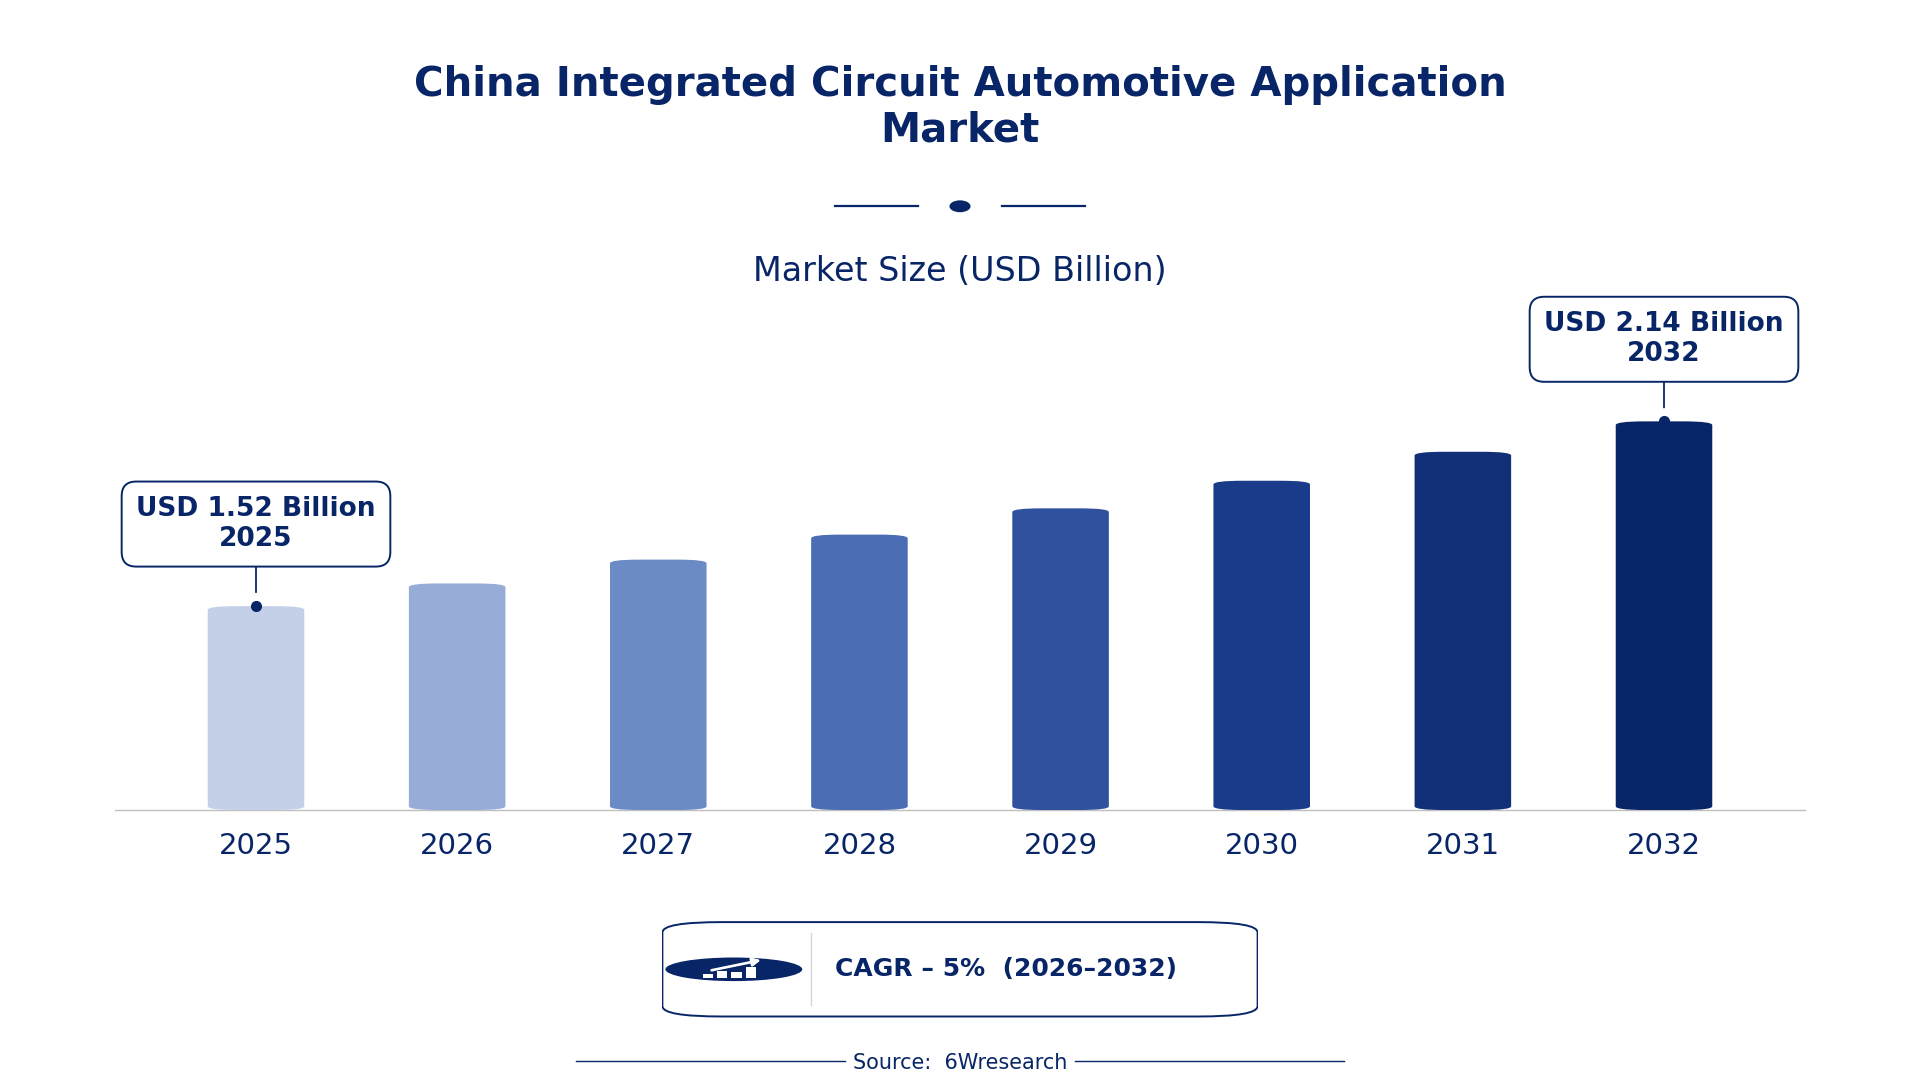
According to 6Wresearch internal database and industry insights, the China Integrated Circuit Automotive Application Market was valued at USD 1.52 billion in 2025 and is projected to reach USD 2.14 billion by 2032, growing at a CAGR of approximately 5% during 2026–2032.
China Integrated Circuit Automotive Application Market Highlights
| Report Metric | Details |
| Report Name | China Integrated Circuit Automotive Application Market |
| Market Size 2025 | USD 1.52 billion |
| Market Size 2032 | USD 2.14 billion |
| Absolute Growth 2025–2032 | USD 0.62 billion |
| CAGR 2026–2032 | 5% |
| Peak Annual Growth | 7.2% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading IC Type, 2025 | Power Management ICs (43% share) |
| Leading Application Area, 2025 | ADAS (45% share) |
| Leading Vehicle Type, 2025 | Electric Vehicles (43% share) |
| Leading Distribution Channel, 2025 | Tier-1 Suppliers (41% share) |
| Leading End User, 2025 | Automotive OEMs (43% share) |
| Fastest-Growing IC Type | Sensor ICs (7.1% CAGR) |
| Fastest-Growing Vehicle Type | Passenger Cars (7.3% CAGR) |
| Fastest-Growing Distribution Channel | Distributors (6.6% CAGR) |
| Fastest-Growing End User | ECU Manufacturers (6.4% CAGR) |
| Growing Sector | Electric Vehicles |
| Key End Users | Automotive OEMs, ECU Manufacturers, Tier-1 Suppliers |
China Integrated Circuit Automotive Application Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
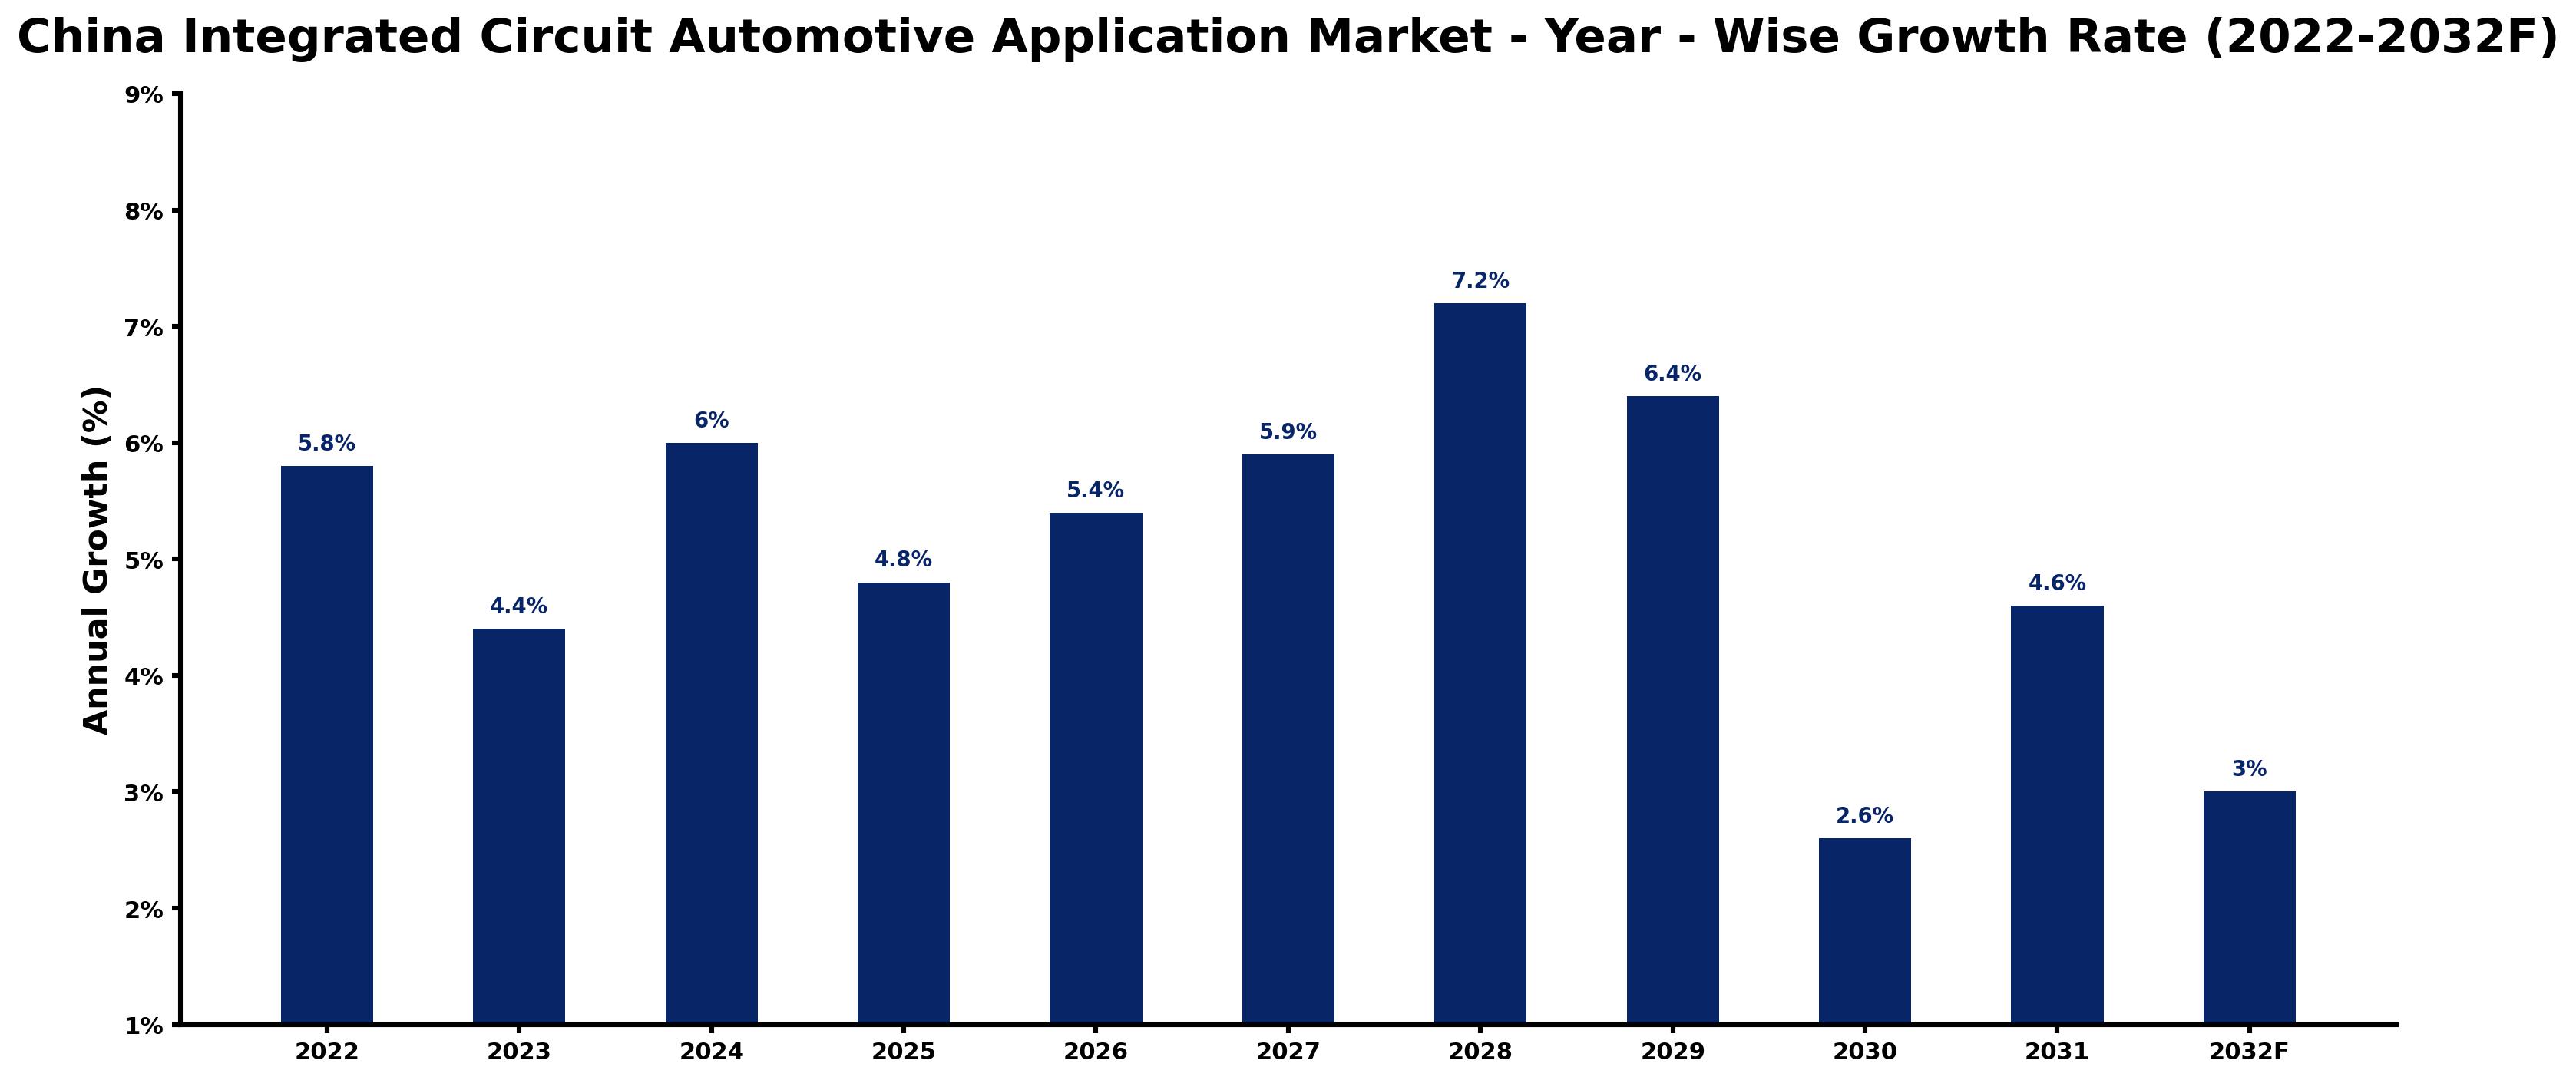
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.8 | The market experienced solid demand due to increased sales of electric vehicles. |
| 2023 | 4.4 | Growth slowed as supply chain issues affected semiconductor availability in the automotive sector. |
| 2024 | 6.0 | Demand surged as the automotive industry recovered and electric vehicle sales increased. |
| 2025 | 4.8 | Growth slowed again as market adjustments took place following rapid expansion in previous years. |
| 2026 | 5.4 | Investment in smart vehicle technologies will drive demand for integrated circuits. |
| 2027 | 5.9 | Rising production of electric vehicles will continue to support market growth in this segment. |
| 2028 | 7.2 | The peak growth rate is anticipated as new automotive technologies gain traction. |
| 2029 | 6.4 | Demand is expected to stabilise as the market adjusts to peak levels. |
| 2030 | 2.6 | A further slowdown is anticipated as market saturation begins to impact growth rates. |
| 2031 | 4.6 | Demand is projected to rise again as new innovations in automotive technology are introduced. |
| 2032 | 3.0 | Growth is expected to continue but at a slower pace as the market matures. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Integrated Circuit Automotive Application Market Synopsis
The Integrated Circuit Automotive Application in China encompasses semiconductor devices that are crucial for automotive systems. These circuits are integral to power management, sensor integration, and communication within vehicles. The China Integrated Circuit Automotive Application Market is expanding due to increasing domestic demand for electric and smart vehicles, along with substantial investments in automotive technologies. In 2022, 3.5 million electric vehicles were sold, underscoring the growing market potential. The Guangdong province stands out as a key hub for automotive electronics production, further stimulating demand.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising investment in electric vehicle production drives demand for integrated circuits. | Driver | High | Power Management ICs |
| The increasing number of registered passenger cars boosts the need for automotive ICs. | Driver | High | Microcontrollers |
| The shift towards electric vehicles creates opportunities for suppliers of battery management ICs. | Opportunity | High | Battery Management |
| The growing focus on advanced driver-assistance systems (ADAS) offers significant market potential. | Opportunity | High | ADAS |
| Supply chain disruptions have led to delays in semiconductor availability. | Restraint | High | Sensor ICs |
| The high cost of advanced semiconductor manufacturing limits new entrants into the market. | Restraint | Medium | Communication ICs |
| The Integrated Circuit Automotive Application Market in China faces challenges from fluctuating demand. | Challenge | High | Electric Vehicles |
| Competition from international semiconductor manufacturers poses challenges for local producers. | Challenge | Medium | Tier-1 Suppliers |
Evaluation of Drivers in China Integrated Circuit Automotive Application Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased sales of electric vehicles drive demand for power management ICs. | Power Management ICs | In 2022, 3.5 million electric vehicles were sold, leading to higher demand for energy management solutions. |
| Growing automotive production increases the need for microcontrollers. | Microcontrollers | China has over 30 million registered passenger cars as of 2023, creating a larger market for vehicle control systems. |
| Investment in smart vehicle technologies enhances the market for battery management ICs. | Battery Management | The National Development and Reform Commission approved 50 new EV projects in 2023, boosting demand for battery management solutions. |
| The push for ADAS systems expands the market for sensor ICs. | Sensor ICs | The automotive electronics market in China is expected to grow by 15% annually until 2025, driven by demand for advanced safety features. |
| The rise in electric vehicle sales increases the need for communication ICs. | Communication ICs | The Smart Vehicle Innovation Development Strategy launched in 2021 supports the integration of communication technologies in vehicles. |
Market growth in China for Integrated Circuit Automotive Application hinges on rising investment in electric vehicle production, increased automotive manufacturing, and the drive for advanced driver-assistance systems. In 2022, 3.5 million electric vehicles were sold, boosting demand for energy management solutions. The automotive sector boasts over 30 million registered passenger cars, creating a robust market for vehicle control systems. The approval of new EV projects intensifies the need for battery management ICs. The automotive electronics market is projected to grow by 15% annually until 2025, reflecting the demand for advanced safety features in vehicles.
Evaluation of Restraints in China Integrated Circuit Automotive Application Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions limit the availability of semiconductor components. | Sensor ICs | These disruptions have resulted in delayed deliveries, impacting production timelines for automotive manufacturers by causing delays of up to 3 months. |
| High manufacturing costs restrict local producers' competitiveness against international firms. | Communication ICs | This situation leads to increased prices for buyers, affecting their procurement strategies by up to 15%. |
| Fluctuating demand from the automotive sector creates uncertainty for producers. | Electric Vehicles | This unpredictability can lead to overproduction or shortages, complicating inventory management and potentially resulting in a 20% increase in costs. |
| Regulatory compliance requirements can delay product launches. | ADAS | Manufacturers must ensure adherence to national standards, which can extend development timelines by several months. |
| Limited access to advanced manufacturing technologies hampers local production capabilities. | Microcontrollers | This limitation affects the ability to scale production effectively, impacting supply and potentially leading to a 10% reduction in output. |
China Integrated Circuit Automotive Application Market Challenges
The China Integrated Circuit Automotive Application Market encounters several practical issues, with supply chain disruptions being a primary concern. These interruptions can delay production timelines for manufacturers, leading to increased costs of up to 20% for automotive ICs. A shortage of skilled engineers in the automotive electronics sector also slows progress, hindering innovation and affecting buyers who depend on timely advancements. Compliance with the national standard GB/T 34590 presents another hurdle; extensive testing can prolong product launch timelines by several months, frustrating buyers eager for new technologies. Lastly, price fluctuations due to volatile market conditions complicate budgeting and forecasting for buyers, making financial planning more challenging.
Trends in the China Integrated Circuit Automotive Application Market
Four trends stand out in the China Integrated Circuit Automotive Application Market.
- Shift towards Electric Vehicles: In 2022, electric vehicle sales in China reached 3.5 million units, reflecting a shift in consumer preference. This trend is likely to continue as the market adapts to new technologies and standards.
- Transition to Advanced Driver-Assistance Systems: The push for enhanced vehicle safety features has led to increased adoption of ADAS technologies. By 2025, ADAS is expected to account for 45% of the automotive IC market, reflecting consumer demand for safer vehicles.
- Emergence of Battery Management Systems: The growing electric vehicle market has catalysed the development of sophisticated battery management systems. In 2023, the approval of numerous new EV projects will further support this trend.
- Focus on Sustainable Automotive Practices: The Automotive Industry Green Development Action Plan initiated in 2023 promotes sustainable practices in automotive manufacturing. This plan aims to reduce emissions and improve environmental standards across the industry.
Investment Opportunities in the China Integrated Circuit Automotive Application Market
Several openings in the China Integrated Circuit Automotive Application Market merit attention from investors.
- Timing for Investment in Battery Management: With the increasing sales of electric vehicles, there is a prime opportunity to invest in battery management ICs. The approval of numerous new EV projects in 2023 highlights this potential.
- Demand from Automotive OEMs: Automotive OEMs are actively seeking advanced integrated circuits to improve vehicle performance and safety. The anticipated growth of the automotive electronics market by 15% annually until 2025 presents a promising opportunity for suppliers.
- Entry into the ADAS Market: Companies can enter the ADAS market by forming joint ventures with local manufacturers. This strategy allows for shared expertise and access to the growing demand for advanced safety features.
- Expansion of Distribution Channels: The rise of distributors as a key channel for automotive ICs presents an opportunity for suppliers. With distributors expected to grow at 6.6% annually, partnerships in this area can broaden market reach.
Government Initiatives in the China Integrated Circuit Automotive Application Market
The '14th Five-Year Plan for the Development of the Automotive Industry' released by the Ministry of Industry and Information Technology in 2021 aims to boost innovation and competitiveness in the sector. This plan sets ambitious targets for the automotive industry, including a focus on electric vehicles and smart technologies. The updated 'New Energy Vehicle Industry Development Plan' in 2022 by the State Council targets 20% of total vehicle sales to be electric by 2025, promoting further growth in the market. Additionally, the 'Automotive Industry Standardization Work Plan' issued in 2022 focuses on improving the quality and safety of automotive components, ensuring that manufacturers adhere to stringent standards.
The 'Smart Vehicle Innovation Development Strategy' launched in 2021 provides funding for research and development in smart vehicle technologies. The Ministry of Industry and Information Technology oversees this initiative, facilitating partnerships between OEMs and technology providers. The National Development and Reform Commission supports projects aimed at advancing automotive innovation, ensuring that manufacturers can access the latest technologies and standards. In 2023, this commission approved funding for 50 new EV projects, enhancing the capabilities of automotive manufacturers.
Future Insight of the China Integrated Circuit Automotive Application Market
By 2032, buyers and suppliers in the China Integrated Circuit Automotive Application Market can anticipate transformative changes from government initiatives and technological advancements. The 'Smart Vehicle Innovation Development Strategy' will drive the integration of smart technologies in vehicles, enhancing overall functionality. The automotive electronics sector is poised for significant expansion, with projections indicating a growth rate of 15% annually until 2025, increasing production capacity and product offerings. The approval of numerous new EV projects will stimulate demand for automotive ICs, creating a more competitive landscape for suppliers.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By IC Type – Power Management ICs Dominated, Sensor ICs Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, Power Management ICs accounted for a 43% market share by ic type in 2025. Power Management ICs command the largest share in the China Integrated Circuit Automotive Application Market because they are essential for managing energy in vehicles, particularly in electric models. The reliance on these components is highlighted by the 3.5 million electric vehicles sold in 2022, which require efficient energy management. The quickest growth will come from Sensor ICs, forecast to expand at a CAGR of 7.1% between 2026 and 2032. Sensor ICs are experiencing rapid growth as the automotive industry increasingly adopts advanced safety features and smart technologies. This surge in demand for sophisticated sensor systems is expected to continue, further propelling the growth of this segment. Suppliers should focus on developing Power Management and Sensor ICs to meet the automotive industry's increasing demands.
By Application Area – ADAS Dominated and Is Expected to Record the Fastest Growth
ADAS held a 45% share of the China Integrated Circuit Automotive Application Market by application area in 2025. ADAS holds the largest share as it is necessary for advanced driver-assistance systems, which are increasingly integrated into modern vehicles. The emphasis on safety and automation in the automotive industry drives the demand for ADAS technologies. The same category is also set to grow fastest, at a CAGR of 6.2% during 2026–2032. ADAS is also the fastest-growing area, reflecting the automotive industry's shift towards smarter and safer vehicles. The ongoing development of new technologies in this space ensures that ADAS will continue to expand rapidly. This trend indicates that suppliers should prioritise investments in ADAS technologies to capture market opportunities.
By Vehicle Type – Electric Vehicles Dominated, Passenger Cars Expected to Grow Fastest
The largest vehicle type category in 2025 was Electric Vehicles, with a 43% share of total revenue. Electric Vehicles hold the largest market share for integrated circuits, reflecting the strong consumer shift towards sustainable transportation solutions in China. The growth in electric vehicle registrations underscores the critical role of ICs in this rapidly expanding segment. Passenger Cars are projected to grow fastest, at a CAGR of 7.3% during 2026–2032. Passenger Cars represent the fastest-growing segment, as they are a major application area for integrated circuits in everyday transportation. The increase in production rates of passenger cars in China significantly drives the growth of this segment. Suppliers must adapt their offerings to cater to the rising demand for integrated circuits in passenger cars.
By Distribution Channel – Tier-1 Suppliers Dominated, Distributors Expected to Grow Fastest
Tier-1 Suppliers took a 41% share of distribution channel in 2025, more than any other category. Tier-1 Suppliers dominate the distribution channel for integrated circuits, acting as the primary conduit to automotive manufacturers. Their established relationships with OEMs ensure a consistent and reliable supply of ICs to the market. Distributors are set to record the highest CAGR in this split, 6.6% over 2026–2032. Distributors are the fastest-growing channel, as they play a crucial role in expanding access to a broader customer base within the automotive sector. Their ability to adapt to market changes positions them well for sustained growth. Suppliers should strengthen partnerships with distributors to enhance their market reach and presence.
By End User – Automotive OEMs Dominated, ECU Manufacturers Expected to Grow Fastest
In 2025, Automotive OEMs led the end user split with a 43% share. Automotive OEMs are the leading end-users of integrated circuits, reflecting their direct involvement in vehicle manufacturing processes. Their significant purchasing power allows them to maintain a dominant share in the market. The quickest growth will come from ECU Manufacturers, forecast to expand at a CAGR of 6.4% between 2026 and 2032. ECU Manufacturers are witnessing the fastest growth due to their vital role in developing advanced vehicle control systems. The increasing complexity of automotive electronics drives a higher demand for their products, accelerating this segment's expansion. Suppliers should prioritise building strong partnerships with ECU Manufacturers to capitalise on this growth opportunity.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Integrated Circuit Automotive Application Market Outlook
- Market Size of China Integrated Circuit Automotive Application Market, 2025
- Forecast of China Integrated Circuit Automotive Application Market, 2032
- Historical Data and Forecast of China Integrated Circuit Automotive Application Revenues & Volume for the Period 2022 - 2032F
- China Integrated Circuit Automotive Application Market Trend Evolution
- China Integrated Circuit Automotive Application Market Drivers and Challenges
- China Integrated Circuit Automotive Application Price Trends
- China Integrated Circuit Automotive Application Porter's Five Forces
- China Integrated Circuit Automotive Application Industry Life Cycle
- Historical Data and Forecast of China Integrated Circuit Automotive Application Market Revenues & Volume By IC Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Circuit Automotive Application Market Revenues & Volume By Power Management ICs for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Circuit Automotive Application Market Revenues & Volume By Sensor ICs for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Circuit Automotive Application Market Revenues & Volume By Communication ICs for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Circuit Automotive Application Market Revenues & Volume By Microcontrollers for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Circuit Automotive Application Market Revenues & Volume By Application Area for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Circuit Automotive Application Market Revenues & Volume By Battery Management for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Circuit Automotive Application Market Revenues & Volume By ADAS for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Circuit Automotive Application Market Revenues & Volume By Infotainment for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Circuit Automotive Application Market Revenues & Volume By Engine Control Units for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Circuit Automotive Application Market Revenues & Volume By Vehicle Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Circuit Automotive Application Market Revenues & Volume By Electric Vehicles for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Circuit Automotive Application Market Revenues & Volume By SUVs for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Circuit Automotive Application Market Revenues & Volume By Passenger Cars for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Circuit Automotive Application Market Revenues & Volume By Commercial Vehicles for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Circuit Automotive Application Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Circuit Automotive Application Market Revenues & Volume By Tier-1 Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Circuit Automotive Application Market Revenues & Volume By Distributors for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Circuit Automotive Application Market Revenues & Volume By Online Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Circuit Automotive Application Market Revenues & Volume By Semiconductor Vendors for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Circuit Automotive Application Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Circuit Automotive Application Market Revenues & Volume By Automotive OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Circuit Automotive Application Market Revenues & Volume By Electronics Assemblers for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Circuit Automotive Application Market Revenues & Volume By ECU Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Circuit Automotive Application Market Revenues & Volume By Telematics Providers for the Period 2022 - 2032F
- China Integrated Circuit Automotive Application Import Export Trade Statistics
- Market Opportunity Assessment By IC Type
- Market Opportunity Assessment By Application Area
- Market Opportunity Assessment By Vehicle Type
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China Integrated Circuit Automotive Application Top Companies Market Share
- China Integrated Circuit Automotive Application Competitive Benchmarking By Technical and Operational Parameters
- China Integrated Circuit Automotive Application Company Profiles
- China Integrated Circuit Automotive Application Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By IC Type
- Power Management ICs
- Sensor ICs
- Communication ICs
- Microcontrollers
By Application Area
- Battery Management
- ADAS
- Infotainment
- Engine Control Units
By Vehicle Type
- Electric Vehicles
- SUVs
- Passenger Cars
- Commercial Vehicles
By Distribution Channel
- Tier-1 Suppliers
- Distributors
- Online Platforms
- Semiconductor Vendors
By End User
- Automotive OEMs
- Electronics Assemblers
- ECU Manufacturers
- Telematics Providers































