China Integrated Electrical System Market Size & Growth Rate
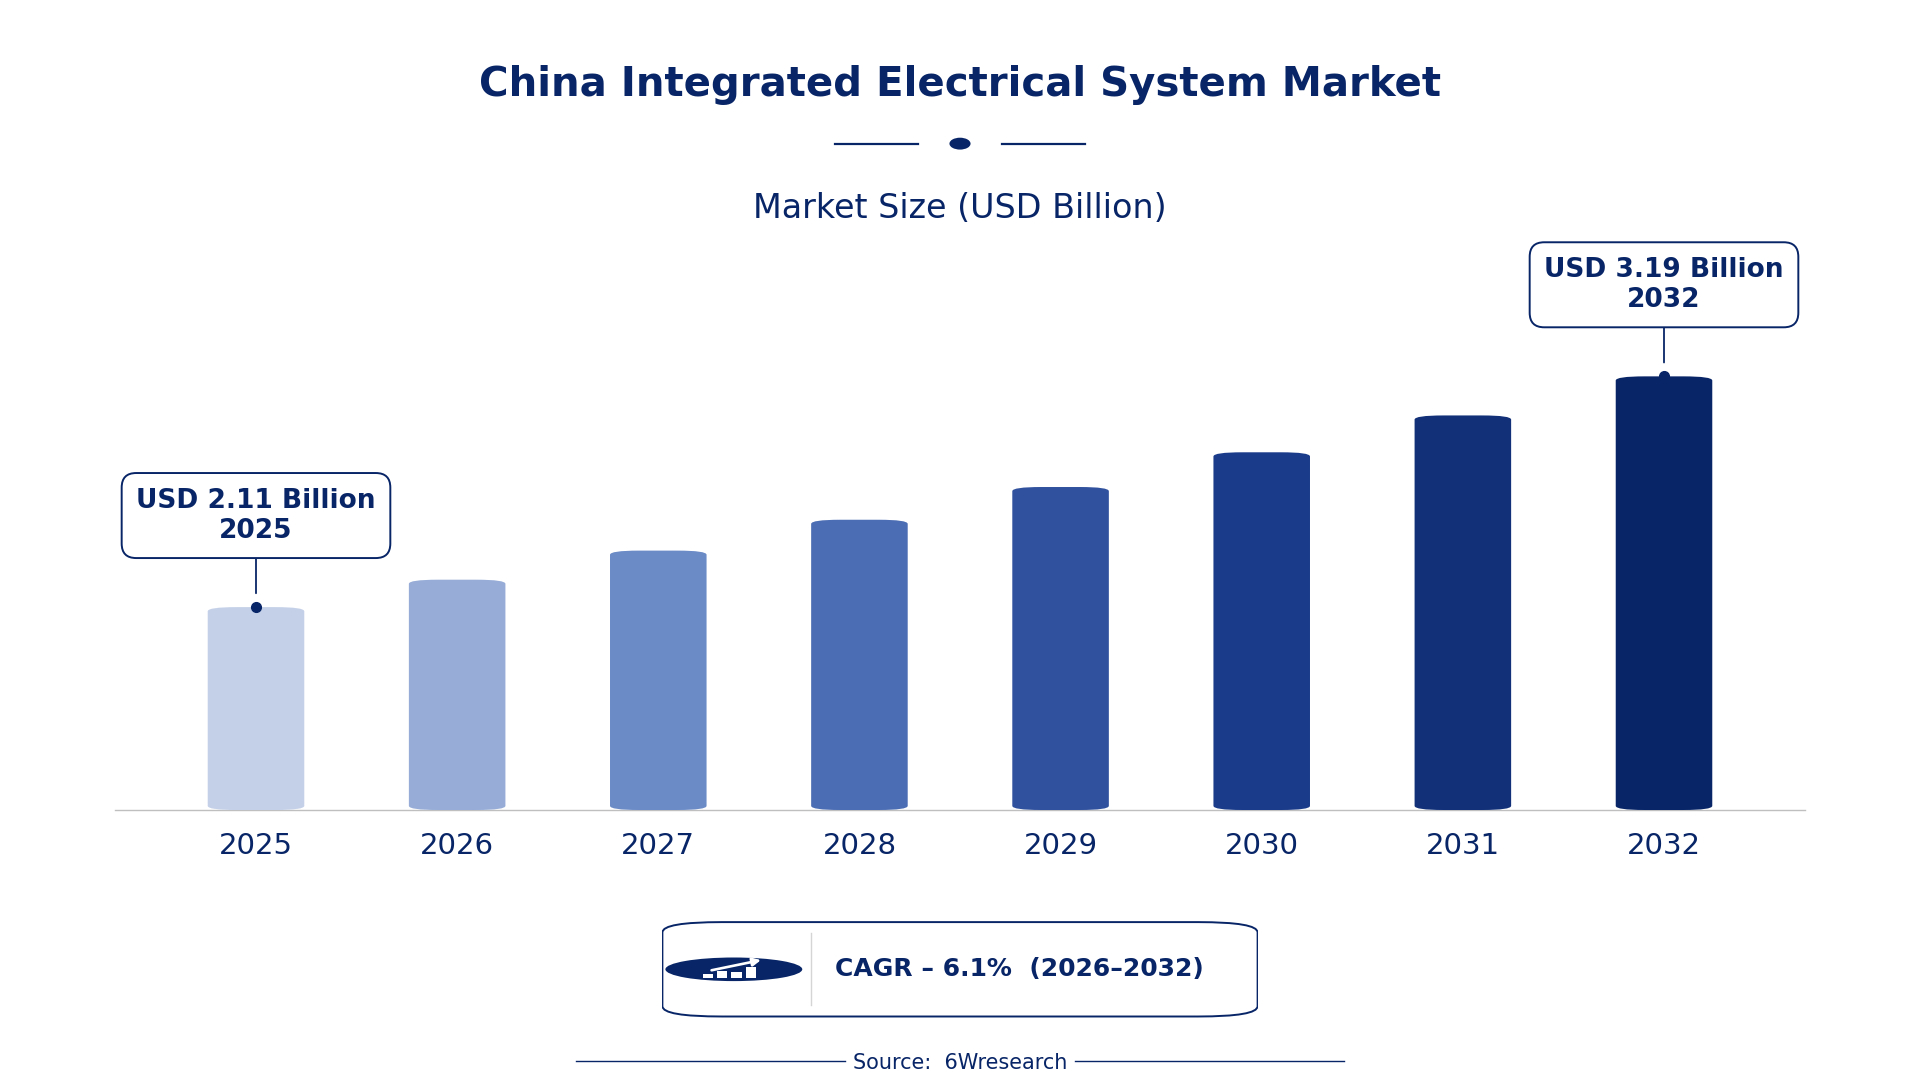
According to 6Wresearch internal database and industry insights, the China Integrated Electrical System Market was valued at USD 2.11 billion in 2025 and is projected to reach USD 3.19 billion by 2032, growing at a CAGR of approximately 6.1% during 2026–2032.
China Integrated Electrical System Market Highlights
| Report Metric | Details |
| Report Name | China Integrated Electrical System Market |
| Market Size 2025 | USD 2.11 billion |
| Market Size 2032 | USD 3.19 billion |
| Absolute Growth 2025–2032 | USD 1.08 billion |
| CAGR 2026–2032 | 6.1% |
| Peak Annual Growth | 8.6% in 2030 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading System Type, 2025 | High-Voltage Systems (39% share) |
| Leading Power Level, 2025 | >1000V (52% share) |
| Leading Integration Area, 2025 | Industrial Plants (52% share) |
| Leading End User Industry, 2025 | Utilities & Factories (40% share) |
| Leading Distribution Channel, 2025 | Turnkey Installers (40% share) |
| Fastest-Growing System Type | Low-Voltage Systems (8.3% CAGR) |
| Fastest-Growing Power Level | <600V (8.9% CAGR) |
| Fastest-Growing Integration Area | Buildings (7.6% CAGR) |
| Fastest-Growing End User Industry | Construction Firms (8.5% CAGR) |
| Fastest-Growing Distribution Channel | Panel Builders (7.5% CAGR) |
| Growing Sector | Construction Firms |
| Key End Users | Utilities & Factories, Construction Firms, Energy Companies, Infrastructure Providers |
China Integrated Electrical System Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
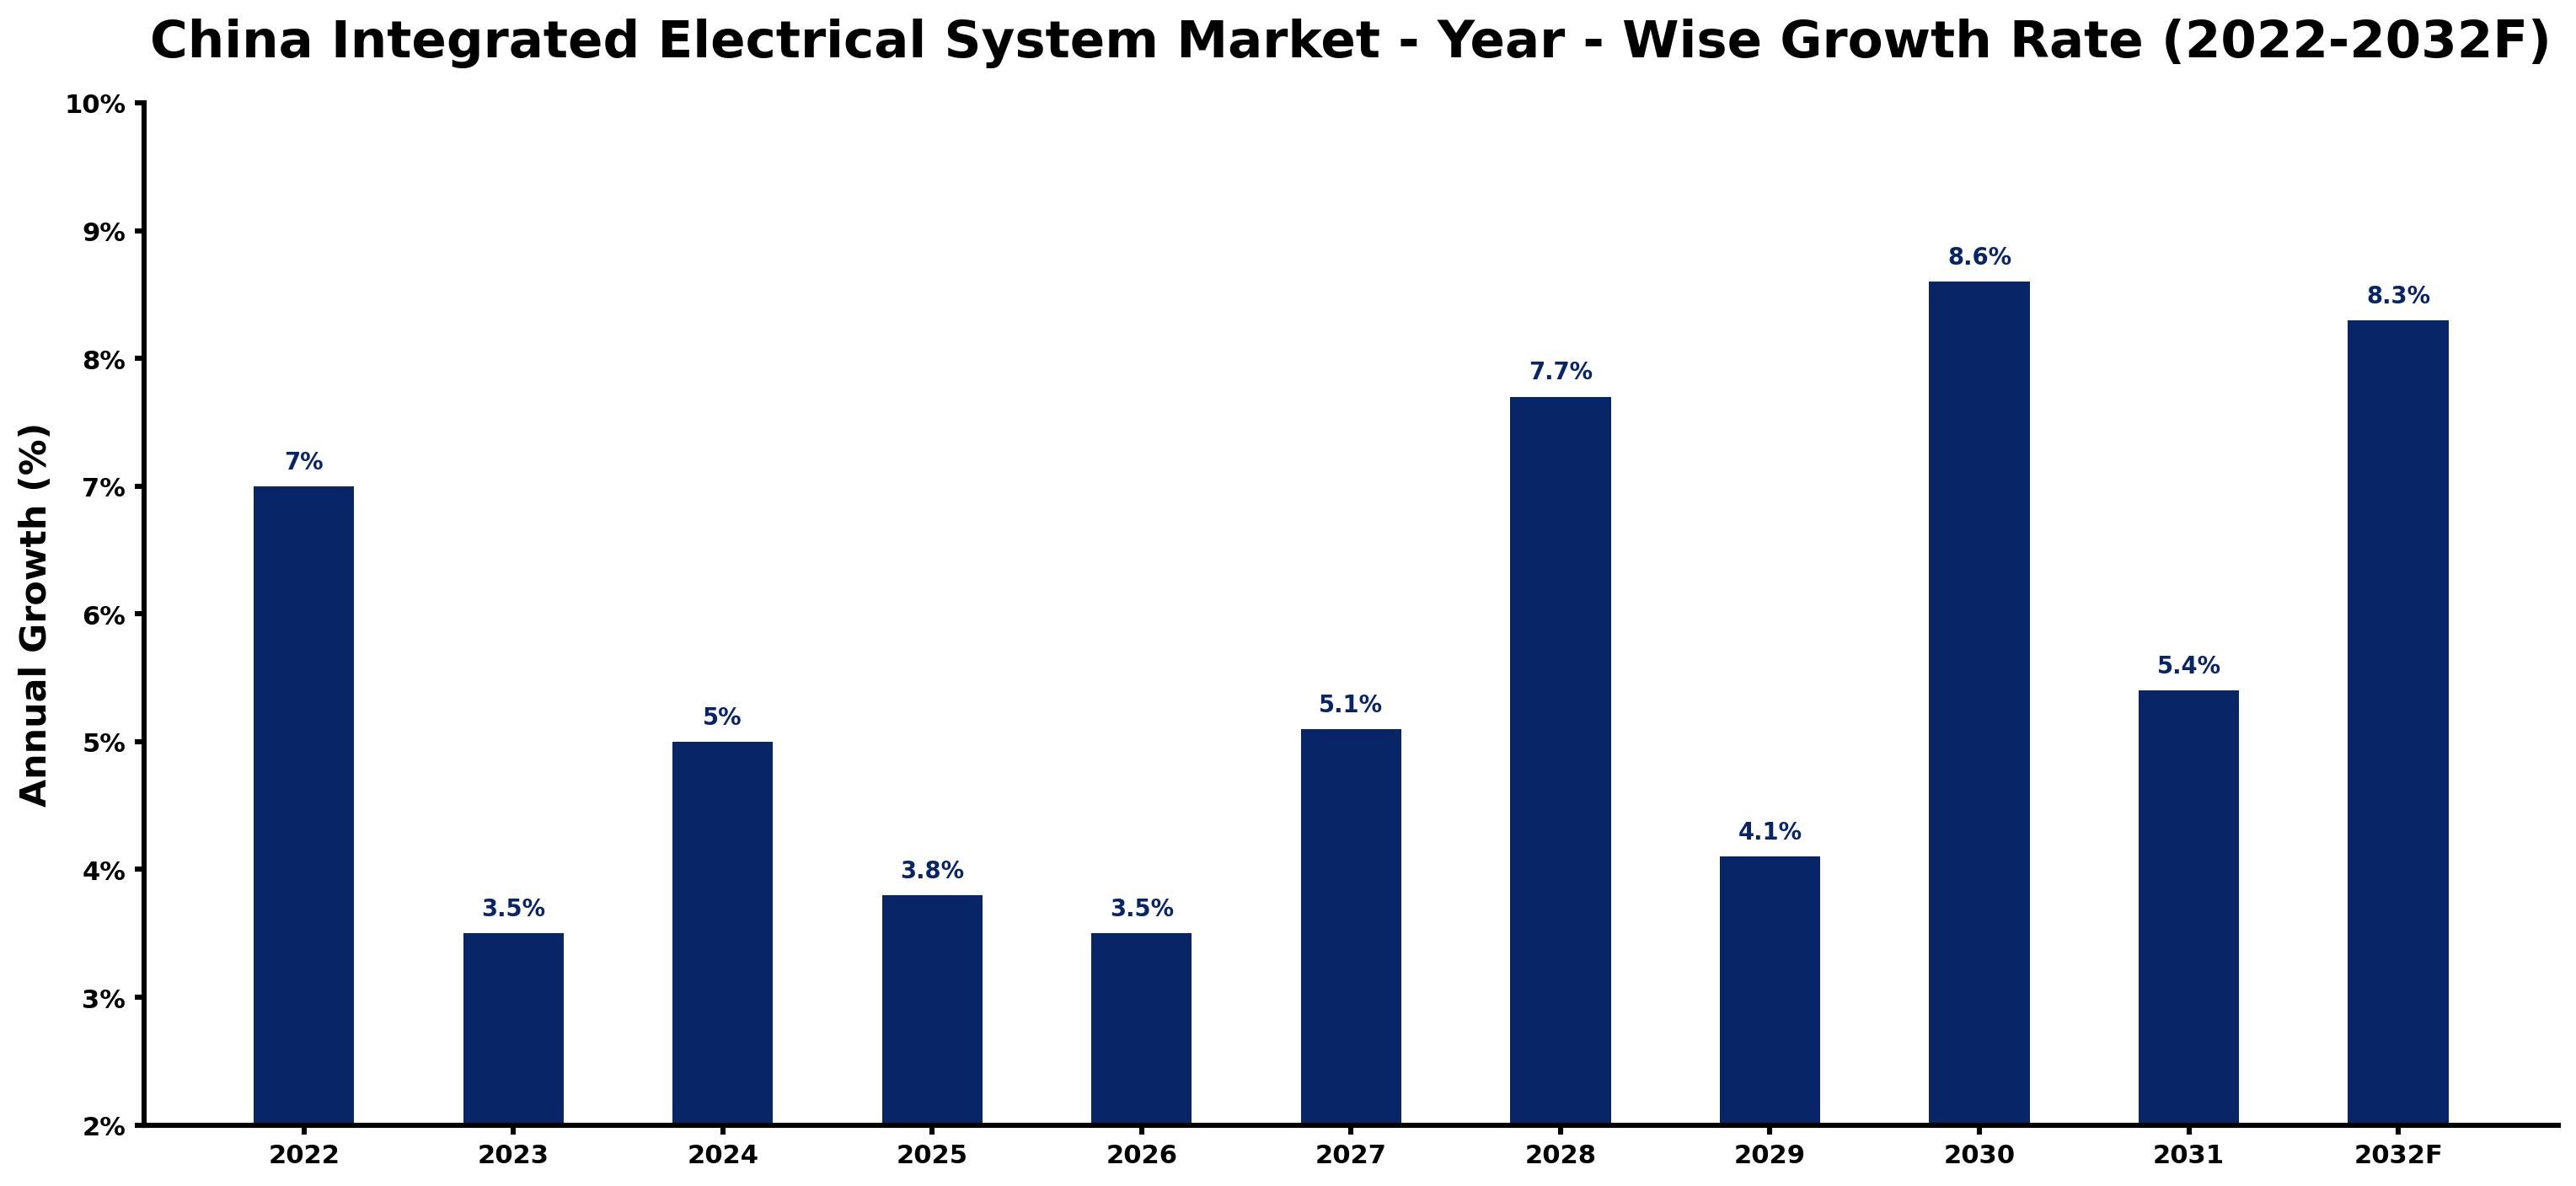
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.0 | The market experienced strong demand from industrial plants and construction sectors. |
| 2023 | 3.5 | Growth slowed due to a temporary dip in new construction projects in urban areas. |
| 2024 | 5.0 | Increased investments in smart buildings boosted demand for integrated systems. |
| 2025 | 3.8 | The market experienced slower growth as energy efficiency regulations were implemented. |
| 2026 | 3.5 | Demand is expected to stabilise as the National Energy Administration promotes new energy management standards. |
| 2027 | 5.1 | Investment in renewable energy integration will spur growth in integrated systems. |
| 2028 | 7.7 | Smart building projects are projected to accelerate, driving higher demand for integrated solutions. |
| 2029 | 4.1 | Growth is expected to slow as the market faces supply chain challenges in component availability. |
| 2030 | 8.6 | A surge in smart infrastructure projects will lead to peak growth in the market. |
| 2031 | 5.4 | Growth is projected to moderate as the market adjusts to the completion of major projects. |
| 2032 | 8.3 | Continued investment in energy efficiency and smart systems will drive growth. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Integrated Electrical System Market Synopsis
The Integrated Electrical System market in China includes technologies that manage power distribution efficiently across various sectors. This encompasses high-voltage and low-voltage systems, modular wiring, and smart technologies, mainly utilised in industrial plants, buildings, and renewable energy setups. The market is set to reach 1.5 trillion yuan by 2025, propelled by rising demand from domestic users in industrial and construction sectors. The increasing focus on smart buildings and renewable energy integration further stimulates this demand, especially in regions like Guangdong, which leads in smart building implementations.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising investments in smart infrastructure projects | Driver | High | Smart Buildings |
| Growing demand for energy-efficient solutions | Driver | High | Industrial Plants |
| Increased focus on renewable energy integration | Opportunity | High | Renewable Setups |
| Growing urbanisation leading to more construction projects | Opportunity | High | Buildings |
| Supply chain disruptions affecting component availability | Restraint | Medium | High-Voltage Systems |
| Regulatory compliance costs for energy management standards | Restraint | Medium | Low-Voltage Systems |
| High initial investment costs for integrated systems | Challenge | High | Modular Wiring Systems |
| Complex approval processes for new technologies | Challenge | Medium | Hybrid Electrical Units |
Evaluation of Drivers in China Integrated Electrical System Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Investment in smart building technologies | Smart Buildings | This investment is driving demand for integrated electrical systems, with smart buildings projected to account for 40% of new constructions by 2025. |
| Increased energy management regulations | Low-Voltage Systems | Regulations such as ISO 50001 are pushing residential and commercial sectors to adopt integrated systems for better energy efficiency. |
| Urbanisation leading to more construction projects | Buildings | The 15% increase in residential building projects in 2022 has created a higher demand for integrated electrical systems. |
| Growth in renewable energy capacity | Renewable Setups | China's renewable energy capacity reached 1,000 GW in 2022, necessitating integrated systems for efficient energy distribution. |
| Rising energy consumption in industrial plants | Industrial Plants | With an average energy consumption of 2,000 kWh per day, industrial plants are increasingly adopting integrated systems for efficiency. |
The Integrated Electrical System market in China is expanding as investment in smart building technologies, increased energy management standards, and urbanisation drive demand. The projected growth in smart buildings, expected to represent 40% of new constructions by 2025, boosts the need for integrated systems. The rise in renewable energy capacity, which reached 1,000 GW in 2022, necessitates efficient energy distribution solutions. With industrial plants consuming an average of 2,000 kWh per day, the demand for integrated systems is amplified. As the residential sector sees a 15% increase in building projects, the market is well-positioned for continued growth.
Evaluation of Restraints in China Integrated Electrical System Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High installation costs | High-Voltage Systems | The average installation cost for integrated systems can exceed 15% of total project budgets, deterring some buyers. |
| Limited skilled workforce | Construction Firms | A shortage of qualified technicians leads to project delays and increased labour costs for construction firms. |
| Technological integration issues | High-Voltage Systems | Many existing systems lack compatibility with newer technologies, causing inefficiencies and additional costs for buyers. |
| Regulatory compliance delays | High-Voltage Systems | Compliance with standards like ISO 50001 can prolong project timelines, impacting energy efficiency upgrades. |
| Fluctuating demand from buyers | High-Voltage Systems | Variable demand in the residential sector complicates production planning and can lead to excess inventory costs. |
China Integrated Electrical System Market Challenges
The China Integrated Electrical System market faces a critical skills shortage that delays project completions, raising installation costs for construction firms by around 20%. Technological integration issues stem from compatibility problems with existing systems, leading to inefficiencies that can inflate operational costs by 15% for buyers. Regulatory compliance with standards can prolong project timelines, hindering energy efficiency improvements in industrial plants. Demand fluctuations in the residential sector complicate production planning, resulting in excess inventory costs that can reach 10% for suppliers.
Trends in the China Integrated Electrical System Market
Several trends are reshaping the China Integrated Electrical System Market; the most important are set out below.
- Shift Towards Smart Buildings: Construction firms are increasingly adopting integrated electrical systems to improve energy efficiency. In 2022, 30% of new buildings in urban areas were equipped with smart electrical systems, reflecting a growing trend.
- Integration of Renewable Energy: The focus on renewable setups is rising, with integrated systems becoming essential for energy management. China's renewable energy capacity reached 1,000 GW in 2022, driving further demand for integrated solutions.
- Expansion of Modular Wiring Systems: Modular wiring systems are gaining traction for their flexibility in installations. The installation of these systems has increased by 25% in urban construction projects since 2021.
- Government Support for Energy Efficiency: The government allocated 500 million yuan for renewable energy integration projects in 2023. This funding is expected to promote the adoption of integrated systems across various sectors.
Investment Opportunities in the China Integrated Electrical System Market
Investors looking at the China Integrated Electrical System Market should consider the following areas.
- Expansion in Urban Areas: The growing urban population presents opportunities for integrated systems in new constructions. Targeting construction firms in major cities can facilitate successful market entry.
- Investment in Smart Infrastructure: With smart buildings projected to account for 40% of new constructions by 2025, suppliers can concentrate on providing integrated systems to construction firms in urban areas.
- Partnerships with EPC Contractors: Collaborating with EPC contractors can ease market entry, particularly in large-scale projects that require integrated electrical systems for efficiency.
- Focus on Renewable Energy Integration: The government's investment of 500 million yuan in renewable energy projects opens avenues for suppliers of integrated systems, especially in regions like Guangdong.
Government Initiatives in the China Integrated Electrical System Market
In 2023, the Ministry of Housing and Urban-Rural Development issued guidelines for smart building integration, refining previous regulations. These guidelines aim to standardise the adoption of integrated electrical systems, ensuring compliance with energy efficiency standards and promoting sustainable practices. Additionally, the National Energy Administration's 'Energy Development Plan 2021-2025' allocates 500 million yuan for renewable energy integration projects, supporting the implementation of integrated systems in urban developments and improving energy efficiency across sectors.
The National Energy Administration oversees the funding of renewable energy integration projects, facilitating the adoption of integrated electrical systems. This funding enables producers to invest in advanced technologies and enhance compliance with energy management standards, ultimately benefiting buyers through improved system performance and reliability.
Future Insight of the China Integrated Electrical System Market
The China Integrated Electrical System market will experience notable changes by 2032, driven by advancements in smart grid technologies and supportive government initiatives. The National Energy Administration's focus on energy efficiency will bolster urban development projects. By 2025, smart systems are expected to account for 30% of new constructions, indicating a shift towards modern infrastructure. The government's allocation of 500 million yuan for renewable energy integration projects will stimulate demand, particularly in regions like Jiangsu, which is central to electrical system manufacturing.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By System Type – High-Voltage Systems Dominated, Low-Voltage Systems Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, High-Voltage Systems took a 39% share of system type in 2025, more than any other category. High-voltage systems dominate the market share due to their critical role in large-scale power distribution and their necessity for industrial applications. Major industrial plants, which consume vast amounts of energy, rely heavily on these systems to manage their power needs effectively. Low-Voltage Systems are set to record the highest CAGR in this split, 8.3% over 2026–2032. Low-voltage systems are experiencing rapid growth, primarily driven by their increasing adoption in residential and commercial sectors for efficient power management. The notable 15% increase in residential building projects in 2022 is significantly boosting demand for these solutions. Suppliers should focus on low-voltage systems to capture the expanding market share effectively.
By Power Level – >1000V Dominated, <600V Expected to Grow Fastest
In 2025, >1000V led the power level split with a 52% share. >1000V systems hold the largest market share as they are essential for high-capacity industrial systems requiring robust power solutions. Their widespread application in large factories and utilities solidifies their leading position in the China Integrated Electrical System Market. <600V is projected to grow fastest, at a CAGR of 8.9% during 2026–2032. The <600V segment is rapidly growing, fueled by the rising integration of electrical systems in residential and commercial applications. This trend is particularly evident as smart building initiatives gain momentum across urban areas. Buyers in the <600V segment can expect a broader range of options and competitive pricing as suppliers expand their product offerings.
By Integration Area – Industrial Plants Dominated, Buildings Expected to Grow Fastest
Industrial Plants held a 52% share of the China Integrated Electrical System Market by integration area in 2025. Industrial plants are the primary users of integrated electrical systems, leveraging these technologies to enhance operational efficiency. Their substantial energy consumption makes them a key segment in the market, driving demand for integrated solutions. Over 2026–2032, Buildings are expected to post the fastest growth, at a CAGR of 7.6%. Buildings are witnessing the fastest growth in adopting integrated systems, especially as energy management becomes a priority in new construction projects. Recent guidelines for smart building integration are significantly contributing to this trend. Suppliers should tailor their offerings to meet the specific needs of the building sector to capitalise on this growing market opportunity.
By End User Industry – Utilities & Factories Dominated, Construction Firms Expected to Grow Fastest
The largest end user industry category in 2025 was Utilities & Factories, with a 40% share of total revenue. Utilities and factories are the main consumers of integrated electrical systems, relying on these technologies to optimise their operations. Their substantial energy demands ensure that they maintain a leading market share. The quickest growth will come from Construction Firms, forecast to expand at a CAGR of 8.5% between 2026 and 2032. Construction firms are increasingly involved in the installation of integrated systems, which is driving their rapid growth in the market. The rise in construction projects, particularly those focusing on energy efficiency, fuels this trend. Suppliers must engage with construction firms to ensure their products meet the evolving demands of this expanding sector.
By Distribution Channel – Turnkey Installers Dominated, Panel Builders Expected to Grow Fastest
With a 40% revenue share in 2025, Turnkey Installers was the largest distribution channel category. Turnkey installers lead the market by offering comprehensive solutions tailored to client needs, making them essential for large-scale projects. Their complete service offerings ensure they capture a significant market share in distributing integrated electrical systems. Panel Builders are set to record the highest CAGR in this split, 7.5% over 2026–2032. Panel builders are experiencing the fastest growth due to their vital role in manufacturing components for integrated systems, which are in high demand. As the market expands, their contributions become increasingly crucial for fulfilling customer needs. Suppliers should consider partnerships with panel builders to enhance distribution capabilities and reach a broader customer base.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Integrated Electrical System Market Outlook
- Market Size of China Integrated Electrical System Market, 2025
- Forecast of China Integrated Electrical System Market, 2032
- Historical Data and Forecast of China Integrated Electrical System Revenues & Volume for the Period 2022 - 2032F
- China Integrated Electrical System Market Trend Evolution
- China Integrated Electrical System Market Drivers and Challenges
- China Integrated Electrical System Price Trends
- China Integrated Electrical System Porter's Five Forces
- China Integrated Electrical System Industry Life Cycle
- Historical Data and Forecast of China Integrated Electrical System Market Revenues & Volume By System Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Electrical System Market Revenues & Volume By High-Voltage Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Electrical System Market Revenues & Volume By Low-Voltage Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Electrical System Market Revenues & Volume By Hybrid Electrical Units for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Electrical System Market Revenues & Volume By Modular Wiring Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Electrical System Market Revenues & Volume By Power Level for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Electrical System Market Revenues & Volume By >1000V for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Electrical System Market Revenues & Volume By <600V for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Electrical System Market Revenues & Volume By AC/DC Combo for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Electrical System Market Revenues & Volume By Plug-and-Play for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Electrical System Market Revenues & Volume By Integration Area for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Electrical System Market Revenues & Volume By Industrial Plants for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Electrical System Market Revenues & Volume By Buildings for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Electrical System Market Revenues & Volume By Renewable Setups for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Electrical System Market Revenues & Volume By Smart Buildings for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Electrical System Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Electrical System Market Revenues & Volume By Utilities & Factories for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Electrical System Market Revenues & Volume By Construction Firms for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Electrical System Market Revenues & Volume By Energy Companies for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Electrical System Market Revenues & Volume By Infrastructure Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Electrical System Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Electrical System Market Revenues & Volume By Turnkey Installers for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Electrical System Market Revenues & Volume By Panel Builders for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Electrical System Market Revenues & Volume By EPC Contractors for the Period 2022 - 2032F
- Historical Data and Forecast of China Integrated Electrical System Market Revenues & Volume By Smart System Vendors for the Period 2022 - 2032F
- China Integrated Electrical System Import Export Trade Statistics
- Market Opportunity Assessment By System Type
- Market Opportunity Assessment By Power Level
- Market Opportunity Assessment By Integration Area
- Market Opportunity Assessment By End User Industry
- Market Opportunity Assessment By Distribution Channel
- China Integrated Electrical System Top Companies Market Share
- China Integrated Electrical System Competitive Benchmarking By Technical and Operational Parameters
- China Integrated Electrical System Company Profiles
- China Integrated Electrical System Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By System Type
- High-Voltage Systems
- Low-Voltage Systems
- Hybrid Electrical Units
- Modular Wiring Systems
By Power Level
- >1000V
- <600V
- AC/DC Combo
- Plug-and-Play
By Integration Area
- Industrial Plants
- Buildings
- Renewable Setups
- Smart Buildings
By End User Industry
- Utilities & Factories
- Construction Firms
- Energy Companies
- Infrastructure Providers
By Distribution Channel
- Turnkey Installers
- Panel Builders
- EPC Contractors
- Smart System Vendors































