China IoT DevOps Market Size & Growth Rate
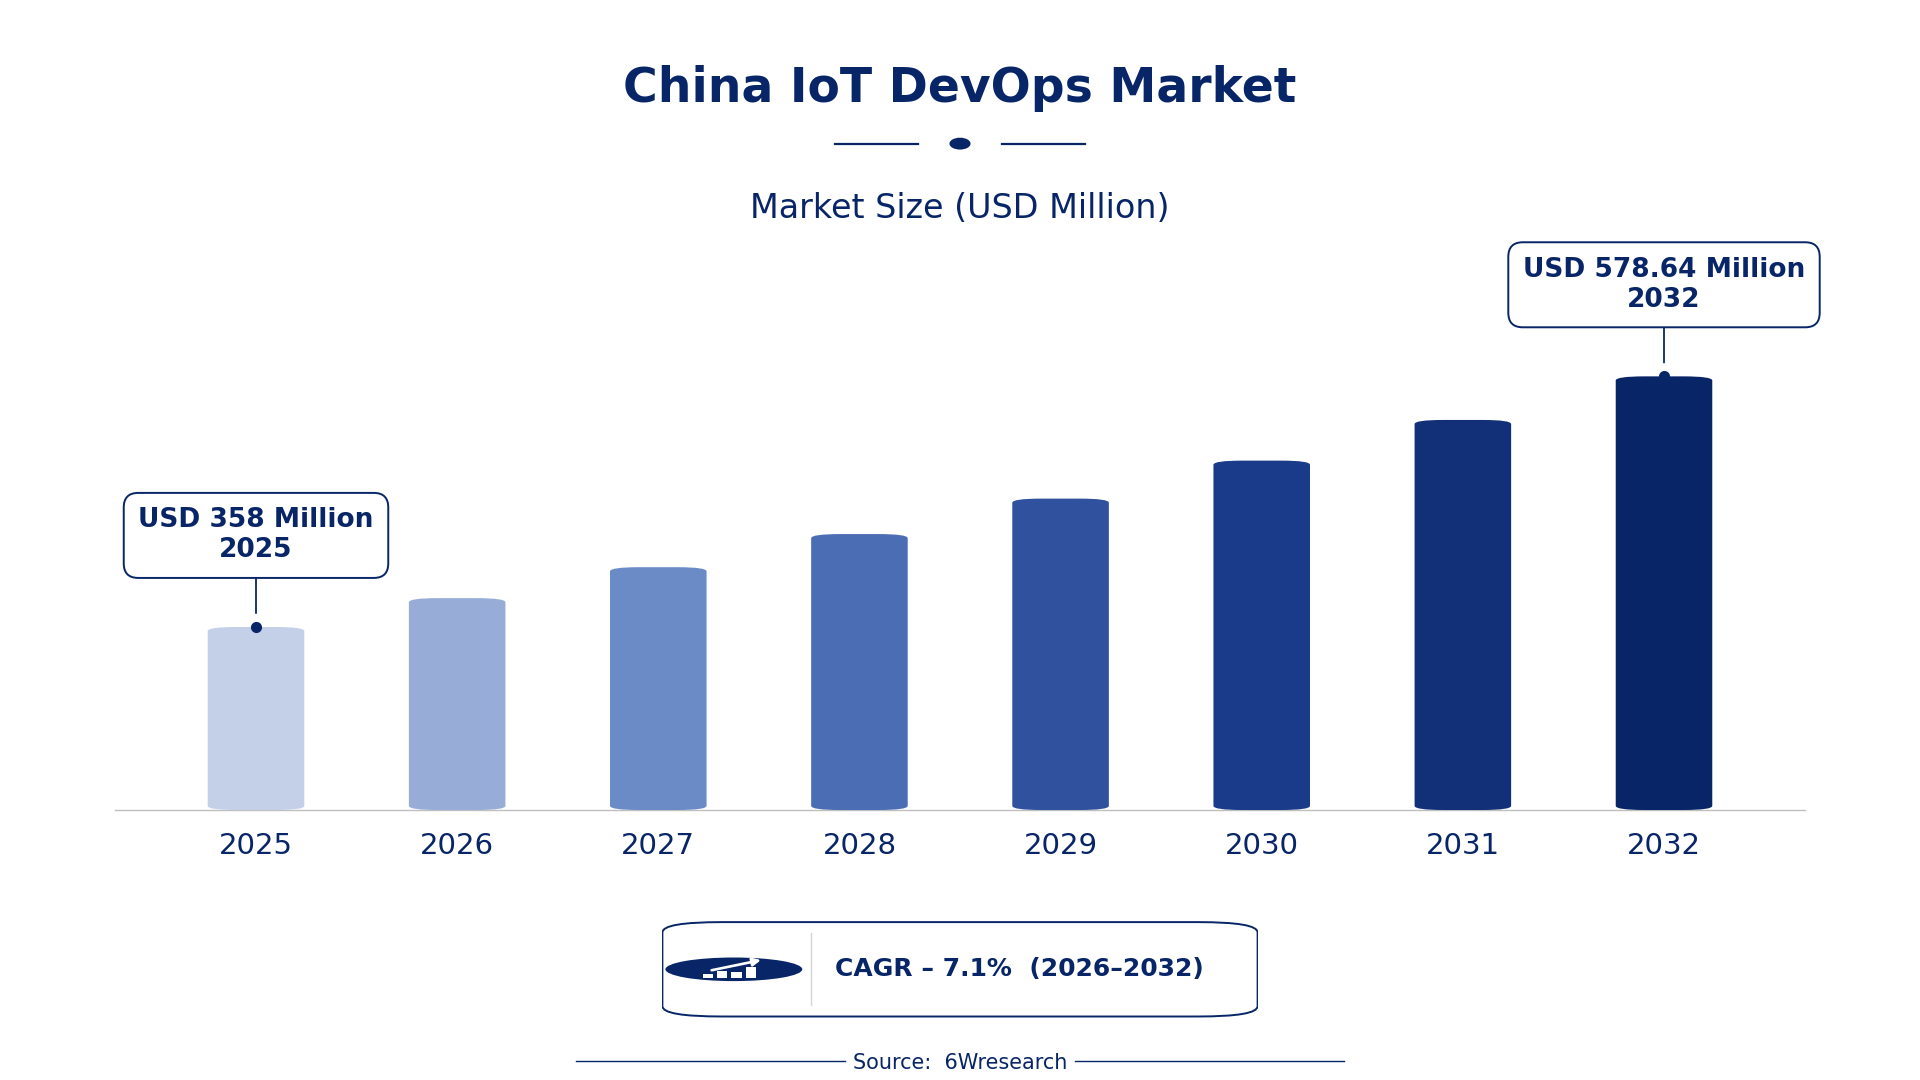
According to 6Wresearch internal database and industry insights, the China IoT DevOps Market was valued at USD 358.0 million in 2025 and is projected to reach USD 578.64 million by 2032, growing at a CAGR of approximately 7.1% during 2026–2032.
China IoT DevOps Market Highlights
| Report Metric | Details |
| Report Name | China IoT DevOps Market |
| Market Size 2025 | USD 358.0 million |
| Market Size 2032 | USD 578.64 million |
| Absolute Growth 2025–2032 | USD 220.64 million |
| CAGR 2026–2032 | 7.1% |
| Peak Annual Growth | 9.4% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Platform Type, 2025 | CI/CD Platforms (40% share) |
| Leading Deployment Mode, 2025 | Cloud (42% share) |
| Leading Toolset Type, 2025 | Proprietary (39% share) |
| Leading End User, 2025 | IoT Device Makers (41% share) |
| Leading Distribution Channel, 2025 | DevOps Vendors (35% share) |
| Fastest-Growing Platform Type | Monitoring Tools (8.7% CAGR) |
| Fastest-Growing Deployment Mode | Edge (8.3% CAGR) |
| Fastest-Growing Toolset Type | AI-Driven (9.2% CAGR) |
| Fastest-Growing End User | Smart Factory Operators (8.9% CAGR) |
| Growing Sector | smart manufacturing |
| Key End Users | IoT Device Makers, System Integrators, Smart Factory Operators |
China IoT DevOps Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
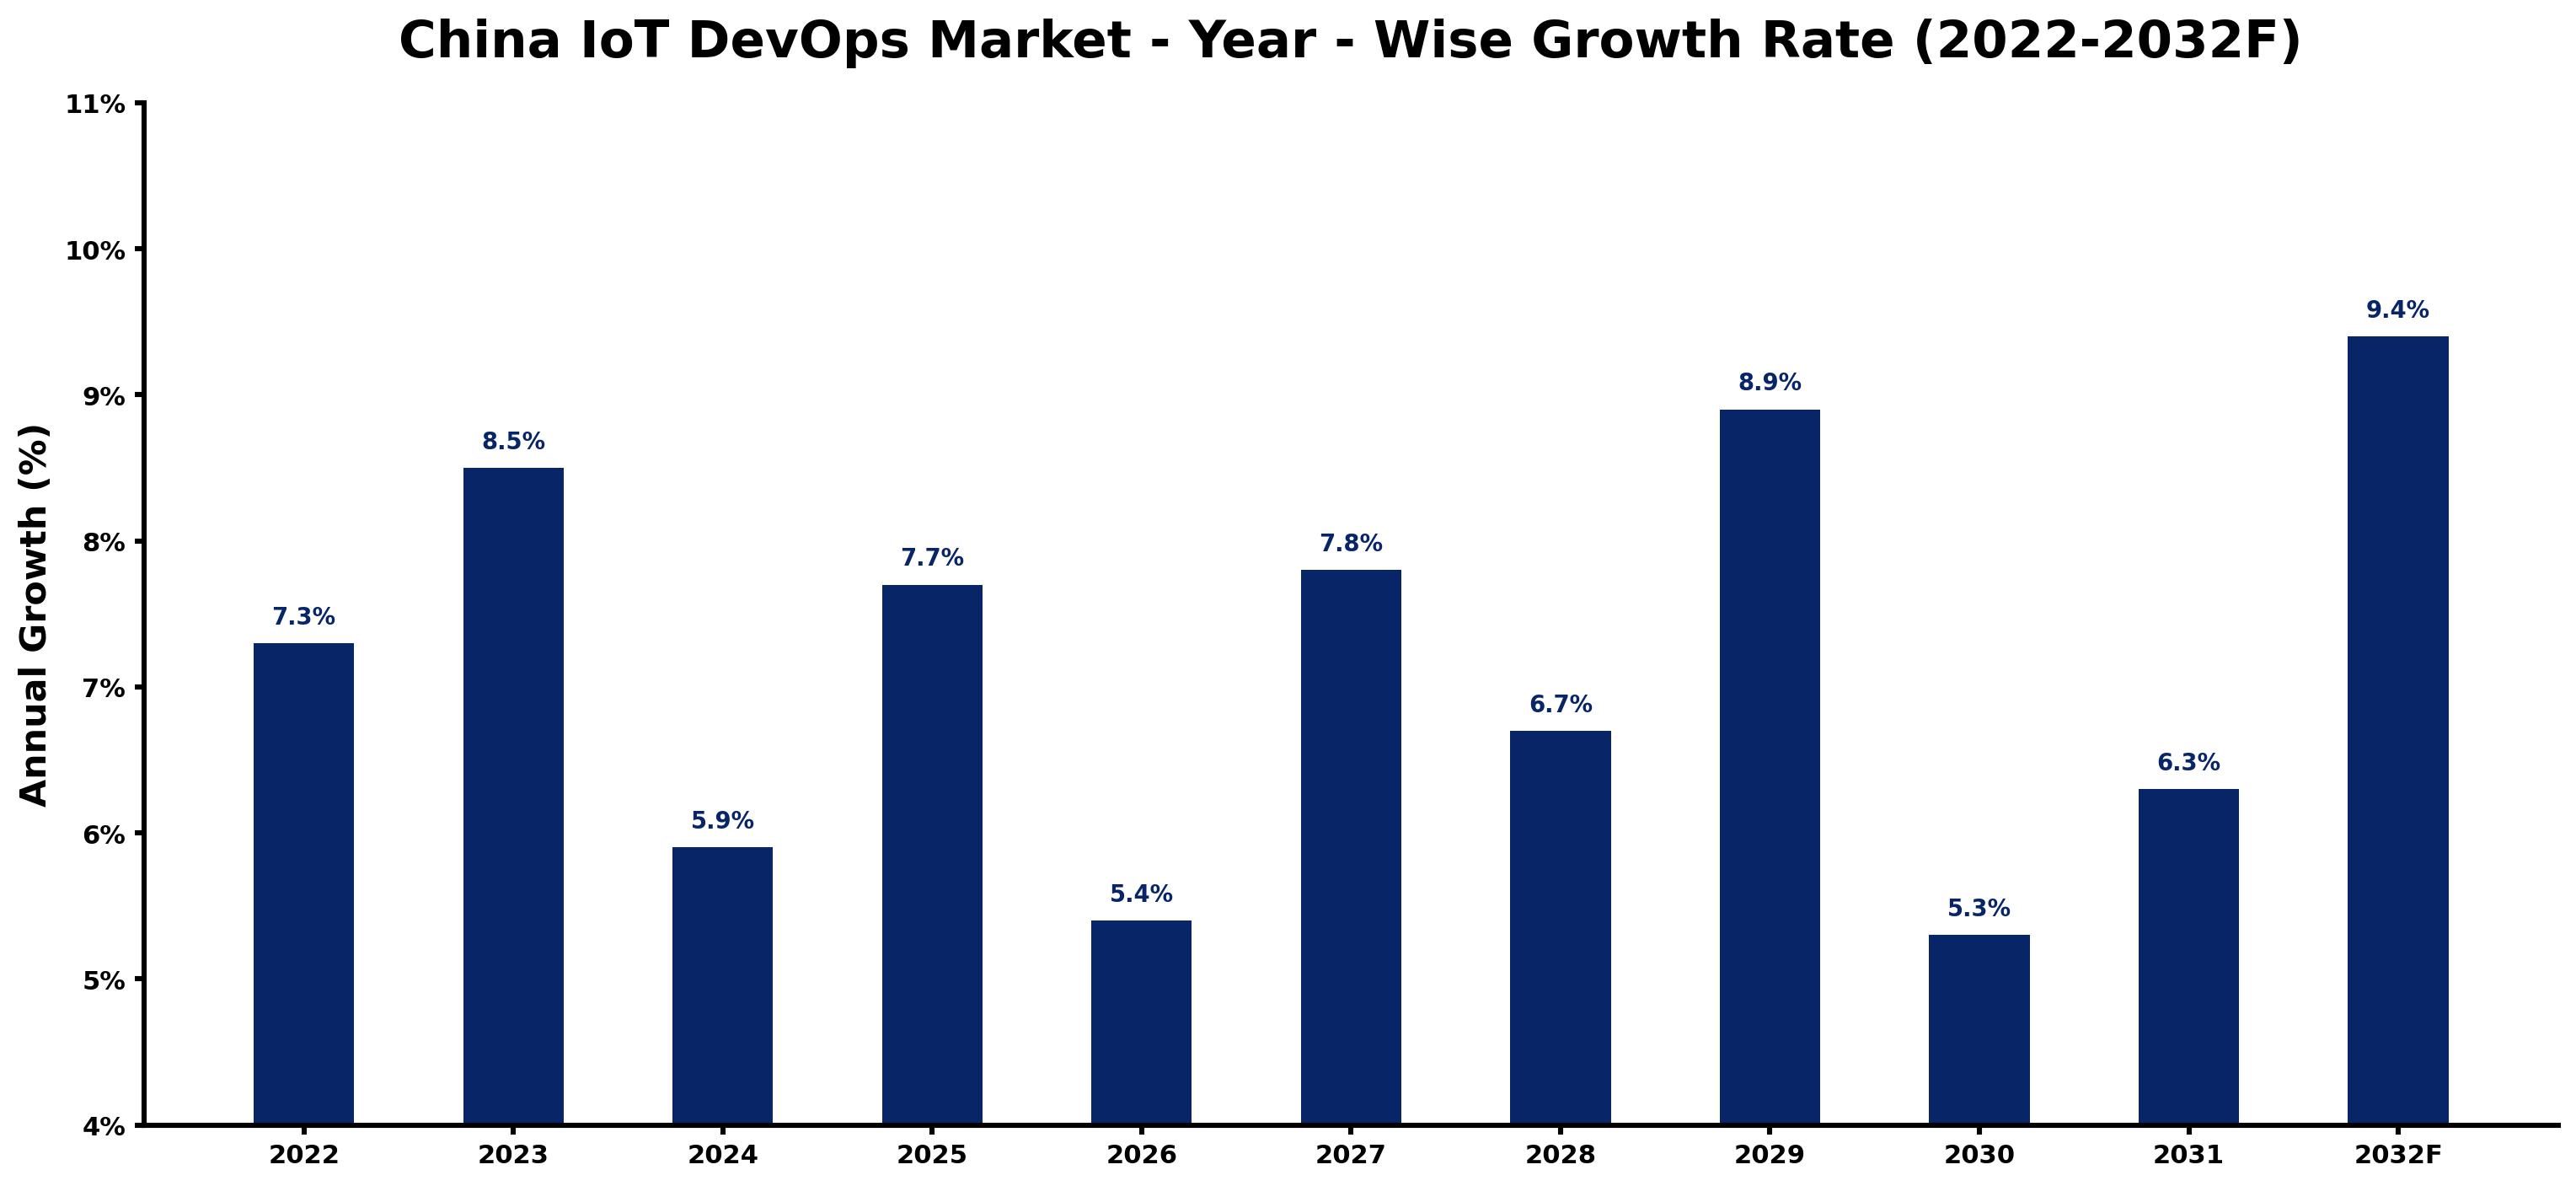
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.3 | The market experienced steady growth, driven by increased adoption of the 'IoT Development Action Plan' among manufacturers. |
| 2023 | 8.5 | Demand surged as smart factory initiatives gained traction across various sectors, boosting IoT DevOps usage. |
| 2024 | 5.9 | Growth slowed due to evolving technology requirements and the implementation of the National Standards of China for IoT. |
| 2025 | 7.7 | The market rebounded with renewed investments in IoT DevOps for smart manufacturing, aligning with the 'Made in China 2025' initiative. |
| 2026 | 5.4 | A slowdown occurred as companies reassessed their IoT strategies and investments amid changing regulations. |
| 2027 | 7.8 | Growth accelerated again as demand for automation in factories increased due to rising operational efficiency needs. |
| 2028 | 6.7 | The market saw a slowdown as companies faced challenges in scaling IoT solutions effectively. |
| 2029 | 8.9 | Demand picked up as more industries adopted edge computing solutions, supported by increasing investments. |
| 2030 | 5.3 | Growth slowed again, reflecting a period of consolidation in the IoT sector as companies adapted to new technologies. |
| 2031 | 6.3 | The market rebounded with increased investments in AI-driven IoT applications, improving operational capabilities. |
| 2032 | 9.4 | A peak in growth is expected as IoT integration becomes critical for urban infrastructure development. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China IoT DevOps Market Synopsis
IoT DevOps in China refers to the integration of development and operations practices for IoT applications. This approach streamlines the software development lifecycle, automating deployment processes and monitoring device performance. The China IoT DevOps Market is growing due to strong demand from smart manufacturing and urban infrastructure projects. With the IoT market projected to reach 1 trillion yuan by 2025, investments in cloud computing and smart city initiatives are driving further growth. The 'Made in China 2025' initiative highlights the importance of IoT in improving manufacturing efficiency and innovation.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased investment in smart manufacturing technologies | Driver | High | CI/CD Platforms |
| Growing demand for automation in urban infrastructure projects | Driver | High | Automation Frameworks |
| Rising need for real-time data processing solutions | Opportunity | High | Edge |
| Significant government funding for IoT research and development | Opportunity | High | Monitoring Tools |
| Challenges in interoperability between IoT devices | Restraint | High | IoT Device Makers |
| High costs associated with implementing IoT solutions | Restraint | Medium | System Integrators |
| Limited availability of skilled professionals in IoT DevOps | Challenge | High | Smart Factory Operators |
| Complex regulatory requirements for IoT devices | Challenge | Medium | DevOps Vendors |
Evaluation of Drivers in China IoT DevOps Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased investments in smart manufacturing | CI/CD Platforms | Over 70% of IoT device makers in China utilise CI/CD platforms for development, driving demand. |
| Growing demand for automation solutions | Automation Frameworks | The smart factory sector is projected to grow, leading to increased purchases of automation tools. |
| Rising cloud computing adoption | Cloud | China's cloud computing market is expected to reach 1 trillion yuan by 2025, boosting IoT scalability. |
| Surge in AI-driven applications | AI-Driven | AI-driven IoT applications are increasingly adopted, improving operational efficiency across sectors. |
| Expansion of edge computing solutions | Edge | The demand for edge computing is rising, with significant investments planned through 2025. |
Expansion of the IoT DevOps market in China is supported by increased investments in smart manufacturing and automation frameworks. More than 70% of IoT device makers in China employ CI/CD platforms, optimising their development processes. The smart factory sector is poised for substantial growth, leading to heightened purchases of automation solutions. China's cloud computing market is anticipated to reach 1 trillion yuan by 2025, boosting the scalability of IoT applications. The growing adoption of AI-driven applications further promotes operational efficiency, resulting in increased demand for IoT DevOps tools.
Evaluation of Restraints in China IoT DevOps Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Interoperability issues between different IoT devices | IoT Device Makers | The National Standards of China for IoT include guidelines for interoperability, impacting manufacturers. |
| High implementation costs for IoT solutions | System Integrators | The costs associated with deploying IoT solutions can deter potential clients from investing. |
| Limited availability of skilled professionals | Smart Factory Operators | The rapid growth of IoT has outpaced the training of skilled professionals in this sector. |
| Complex regulatory requirements for IoT devices | DevOps Vendors | Manufacturers must navigate stringent regulations, adding to the complexity and cost of compliance. |
| Slow adoption of new technologies by traditional industries | System Integrators | Many traditional industries are hesitant to adopt IoT technologies, limiting market growth. |
China IoT DevOps Market Challenges
Buyers in the China IoT DevOps market encounter rising costs due to the complex integration of IoT devices, inflating project budgets by as much as 30%. A shortage of skilled professionals hampers suppliers, as the rapid growth of the IoT sector has outpaced workforce development, causing project delays averaging six months for companies. Intense competition exists, with over 300 IoT industry associations promoting standards, complicating market entry for new players. Buyers also face challenges with regulatory compliance, which can prolong approval processes by several weeks, affecting timely project execution.
Trends in the China IoT DevOps Market
Buyers and suppliers in the China IoT DevOps Market are adjusting to the following trends.
- Shift Towards Edge Computing Solutions: China is increasingly adopting edge computing solutions for real-time processing of IoT data. The demand for such solutions is rising, with investments planned through 2025, improving operational efficiency.
- Growing Adoption of AI-Driven Applications: Smart factory operators are increasingly implementing AI-driven applications to improve operational efficiency. This trend is supported by the rising number of IoT startups in China, which has increased by 30% since 2020.
- Focus on Smart City Initiatives: The Chinese government has invested 100 billion yuan in smart city initiatives, boosting IoT adoption. This investment is expected to drive the integration of IoT technologies across urban infrastructure.
- Expansion of CI/CD Platforms: CI/CD platforms are becoming essential for automating software delivery in IoT applications. Over 70% of IoT device makers in China are utilising these platforms to streamline their development processes.
Investment Opportunities in the China IoT DevOps Market
Investors looking at the China IoT DevOps Market should consider the following areas.
- Investment in Smart Manufacturing Facilities: With China's smart factory sector projected to grow, there is a pressing need for advanced IoT DevOps solutions. Investing in this area could yield substantial returns, especially for system integrators.
- Supply of Edge Computing Solutions: The rising demand for edge computing solutions presents an opportunity for suppliers to enter the market. Focusing on partnerships with smart factory operators can facilitate market entry and growth.
- Development of AI-Driven IoT Applications: The increasing adoption of AI-driven applications in IoT creates a significant opportunity for tech consultants. Investing in this area can help meet the growing demand for intelligent data processing solutions.
- Provision of CI/CD Platforms: The growing reliance on CI/CD platforms by IoT device makers indicates a strong market opportunity. Suppliers can enter by offering tailored solutions to improve software delivery processes.
Government Initiatives in the China IoT DevOps Market
In 2021, the Ministry of Industry and Information Technology launched the 'IoT Development Action Plan' to improve IoT integration across industries, focusing on innovation and standards. This plan aims to increase the number of IoT applications in urban management and manufacturing. The National Development and Reform Commission issued the 'Guidelines for Promoting the Development of the IoT Industry' in 2022, targeting a 15% annual growth in IoT applications. In 2023, the Ministry of Science and Technology allocated 50 billion yuan for IoT research and development projects to support innovation in the sector. The State Administration for Market Regulation updated standards for IoT device safety and interoperability in 2022, impacting manufacturers and developers.
In 2023, the Ministry of Science and Technology allocated 50 billion yuan for IoT research and development projects to support innovation in the sector. The National Development and Reform Commission oversees these initiatives, ensuring that funding is directed toward projects that enhance IoT capabilities and infrastructure.
Future Insight of the China IoT DevOps Market
The China IoT DevOps market will evolve significantly by 2032, driven by initiatives like the 'IoT Development Action Plan' and the 'Digital China' strategy, which focus on improving infrastructure. The smart factory sector is expected to expand, with the number of IoT devices projected to increase to over 1.5 billion. Investments in edge computing solutions will enhance data processing capabilities. Collaborations between public and private sectors will encourage innovation, creating a more dynamic environment that benefits both buyers and suppliers.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Platform Type – CI/CD Platforms Dominated, Monitoring Tools Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, with a 40% revenue share in 2025, CI/CD Platforms was the largest platform type category. CI/CD platforms hold the largest market share as they are essential for automating software delivery in IoT applications. Their widespread adoption among over 70% of IoT device makers in China underscores their critical role in streamlining development processes. Monitoring Tools are set to record the highest CAGR in this split, 8.7% over 2026–2032. Monitoring tools are experiencing rapid growth due to the increasing necessity for tracking device performance and operational metrics. The surge in IoT device installations, surpassing 1 billion in 2022, significantly fuels this demand. Suppliers should focus on enhancing monitoring capabilities to meet the growing requirements of IoT device makers.
By Deployment Mode – Cloud Dominated, Edge Expected to Grow Fastest
Cloud took a 42% share of deployment mode in 2025, more than any other category. Cloud deployment leads the market as it provides scalable storage and processing capabilities for vast amounts of IoT data. This approach is particularly preferred in smart manufacturing and urban infrastructure projects across China. Edge is projected to grow fastest, at a CAGR of 8.3% during 2026–2032. Edge deployment is witnessing swift growth as it enables real-time processing of IoT data close to its source, which is crucial for applications requiring immediate responsiveness. The rising demand for edge computing solutions is a key factor in this trend. Buyers should consider integrating edge solutions to boost the efficiency of their IoT operations.
By Toolset Type – Proprietary Dominated, AI-Driven Expected to Grow Fastest
In 2025, Proprietary led the toolset type split with a 39% share. Proprietary tools dominate the market because they offer specialised features and dedicated support tailored for IoT environments. Their effectiveness in addressing specific operational needs makes them highly attractive to users. Over 2026–2032, AI-Driven is expected to post the fastest growth, at a CAGR of 9.2%. AI-driven tools are gaining popularity rapidly as they enhance IoT applications through intelligent data processing and analysis. The increasing adoption of AI technologies across various sectors in China significantly contributes to this trend. Suppliers must invest in AI capabilities to maintain competitiveness in the evolving IoT DevOps market.
By End User – IoT Device Makers Dominated, Smart Factory Operators Expected to Grow Fastest
The largest end user category in 2025 was IoT Device Makers, with a 41% share of total revenue. IoT device makers account for the largest share as they are the primary users of IoT DevOps for product development. Their vital role in the expanding IoT ecosystem highlights the necessity for efficient development practices. The quickest growth will come from Smart Factory Operators, forecast to expand at a CAGR of 8.9% between 2026 and 2032. Smart factory operators are the fastest-growing segment as they leverage IoT DevOps to improve operational efficiency and automation. The anticipated growth in the smart factory sector is a major driver of this demand. Suppliers should tailor their offerings to address the specific needs of smart factory operators for optimal market penetration.
By Distribution Channel – DevOps Vendors Dominated and Is Expected to Record the Fastest Growth
DevOps Vendors held a 35% share of the China IoT DevOps Market by distribution channel in 2025. DevOps vendors lead the market as they provide essential tools and platforms for IoT DevOps. Their established presence and expertise in the field make them the preferred choice for many organisations. Its lead should widen, with a projected CAGR of 9.7% during 2026–2032, the highest in this split. DevOps vendors are also the fastest-growing channel, benefiting from the increasing demand for IoT DevOps solutions across various sectors. Their ability to adapt to market needs ensures sustained growth. Suppliers should strengthen partnerships with DevOps vendors to enhance distribution and reach in the IoT DevOps market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China IoT DevOps Market Outlook
- Market Size of China IoT DevOps Market, 2025
- Forecast of China IoT DevOps Market, 2032
- Historical Data and Forecast of China IoT DevOps Revenues & Volume for the Period 2022 - 2032F
- China IoT DevOps Market Trend Evolution
- China IoT DevOps Market Drivers and Challenges
- China IoT DevOps Price Trends
- China IoT DevOps Porter's Five Forces
- China IoT DevOps Industry Life Cycle
- Historical Data and Forecast of China IoT DevOps Market Revenues & Volume By Platform Type for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT DevOps Market Revenues & Volume By CI/CD Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT DevOps Market Revenues & Volume By Containerization Tools for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT DevOps Market Revenues & Volume By Monitoring Tools for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT DevOps Market Revenues & Volume By Automation Frameworks for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT DevOps Market Revenues & Volume By Deployment Mode for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT DevOps Market Revenues & Volume By Cloud for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT DevOps Market Revenues & Volume By Hybrid for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT DevOps Market Revenues & Volume By On-Premise for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT DevOps Market Revenues & Volume By Edge for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT DevOps Market Revenues & Volume By Toolset Type for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT DevOps Market Revenues & Volume By Open Source for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT DevOps Market Revenues & Volume By Proprietary for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT DevOps Market Revenues & Volume By AI-Driven for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT DevOps Market Revenues & Volume By Lightweight for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT DevOps Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT DevOps Market Revenues & Volume By IoT Device Makers for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT DevOps Market Revenues & Volume By System Integrators for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT DevOps Market Revenues & Volume By Smart Factory Operators for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT DevOps Market Revenues & Volume By Network Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT DevOps Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT DevOps Market Revenues & Volume By DevOps Vendors for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT DevOps Market Revenues & Volume By SaaS Marketplaces for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT DevOps Market Revenues & Volume By Tech Consultants for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT DevOps Market Revenues & Volume By Online Platforms for the Period 2022 - 2032F
- China IoT DevOps Import Export Trade Statistics
- Market Opportunity Assessment By Platform Type
- Market Opportunity Assessment By Deployment Mode
- Market Opportunity Assessment By Toolset Type
- Market Opportunity Assessment By End User
- Market Opportunity Assessment By Distribution Channel
- China IoT DevOps Top Companies Market Share
- China IoT DevOps Competitive Benchmarking By Technical and Operational Parameters
- China IoT DevOps Company Profiles
- China IoT DevOps Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Platform Type
- CI/CD Platforms
- Containerization Tools
- Monitoring Tools
- Automation Frameworks
By Deployment Mode
- Cloud
- Hybrid
- On-Premise
- Edge
By Toolset Type
- Open Source
- Proprietary
- AI-Driven
- Lightweight
By End User
- IoT Device Makers
- System Integrators
- Smart Factory Operators
- Network Providers
By Distribution Channel
- DevOps Vendors
- SaaS Marketplaces
- Tech Consultants
- Online Platforms































