China IoT in Packaging Market Size & Growth Rate
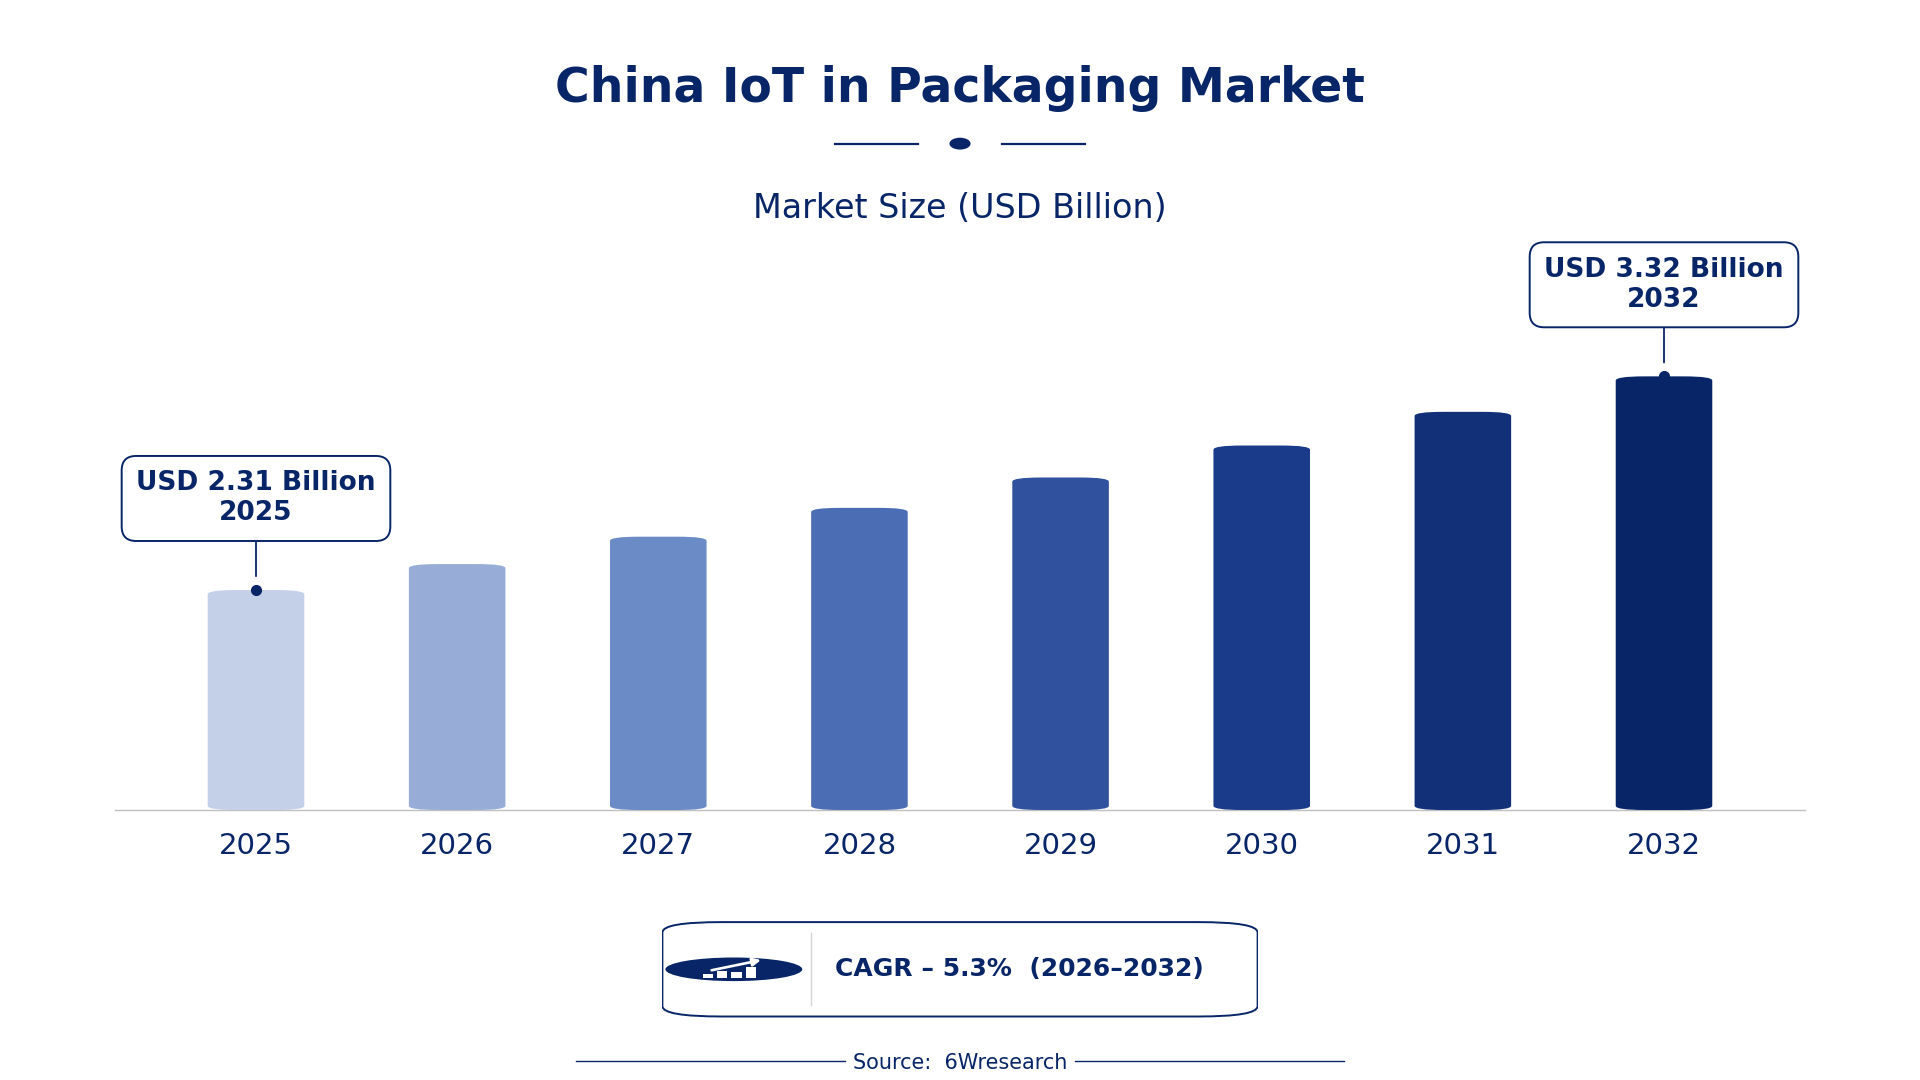
According to 6Wresearch internal database and industry insights, the China IoT in Packaging Market was valued at USD 2.31 billion in 2025 and is projected to reach USD 3.32 billion by 2032, growing at a CAGR of approximately 5.3% during 2026–2032.
China IoT in Packaging Market Highlights
| Report Metric | Details |
| Report Name | China IoT in Packaging Market |
| Market Size 2025 | USD 2.31 billion |
| Market Size 2032 | USD 3.32 billion |
| Absolute Growth 2025–2032 | USD 1.01 billion |
| CAGR 2026–2032 | 5.3% |
| Peak Annual Growth | 7.1% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Packaging Type, 2025 | Smart Labels (48% share) |
| Leading IoT Feature, 2025 | RFID (45% share) |
| Leading Sensor Type, 2025 | Thermistors (49% share) |
| Leading Application Area, 2025 | Food Safety (45% share) |
| Leading End User, 2025 | E-commerce Retailers (47% share) |
| Fastest-Growing Packaging Type | Connected Packaging (6.6% CAGR) |
| Fastest-Growing Sensor Type | Proximity Sensors (7.2% CAGR) |
| Fastest-Growing Application Area | Logistics Visibility (6.4% CAGR) |
| Fastest-Growing End User | FMCG Companies (8.0% CAGR) |
| Growing Sector | E-commerce |
| Key End Users | E-commerce Retailers, FMCG Companies, Retailers |
China IoT in Packaging Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
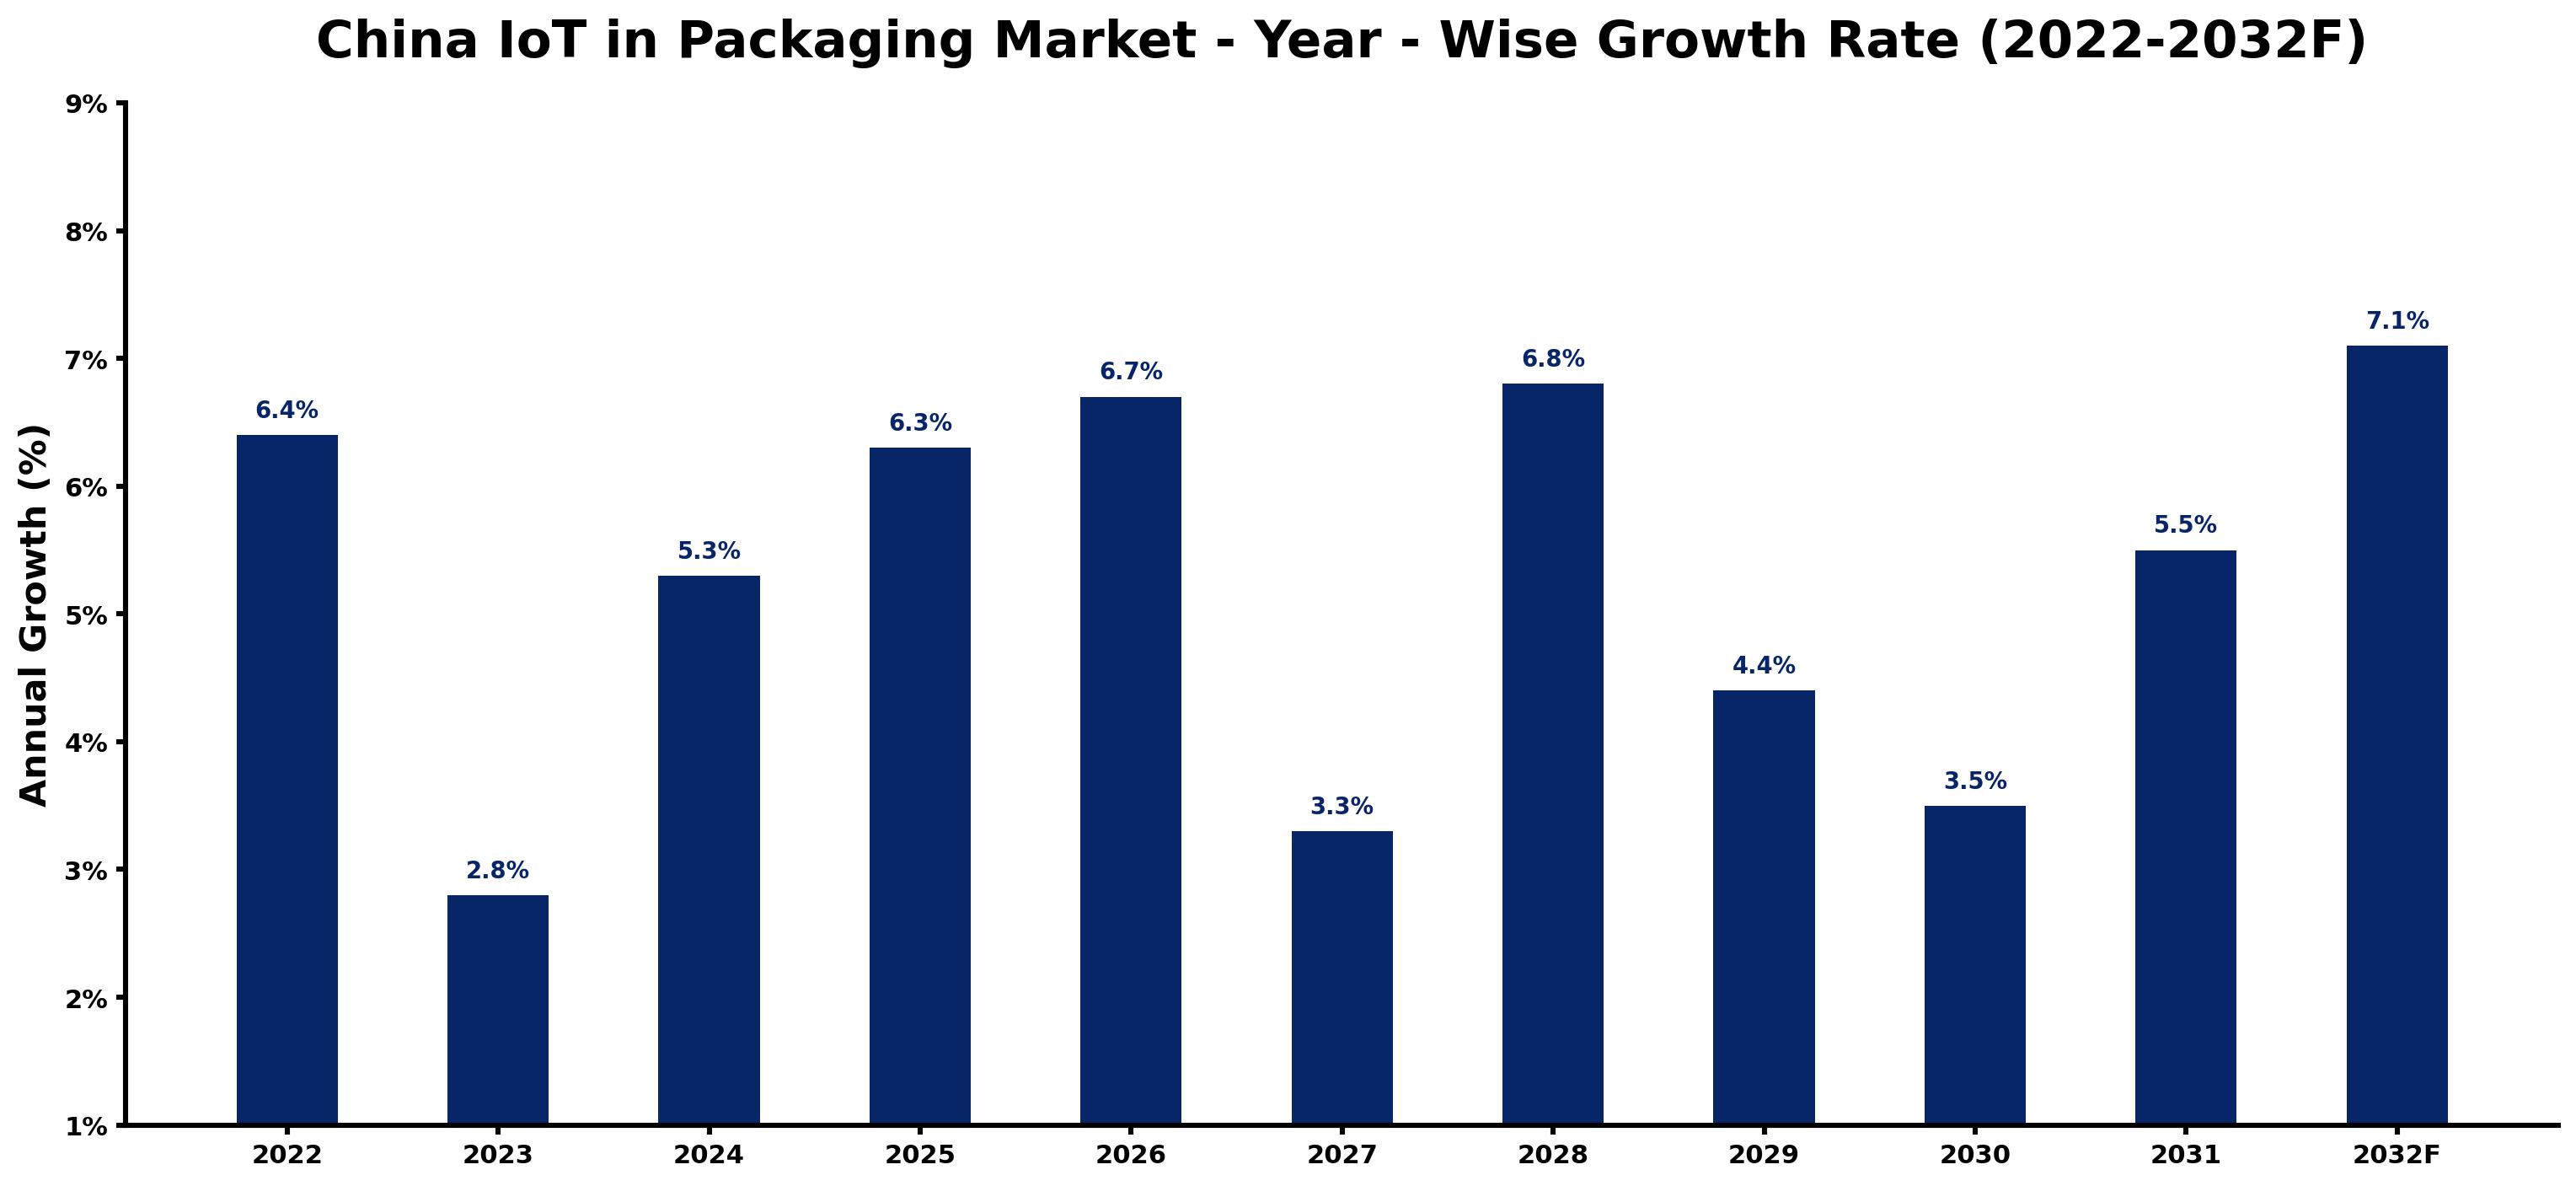
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.4 | The market experienced strong growth due to rising demand for smart packaging solutions. |
| 2023 | 2.8 | Growth slowed as the market adjusted to new standards and consumer preferences. |
| 2024 | 5.3 | Increased investment in IoT technology spurred faster growth compared to the previous year. |
| 2025 | 6.3 | Demand surged as e-commerce retailers increasingly adopted IoT packaging solutions. |
| 2026 | 6.7 | Growth continued as logistics improvements drove demand for advanced packaging features. |
| 2027 | 3.3 | The market saw a slowdown as competition intensified among packaging providers. |
| 2028 | 6.8 | Growth accelerated again with rising consumer interest in smart packaging innovations. |
| 2029 | 4.4 | The market slowed as regulatory challenges impacted the adoption of new technologies. |
| 2030 | 3.5 | Growth decelerated due to the introduction of the Smart Packaging Initiative, which requires compliance with new standards. |
| 2031 | 5.5 | An increase in FMCG companies adopting IoT solutions led to faster growth. |
| 2032 | 7.1 | The market is expected to peak as logistics demand drives further IoT integration. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China IoT in Packaging Market Synopsis
IoT in Packaging in China involves the integration of Internet of Things technology into packaging solutions, enabling real-time data collection and communication. This technology improves supply chain visibility, ensures product safety, and enhances consumer engagement. The China IoT in Packaging Market is expanding due to the booming e-commerce sector and rising consumer spending on smart packaging features. In 2022, the smart packaging market was valued at approximately $3 billion, with substantial growth anticipated as logistics demands increase and technology adoption broadens.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising e-commerce adoption drives demand for innovative packaging solutions. | Driver | High | Smart Labels |
| Increased consumer spending on products with smart packaging features boosts market growth. | Driver | High | Connected Packaging |
| The growing food safety sector creates opportunities for IoT-enabled packaging solutions. | Opportunity | High | Food Safety |
| The Guangdong province's leadership in packaging innovation presents investment opportunities. | Opportunity | High | Logistics Visibility |
| Regulatory challenges surrounding packaging standards may hinder market growth. | Restraint | High | Trackable Packaging |
| High costs associated with IoT technology implementation can limit adoption. | Restraint | Medium | Condition-Aware Boxes |
| Competition among packaging providers is intensifying, affecting pricing strategies. | Challenge | High | Smart Labels |
| Technological integration issues can delay the adoption of IoT solutions. | Challenge | Medium | Connected Packaging |
Evaluation of Drivers in China IoT in Packaging Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased investment in smart packaging technology boosts supply chain efficiency. | Smart Labels | In 2023, the logistics industry is projected to reach $1 trillion, driving demand for smart labels. |
| Growing consumer preference for products with safety features drives demand. | Connected Packaging | The average consumer spends 30% more on products with smart packaging features. |
| The food safety sector's regulatory requirements necessitate IoT solutions for compliance. | Food Safety | The National Food Safety Standards ensure that packaging meets health regulations. |
| E-commerce growth necessitates improved logistics and packaging solutions. | Logistics Visibility | China's logistics industry is projected to grow to $1 trillion by 2025, increasing the need for IoT solutions. |
| Technological advancements in IoT are creating new packaging opportunities. | Trackable Packaging | The Shanghai International Packaging Exhibition 2023 showcased over 200 IoT packaging innovations. |
Market growth for IoT in Packaging in China is underpinned by increased investment in smart packaging technology, which boosts supply chain efficiency. In 2023, the logistics industry is projected to reach $1 trillion, driving demand for smart labels. Consumer preference for products with safety features drives demand, as the average consumer spends 30% more on products with smart packaging features. E-commerce growth requires improved logistics and packaging solutions, with increasing demand for trackable packaging innovations.
Evaluation of Restraints in China IoT in Packaging Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Regulatory challenges surrounding packaging standards may hinder market growth. | Trackable Packaging | The State Administration for Market Regulation updated standards, complicating compliance for producers. |
| High costs associated with IoT technology implementation can limit adoption. | Condition-Aware Boxes | Producers face investment costs that can deter smaller companies from adopting IoT solutions. |
| Intense competition among packaging providers is affecting pricing strategies. | Smart Labels | Increased competition leads to price wars, impacting profit margins for manufacturers. |
| Technological integration issues can delay the adoption of IoT solutions. | Connected Packaging | Many producers struggle with integrating new technologies into existing systems, causing delays. |
| Market saturation in certain segments may limit growth potential. | Logistics Visibility | As more companies adopt IoT solutions, the market may face diminishing returns on investment. |
China IoT in Packaging Market Challenges
Producers in the China IoT in Packaging market encounter significant costs from advanced technology integration, which can raise production expenses by 25%. Compliance with the National Food Safety Standards introduces regulatory complexities, delaying product launches and hindering market access for new entrants. Many smaller producers struggle with slow technology adoption, limiting their competitiveness and forcing buyers to rely on larger firms. Additionally, the overall cost of smart packaging solutions can deter buyers, who typically pay 30% more for products with these features, negatively impacting sales for those unable to invest.
Trends in the China IoT in Packaging Market
Four trends stand out in the China IoT in Packaging Market.
- Shift Towards Smart Labels in E-commerce: The Guangdong province is leading the shift towards smart labels in e-commerce packaging, with a projected 15% increase in adoption among FMCG companies by 2023. This trend enhances logistics visibility and consumer engagement.
- E-commerce Retailers Prioritising IoT Solutions: E-commerce retailers are increasingly prioritising IoT solutions to improve customer experience, with 47% of the market share expected by 2025. This shift supports the demand for enhanced packaging features.
- Smart Packaging Standards Evolving: The National Development and Reform Commission's 'Green Packaging Development Plan' is evolving to include IoT technologies, aiming for a 20% reduction in packaging waste by 2025. This development encourages sustainable practices among producers.
- Increased Focus on Food Safety: The food safety sector is experiencing increased focus on IoT-enabled packaging solutions, driven by stringent regulations. In 2023, the National Food Safety Standards are expected to improve compliance for producers.
Investment Opportunities in the China IoT in Packaging Market
Several openings in the China IoT in Packaging Market merit attention from investors.
- Timing for Investment in Smart Packaging: With the logistics industry projected to reach $1 trillion by 2025, there is an opportunity to invest in smart packaging solutions. E-commerce retailers are actively seeking options to enhance their supply chains.
- FMCG Companies Seeking IoT Solutions: FMCG companies are increasingly looking for IoT-enabled packaging to improve product tracking and safety. With a projected 8.0% growth rate, investing in this sector offers substantial growth potential.
- Guangdong Province as a Hub for Innovation: Guangdong province is emerging as a hub for packaging innovation, providing opportunities for suppliers to collaborate with local manufacturers. The region's focus on smart packaging solutions is driving demand.
- Supply of Condition-Aware Boxes: Now is the time to supply condition-aware boxes as the market for temperature-sensitive products grows. The food safety sector's regulatory requirements create a strong demand for these solutions.
Government Initiatives in the China IoT in Packaging Market
The Ministry of Industry and Information Technology launched the '14th Five-Year Plan for Smart Manufacturing' in 2021 to promote IoT adoption in packaging. This plan aims to integrate advanced technologies into production processes. Additionally, the State Administration for Market Regulation updated the 'National Standards for Packaging Materials' in 2022 to include IoT technology, ensuring that packaging meets modern requirements. These measures are designed to support the growth of the IoT in Packaging market in China, encouraging innovation and compliance.
In 2023, the Smart Packaging Initiative was launched by the Ministry of Industry and Information Technology, promoting the adoption of IoT in packaging solutions. This initiative aims to improve industry standards and support innovation. The China National Institute of Standardization published guidelines for IoT-enabled packaging to ensure compliance with safety regulations. These efforts are vital for producers and buyers to ensure their packaging meets the latest standards, facilitating market growth.
Future Insight of the China IoT in Packaging Market
The IoT in Packaging market in China is poised for transformation by 2032, driven by the Smart Packaging Initiative initiated in 2023. This initiative will facilitate better integration within the supply chain, leading to improved efficiency and reduced waste. By 2025, the logistics industry is projected to reach $1 trillion, which will significantly increase demand for IoT solutions. National standards set forth in GB/T 40878-2021 will simplify compliance, providing benefits for producers and buyers by ensuring consistent quality and safety in packaging.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Packaging Type – Smart Labels Dominated, Connected Packaging Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, in 2025, Smart Labels led the packaging type split with a 48% share. Smart Labels dominate the market share due to their ability to provide real-time tracking and information, which is vital for sectors like e-commerce and logistics. Their extensive adoption in innovative regions such as Guangdong highlights their importance in enhancing operational efficiency. Connected Packaging is set to record the highest CAGR in this split, 6.6% over 2026–2032. Connected Packaging is growing rapidly as it fosters enhanced consumer interaction and brand engagement, driven by the rising demand for personalised shopping experiences. The 2023 'Smart Packaging Initiative' is set to further accelerate this growth, solidifying its position in the market. Suppliers should focus on developing advanced smart packaging solutions to meet the increasing demand from both consumers and businesses.
By IoT Feature – RFID Dominated and Is Expected to Record the Fastest Growth
RFID took a 45% share of iot feature in 2025, more than any other category. RFID technology commands the largest market share due to its extensive use in inventory management and tracking, especially within the logistics sector. Its widespread adoption highlights the critical need for efficient supply chain solutions in China. RFID is also forecast to expand faster than any other category, at a CAGR of 7.5% over 2026–2032. RFID is also the fastest-growing feature, essential for automating inventory processes as China's logistics industry approaches a projected $1 trillion by 2025. Its dual role as both leader and fastest indicates a strengthening market position. Buyers should invest in RFID solutions to improve operational efficiency and maintain competitiveness in the evolving market.
By Sensor Type – Thermistors Dominated, Proximity Sensors Expected to Grow Fastest
With a 49% revenue share in 2025, Thermistors was the largest sensor type category. Thermistors lead this segment as they are vital for temperature monitoring, ensuring compliance with health regulations in food safety applications. Their role in maintaining product integrity makes them a preferred choice among manufacturers. The quickest growth will come from Proximity Sensors, forecast to expand at a CAGR of 7.2% between 2026 and 2032. Proximity Sensors are rapidly growing as they are increasingly integrated into automated systems for detecting packaging presence, streamlining operations. This growth reflects the industry's shift towards automation in packaging processes. Suppliers should expand their sensor offerings to include more automation-friendly solutions to capture emerging opportunities.
By Application Area – Food Safety Dominated, Logistics Visibility Expected to Grow Fastest
The largest application area category in 2025 was Food Safety, with a 45% share of total revenue. Food Safety leads the application area, essential for ensuring compliance with health regulations in food packaging, thereby safeguarding consumer trust. The strict regulatory framework in China significantly boosts the demand for smart packaging solutions in this critical sector. Over 2026–2032, Logistics Visibility is expected to post the fastest growth, at a CAGR of 6.4%. Logistics Visibility is the fastest-growing application area, fuelled by the urgent need for enhanced supply chain efficiency and tracking capabilities as e-commerce continues to expand. This trend is in line with the logistics industry's anticipated growth to $1 trillion by 2025, indicating a strong market opportunity. Companies should invest in solutions that improve logistics visibility to optimise their supply chain operations effectively.
By End User – E-commerce Retailers Dominated, FMCG Companies Expected to Grow Fastest
E-commerce Retailers accounted for a 47% market share by end user in 2025. E-commerce Retailers constitute the largest end-user segment, heavily relying on IoT packaging to improve logistics and enhance customer experience. The surge in online shopping in China has significantly increased the demand for smart packaging solutions tailored to this sector. FMCG Companies are set to record the highest CAGR in this split, 8.0% over 2026–2032. FMCG Companies are the fastest-growing end-user group, increasingly adopting IoT-enabled packaging for efficient product tracking and management. This trend reflects a significant shift towards digitisation in the FMCG sector, indicating a growing market potential. Suppliers must customise their offerings to address the specific requirements of FMCG companies to leverage this growth opportunity.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China IoT in Packaging Market Outlook
- Market Size of China IoT in Packaging Market, 2025
- Forecast of China IoT in Packaging Market, 2032
- Historical Data and Forecast of China IoT in Packaging Revenues & Volume for the Period 2022 - 2032F
- China IoT in Packaging Market Trend Evolution
- China IoT in Packaging Market Drivers and Challenges
- China IoT in Packaging Price Trends
- China IoT in Packaging Porter's Five Forces
- China IoT in Packaging Industry Life Cycle
- Historical Data and Forecast of China IoT in Packaging Market Revenues & Volume By Packaging Type for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT in Packaging Market Revenues & Volume By Smart Labels for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT in Packaging Market Revenues & Volume By Connected Packaging for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT in Packaging Market Revenues & Volume By Trackable Packaging for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT in Packaging Market Revenues & Volume By Condition-Aware Boxes for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT in Packaging Market Revenues & Volume By IoT Feature for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT in Packaging Market Revenues & Volume By Temp Logging for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT in Packaging Market Revenues & Volume By QR/NFC for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT in Packaging Market Revenues & Volume By RFID for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT in Packaging Market Revenues & Volume By Shock + Temp Sensors for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT in Packaging Market Revenues & Volume By Sensor Type for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT in Packaging Market Revenues & Volume By Thermistors for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT in Packaging Market Revenues & Volume By Proximity Sensors for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT in Packaging Market Revenues & Volume By Location Tags for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT in Packaging Market Revenues & Volume By Accelerometers for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT in Packaging Market Revenues & Volume By Application Area for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT in Packaging Market Revenues & Volume By Food Safety for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT in Packaging Market Revenues & Volume By Brand Engagement for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT in Packaging Market Revenues & Volume By Logistics Visibility for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT in Packaging Market Revenues & Volume By Electronics Packaging for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT in Packaging Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT in Packaging Market Revenues & Volume By FMCG Companies for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT in Packaging Market Revenues & Volume By Retailers for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT in Packaging Market Revenues & Volume By E-commerce Retailers for the Period 2022 - 2032F
- Historical Data and Forecast of China IoT in Packaging Market Revenues & Volume By Appliance OEMs for the Period 2022 - 2032F
- China IoT in Packaging Import Export Trade Statistics
- Market Opportunity Assessment By Packaging Type
- Market Opportunity Assessment By IoT Feature
- Market Opportunity Assessment By Sensor Type
- Market Opportunity Assessment By Application Area
- Market Opportunity Assessment By End User
- China IoT in Packaging Top Companies Market Share
- China IoT in Packaging Competitive Benchmarking By Technical and Operational Parameters
- China IoT in Packaging Company Profiles
- China IoT in Packaging Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Packaging Type
- Smart Labels
- Connected Packaging
- Trackable Packaging
- Condition-Aware Boxes
By IoT Feature
- Temp Logging
- QR/NFC
- RFID
- Shock + Temp Sensors
By Sensor Type
- Thermistors
- Proximity Sensors
- Location Tags
- Accelerometers
By Application Area
- Food Safety
- Brand Engagement
- Logistics Visibility
- Electronics Packaging
By End User
- FMCG Companies
- Retailers
- E-commerce Retailers
- Appliance OEMs































