China Semiconductor Etchant / Etchants Market Size & Growth Rate
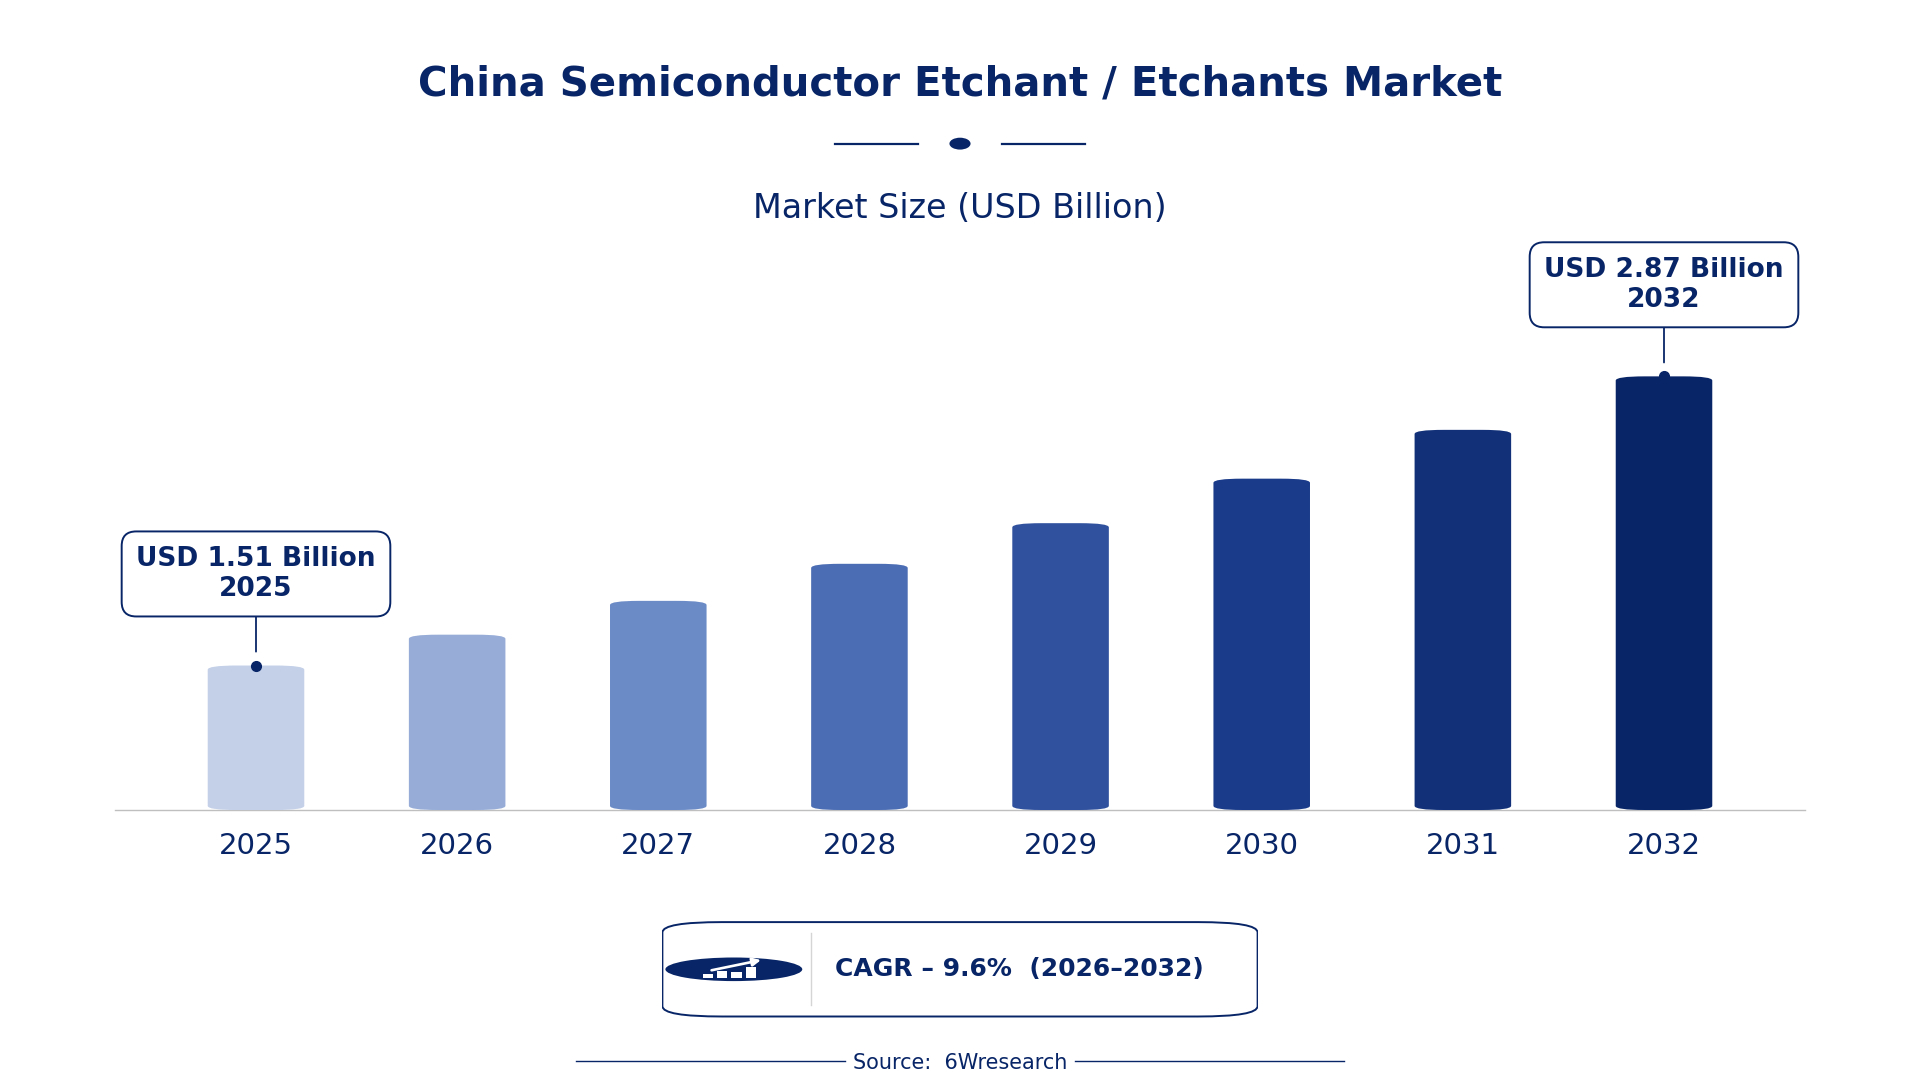
According to 6Wresearch internal database and industry insights, the China Semiconductor Etchant / Etchants Market was valued at USD 1.51 billion in 2025 and is projected to reach USD 2.87 billion by 2032, growing at a CAGR of approximately 9.6% during 2026–2032.
China Semiconductor Etchant / Etchants Market Highlights
| Report Metric | Details |
| Report Name | China Semiconductor Etchant / Etchants Market |
| Market Size 2025 | USD 1.51 billion |
| Market Size 2032 | USD 2.87 billion |
| Absolute Growth 2025–2032 | USD 1.36 billion |
| CAGR 2026–2032 | 9.6% |
| Peak Annual Growth | 11.8% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Etchant Type, 2025 | Wet Etchants (38% share) |
| Leading Target Material, 2025 | Silicon/Oxides (48% share) |
| Leading Application Type, 2025 | Wet Bench Etching (39% share) |
| Leading End User, 2025 | Foundries (49% share) |
| Fastest-Growing Etchant Type | Selective Etchants (10.7% CAGR) |
| Fastest-Growing Target Material | Metal Layers (11.4% CAGR) |
| Fastest-Growing Application Type | Plasma Etching (11.1% CAGR) |
| Fastest-Growing End User | Advanced Node Fabs (10.6% CAGR) |
| Growing Sector | Semiconductor manufacturing |
| Key End Users | Foundries, Memory Device Makers, Advanced Node Fabs |
China Semiconductor Etchant / Etchants Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
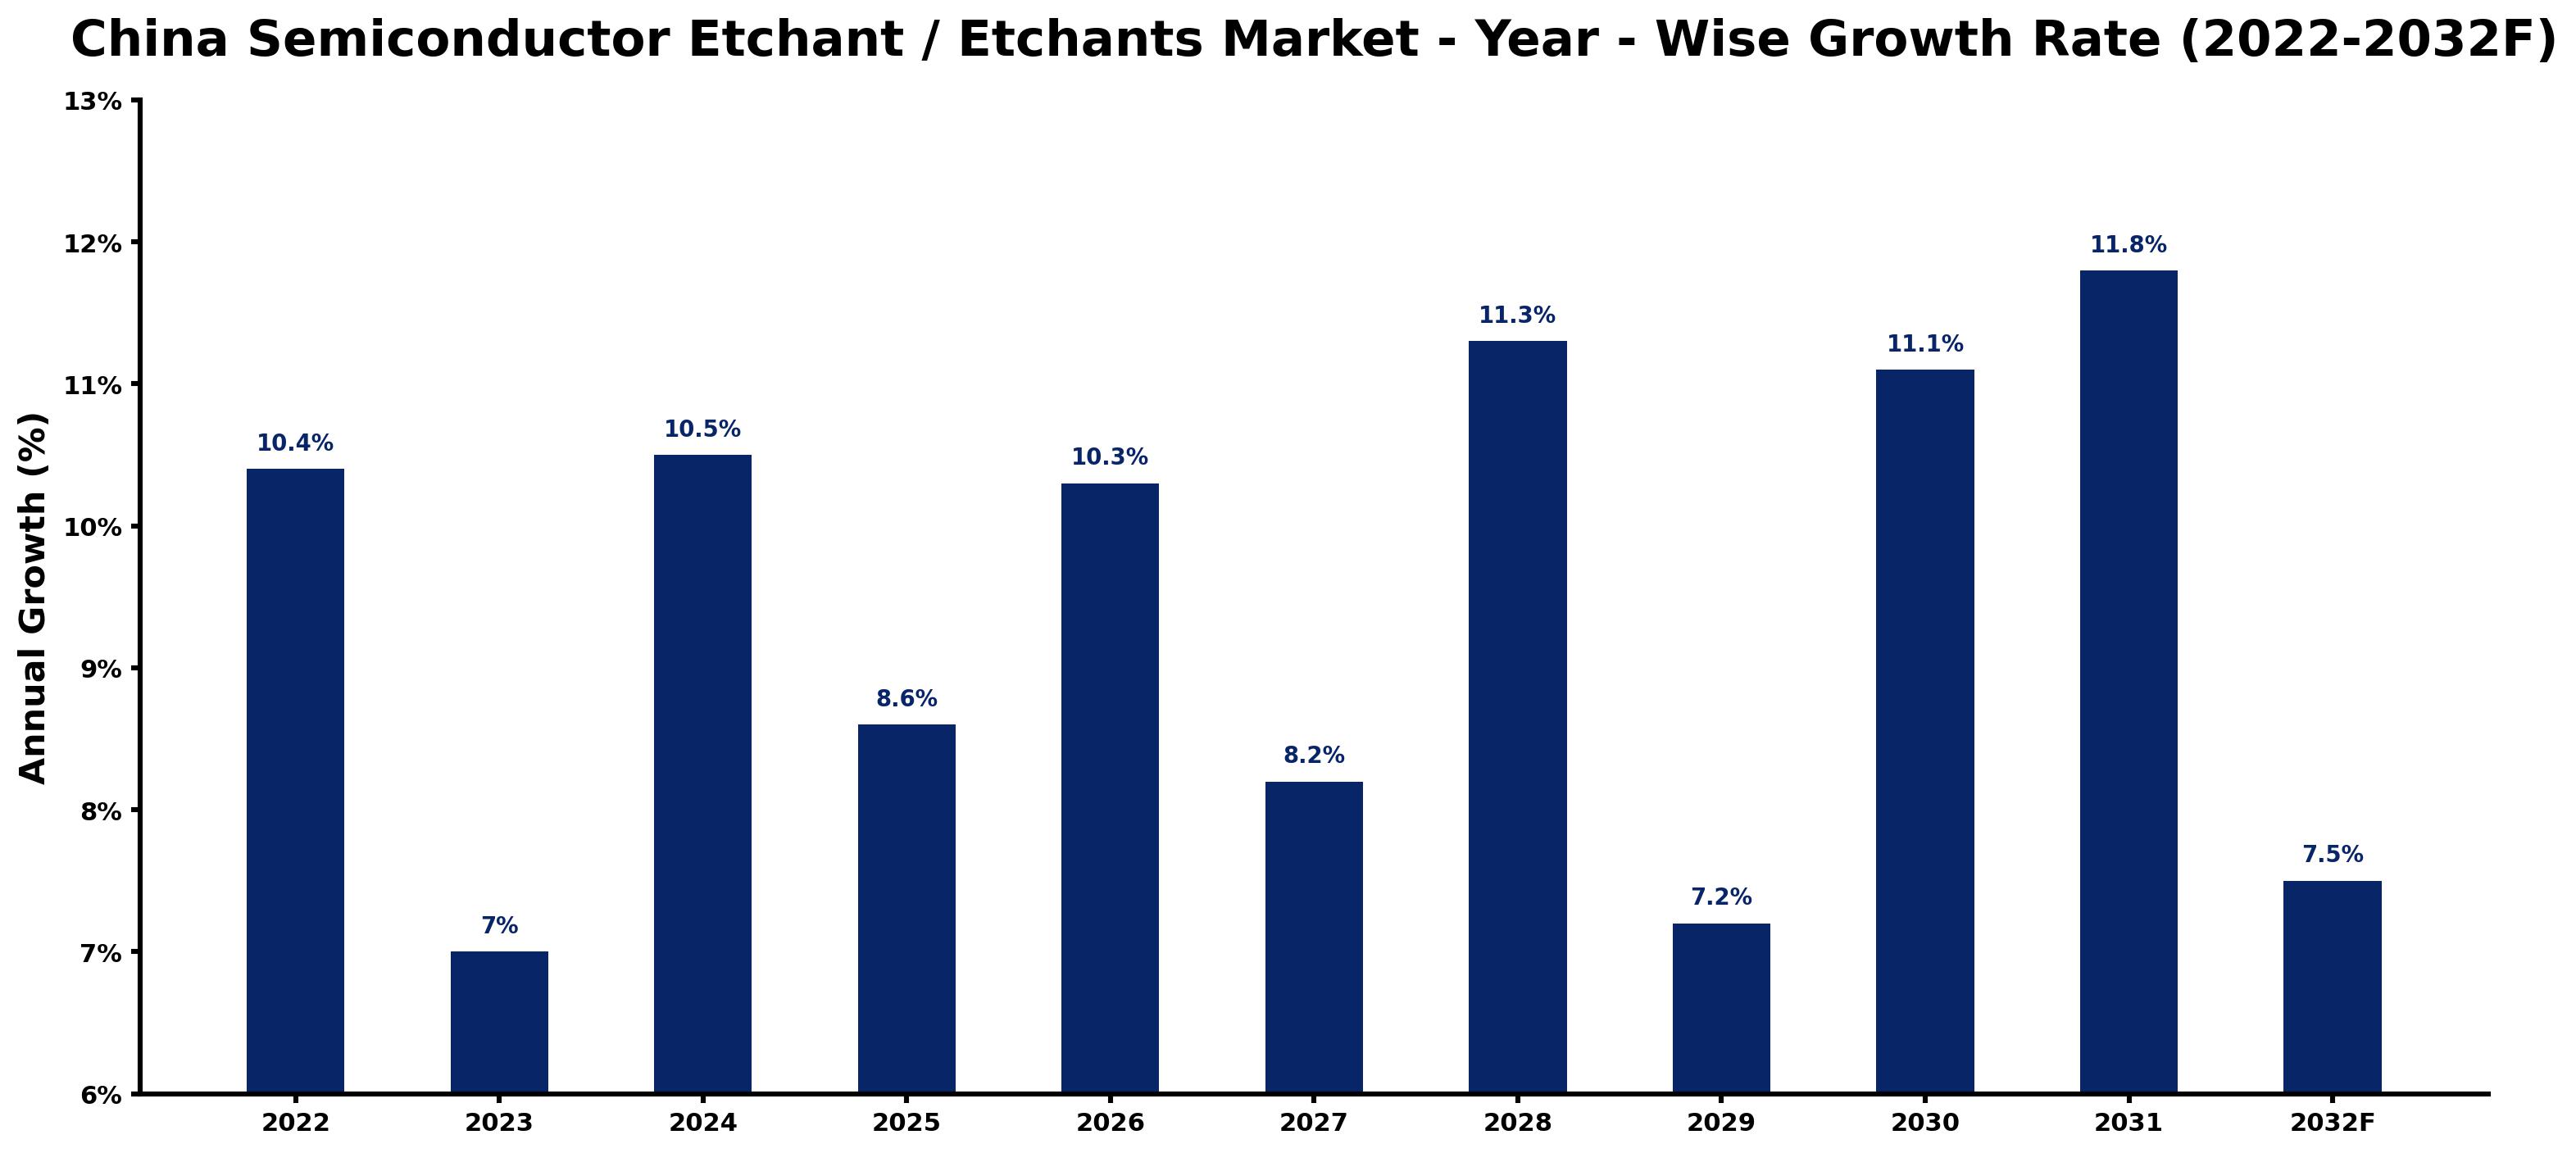
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 10.4 | The semiconductor industry experienced strong domestic production and exports, driving demand. |
| 2023 | 7.0 | Growth slowed as the market adjusted to the impacts of the Integrated Circuit Industry Development Action Plan. |
| 2024 | 10.5 | Demand surged with increased investments in semiconductor manufacturing capabilities across the country. |
| 2025 | 8.6 | The market continued to grow, supported by ongoing advancements in semiconductor technology. |
| 2026 | 10.3 | Growth accelerated due to rising demand for advanced semiconductor devices in various sectors. |
| 2027 | 8.2 | A slowdown occurred as the market stabilised amidst increased competition in semiconductor production. |
| 2028 | 11.3 | Demand rebounded with significant investments in research and development for semiconductor technologies. |
| 2029 | 7.2 | The growth rate slowed, reflecting market adjustments following previous years of rapid expansion. |
| 2030 | 11.1 | Demand increased again as new technologies in semiconductor fabrication gained traction. |
| 2031 | 11.8 | The market peaked with high demand for cutting-edge semiconductor solutions in various applications. |
| 2032 | 7.5 | Growth slowed as the market began to stabilise after reaching its peak. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Semiconductor Etchant / Etchants Market Synopsis
The Semiconductor Etchant / Etchants Market in China includes chemical solutions essential for semiconductor device fabrication. These etchants selectively remove material layers from wafer surfaces, facilitating the patterning of integrated circuits and the cleaning of wafers. The market is expanding due to strong domestic production and increasing demand for electronic devices, supported by a population of over 1.4 billion. In 2022, the semiconductor industry generated around 1 trillion yuan in chip production, highlighting the strength of this sector.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased domestic semiconductor production capabilities | Driver | High | Wet Etchants |
| Growing demand for advanced semiconductor devices | Driver | High | Dry Etchants |
| Investment in semiconductor manufacturing facilities | Opportunity | High | Selective Etchants |
| Expansion of semiconductor research and development | Opportunity | High | Buffered HF |
| High costs associated with advanced etching equipment | Restraint | High | Plasma Etching |
| Strict regulatory compliance for semiconductor materials | Restraint | Medium | Oxide Etching |
| Supply chain disruptions affecting material availability | Challenge | High | Cleaning and Etching |
| Skilled labor shortages in semiconductor fabrication | Challenge | Medium | Foundries |
Evaluation of Drivers in China Semiconductor Etchant / Etchants Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increasing domestic semiconductor production | Wet Etchants | This increase in production drives higher demand for etchants, with the industry producing approximately 1 trillion yuan worth of chips in 2022. |
| Investment in advanced semiconductor technologies | Dry Etchants | Investment in new technologies leads to greater usage of dry etchants, essential for plasma etching techniques in modern fabs. |
| Expansion of semiconductor manufacturing capacity | Selective Etchants | The establishment of new manufacturing facilities boosts the demand for selective etchants, necessary for targeted etching processes. |
| Increased focus on R&D in semiconductor technologies | Buffered HF | Investments in research and development increase the need for buffered HF, commonly used for oxide layer removal. |
| Growing consumption of electronic devices | Plasma Etching | The demand for electronic devices drives the need for plasma etching, vital for precise etching in semiconductor manufacturing. |
Growth across the Semiconductor Etchant / Etchants market in China is anchored in rising domestic semiconductor production, increasing investment in advanced technologies, and expanding manufacturing capacity. In 2022, the semiconductor industry produced approximately 1 trillion yuan worth of chips, creating a strong demand for etchants. The establishment of new manufacturing facilities boosts the need for selective etchants, which are necessary for targeted etching processes. The growing consumption of electronic devices drives demand for plasma etching, essential for precise etching in modern fabs. Investments in research and development further support the market, as companies seek to innovate and improve their semiconductor technologies.
Evaluation of Restraints in China Semiconductor Etchant / Etchants Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs associated with advanced etching equipment | Plasma Etching | The investment required for advanced etching equipment limits access for smaller manufacturers, affecting their competitiveness. |
| Strict regulatory compliance for semiconductor materials | Oxide Etching | Regulatory requirements increase operational costs for producers, impacting their ability to supply etchants efficiently. |
| Supply chain disruptions affecting material availability | Cleaning and Etching | Disruptions in the supply chain can lead to delays in production schedules, affecting the availability of etchants. |
| Skilled labor shortages in semiconductor fabrication | Foundries | A lack of skilled workers hampers production capabilities, limiting the growth potential of the etchants market. |
| Limited access to advanced technology for smaller players | Selective Etchants | Smaller manufacturers struggle to adopt advanced technologies, which can restrict their market share and growth. |
China Semiconductor Etchant / Etchants Market Challenges
China's semiconductor etchants market experiences high production costs due to expensive raw materials, leading to price increases for buyers by up to 20%. Supply chain disruptions impede timely access to critical components, affecting over 30% of semiconductor foundries. The slow pace of technological advancements in etching processes restricts efficiency improvements, diminishing competitiveness for local producers. A shortage of skilled technicians in the sector compels companies to allocate up to 15% more of their budgets on training and recruitment, limiting operational capabilities and productivity.
Trends in the China Semiconductor Etchant / Etchants Market
The trends below show where the China Semiconductor Etchant / Etchants Market is heading.
- Shift towards Advanced Etching Technologies: The National Semiconductor Technology Development Strategy initiated in 2023 promotes advanced etching technologies, focusing on innovation. This shift is expected to improve production efficiency and quality, aligning with the growing demand for high-performance semiconductors.
- Increased Collaboration among Semiconductor Manufacturers: Foundries are increasingly collaborating to share resources and technology, driven by the need for efficiency. This trend has led to a 15% increase in domestic semiconductor consumption in 2022, creating a more competitive environment.
- Emergence of Eco-Friendly Etching Solutions: The semiconductor industry is moving towards eco-friendly etching solutions, with initiatives launched in 2023 promoting sustainable practices. This shift is important as manufacturers seek to reduce environmental impact while maintaining efficiency.
- Expansion of Semiconductor Manufacturing Facilities: The establishment of new semiconductor manufacturing facilities is accelerating, particularly in Jiangsu and Guangdong provinces. With over 200 foundries in China, this expansion aims to meet the increasing demand for chips.
Investment Opportunities in the China Semiconductor Etchant / Etchants Market
Investors looking at the China Semiconductor Etchant / Etchants Market should consider the following areas.
- Investment in Advanced Etching Equipment: There is an opportunity to supply advanced etching equipment, with the market projected to reach 2.87 billion USD by 2032. Foundries are particularly in need of these technologies to improve production efficiency.
- Development of Eco-Friendly Etchants: The market for eco-friendly etchants is growing, with a projected demand increase driven by sustainability initiatives. Manufacturers in Jiangsu province are looking for greener solutions to meet regulatory requirements.
- Expansion of Semiconductor R&D Facilities: The semiconductor R&D sector is expanding, with over 150 billion yuan invested since 2020. This presents opportunities for suppliers of specialized etchants tailored for research applications.
- Collaboration with Local Foundries: Local foundries are seeking partnerships to improve their etching processes, creating opportunities for suppliers. Collaborating with foundries in Guangdong province can facilitate market entry.
Government Initiatives in the China Semiconductor Etchant / Etchants Market
In 2023, the State Council introduced the 'National Semiconductor Technology Development Strategy', aimed at boosting R&D and innovation in the sector. This strategy builds on the '14th Five-Year Plan for the Integrated Circuit Industry' launched in 2022, which strengthens domestic production capabilities. Together, these measures are designed to improve the semiconductor industry's infrastructure and support local manufacturers in meeting demand for advanced technologies. The government has allocated substantial resources to ensure the success of these initiatives, creating a more competitive environment for producers.
The Ministry of Industry and Information Technology oversees the implementation of various semiconductor programs, including the 'Integrated Circuit Industry Development Action Plan'. This agency approves funding for infrastructure improvements and supports initiatives aimed at enhancing the capabilities of semiconductor manufacturers. In 2023, the government initiated the 'National Semiconductor Innovation Fund' with a budget of 50 billion yuan, facilitating investments in new technologies and supporting local production efforts.
Future Insight of the China Semiconductor Etchant / Etchants Market
Several forward-looking factors should support the semiconductor etchants market in China over the coming years. The 'Integrated Circuit Industry Development Action Plan' will streamline regulations and promote innovation in the sector. The 'National Semiconductor Innovation Fund' will boost research efforts, encouraging the development of advanced etching technologies. By 2025, the installed base of semiconductor manufacturing equipment is expected to reach 2 million units, which will improve production capacity and operational efficiency for suppliers.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Etchant Type – Wet Etchants Dominated, Selective Etchants Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, Wet Etchants took a 38% share of etchant type in 2025, more than any other category. Wet etchants hold the largest share in the market due to their critical function in cleaning and etching during semiconductor fabrication. Their extensive application across China's 200 semiconductor foundries underpins their dominance in this segment. Over 2026–2032, Selective Etchants are expected to post the fastest growth, at a CAGR of 10.7%. Selective etchants are rapidly gaining traction as they are specifically designed for targeted etching of materials in complex multi-layer structures. The increasing sophistication of semiconductor designs fuels the demand for these precise etching solutions. Suppliers should prioritise the development and distribution of selective etchants to address the rising complexity in semiconductor manufacturing.
By Target Material – Silicon/Oxides Dominated, Metal Layers Expected to Grow Fastest
Silicon/Oxides held a 48% share of the China Semiconductor Etchant / Etchants Market by target material in 2025. Silicon and oxides are fundamental materials in semiconductor manufacturing, resulting in a robust market share for etchants targeting these substances. Their extensive application across numerous foundries solidifies their leading position in the market. The quickest growth will come from Metal Layers, forecast to expand at a CAGR of 11.4% between 2026 and 2032. Metal layers are experiencing rapid growth due to their critical function in establishing interconnects within semiconductor devices. This surge in demand is propelled by the industry's shift towards more efficient etching processes in advanced technologies. Suppliers should prioritise etchants for metal layers to remain competitive in the fast-evolving semiconductor market.
By Application Type – Wet Bench Etching Dominated, Plasma Etching Expected to Grow Fastest
Wet Bench Etching accounted for a 39% market share by application type in 2025. Wet bench etching is the predominant application type, extensively utilised in semiconductor fabrication across various production facilities. Its established presence in the industry contributes significantly to its market share. Plasma Etching is set to record the highest CAGR in this split, 11.1% over 2026–2032. Plasma etching is gaining momentum as it is vital for achieving the precision required in modern fabrication environments. The increasing demand for accuracy in semiconductor manufacturing is driving its rapid adoption. Suppliers need to invest in plasma etching technologies to meet the industry's growing emphasis on precision and advanced manufacturing processes.
By End User – Foundries Dominated, Advanced Node Fabs Expected to Grow Fastest
The largest end user category in 2025 was Foundries, with a 49% share of total revenue. Foundries represent the largest consumer group of etchants, playing a pivotal role in semiconductor production across China. Their expansive operations and consistent demand for etchants ensure a commanding market share in this segment. Advanced Node Fabs are projected to grow fastest, at a CAGR of 10.6% during 2026–2032. Advanced node fabs are experiencing the fastest growth as they necessitate etchants for sophisticated semiconductor technologies that require enhanced performance. This trend towards advanced manufacturing processes underscores the need for superior etching solutions. Suppliers should focus on developing products tailored for advanced node fabs to capture the increasing demand in high-tech semiconductor production.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Semiconductor Etchant / Etchants Market Outlook
- Market Size of China Semiconductor Etchant / Etchants Market, 2025
- Forecast of China Semiconductor Etchant / Etchants Market, 2032
- Historical Data and Forecast of China Semiconductor Etchant / Etchants Revenues & Volume for the Period 2022 - 2032F
- China Semiconductor Etchant / Etchants Market Trend Evolution
- China Semiconductor Etchant / Etchants Market Drivers and Challenges
- China Semiconductor Etchant / Etchants Price Trends
- China Semiconductor Etchant / Etchants Porter's Five Forces
- China Semiconductor Etchant / Etchants Industry Life Cycle
- Historical Data and Forecast of China Semiconductor Etchant / Etchants Market Revenues & Volume By Etchant Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Etchant / Etchants Market Revenues & Volume By Wet Etchants for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Etchant / Etchants Market Revenues & Volume By Dry Etchants for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Etchant / Etchants Market Revenues & Volume By Selective Etchants for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Etchant / Etchants Market Revenues & Volume By Buffered HF for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Etchant / Etchants Market Revenues & Volume By Target Material for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Etchant / Etchants Market Revenues & Volume By Silicon/Oxides for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Etchant / Etchants Market Revenues & Volume By Metal Layers for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Etchant / Etchants Market Revenues & Volume By Layer-Specific for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Etchant / Etchants Market Revenues & Volume By Oxide Etching for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Etchant / Etchants Market Revenues & Volume By Application Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Etchant / Etchants Market Revenues & Volume By Wet Bench Etching for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Etchant / Etchants Market Revenues & Volume By Plasma Etching for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Etchant / Etchants Market Revenues & Volume By Critical Dimension Control for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Etchant / Etchants Market Revenues & Volume By Cleaning and Etching for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Etchant / Etchants Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Etchant / Etchants Market Revenues & Volume By Foundries for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Etchant / Etchants Market Revenues & Volume By Memory Device Makers for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Etchant / Etchants Market Revenues & Volume By Advanced Node Fabs for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Etchant / Etchants Market Revenues & Volume By Wafer Processing Plants for the Period 2022 - 2032F
- China Semiconductor Etchant / Etchants Import Export Trade Statistics
- Market Opportunity Assessment By Etchant Type
- Market Opportunity Assessment By Target Material
- Market Opportunity Assessment By Application Type
- Market Opportunity Assessment By End User
- China Semiconductor Etchant / Etchants Top Companies Market Share
- China Semiconductor Etchant / Etchants Competitive Benchmarking By Technical and Operational Parameters
- China Semiconductor Etchant / Etchants Company Profiles
- China Semiconductor Etchant / Etchants Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Etchant Type
- Wet Etchants
- Dry Etchants
- Selective Etchants
- Buffered HF
By Target Material
- Silicon/Oxides
- Metal Layers
- Layer-Specific
- Oxide Etching
By Application Type
- Wet Bench Etching
- Plasma Etching
- Critical Dimension Control
- Cleaning and Etching
By End User
- Foundries
- Memory Device Makers
- Advanced Node Fabs
- Wafer Processing Plants































