China Semiconductor IP Core Market Size & Growth Rate
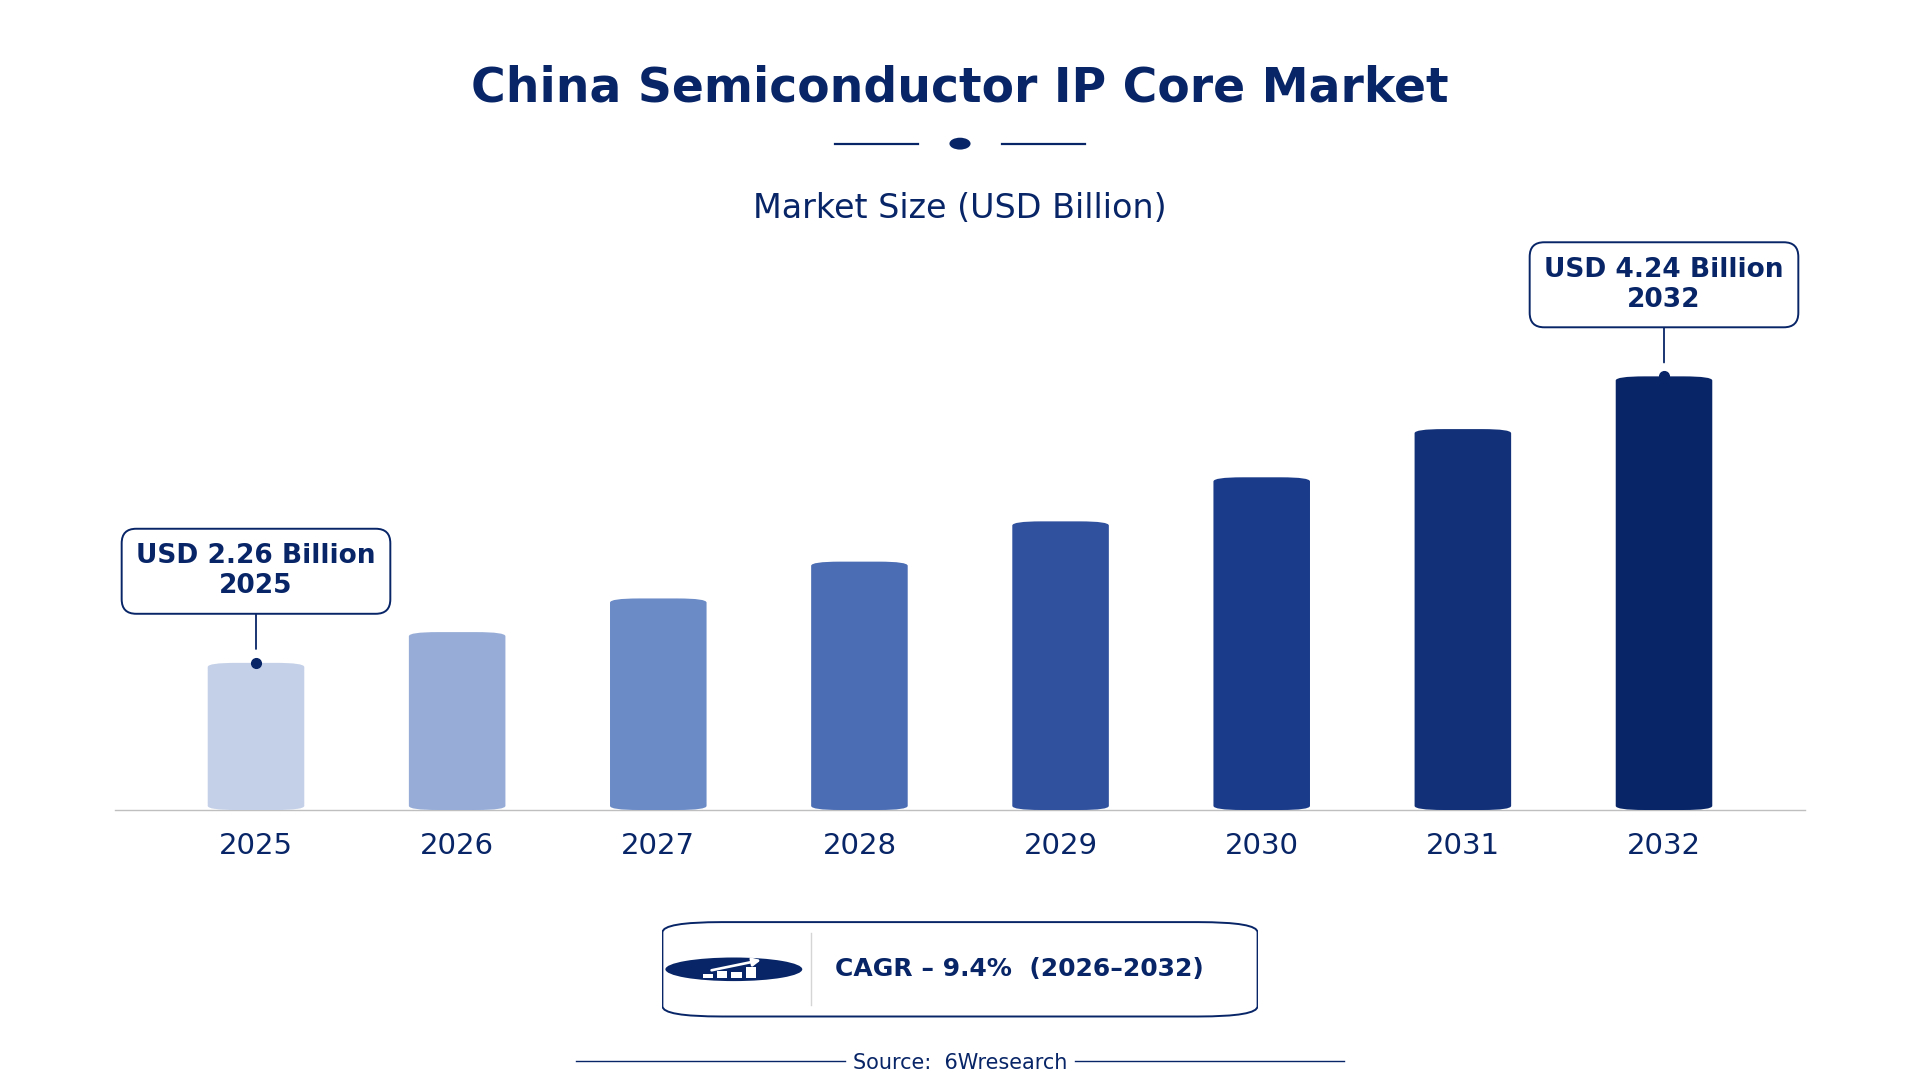
According to 6Wresearch internal database and industry insights, the China Semiconductor IP Core Market was valued at USD 2.26 billion in 2025 and is projected to reach USD 4.24 billion by 2032, growing at a CAGR of approximately 9.4% during 2026–2032.
China Semiconductor IP Core Market Highlights
| Report Metric | Details |
| Report Name | China Semiconductor IP Core Market |
| Market Size 2025 | USD 2.26 billion |
| Market Size 2032 | USD 4.24 billion |
| Absolute Growth 2025–2032 | USD 1.98 billion |
| CAGR 2026–2032 | 9.4% |
| Peak Annual Growth | 11.3% in 2026 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading IP Core Type, 2025 | Processor Cores (40% share) |
| Leading Functionality, 2025 | Computation Engine (41% share) |
| Leading Licensing Model, 2025 | Royalty-Based (35% share) |
| Leading End User, 2025 | SoC Designers (45% share) |
| Fastest-Growing IP Core Type | Interface Cores (11.9% CAGR) |
| Fastest-Growing Functionality | I/O Integration (10.6% CAGR) |
| Fastest-Growing Licensing Model | Subscription-Based (11.3% CAGR) |
| Fastest-Growing End User | Foundries (11.0% CAGR) |
| Growing Sector | Foundries |
| Key End Users | SoC Designers, Chipmakers, Foundries, Embedded Device Makers |
China Semiconductor IP Core Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
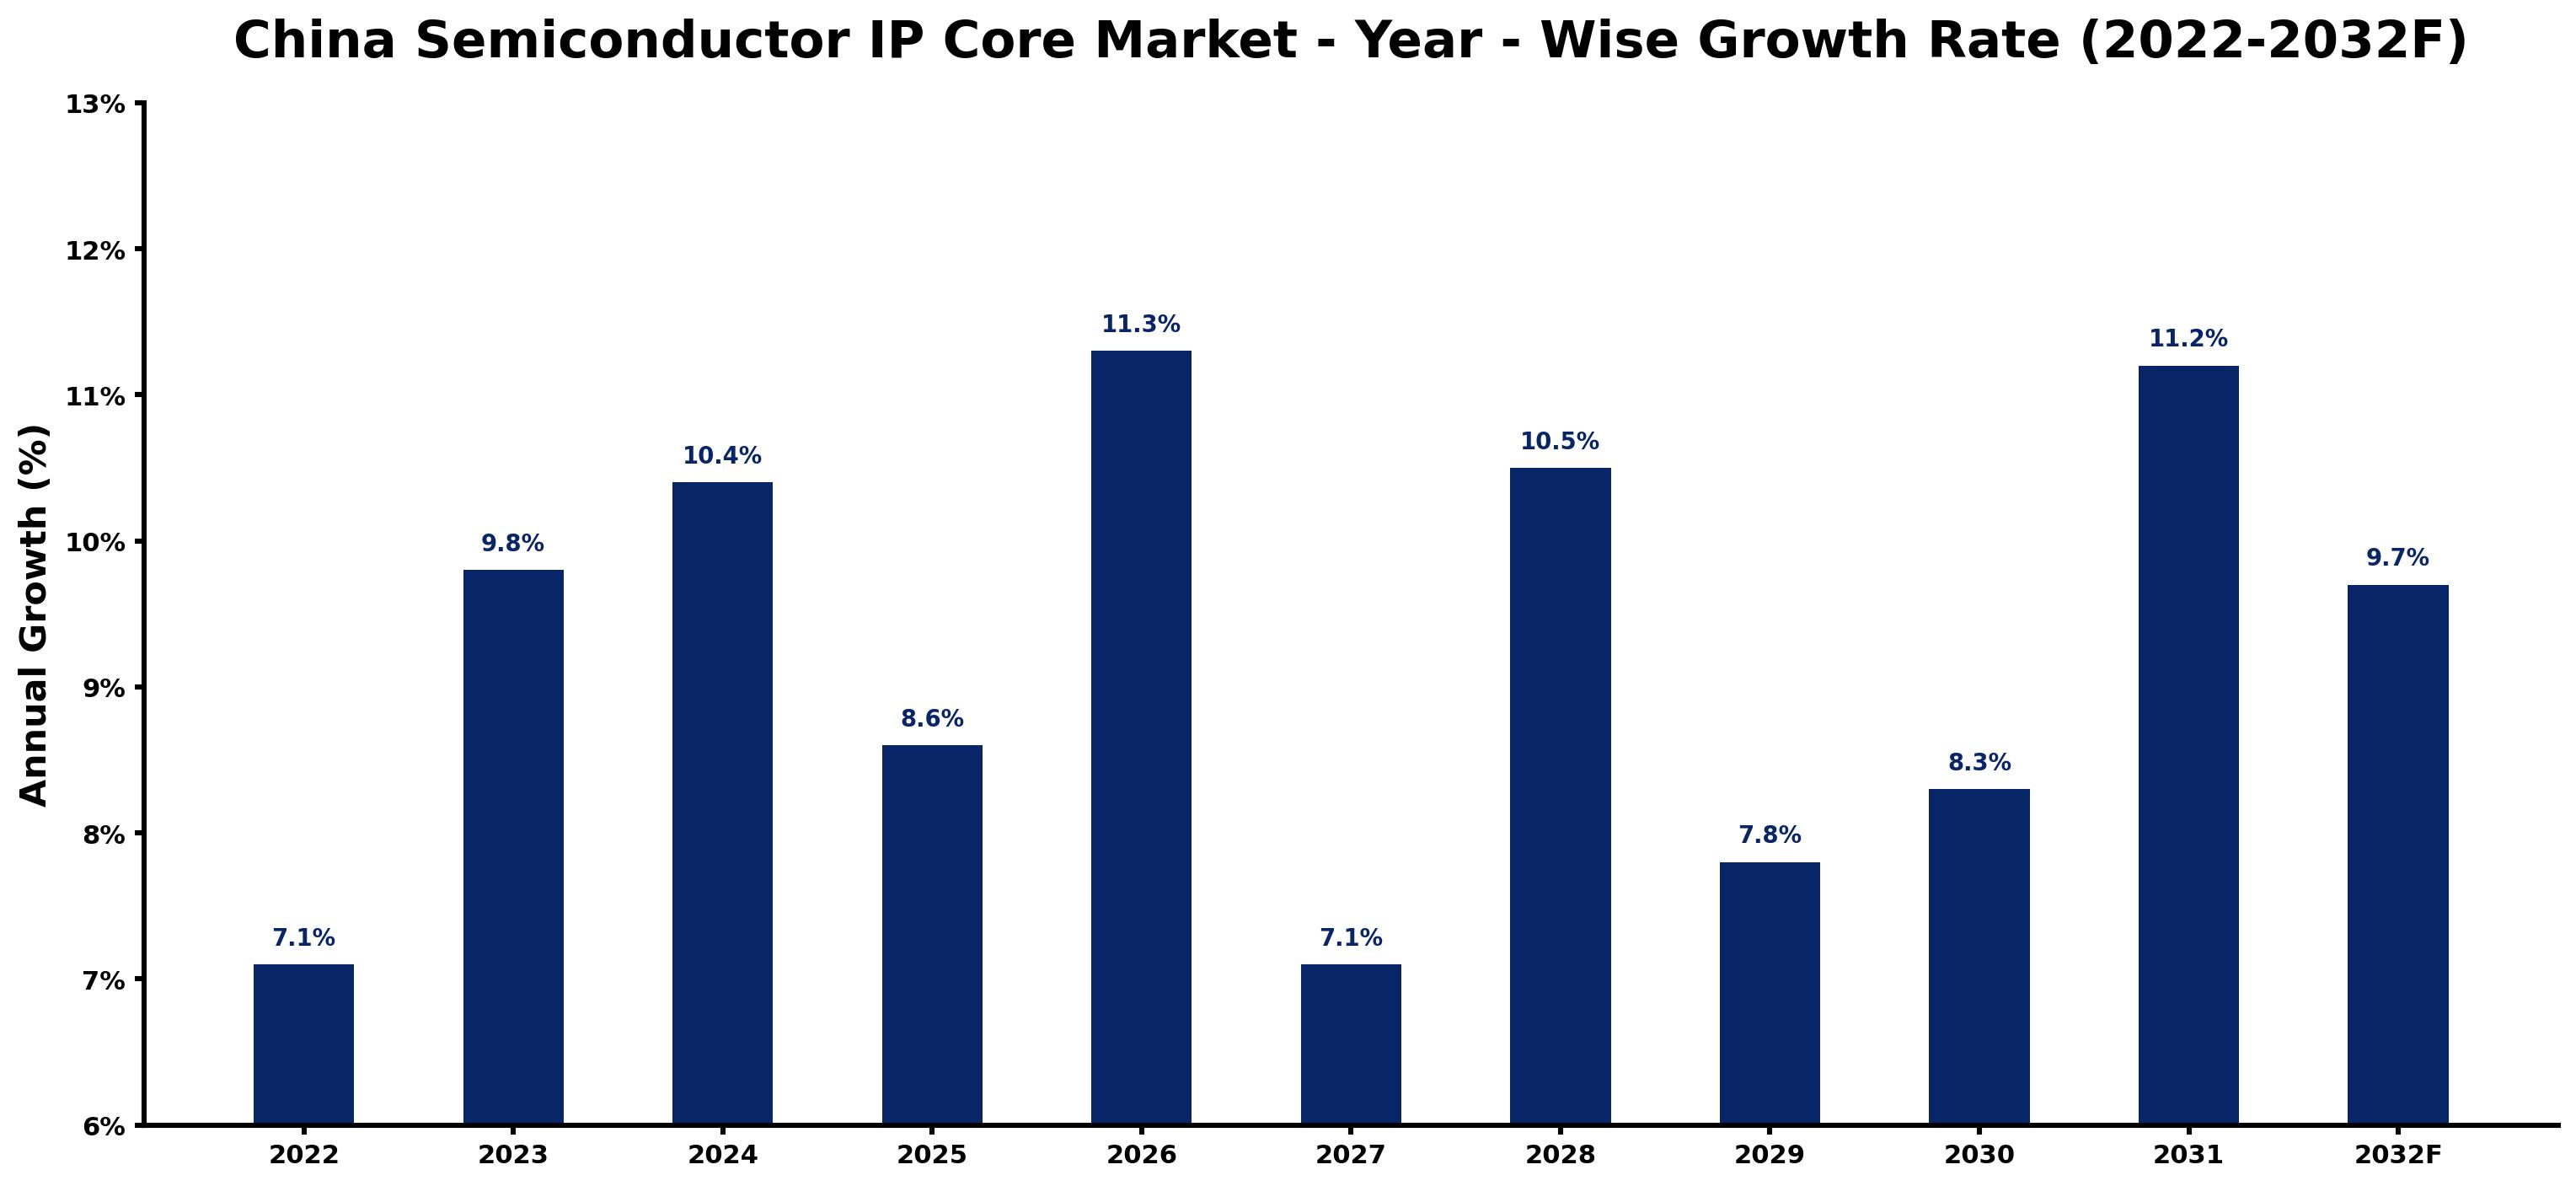
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.1 | The market experienced steady growth, supported by strong domestic demand from local chipmakers. |
| 2023 | 9.8 | Growth accelerated as semiconductor design companies expanded their operations and product offerings. |
| 2024 | 10.4 | The market saw further growth due to increased production capabilities and technological advancements. |
| 2025 | 8.6 | Growth slowed slightly as some companies adjusted to production capacities. |
| 2026 | 11.3 | The market is expected to rebound with heightened investments in semiconductor technology and infrastructure. |
| 2027 | 7.1 | Growth is projected to slow again as companies face challenges in scaling production. |
| 2028 | 10.5 | The market is expected to pick up momentum as demand for advanced chips surges in various sectors. |
| 2029 | 7.8 | Growth is projected to slow as companies face supply chain constraints. |
| 2030 | 8.3 | The market is expected to experience renewed growth driven by innovations in semiconductor technologies. |
| 2031 | 11.2 | Growth is projected to accelerate again as local firms capitalise on new opportunities in the sector. |
| 2032 | 9.7 | Growth is expected to slow as the market stabilises, reflecting a mature phase of development. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Semiconductor IP Core Market Synopsis
The China Semiconductor IP Core Market encompasses reusable units of logic or functional blocks used in integrated circuits. These cores facilitate efficient chip design for applications in consumer electronics and telecommunications. The market is growing due to strong domestic demand from over 1,000 semiconductor design companies and investments in technology. The National Development and Reform Commission's allocation of $30 billion for semiconductor advancements is driving this growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Strong domestic demand from local chipmakers drives the need for efficient design solutions. | Driver | High | Processor Cores |
| Investment in semiconductor technology advancements enhances production capabilities. | Driver | High | Memory Cores |
| Growing demand for advanced chips in telecommunications creates opportunities for suppliers. | Opportunity | High | Interface Cores |
| Emerging markets for secure transactions increase the need for encryption cores. | Opportunity | Medium | Security Cores |
| Challenges in scaling production capacity can limit supply for manufacturers. | Restraint | High | Computation Engine |
| Intense competition among design companies may constrain pricing power. | Restraint | Medium | I/O Integration |
| The Semiconductor IP Core market in China faces significant supply chain disruptions. | Challenge | High | Embedded Device Makers |
| Regulatory hurdles in semiconductor manufacturing can delay project timelines. | Challenge | Medium | Chipmakers |
Evaluation of Drivers in China Semiconductor IP Core Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increasing production of integrated circuits boosts demand for semiconductor IP cores. | Processor Cores | China produced over 1 trillion integrated circuits in 2022, leading to higher demand for efficient design solutions. |
| Technological advancements in chip design increase the need for sophisticated cores. | Memory Cores | The adoption of advanced security standards raises the complexity of chip designs, requiring more advanced IP cores. |
| Investment in semiconductor parks promotes local production capabilities. | Interface Cores | Several semiconductor industrial parks were established in Jiangsu and Guangdong, enhancing local supply and reducing reliance on imports. |
| Rising consumer electronics demand drives the need for efficient chip solutions. | Security Cores | China's population of approximately 1.4 billion creates a vast consumer market for electronics, increasing demand for semiconductor solutions. |
| Government initiatives support local semiconductor manufacturers, boosting market growth. | Computation Engine | The National Integrated Circuit Industry Investment Fund allocated $21 billion to support local firms, enhancing their competitive edge. |
Growth in the Semiconductor IP Core market in China comes from increasing production of integrated circuits, technological advancements, and substantial investments in local semiconductor parks. In 2022, over 1 trillion integrated circuits were produced, driving demand for efficient design solutions. The establishment of semiconductor industrial parks in Jiangsu and Guangdong enhances supply capabilities, allowing for quicker production cycles. The adoption of advanced security standards increases the complexity of chip designs, further boosting demand for sophisticated cores.
Evaluation of Restraints in China Semiconductor IP Core Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions hinder timely delivery of semiconductor components. | Computation Engine | Increased global demand has led to shortages, affecting production timelines for manufacturers and delaying product launches. |
| Intense competition limits pricing power for semiconductor firms. | I/O Integration | With over 1,000 design companies, pricing pressures can impact profit margins and reduce overall profitability. |
| Regulatory hurdles delay project timelines for semiconductor manufacturers. | Embedded Device Makers | Compliance with local regulations can slow down product development and market entry, affecting competitiveness. |
| Challenges in scaling production capacity can limit supply for manufacturers. | Processor Cores | Many companies are struggling to keep up with the rapid growth in demand, leading to potential supply shortages. |
| Technological complexities increase development costs for semiconductor firms. | Memory Cores | Advanced chip designs require significant R&D investment, impacting profitability and resource allocation. |
China Semiconductor IP Core Market Challenges
Buyers in the China Semiconductor IP Core market face supply chain disruptions, as reliance on imported components can delay projects by up to six months. Rising costs have a considerable impact on buyers, with semiconductor material prices increasing by 20% in the past year, straining budgets. Competition intensifies for smaller firms, as over 1,000 domestic design companies compete for limited contracts, making market entry difficult. Additionally, the pressure for constant technological upgrades necessitates around $30 billion in R&D investments, which can overwhelm smaller producers and restrict their growth potential.
Trends in the China Semiconductor IP Core Market
Buyers and suppliers in the China Semiconductor IP Core Market are adjusting to the following trends.
- Shift Towards Advanced Chip Designs: Increased demand for advanced semiconductor solutions is clear as SoC designers focus on efficiency. In 2022, domestic chip production rose by 15%, underscoring the trend towards sophisticated designs.
- Growing Focus on Security Cores: Embedded device makers are prioritising security cores to enhance data protection. The widespread adoption of advanced security standards reflects the industry's shift towards secure transactions, with notable growth in demand for these cores.
- Expansion of Semiconductor Industrial Parks: Jiangsu and Guangdong provinces are emerging as hubs for semiconductor manufacturing, with several parks being established. This trend is supported by the $30 billion allocated for technology advancements in 2023, improving local production capabilities.
- Rise of Subscription-Based Licensing Models: The licensing model is evolving towards subscription-based frameworks, gaining popularity among SoC designers. This shift is driven by the need for continuous updates and support in chip designs, reflecting changing market demands.
Investment Opportunities in the China Semiconductor IP Core Market
Investors looking at the China Semiconductor IP Core Market should consider the following areas.
- SoC Designers Seeking Advanced Solutions: SoC designers are increasingly in search of advanced semiconductor IP cores to boost design efficiency. The market is projected to reach USD 2.26 billion by 2025, presenting an opportunity for suppliers to meet this demand.
- Gap in Secure Chip Designs: With the rise in cyber threats, there is a growing need for secure chip designs. The demand for security cores is expected to increase, offering opportunities for manufacturers to invest in this area and improve their offerings.
- Investment in Semiconductor Technology: The $30 billion allocated for semiconductor technology advancements provides a unique opportunity for local manufacturers. Collaborating with local firms can enable suppliers to enter the market effectively and leverage this funding.
- Emerging Markets for Telecommunications: Telecommunications companies are broadening their product lines, creating demand for advanced semiconductor solutions. Suppliers can capitalise on this growing market by aligning with local chipmakers and offering tailored solutions.
Government Initiatives in the China Semiconductor IP Core Market
The Ministry of Industry and Information Technology launched the "14th Five-Year Plan for the Development of the Integrated Circuit Industry" in 2021 to improve domestic semiconductor capabilities. This plan supports local manufacturers in achieving technological advancements and increasing production capacity. The National Development and Reform Commission initiated the "Integrated Circuit Industry Development Fund" in 2020, with a budget of $30 billion to support local manufacturers. This funding is essential for driving innovation and competitiveness in the semiconductor sector. Additionally, the State Council approved the "National Plan for the Development of the Semiconductor Industry" in 2022, targeting a 70% self-sufficiency rate by 2025, further solidifying the government's commitment to the sector.
The National Development and Reform Commission oversees the allocation of the Integrated Circuit Industry Development Fund, which supports local manufacturers in advancing their technology and production capabilities. The Ministry of Finance's tax incentive program for semiconductor companies investing in R&D aims to boost innovation and competitiveness in the industry. The Ministry of Science and Technology's National Key Research and Development Program focuses on advanced semiconductor technologies, providing funding for research initiatives that enhance the sector's capabilities. This comprehensive approach ensures that local firms are well-positioned to compete in the global market.
Future Insight of the China Semiconductor IP Core Market
The China Semiconductor IP Core market is set for transformative changes by 2032, driven by government initiatives like the "14th Five-Year Plan for the Development of the Integrated Circuit Industry." Increased funding of $30 billion for semiconductor technology advancements will enhance local production capabilities. The establishment of industrial parks in Jiangsu and Guangdong provinces will facilitate collaboration among design companies. By 2025, the goal of 70% self-sufficiency in semiconductor manufacturing will reshape market dynamics, creating new opportunities for buyers and suppliers.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By IP Core Type – Processor Cores Dominated, Interface Cores Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, with a 40% revenue share in 2025, Processor Cores was the largest ip core type category. Processor cores dominate the market share in China due to their critical role in ensuring chip functionality across diverse applications. The substantial production of over 1 trillion integrated circuits in 2022 highlights the robust demand for these cores from local chipmakers. Interface Cores are set to record the highest CAGR in this split, 11.9% over 2026–2032. Interface cores are experiencing rapid growth as they are crucial for facilitating communication between components, particularly with the rising complexity of integrated circuits. The increase in semiconductor design companies, exceeding 1,000 in 2023, further accelerates the demand for interface cores. Suppliers should focus on enhancing their interface core offerings to effectively capture the growing market share.
By Functionality – Computation Engine Dominated, I/O Integration Expected to Grow Fastest
In 2025, Computation Engine led the functionality split with a 41% share. The computation engine leads the market as it is fundamental for processing tasks in integrated circuits, making it indispensable for various electronic applications. Its widespread adoption among semiconductor companies ensures a strong market presence. The quickest growth will come from I/O Integration, forecast to expand at a CAGR of 10.6% between 2026 and 2032. I/O integration is the fastest-growing segment, integral for external device connectivity, which is increasingly critical as consumer electronics evolve. The push for more interconnected devices fuels the demand for efficient I/O integration solutions. Buyers should prioritise I/O integration capabilities to stay competitive in the rapidly advancing electronics market.
By Licensing Model – Royalty-Based Dominated, Subscription-Based Expected to Grow Fastest
The largest licensing model category in 2025 was Royalty-Based, with a 35% share of total revenue. The royalty-based licensing model captures the largest market share as it is widely adopted by IP core suppliers, providing flexibility for semiconductor companies. This model resonates with the financial strategies of many local firms, making it a preferred option for licensing. Over 2026–2032, Subscription-Based is expected to post the fastest growth, at a CAGR of 11.3%. Subscription-based licensing is rapidly gaining traction as it allows for continuous updates and support, which are vital in a fast-paced technological environment. The increasing complexity of semiconductor designs necessitates ongoing access to the latest advancements, driving demand for this model. Suppliers may need to transition towards subscription-based models to meet the evolving preferences of their clients.
By End User – SoC Designers Dominated, Foundries Expected to Grow Fastest
SoC Designers accounted for a 45% market share by end user in 2025. SoC designers command the largest share as they are the primary users of IP cores, directly influencing the design and functionality of integrated circuits. Their critical role in the semiconductor supply chain reinforces their market dominance. Foundries are projected to grow fastest, at a CAGR of 11.0% during 2026–2032. Foundries are the fastest-growing end user segment, manufacturing chips that utilise IP cores, driven by the increasing domestic chip production reported at a 15% rise in 2022. This growth reflects the expanding capabilities of local semiconductor firms. Suppliers should tailor their products to meet the specific needs of foundries to capitalise on this growth opportunity.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Semiconductor IP Core Market Outlook
- Market Size of China Semiconductor IP Core Market, 2025
- Forecast of China Semiconductor IP Core Market, 2032
- Historical Data and Forecast of China Semiconductor IP Core Revenues & Volume for the Period 2022 - 2032F
- China Semiconductor IP Core Market Trend Evolution
- China Semiconductor IP Core Market Drivers and Challenges
- China Semiconductor IP Core Price Trends
- China Semiconductor IP Core Porter's Five Forces
- China Semiconductor IP Core Industry Life Cycle
- Historical Data and Forecast of China Semiconductor IP Core Market Revenues & Volume By IP Core Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor IP Core Market Revenues & Volume By Processor Cores for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor IP Core Market Revenues & Volume By Memory Cores for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor IP Core Market Revenues & Volume By Interface Cores for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor IP Core Market Revenues & Volume By Security Cores for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor IP Core Market Revenues & Volume By Functionality for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor IP Core Market Revenues & Volume By Computation Engine for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor IP Core Market Revenues & Volume By Storage Blocks for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor IP Core Market Revenues & Volume By I/O Integration for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor IP Core Market Revenues & Volume By Encryption/Authentication for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor IP Core Market Revenues & Volume By Licensing Model for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor IP Core Market Revenues & Volume By Royalty-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor IP Core Market Revenues & Volume By One-Time License for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor IP Core Market Revenues & Volume By Subscription-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor IP Core Market Revenues & Volume By Per Unit Royalty for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor IP Core Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor IP Core Market Revenues & Volume By SoC Designers for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor IP Core Market Revenues & Volume By Chipmakers for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor IP Core Market Revenues & Volume By Foundries for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor IP Core Market Revenues & Volume By Embedded Device Makers for the Period 2022 - 2032F
- China Semiconductor IP Core Import Export Trade Statistics
- Market Opportunity Assessment By IP Core Type
- Market Opportunity Assessment By Functionality
- Market Opportunity Assessment By Licensing Model
- Market Opportunity Assessment By End User
- China Semiconductor IP Core Top Companies Market Share
- China Semiconductor IP Core Competitive Benchmarking By Technical and Operational Parameters
- China Semiconductor IP Core Company Profiles
- China Semiconductor IP Core Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By IP Core Type
- Processor Cores
- Memory Cores
- Interface Cores
- Security Cores
By Functionality
- Computation Engine
- Storage Blocks
- I/O Integration
- Encryption/Authentication
By Licensing Model
- Royalty-Based
- One-Time License
- Subscription-Based
- Per Unit Royalty
By End User
- SoC Designers
- Chipmakers
- Foundries
- Embedded Device Makers































