China Smart Grid Instrumentation Market Size & Growth Rate
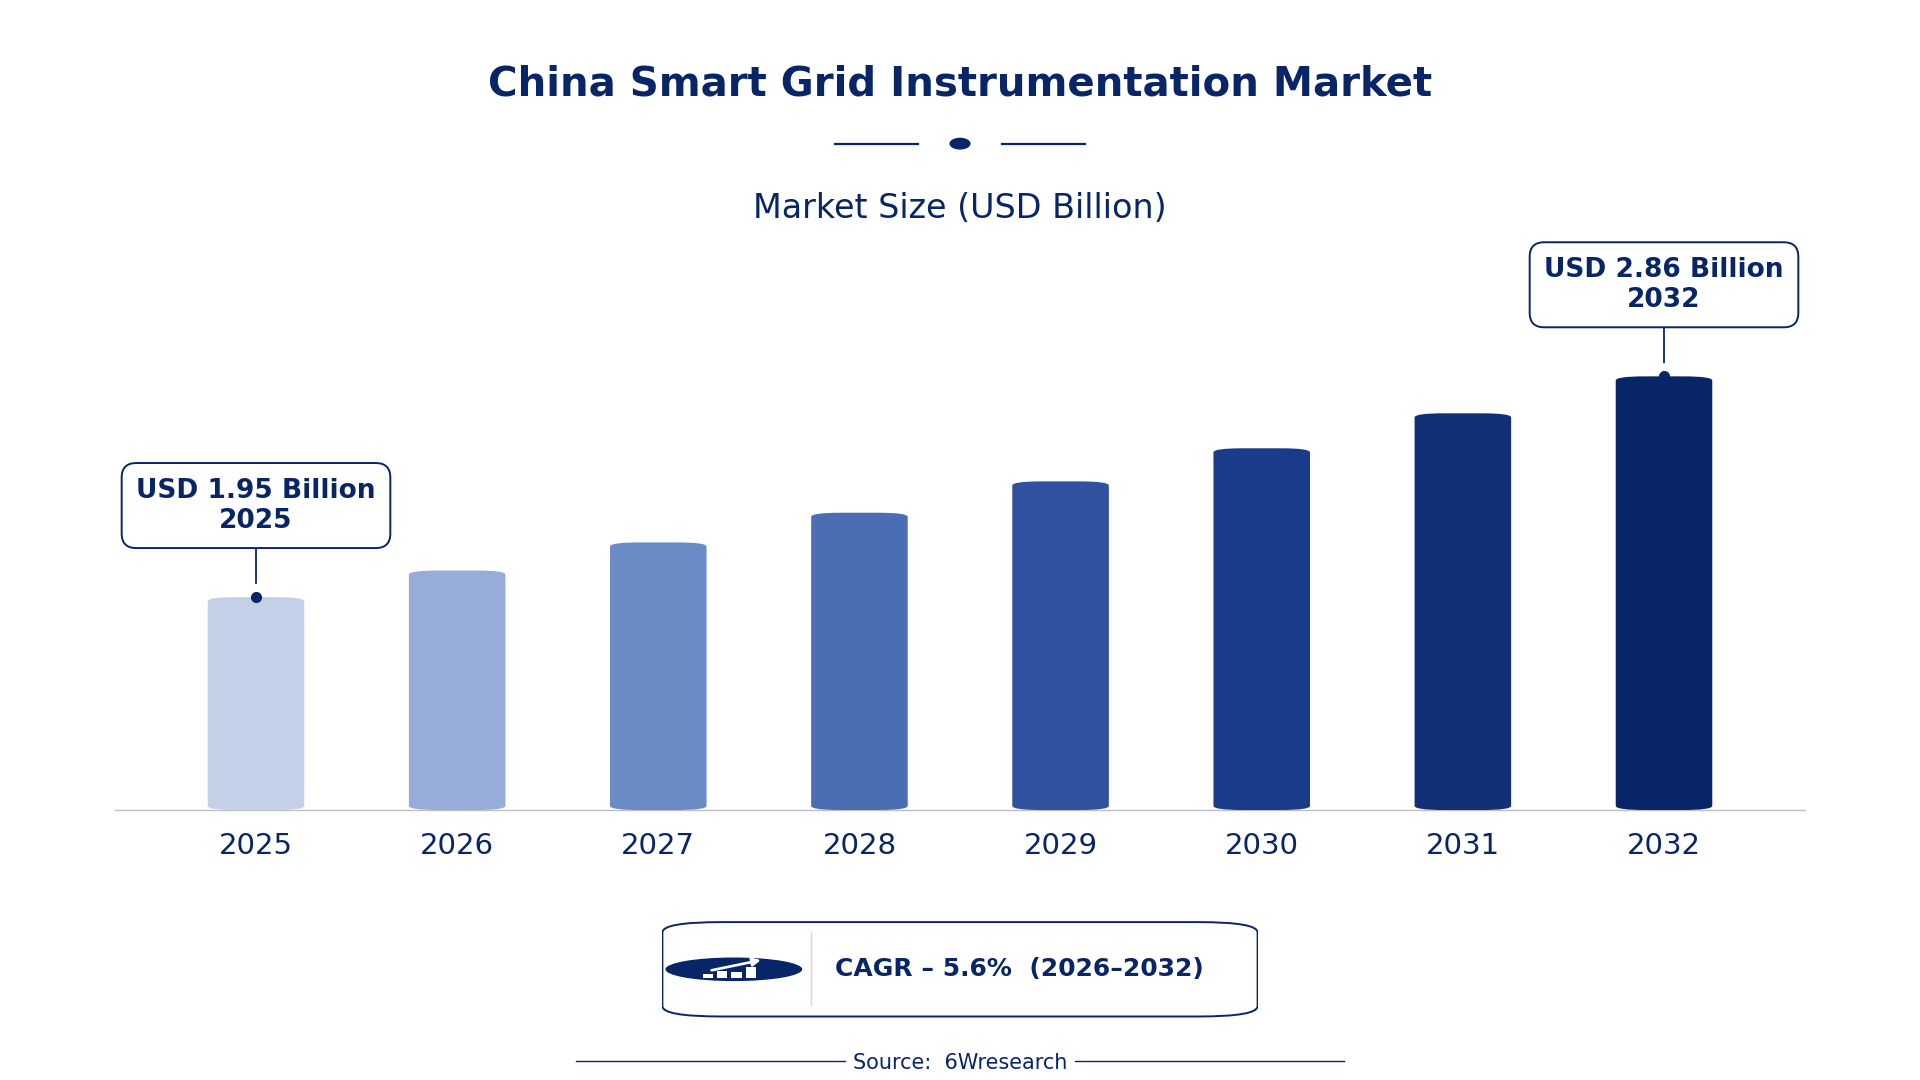
According to 6Wresearch internal database and industry insights, the China Smart Grid Instrumentation Market was valued at USD 1.95 billion in 2025 and is projected to reach USD 2.86 billion by 2032, growing at a CAGR of approximately 5.6% during 2026–2032.
China Smart Grid Instrumentation Market Highlights
| Report Metric | Details |
| Report Name | China Smart Grid Instrumentation Market |
| Market Size 2025 | USD 1.95 billion |
| Market Size 2032 | USD 2.86 billion |
| Absolute Growth 2025–2032 | USD 0.91 billion |
| CAGR 2026–2032 | 5.6% |
| Peak Annual Growth | 7.5% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Instrument Type, 2025 | Smart Energy Meters (48% share) |
| Leading Functionality, 2025 | Real-Time Grid Control (47% share) |
| Leading Deployment Zone, 2025 | Transmission Networks (34% share) |
| Leading End User, 2025 | Grid Operators (49% share) |
| Fastest-Growing Instrument Type | Remote Terminal Units (8.0% CAGR) |
| Fastest-Growing Functionality | Load Balancing (7.4% CAGR) |
| Fastest-Growing Deployment Zone | Substations (7.8% CAGR) |
| Fastest-Growing End User | Transmission Companies (6.9% CAGR) |
| Growing Sector | Transmission Companies |
| Key End Users | Utility Companies, Energy Providers, Grid Operators, Transmission Companies |
China Smart Grid Instrumentation Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
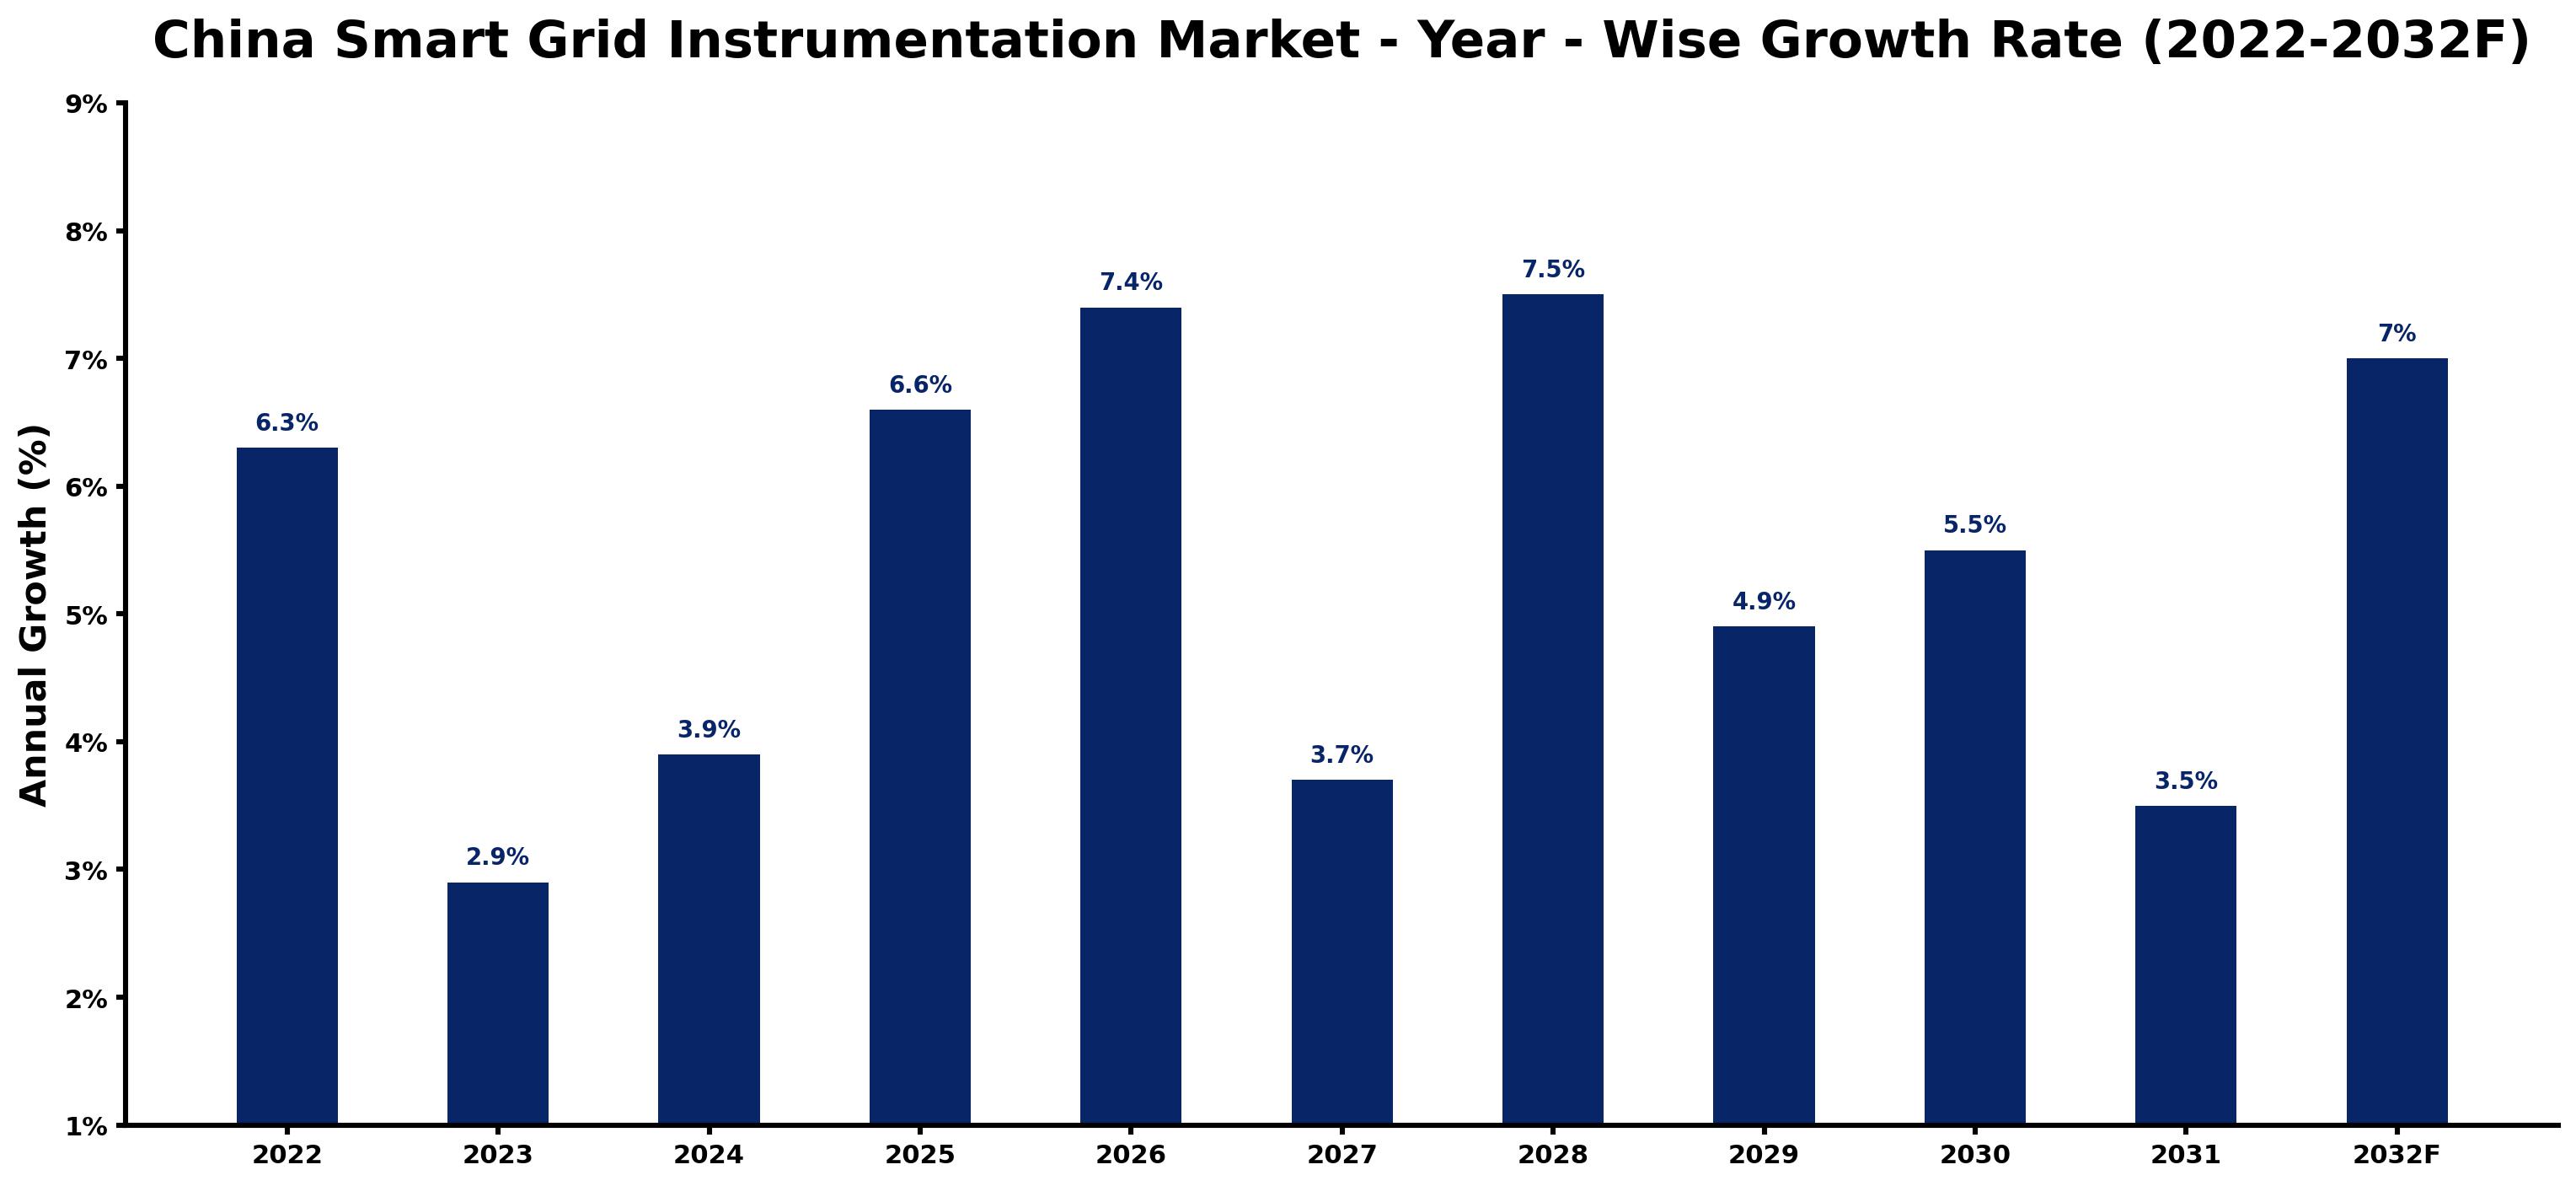
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.3 | Investment in smart grid technologies increased due to government initiatives. |
| 2023 | 2.9 | Growth slowed as some projects faced delays in implementation. |
| 2024 | 3.9 | Demand rose with the deployment of smart energy meters across households. |
| 2025 | 6.6 | Investment surged as the '13th Five-Year Plan' advanced smart grid integration. |
| 2026 | 7.4 | Real-time grid control technologies gained traction in urban areas. |
| 2027 | 3.7 | Growth slowed as the 'Digital Energy Development Strategy' is expected to enhance innovation. |
| 2028 | 7.5 | Peak growth was driven by heightened investment in infrastructure. |
| 2029 | 4.9 | Market growth slowed as some projects reached completion. |
| 2030 | 5.5 | Demand increased with further integration of renewable energy sources. |
| 2031 | 3.5 | Growth slowed as the 'National Energy Administration' promotes smart grid standards. |
| 2032 | 7.0 | Investment in smart grid technologies is expected to rise as the 'National Smart Grid Research and Development Center' advances. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Smart Grid Instrumentation Market Synopsis
The China Smart Grid Instrumentation Market includes advanced technologies designed for the monitoring and management of electrical grids. These technologies boost energy efficiency, improve reliability, and allow for real-time monitoring of electrical systems. The market is expanding due to substantial investments, with around 1 trillion yuan allocated in 2022. Government initiatives, such as the 'Smart Grid Development Plan', are driving demand from utility companies and supporting infrastructure modernisation efforts. By 2025, the installed base of smart meters is expected to surpass 400 million, enabling better energy management.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Significant investment in smart grid technologies enhances infrastructure and operational efficiency. | Driver | High | Smart Energy Meters |
| The deployment of smart energy meters across over 200 million households boosts demand for monitoring solutions. | Driver | High | Remote Terminal Units |
| Growing urbanisation in cities like Beijing creates opportunities for smart grid solutions. | Opportunity | High | Voltage Regulators |
| The need for improved energy management in residential areas presents a chance for smart grid integration. | Opportunity | High | Real-Time Grid Control |
| Challenges in integrating renewable energy sources can hinder market growth. | Restraint | High | Phasor Measurement Units |
| High costs associated with advanced technologies may limit adoption rates. | Restraint | Medium | Voltage Regulators |
| Regulatory compliance and standards can delay product approvals and market entry. | Challenge | High | Smart Energy Meters |
| Limited skilled workforce in smart grid technologies poses a challenge for implementation. | Challenge | Medium | Remote Terminal Units |
Evaluation of Drivers in China Smart Grid Instrumentation Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Investment in smart grid technologies supports infrastructure upgrades and operational efficiency. | Smart Energy Meters | China's smart grid investment reached approximately 1 trillion yuan in 2022. |
| Deployment of smart energy meters facilitates two-way communication and energy management. | Remote Terminal Units | Over 200 million households have adopted smart energy meters. |
| Real-time monitoring improves grid stability and reliability for energy providers. | Phasor Measurement Units | Energy reliability firms report a 30% improvement in outage response times. |
| Voltage regulators are essential for maintaining energy supply in high-demand urban areas. | Voltage Regulators | Urban areas like Beijing and Shanghai experience critical energy demand. |
| The integration of renewable energy sources necessitates advanced monitoring solutions. | Real-Time Grid Control | The '13th Five-Year Plan' emphasizes smart grid integration for renewables. |
The Smart Grid Instrumentation market in China is growing on the back of substantial investments and increasing end-use demand. China's smart grid investment reached approximately 1 trillion yuan in 2022, which supports infrastructure upgrades and operational efficiency. The deployment of smart energy meters across over 200 million households facilitates two-way communication and energy management. Energy reliability firms report a 30% improvement in outage response times due to real-time monitoring. The emphasis on integrating renewable energy sources drives demand for advanced monitoring solutions, ensuring grid stability and reliability.
Evaluation of Restraints in China Smart Grid Instrumentation Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Integration challenges with renewable energy sources can hinder market growth. | Phasor Measurement Units | The complex nature of renewable systems complicates their integration into existing grids. |
| High costs associated with advanced technologies may limit adoption rates. | Voltage Regulators | Producers face high expenses in developing and implementing smart grid solutions. |
| Regulatory compliance and standards can delay product approvals and market entry. | Smart Energy Meters | Meeting stringent regulations can prolong the time to market for new technologies. |
| Limited skilled workforce in smart grid technologies poses a challenge for implementation. | Remote Terminal Units | A shortage of qualified personnel affects the deployment of advanced grid solutions. |
| Market fluctuations can impact investment levels in smart grid projects. | Real-Time Grid Control | Economic uncertainties may lead to reduced funding for infrastructure improvements. |
China Smart Grid Instrumentation Market Challenges
Producers in the China Smart Grid Instrumentation Market face considerable challenges, starting with technology integration issues. Many find it difficult to incorporate advanced smart grid technologies due to the complexity of legacy systems, which can delay utility projects by several months. High costs present another obstacle; the average investment per smart grid project can exceed 100 million yuan, creating budget constraints for buyers. Furthermore, a shortage of skilled professionals familiar with these systems leads to additional delays, complicating project timelines for producers. Supply chain disruptions can arise from reliance on specific components, extending project timelines for buyers and increasing costs.
Trends in the China Smart Grid Instrumentation Market
The trends below show where the China Smart Grid Instrumentation Market is heading.
- Shift towards Smart Energy Meter Deployment: The 'Smart Grid Development Plan' initiated a shift in smart energy meter deployment across China. By 2022, over 200 million households were equipped with these meters, improving energy management capabilities.
- Transition to Real-Time Grid Control Technologies: Real-time grid control technologies are increasingly being implemented in major cities to improve efficiency. By 2025, this technology is expected to be standard in urban areas, ensuring better management of energy resources.
- Emergence of Voltage Regulation Solutions: Voltage regulators are becoming essential in urban areas with high energy demand. In cities like Beijing and Shanghai, these solutions are critical for maintaining stable voltage levels, reflecting a growing trend in energy management.
- Adoption of Advanced Monitoring Systems: The establishment of the 'National Smart Grid Research and Development Center' in 2020 marks a trend towards advanced monitoring systems. This initiative aims to improve grid reliability and efficiency through advanced technologies.
Investment Opportunities in the China Smart Grid Instrumentation Market
Below are the investment opportunities with the strongest case in the China Smart Grid Instrumentation Market.
- Investment in Substation Upgrades: With over 1,000 substations equipped with advanced instrumentation, there is a strong opportunity for investment in upgrades. Companies can partner with local firms to improve substation capabilities, addressing the growing demand for efficiency.
- Entry into Residential Energy Management: The increasing deployment of smart energy meters in residential areas presents an opportunity for energy management solutions. Collaborating with local utility companies can facilitate market entry and product adoption.
- Focus on Urban Energy Solutions: Urban centres like Beijing are prioritising smart grid technologies to manage high energy demands. Suppliers can invest in tailored solutions for these markets, addressing specific local needs and improving grid reliability.
- Expansion into Renewable Energy Integration: As China aims to integrate more renewable energy sources, there is a pressing need for smart grid solutions. Companies should seek partnerships with energy providers to develop technologies that support this transition.
Government Initiatives in the China Smart Grid Instrumentation Market
The 'Smart Grid Development Plan' by the National Energy Administration, launched in 2020, aims to improve grid reliability and efficiency through advanced technologies. This plan mandates the adoption of smart grid solutions across urban and rural areas, encouraging investment in infrastructure and innovation. Additionally, the 'National Energy Administration's 2022 Action Plan' highlights the need for smart grid infrastructure to support renewable energy integration, further driving demand for smart grid instrumentation. By 2025, notable advancements in grid capabilities are expected as a result of these initiatives.
The National Energy Administration oversees the approval of smart grid projects and funding for infrastructure improvements. The agency's initiatives aim to facilitate the integration of renewable energy sources and enhance overall grid efficiency, benefiting both producers and consumers.
Future Insight of the China Smart Grid Instrumentation Market
By 2032, buyers and suppliers in the China Smart Grid Instrumentation Market can expect substantial advancements driven by government initiatives and technological progress. The 'Smart Grid Development Plan' will continue to support integration, leading to improved operational efficiency across the sector. Approximately 400 million smart meters will be in use, enhancing data management capabilities for utility companies. Innovations in real-time monitoring will greatly improve energy reliability, resulting in quicker outage response times, particularly in urban areas like Beijing and Shanghai.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Instrument Type – Smart Energy Meters Dominated, Remote Terminal Units Expected to Grow Fastest
According to Dhaval Chaurasia, Assistant Manager at 6Wresearch, Smart Energy Meters took a 48% share of instrument type in 2025, more than any other category. Smart energy meters command the largest market share because they are essential for measuring energy consumption and enabling two-way communication. Their extensive deployment across over 200 million households highlights their foundational role in advancing China's smart grid. Remote Terminal Units are set to record the highest CAGR in this split, 8.0% over 2026–2032. Remote terminal units are experiencing rapid growth as they facilitate remote monitoring and control of grid operations, crucial for managing energy in densely populated urban areas. The increasing urban demand for operational efficiency is driving their swift adoption. Suppliers should focus on enhancing remote terminal unit technologies to meet the rising demand in urban environments.
By Functionality – Real-Time Grid Control Dominated, Load Balancing Expected to Grow Fastest
Real-Time Grid Control held a 47% share of the China Smart Grid Instrumentation Market by functionality in 2025. Real-time grid control holds the largest market share as it is vital for managing grid operations and responding to fluctuations in energy supply and demand. Its importance is underscored by the implementation of these technologies in major urban areas. Load Balancing is projected to grow fastest, at a CAGR of 7.4% during 2026–2032. Load balancing is the fastest-growing functionality due to its critical role in distributing electrical load efficiently across the grid, particularly in densely populated regions. The increasing complexity of energy consumption patterns is driving this growth. Suppliers must invest in load balancing technologies to capitalise on this expanding segment.
By Deployment Zone – Transmission Networks Dominated, Substations Expected to Grow Fastest
Transmission Networks accounted for a 34% market share by deployment zone in 2025. Transmission networks lead the market share as they are critical for managing high-voltage electricity transmission over long distances. The existing infrastructure effectively supports the integration of smart grid technologies, ensuring reliable energy distribution. Over 2026–2032, Substations are expected to post the fastest growth, at a CAGR of 7.8%. Substations represent the fastest-growing deployment zone, acting as key locations for implementing smart grid technologies that enable localised control and monitoring. Their strategic importance in urban energy systems is accelerating their development and adoption. This suggests that suppliers should develop tailored solutions for substations to capitalise on growth opportunities in this sector.
By End User – Grid Operators Dominated, Transmission Companies Expected to Grow Fastest
With a 49% revenue share in 2025, Grid Operators was the largest end user category. Grid operators hold the largest market share as they are the primary users of smart grid technologies, essential for enhancing operational efficiency and reliability. Their pivotal role in grid management drives the demand for advanced instrumentation solutions. The quickest growth will come from Transmission Companies, forecast to expand at a CAGR of 6.9% between 2026 and 2032. Transmission companies are the fastest-growing end user segment, utilising smart grid solutions to manage transmission lines effectively amid rising energy demands. Their focus on efficiency is propelling the rapid adoption of smart technologies. Suppliers should customise their products to meet the specific needs of transmission companies to leverage this growth trend.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Smart Grid Instrumentation Market Outlook
- Market Size of China Smart Grid Instrumentation Market, 2025
- Forecast of China Smart Grid Instrumentation Market, 2032
- Historical Data and Forecast of China Smart Grid Instrumentation Revenues & Volume for the Period 2022 - 2032F
- China Smart Grid Instrumentation Market Trend Evolution
- China Smart Grid Instrumentation Market Drivers and Challenges
- China Smart Grid Instrumentation Price Trends
- China Smart Grid Instrumentation Porter's Five Forces
- China Smart Grid Instrumentation Industry Life Cycle
- Historical Data and Forecast of China Smart Grid Instrumentation Market Revenues & Volume By Instrument Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Smart Grid Instrumentation Market Revenues & Volume By Smart Energy Meters for the Period 2022 - 2032F
- Historical Data and Forecast of China Smart Grid Instrumentation Market Revenues & Volume By Remote Terminal Units for the Period 2022 - 2032F
- Historical Data and Forecast of China Smart Grid Instrumentation Market Revenues & Volume By Phasor Measurement Units for the Period 2022 - 2032F
- Historical Data and Forecast of China Smart Grid Instrumentation Market Revenues & Volume By Voltage Regulators for the Period 2022 - 2032F
- Historical Data and Forecast of China Smart Grid Instrumentation Market Revenues & Volume By Functionality for the Period 2022 - 2032F
- Historical Data and Forecast of China Smart Grid Instrumentation Market Revenues & Volume By Two-Way Communication for the Period 2022 - 2032F
- Historical Data and Forecast of China Smart Grid Instrumentation Market Revenues & Volume By Real-Time Grid Control for the Period 2022 - 2032F
- Historical Data and Forecast of China Smart Grid Instrumentation Market Revenues & Volume By Grid Stability Monitoring for the Period 2022 - 2032F
- Historical Data and Forecast of China Smart Grid Instrumentation Market Revenues & Volume By Load Balancing for the Period 2022 - 2032F
- Historical Data and Forecast of China Smart Grid Instrumentation Market Revenues & Volume By Deployment Zone for the Period 2022 - 2032F
- Historical Data and Forecast of China Smart Grid Instrumentation Market Revenues & Volume By Residential/Commercial for the Period 2022 - 2032F
- Historical Data and Forecast of China Smart Grid Instrumentation Market Revenues & Volume By Substations for the Period 2022 - 2032F
- Historical Data and Forecast of China Smart Grid Instrumentation Market Revenues & Volume By Transmission Networks for the Period 2022 - 2032F
- Historical Data and Forecast of China Smart Grid Instrumentation Market Revenues & Volume By Transformer Stations for the Period 2022 - 2032F
- Historical Data and Forecast of China Smart Grid Instrumentation Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Smart Grid Instrumentation Market Revenues & Volume By Grid Operators for the Period 2022 - 2032F
- Historical Data and Forecast of China Smart Grid Instrumentation Market Revenues & Volume By Transmission Companies for the Period 2022 - 2032F
- Historical Data and Forecast of China Smart Grid Instrumentation Market Revenues & Volume By Energy Reliability Firms for the Period 2022 - 2032F
- Historical Data and Forecast of China Smart Grid Instrumentation Market Revenues & Volume By Power Distribution Firms for the Period 2022 - 2032F
- China Smart Grid Instrumentation Import Export Trade Statistics
- Market Opportunity Assessment By Instrument Type
- Market Opportunity Assessment By Functionality
- Market Opportunity Assessment By Deployment Zone
- Market Opportunity Assessment By End User
- China Smart Grid Instrumentation Top Companies Market Share
- China Smart Grid Instrumentation Competitive Benchmarking By Technical and Operational Parameters
- China Smart Grid Instrumentation Company Profiles
- China Smart Grid Instrumentation Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Instrument Type
- Smart Energy Meters
- Remote Terminal Units
- Phasor Measurement Units
- Voltage Regulators
By Functionality
- Two-Way Communication
- Real-Time Grid Control
- Grid Stability Monitoring
- Load Balancing
By Deployment Zone
- Residential/Commercial
- Substations
- Transmission Networks
- Transformer Stations
By End User
- Grid Operators
- Transmission Companies
- Energy Reliability Firms
- Power Distribution Firms































