China Solvent & Intermediate Market Size & Growth Rate
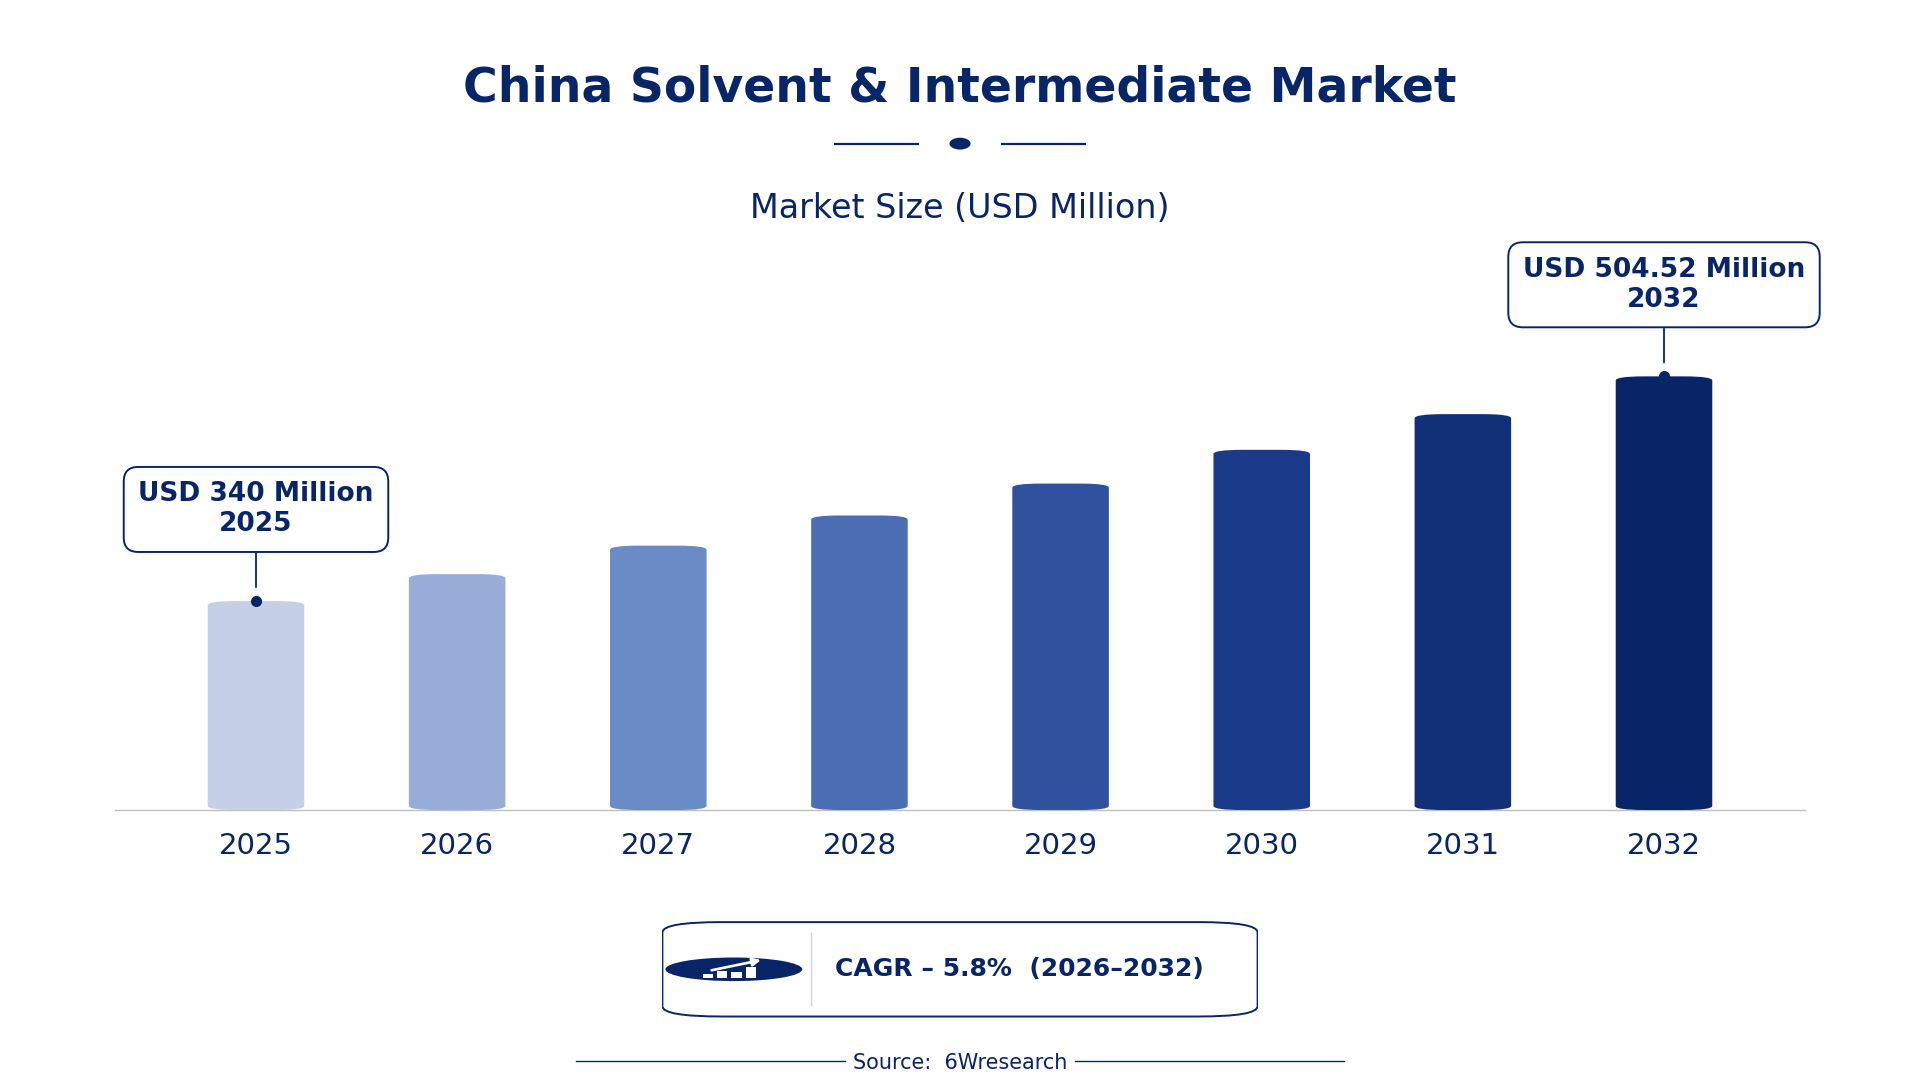
According to 6Wresearch internal database and industry insights, the China Solvent & Intermediate Market was valued at USD 340.0 million in 2025 and is projected to reach USD 504.52 million by 2032, growing at a CAGR of approximately 5.8% during 2026–2032.
China Solvent & Intermediate Market Highlights
| Report Metric | Details |
| Report Name | China Solvent & Intermediate Market |
| Market Size 2025 | USD 340.0 million |
| Market Size 2032 | USD 504.52 million |
| Absolute Growth 2025–2032 | USD 164.52 million |
| CAGR 2026–2032 | 5.8% |
| Peak Annual Growth | 8.2% in 2029 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Product Type, 2025 | Glycol Ethers (46% share) |
| Leading Source Type, 2025 | Petrochemical-Based (45% share) |
| Leading Application Area, 2025 | Paints & Coatings (48% share) |
| Leading End User, 2025 | Industrial Paint Firms (35% share) |
| Fastest-Growing Product Type | Acetates (7.6% CAGR) |
| Fastest-Growing Source Type | Renewable-Based (7.7% CAGR) |
| Fastest-Growing Application Area | Cosmetics & Fragrances (8.4% CAGR) |
| Fastest-Growing End User | Personal Care Companies (8.5% CAGR) |
| Growing Sector | Personal Care |
| Key End Users | Industrial Paint Firms, Personal Care Companies, Agrochemical Manufacturers |
China Solvent & Intermediate Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
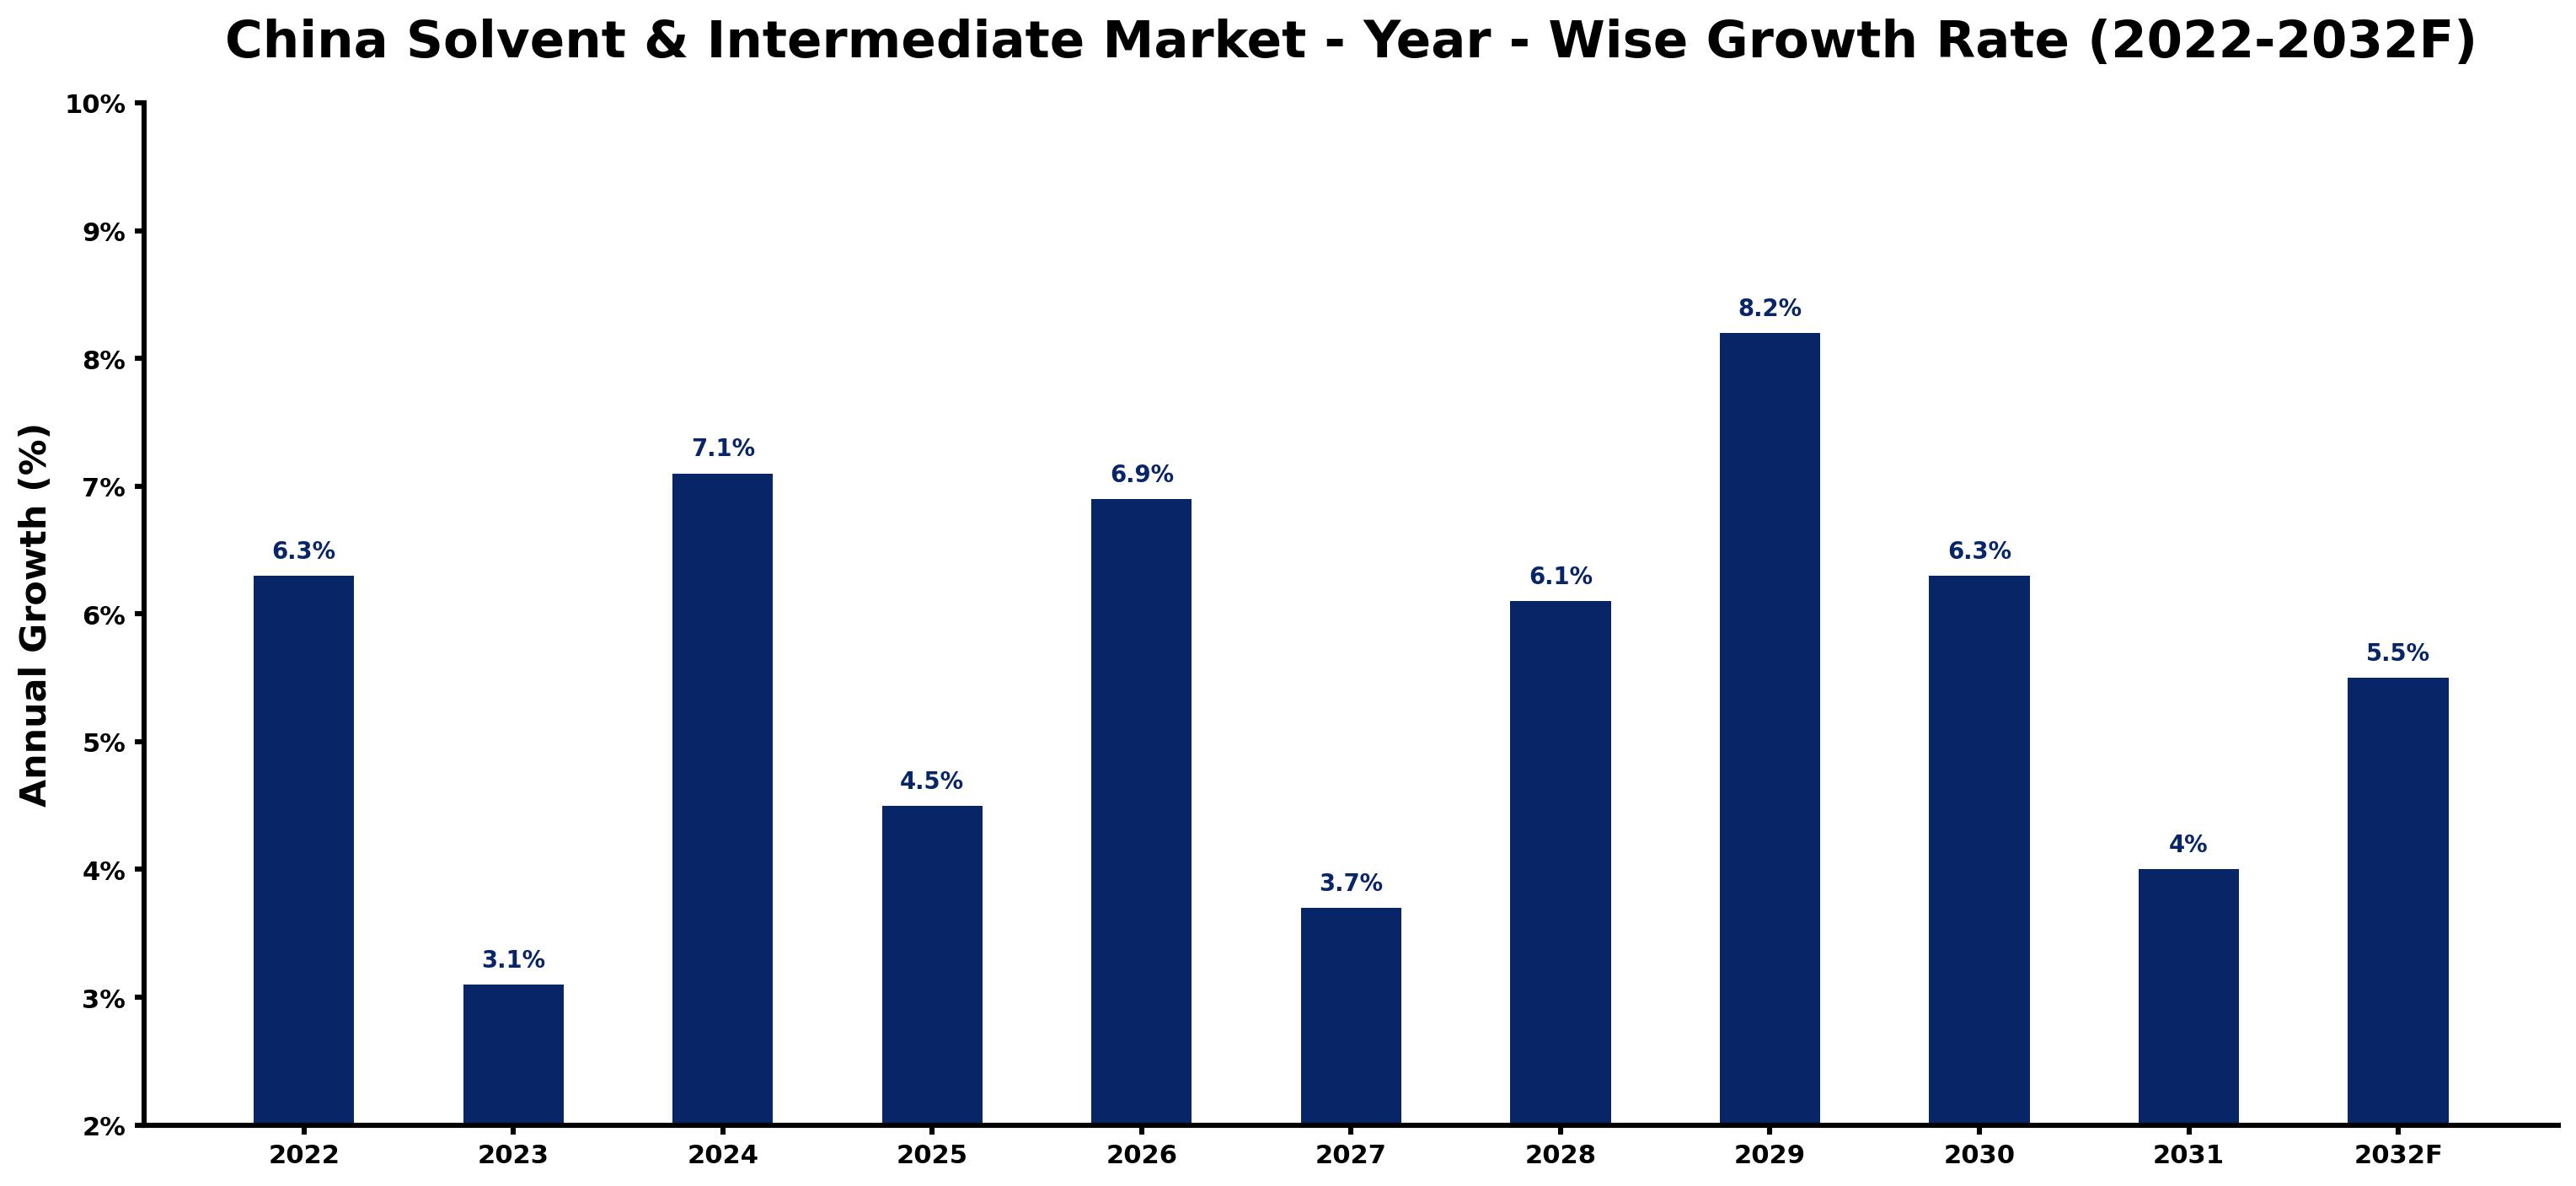
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.3 | The market experienced solid growth, driven by high demand from the coatings industry. |
| 2023 | 3.1 | Growth slowed due to adjustments in the solvent supply chain following the Green Chemistry Initiative. |
| 2024 | 7.1 | Demand surged as the coatings industry expanded production capabilities and adopted new technologies. |
| 2025 | 4.5 | Growth decelerated as manufacturers faced challenges in sourcing raw materials and compliance costs. |
| 2026 | 6.9 | Increased demand from personal care companies is expected to boost market performance. |
| 2027 | 3.7 | A slowdown is anticipated as the market adjusts to new environmental regulations and standards. |
| 2028 | 6.1 | Demand is projected to rise again, supported by innovations in solvent production technologies. |
| 2029 | 8.2 | The market is expected to peak as the personal care sector increases solvent consumption. |
| 2030 | 6.3 | Growth is anticipated to slow as manufacturers face rising operational costs and competition. |
| 2031 | 4.0 | Demand is projected to decelerate due to saturation in the personal care sector. |
| 2032 | 5.5 | A rebound is expected as new regulations promote sustainable solvent practices and technologies. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Solvent & Intermediate Market Synopsis
The Solvent & Intermediate Market in China includes chemical substances essential for paints, coatings, and diverse industrial applications. These solvents, sourced from petrochemical processes, are crucial for product performance. The market is growing due to increased demand from sectors such as personal care and agrochemicals. In 2022, the coatings industry consumed over 1 million tons of solvents, propelling industrial demand. The Green Chemistry Initiative, launched in 2023, advocates for sustainable practices in solvent production, further driving market expansion.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing demand from the coatings industry | Driver | High | Paints & Coatings |
| Increasing consumption in personal care products | Driver | High | Cosmetics & Fragrances |
| Expansion of the personal care sector | Opportunity | High | Personal Care Companies |
| Rising interest in renewable-based solvents | Opportunity | Medium | Renewable-Based |
| Environmental regulations impacting production | Restraint | High | Petrochemical-Based |
| Volatility in raw material prices | Restraint | Medium | Alcohol Solvents |
| Compliance costs for new environmental standards | Challenge | High | Glycol Ethers |
| Competition from alternative solvent technologies | Challenge | Medium | Acetates |
Evaluation of Drivers in China Solvent & Intermediate Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| High consumption of solvents in coatings | Paints & Coatings | In 2022, the coatings industry consumed over 1 million tons of solvents, driving demand for high-performance products. |
| Rising personal care sector demand | Cosmetics & Fragrances | The personal care sector is projected to consume 500,000 tons of solvents by 2025, increasing purchases from suppliers. |
| Increased demand for sustainable products | Renewable-Based | The Green Chemistry Initiative promotes renewable solvents, encouraging manufacturers to invest in sustainable production methods. |
| Growth in agrochemical formulations | Agrochemicals | The agrochemical sector is expected to grow, leading to increased solvent use in formulations. |
| Technological advancements in solvent production | Synthetically Derived | Innovations in production technologies are improving the efficiency and quality of synthetically derived solvents. |
The Solvent & Intermediate market in China is expanding as demand rises in coatings and personal care. The coatings industry consumed over 1 million tons of solvents in 2022, prompting manufacturers to ramp up production. The personal care sector is expected to consume 500,000 tons of solvents by 2025, fuelling additional demand. These developments support market growth and attract new investments.
Evaluation of Restraints in China Solvent & Intermediate Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Compliance costs for environmental regulations | Petrochemical-Based | Manufacturers face increased costs to meet new environmental standards, impacting profitability by approximately 15%. |
| Volatility in raw material prices | Alcohol Solvents | Fluctuating prices for petrochemical feedstocks create uncertainty for suppliers and buyers, affecting production costs. |
| Limited market share of renewable solvents | Renewable-Based | Renewable solvents currently hold a small market share of around 5%, limiting growth potential in this segment. |
| Challenges in sourcing sustainable materials | Glycol Ethers | Sourcing sustainable raw materials can delay production timelines for manufacturers by several weeks. |
| Increased competition from alternative technologies | Acetates | Emerging solvent technologies pose a threat to traditional solvent producers, affecting market share and pricing. |
China Solvent & Intermediate Market Challenges
Buyers and suppliers in the China solvent and intermediate market face rising costs due to volatile raw material prices, which can increase production expenses by up to 15%. Producers struggle with outdated technology that leads to a 20% higher energy consumption rate compared to modern facilities, reducing their competitiveness. Compliance with stringent emissions standards set by the Ministry of Ecology and Environment often results in production delays, costing manufacturers valuable time and resources. Supply chain disruptions are common in the Yangtze River Delta, where logistical issues can halt operations for weeks, delaying deliveries for buyers and impacting their production schedules.
Trends in the China Solvent & Intermediate Market
Several trends are reshaping the China Solvent & Intermediate Market; the most important are set out below.
- Shift towards Renewable Solvents: The Green Chemistry Initiative, initiated in 2023, is driving a transition towards renewable solvents in China. This shift is likely to increase the market share of renewable-based solvents, which currently represents a small fraction of total consumption.
- Growing Adoption of Sustainable Practices: The Chemical Industry Transformation Plan, introduced in 2021, promotes sustainable production methods. This initiative aims to increase the adoption of eco-friendly solvents among manufacturers, aligning with global sustainability trends.
- Increased Demand for High-Performance Coatings: As the coatings industry expands, manufacturers are seeking high-performance solvents to meet evolving product standards. This trend is reflected in the substantial consumption of over 1 million tons of solvents in 2022.
- Expansion of Personal Care Applications: The personal care sector is increasingly utilising solvents, with projections indicating consumption of 500,000 tons by 2025. This growth is prompting suppliers to focus on developing tailored solvent solutions for this market.
Investment Opportunities in the China Solvent & Intermediate Market
Some of the investment opportunities in the China Solvent & Intermediate Market are mentioned below.
- Personal Care Companies Seeking Solvents: Personal care companies are projected to consume 500,000 tons of solvents by 2025, creating an opportunity for suppliers to meet this demand with tailored products.
- Emerging Market for Renewable Solvents: The coatings industry is a major consumer of solvents, with over 1 million tons used in 2022. Suppliers can focus on developing high-performance formulations to cater to this demand.
- Yangtze River Delta as a Key Production Hub: The Yangtze River Delta is a key region for solvent production, with significant industrial activity. Establishing partnerships with local manufacturers can enhance market entry.
- Investment in Sustainable Practices: With the government's Green Chemistry Initiative promoting eco-friendly solvents, suppliers can invest in renewable-based products to capture emerging market demand.
Government Initiatives in the China Solvent & Intermediate Market
The Ministry of Ecology and Environment launched the 'Green Chemistry Initiative' in 2022 to promote sustainable practices in the solvent industry, focusing on reducing environmental impact. This initiative encourages manufacturers to adopt eco-friendly production methods and comply with new regulations. Additionally, the National Development and Reform Commission introduced the 'Chemical Industry Transformation Plan' in 2021, aiming to modernise production processes and improve efficiency. This plan supports innovation in the solvent sector, ensuring compliance with safety standards and enhancing overall market competitiveness.
The State Administration for Market Regulation oversees the implementation of the 'Chemical Product Safety Standards', updated in 2023 to improve safety measures in solvent handling. This regulation ensures that manufacturers comply with stringent safety protocols, improving product safety for consumers. Furthermore, the Ministry of Industry and Information Technology initiated the 'Solvent Emission Reduction Program' in 2021, targeting a 20% reduction in emissions by 2025. This program provides funding and support for manufacturers to adopt cleaner technologies and reduce environmental impact.
Future Insight of the China Solvent & Intermediate Market
The China solvent and intermediate market will experience transformative changes by 2032, primarily driven by the government's Green Chemistry Initiative aimed at promoting sustainable practices. This initiative will lead to a 30% increase in the adoption of eco-friendly solvents across various industries. Advancements in production technology will enhance operational efficiency, benefiting suppliers. The growth of the personal care sector will further elevate solvent demand, particularly in formulations, ensuring a consistent supply for buyers in the coming years.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Product Type – Glycol Ethers Dominated, Acetates Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, the largest product type category in 2025 was Glycol Ethers, with a 46% share of total revenue. Glycol ethers hold the largest share in China's solvent market due to their essential role in paints and coatings, which are vital for numerous industrial applications. The coatings industry consumed over 1 million tons of solvents in 2022, highlighting the robust demand for glycol ethers. Acetates are projected to grow fastest, at a CAGR of 7.6% during 2026–2032. Acetates are experiencing rapid growth as they find increasing applications in various industrial sectors, particularly due to their effective solvent properties. The expansion of the packaging industry, notably in printing applications, significantly fuels this growth. Suppliers should focus on enhancing their acetate offerings to leverage the rising demand in industrial applications.
By Source Type – Petrochemical-Based Dominated, Renewable-Based Expected to Grow Fastest
With a 45% revenue share in 2025, Petrochemical-Based was the largest source type category. Petrochemical-based solvents dominate the market, constituting the majority of solvent production in China. Established supply chains and the prevalent use of petrochemicals in solvent manufacturing reinforce this leading position. Renewable-Based is set to record the highest CAGR in this split, 7.7% over 2026–2032. Renewable-based solvents are witnessing the fastest growth as the interest in sustainable production methods escalates. The government's 'Green Chemistry Initiative' actively supports these sustainable practices, propelling further expansion in this segment. Buyers may increasingly pursue renewable-based options as sustainability becomes a key focus in procurement strategies.
By Application Area – Paints & Coatings Dominated, Cosmetics & Fragrances Expected to Grow Fastest
Paints & Coatings took a 48% share of application area in 2025, more than any other category. Paints and coatings represent the primary application area for solvents, crucial for enhancing product performance across diverse industrial uses. The substantial consumption within this sector underscores the critical role of solvents in manufacturing processes. The quickest growth will come from Cosmetics & Fragrances, forecast to expand at a CAGR of 8.4% between 2026 and 2032. Cosmetics and fragrances are the fastest-growing application area, driven by the surging demand for personal care products. As consumers increasingly prioritise quality formulations, the need for effective solvents in this sector is rapidly escalating. Suppliers should tailor their products to meet the specific requirements of the cosmetics and fragrances market.
By End User – Industrial Paint Firms Dominated, Personal Care Companies Expected to Grow Fastest
Industrial Paint Firms accounted for a 35% market share by end user in 2025. Industrial paint firms are the largest consumers of solvents, relying on these substances heavily for their production processes. Their significant demand reflects the strong nature of the coatings industry in China. Over 2026–2032, Personal Care Companies are expected to post the fastest growth, at a CAGR of 8.5%. Personal care companies are the fastest-growing end users of solvents, integrating these ingredients into their formulations. The anticipated consumption of 500,000 tons of solvents by this sector by 2025 indicates robust future demand. Suppliers may benefit from developing targeted strategies to engage with personal care companies as they expand their product lines.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Solvent & Intermediate Market Outlook
- Market Size of China Solvent & Intermediate Market, 2025
- Forecast of China Solvent & Intermediate Market, 2032
- Historical Data and Forecast of China Solvent & Intermediate Revenues & Volume for the Period 2022 - 2032F
- China Solvent & Intermediate Market Trend Evolution
- China Solvent & Intermediate Market Drivers and Challenges
- China Solvent & Intermediate Price Trends
- China Solvent & Intermediate Porter's Five Forces
- China Solvent & Intermediate Industry Life Cycle
- Historical Data and Forecast of China Solvent & Intermediate Market Revenues & Volume By Product Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Solvent & Intermediate Market Revenues & Volume By Glycol Ethers for the Period 2022 - 2032F
- Historical Data and Forecast of China Solvent & Intermediate Market Revenues & Volume By Acetates for the Period 2022 - 2032F
- Historical Data and Forecast of China Solvent & Intermediate Market Revenues & Volume By Alcohol Solvents for the Period 2022 - 2032F
- Historical Data and Forecast of China Solvent & Intermediate Market Revenues & Volume By Ketones for the Period 2022 - 2032F
- Historical Data and Forecast of China Solvent & Intermediate Market Revenues & Volume By Source Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Solvent & Intermediate Market Revenues & Volume By Petrochemical-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Solvent & Intermediate Market Revenues & Volume By Natural/Petro-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Solvent & Intermediate Market Revenues & Volume By Renewable-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Solvent & Intermediate Market Revenues & Volume By Synthetically Derived for the Period 2022 - 2032F
- Historical Data and Forecast of China Solvent & Intermediate Market Revenues & Volume By Application Area for the Period 2022 - 2032F
- Historical Data and Forecast of China Solvent & Intermediate Market Revenues & Volume By Paints & Coatings for the Period 2022 - 2032F
- Historical Data and Forecast of China Solvent & Intermediate Market Revenues & Volume By Printing Inks for the Period 2022 - 2032F
- Historical Data and Forecast of China Solvent & Intermediate Market Revenues & Volume By Cosmetics & Fragrances for the Period 2022 - 2032F
- Historical Data and Forecast of China Solvent & Intermediate Market Revenues & Volume By Agrochemicals for the Period 2022 - 2032F
- Historical Data and Forecast of China Solvent & Intermediate Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Solvent & Intermediate Market Revenues & Volume By Industrial Paint Firms for the Period 2022 - 2032F
- Historical Data and Forecast of China Solvent & Intermediate Market Revenues & Volume By Packaging Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Solvent & Intermediate Market Revenues & Volume By Personal Care Companies for the Period 2022 - 2032F
- Historical Data and Forecast of China Solvent & Intermediate Market Revenues & Volume By Pesticide Manufacturers for the Period 2022 - 2032F
- China Solvent & Intermediate Import Export Trade Statistics
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Source Type
- Market Opportunity Assessment By Application Area
- Market Opportunity Assessment By End User
- China Solvent & Intermediate Top Companies Market Share
- China Solvent & Intermediate Competitive Benchmarking By Technical and Operational Parameters
- China Solvent & Intermediate Company Profiles
- China Solvent & Intermediate Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Product Type
- Glycol Ethers
- Acetates
- Alcohol Solvents
- Ketones
By Source Type
- Petrochemical-Based
- Natural/Petro-Based
- Renewable-Based
- Synthetically Derived
By Application Area
- Paints & Coatings
- Printing Inks
- Cosmetics & Fragrances
- Agrochemicals
By End User
- Industrial Paint Firms
- Packaging Industry
- Personal Care Companies
- Pesticide Manufacturers































