China Specialty Monomers Market Size & Growth Rate
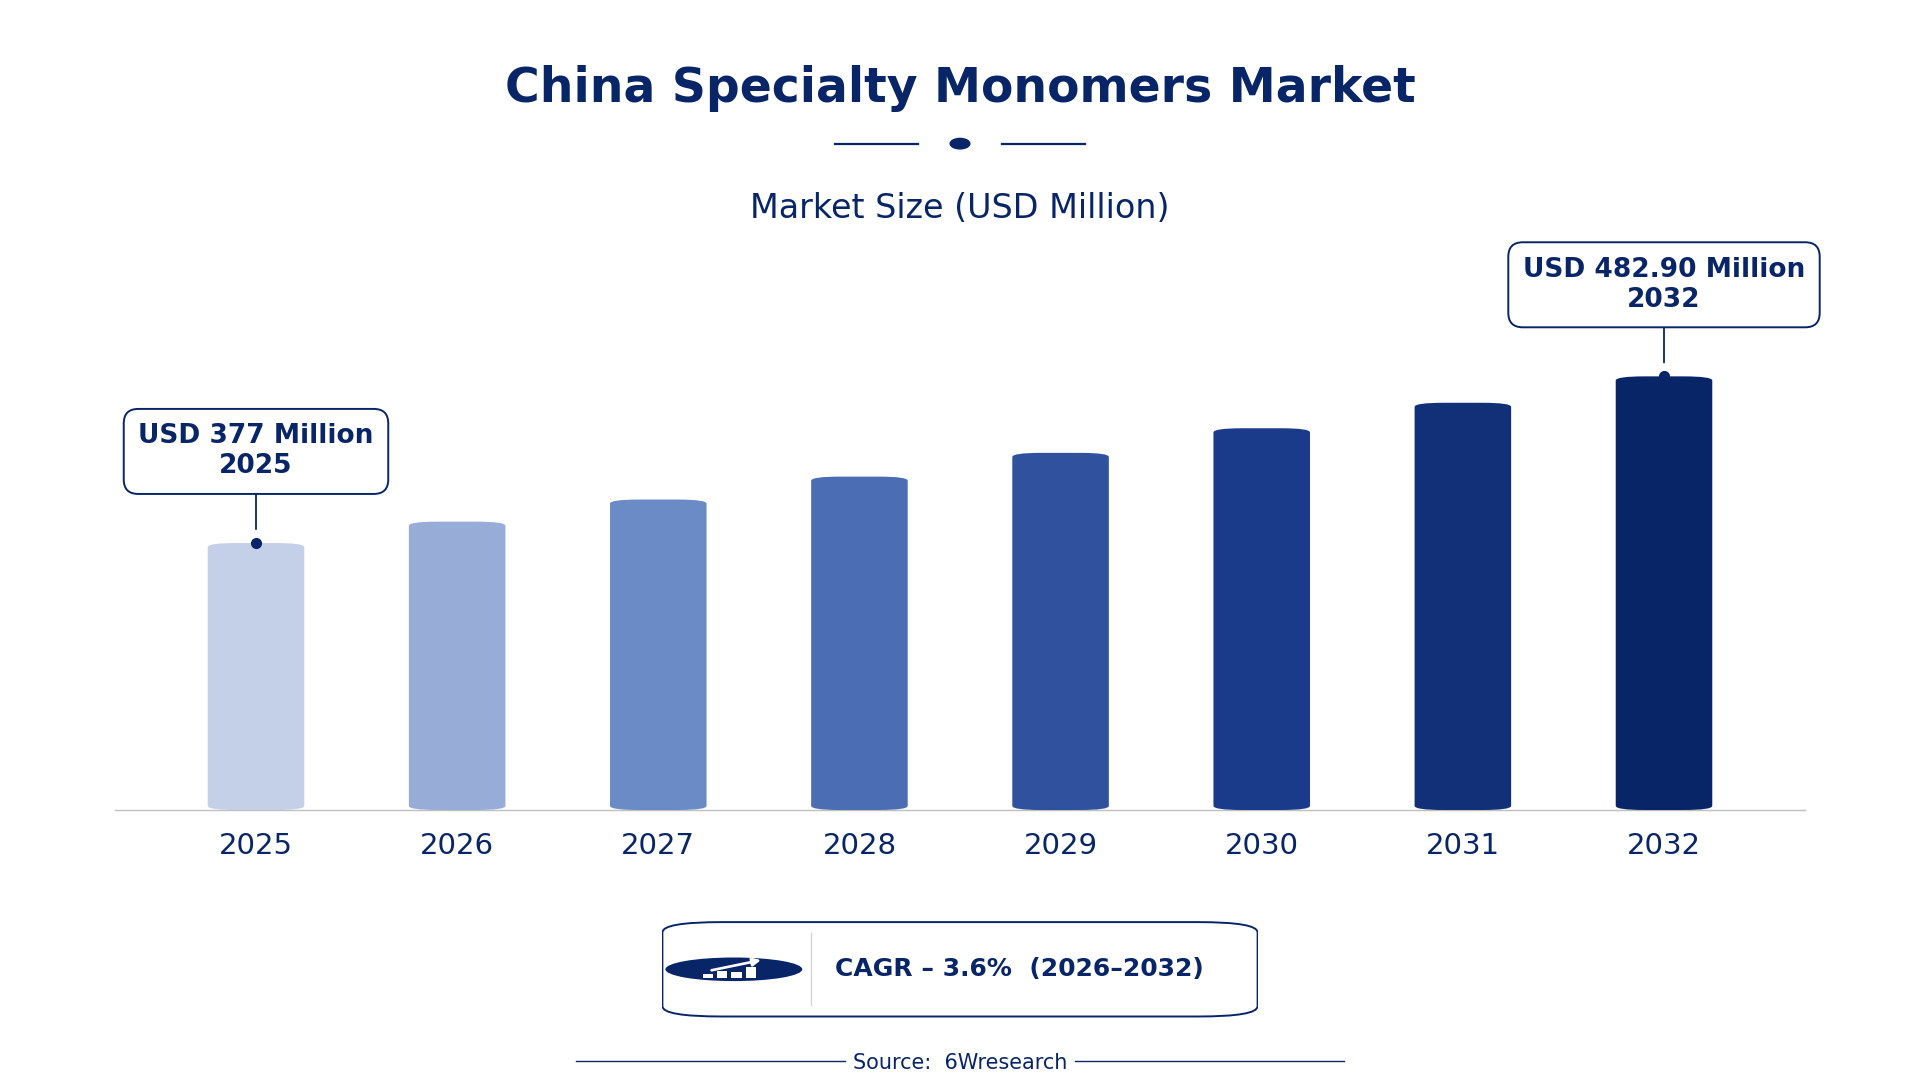
According to 6Wresearch internal database and industry insights, the China Specialty Monomers Market was valued at USD 377 million in 2025 and is projected to reach USD 482.90 million by 2032, growing at a CAGR of approximately 3.6% during 2026–2032.
China Specialty Monomers Market Highlights
| Report Metric | Details |
| Report Name | China Specialty Monomers Market |
| Market Size 2025 | USD 377 million |
| Market Size 2032 | USD 482.90 million |
| Absolute Growth 2025–2032 | USD 105.90 million |
| CAGR 2026–2032 | 3.6% |
| Peak Annual Growth | 6.6% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Monomer Type, 2025 | Methacrylate Monomers (43% share) |
| Leading Polymer Compatibility, 2025 | Acrylic Resins (52% share) |
| Leading Key Application, 2025 | Coatings & Adhesives (38% share) |
| Leading End User, 2025 | Paint Manufacturers (50% share) |
| Fastest-Growing Monomer Type | Maleic Anhydride (4.7% CAGR) |
| Fastest-Growing Polymer Compatibility | PVDF Resins (6.4% CAGR) |
| Fastest-Growing Key Application | Electrical Insulation (6.3% CAGR) |
| Fastest-Growing End User | Cable Coating Companies (5.2% CAGR) |
| Growing Sector | automotive sector |
| Key End Users | paint manufacturers, vehicle OEMs, plastic sheet producers, cable coating companies |
China Specialty Monomers Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
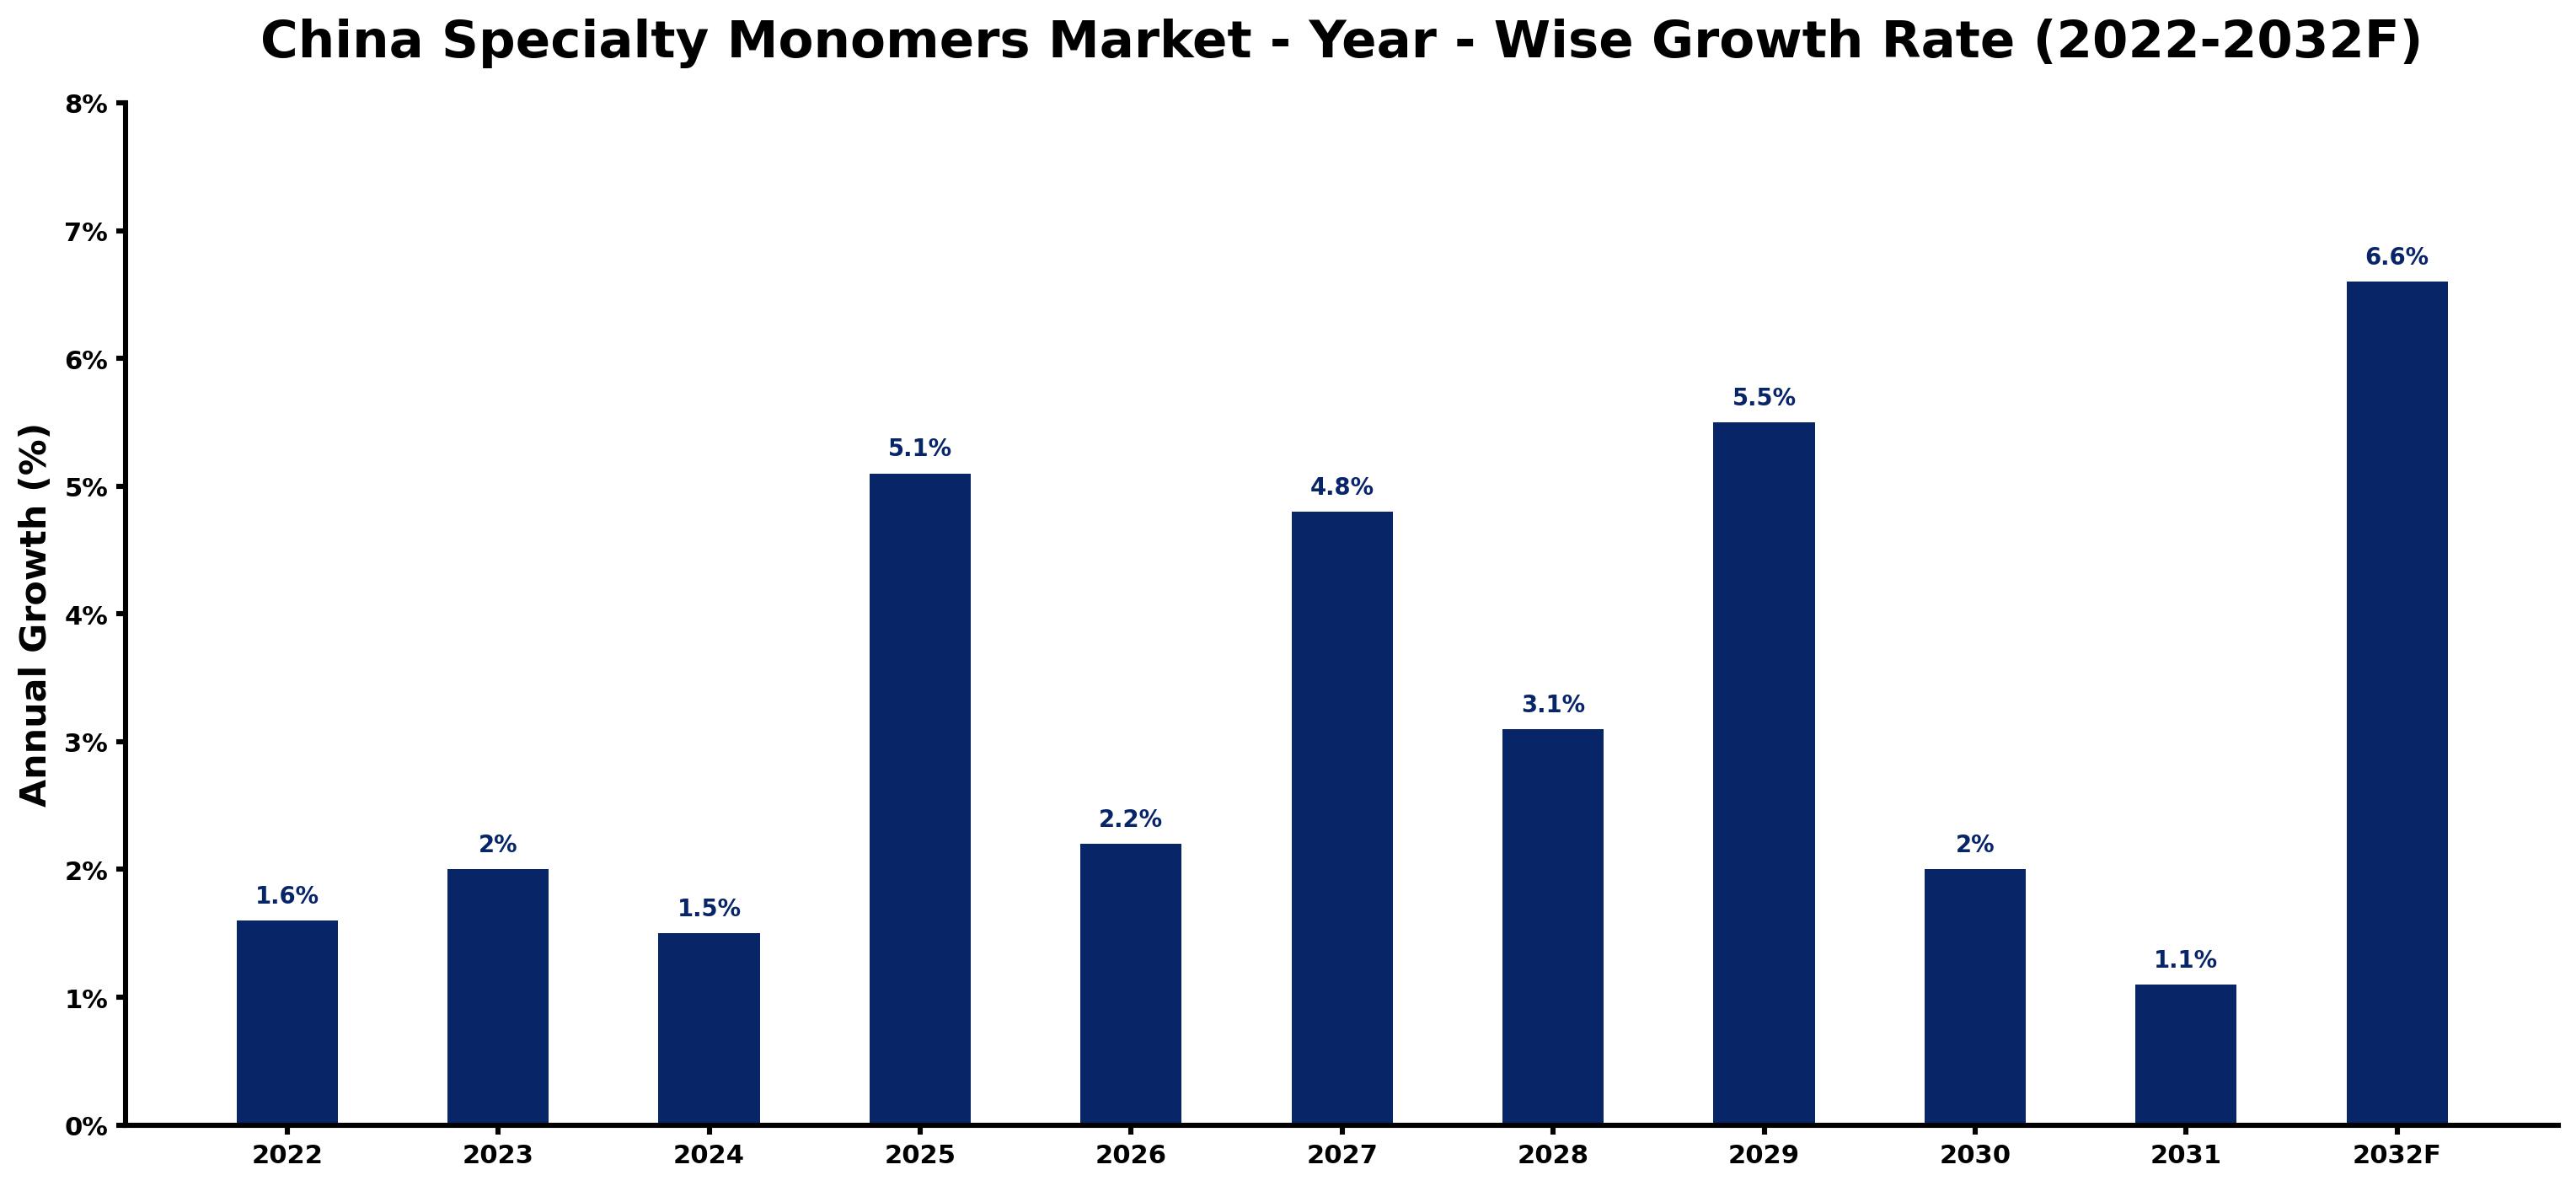
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 1.6 | The market experienced steady demand from various end-use sectors, including automotive and construction. |
| 2023 | 2.0 | Increased production in the coatings and adhesives sector spurred demand for specialty monomers. |
| 2024 | 1.5 | The growth rate slowed as the market adjusted to previous high demand levels in automotive applications. |
| 2025 | 5.1 | A surge in demand from the automotive sector, particularly for plastics, contributed to growth in specialty monomers. |
| 2026 | 2.2 | Manufacturers are expected to slow production in response to new regulatory changes in environmental standards. |
| 2027 | 4.8 | Increased vehicle production will drive demand for specialty monomers, particularly in automotive plastics. |
| 2028 | 3.1 | Demand is projected to stabilise as manufacturers adapt to the updated National Standard for Coatings. |
| 2029 | 5.5 | An uptick in demand is anticipated, driven by rising automotive production and consumer goods sectors. |
| 2030 | 2.0 | Growth will slow as manufacturers adjust to evolving market conditions and production capacities. |
| 2031 | 1.1 | Demand growth will continue to decelerate as the market matures and stabilises. |
| 2032 | 6.6 | A resurgence in demand is expected as new automotive initiatives boost specialty monomer usage. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Specialty Monomers Market Synopsis
Specialty Monomers in China includes chemical compounds primarily used in the production of polymers and resins. These compounds are synthesised through various chemical processes for applications in coatings, adhesives, and plastics. The China Specialty Monomers Market is growing, driven by increasing demand from the automotive sector, which is projected to consume 30% of specialty monomers by 2025. The updated National Standard for Coatings improves environmental safety, leading to more sustainable production practices. With a population exceeding 1.4 billion, the demand for consumer goods further fuels this market's expansion.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing automotive production increases the demand for specialty monomers in automotive plastics. | Driver | High | Styrenic Monomers |
| Rising demand for coatings and adhesives drives the need for acrylic resins. | Driver | High | Acrylic Resins |
| Investment in eco-friendly production facilities creates opportunities for sustainable specialty monomers. | Opportunity | High | Methacrylate Monomers |
| The expansion of the electric vehicle market presents new avenues for specialty monomer applications. | Opportunity | High | Automotive Plastics |
| Stricter regulations on VOC emissions may limit formulation options for manufacturers. | Restraint | High | Coatings & Adhesives |
| Environmental compliance costs can burden smaller manufacturers, affecting their competitiveness. | Restraint | Medium | Acrylic Resins |
| The Specialty Monomers Market in China faces challenges from fluctuating raw material prices. | Challenge | High | Styrenic Monomers |
| Limited awareness of new applications in emerging sectors may hinder market growth. | Challenge | Medium | Maleic Anhydride |
Evaluation of Drivers in China Specialty Monomers Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased vehicle production drives demand for durable automotive plastics. | Styrenic Monomers | The automotive sector is expected to consume 30% of specialty monomers by 2025. |
| Growing demand for high-performance coatings boosts the use of acrylic resins. | Acrylic Resins | The paint and coatings industry generated revenues exceeding $50 billion in 2022. |
| Investment in sustainable production methods increases specialty chemical output. | Methacrylate Monomers | The 'New Materials Industry Development Plan' aims to raise production capacity by 20% by 2025. |
| Rising consumer demand for packaging solutions increases specialty monomer usage. | Packaging Films | China's population of approximately 1.4 billion drives significant demand for consumer goods. |
| Technological advancements in polymerization processes improve product quality. | Polyester Resins | The Shanghai Chemical Industry Park is a major hub for specialty monomer production, enhancing output. |
Market growth in China for Specialty Monomers rests on increased vehicle production, rising consumer demand for packaging solutions, and investment in sustainable production methods. The automotive sector is set to consume 30% of specialty monomers by 2025, boosting demand for durable plastics. The paint and coatings industry generated revenues exceeding $50 billion in 2022, leading to increased use of acrylic resins. The 'New Materials Industry Development Plan' aims to raise production capacity by 20% by 2025, enhancing output in specialty chemicals. Technological advancements in polymerization processes are also improving product quality, stimulating further demand.
Evaluation of Restraints in China Specialty Monomers Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Stricter regulations on VOC emissions may limit formulation options for manufacturers. | Coatings & Adhesives | The Ministry of Ecology and Environment has set stricter regulations impacting specialty monomer formulations, increasing compliance costs. |
| Environmental compliance costs can burden smaller manufacturers, affecting their competitiveness. | Acrylic Resins | The revised National Standard for Environmental Protection in Coatings reduces harmful substances, raising production costs for compliance. |
| Fluctuating raw material prices can disrupt production schedules and profitability. | Styrenic Monomers | Volatility in the chemical supply chain affects pricing stability, leading to unpredictable costs for manufacturers. |
| Limited awareness of new applications in emerging sectors may hinder market growth. | Maleic Anhydride | Manufacturers may not fully explore potential uses in new applications, restricting market expansion opportunities. |
| Competition from alternative materials can impact market share for specialty monomers. | Methacrylate Monomers | Substitutes in coatings and adhesives may reduce demand for traditional specialty monomers, affecting sales. |
China Specialty Monomers Market Challenges
The China Specialty Monomers Market faces a critical skills shortage, which limits production efficiency for producers in the automotive sector. This gap exists due to a lack of specialised training programmes, resulting in delays that can extend lead times by 20%. Suppliers struggle with outdated technology, as many facilities have not upgraded since 2010, which can increase production costs by 15% and raise prices for buyers. Intense competition from international markets pressures local producers to lower prices, often compromising quality and reliability for domestic buyers. Stricter regulations on VOC emissions from the Ministry of Ecology and Environment require costly reformulations, impacting supply timelines for coatings manufacturers.
Trends in the China Specialty Monomers Market
Buyers and suppliers in the China Specialty Monomers Market are adjusting to the following trends.
- Shift towards Eco-Friendly Production: The Shanghai Chemical Industry Park is adopting sustainable practices, focusing on reducing carbon emissions. In 2022, the Ministry of Ecology and Environment launched a subsidy program for eco-friendly specialty chemical production, supporting this transition.
- Rise of Electric Vehicles: The installed base of electric vehicles in China surpassed 10 million units in 2022, driving demand for specialty monomers in automotive applications. This shift is expected to significantly increase the market for automotive plastics.
- Increased Focus on High-Performance Coatings: Paint manufacturers are prioritising high-performance formulations, utilising specialty monomers to improve product quality. The coatings industry generated revenues exceeding $50 billion in 2022, reflecting this growing trend.
- Expansion of Specialty Monomer Applications: New applications for specialty monomers are emerging in sectors like electrical insulation. The demand for electrical insulation products is projected to grow, driven by safety and performance requirements.
Investment Opportunities in the China Specialty Monomers Market
Several openings in the China Specialty Monomers Market merit attention from investors.
- Growing Demand for Eco-Friendly Solutions: The demand for eco-friendly specialty monomers is increasing, with the market expected to expand. The Ministry of Ecology and Environment's subsidy program supports this shift, focusing on reducing carbon emissions.
- Expansion in the Automotive Sector: The automotive sector's growth presents opportunities for specialty monomer suppliers. With 30% of specialty monomers expected for automotive use by 2025, partnerships with vehicle OEMs can be beneficial.
- Investment in New Applications: Investing in research for new applications of specialty monomers can yield high returns. The electrical insulation market is expanding, driven by safety and performance requirements.
- Utilising Advanced Production Techniques: Advanced production techniques can improve the quality of specialty monomers. Collaborating with facilities in the Shanghai Chemical Industry Park can provide access to new technology.
Government Initiatives in the China Specialty Monomers Market
The 'New Materials Industry Development Plan' by the Ministry of Industry and Information Technology aims to increase specialty chemical production capacity by 20% by 2025. This measure builds on previous regulations by focusing on innovation and sustainability, ensuring that producers can meet growing market demands while adhering to environmental standards. The plan encourages investments in new technologies and processes, creating a more competitive industry.
The Ministry of Ecology and Environment oversees the implementation of various environmental standards and funding programs. Their initiatives include subsidies for eco-friendly specialty chemical production, which support manufacturers in adopting sustainable practices. The agency also approves projects that align with national environmental goals, ensuring compliance with regulations while promoting innovation in the specialty chemicals sector. This support helps producers transition to greener production methods and improves market competitiveness.
Future Insight of the China Specialty Monomers Market
By 2032, buyers and suppliers in the China Specialty Monomers Market can expect significant changes driven by key developments. The National Standard for Coatings will evolve, enhancing product safety and fostering innovation. The 'New Materials Industry Development Plan' will stimulate advancements in production methods, making local suppliers more competitive. With the installed base of electric vehicles projected to surpass 20 million units, demand for specialty monomers in automotive applications will rise sharply. The paint and coatings industry will likely continue generating revenues above $50 billion, solidifying the market's growth potential.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Monomer Type – Methacrylate Monomers Dominated, Maleic Anhydride Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, the largest monomer type category in 2025 was Methacrylate Monomers, with a 43% share of total revenue. Methacrylate monomers command the largest market share in China due to their essential role in producing coatings and adhesives. Their superior adhesion properties are particularly valued by manufacturers in the automotive and construction sectors, making them a preferred choice for high-performance applications. Maleic Anhydride is projected to grow fastest, at a CAGR of 4.7% during 2026–2032. Maleic anhydride is experiencing rapid growth as it plays a crucial role as a chemical intermediate in various applications, especially in specialty resins. The automotive sector's increasing consumption of specialty monomers will likely drive further demand for maleic anhydride, widening its market position. Suppliers should focus on enhancing maleic anhydride production capabilities to capitalise on its growing market share.
By Polymer Compatibility – Acrylic Resins Dominated, PVDF Resins Expected to Grow Fastest
Acrylic Resins held a 52% share of the China Specialty Monomers Market by polymer compatibility in 2025. Acrylic resins hold the largest market share due to their extensive use in coatings and adhesives, where clarity and UV resistance are paramount. This widespread application makes them indispensable for manufacturers aiming for high-performance products, especially in the coatings sector. The quickest growth will come from PVDF Resins, forecast to expand at a CAGR of 6.4% between 2026 and 2032. PVDF resins are projected to grow rapidly as they cater to specialised applications that demand high chemical resistance, particularly in niche markets. As industries increasingly seek durable materials, the demand for PVDF resins is expected to surge, enhancing their market position. Buyers should consider increasing their sourcing of PVDF resins to meet the rising demand for specialised applications.
By Key Application – Coatings & Adhesives Dominated, Electrical Insulation Expected to Grow Fastest
Coatings & Adhesives took a 38% share of key application in 2025, more than any other category. Coatings and adhesives represent the leading application area for specialty monomers, driven by their critical role in various manufacturing processes. This segment's prominence is underscored by the substantial revenues generated in the paint and coatings industry. Electrical Insulation is set to record the highest CAGR in this split, 6.3% over 2026–2032. Electrical insulation is the fastest-growing application, as safety and performance in electrical systems become increasingly paramount. The rise in electric vehicle installations further fuels this demand, highlighting the need for effective insulation solutions. Suppliers must prioritise the development of specialty monomers tailored for electrical insulation to capture emerging market opportunities.
By End User – Paint Manufacturers Dominated, Cable Coating Companies Expected to Grow Fastest
In 2025, Paint Manufacturers led the end user split with a 50% share. Paint manufacturers represent the largest end user group for specialty monomers, relying heavily on them for high-performance formulations in coatings. Their significant demand is reflected in the coatings industry's revenue, which surpassed $50 billion in 2022, underscoring their market influence. Over 2026–2032, Cable Coating Companies are expected to post the fastest growth, at a CAGR of 5.2%. Cable coating companies are experiencing rapid growth as they require specialty monomers for protective coatings, essential for ensuring safety and durability in electrical applications. This trend aligns with the increasing electrification across various sectors, driving further demand. Suppliers should strengthen collaborations with cable coating companies to leverage the growing need for protective coatings.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Specialty Monomers Market Outlook
- Market Size of China Specialty Monomers Market, 2025
- Forecast of China Specialty Monomers Market, 2032
- Historical Data and Forecast of China Specialty Monomers Revenues & Volume for the Period 2022 - 2032F
- China Specialty Monomers Market Trend Evolution
- China Specialty Monomers Market Drivers and Challenges
- China Specialty Monomers Price Trends
- China Specialty Monomers Porter's Five Forces
- China Specialty Monomers Industry Life Cycle
- Historical Data and Forecast of China Specialty Monomers Market Revenues & Volume By Monomer Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Monomers Market Revenues & Volume By Methacrylate Monomers for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Monomers Market Revenues & Volume By Styrenic Monomers for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Monomers Market Revenues & Volume By Maleic Anhydride for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Monomers Market Revenues & Volume By Fluoro Monomers for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Monomers Market Revenues & Volume By Polymer Compatibility for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Monomers Market Revenues & Volume By Acrylic Resins for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Monomers Market Revenues & Volume By ABS & SAN Plastics for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Monomers Market Revenues & Volume By Polyester Resins for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Monomers Market Revenues & Volume By PVDF Resins for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Monomers Market Revenues & Volume By Key Application for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Monomers Market Revenues & Volume By Coatings & Adhesives for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Monomers Market Revenues & Volume By Automotive Plastics for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Monomers Market Revenues & Volume By Packaging Films for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Monomers Market Revenues & Volume By Electrical Insulation for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Monomers Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Monomers Market Revenues & Volume By Paint Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Monomers Market Revenues & Volume By Vehicle OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Monomers Market Revenues & Volume By Plastic Sheet Producers for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Monomers Market Revenues & Volume By Cable Coating Companies for the Period 2022 - 2032F
- China Specialty Monomers Import Export Trade Statistics
- Market Opportunity Assessment By Monomer Type
- Market Opportunity Assessment By Polymer Compatibility
- Market Opportunity Assessment By Key Application
- Market Opportunity Assessment By End User
- China Specialty Monomers Top Companies Market Share
- China Specialty Monomers Competitive Benchmarking By Technical and Operational Parameters
- China Specialty Monomers Company Profiles
- China Specialty Monomers Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Monomer Type
- Methacrylate Monomers
- Styrenic Monomers
- Maleic Anhydride
- Fluoro Monomers
By Polymer Compatibility
- Acrylic Resins
- ABS & SAN Plastics
- Polyester Resins
- PVDF Resins
By Key Application
- Coatings & Adhesives
- Automotive Plastics
- Packaging Films
- Electrical Insulation
By End User
- Paint Manufacturers
- Vehicle OEMs
- Plastic Sheet Producers
- Cable Coating Companies































