China Spine Fixation Market Size & Growth Rate
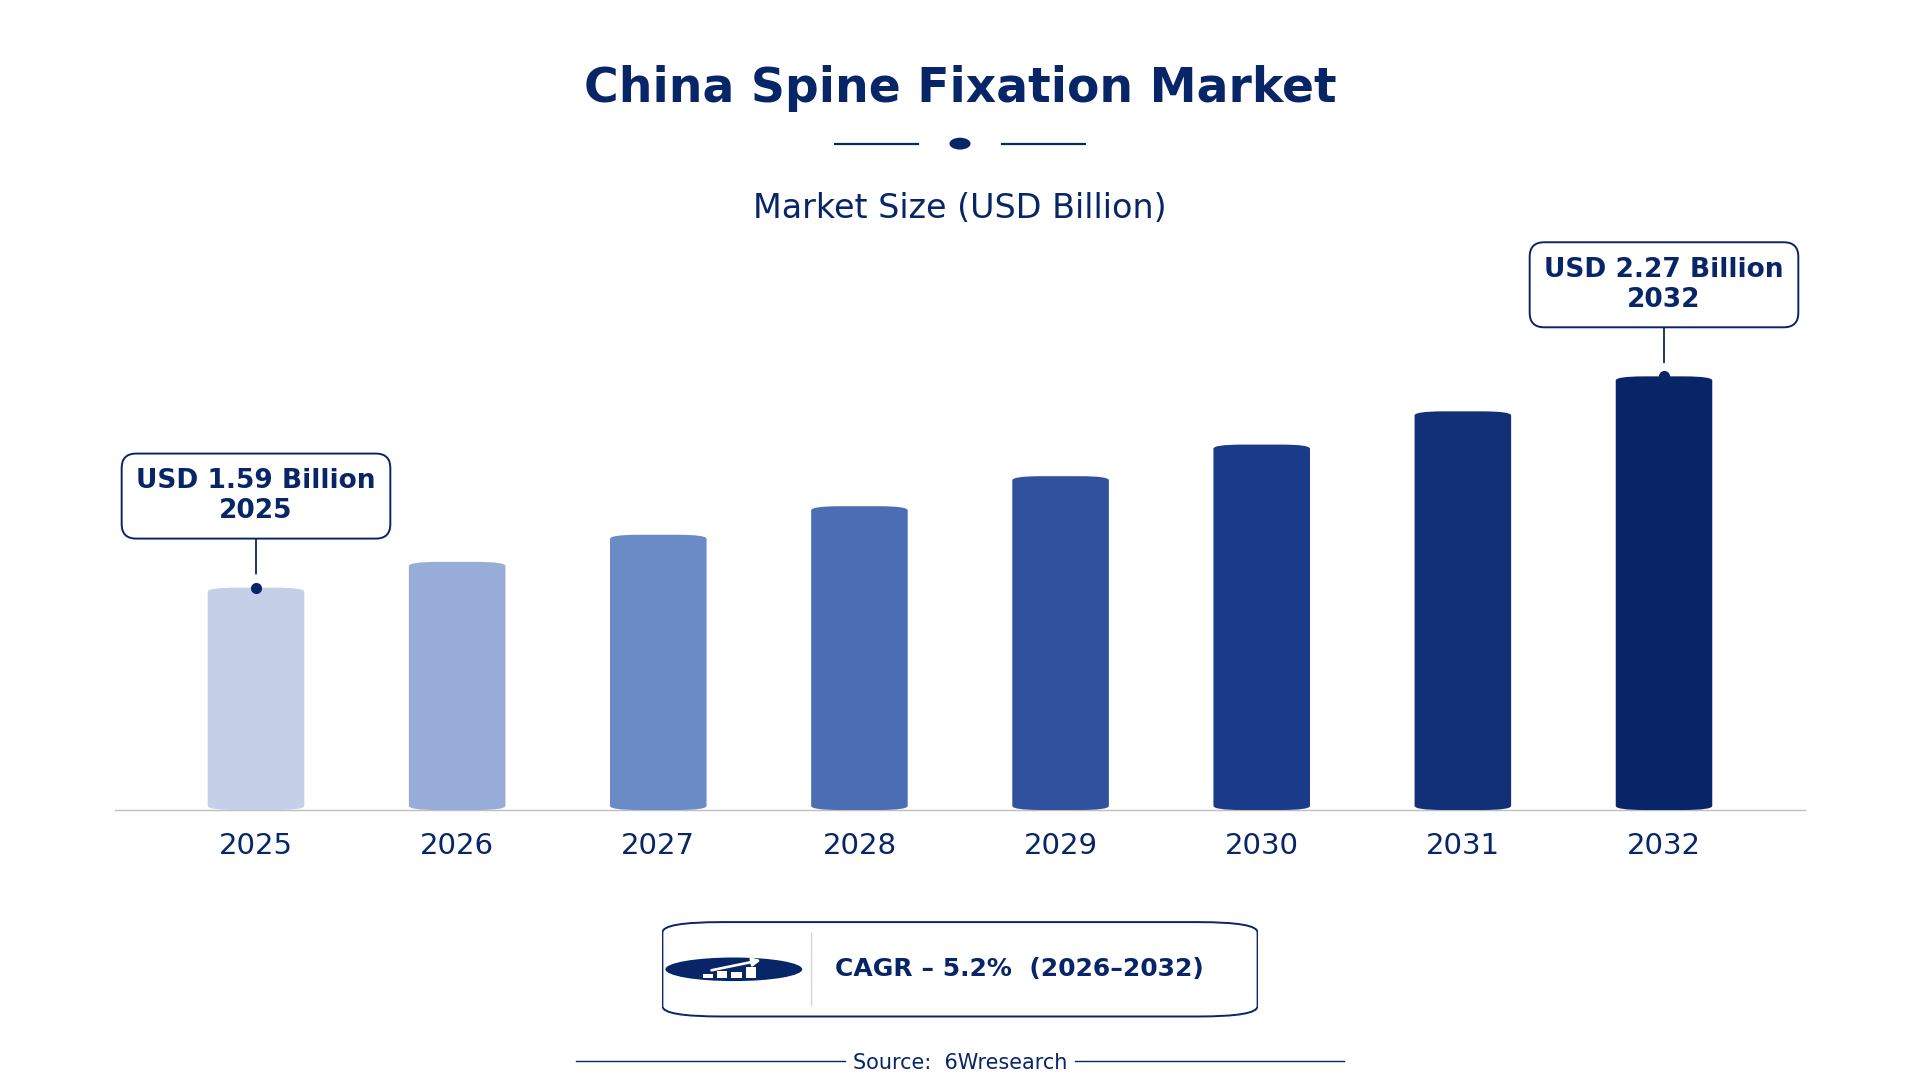
According to 6Wresearch internal database and industry insights, the China Spine Fixation Market was valued at USD 1.59 billion in 2025 and is projected to reach USD 2.27 billion by 2032, growing at a CAGR of approximately 5.2% during 2026–2032.
China Spine Fixation Market Highlights
| Report Metric | Details |
| Report Name | China Spine Fixation Market |
| Market Size 2025 | USD 1.59 billion |
| Market Size 2032 | USD 2.27 billion |
| Absolute Growth 2025–2032 | USD 0.68 billion |
| CAGR 2026–2032 | 5.2% |
| Peak Annual Growth | 7.7% in 2029 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Fixation Type, 2025 | Pedicle Screw Systems (44% share) |
| Leading Material Used, 2025 | Titanium/SS (50% share) |
| Leading Implant Site, 2025 | Thoracic/Lumbar Spine (53% share) |
| Leading End User, 2025 | Orthopedic Hospitals (51% share) |
| Fastest-Growing Fixation Type | Minimally Invasive Fixation (6.9% CAGR) |
| Fastest-Growing Material Used | PEEK/Carbon Fiber (7.0% CAGR) |
| Fastest-Growing Implant Site | Interbody Support (7.3% CAGR) |
| Fastest-Growing End User | Surgical Centers (6.6% CAGR) |
| Growing Sector | Orthopedic Hospitals |
| Key End Users | Orthopedic Hospitals, Surgical Centers, Spine Surgeons |
China Spine Fixation Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
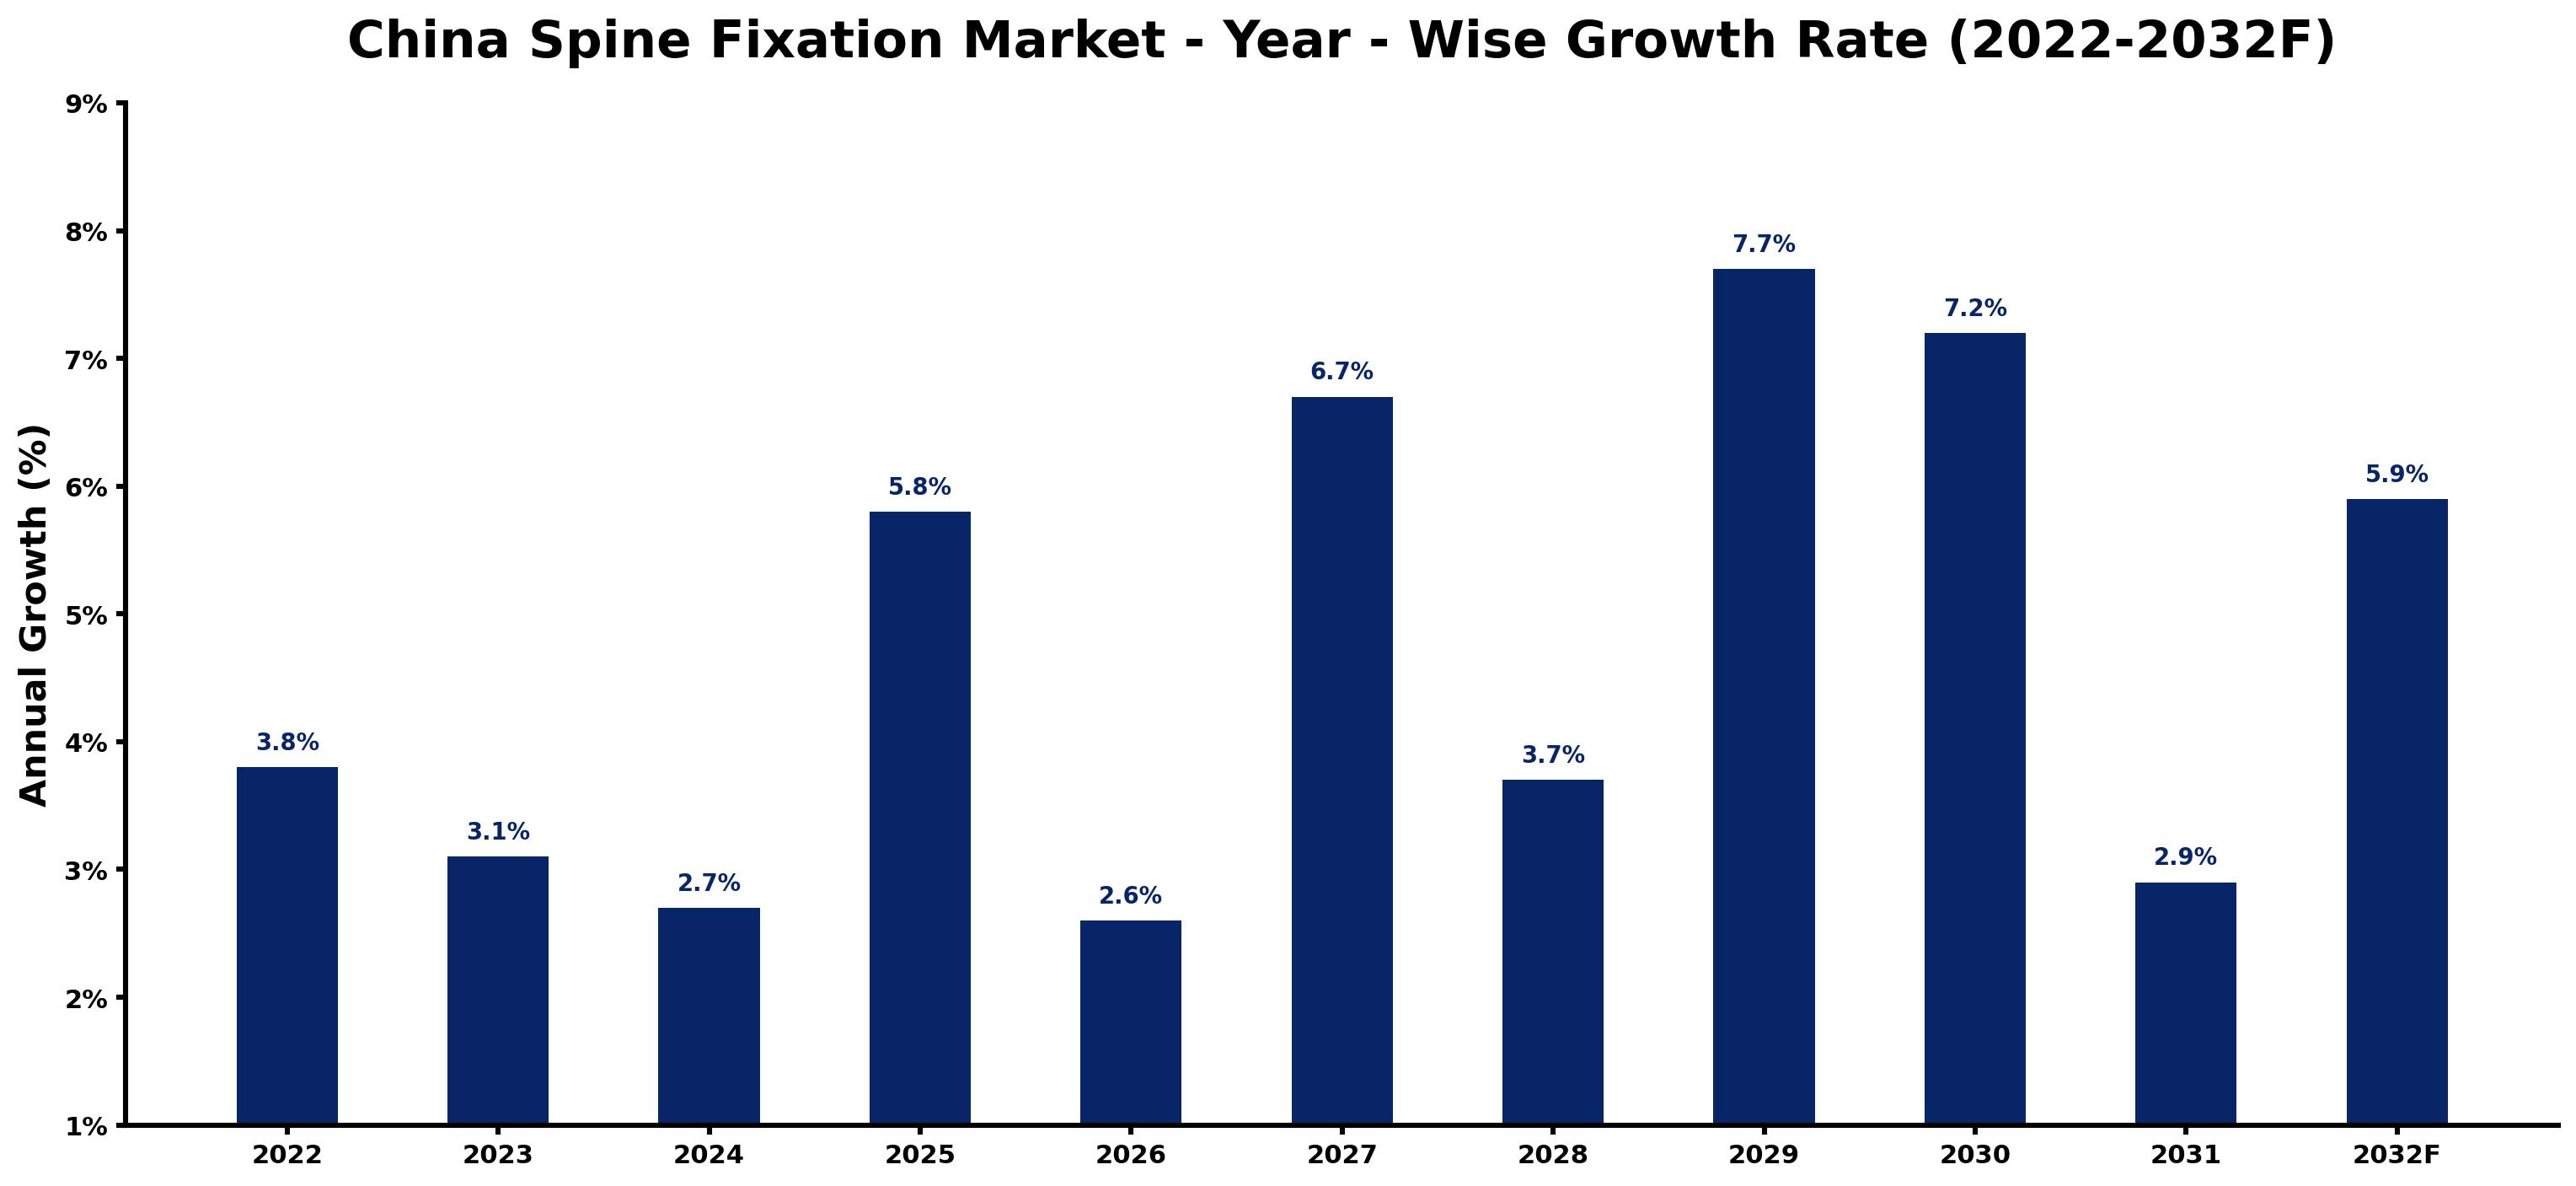
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.8 | The market showed steady growth due to increased surgeries and hospital capacities. |
| 2023 | 3.1 | Growth slowed as the National Health Commission's initiatives faced implementation challenges. |
| 2024 | 2.7 | Demand continued to rise, but growth decelerated due to longer regulatory approval timelines. |
| 2025 | 5.8 | A surge in surgeries led to accelerated growth, driven by improved hospital infrastructure. |
| 2026 | 2.6 | Market growth is expected to slow as hospitals adjust to new regulations and standards. |
| 2027 | 6.7 | Increased investment in surgical technologies is projected to boost growth, attracting more patients. |
| 2028 | 3.7 | Growth is expected to slow as the market stabilises after the previous year's surge in surgeries. |
| 2029 | 7.7 | A peak in growth is projected due to heightened demand for advanced fixation devices. |
| 2030 | 7.2 | Growth is expected to slow slightly as market conditions normalise after peak demand. |
| 2031 | 2.9 | The market is projected to experience slower growth as competition intensifies among suppliers. |
| 2032 | 5.9 | A rebound in growth is expected as new technologies gain traction in hospitals. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Spine Fixation Market Synopsis
The China Spine Fixation Market encompasses medical devices used to stabilise the spine during surgical procedures. These products are typically made from materials such as titanium and stainless steel and are essential for treating spinal deformities and trauma. The market is expanding due to the increasing number of spine surgeries, with approximately 300,000 performed in 2022. Factors driving this growth include a rise in spinal disorders and government initiatives to improve treatment accessibility, such as the National Spine Health Initiative launched in 2021.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising prevalence of spinal disorders drives demand for surgical interventions. | Driver | High | Pedicle Screw Systems |
| Increasing adoption of minimally invasive techniques enhances market opportunities. | Driver | High | Minimally Invasive Fixation |
| Growing demand for advanced surgical technologies presents investment opportunities. | Opportunity | High | Orthopedic Hospitals |
| The establishment of new surgical centres expands the market for spine fixation products. | Opportunity | Medium | Surgical Centers |
| Regulatory hurdles delay product approvals and market entry for new devices. | Restraint | High | Plates & Cages |
| Limited availability of advanced materials restricts product development. | Restraint | Medium | Titanium/SS |
| High costs associated with advanced technologies deter some hospitals from upgrading. | Challenge | High | Rod Systems |
| Supply chain disruptions impact the timely availability of fixation devices. | Challenge | Medium | Minimally Invasive Fixation |
Evaluation of Drivers in China Spine Fixation Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increasing number of spine surgeries due to rising spinal disorders. | Pedicle Screw Systems | Approximately 300,000 surgeries were performed in China in 2022, boosting demand. |
| Government initiatives promoting minimally invasive surgical techniques. | Minimally Invasive Fixation | The National Health Commission's support for these techniques is driving greater adoption. |
| Investment in advanced surgical technologies improves operational capabilities. | Orthopedic Hospitals | The Chinese government allocated $10 million for research in spine surgery technologies in 2022. |
| Growing patient population aged around 60 increases surgery demand. | Rod Systems | The average age of patients undergoing spine surgery is around 60 years. |
| Rising popularity of PEEK implants due to their imaging compatibility. | PEEK/Carbon Fiber | PEEK implants are gaining traction, resulting in increased purchases by hospitals. |
In 2022, around 300,000 spine surgeries were performed, which spurred demand for fixation solutions. Support for minimally invasive techniques is leading to wider adoption in hospitals. The average age of patients undergoing spine surgeries is approximately 60 years, which further drives the need for effective fixation solutions.
Evaluation of Restraints in China Spine Fixation Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Regulatory hurdles delay product approvals and market entry. | Plates & Cages | The Medical Device Supervision and Administration Regulation updates in 2020 have extended approval timelines. |
| Limited availability of advanced materials restricts product development. | Titanium/SS | The reliance on traditional materials hampers innovation in device design. |
| High costs associated with advanced technologies deter some hospitals from upgrading. | Rod Systems | Budget constraints in hospitals limit investment in new fixation technologies. |
| Supply chain disruptions impact the timely availability of fixation devices. | Minimally Invasive Fixation | Global supply chain issues have delayed shipments of essential components. |
| Competition among suppliers leads to price pressures in the market. | Pedicle Screw Systems | Increased competition has resulted in aggressive pricing strategies. |
China Spine Fixation Market Challenges
The China Spine Fixation Market encounters high costs for hospitals, with the average price of advanced devices rising by 15% last year. Supply chain disruptions stem from dependence on imported materials, which delay product availability for surgical centres and increase operational expenses. A lack of skilled surgeons in rural areas limits the effective use of advanced techniques, resulting in longer recovery times for patients. Regulatory challenges, particularly compliance with ISO 13485, complicate the approval process, causing delays for manufacturers in launching new spine devices.
Trends in the China Spine Fixation Market
Buyers and suppliers in the China Spine Fixation Market are adjusting to the following trends.
- Shift towards Minimally Invasive Surgery: Orthopedic hospitals are increasingly adopting minimally invasive techniques, driven by the National Health Commission's initiatives. This shift is projected to increase the demand for minimally invasive fixation products, which is expected to grow by 20% by 2025.
- Growing Adoption of PEEK Implants: The popularity of PEEK implants is rising in surgical centres due to their imaging compatibility. This trend is evident in the increasing number of surgeries, with PEEK implants gaining traction in recent years.
- Expansion of Surgical Centres: New surgical centres are being established across China, particularly in Guangdong province, which is leading in spine fixation surgeries. This expansion is anticipated to significantly increase the availability of spine fixation products.
- Increased Investment in Robotic-Assisted Surgery: The adoption of robotic-assisted spine surgery is on the rise in major cities, improving surgical precision. This trend is supported by the growing demand for advanced surgical technologies.
Investment Opportunities in the China Spine Fixation Market
Below are the investment opportunities with the strongest case in the China Spine Fixation Market.
- Investment in Advanced Surgical Technologies: With the Chinese government allocating $10 million for research in spine surgery technologies, there is an opportunity to invest in advanced devices. Hospitals are seeking solutions to improve surgical outcomes.
- Expansion of Surgical Centres: The establishment of new surgical centres in regions like Guangdong presents opportunities for suppliers. Collaborating with local hospitals can facilitate market entry and product distribution.
- Focus on Minimally Invasive Fixation Products: As demand for minimally invasive fixation rises, suppliers can concentrate on developing these products. The National Spine Health Initiative promotes such technologies, creating a favourable environment for investment.
- Partnerships with Orthopedic Hospitals: Now is an ideal time to partner with orthopedic hospitals that are expanding their surgical capabilities. This collaboration can lead to increased sales of spine fixation products.
Government Initiatives in the China Spine Fixation Market
The "National Spine Health Initiative" launched by the National Health Commission in 2021 aims to improve spine care access and quality across China. This initiative enhances the availability of spine fixation products, as it encourages hospitals to adopt advanced technologies and techniques. It also promotes research and development in this field, ensuring better patient outcomes and accessibility to care. In 2022, the Ministry of Health introduced a subsidy program for hospitals adopting advanced spine fixation technologies, providing financial support to improve surgical outcomes. The initiative aims to increase the adoption of innovative technologies in spine surgeries.
In 2023, the National Clinical Research Center for Orthopedics was established to promote research and development in spine fixation and related fields. This centre is expected to facilitate collaboration among hospitals and researchers, enhancing the development of new fixation devices. The National Medical Products Administration oversees the approval processes for these technologies, ensuring compliance with safety standards and improving market access for producers.
Future Insight of the China Spine Fixation Market
By 2032, the China Spine Fixation Market will see improved access to advanced technologies, driven by initiatives like the National Spine Health Initiative. The adoption of robotic-assisted spine surgery will enhance surgical precision and patient outcomes. Demand for minimally invasive fixation techniques will rise significantly, reflecting a shift towards more efficient care. Research funding of $10 million allocated in 2022 will support innovations in spine surgery technologies, broadening treatment options for patients.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Fixation Type – Pedicle Screw Systems Dominated, Minimally Invasive Fixation Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, the largest fixation type category in 2025 was Pedicle Screw Systems, with a 44% share of total revenue. Pedicle screw systems hold the largest market share as they are extensively used in stabilising the spine during surgeries, particularly in over 1,000 orthopedic hospitals across China. Their reliability and effectiveness in addressing spinal disorders make them the preferred choice for many surgeons. Over 2026–2032, Minimally Invasive Fixation is expected to post the fastest growth, at a CAGR of 6.9%. The demand for minimally invasive fixation is surging, spurred by the National Health Commission's endorsement of less invasive surgical techniques, projected to increase by 20% by 2025. This trend is supported by the rising number of spine surgeries, which reached approximately 300,000 in 2022. Suppliers should focus on developing minimally invasive technologies to align with market trends and meet surgical demands.
By Material Used – Titanium/SS Dominated, PEEK/Carbon Fiber Expected to Grow Fastest
With a 50% revenue share in 2025, Titanium/SS was the largest material used category. Titanium and stainless steel hold the largest market share in China due to their excellent biocompatibility and strength, making them the preferred choice for spine fixation products. Their widespread use in over 1,000 orthopedic hospitals ensures a robust installed base for these materials across the country. PEEK/Carbon Fiber is projected to grow fastest, at a CAGR of 7.0% during 2026–2032. PEEK and carbon fiber materials are rapidly gaining traction because they offer superior imaging compatibility, which is increasingly important in contemporary surgical practices. The growing adoption of these materials reflects a shift towards advanced technologies that enhance surgical precision and patient outcomes. Manufacturers should focus on developing advanced materials to meet the rising demand for imaging-compatible spine fixation solutions.
By Implant Site – Thoracic/Lumbar Spine Dominated, Interbody Support Expected to Grow Fastest
Thoracic/Lumbar Spine held a 53% share of the China Spine Fixation Market by implant site in 2025. The thoracic and lumbar spine is the leading site for fixation procedures, capturing a significant market share due to the high incidence of spinal disorders in these regions. With around 30% of adults in China experiencing spinal issues, these areas are critical for effective treatment and intervention. The quickest growth will come from Interbody Support, forecast to expand at a CAGR of 7.3% between 2026 and 2032. Interbody support is emerging as the fastest-growing segment, essential for spinal fusion procedures that are increasingly necessary due to the rising prevalence of spinal disorders. The focus on effective fusion techniques highlights the importance of this segment in achieving successful surgical outcomes. Suppliers should prioritise the development of interbody support products to align with the increasing demand for effective spinal fusion solutions.
By End User – Orthopedic Hospitals Dominated, Surgical Centers Expected to Grow Fastest
Orthopedic Hospitals accounted for a 51% market share by end user in 2025. Orthopedic hospitals dominate the market share as the primary users of spine fixation products, providing essential surgical services to patients with spinal disorders. Their extensive infrastructure and expertise in spine surgeries solidify their leading position in the market. Surgical Centers are set to record the highest CAGR in this split, 6.6% over 2026–2032. Surgical centers are experiencing the fastest growth due to their pivotal role in facilitating outpatient spine surgeries, which are becoming more common as minimally invasive techniques gain popularity. This trend signifies a shift towards more accessible surgical options for patients. Suppliers must explore partnerships with surgical centers to improve distribution and access to their spine fixation products.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Spine Fixation Market Outlook
- Market Size of China Spine Fixation Market, 2025
- Forecast of China Spine Fixation Market, 2032
- Historical Data and Forecast of China Spine Fixation Revenues & Volume for the Period 2022 - 2032F
- China Spine Fixation Market Trend Evolution
- China Spine Fixation Market Drivers and Challenges
- China Spine Fixation Price Trends
- China Spine Fixation Porter's Five Forces
- China Spine Fixation Industry Life Cycle
- Historical Data and Forecast of China Spine Fixation Market Revenues & Volume By Fixation Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Spine Fixation Market Revenues & Volume By Pedicle Screw Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Spine Fixation Market Revenues & Volume By Rod Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Spine Fixation Market Revenues & Volume By Plates & Cages for the Period 2022 - 2032F
- Historical Data and Forecast of China Spine Fixation Market Revenues & Volume By Minimally Invasive Fixation for the Period 2022 - 2032F
- Historical Data and Forecast of China Spine Fixation Market Revenues & Volume By Material Used for the Period 2022 - 2032F
- Historical Data and Forecast of China Spine Fixation Market Revenues & Volume By Titanium/SS for the Period 2022 - 2032F
- Historical Data and Forecast of China Spine Fixation Market Revenues & Volume By Alloy/CoCr for the Period 2022 - 2032F
- Historical Data and Forecast of China Spine Fixation Market Revenues & Volume By PEEK/Carbon Fiber for the Period 2022 - 2032F
- Historical Data and Forecast of China Spine Fixation Market Revenues & Volume By Composite Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of China Spine Fixation Market Revenues & Volume By Implant Site for the Period 2022 - 2032F
- Historical Data and Forecast of China Spine Fixation Market Revenues & Volume By Thoracic/Lumbar Spine for the Period 2022 - 2032F
- Historical Data and Forecast of China Spine Fixation Market Revenues & Volume By Cervical/Thoracic for the Period 2022 - 2032F
- Historical Data and Forecast of China Spine Fixation Market Revenues & Volume By Interbody Support for the Period 2022 - 2032F
- Historical Data and Forecast of China Spine Fixation Market Revenues & Volume By Posterior Segment for the Period 2022 - 2032F
- Historical Data and Forecast of China Spine Fixation Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Spine Fixation Market Revenues & Volume By Orthopedic Hospitals for the Period 2022 - 2032F
- Historical Data and Forecast of China Spine Fixation Market Revenues & Volume By Surgical Centers for the Period 2022 - 2032F
- Historical Data and Forecast of China Spine Fixation Market Revenues & Volume By Spine Surgeons for the Period 2022 - 2032F
- Historical Data and Forecast of China Spine Fixation Market Revenues & Volume By Specialty Clinics for the Period 2022 - 2032F
- China Spine Fixation Import Export Trade Statistics
- Market Opportunity Assessment By Fixation Type
- Market Opportunity Assessment By Material Used
- Market Opportunity Assessment By Implant Site
- Market Opportunity Assessment By End User
- China Spine Fixation Top Companies Market Share
- China Spine Fixation Competitive Benchmarking By Technical and Operational Parameters
- China Spine Fixation Company Profiles
- China Spine Fixation Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Fixation Type
- Pedicle Screw Systems
- Rod Systems
- Plates & Cages
- Minimally Invasive Fixation
By Material Used
- Titanium/SS
- Alloy/CoCr
- PEEK/Carbon Fiber
- Composite Alloys
By Implant Site
- Thoracic/Lumbar Spine
- Cervical/Thoracic
- Interbody Support
- Posterior Segment
By End User
- Orthopedic Hospitals
- Surgical Centers
- Spine Surgeons
- Specialty Clinics































