India Spine Fixation Market Size & Growth Rate
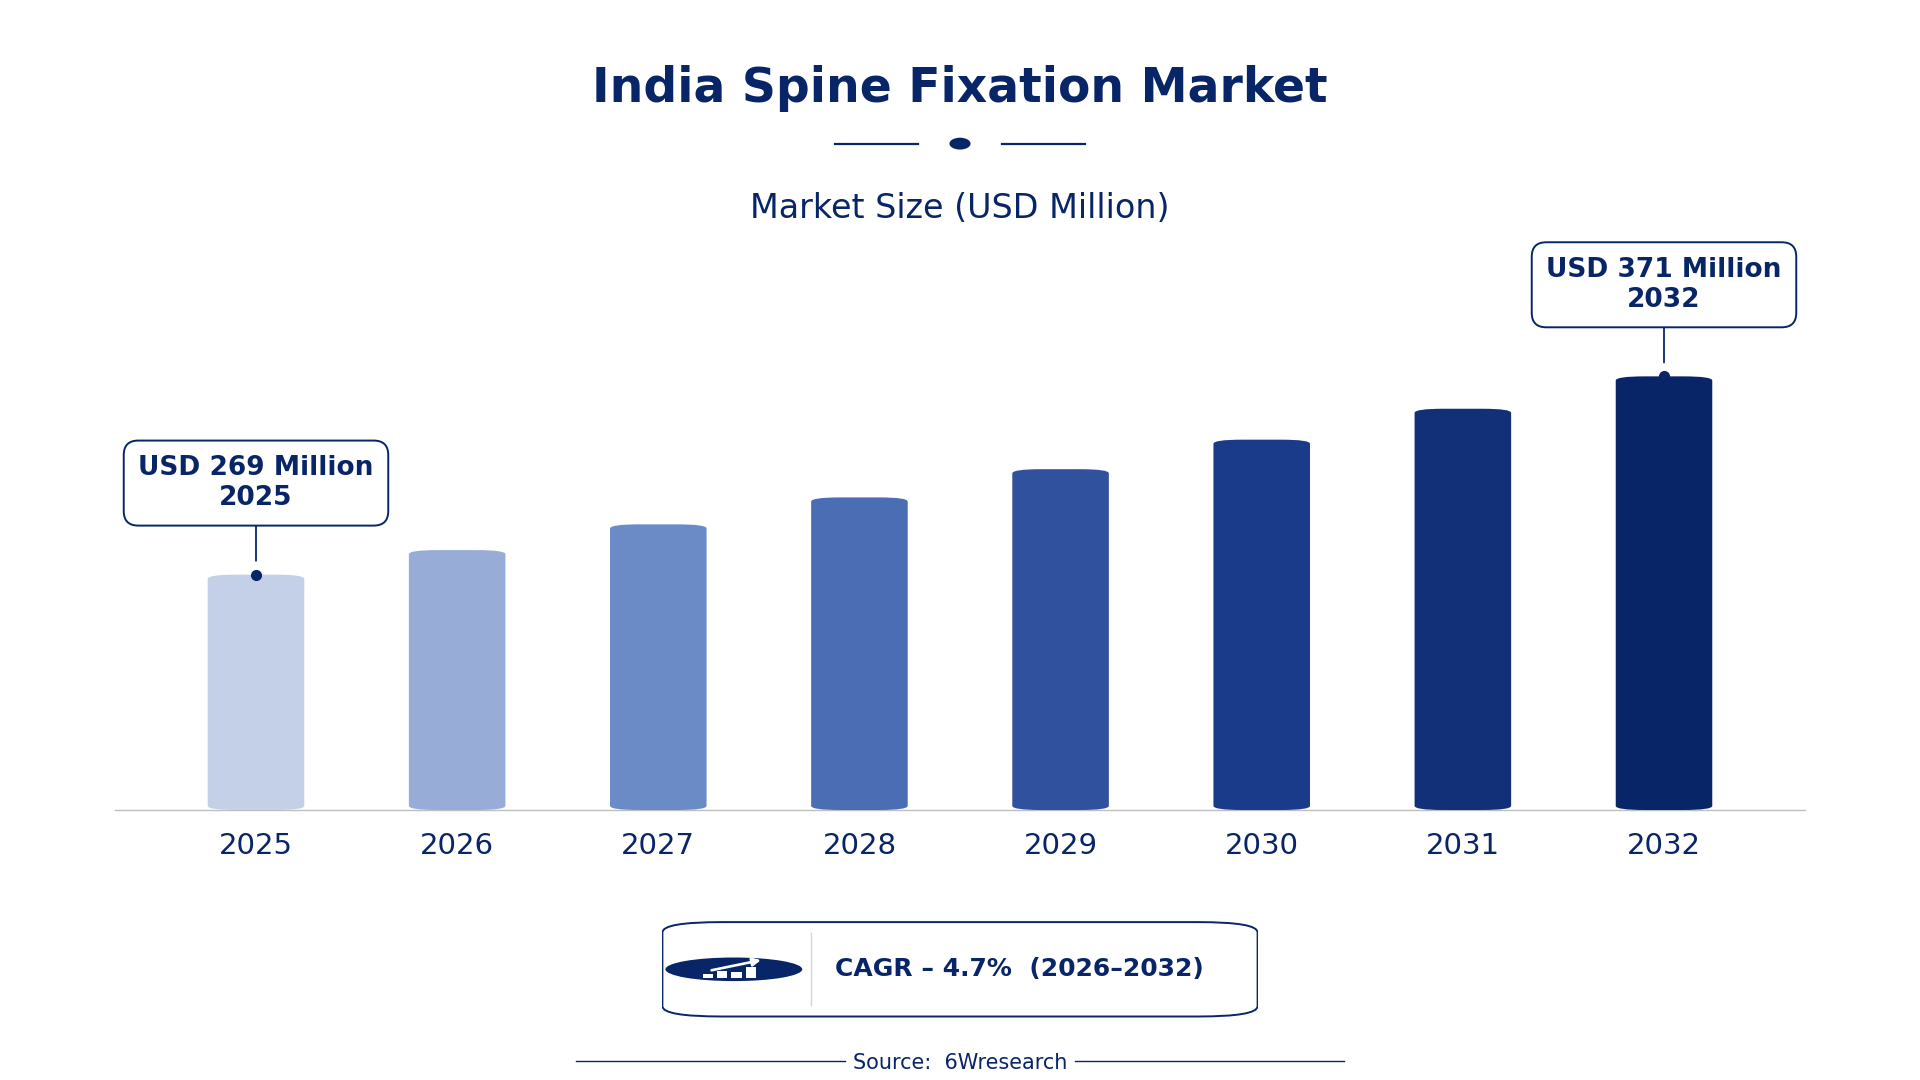
According to 6Wresearch internal database and industry insights, the India Spine Fixation Market was valued at USD 269.0 million in 2025 and is projected to reach USD 371 million by 2032, growing at a CAGR of approximately 4.7% during 2026–2032.
India Spine Fixation Market Highlights
| Report Metric | Details |
| Report Name | India Spine Fixation Market |
| Market Size 2025 | USD 269.0 million |
| Market Size 2032 | USD 371 million |
| Absolute Growth 2025–2032 | USD 102 million |
| CAGR 2026–2032 | 4.7% |
| Peak Annual Growth | 6.8% in 2030 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Fixation Type, 2025 | Pedicle Screw Systems (46% share) |
| Leading Material Used, 2025 | Titanium/SS (35% share) |
| Leading Implant Site, 2025 | Thoracic/Lumbar Spine (42% share) |
| Leading End User, 2025 | Orthopedic Hospitals (40% share) |
| Fastest-Growing Fixation Type | Minimally Invasive Fixation (6.7% CAGR) |
| Fastest-Growing Material Used | PEEK/Carbon Fiber (6.1% CAGR) |
| Fastest-Growing Implant Site | Interbody Support (6.8% CAGR) |
| Fastest-Growing End User | Surgical Centers (7.3% CAGR) |
| Growing Sector | Orthopedic Hospitals |
| Key End Users | Orthopedic Hospitals, Surgical Centers, Spine Surgeons, Specialty Clinics |
India Spine Fixation Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
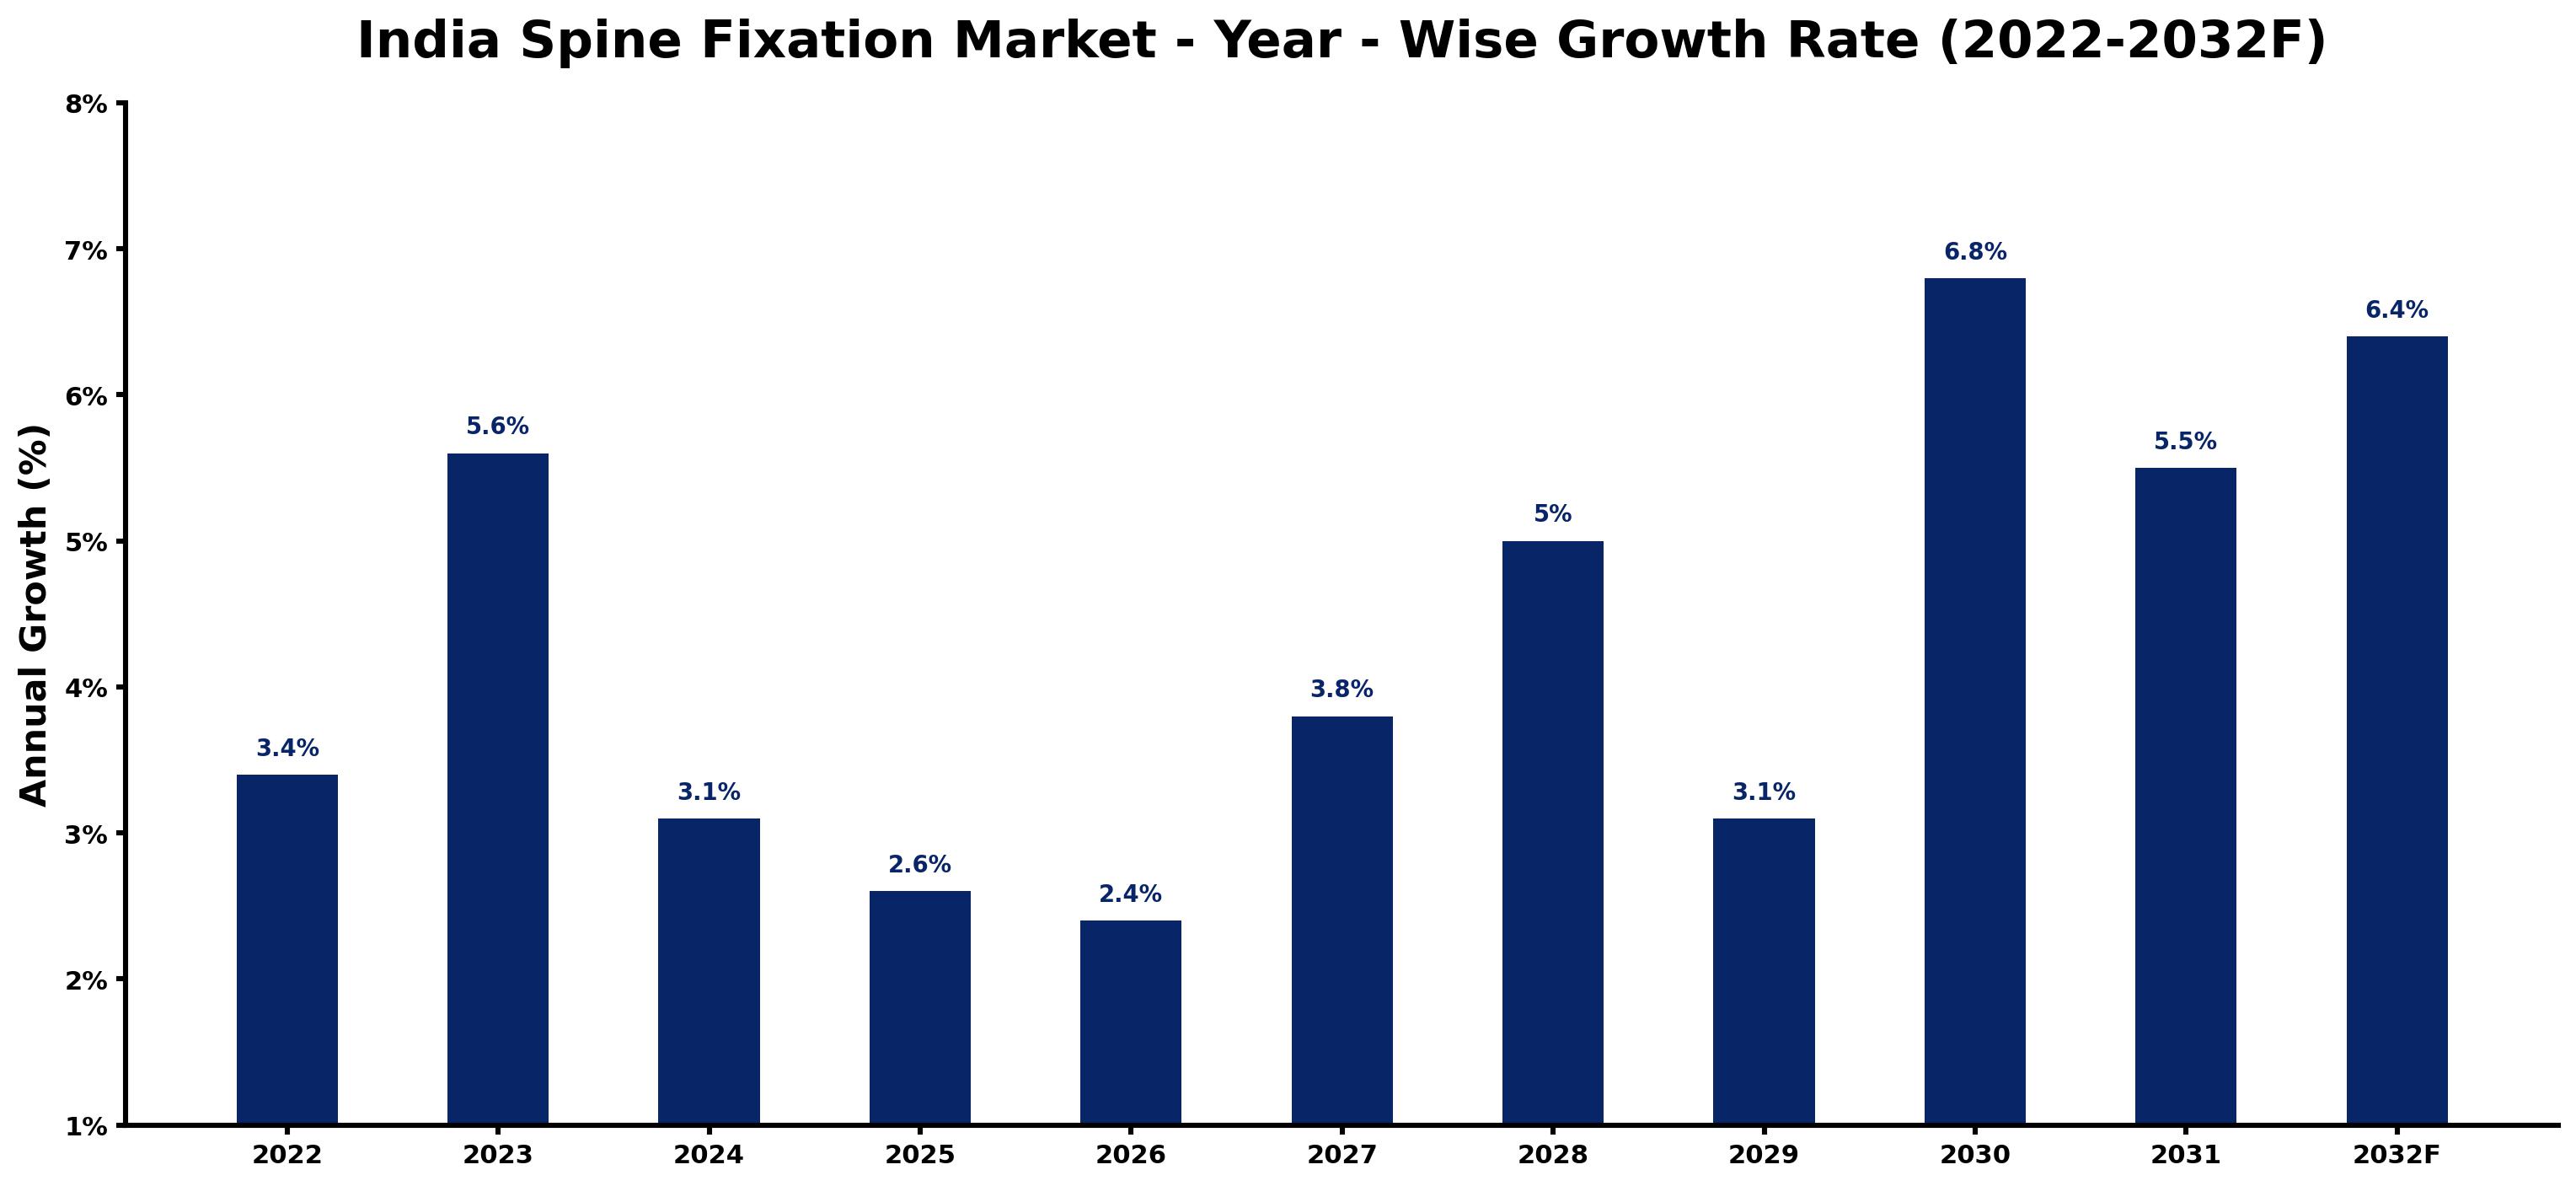
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.4 | The market showed steady growth due to ongoing surgical procedures across the country. |
| 2023 | 5.6 | Demand surged as over 200,000 spine surgeries were performed, reflecting increased healthcare access. |
| 2024 | 3.1 | Growth slowed as hospitals faced resource allocation challenges amid rising operational costs. |
| 2025 | 2.6 | Market growth decelerated further due to limited advancements in surgical techniques and materials. |
| 2026 | 2.4 | A continued slowdown is expected as hospitals adjust to new healthcare policies and standards. |
| 2027 | 3.8 | Demand is expected to rise as minimally invasive techniques gain traction in urban surgical centers. |
| 2028 | 5.0 | The aging population is projected to increase the number of patients requiring spine surgeries. |
| 2029 | 3.1 | Market growth is expected to slow as competition intensifies among suppliers of fixation devices. |
| 2030 | 6.8 | A peak in growth is projected, driven by a surge in advanced surgical procedures and training. |
| 2031 | 5.5 | Growth is expected to moderate as the market adjusts to the previous year's peak demand. |
| 2032 | 6.4 | Demand is projected to rise again with the introduction of new fixation technologies. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Spine Fixation Market Synopsis
The India Spine Fixation Market includes medical devices used to stabilise the spine during surgeries. These products, primarily made from titanium or stainless steel, are essential for treating spinal deformities and trauma. The market is growing due to increased surgical procedures, supported by initiatives like the Ayushman Bharat scheme. With over 1,000 orthopedic hospitals in India, the demand for spine fixation devices is driven by the aging population and advancements in surgical techniques. The increasing preference for minimally invasive procedures further boosts the market's expansion.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing number of orthopedic surgeries due to an aging population | Driver | High | Pedicle Screw Systems |
| Growing preference for minimally invasive techniques among surgeons | Driver | High | Minimally Invasive Fixation |
| Rising demand for titanium fixation systems among spine surgeons | Opportunity | High | Titanium/SS |
| Expansion of surgical centers offering spine procedures | Opportunity | Medium | Surgical Centers |
| High costs associated with advanced spine fixation devices | Restraint | High | Rod Systems |
| Limited availability of advanced materials for fixation devices | Restraint | Medium | Plates & Cages |
| Regulatory delays in the approval of new fixation technologies | Challenge | High | Minimally Invasive Fixation |
| Supply chain disruptions affecting the availability of materials | Challenge | Medium | Titanium/SS |
Evaluation of Drivers in India Spine Fixation Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased surgical procedures annually | Pedicle Screw Systems | Over 200,000 surgeries performed annually drive demand for stabilisation devices. |
| Surgeons' preference for titanium systems | Titanium/SS | 60% of spine surgeons prefer titanium due to its strength and biocompatibility. |
| Growth in urban surgical centers | Minimally Invasive Fixation | In 2023, 40% of surgeries in urban centers utilised minimally invasive techniques. |
| Government support for orthopedic advancements | Rod Systems | The National Health Mission promotes access to orthopedic surgeries, increasing demand. |
| Rising awareness of spine health | Plates & Cages | Educational initiatives by the Indian Orthopedic Association boost demand for fixation devices. |
Expansion of the Spine Fixation market in India is backed by rising investment in healthcare infrastructure, increasing end-use demand from orthopedic hospitals, and advancements in surgical techniques. The annual performance of over 200,000 surgeries creates a steady need for stabilisation devices. Approximately 60% of spine surgeons prefer titanium fixation systems, which drives further demand for these materials. The growing awareness of spine health among the population contributes to the rising need for effective fixation solutions. Additionally, the adoption of minimally invasive techniques is expected to enhance recovery times, prompting hospitals to invest in new technologies.
Evaluation of Restraints in India Spine Fixation Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs of advanced fixation devices | Rod Systems | The average price of titanium systems limits accessibility for some hospitals. |
| Limited advanced material availability | Plates & Cages | Supply chain issues hinder the procurement of new materials for fixation. |
| Regulatory delays in new technology approvals | Minimally Invasive Fixation | Long approval processes slow down the introduction of new fixation solutions. |
| Competition among suppliers driving prices down | Titanium/SS | Intense competition affects profit margins for manufacturers of fixation devices. |
| Inconsistent quality standards across suppliers | Pedicle Screw Systems | Variability in quality impacts buyer confidence and purchasing decisions. |
India Spine Fixation Market Challenges
The India Spine Fixation Market faces a notable skills shortage among spine surgeons, which affects the delivery of advanced surgical procedures. This challenge arises as training programs have not kept pace with the 200,000 annual surgeries, leading to delays for hospitals in finding qualified personnel. Technology adoption is slow, with many surgical centres still relying on traditional methods, resulting in prolonged recovery times for patients. Regulatory compliance with ISO 13485 extends the time and costs for producers to launch new products, limiting their ability to meet market demand. The high cost of titanium fixation systems, preferred by 60% of surgeons, restricts access for buyers, particularly in rural areas with limited budgets.
Trends in the India Spine Fixation Market
Four trends stand out in the India Spine Fixation Market.
- Surgeons Increasingly Favor Minimally Invasive Techniques: Orthopedic hospitals are adopting minimally invasive spine fixation methods, which improve patient recovery times. In 2022, 40% of surgeries in urban centres employed these techniques, indicating a shift in surgical practices.
- Surgeons Prefer Titanium Fixation Systems: Surgeons are increasingly choosing titanium fixation systems for their strength and compatibility. A recent survey revealed that 60% of spine surgeons prefer these systems, influencing purchasing decisions across hospitals.
- Rise in Surgical Centers Offering Spine Procedures: The number of surgical centres providing spine fixation procedures has risen significantly. In 2023, urban areas experienced a 25% increase in such centres, catering to the growing demand for outpatient surgeries.
- Growing Adoption of PEEK Implants: The use of PEEK implants is on the rise among spine surgeons due to their favourable properties for interbody fusion. In 2023, adoption rates increased by 15%, indicating a shift in material preference.
Investment Opportunities in the India Spine Fixation Market
Some of the investment opportunities in the India Spine Fixation Market are mentioned below.
- Orthopedic Hospitals Seeking Advanced Fixation Solutions: With over 1,000 orthopedic hospitals in India, there is a strong demand for advanced spine fixation devices. The market gap is clear as hospitals seek innovative materials, particularly titanium systems.
- Surgical Centers Expanding Offerings: Surgical centres are increasingly aiming to supply minimally invasive fixation products. The demand is supported by a 25% increase in such centres, presenting an opportunity for suppliers to enter this market.
- Investment in Titanium Fixation Systems: The growing preference for titanium fixation systems presents a promising opportunity. With 60% of surgeons favouring these materials, suppliers can target orthopedic hospitals and surgical centres.
- Emerging Demand for PEEK Implants: The rise in PEEK implant adoption indicates a growing market need. Suppliers can invest in this segment, especially as adoption rates increased by 15% in 2023.
Government Initiatives in the India Spine Fixation Market
The National Medical Devices Policy 2023 aims to strengthen local manufacturing of spine fixation devices, focusing on innovation and quality. This policy aligns with the 'Make in India' initiative, which promotes domestic production with a budget allocation of ₹1,000 crores for medical technology. These measures enhance the local supply chain and ensure better access to quality fixation systems for hospitals and surgical centres. Additionally, the Biomedical Device Standardization Program initiated by the Bureau of Indian Standards in 2022 includes spine fixation devices to ensure safety and efficacy in the market. This program mandates manufacturers to adhere to strict quality standards, boosting buyer confidence in product safety.
The Bureau of Indian Standards oversees the Biomedical Device Standardization Program initiated in 2022, which includes spine fixation devices. This program ensures safety and efficacy in the market, requiring manufacturers to comply with strict quality standards. The Ministry of Health and Family Welfare funds initiatives under the Ayushman Bharat scheme, improving access to orthopedic surgeries for millions of beneficiaries. This scheme targets 10 million beneficiaries, significantly enhancing healthcare access and supporting the demand for spine fixation products.
Future Insight of the India Spine Fixation Market
The India Spine Fixation Market is set for substantial changes by 2032, as advancements in surgical training programs and government initiatives like the National Health Mission improve capabilities. The shift towards minimally invasive techniques will accelerate, leading to quicker patient recovery and a broader market for spine stabilisation products. The increasing preference for PEEK implants, due to their advantageous properties, will influence product development. With a rise in surgical procedures projected, the demand for effective spine stabilisation solutions will grow, benefiting both suppliers and healthcare providers.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Fixation Type – Pedicle Screw Systems Dominated, Minimally Invasive Fixation Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, Pedicle Screw Systems took a 46% share of fixation type in 2025, more than any other category. Pedicle screw systems dominate the market share as they are essential for stabilising spinal segments during surgery. With over 200,000 surgical procedures performed annually in India, these systems are integral to the operations of numerous orthopedic hospitals. Over 2026–2032, Minimally Invasive Fixation is expected to post the fastest growth, at a CAGR of 6.7%. Minimally invasive fixation is rapidly gaining traction due to its effectiveness in reducing recovery time for patients. This approach is increasingly embraced in urban surgical centres, suggesting a shift towards more efficient surgical methodologies that will likely continue to expand. Suppliers should focus on increasing the availability of minimally invasive options to meet the rising demand from surgical centres.
By Material Used – Titanium/SS Dominated, PEEK/Carbon Fiber Expected to Grow Fastest
The largest material used category in 2025 was Titanium/SS, with a 35% share of total revenue. Titanium and stainless steel lead the market due to their exceptional strength and biocompatibility. Their extensive utilisation across more than 1,000 orthopedic hospitals in India ensures a consistent supply of these materials for spine fixation procedures. PEEK/Carbon Fiber is projected to grow fastest, at a CAGR of 6.1% during 2026–2032. PEEK and carbon fiber are witnessing growth as they cater to niche applications in interbody fusion, attracting surgeons interested in advanced materials. This increasing preference signals a trend towards innovation in spine fixation that could significantly alter market dynamics. Buyers should consider exploring advanced material options to enhance surgical outcomes and improve patient recovery.
By Implant Site – Thoracic/Lumbar Spine Dominated, Interbody Support Expected to Grow Fastest
Thoracic/Lumbar Spine accounted for a 42% market share by implant site in 2025. The thoracic and lumbar spine is the primary site for fixation procedures, reflecting the high volume of surgeries performed in these areas. This focus is supported by the aging demographic in India, which increases the demand for spinal interventions. The quickest growth will come from Interbody Support, forecast to expand at a CAGR of 6.8% between 2026 and 2032. Interbody support is critical for spinal fusion procedures, which are becoming more common as surgical techniques advance. The emphasis on this site indicates a growing recognition of its importance in achieving successful surgical outcomes. Suppliers should ensure adequate inventory of interbody support products to cater to the rising demand in surgical procedures.
By End User – Orthopedic Hospitals Dominated, Surgical Centers Expected to Grow Fastest
In 2025, Orthopedic Hospitals led the end user split with a 40% share. Orthopedic hospitals are the primary facilities performing spine surgeries, capturing a substantial share of the market. Their established infrastructure and expertise in spine procedures make them the main buyers of fixation products in India. Surgical Centers are set to record the highest CAGR in this split, 7.3% over 2026–2032. Surgical centres are becoming increasingly popular for outpatient spine procedures, reflecting a shift in patient preferences towards more accessible surgical options. This trend indicates a growing market segment that suppliers should not overlook. Suppliers should consider tailoring their offerings to meet the specific needs of surgical centres as they expand their services.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Spine Fixation Market Outlook
- Market Size of India Spine Fixation Market, 2025
- Forecast of India Spine Fixation Market, 2032
- Historical Data and Forecast of India Spine Fixation Revenues & Volume for the Period 2022 - 2032F
- India Spine Fixation Market Trend Evolution
- India Spine Fixation Market Drivers and Challenges
- India Spine Fixation Price Trends
- India Spine Fixation Porter's Five Forces
- India Spine Fixation Industry Life Cycle
- Historical Data and Forecast of India Spine Fixation Market Revenues & Volume By Fixation Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Spine Fixation Market Revenues & Volume By Pedicle Screw Systems for the Period 2022 - 2032F
- Historical Data and Forecast of India Spine Fixation Market Revenues & Volume By Rod Systems for the Period 2022 - 2032F
- Historical Data and Forecast of India Spine Fixation Market Revenues & Volume By Plates & Cages for the Period 2022 - 2032F
- Historical Data and Forecast of India Spine Fixation Market Revenues & Volume By Minimally Invasive Fixation for the Period 2022 - 2032F
- Historical Data and Forecast of India Spine Fixation Market Revenues & Volume By Material Used for the Period 2022 - 2032F
- Historical Data and Forecast of India Spine Fixation Market Revenues & Volume By Titanium/SS for the Period 2022 - 2032F
- Historical Data and Forecast of India Spine Fixation Market Revenues & Volume By Alloy/CoCr for the Period 2022 - 2032F
- Historical Data and Forecast of India Spine Fixation Market Revenues & Volume By PEEK/Carbon Fiber for the Period 2022 - 2032F
- Historical Data and Forecast of India Spine Fixation Market Revenues & Volume By Composite Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of India Spine Fixation Market Revenues & Volume By Implant Site for the Period 2022 - 2032F
- Historical Data and Forecast of India Spine Fixation Market Revenues & Volume By Thoracic/Lumbar Spine for the Period 2022 - 2032F
- Historical Data and Forecast of India Spine Fixation Market Revenues & Volume By Cervical/Thoracic for the Period 2022 - 2032F
- Historical Data and Forecast of India Spine Fixation Market Revenues & Volume By Interbody Support for the Period 2022 - 2032F
- Historical Data and Forecast of India Spine Fixation Market Revenues & Volume By Posterior Segment for the Period 2022 - 2032F
- Historical Data and Forecast of India Spine Fixation Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of India Spine Fixation Market Revenues & Volume By Orthopedic Hospitals for the Period 2022 - 2032F
- Historical Data and Forecast of India Spine Fixation Market Revenues & Volume By Surgical Centers for the Period 2022 - 2032F
- Historical Data and Forecast of India Spine Fixation Market Revenues & Volume By Spine Surgeons for the Period 2022 - 2032F
- Historical Data and Forecast of India Spine Fixation Market Revenues & Volume By Specialty Clinics for the Period 2022 - 2032F
- India Spine Fixation Import Export Trade Statistics
- Market Opportunity Assessment By Fixation Type
- Market Opportunity Assessment By Material Used
- Market Opportunity Assessment By Implant Site
- Market Opportunity Assessment By End User
- India Spine Fixation Top Companies Market Share
- India Spine Fixation Competitive Benchmarking By Technical and Operational Parameters
- India Spine Fixation Company Profiles
- India Spine Fixation Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Fixation Type
- Pedicle Screw Systems
- Rod Systems
- Plates & Cages
- Minimally Invasive Fixation
By Material Used
- Titanium/SS
- Alloy/CoCr
- PEEK/Carbon Fiber
- Composite Alloys
By Implant Site
- Thoracic/Lumbar Spine
- Cervical/Thoracic
- Interbody Support
- Posterior Segment
By End User
- Orthopedic Hospitals
- Surgical Centers
- Spine Surgeons
- Specialty Clinics































