China Structural Body Component Market Size & Growth Rate
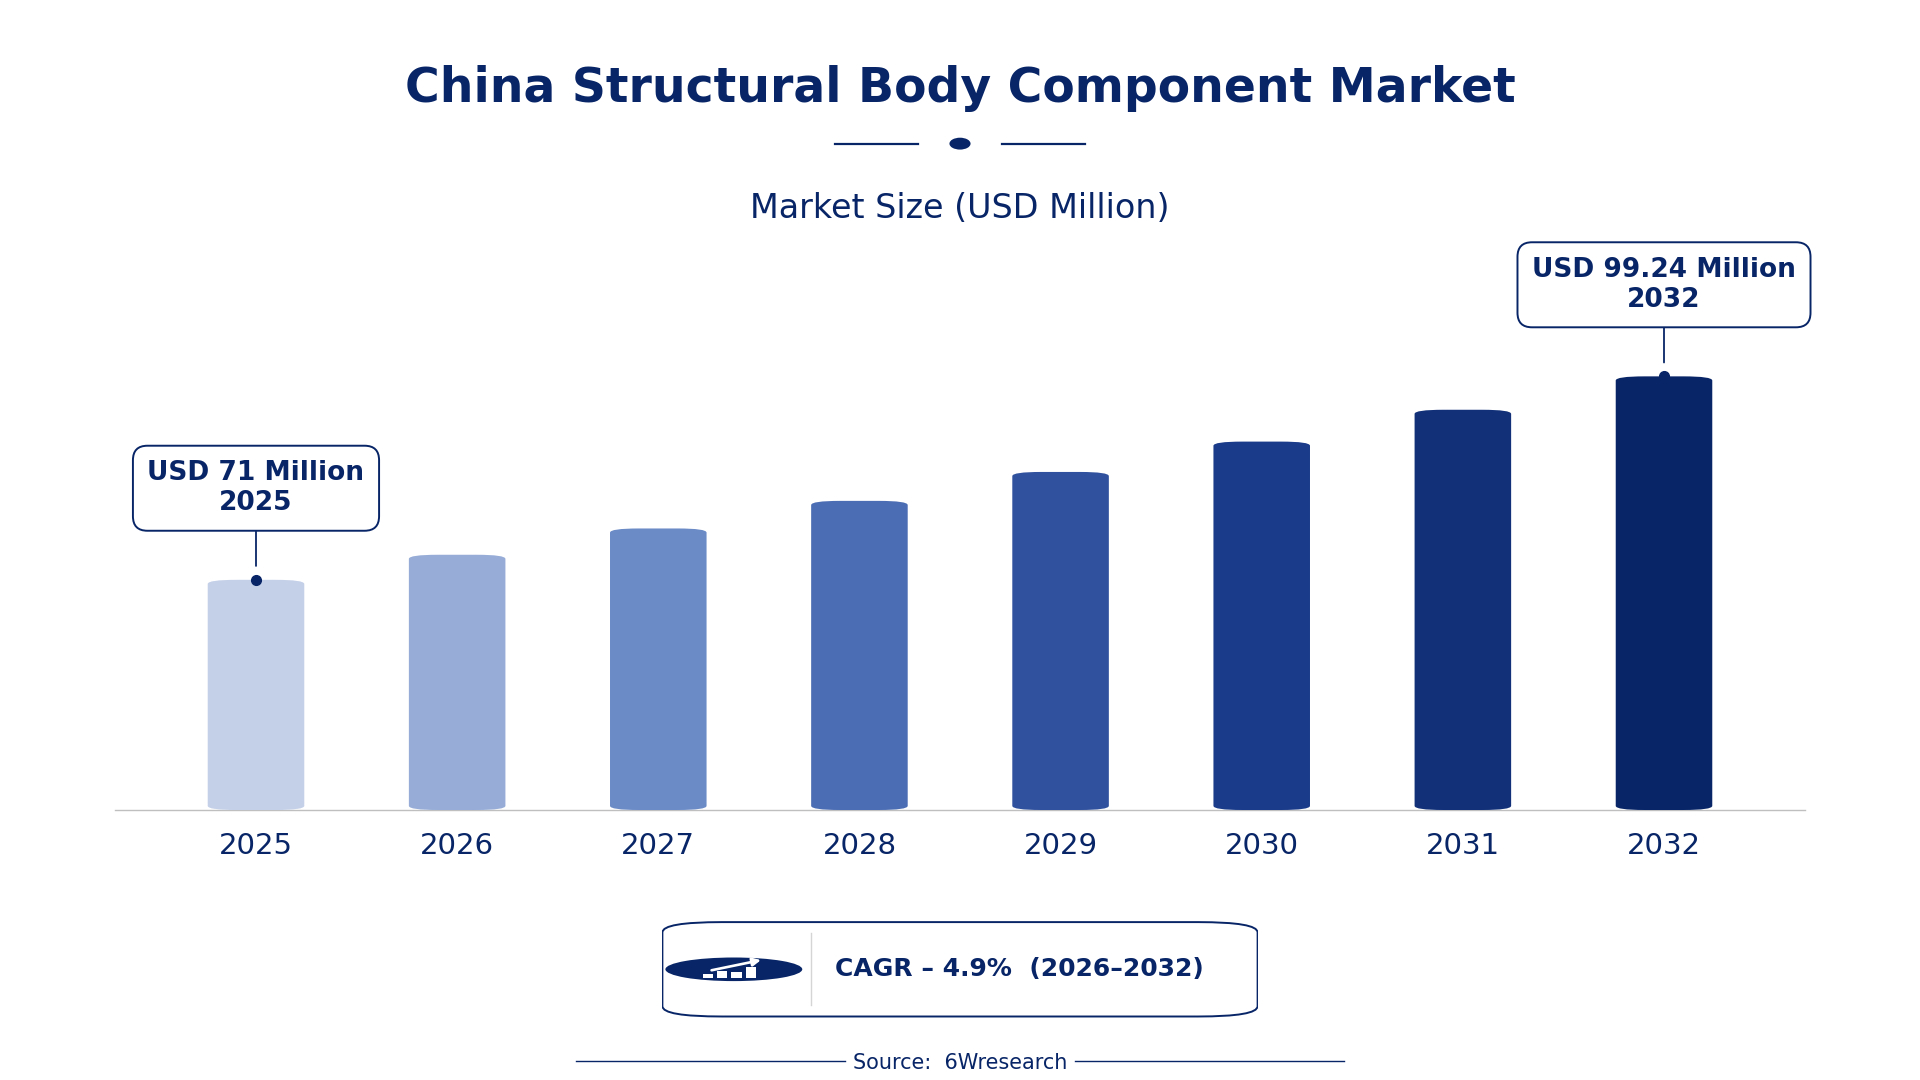
According to 6Wresearch internal database and industry insights, the China Structural Body Component Market was valued at USD 71.0 million in 2025 and is projected to reach USD 99.24 million by 2032, growing at a CAGR of approximately 4.9% during 2026–2032.
China Structural Body Component Market Highlights
| Report Metric | Details |
| Report Name | China Structural Body Component Market |
| Market Size 2025 | USD 71.0 million |
| Market Size 2032 | USD 99.24 million |
| Absolute Growth 2025–2032 | USD 28.24 million |
| CAGR 2026–2032 | 4.9% |
| Peak Annual Growth | 7.3% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Component Type, 2025 | Front End Structures (44% share) |
| Leading Position, 2025 | Front (45% share) |
| Leading Manufacturing Process, 2025 | Press Forming (34% share) |
| Leading End User, 2025 | Passenger Car Manufacturers (38% share) |
| Fastest-Growing Component Type | Roof Rails (6.4% CAGR) |
| Fastest-Growing Position | Top (7.4% CAGR) |
| Fastest-Growing Manufacturing Process | Hot Stamping (6.8% CAGR) |
| Fastest-Growing End User | Electric Vehicle Makers (6.0% CAGR) |
| Growing Sector | Electric Vehicles |
| Key End Users | Passenger Car Manufacturers, Electric Vehicle Makers, Automotive OEMs, Safety System Providers |
China Structural Body Component Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
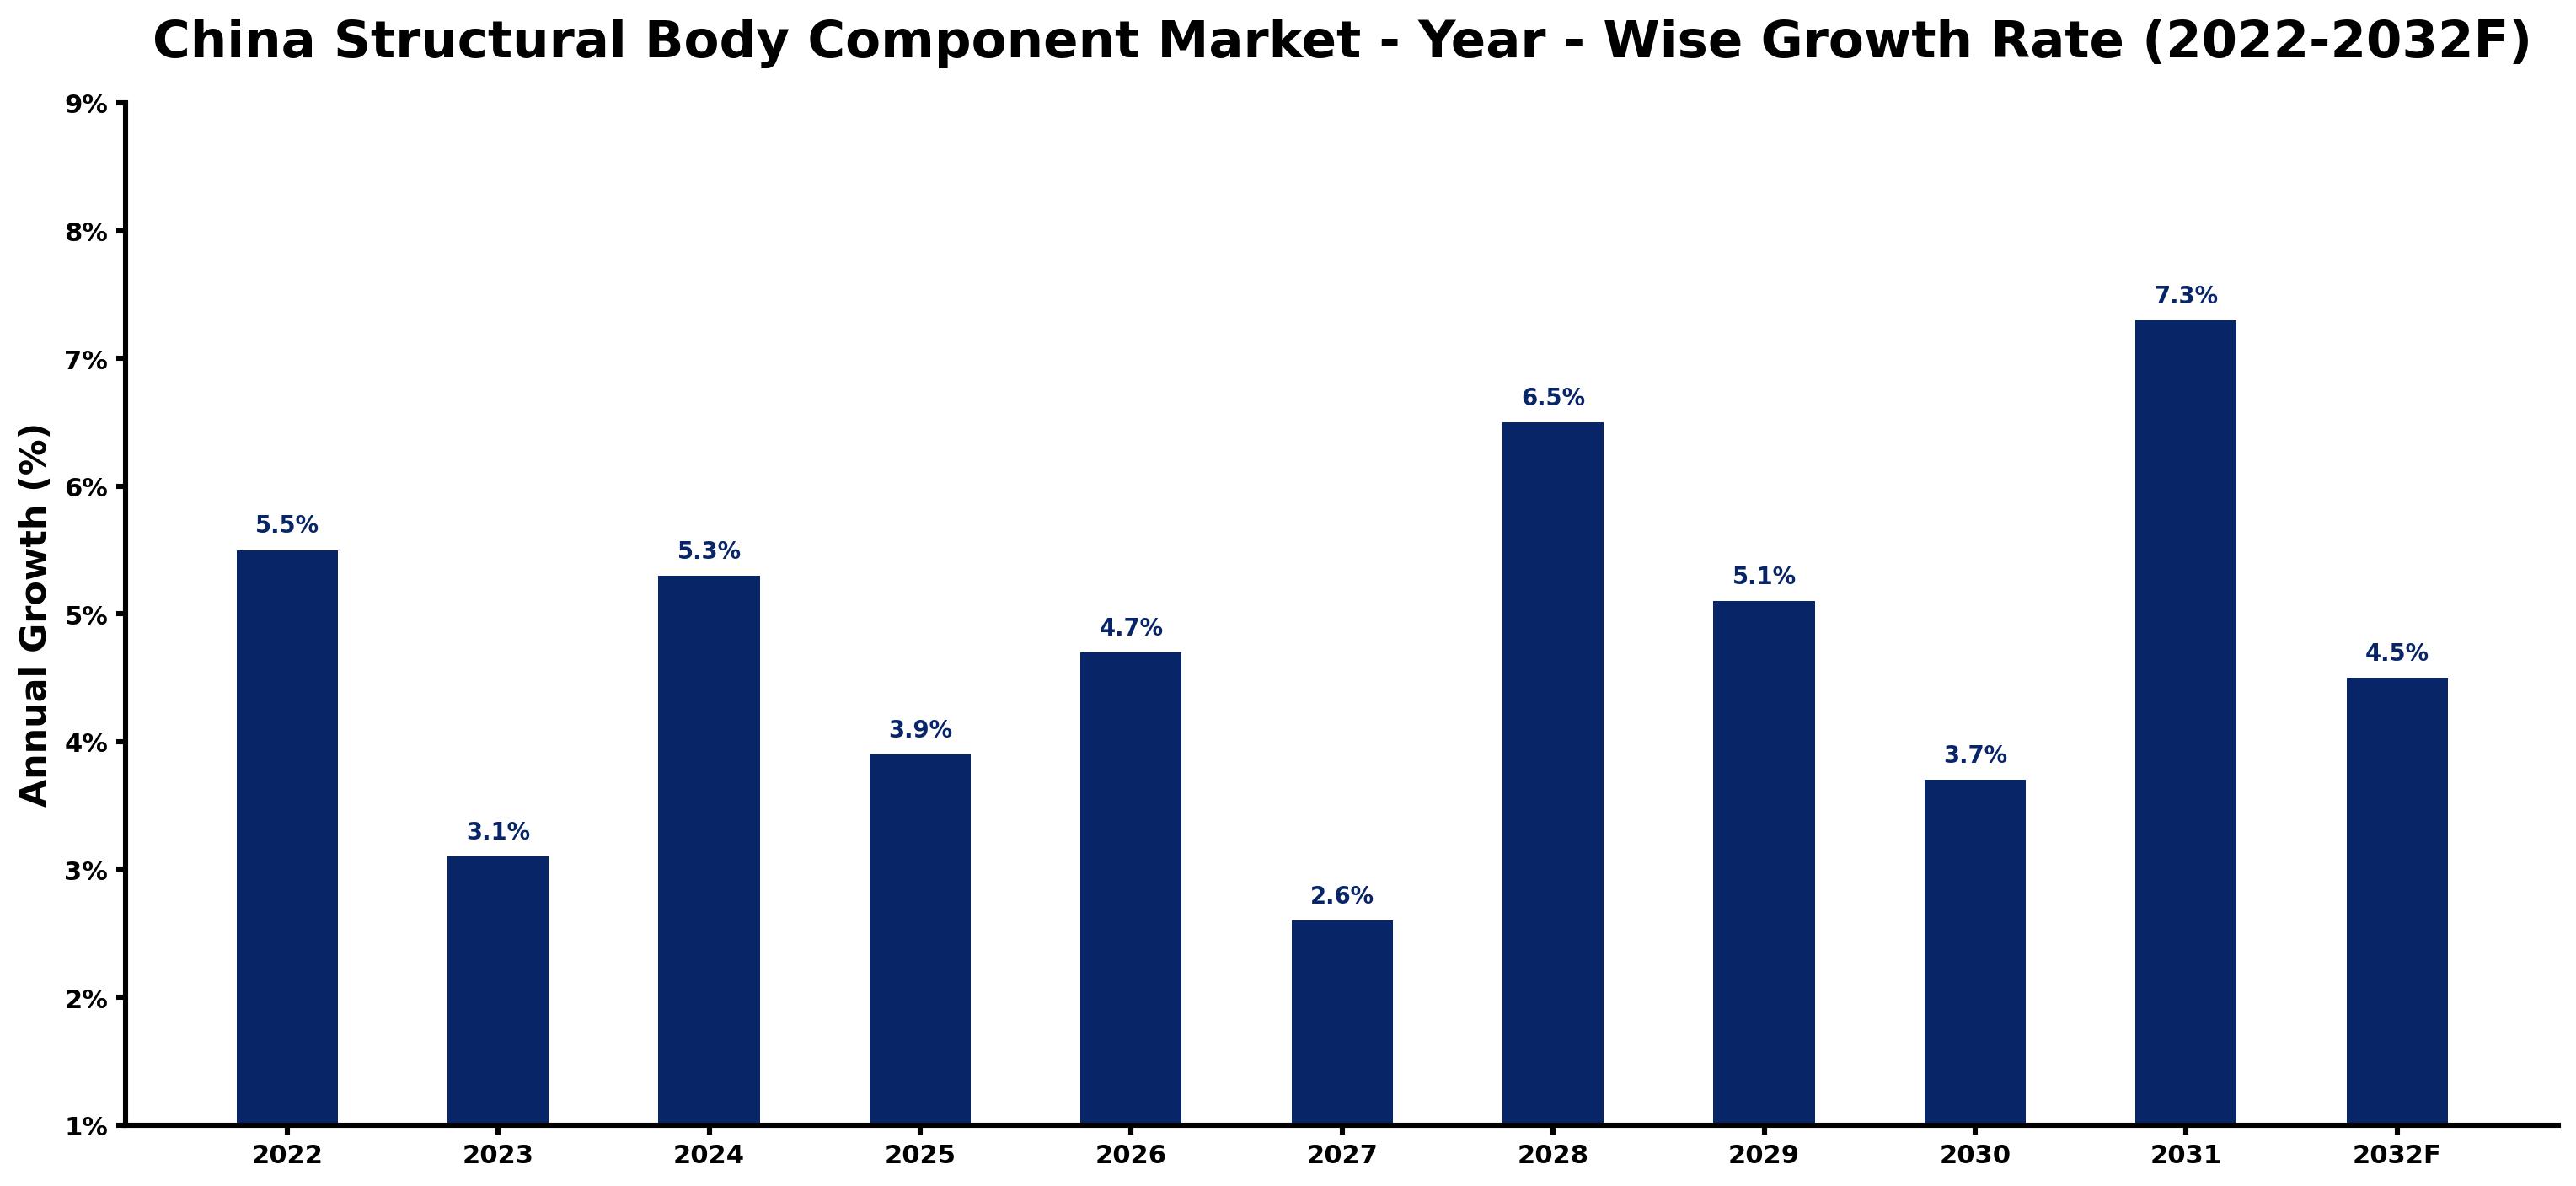
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.5 | The market experienced strong demand due to high production rates in the automotive sector. |
| 2023 | 3.1 | Growth slowed as manufacturers adjusted to supply chain disruptions affecting production schedules. |
| 2024 | 5.3 | Demand increased as passenger car manufacturers ramped up production to meet consumer needs. |
| 2025 | 3.9 | A slowdown in growth occurred as the 'New Energy Vehicle Industry Development Plan' began to take effect. |
| 2026 | 4.7 | Investment in electric vehicle production is expected to spur demand for advanced structural components. |
| 2027 | 2.6 | Growth is projected to slow as manufacturers face challenges in sourcing lightweight materials. |
| 2028 | 6.5 | A surge in demand for electric vehicles is anticipated to boost the need for lightweight structural components. |
| 2029 | 5.1 | Growth is expected to slow as the market adjusts to the rapid increase in production capacity. |
| 2030 | 3.7 | Demand is projected to stabilise as manufacturers focus on meeting enhanced vehicle safety standards. |
| 2031 | 7.3 | The market is expected to peak as manufacturers invest heavily in innovative structural solutions. |
| 2032 | 4.5 | Growth is anticipated to slow as the market normalises after reaching peak production levels. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Structural Body Component Market Synopsis
The China Structural Body Component Market encompasses essential vehicle parts made from metals and composites, vital for vehicle safety and structural integrity. These components are primarily used in passenger cars and safety systems, with a growing emphasis on lightweight materials for improved fuel efficiency. The market is expanding due to the robust automotive industry, which produced over 25 million passenger vehicles in 2022. Increasing demand from electric vehicle manufacturers and ongoing investments in advanced manufacturing techniques are driving growth. The focus on energy efficiency and safety standards further fuels market expansion.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased investments in electric vehicle production drive demand for lightweight components. | Driver | High | Roof Rails |
| Growing consumer preference for enhanced vehicle safety standards boosts demand for structural components. | Driver | High | Side Impact Beams |
| The transition to electric vehicles presents opportunities for suppliers of lightweight materials. | Opportunity | High | Roof Rails |
| The demand for advanced manufacturing processes is growing, creating openings for new technologies. | Opportunity | High | Press Forming |
| Supply chain disruptions are causing delays in the availability of raw materials. | Restraint | High | Rear Cross Members |
| The high cost of advanced manufacturing technologies can limit investment in new facilities. | Restraint | Medium | Hot Stamping |
| The Structural Body Component Market in China faces challenges from fluctuating raw material prices. | Challenge | High | Die Casting |
| Intensifying competition from international manufacturers is affecting local producers' market share. | Challenge | Medium | Passenger Car Manufacturers |
Evaluation of Drivers in China Structural Body Component Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased investments in electric vehicle production drive demand for lightweight components. | Roof Rails | The average annual growth rate of electric vehicles is expected to be 30% until 2030, prompting manufacturers to seek lighter materials. |
| Growing consumer preference for improved vehicle safety standards boosts demand for structural components. | Side Impact Beams | The National Standard GB/T 18352.5-2019 regulates vehicle safety, prompting manufacturers to invest in better components. |
| The automotive industry's expansion in Guangdong province is driving demand for structural body components. | Front End Structures | Guangdong produced a significant share of China's 25 million passenger vehicles in 2022, increasing component needs. |
| The shift towards energy-efficient vehicles fosters demand for advanced structural solutions. | Rear Cross Members | The government aims for 50% of new vehicles to be electric by 2035, necessitating new components. |
| The automotive manufacturing investment in China exceeded $100 billion in 2022, boosting production capabilities. | Hot Stamping | This investment supports the development of advanced manufacturing processes for structural components. |
Market growth in China for Structural Body Component rests on increased investments in electric vehicle production, which is driving demand for lightweight components. The automotive industry produced over 25 million passenger vehicles in 2022, creating a strong need for structural integrity. The automotive sector in Jiangsu province is a major production hub, increasing the need for structural body components.
Evaluation of Restraints in China Structural Body Component Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions are causing delays in the availability of raw materials, impacting production schedules. | Rear Cross Members | The total vehicle population in China reached 300 million in 2023, increasing competition for materials. |
| The high cost of advanced manufacturing technologies can limit investment in new facilities, affecting capacity. | Hot Stamping | The automotive manufacturing investment in China was over $100 billion in 2022, but costs remain a concern. |
| Fluctuating raw material prices can create uncertainty for manufacturers, affecting their operational budgets. | Die Casting | The automotive industry contributes approximately 10% to China's GDP, making it sensitive to price changes. |
| Regulatory compliance costs can burden manufacturers, impacting their profitability. | Press Forming | The Ministry of Industry and Information Technology oversees automotive standards, requiring significant investments. |
| Intensifying competition from international manufacturers is affecting local producers' market share. | Passenger Car Manufacturers | China's automotive exports reached $30 billion in 2022, increasing competitive pressure. |
China Structural Body Component Market Challenges
The China Structural Body Component Market faces rising material costs, which compel buyers to reassess their procurement strategies. With automotive manufacturing investment exceeding $100 billion in 2022, suppliers encounter challenges in maintaining quality while managing expenses, leading to potential production delays. Intense competition among local manufacturers drives aggressive pricing strategies, forcing buyers to choose between quality compromises or seeking alternative suppliers, which can disrupt their supply chains. Adhering to regulations like ISO 26262 requires significant investments in safety measures, increasing operational costs for suppliers and squeezing profit margins for buyers.
Trends in the China Structural Body Component Market
Several trends are reshaping the China Structural Body Component Market; the most important are set out below.
- Shift Towards Lightweight Materials: The automotive market increasingly prioritises lightweight materials to improve fuel efficiency. The government's aim for 50% of new vehicles to be electric by 2035 aligns with this trend. This shift is expected to drive demand for advanced structural components.
- Increased Focus on Safety Standards: The National Standard for Automotive Safety was revised in 2022, enhancing regulations for structural components. This change is prompting manufacturers to invest in safer designs, resulting in a rise in demand for compliant components.
- Rise of Electric Vehicle Manufacturing: The average annual growth rate of electric vehicles is projected at 30% until 2030. This surge in production is driving demand for structural components tailored for electric vehicles, creating new market opportunities.
- Expansion of Automotive Supply Chains: The automotive supply chain in Jiangsu province is rapidly expanding, supporting local manufacturers. This growth is anticipated to improve the availability of structural components, facilitating increased production capacity.
Investment Opportunities in the China Structural Body Component Market
The following opportunities in the China Structural Body Component Market pair current demand with a clear way in.
- Surge in Electric Vehicle Production: With the average annual growth rate of electric vehicles expected to be 30% until 2030, there is an opportunity for suppliers of lightweight structural components. Electric vehicle makers are actively seeking materials to improve efficiency.
- Investment in Advanced Manufacturing Processes: The push for advanced manufacturing techniques presents opportunities for suppliers of new technologies. The 'Made in China 2025' initiative emphasises advanced manufacturing in the automotive sector, encouraging partnerships with local firms.
- Support for Green Vehicle Initiatives: The National Development and Reform Commission backs green vehicle initiatives, creating openings for manufacturers of sustainable components. This aligns with the government’s goal of promoting energy-efficient vehicles, enhancing market potential.
- Expansion in Automotive Hubs: The automotive supply chain in Guangdong province is rapidly expanding, providing opportunities for suppliers of structural components. Local partnerships can facilitate market entry and enhance competitiveness.
Government Initiatives in the China Structural Body Component Market
The 'Automotive Industry Development Policy' was updated in 2021 by the National Development and Reform Commission to promote the use of lightweight materials in vehicle manufacturing, encouraging manufacturers to invest in advanced structural components. This measure aligns with the goal of increasing the production of electric vehicles to 20 million units by 2025. The updated policy aims to improve energy efficiency and support the automotive sector's growth, which contributes approximately 10% to China's GDP. Additionally, the 'National Standard for Automotive Safety' was revised in 2022 by the Ministry of Ecology and Environment to enhance safety regulations for structural components in vehicles, ensuring compliance with international standards.
The Ministry of Industry and Information Technology oversees the implementation of the 'New Energy Vehicle Industry Development Plan', which includes a subsidy program for electric vehicle manufacturers focusing on advanced structural components, with a budget of $5 billion in 2023. This funding supports the development of innovative technologies and encourages manufacturers to improve their production capabilities. The National Development and Reform Commission also funds initiatives aimed at enhancing the competitiveness of domestic manufacturers in the global market, facilitating better access to resources and technology for producers.
Future Insight of the China Structural Body Component Market
The China Structural Body Component Market will undergo substantial changes by 2032, driven by the shift towards lightweight materials that improve fuel efficiency. The automotive sector in Guangdong province will lead this transition, with suppliers adopting advanced production methods. The government's 'New Energy Vehicle Industry Development Plan' will boost demand for components in electric vehicles, prompting buyers to incorporate state-of-the-art safety technologies. By 2030, the vehicle population will likely reach 300 million, presenting substantial opportunities for both buyers and suppliers in this dynamic market.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Component Type – Front End Structures Dominated, Roof Rails Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, Front End Structures held a 44% share of the China Structural Body Component Market by component type in 2025. Front End Structures hold the largest market share due to their critical role in ensuring vehicle safety and aesthetics, particularly for passenger vehicles. The production of over 25 million passenger vehicles in 2022 in China underscores the strong demand for these essential components. Roof Rails are projected to grow fastest, at a CAGR of 6.4% during 2026–2032. Roof Rails are experiencing the fastest growth as they are vital for supporting structural integrity and managing cargo, especially with the increasing focus on electric vehicles. The automotive sector's shift towards lightweight materials is expected to significantly accelerate the growth of this segment. Suppliers should enhance their Roof Rails offerings to capitalise on the rising demand for lightweight solutions in the automotive sector.
By Position – Front Dominated, Top Expected to Grow Fastest
With a 45% revenue share in 2025, Front was the largest position category. The Front position commands the largest market share as it is the primary area for structural components, crucial for vehicle stability and safety. With 300 million vehicles on the road in China, the need for robust front-end designs remains paramount. Top is set to record the highest CAGR in this split, 7.4% over 2026–2032. The Top position is the fastest-growing segment, as it directly supports roof structure and safety features, which are increasingly important in vehicle safety standards. The anticipated shift towards lightweight materials by 2025 will further stimulate growth in this area. Buyers should prioritise sourcing from suppliers with expertise in Top-position components to ensure compliance with evolving safety regulations.
By Manufacturing Process – Press Forming Dominated, Hot Stamping Expected to Grow Fastest
In 2025, Press Forming led the manufacturing process split with a 34% share. Press Forming leads the market share due to its extensive application in shaping metal components, making it a preferred method among automotive manufacturers. This process is crucial for producing various structural body components, ensuring both efficiency and quality in manufacturing. The quickest growth will come from Hot Stamping, forecast to expand at a CAGR of 6.8% between 2026 and 2032. Hot Stamping is the fastest-growing manufacturing process as it significantly enhances the strength of components through heat treatment, which is increasingly necessary for modern vehicle designs. The rising demand for stronger and lighter materials in vehicles is driving the adoption of this method. Suppliers should invest in Hot Stamping technologies to meet the increasing demand for high-strength components in the automotive industry.
By End User – Passenger Car Manufacturers Dominated, Electric Vehicle Makers Expected to Grow Fastest
Passenger Car Manufacturers accounted for a 38% market share by end user in 2025. Passenger Car Manufacturers dominate the market share as they are the primary consumers of structural components, driven by high production rates in China. The automotive industry's contribution of approximately 10% to China's GDP highlights the importance of these manufacturers in the market. Over 2026–2032, Electric Vehicle Makers are expected to post the fastest growth, at a CAGR of 6.0%. Electric Vehicle Makers represent the fastest-growing end user segment, focusing on lightweight components to enhance efficiency and performance. The government's goal for 50% of new vehicles to be electric by 2035 is expected to significantly boost this market. Suppliers should align their strategies to cater to the specific needs of Electric Vehicle Makers to capture growth opportunities.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Structural Body Component Market Outlook
- Market Size of China Structural Body Component Market, 2025
- Forecast of China Structural Body Component Market, 2032
- Historical Data and Forecast of China Structural Body Component Revenues & Volume for the Period 2022 - 2032F
- China Structural Body Component Market Trend Evolution
- China Structural Body Component Market Drivers and Challenges
- China Structural Body Component Price Trends
- China Structural Body Component Porter's Five Forces
- China Structural Body Component Industry Life Cycle
- Historical Data and Forecast of China Structural Body Component Market Revenues & Volume By Component Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Body Component Market Revenues & Volume By Front End Structures for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Body Component Market Revenues & Volume By Side Impact Beams for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Body Component Market Revenues & Volume By Roof Rails for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Body Component Market Revenues & Volume By Rear Cross Members for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Body Component Market Revenues & Volume By Position for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Body Component Market Revenues & Volume By Front for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Body Component Market Revenues & Volume By Side for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Body Component Market Revenues & Volume By Top for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Body Component Market Revenues & Volume By Rear for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Body Component Market Revenues & Volume By Manufacturing Process for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Body Component Market Revenues & Volume By Press Forming for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Body Component Market Revenues & Volume By Laser Welding for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Body Component Market Revenues & Volume By Hot Stamping for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Body Component Market Revenues & Volume By Die Casting for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Body Component Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Body Component Market Revenues & Volume By Passenger Car Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Body Component Market Revenues & Volume By Safety System Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Body Component Market Revenues & Volume By Automotive OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Body Component Market Revenues & Volume By Electric Vehicle Makers for the Period 2022 - 2032F
- China Structural Body Component Import Export Trade Statistics
- Market Opportunity Assessment By Component Type
- Market Opportunity Assessment By Position
- Market Opportunity Assessment By Manufacturing Process
- Market Opportunity Assessment By End User
- China Structural Body Component Top Companies Market Share
- China Structural Body Component Competitive Benchmarking By Technical and Operational Parameters
- China Structural Body Component Company Profiles
- China Structural Body Component Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Component Type
- Front End Structures
- Side Impact Beams
- Roof Rails
- Rear Cross Members
By Position
- Front
- Side
- Top
- Rear
By Manufacturing Process
- Press Forming
- Laser Welding
- Hot Stamping
- Die Casting
By End User
- Passenger Car Manufacturers
- Safety System Providers
- Automotive OEMs
- Electric Vehicle Makers































