China Structural Composites Market Size & Growth Rate
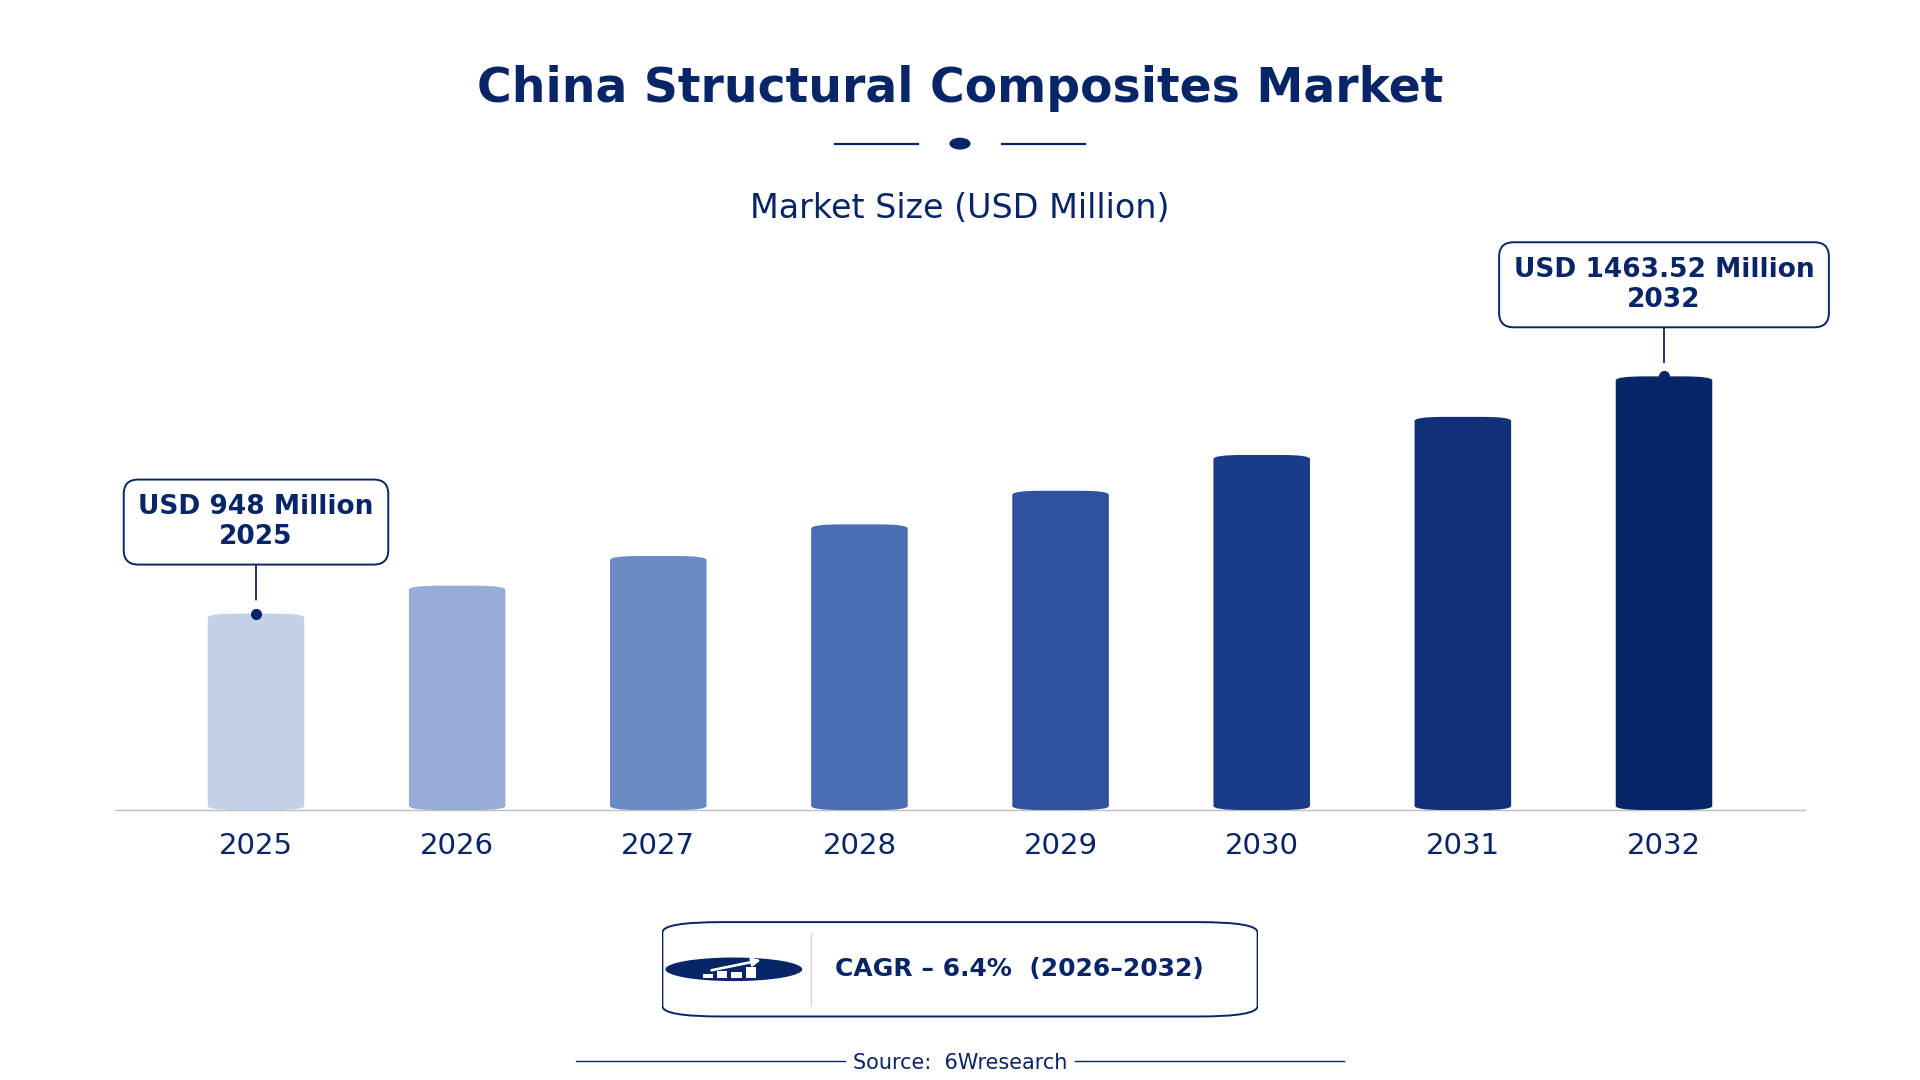
According to 6Wresearch internal database and industry insights, the China Structural Composites Market was valued at USD 948.0 million in 2025 and is projected to reach USD 1,463.52 million by 2032, growing at a CAGR of approximately 6.4% during 2026–2032.
China Structural Composites Market Highlights
| Report Metric | Details |
| Report Name | China Structural Composites Market |
| Market Size 2025 | USD 948.0 million |
| Market Size 2032 | USD 1,463.52 million |
| Absolute Growth 2025–2032 | USD 515.52 million |
| CAGR 2026–2032 | 6.4% |
| Peak Annual Growth | 8.6% in 2027 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Composite Type, 2025 | Carbon Fiber Composites (37% share) |
| Leading Fiber Type, 2025 | Carbon (45% share) |
| Leading Matrix Material, 2025 | Epoxy Resin (45% share) |
| Leading End User, 2025 | Aerospace Industry (51% share) |
| Fastest-Growing Composite Type | Glass Fiber Composites (8.5% CAGR) |
| Fastest-Growing Fiber Type | E-Glass (8.7% CAGR) |
| Fastest-Growing Matrix Material | Polyester (8.7% CAGR) |
| Fastest-Growing End User | Automotive Suppliers (7.5% CAGR) |
| Growing Sector | Aerospace Industry |
| Key End Users | Aerospace Industry, Automotive Suppliers, Ballistic Protection Firms |
China Structural Composites Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
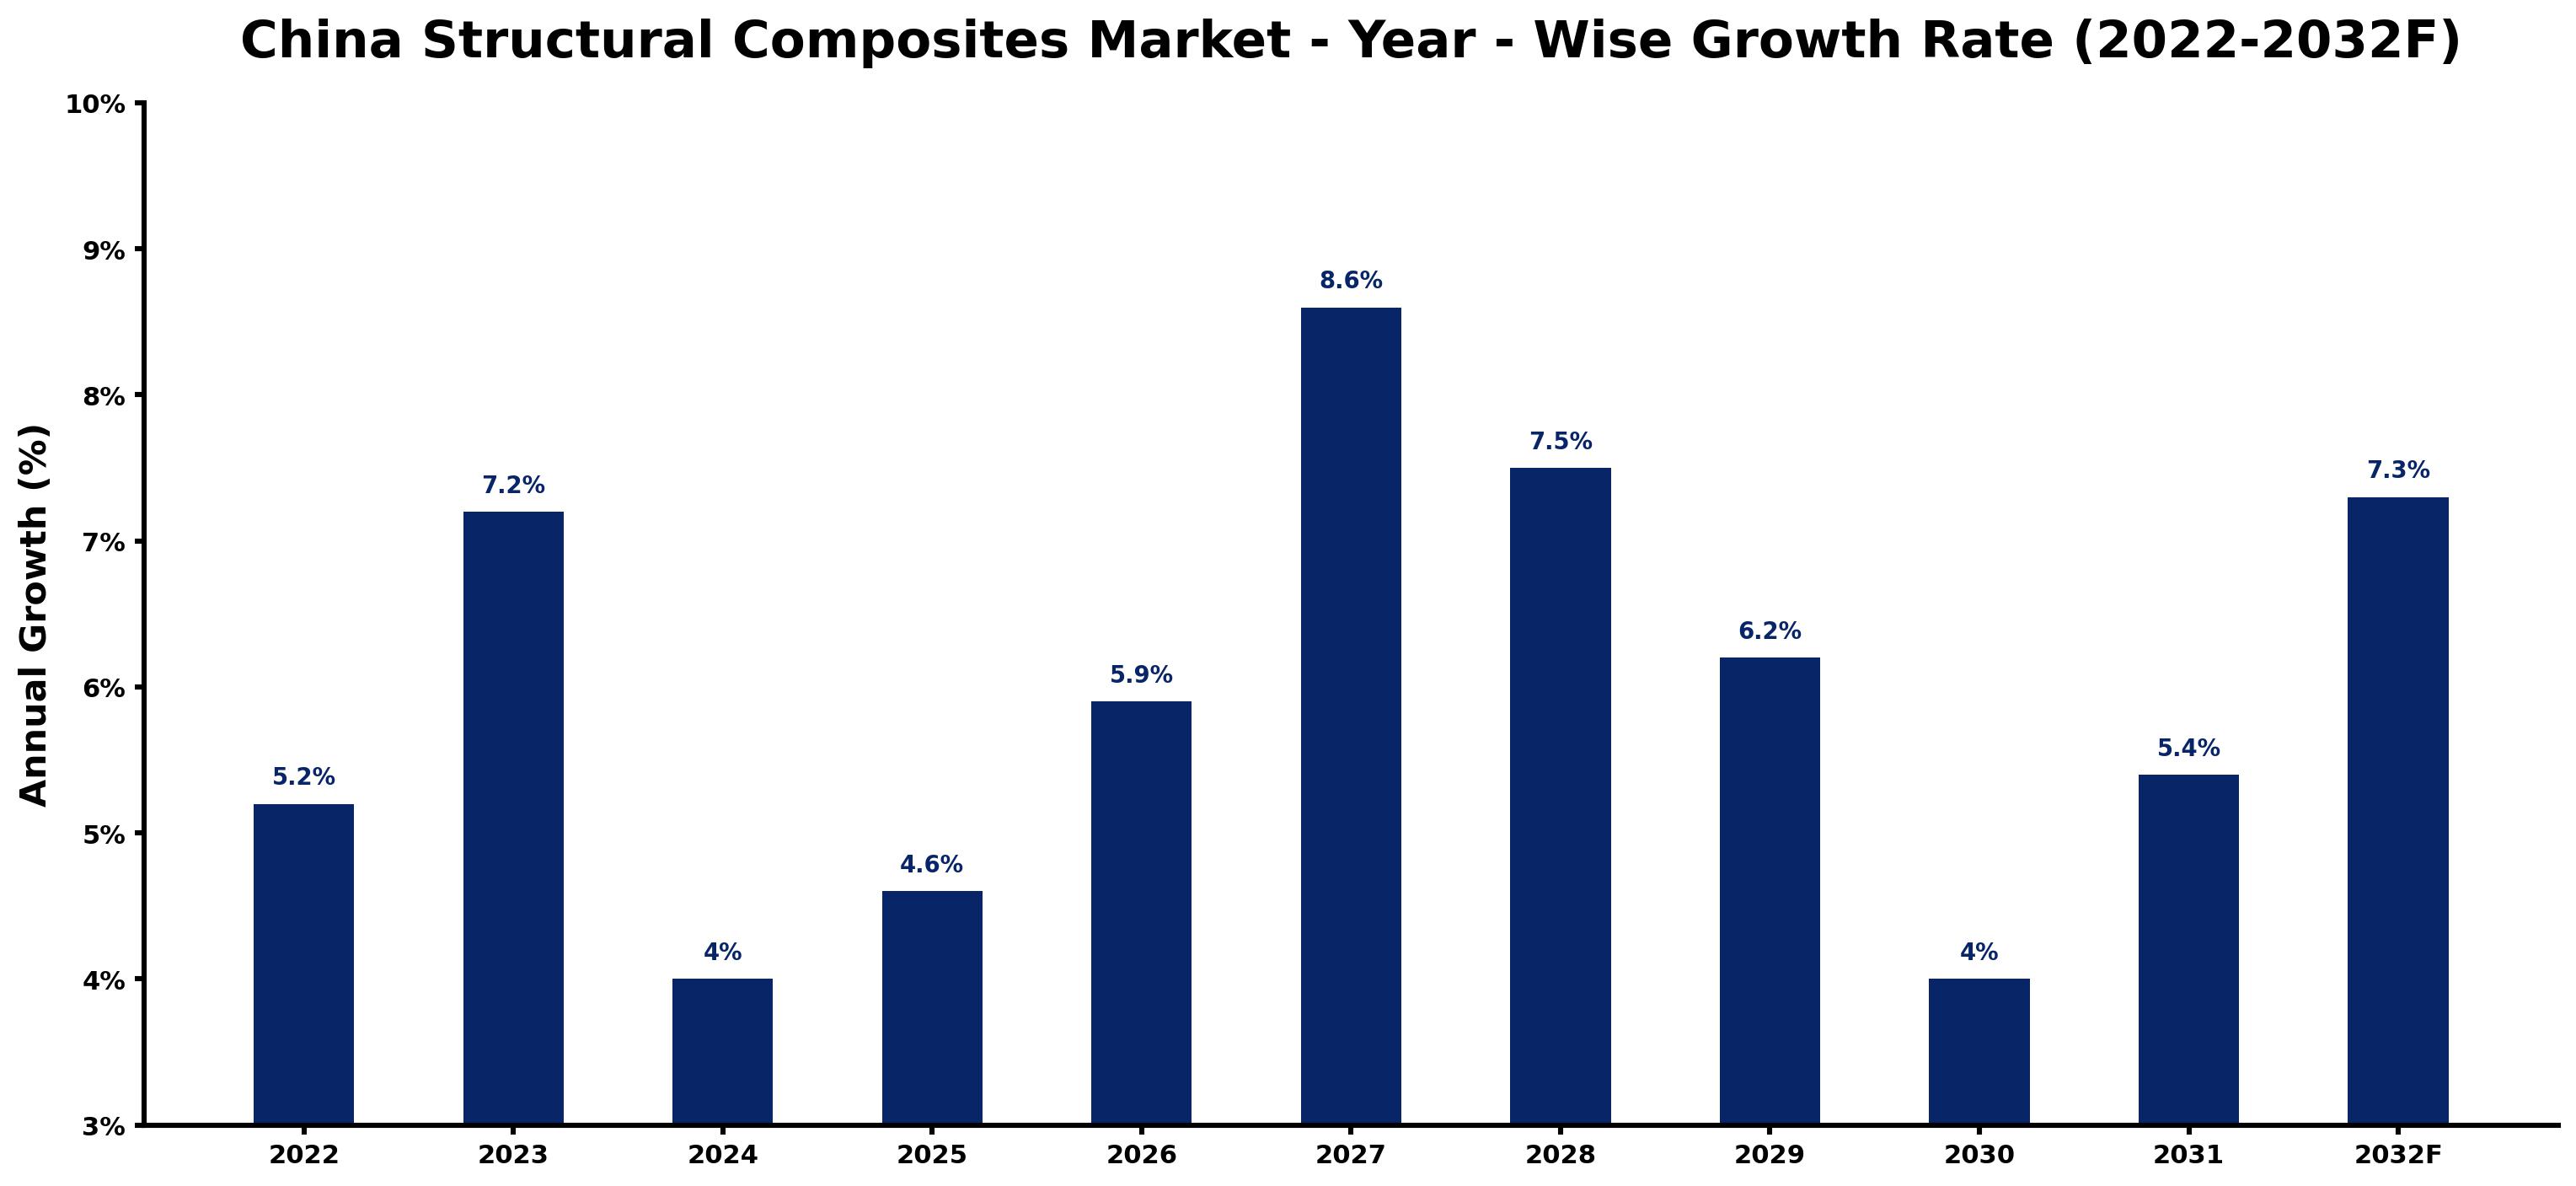
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.2 | The market experienced steady growth due to increasing demand from the aerospace sector, particularly for carbon fiber composites under the 'Made in China 2025' initiative. |
| 2023 | 7.2 | Growth accelerated as the aerospace industry projected a need for 10,000 tons of carbon fiber composites by 2025, boosting production capabilities. |
| 2024 | 4.0 | A slowdown occurred as demand stabilised following rapid growth in the previous year, influenced by the automotive sector's adjustments. |
| 2025 | 4.6 | Growth resumed with the automotive industry producing over 25 million vehicles, increasing the need for lightweight materials and composites. |
| 2026 | 5.9 | Demand is expected to rise as the Ministry of Industry and Information Technology launches the 'Advanced Materials Innovation Action Plan', promoting R&D. |
| 2027 | 8.6 | The market is projected to peak with a surge in demand driven by aerospace and automotive applications, reflecting industry growth. |
| 2028 | 7.5 | A slowdown is anticipated as growth rates normalise after the peak year, influenced by shifting market dynamics in automotive production. |
| 2029 | 6.2 | Demand will continue to grow but at a slower rate, reflecting adjustments in the automotive sector's production strategies. |
| 2030 | 4.0 | Growth is expected to slow as the market stabilises after high demand years, particularly in the aerospace segment. |
| 2031 | 5.4 | An increase in demand is projected as the industry adapts to new standards and innovations in composite applications. |
| 2032 | 7.3 | Growth is expected to rise again as the focus shifts to sustainable practices and advanced materials, driven by government initiatives. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Structural Composites Market Synopsis
Structural Composites in China consist of advanced materials that merge fibres with matrix materials like epoxy or polyester. These composites are manufactured through processes such as moulding and curing, finding applications in aerospace, automotive, and ballistic protection. The China Structural Composites Market is set for robust growth, fuelled by the aerospace sector's demand for 10,000 tons of carbon fibre composites by 2025 and the automotive industry's pursuit of lightweight materials. Initiatives like 'Made in China 2025' further underpin this growth, boosting manufacturing capabilities and driving innovation.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing demand from the aerospace sector drives the need for high-performance composites. | Driver | High | Carbon Fiber Composites |
| The automotive industry's production of over 25 million vehicles boosts demand for lightweight materials. | Driver | High | Glass Fiber Composites |
| The Guangdong province is a major hub for composite production, offering significant investment opportunities. | Opportunity | High | Glass Fiber Composites |
| The growing need for sustainable practices opens avenues for eco-friendly composite materials. | Opportunity | Medium | Hybrid Composites |
| High production costs can limit the competitiveness of local manufacturers. | Restraint | High | Carbon Fiber Composites |
| Strict regulations on quality and safety standards can hinder market entry for new players. | Restraint | Medium | Epoxy Resin |
| Supply chain disruptions can delay the availability of raw materials for production. | Challenge | High | Aramid Composites |
| Technological advancements require continuous investment, posing a financial burden on smaller firms. | Challenge | Medium | Hybrid Composites |
Evaluation of Drivers in China Structural Composites Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Growing demand from the aerospace industry for lightweight materials increases carbon fiber composite usage. | Carbon Fiber Composites | China's aerospace sector is projected to require 10,000 tons of carbon fiber composites by 2025, driving purchases. |
| The automotive industry's shift towards lightweight vehicles drives the use of glass fiber composites. | Glass Fiber Composites | The automotive industry produced over 25 million vehicles in 2022, increasing demand for lightweight materials by 15%. |
| The increasing focus on ballistic protection drives demand for aramid composites in security applications. | Aramid Composites | The use of aramid composites in ballistic protection has surged by 20% in the last three years due to rising security concerns. |
| Growing interest in eco-friendly materials fosters demand for hybrid composites in various applications. | Hybrid Composites | The composites recycling program initiated by the Ministry of Ecology and Environment aims to promote sustainable practices, increasing market adoption. |
| The automotive sector's push for lightweight materials enhances the demand for epoxy resin in composite applications. | Epoxy Resin | The Chinese government aims to increase the use of lightweight materials in vehicles by 30% by 2025, driving demand. |
The aerospace sector's need for lightweight materials is clear, with projections indicating a requirement of 10,000 tons of carbon fiber composites by 2025. In 2022, the automotive industry produced over 25 million vehicles, significantly increasing the demand for lightweight materials. Additionally, the use of aramid composites in ballistic protection surged by 20% in the last three years, reflecting heightened security concerns and the need for advanced solutions.
Evaluation of Restraints in China Structural Composites Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High production costs limit competitiveness in the structural composites market. | Carbon Fiber Composites | The cost of raw materials has risen by 15%, impacting pricing strategies for manufacturers and reducing margins. |
| Strict regulations on quality standards can hinder new market entrants. | Epoxy Resin | Compliance with the updated 'Quality Standards for Composite Materials' requires substantial investment, limiting entry for smaller firms. |
| Supply chain disruptions can delay the availability of key materials for production. | Glass Fiber Composites | Global supply chain issues have affected the timely procurement of composite materials, causing project delays of up to three months. |
| Limited recycling capabilities for composites can restrict sustainable practices. | Hybrid Composites | The current recycling infrastructure is not fully equipped to handle composite materials efficiently, affecting sustainability efforts. |
| Technological advancements require continuous investment, posing challenges for smaller firms. | Aramid Composites | Smaller manufacturers struggle to keep pace with rapid technological changes, leading to increased operational costs of around 20%. |
China Structural Composites Market Challenges
The China Structural Composites Market faces immediate challenges that impede its progress. Rapid technological advancements create a gap for manufacturers, leading to production costs that can escalate by 15% annually for suppliers. A shortage of skilled workers in composite manufacturing restricts production capacity, extending lead times for buyers by an average of three months. Compliance with regulations such as GB/T 1447-2019 complicates operations for producers, requiring substantial investments in testing and certification. Unpredictable demand from the automotive sector, which produced over 25 million vehicles in 2022, introduces uncertainty for buyers, risking overstock or shortages in the supply chain.
Trends in the China Structural Composites Market
Four trends stand out in the China Structural Composites Market.
- Shift towards Eco-Friendly Composites: The 'Green Manufacturing Program' launched in 2023 promotes sustainable practices in the composites industry. This initiative aims to encourage recycling and reduce environmental impact, targeting a 30% increase in eco-friendly material usage by 2025.
- Growing Demand for Lightweight Materials: Automotive suppliers are increasingly embracing lightweight materials to enhance vehicle efficiency. With over 25 million vehicles produced in 2022, the demand for composites is projected to rise by 15%, mirroring market trends.
- Increase in Ballistic Protection Applications: The use of aramid composites in ballistic protection has surged, driven by escalating security concerns. The market for these materials has expanded by 20% in the last three years, underscoring heightened demand.
- Advancements in Composite Recycling: A new initiative focused on composites recycling aims to bolster recycling capabilities within the industry. This programme is designed to strengthen sustainability efforts and support eco-friendly growth.
Investment Opportunities in the China Structural Composites Market
The following opportunities in the China Structural Composites Market pair current demand with a clear way in.
- Guangdong Province as a Composite Hub: Guangdong province is a major hub for composite production, driven by the automotive and aerospace industries. With a projected demand of 1.5 million tons of glass fiber composites by 2025, investment opportunities abound for suppliers.
- Supply of Eco-Friendly Composites: The growing focus on sustainability presents opportunities to supply eco-friendly composite materials. The 'Green Manufacturing Program' encourages the adoption of such materials across various industries, increasing market potential.
- Partnerships for Advanced Material Development: Establishing partnerships with local manufacturers can facilitate entry into the Chinese market. Collaborating with firms in the aerospace sector can improve product offerings and market reach, creating valuable synergies.
- Timing for Investment in Composites: The current push for lightweight materials in vehicles creates a prime opportunity for investment. The Chinese government aims to increase the use of lightweight materials by 30% by 2025, driving demand.
Government Initiatives in the China Structural Composites Market
The 'Advanced Materials Innovation Action Plan' launched by the Ministry of Industry and Information Technology in 2022 is crucial for buyers of structural composites. This initiative promotes research and development in advanced materials, particularly in aerospace and automotive applications, improving the competitiveness of local manufacturers. The plan aims to stimulate innovation and improve production capabilities, ensuring that the industry meets both domestic and international standards. Additionally, the 'New Material Industry Development Plan' approved by the National Development and Reform Commission in 2021 targets a 15% increase in high-performance composites production by 2025, supporting industry growth.
The 'Green Manufacturing Program' introduced by the Ministry of Ecology and Environment in 2023 encourages sustainable practices, including recycling initiatives. This programme supports buyers in adopting eco-friendly materials, enhancing the industry's sustainability. The programme aims to improve recycling capabilities and promote the use of advanced materials, benefiting producers and buyers alike. Furthermore, the National Composites Center focuses on R&D, funding projects that advance composite material development, further supporting the sector's growth.
Future Insight of the China Structural Composites Market
The China Structural Composites Market will undergo substantial transformations by 2032, primarily due to the government's 'Made in China 2025' initiative, which aims to elevate advanced manufacturing. Demand for glass fibre composites in construction and automotive sectors will reach 1.5 million tons by 2025, reflecting a shift towards lightweight materials. The composites recycling programme will encourage sustainable practices, appealing to environmentally conscious buyers. Increased research and development efforts at the National Composites Center will drive innovations in composite applications, boosting market competitiveness.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Composite Type – Carbon Fiber Composites Dominated, Glass Fiber Composites Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, Carbon Fiber Composites took a 37% share of composite type in 2025, more than any other category. Carbon fiber composites dominate the market due to their essential role in aerospace and automotive applications, where their strength-to-weight ratio is crucial. The aerospace sector's projected requirement of 10,000 tons of carbon fiber composites by 2025 exemplifies their importance in high-performance uses. Over 2026–2032, Glass Fiber Composites are expected to post the fastest growth, at a CAGR of 8.5%. Glass fiber composites are experiencing rapid growth, largely due to their cost-effectiveness in construction and automotive applications. The expected demand for glass fiber composites to reach 1.5 million tons by 2025 indicates a strong upward trend in this segment. Suppliers should enhance production capabilities for glass fiber composites to meet the increasing demand across various industries.
By Fiber Type – Carbon Dominated, E-Glass Expected to Grow Fastest
Carbon accounted for a 45% market share by fiber type in 2025. Carbon is the leading fiber type, vital for high-performance applications in aerospace and automotive sectors where durability and lightweight properties are essential. The installed base of carbon fiber composites in aerospace being around 30% as of 2023 highlights its critical role. E-Glass is set to record the highest CAGR in this split, 8.7% over 2026–2032. E-glass fiber is witnessing the fastest growth due to its extensive use in construction and automotive sectors for insulation and strength. The push for lightweight materials in vehicles is expected to significantly increase the demand for E-glass composites by 2025. Manufacturers should consider expanding their offerings in E-glass fiber composites to capitalise on the rising demand across multiple sectors.
By Matrix Material – Epoxy Resin Dominated, Polyester Expected to Grow Fastest
In 2025, Epoxy Resin led the matrix material split with a 45% share. Epoxy resin serves as the primary matrix material for high-performance composites, making it essential in industries that require superior mechanical properties. Its widespread application in aerospace ensures a robust market share for epoxy resin. Polyester is projected to grow fastest, at a CAGR of 8.7% during 2026–2032. Polyester is rapidly gaining traction as a cost-effective matrix material for composite applications, especially in automotive and construction sectors. The growing emphasis on affordable composite solutions is anticipated to drive polyester's market growth. Suppliers should explore opportunities in polyester matrix materials to cater to the rising demand for cost-effective composite solutions.
By End User – Aerospace Industry Dominated, Automotive Suppliers Expected to Grow Fastest
Aerospace Industry held a 51% share of the China Structural Composites Market by end user in 2025. The aerospace industry is the largest end user of structural composites, driven by its need for high-performance materials in aircraft manufacturing. This sector's substantial demand for advanced composites ensures a significant market share. The quickest growth will come from Automotive Suppliers, forecast to expand at a CAGR of 7.5% between 2026 and 2032. Automotive suppliers represent the fastest-growing end user segment, increasingly adopting composites for lightweight vehicle components. The Chinese government's target to increase lightweight materials in vehicles by 30% by 2025 will further accelerate this growth. Suppliers must align their strategies to meet the evolving needs of automotive suppliers, focusing on lightweight composite solutions.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Structural Composites Market Outlook
- Market Size of China Structural Composites Market, 2025
- Forecast of China Structural Composites Market, 2032
- Historical Data and Forecast of China Structural Composites Revenues & Volume for the Period 2022 - 2032F
- China Structural Composites Market Trend Evolution
- China Structural Composites Market Drivers and Challenges
- China Structural Composites Price Trends
- China Structural Composites Porter's Five Forces
- China Structural Composites Industry Life Cycle
- Historical Data and Forecast of China Structural Composites Market Revenues & Volume By Composite Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Composites Market Revenues & Volume By Carbon Fiber Composites for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Composites Market Revenues & Volume By Glass Fiber Composites for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Composites Market Revenues & Volume By Aramid Composites for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Composites Market Revenues & Volume By Hybrid Composites for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Composites Market Revenues & Volume By Fiber Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Composites Market Revenues & Volume By Carbon for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Composites Market Revenues & Volume By E-Glass for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Composites Market Revenues & Volume By Kevlar for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Composites Market Revenues & Volume By Mixed Fiber for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Composites Market Revenues & Volume By Matrix Material for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Composites Market Revenues & Volume By Epoxy Resin for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Composites Market Revenues & Volume By Polyester for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Composites Market Revenues & Volume By Thermoplastic for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Composites Market Revenues & Volume By Vinyl Ester for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Composites Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Composites Market Revenues & Volume By Aerospace Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Composites Market Revenues & Volume By Automotive Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Composites Market Revenues & Volume By Ballistic Protection Firms for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Composites Market Revenues & Volume By Sports Equipment Makers for the Period 2022 - 2032F
- China Structural Composites Import Export Trade Statistics
- Market Opportunity Assessment By Composite Type
- Market Opportunity Assessment By Fiber Type
- Market Opportunity Assessment By Matrix Material
- Market Opportunity Assessment By End User
- China Structural Composites Top Companies Market Share
- China Structural Composites Competitive Benchmarking By Technical and Operational Parameters
- China Structural Composites Company Profiles
- China Structural Composites Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Composite Type
- Carbon Fiber Composites
- Glass Fiber Composites
- Aramid Composites
- Hybrid Composites
By Fiber Type
- Carbon
- E-Glass
- Kevlar
- Mixed Fiber
By Matrix Material
- Epoxy Resin
- Polyester
- Thermoplastic
- Vinyl Ester
By End User
- Aerospace Industry
- Automotive Suppliers
- Ballistic Protection Firms
- Sports Equipment Makers































