China Structural Stamp Components Market Size & Growth Rate
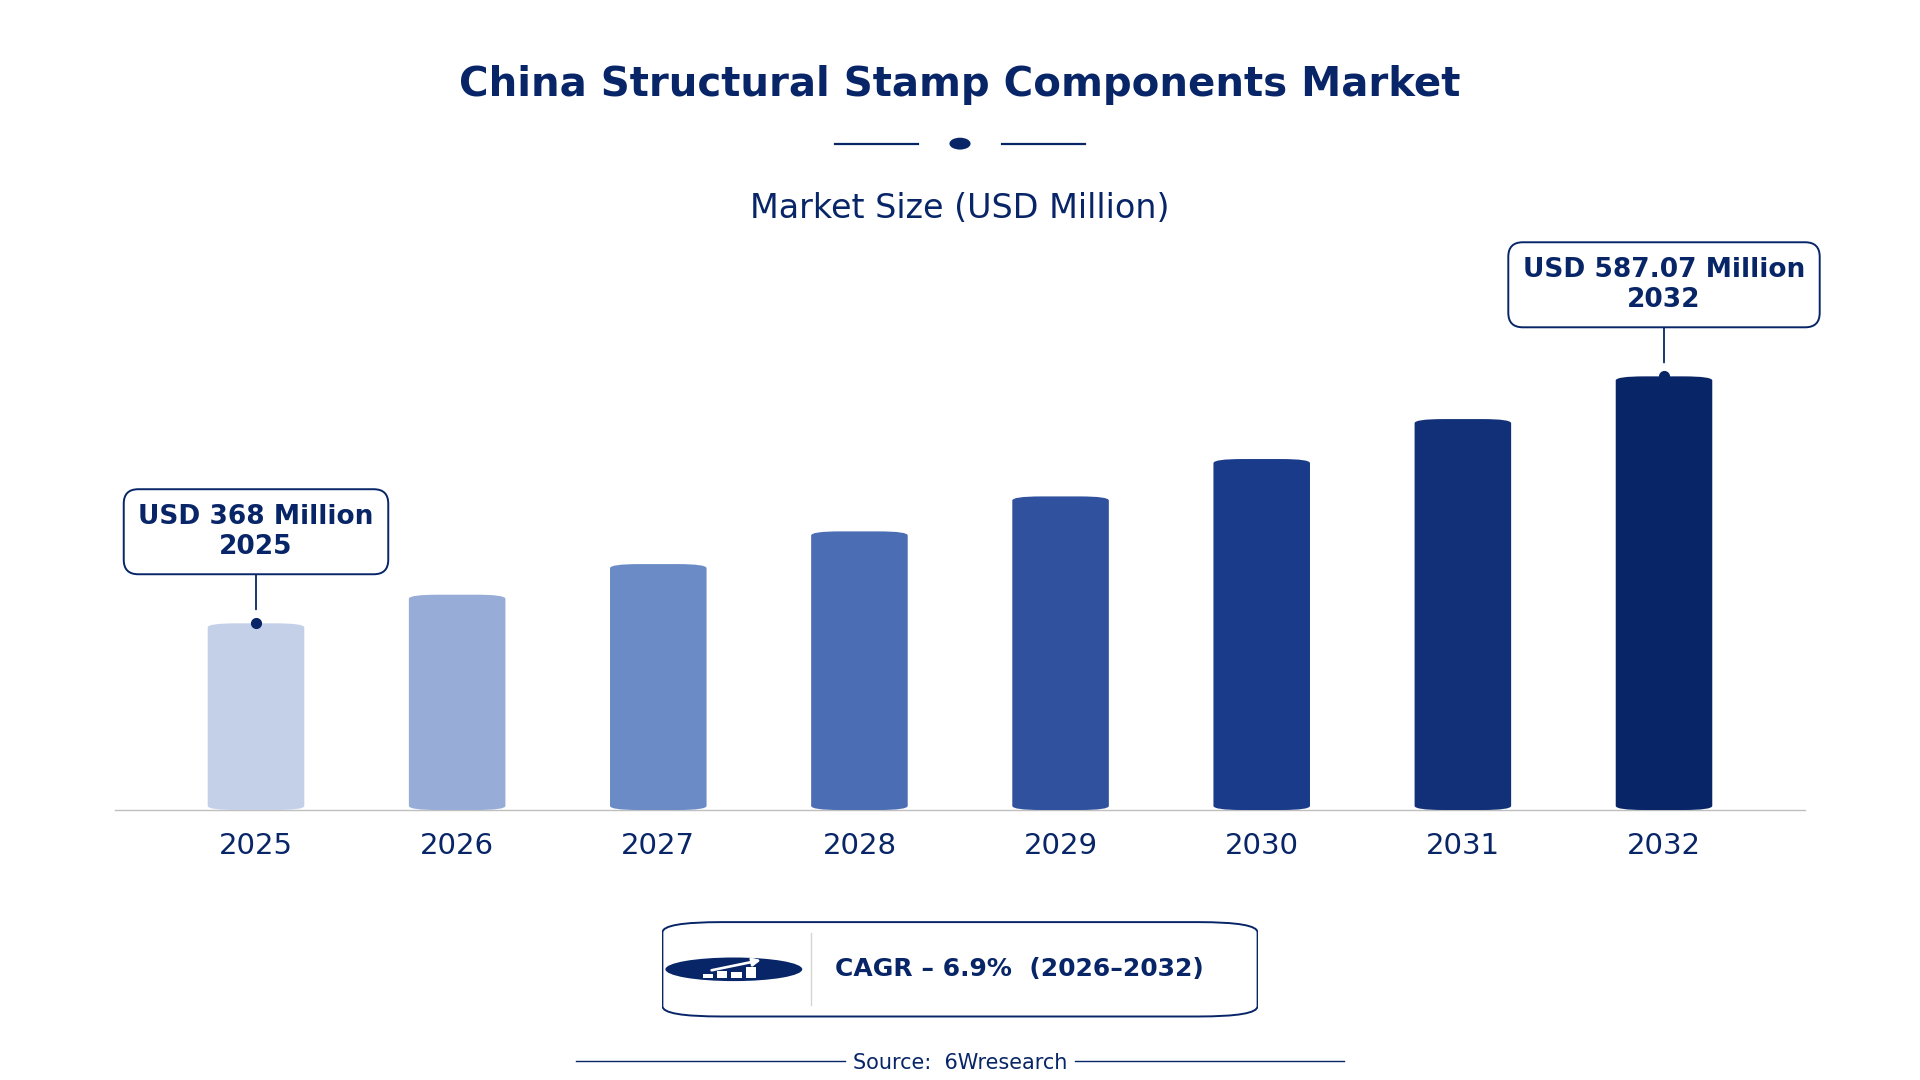
According to 6Wresearch internal database and industry insights, the China Structural Stamp Components Market was valued at USD 368.0 million in 2025 and is projected to reach USD 587.07 million by 2032, growing at a CAGR of approximately 6.9% during 2026–2032.
China Structural Stamp Components Market Highlights
| Report Metric | Details |
| Report Name | China Structural Stamp Components Market |
| Market Size 2025 | USD 368.0 million |
| Market Size 2032 | USD 587.07 million |
| Absolute Growth 2025–2032 | USD 219.07 million |
| CAGR 2026–2032 | 6.9% |
| Peak Annual Growth | 8.9% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Component Type, 2025 | Floor Panels (46% share) |
| Leading Metal Type, 2025 | Aluminum Alloy (39% share) |
| Leading Manufacturing Method, 2025 | Deep Drawing (41% share) |
| Leading End User, 2025 | Car Body Shops (41% share) |
| Fastest-Growing Component Type | Door Frames (9.1% CAGR) |
| Fastest-Growing Metal Type | Cold-Rolled Steel (9.5% CAGR) |
| Fastest-Growing Manufacturing Method | Progressive Die (8.5% CAGR) |
| Fastest-Growing End User | Vehicle OEMs (9.3% CAGR) |
| Growing Sector | Vehicle OEMs |
| Key End Users | Car Body Shops, Vehicle OEMs, Auto Part Suppliers, Crash Structure Engineers |
China Structural Stamp Components Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
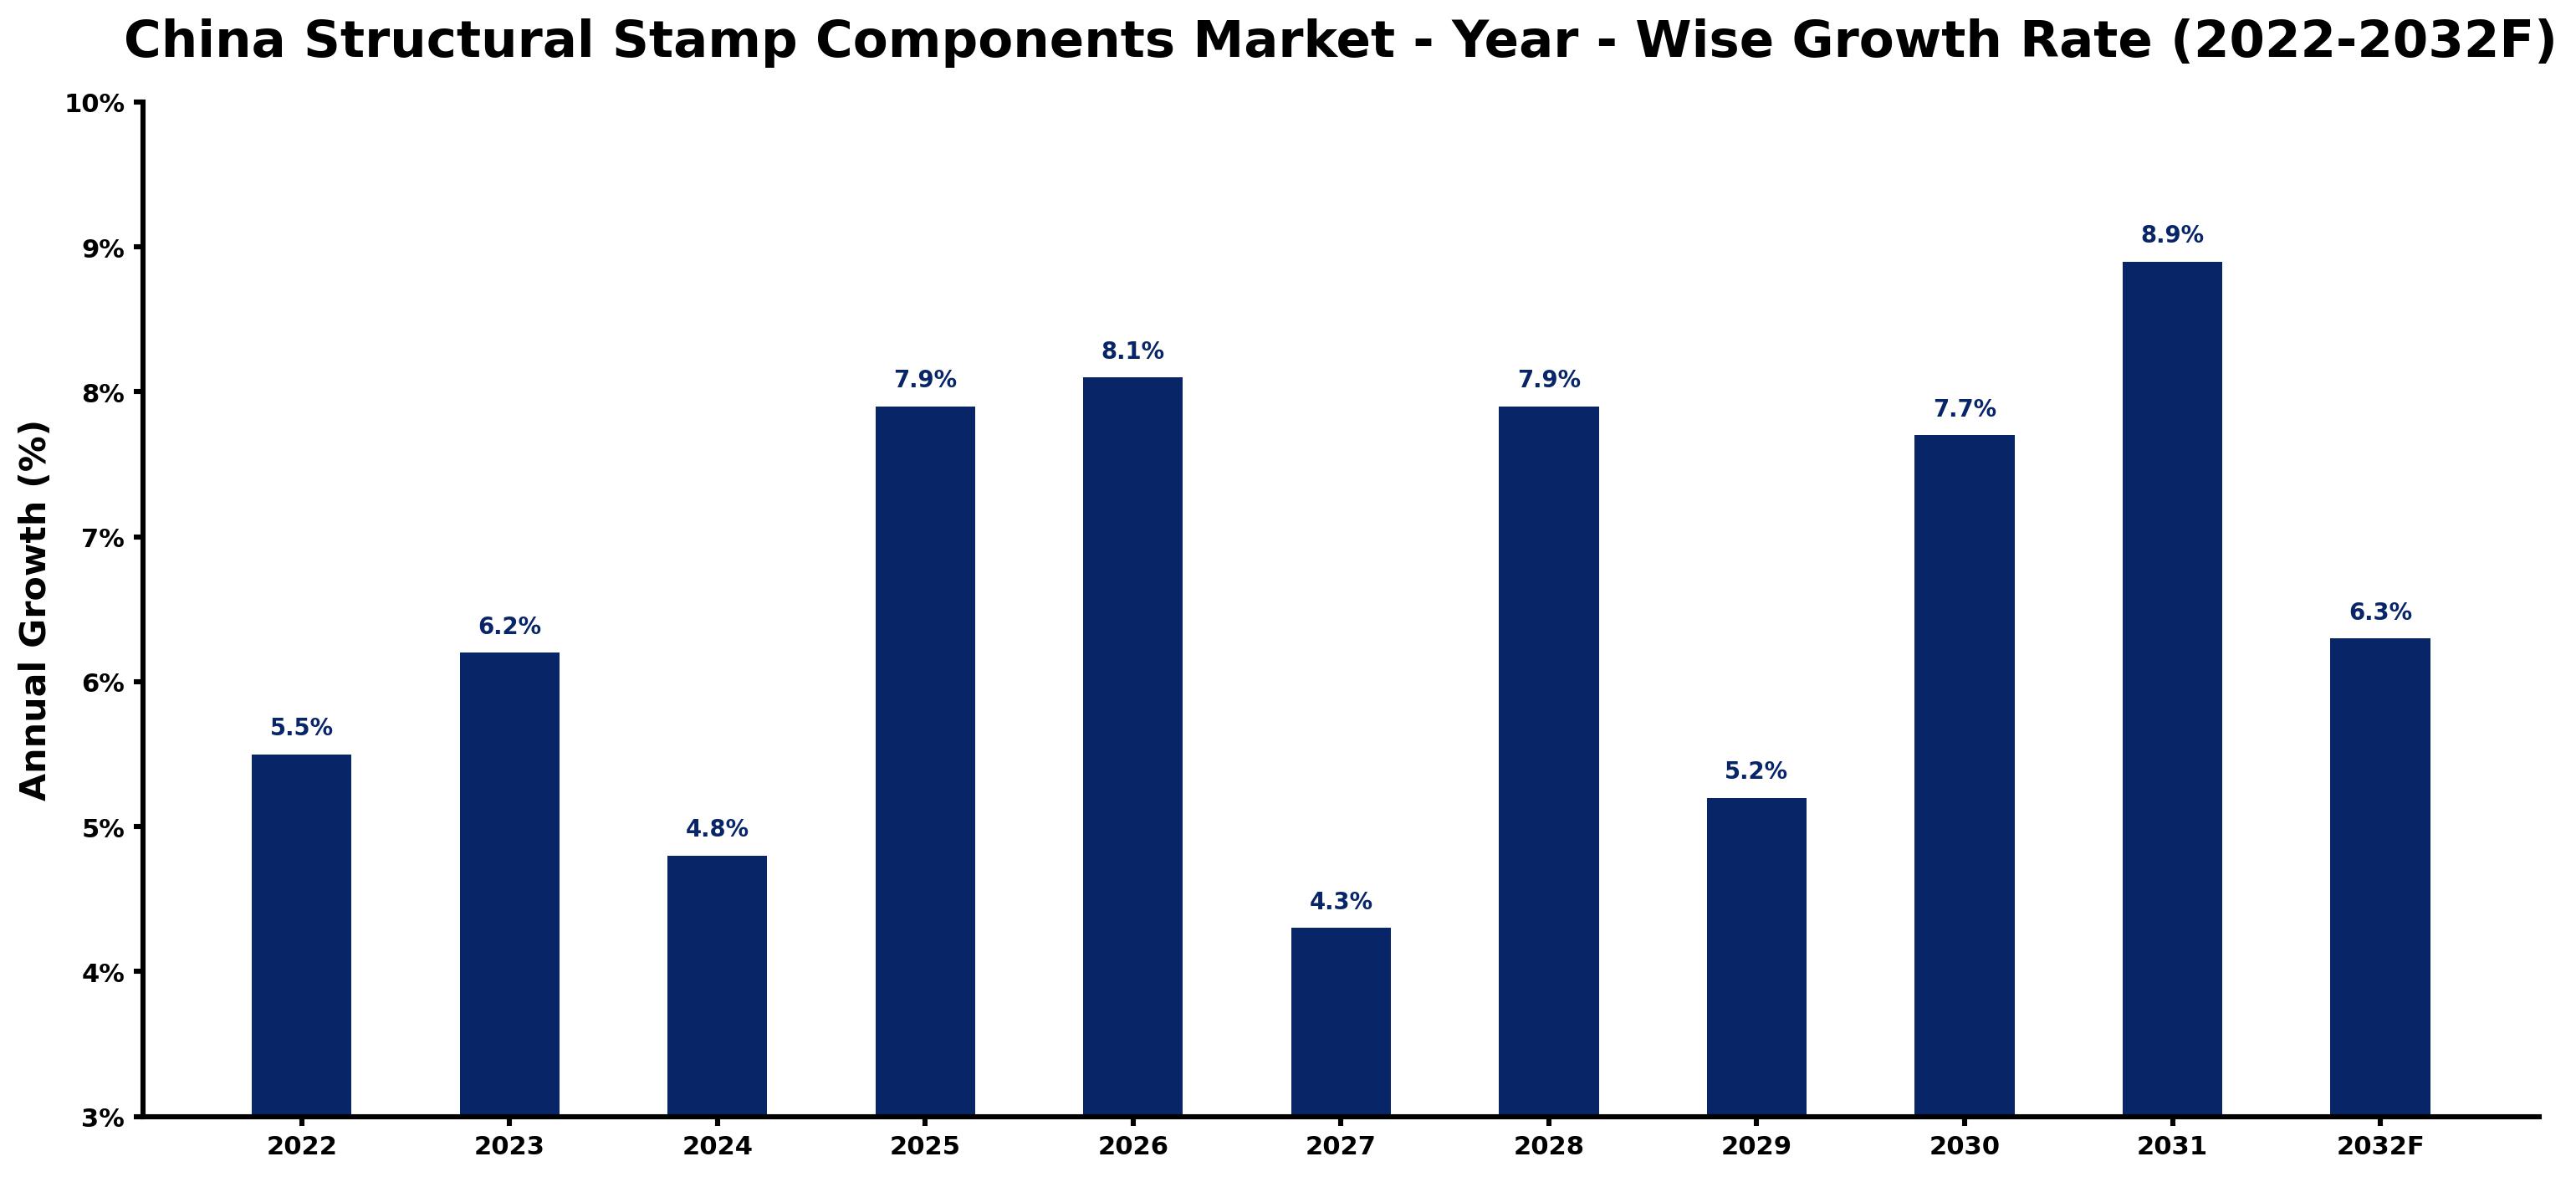
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.5 | The automotive sector in China experienced steady production levels, maintaining demand for structural components. |
| 2023 | 6.2 | Increased investments in the automotive sector boosted demand for structural stamp components. |
| 2024 | 4.8 | Temporary supply chain disruptions slowed growth, affecting production rates for structural components. |
| 2025 | 7.9 | A surge in vehicle production led to heightened demand for structural components in the automotive sector. |
| 2026 | 8.1 | Investment in automotive innovation is projected to support a rise in demand for advanced components. |
| 2027 | 4.3 | Demand growth is expected to slow as manufacturers adapt to changing market conditions. |
| 2028 | 7.9 | A focus on improving vehicle safety features will drive demand for structural components in new models. |
| 2029 | 5.2 | Market growth is projected to slow as manufacturers face challenges in sourcing raw materials efficiently. |
| 2030 | 7.7 | A renewed push for electric vehicle production will increase demand for lightweight structural components. |
| 2031 | 8.9 | The automotive market is anticipated to peak, driven by high production rates and innovations in vehicle design. |
| 2032 | 6.3 | Demand growth is expected to slow as the Automotive Industry Development Plan (2021-2025) influences production levels. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Structural Stamp Components Market Synopsis
Structural Stamp Components are key elements in China's automotive industry, primarily crafted from metals such as steel and aluminium. These components play a crucial role in ensuring vehicle safety and structural integrity, which are fundamental for performance. The China Structural Stamp Components Market is expanding, driven by a thriving domestic automotive sector that produced over 25 million vehicles in 2022. Substantial investments, amounting to around 1 trillion yuan in 2022, are propelling innovation and increasing production capacity. Vehicle OEMs and auto part suppliers represent the main buyers, further stimulating market growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing vehicle production rates | Driver | High | Vehicle OEMs |
| Growing use of lightweight materials | Driver | High | Aluminum Alloy |
| Rising demand for vehicle safety features | Opportunity | High | Crash Structure Engineers |
| Increased investment in automotive innovation | Opportunity | High | Auto Part Suppliers |
| Supply chain disruptions | Restraint | High | Floor Panels |
| Regulatory compliance costs | Restraint | Medium | Floor Panels |
| Talent shortages in manufacturing | Challenge | High | Floor Panels |
| Fluctuating raw material prices | Challenge | Medium | Floor Panels |
Evaluation of Drivers in China Structural Stamp Components Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Surge in vehicle production | Vehicle OEMs | China's automotive sector produced over 25 million vehicles annually, increasing demand for structural components. |
| Adoption of lightweight materials | Aluminum Alloy | Lightweight materials are increasingly used, accounting for 30% of vehicle weight, driving demand for structural stamp components. |
| Focus on safety regulations | Crash Structure Engineers | Recent safety regulations prioritise features, increasing demand for structural components in vehicle design. |
| Investment in automotive innovation | Auto Part Suppliers | The automotive sector saw an investment of approximately 1 trillion yuan in 2022, boosting component demand. |
| Demand for complex shapes | Progressive Die | The need for intricate designs in vehicles drives the use of progressive die manufacturing methods. |
In 2022, over 25 million vehicles were produced, driving demand for structural components. The automotive sector received approximately 1 trillion yuan in investments, which supports innovation and production capabilities. The adoption of advanced manufacturing methods, such as progressive die stamping, is also pushing demand for complex shapes in vehicle design.
Evaluation of Restraints in China Structural Stamp Components Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions | Floor Panels | Recent disruptions have delayed production schedules, impacting the availability of structural components. |
| Regulatory compliance costs | Floor Panels | Manufacturers face increased costs to meet national standards, affecting their pricing strategies. |
| Talent shortages in manufacturing | Floor Panels | A lack of skilled workers in the automotive sector is hindering production efficiency and capacity. |
| Fluctuating raw material prices | Floor Panels | Volatility in raw material costs affects budgeting and profitability for manufacturers. |
| Limited access to advanced technologies | Floor Panels | Some manufacturers struggle to adopt new technologies, impacting their competitiveness. |
China Structural Stamp Components Market Challenges
The China Structural Stamp Components Market encounters significant technological hurdles, particularly in the adoption of Advanced High-Strength Steel, which many producers cannot implement due to outdated machinery, causing delays for vehicle OEMs. A skills gap persists in the automotive sector, which employs over 5 million people, leading to inefficiencies that hinder production timelines for auto part suppliers. Buyers face unpredictable costs driven by the reliance on specific materials, such as aluminum, which now constitutes 30% of vehicle weight, complicating budgeting for manufacturers. Supply chain disruptions are common, as the automotive supply chain comprises over 30,000 registered auto part suppliers, resulting in delays for manufacturers and increased operational costs.
Trends in the China Structural Stamp Components Market
Four trends stand out in the China Structural Stamp Components Market.
- Shift towards Lightweight Materials: The automotive industry is increasingly adopting lightweight materials like aluminium alloys to improve fuel efficiency. This trend began in 2021 and is reflected in the growing use of aluminium components, which account for 30% of vehicle weight.
- Increased Focus on Vehicle Safety: Crash structure engineers are prioritising safety features in vehicle designs, leading to a rise in demand for structural components. This shift has been notable since 2023, with safety regulations driving innovations in design.
- Transition to Advanced Manufacturing Techniques: Manufacturers are moving towards advanced techniques like progressive die stamping to produce complex shapes more efficiently. This trend started gaining traction in 2022, reflecting the need for innovative production methods.
- Growing Investment in Automotive Innovation: Investment in the automotive sector surged in 2022, with approximately 1 trillion yuan allocated to enhance production capabilities. This trend highlights the industry's commitment to innovation and competitiveness.
Investment Opportunities in the China Structural Stamp Components Market
Several openings in the China Structural Stamp Components Market merit attention from investors.
- Investment in Lightweight Components: With the automotive sector producing over 25 million vehicles annually, there is a growing demand for lightweight structural components. Suppliers can target Vehicle OEMs in regions like Jiangsu by providing advanced aluminium alloy products.
- Expansion of Manufacturing Capabilities: The current investment climate presents an opportunity to improve manufacturing capabilities. Auto part suppliers can benefit from the Automotive Industry Development Plan (2021-2025) by collaborating with local manufacturers in Guangdong.
- Focus on Safety Innovations: As safety regulations become stricter, there is an opportunity to supply advanced structural components. Crash structure engineers in Shandong are seeking innovative solutions to improve vehicle safety features.
- Technological Upgrades in Production: The shift towards advanced manufacturing techniques creates a demand for suppliers of new technologies. Manufacturers in Guangdong are looking to adopt progressive die methods to improve production efficiency.
Government Initiatives in the China Structural Stamp Components Market
The national standard GB/T 5237, established in 2020, governs the quality of automotive stampings in China, ensuring that manufacturers meet specific safety and performance criteria. Additionally, the Automotive Industry Development Plan (2021-2025) aims to boost innovation and efficiency in the automotive sector, encouraging investment in advanced manufacturing technologies and materials. This plan is expected to enhance the overall competitiveness of the industry and improve product quality for consumers.
The Ministry of Industry and Information Technology oversees the implementation of automotive standards and regulations, approving projects that improve production capabilities. This agency also funds initiatives aimed at enhancing the overall efficiency and safety of the automotive supply chain, benefiting both producers and consumers. In 2022, funding for innovation projects reached approximately 500 million yuan, supporting advancements in technology adoption and compliance with national standards.
Future Insight of the China Structural Stamp Components Market
The China Structural Stamp Components Market is set to evolve significantly by 2032, propelled by the Automotive Industry Development Plan (2021-2025) that prioritises innovation. Investment in advanced production technologies will enhance efficiency, benefiting both buyers and suppliers. A growing focus on safety features will drive the development of structural components, ensuring adherence to national standards like GB/T 5237. With domestic vehicle production increasing by 15% in 2023, the demand for high-quality stamped parts will remain robust, reinforcing the market's growth trajectory.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Component Type – Floor Panels Dominated, Door Frames Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, the largest component type category in 2025 was Floor Panels, with a 46% share of total revenue. Floor panels are crucial for providing structural support in vehicle bodies, which is essential for safety and performance. Their widespread use across various vehicle types in China reinforces their dominant market share, particularly in regions with high automotive production. The quickest growth will come from Door Frames, forecast to expand at a CAGR of 9.1% between 2026 and 2032. The rapid growth of door frames is attributed to the increasing emphasis on vehicle safety and innovative designs that enhance crash protection. This trend is further accelerated by regulatory changes prioritising safety features in automotive manufacturing. Suppliers should focus on increasing production capabilities for door frames to satisfy the rising demand from manufacturers.
By Metal Type – Aluminum Alloy Dominated, Cold-Rolled Steel Expected to Grow Fastest
With a 39% revenue share in 2025, Aluminum Alloy was the largest metal type category. Aluminum alloy leads the market due to its lightweight and corrosion-resistant characteristics, making it a preferred choice for vehicle manufacturers aiming to enhance fuel efficiency. Its role in reducing overall vehicle weight is underscored by the average of over 300 stamped metal parts per vehicle. Cold-Rolled Steel is set to record the highest CAGR in this split, 9.5% over 2026–2032. Cold-rolled steel is witnessing rapid growth as manufacturers seek materials that provide superior strength and formability for various applications. This shift is particularly relevant as the automotive sector adapts to evolving safety standards that necessitate more robust components. Buyers should consider sourcing more cold-rolled steel to align with the changing demands of manufacturing and safety regulations.
By Manufacturing Method – Deep Drawing Dominated, Progressive Die Expected to Grow Fastest
Deep Drawing held a 41% share of the China Structural Stamp Components Market by manufacturing method in 2025. Deep drawing is the predominant manufacturing method, adept at creating complex shapes that are vital for various structural components in vehicles. Its established usage in producing critical parts reinforces its leading position in the market. Progressive Die is projected to grow fastest, at a CAGR of 8.5% during 2026–2032. The progressive die method is experiencing the fastest growth due to its efficiency in high-volume production, which meets the increasing demand for structural components in the automotive industry. This efficiency is essential for manufacturers aiming to scale operations amid rising production rates. Manufacturers must invest in progressive die technology to improve production efficiency and address the growing market demands.
By End User – Car Body Shops Dominated, Vehicle OEMs Expected to Grow Fastest
Car Body Shops accounted for a 41% market share by end user in 2025. Car body shops represent the largest market share as they are the primary users of structural components during vehicle assembly. Their integral role in the automotive supply chain ensures a steady demand for essential parts, particularly in regions with high vehicle production. Over 2026–2032, Vehicle OEMs are expected to post the fastest growth, at a CAGR of 9.3%. Vehicle OEMs are the fastest-growing end users, driven by their requirement for high-quality structural components to meet escalating production targets and safety standards. The reported 15% increase in domestic vehicle production in 2023 highlights their expanding influence in the market. Suppliers should strengthen partnerships with vehicle OEMs to capitalise on their increasing demand for structural components.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Structural Stamp Components Market Outlook
- Market Size of China Structural Stamp Components Market, 2025
- Forecast of China Structural Stamp Components Market, 2032
- Historical Data and Forecast of China Structural Stamp Components Revenues & Volume for the Period 2022 - 2032F
- China Structural Stamp Components Market Trend Evolution
- China Structural Stamp Components Market Drivers and Challenges
- China Structural Stamp Components Price Trends
- China Structural Stamp Components Porter's Five Forces
- China Structural Stamp Components Industry Life Cycle
- Historical Data and Forecast of China Structural Stamp Components Market Revenues & Volume By Component Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Stamp Components Market Revenues & Volume By Floor Panels for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Stamp Components Market Revenues & Volume By Door Frames for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Stamp Components Market Revenues & Volume By Crossmembers for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Stamp Components Market Revenues & Volume By Roof Rails for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Stamp Components Market Revenues & Volume By Metal Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Stamp Components Market Revenues & Volume By Aluminum Alloy for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Stamp Components Market Revenues & Volume By Cold-Rolled Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Stamp Components Market Revenues & Volume By Galvanized Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Stamp Components Market Revenues & Volume By AHSS for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Stamp Components Market Revenues & Volume By Manufacturing Method for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Stamp Components Market Revenues & Volume By Deep Drawing for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Stamp Components Market Revenues & Volume By Progressive Die for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Stamp Components Market Revenues & Volume By Press Stamping for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Stamp Components Market Revenues & Volume By Transfer Die for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Stamp Components Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Stamp Components Market Revenues & Volume By Car Body Shops for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Stamp Components Market Revenues & Volume By Vehicle OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Stamp Components Market Revenues & Volume By Auto Part Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Stamp Components Market Revenues & Volume By Crash Structure Engineers for the Period 2022 - 2032F
- China Structural Stamp Components Import Export Trade Statistics
- Market Opportunity Assessment By Component Type
- Market Opportunity Assessment By Metal Type
- Market Opportunity Assessment By Manufacturing Method
- Market Opportunity Assessment By End User
- China Structural Stamp Components Top Companies Market Share
- China Structural Stamp Components Competitive Benchmarking By Technical and Operational Parameters
- China Structural Stamp Components Company Profiles
- China Structural Stamp Components Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Component Type
- Floor Panels
- Door Frames
- Crossmembers
- Roof Rails
By Metal Type
- Aluminum Alloy
- Cold-Rolled Steel
- Galvanized Steel
- AHSS
By Manufacturing Method
- Deep Drawing
- Progressive Die
- Press Stamping
- Transfer Die
By End User
- Car Body Shops
- Vehicle OEMs
- Auto Part Suppliers
- Crash Structure Engineers































