China Suspension System Market Size & Growth Rate
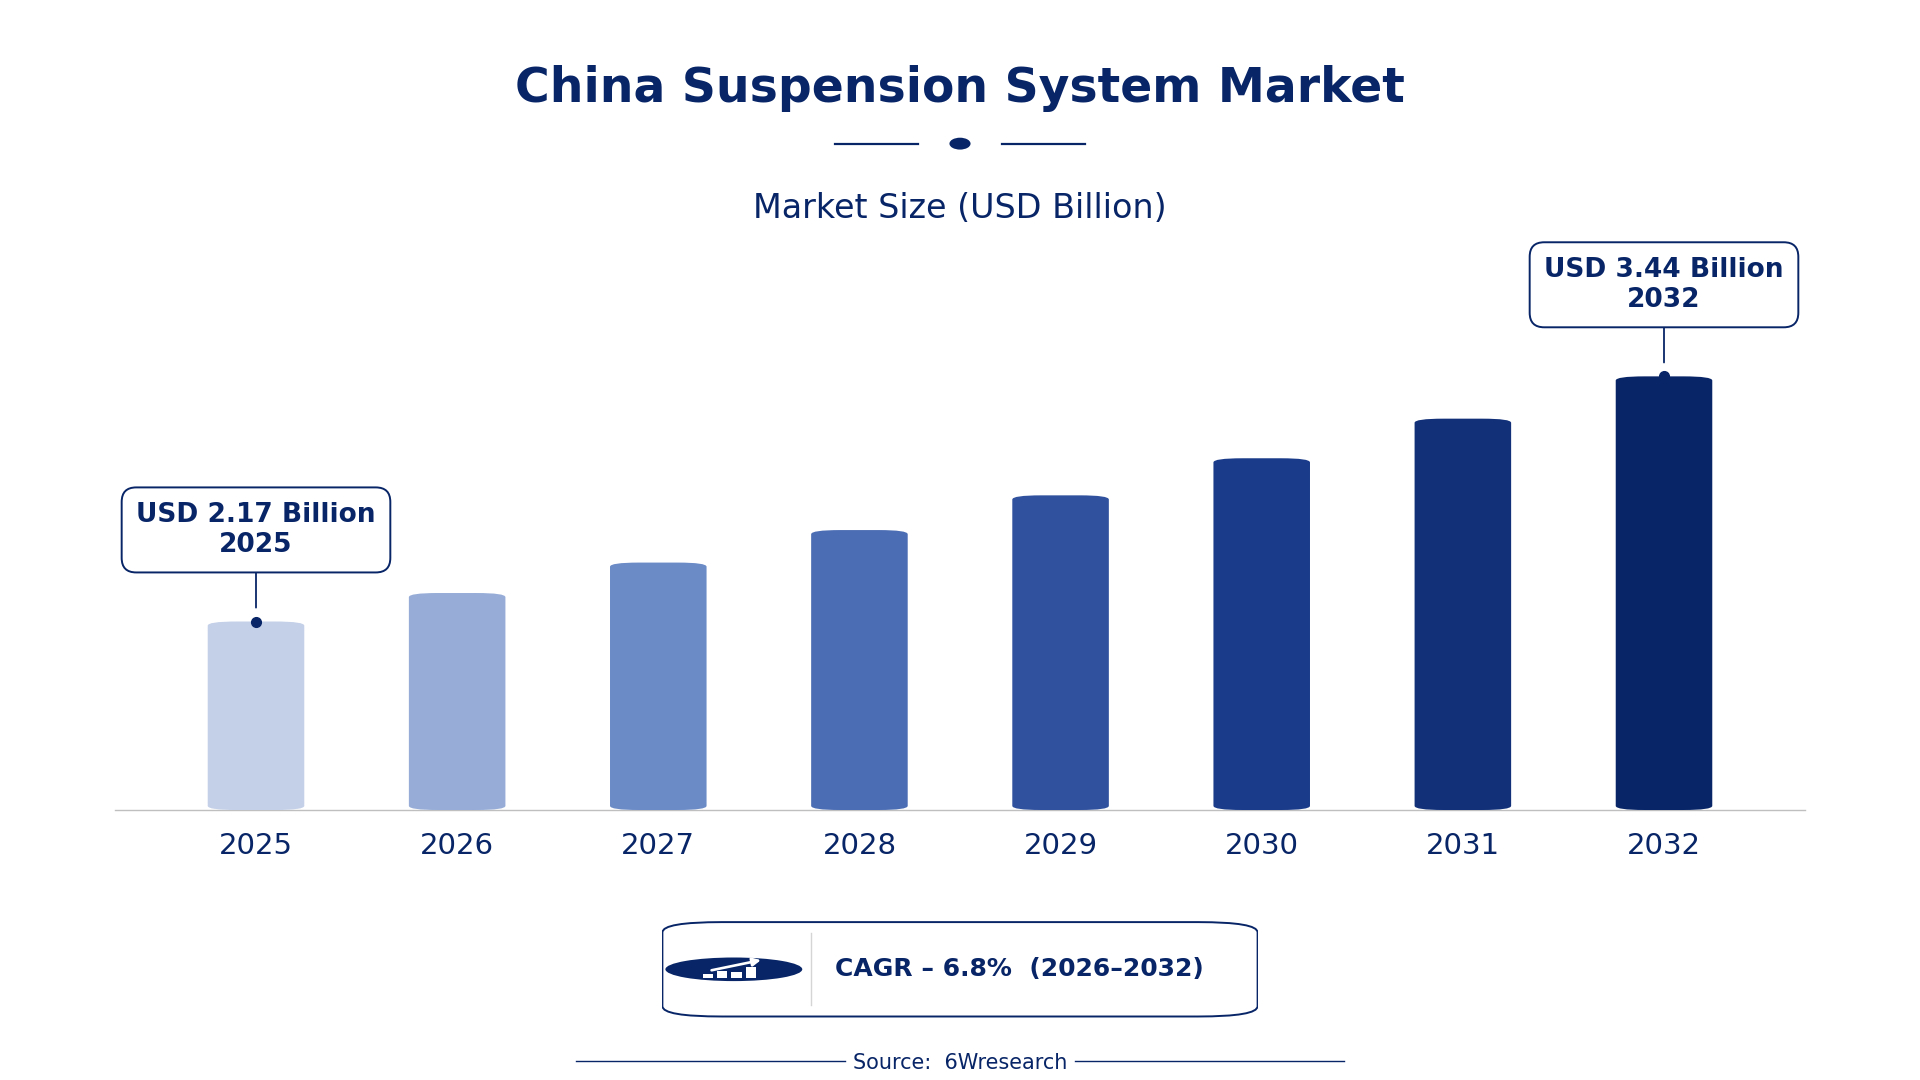
According to 6Wresearch internal database and industry insights, the China Suspension System Market was valued at USD 2.17 billion in 2025 and is projected to reach USD 3.44 billion by 2032, growing at a CAGR of approximately 6.8% during 2026–2032.
China Suspension System Market Highlights
| Report Metric | Details |
| Report Name | China Suspension System Market |
| Market Size 2025 | USD 2.17 billion |
| Market Size 2032 | USD 3.44 billion |
| Absolute Growth 2025–2032 | USD 1.27 billion |
| CAGR 2026–2032 | 6.8% |
| Peak Annual Growth | 8.2% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading System Type, 2025 | Passive Suspension (32% share) |
| Leading Technology Used, 2025 | Conventional Shock Absorbers (44% share) |
| Leading Vehicle Segment, 2025 | Compact & Sedan Cars (48% share) |
| Leading End User, 2025 | OEMs (36% share) |
| Fastest-Growing System Type | Active Suspension (8.2% CAGR) |
| Fastest-Growing Technology Used | Electronically Controlled (8.0% CAGR) |
| Fastest-Growing Vehicle Segment | EVs & Hybrids (8.2% CAGR) |
| Fastest-Growing End User | Fleet Manufacturers (9.5% CAGR) |
| Growing Sector | Luxury & Premium Vehicles |
| Key End Users | OEMs, Fleet Manufacturers, Suspension Tech Providers |
China Suspension System Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
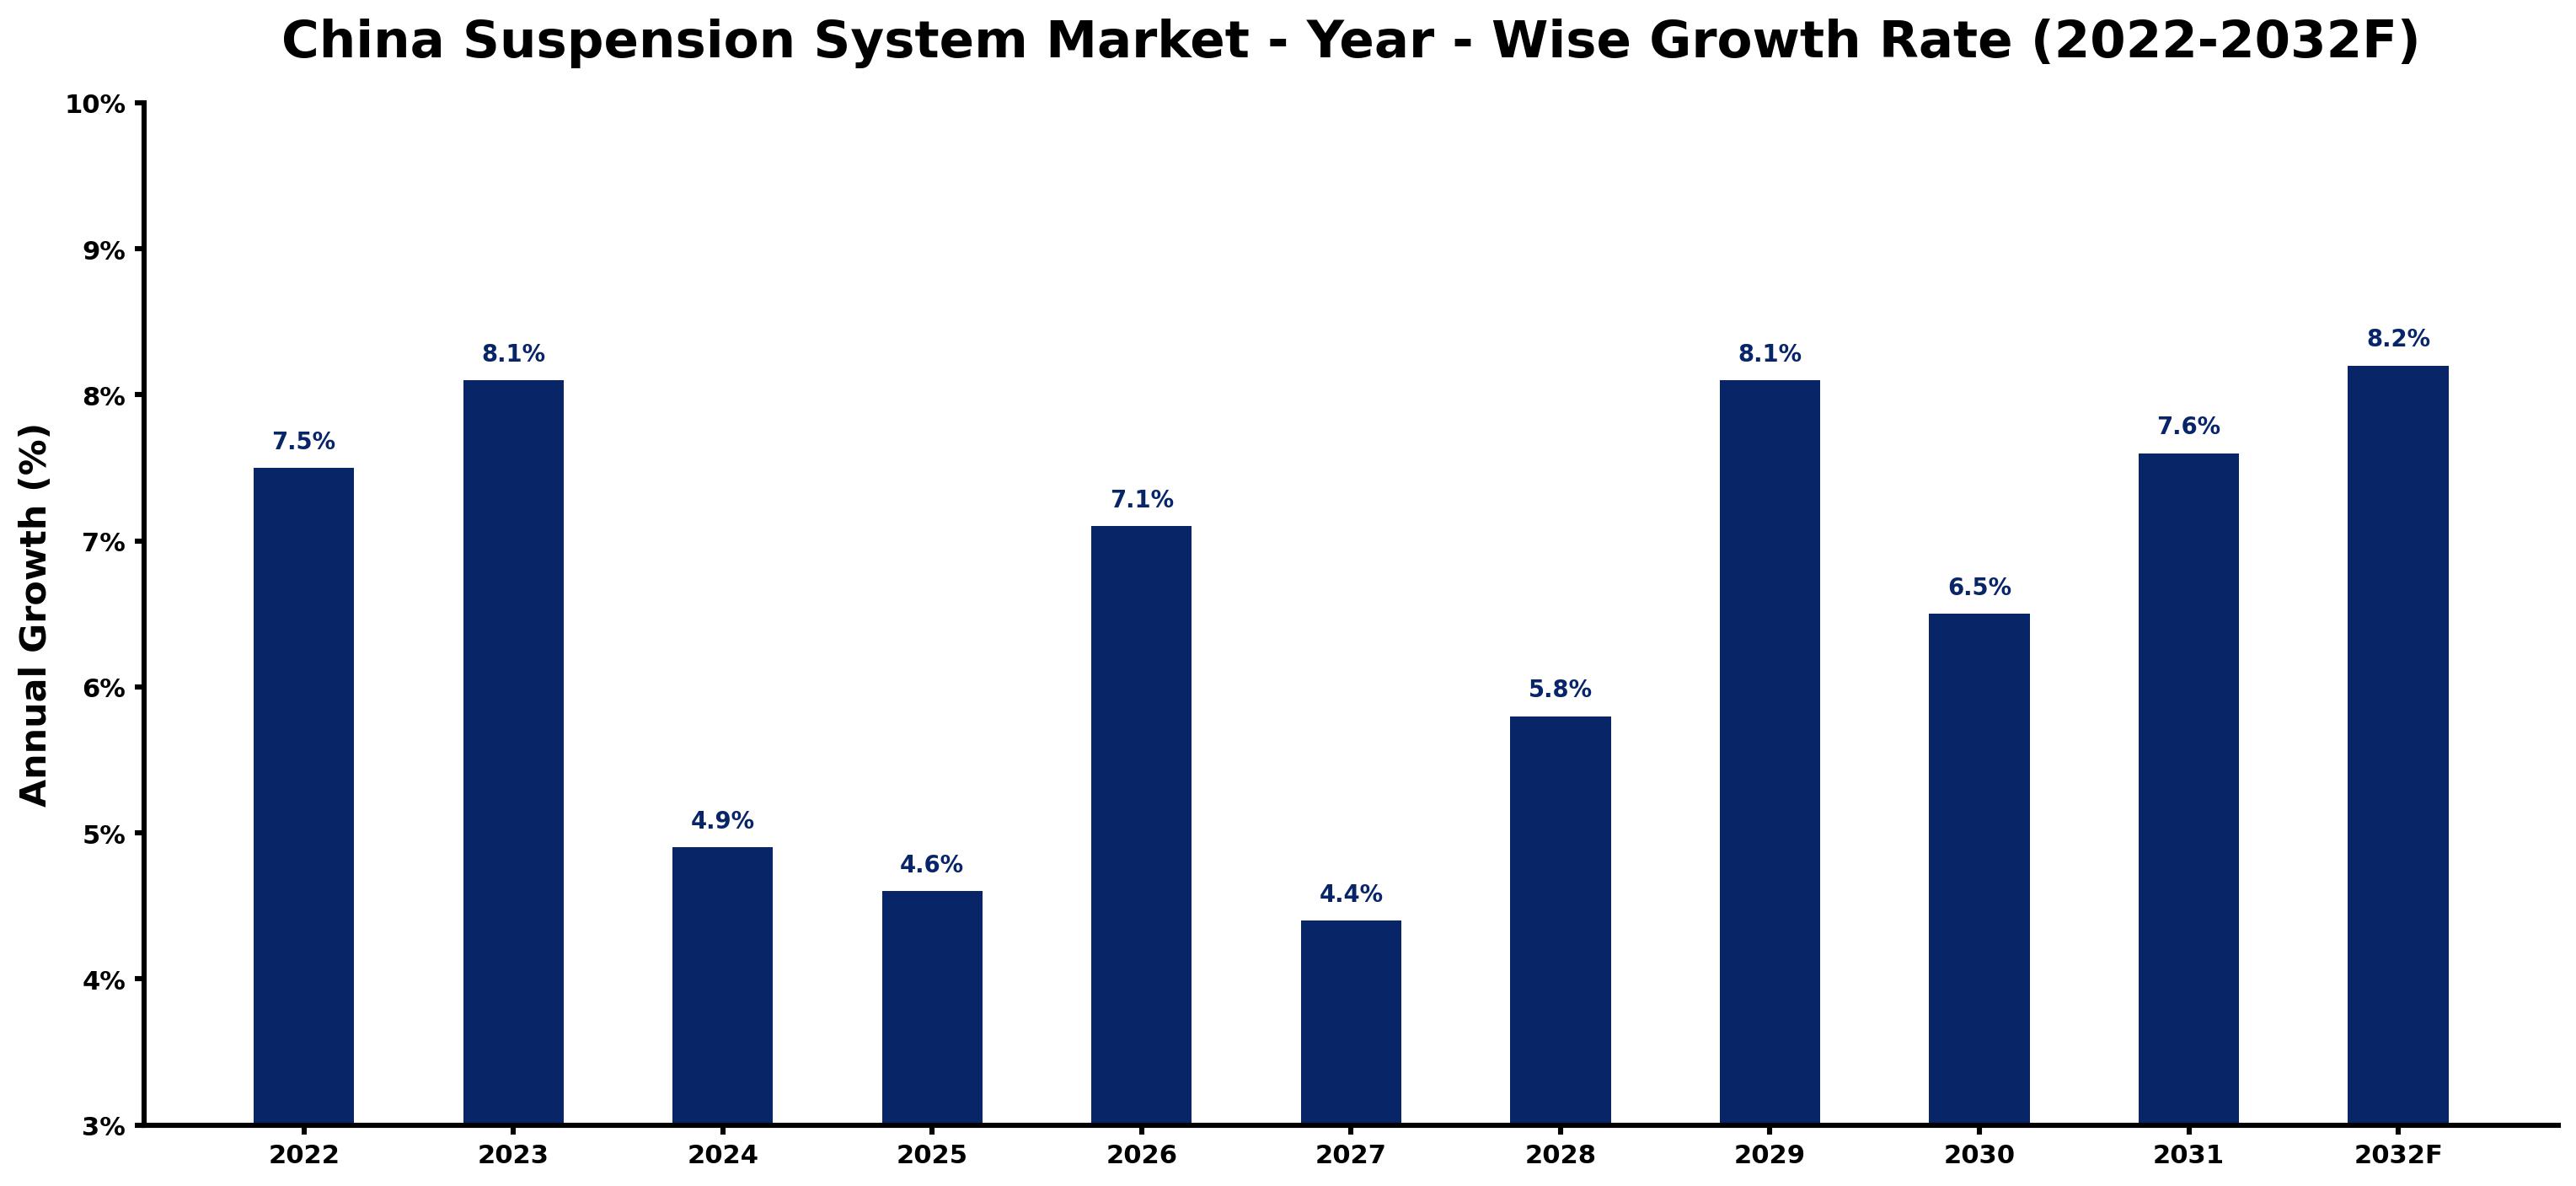
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.5 | The market experienced steady growth due to ongoing vehicle production and demand from OEMs. |
| 2023 | 8.1 | Demand surged as production exceeded 25 million vehicles, driving suspension system needs. |
| 2024 | 4.9 | Growth slowed as manufacturers adjusted to the National Standard GB/T 18655-2020 and demand stabilised. |
| 2025 | 4.6 | A further slowdown occurred as competition intensified among over 300 registered OEMs for market share. |
| 2026 | 7.1 | Investment in advanced technologies is anticipated to boost growth as manufacturers seek to innovate. |
| 2027 | 4.4 | The market will see a slowdown as manufacturers face challenges in sourcing high-quality materials. |
| 2028 | 5.8 | Growth is projected to rebound as demand for luxury vehicles increases, requiring advanced systems. |
| 2029 | 8.1 | Demand is expected to accelerate again as the automotive sector expands, particularly in EVs. |
| 2030 | 6.5 | Growth will slow as the market adjusts to new safety standards and regulations. |
| 2031 | 7.6 | An increase in vehicle production and technology adoption will spur demand for suspension systems. |
| 2032 | 8.2 | The market is anticipated to peak as advanced suspension systems become standard across all vehicle types. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Suspension System Market Synopsis
The Suspension System Market in China encompasses technologies that support vehicle weight, absorb shocks, and maintain tire contact with the road. Key components include shock absorbers, springs, and linkages, primarily used to improve ride comfort and safety. The market is expanding due to substantial vehicle production, with over 25 million units in 2022, and increasing demand from OEMs and luxury vehicle manufacturers. The Electric Vehicle Industry Development Plan (2021-2035) promotes advanced suspension technologies, further driving market expansion.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing vehicle production in China drives demand for suspension systems. | Driver | High | OEMs |
| Growing demand for luxury vehicles leads to higher adoption of advanced suspension technologies. | Driver | High | Luxury & Premium Vehicles |
| The projected 15% increase in air suspension demand for heavy vehicles creates opportunities for suppliers. | Opportunity | High | Air Suspension |
| The automotive aftermarket valued at approximately 50 billion CNY presents investment opportunities for new entrants. | Opportunity | High | Passive Suspension |
| Intense competition among OEMs may limit profit margins for suspension system suppliers. | Restraint | Medium | OEMs |
| The need for compliance with evolving safety standards can increase production costs for manufacturers. | Restraint | Medium | Passive Suspension |
| The Suspension System Market in China faces challenges in sourcing advanced materials for production. | Challenge | High | Passive Suspension |
| Technological advancements require continuous investment, which can strain smaller manufacturers financially. | Challenge | Medium | Passive Suspension |
Evaluation of Drivers in China Suspension System Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising vehicle production in China boosts demand for suspension systems. | OEMs | In 2022, over 25 million vehicles produced increased the need for suspension systems. |
| Growing luxury vehicle segment drives demand for advanced suspension technologies. | Luxury & Premium Vehicles | In Shanghai, luxury vehicle production heavily utilises advanced suspension systems. |
| Increased focus on electric vehicles leads to higher suspension system adoption. | EVs & Hybrids | The Electric Vehicle Industry Development Plan promotes advanced suspension systems. |
| Demand for air suspension systems in heavy vehicles is projected to rise by 15% by 2025. | Air Suspension | The demand for air suspension systems is expected to increase. |
| The automotive aftermarket is expanding, creating opportunities for suspension component suppliers. | Passive Suspension | The aftermarket for suspension components is valued at approximately 50 billion CNY annually. |
Market growth for Suspension System in China is driven by increasing vehicle production, a surge in demand for luxury vehicles, and a transition towards electric vehicles. In 2022, vehicle production surpassed 25 million units, intensifying the need for suspension systems. The Electric Vehicle Industry Development Plan promotes advanced suspension technologies, further stimulating market expansion. The automotive aftermarket, valued at around 50 billion CNY annually, also offers opportunities for suppliers. Demand for air suspension systems in heavy vehicles is expected to grow by 15% by 2025, reflecting changing consumer preferences.
Evaluation of Restraints in China Suspension System Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Intense competition among OEMs may limit profit margins for suspension system suppliers. | OEMs | As of 2023, over 300 registered OEMs in China intensify competition for market share. |
| Compliance with evolving safety standards can increase production costs for manufacturers. | Passive Suspension | The National Standard GB/T 18655-2020 requires manufacturers to meet stringent safety regulations. |
| Sourcing advanced materials for production poses challenges for manufacturers. | Passive Suspension | The growing demand for high-quality materials increases sourcing difficulties in the market. |
| Technological advancements require continuous investment, straining smaller manufacturers financially. | Passive Suspension | Smaller manufacturers may struggle to keep up with the pace of technological innovation. |
| Market saturation in certain segments can limit growth potential for suppliers. | Passive Suspension | The automotive sector is experiencing saturation, particularly in standard vehicle segments. |
China Suspension System Market Challenges
The China Suspension System Market encounters several practical issues, with intense competition among manufacturers being a primary concern. This oversupply results in aggressive pricing strategies that compress profit margins for suppliers and limit their capacity to invest in new developments. Supply chain disruptions pose additional challenges, as delays in sourcing critical components can extend lead times for producers, affecting their delivery commitments to OEMs. Skills shortages in advanced manufacturing techniques complicate recruitment efforts, leading to increased training costs for companies. Rising raw material prices have pressured suppliers, with key component costs increasing by 10% in the past year, forcing them to transfer these expenses to buyers.
Trends in the China Suspension System Market
Below mentioned are some of the trends shaping the China Suspension System Market growth.
- Shift towards Advanced Suspension Technologies: The market is increasingly adopting advanced suspension technologies to improve vehicle performance. The Electric Vehicle Industry Development Plan (2021-2035) supports this shift, with a projected increase in air suspension demand by 15% by 2025.
- Growing Demand for Air Suspension Systems: Heavy commercial vehicles are increasingly utilising air suspension systems for improved load management. The demand for air suspension systems is anticipated to rise by 15% by 2025, reflecting a notable trend in the market.
- Luxury Vehicles Prioritising Advanced Suspension Systems: Luxury vehicle manufacturers are prioritising advanced suspension systems to improve ride quality. In Shanghai, the production of luxury vehicles heavily utilises these technologies, indicating a clear market trend.
- Increased Focus on Electric Vehicles: The rise of electric vehicles is driving demand for efficient suspension systems. The total vehicle population in China reached 300 million in 2023, increasing the need for efficient suspension systems.
Investment Opportunities in the China Suspension System Market
Several openings in the China Suspension System Market merit attention from investors.
- Current Market Demand for Advanced Technologies: The demand for advanced suspension technologies is increasing, particularly in luxury vehicles. With over 300 registered OEMs in China, suppliers have a strong opportunity to invest in innovative solutions.
- Investment in Aftermarket Components: The automotive aftermarket, valued at around 50 billion CNY annually, presents a promising opportunity for suppliers. Targeting OEMs and fleet manufacturers can facilitate market entry.
- Growing Electric Vehicle Segment: The electric vehicle segment is rapidly expanding, necessitating efficient suspension systems. With the Electric Vehicle Industry Development Plan encouraging innovation, suppliers can concentrate on this burgeoning market.
- Demand for Air Suspension Systems in Heavy Vehicles: The anticipated 15% increase in air suspension demand by 2025 provides a timely opportunity for suppliers. Focusing on heavy commercial vehicle manufacturers can yield substantial returns.
Government Initiatives in the China Suspension System Market
The National Standard GB/T 18655-2020, established by the Standardization Administration of China, regulates automotive suspension systems to ensure safety and performance. The Automotive Industry Development Plan (2021-2025) encourages innovation in suspension technologies, supported by a budget of 10 billion CNY for R&D. These measures compel manufacturers to invest in compliant technologies, improving overall market standards. The Electric Vehicle Industry Development Plan (2021-2035) promotes advanced suspension technologies for EVs, further enhancing safety and performance standards.
The China Automotive Technology and Research Center (CATARC) provides guidelines for suspension system testing, ensuring compliance with national standards. The Automotive Industry Standards Committee develops and revises standards for suspension systems, aligning them with international practices. These agencies play a vital role in shaping the market by approving new technologies and funding research initiatives. The Ministry of Industry and Information Technology oversees standards for automotive components, including suspension systems, facilitating compliance and innovation.
Future Insight of the China Suspension System Market
The China Suspension System Market is set for substantial transformations by 2032, driven by several key factors. The Electric Vehicle Industry Development Plan will advance suspension technologies, improving vehicle performance and safety. The total vehicle population in China reached 300 million in 2023, generating an increased need for efficient suspension systems. The implementation of the National Standard GB/T 18655-2020 will establish higher quality and safety benchmarks, benefiting both buyers and manufacturers. The automotive aftermarket, valued at approximately 50 billion CNY annually, continues to grow, presenting further opportunities for producers.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By System Type – Passive Suspension Dominated, Active Suspension Expected to Grow Fastest
According to Sumit Sagar, AM at 6Wresearch, in 2025, Passive Suspension led the system type split with a 32% share. Passive suspension systems hold the largest market share due to their essential role in the over 25 million vehicles produced in China in 2022. Their widespread use across various vehicle types ensures a steady demand from manufacturers prioritising basic shock absorption. The quickest growth will come from Active Suspension, forecast to expand at a CAGR of 8.2% between 2026 and 2032. Active suspension systems are experiencing rapid growth as they are increasingly incorporated into high-end vehicles, enhancing ride quality and handling. This growth is propelled by a rising consumer preference for advanced driving experiences in luxury models, indicating a shift towards more sophisticated technologies. Suppliers should focus on advancing active suspension technologies to capitalise on the growing demand in the premium vehicle segment.
By Technology Used – Conventional Shock Absorbers Dominated, Electronically Controlled Expected to Grow Fastest
Conventional Shock Absorbers took a 44% share of technology used in 2025, more than any other category. Conventional shock absorbers dominate the market due to their widespread application in most vehicles, effectively addressing basic suspension needs. Their reliability and affordability make them a preferred choice among manufacturers, ensuring a strong market presence. Electronically Controlled is projected to grow fastest, at a CAGR of 8.0% during 2026–2032. The demand for electronically controlled systems is accelerating, particularly in premium vehicles, as they offer superior performance and adaptability. This growth is propelled by the automotive industry's shift towards more technologically advanced solutions. Manufacturers should focus on advancing electronically controlled technologies to remain competitive in the changing automotive market.
By Vehicle Segment – Compact & Sedan Cars Dominated, EVs & Hybrids Expected to Grow Fastest
Compact & Sedan Cars held a 48% share of the China Suspension System Market by vehicle segment in 2025. Compact and sedan cars represent the largest share of the market as they are the most commonly produced vehicles in China, utilising suspension systems extensively. Their popularity ensures a steady demand for reliable suspension solutions. EVs & Hybrids are set to record the highest CAGR in this split, 8.2% over 2026–2032. The EVs and hybrids segment is rapidly expanding, driven by increasing consumer interest in environmentally friendly vehicles that require efficient suspension systems for optimal performance. This growth reflects the broader shift towards sustainable transportation. Suppliers should align their product development with the rising demand for suspension systems in the EV and hybrid market to capture new opportunities.
By End User – OEMs Dominated, Fleet Manufacturers Expected to Grow Fastest
With a 36% revenue share in 2025, OEMs was the largest end user category. OEMs dominate the market share as they are the primary users of suspension systems in vehicle manufacturing. Their extensive production capabilities and the need for various suspension technologies solidify their leading position in the market. Over 2026–2032, Fleet Manufacturers are expected to post the fastest growth, at a CAGR of 9.5%. Fleet manufacturers are rapidly increasing their use of robust suspension systems to ensure vehicle durability and performance across their fleets. This trend is driven by the demand for reliable vehicles in commercial operations, resulting in a significant uptick in their market share. Suppliers must tailor their products to meet the specific durability and performance needs of fleet manufacturers, ensuring their suspension systems are fit for commercial use.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Suspension System Market Outlook
- Market Size of China Suspension System Market, 2025
- Forecast of China Suspension System Market, 2032
- Historical Data and Forecast of China Suspension System Revenues & Volume for the Period 2022 - 2032F
- China Suspension System Market Trend Evolution
- China Suspension System Market Drivers and Challenges
- China Suspension System Price Trends
- China Suspension System Porter's Five Forces
- China Suspension System Industry Life Cycle
- Historical Data and Forecast of China Suspension System Market Revenues & Volume By System Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension System Market Revenues & Volume By Passive Suspension for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension System Market Revenues & Volume By Active Suspension for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension System Market Revenues & Volume By Semi-Active Suspension for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension System Market Revenues & Volume By Air Suspension for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension System Market Revenues & Volume By Technology Used for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension System Market Revenues & Volume By Conventional Shock Absorbers for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension System Market Revenues & Volume By Adaptive Control for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension System Market Revenues & Volume By Electronically Controlled for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension System Market Revenues & Volume By Pneumatic Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension System Market Revenues & Volume By Vehicle Segment for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension System Market Revenues & Volume By Compact & Sedan Cars for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension System Market Revenues & Volume By Luxury & Premium Vehicles for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension System Market Revenues & Volume By EVs & Hybrids for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension System Market Revenues & Volume By Heavy Commercial Vehicles for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension System Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension System Market Revenues & Volume By OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension System Market Revenues & Volume By Suspension Tech Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension System Market Revenues & Volume By Smart Vehicle Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China Suspension System Market Revenues & Volume By Fleet Manufacturers for the Period 2022 - 2032F
- China Suspension System Import Export Trade Statistics
- Market Opportunity Assessment By System Type
- Market Opportunity Assessment By Technology Used
- Market Opportunity Assessment By Vehicle Segment
- Market Opportunity Assessment By End User
- China Suspension System Top Companies Market Share
- China Suspension System Competitive Benchmarking By Technical and Operational Parameters
- China Suspension System Company Profiles
- China Suspension System Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By System Type
- Passive Suspension
- Active Suspension
- Semi-Active Suspension
- Air Suspension
By Technology Used
- Conventional Shock Absorbers
- Adaptive Control
- Electronically Controlled
- Pneumatic Systems
By Vehicle Segment
- Compact & Sedan Cars
- Luxury & Premium Vehicles
- EVs & Hybrids
- Heavy Commercial Vehicles
By End User
- OEMs
- Suspension Tech Providers
- Smart Vehicle Platforms
- Fleet Manufacturers































