China Telecom Infrastructure Market Size & Growth Rate
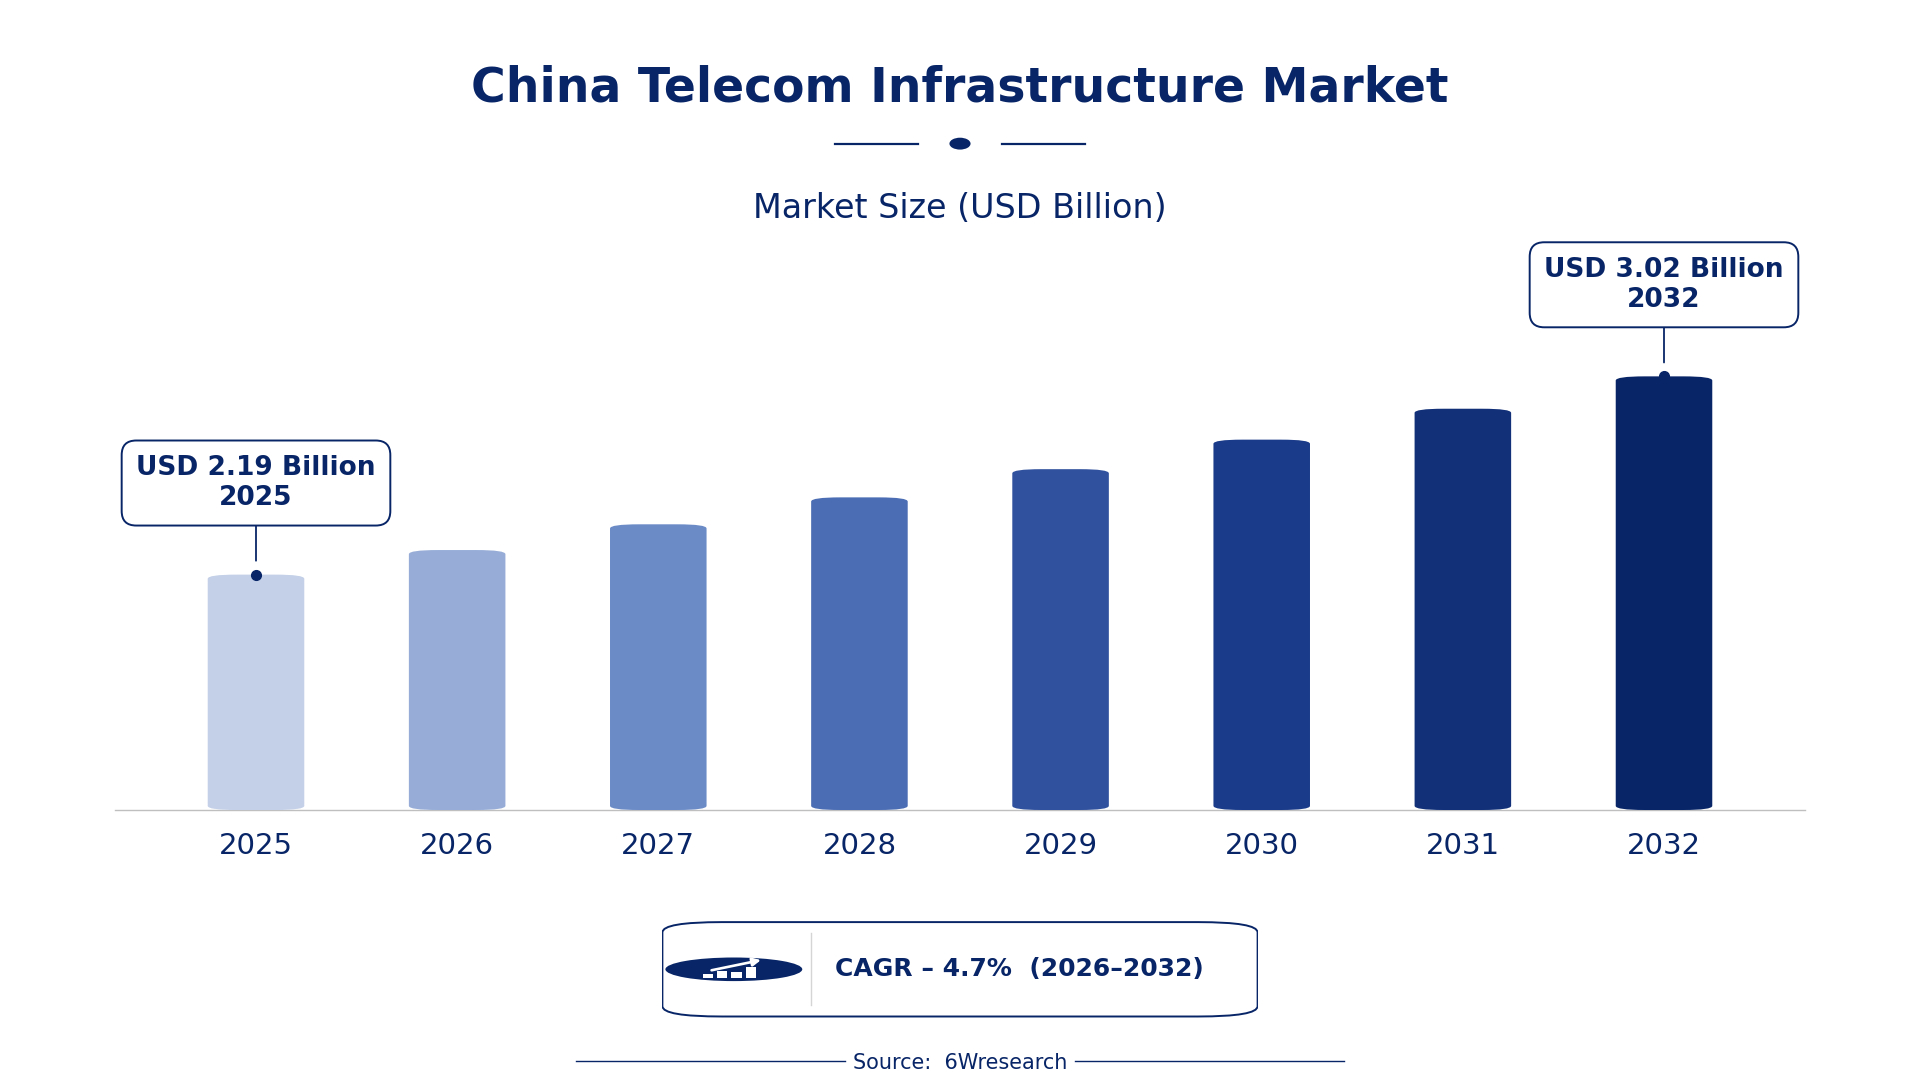
According to 6Wresearch internal database and industry insights, the China Telecom Infrastructure Market was valued at USD 2.19 billion in 2025 and is projected to reach USD 3.02 billion by 2032, growing at a CAGR of approximately 4.7% during 2026–2032.
China Telecom Infrastructure Market Highlights
| Report Metric | Details |
| Report Name | China Telecom Infrastructure Market |
| Market Size 2025 | USD 2.19 billion |
| Market Size 2032 | USD 3.02 billion |
| Absolute Growth 2025–2032 | USD 0.83 billion |
| CAGR 2026–2032 | 4.7% |
| Peak Annual Growth | 7.3% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Telecom Infrastructure, 2025 | Mobile Infrastructure (39% share) |
| Leading Product Type, 2025 | Towers (45% share) |
| Leading Technology Layer, 2025 | 5G (45% share) |
| Leading Distribution Channel, 2025 | Infra Developers (51% share) |
| Leading End User Industry, 2025 | Mobile Network Operators (51% share) |
| Fastest-Growing Telecom Infrastructure | Data Center Infrastructure (7.3% CAGR) |
| Fastest-Growing Product Type | Cloud/Edge Facilities (6.8% CAGR) |
| Fastest-Growing Distribution Channel | System Integrators (7.0% CAGR) |
| Fastest-Growing End User Industry | OTT and CDNs (6.8% CAGR) |
| Growing Sector | Mobile Infrastructure |
| Key End Users | Mobile Network Operators, Internet Providers, Telco Enterprises, OTT and CDNs |
China Telecom Infrastructure Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
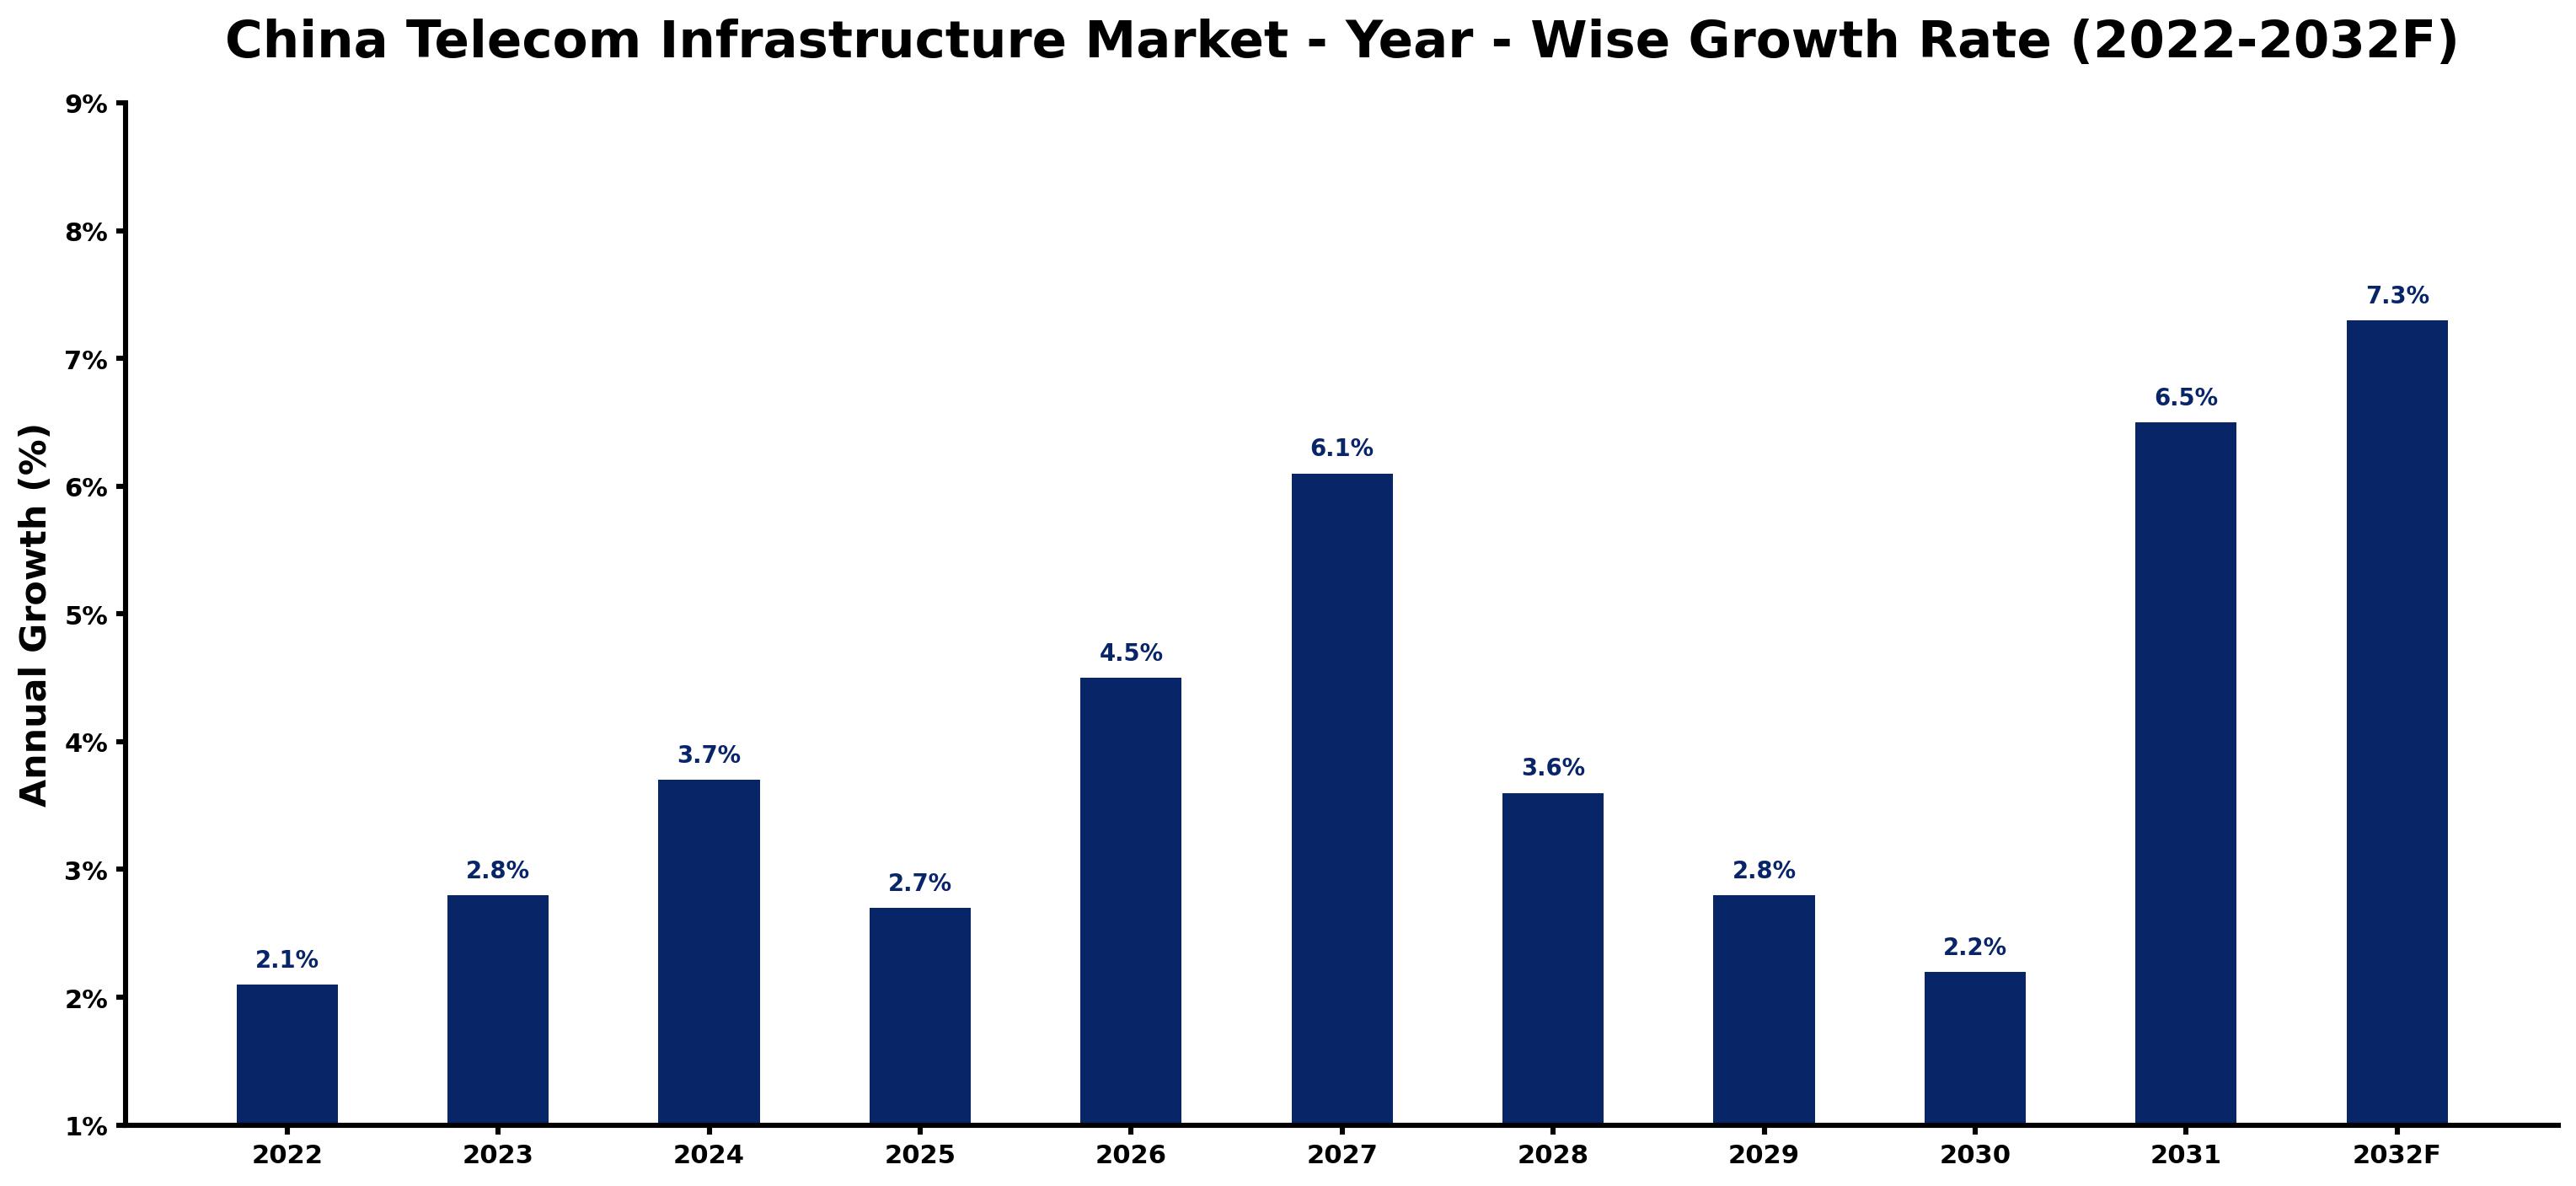
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 2.1 | The market experienced steady growth, driven by strong mobile subscriber demand from mobile network operators. |
| 2023 | 2.8 | Increased investments in 5G infrastructure propelled growth beyond the previous year, supported by the 14th Five-Year Plan for Economic and Social Development. |
| 2024 | 3.7 | A surge in data traffic contributed to growth, supported by mobile network operators investing in core network infrastructure. |
| 2025 | 2.7 | Growth slowed as investments stabilised, yet demand for broadband remained strong due to the Broadband China Strategy targeting rural connectivity. |
| 2026 | 4.5 | A renewed focus on 5G deployment is expected to lead to faster growth in infrastructure investments, driven by the Digital Economy Development Plan. |
| 2027 | 6.1 | Growing data traffic and mobile connectivity needs will spur further market expansion, driven by rising subscriber numbers and the 14th Five-Year Plan. |
| 2028 | 3.6 | Market growth is projected to slow as 5G infrastructure reaches saturation in urban areas, impacting new investments. |
| 2029 | 2.8 | Demand for telecom services will continue to grow, although at a slower pace than before, influenced by urbanisation and the need for broadband access. |
| 2030 | 2.2 | Investment in digital infrastructure is expected to slow, leading to a further deceleration in growth as rural projects progress under the Broadband China Strategy. |
| 2031 | 6.5 | A resurgence in infrastructure projects is anticipated to lead to faster growth, driven by urbanisation and the Digital China Initiative. |
| 2032 | 7.3 | The market is projected to peak as 5G coverage reaches urban areas, boosting overall demand. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Telecom Infrastructure Market Synopsis
Telecom Infrastructure in China encompasses the essential components for telecommunications services, including mobile and wireline networks, data centers, and core systems. It employs advanced technologies like fiber optics and wireless systems to enable mobile communications and internet access. The market is experiencing growth due to strong domestic demand from mobile network operators and ongoing investments in 5G technology. With over 1.4 billion mobile subscribers and a revenue of approximately 1.3 trillion CNY in 2022, the market is set for continued expansion.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing mobile subscriber base driving demand for infrastructure development. | Driver | High | Mobile Infrastructure |
| Expansion of 5G networks enhancing connectivity and service quality. | Driver | High | 5G |
| Urbanisation leading to increased demand for telecom services. | Opportunity | High | Core Network Infrastructure |
| Investment in data centers to support rising data traffic. | Opportunity | High | Data Center Infrastructure |
| High costs associated with infrastructure deployment limiting smaller players. | Restraint | Medium | Mobile Infrastructure |
| Regulatory hurdles delaying project approvals and implementations. | Restraint | Medium | Mobile Infrastructure |
| Challenges in securing funding for large-scale projects in rural areas. | Challenge | High | Wireline Infrastructure |
| Technological integration issues hindering the adoption of new systems. | Challenge | High | Core Network Infrastructure |
Evaluation of Drivers in China Telecom Infrastructure Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising mobile subscriber base increasing demand for infrastructure. | Mobile Infrastructure | China has over 1.4 billion mobile subscribers as of 2023, prompting investments in infrastructure. |
| Government support for 5G deployment driving infrastructure expansion. | 5G | The 14th Five-Year Plan prioritises 5G infrastructure, aiming for universal coverage by 2025. |
| Increasing data traffic necessitating upgrades in telecom networks. | Core Network Infrastructure | Annual data traffic is increasing by 30%, requiring significant network upgrades. |
| Growing demand for cloud services driving investment in data centers. | Data Center Infrastructure | China's telecom infrastructure investment reached 500 billion CNY in 2022, focusing on data management. |
| Rural broadband initiatives expanding market opportunities. | Wireline Infrastructure | The Broadband China Strategy aims for 50 million new connections by 2025, enhancing rural access. |
Growth across the Telecom Infrastructure market in China is anchored in rising mobile subscriber numbers, support for 5G deployment, and increasing data traffic. With over 1.4 billion mobile subscribers as of 2023, the demand for infrastructure is substantial. The 14th Five-Year Plan prioritises 5G infrastructure, aiming for universal coverage by 2025, which drives investments. A reported increase in data traffic necessitates upgrades in telecom networks, prompting mobile network operators to invest more in core network infrastructure, thereby improving service delivery and connectivity.
Evaluation of Restraints in China Telecom Infrastructure Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High deployment costs limiting access for smaller telecom providers. | Mobile Infrastructure | The substantial costs associated with building infrastructure can deter smaller players from entering the market. |
| Regulatory delays impacting project timelines and approvals. | Mobile Infrastructure | Regulatory hurdles can prolong the approval process, causing delays in infrastructure rollout. |
| Limited funding for rural telecom projects hindering expansion. | Wireline Infrastructure | Securing financing for large-scale projects in rural areas remains a challenge, limiting growth. |
| Technological integration issues delaying new system adoption. | Core Network Infrastructure | Challenges in integrating new technologies can slow down infrastructure upgrades and improvements. |
| Market saturation in urban areas slowing growth rates. | Mobile Infrastructure | As urban areas reach saturation, the pace of new infrastructure development may decelerate. |
China Telecom Infrastructure Market Challenges
The Telecom Infrastructure Market in China faces several practical problems, beginning with regulatory complexities that burden buyers, as the Ministry of Industry and Information Technology enforces strict compliance, delaying project approvals by an average of six months. Suppliers struggle with technological hurdles; the rapid pace of innovation, including the recent push for 6G research, strains existing capabilities and raises development costs by an estimated 20%. Cost pressures arise from the 500 billion CNY investment in infrastructure, forcing producers to allocate more budget to maintain competitiveness. Intense competition among telecom providers leads to price wars, eroding profit margins and limiting suppliers' ability to invest in new technologies.
Trends in the China Telecom Infrastructure Market
Four trends stand out in the China Telecom Infrastructure Market.
- Shift from Traditional to 5G Infrastructure: China is transitioning from traditional telecom infrastructure to 5G systems, with over 700,000 5G base stations installed by mid-2023, reflecting this shift.
- Increase in Data Center Investments: Since 2022, there has been a marked increase in investments in data center infrastructure, with significant funding allocated to new facilities to support cloud services.
- Expansion of Fiber Optic Networks: The expansion of fiber optic networks is essential for improving broadband access, with fiber optic networks covering over 90% of urban households as of 2023.
- Government Focus on Digital Infrastructure: The State Council's Digital Economy Development Plan allocates 300 billion CNY to improve digital infrastructure, aiming to enhance telecom capabilities nationwide by 2025.
Investment Opportunities in the China Telecom Infrastructure Market
Investors looking at the China Telecom Infrastructure Market should consider the following areas.
- Investment in Rural Broadband Initiatives: With a goal of 50 million new connections by 2025, there is a growing opportunity in rural broadband, underscored by the Broadband China Strategy's emphasis on infrastructure expansion.
- Development of Cloud/Edge Facilities: The demand for cloud services is increasing, creating opportunities for investment in cloud and edge facilities, particularly in urban centres where OTT services are rapidly expanding.
- Partnerships with Infra Developers: Collaborating with Infra Developers can ease entry into the telecom infrastructure market, which holds a 51% share in distribution channels, indicating strong demand for partnerships.
- Focus on 5G Technology Adoption: The ongoing drive for 5G technology presents opportunities for suppliers of related infrastructure, as the market aims for 100% coverage in urban areas by 2025, necessitating substantial investment.
Government Initiatives in the China Telecom Infrastructure Market
The National Development and Reform Commission's 14th Five-Year Plan for Economic and Social Development (2021) emphasises the expansion of 5G networks, aiming for universal coverage by 2025. This plan drives investment in telecom infrastructure and encourages private sector involvement in infrastructure projects. It sets a clear direction for the development of 5G technologies and supports economic growth through improved telecom services across the country. As a result, mobile network operators are incentivised to invest in new infrastructure to meet these targets.
The National Telecommunications Regulatory Authority approves funding for broadband expansion initiatives. This agency oversees projects that improve digital infrastructure, particularly in rural areas. The agency's support for the Broadband China Strategy ensures that new connections are established, enhancing access to telecom services. Additionally, the National Development and Reform Commission oversees spectrum allocation, ensuring compliance with national standards. These agencies work together to facilitate the growth of the telecom infrastructure market, promoting innovation and connectivity nationwide.
Future Insight of the China Telecom Infrastructure Market
The Telecom Infrastructure Market in China is set for transformative growth by 2032, driven by initiatives like the Digital China Initiative aimed at enhancing digital capabilities. The national priority for 5G deployment will spur further investment, with over 700,000 5G base stations already operational by mid-2023. Urban areas are on track for 100% 5G coverage by 2025, improving connectivity for buyers. Suppliers will need to align with evolving standards established by the Telecommunications Equipment Industry Association to remain competitive in a rapidly changing environment.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Telecom Infrastructure – Mobile Infrastructure Dominated, Data Center Infrastructure Expected to Grow Fastest
According to Sumit Sagar, AM at 6Wresearch, Mobile Infrastructure took a 39% share of telecom infrastructure in 2025, more than any other category. Mobile infrastructure holds the largest share due to its critical role in supporting over 1.4 billion mobile subscribers across China. This segment is essential for ensuring reliable mobile connectivity in both urban and rural environments, reflecting the vast demand for telecommunications services. The quickest growth will come from Data Center Infrastructure, forecast to expand at a CAGR of 7.3% between 2026 and 2032. Data center infrastructure is experiencing rapid growth, driven by a 30% annual increase in data traffic. As organisations increasingly adopt cloud services, the need for efficient and scalable data centres is rising sharply, contributing to this segment's expansion. Suppliers should focus on enhancing data centre capabilities to meet the growing demands of the telecom infrastructure market.
By Product Type – Towers Dominated, Cloud/Edge Facilities Expected to Grow Fastest
In 2025, Towers led the product type split with a 45% share. Towers dominate the market share as they are crucial for supporting mobile antennas and equipment necessary for seamless connectivity. Their extensive presence across urban areas underscores their importance in the telecom infrastructure ecosystem. Over 2026–2032, Cloud/Edge Facilities are expected to post the fastest growth, at a CAGR of 6.8%. Cloud and edge facilities are rapidly gaining traction, driven by the increasing demand for low-latency applications and services. The shift towards cloud computing and edge processing is reshaping the telecom infrastructure landscape, propelling this segment's growth. Buyers should prioritise investments in cloud and edge facilities to remain competitive in the evolving telecom sector.
By Technology Layer – 5G Dominated and Is Expected to Record the Fastest Growth
The largest technology layer category in 2025 was 5G, with a 45% share of total revenue. 5G technology leads the market share as it underpins next-generation mobile services, providing faster and more reliable connectivity. The national focus on 5G deployment ensures its continued dominance within the telecom infrastructure market. The same category is also set to grow fastest, at a CAGR of 6.3% during 2026–2032. 5G technology is also the fastest-growing segment, with ongoing investments and infrastructure development accelerating its adoption. The rising demand for high-speed mobile internet further solidifies its growth trajectory in the telecom landscape. Suppliers must prioritise 5G solutions to keep pace with the rapid advancements in telecom technology.
By Distribution Channel – Infra Developers Dominated, System Integrators Expected to Grow Fastest
Infra Developers accounted for a 51% market share by distribution channel in 2025. Infra developers capture the largest market share as they are directly responsible for constructing and expanding telecom infrastructure across China. Their vital role in addressing the needs of a growing subscriber base reinforces their market position. System Integrators are set to record the highest CAGR in this split, 7.0% over 2026–2032. System integrators are witnessing rapid growth due to their essential role in integrating diverse telecom systems and technologies. The increasing complexity of telecom solutions highlights their significance in ensuring seamless operations within the market. Buyers should engage with system integrators to facilitate the effective implementation of advanced telecom technologies.
By End User Industry – Mobile Network Operators Dominated, OTT and CDNs Expected to Grow Fastest
With a 51% revenue share in 2025, Mobile Network Operators was the largest end user industry category. Mobile network operators dominate the market share as the primary users of telecom infrastructure, crucial for delivering services to millions of subscribers. Their extensive networks drive the demand for robust infrastructure throughout the country. The quickest growth will come from OTT and CDNs, forecast to expand at a CAGR of 6.8% between 2026 and 2032. OTT and CDN services are the fastest-growing segment, spurred by the surge in online content consumption and streaming services. This trend reflects shifting consumer behaviours and preferences in media consumption, driving demand for enhanced infrastructure. Suppliers should tailor their offerings to meet the specific requirements of OTT and CDN providers to capitalise on this expanding market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Telecom Infrastructure Market Outlook
- Market Size of China Telecom Infrastructure Market, 2025
- Forecast of China Telecom Infrastructure Market, 2032
- Historical Data and Forecast of China Telecom Infrastructure Revenues & Volume for the Period 2022 - 2032F
- China Telecom Infrastructure Market Trend Evolution
- China Telecom Infrastructure Market Drivers and Challenges
- China Telecom Infrastructure Price Trends
- China Telecom Infrastructure Porter's Five Forces
- China Telecom Infrastructure Industry Life Cycle
- Historical Data and Forecast of China Telecom Infrastructure Market Revenues & Volume By Telecom Infrastructure for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Market Revenues & Volume By Mobile Infrastructure for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Market Revenues & Volume By Wireline Infrastructure for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Market Revenues & Volume By Core Network Infrastructure for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Market Revenues & Volume By Data Center Infrastructure for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Market Revenues & Volume By Product Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Market Revenues & Volume By Towers, RAN Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Market Revenues & Volume By Fiber Backbone for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Market Revenues & Volume By EPC, IMS for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Market Revenues & Volume By Cloud/Edge Facilities for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Market Revenues & Volume By Technology Layer for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Market Revenues & Volume By 4G, 5G for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Market Revenues & Volume By GPON, Ethernet for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Market Revenues & Volume By Virtualized Core for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Market Revenues & Volume By Virtual + Physical for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Market Revenues & Volume By Infra Developers for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Market Revenues & Volume By Government Bidding for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Market Revenues & Volume By System Integrators for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Market Revenues & Volume By Colocation Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Market Revenues & Volume By Mobile Network Operators for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Market Revenues & Volume By Internet Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Market Revenues & Volume By Telco Enterprises for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecom Infrastructure Market Revenues & Volume By OTT and CDNs for the Period 2022 - 2032F
- China Telecom Infrastructure Import Export Trade Statistics
- Market Opportunity Assessment By Telecom Infrastructure
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Technology Layer
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User Industry
- China Telecom Infrastructure Top Companies Market Share
- China Telecom Infrastructure Competitive Benchmarking By Technical and Operational Parameters
- China Telecom Infrastructure Company Profiles
- China Telecom Infrastructure Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Telecom Infrastructure
- Mobile Infrastructure
- Wireline Infrastructure
- Core Network Infrastructure
- Data Center Infrastructure
By Product Type
- Towers
- RAN Systems
- Fiber Backbone
- EPC
- IMS
- Cloud/Edge Facilities
By Technology Layer
- 4G
- 5G
- GPON
- Ethernet
- Virtualized Core
- Virtual + Physical
By Distribution Channel
- Infra Developers
- Government Bidding
- System Integrators
- Colocation Providers
By End User Industry
- Mobile Network Operators
- Internet Providers
- Telco Enterprises
- OTT and CDNs































